
 Screw Top Jar Market | 2026-2036
Screw Top Jar Market Size, Share, and Industry Trends Forecast 2026-2036
Screw Top Jar Market Analytics
Multi-source procurement for glass and polymer resins is broadening as brand owners reduce dependency on single-region supply. Owens-Illinois leverages vertical integration across furnace operations and mold fabrication to sustain cost leadership in North American glass packaging. Berry Global anchors its position through blown plastic jar capacity scaled for food and personal care volumes. Ardagh Group competes via lightweighting technology that reduces per-unit material without sacrificing thread integrity.
A screw top jar denotes a cylindrical container with machined helical threads on its neck, designed to mate with a matching closure for repeatable sealing; wall thickness, thread pitch, and bore diameter determine compatibility with capping equipment and shelf-life performance. Glass dominates premium food and cosmetic segments where chemical inertness and visual clarity command margin pools, while plastic leads in high-volume food storage where drop resistance and light weight reduce logistics costs. Child-resistant closures represent the fastest-expanding closure category, driven by pharmaceutical and cannabis packaging regulations that mandate push-and-turn mechanisms.
The FDA sets food-contact material standards under 21 CFR that govern resin selection and migration testing for plastic jars, while the EPA regulates emissions from glass melting furnaces under the Clean Air Act. Europe's REACH framework restricts Substances of Very High Concern in coatings and colorants, forcing reformulation of decorative finishes. Stakeholders must monitor evolving extended producer responsibility laws that shift end-of-life collection costs onto manufacturers.
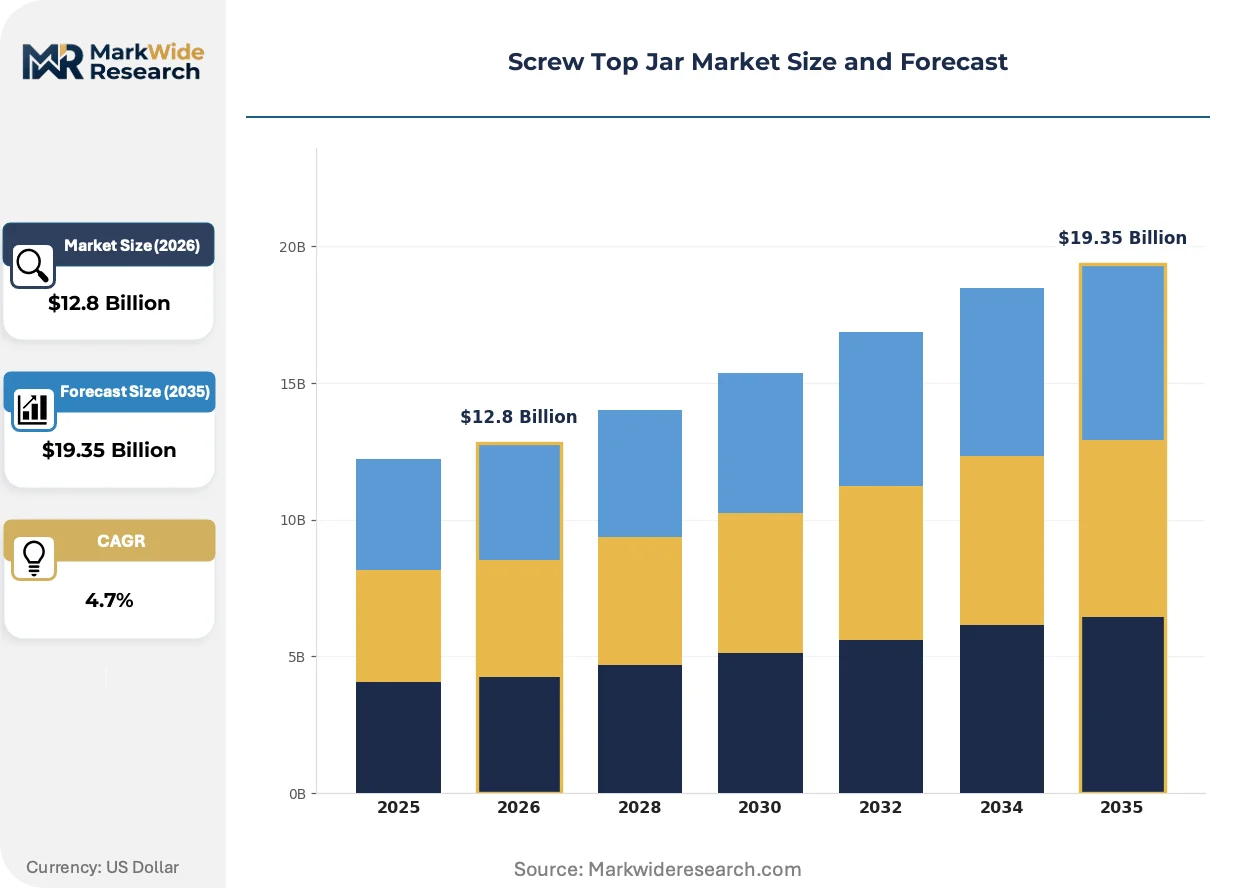
Market Dynamics
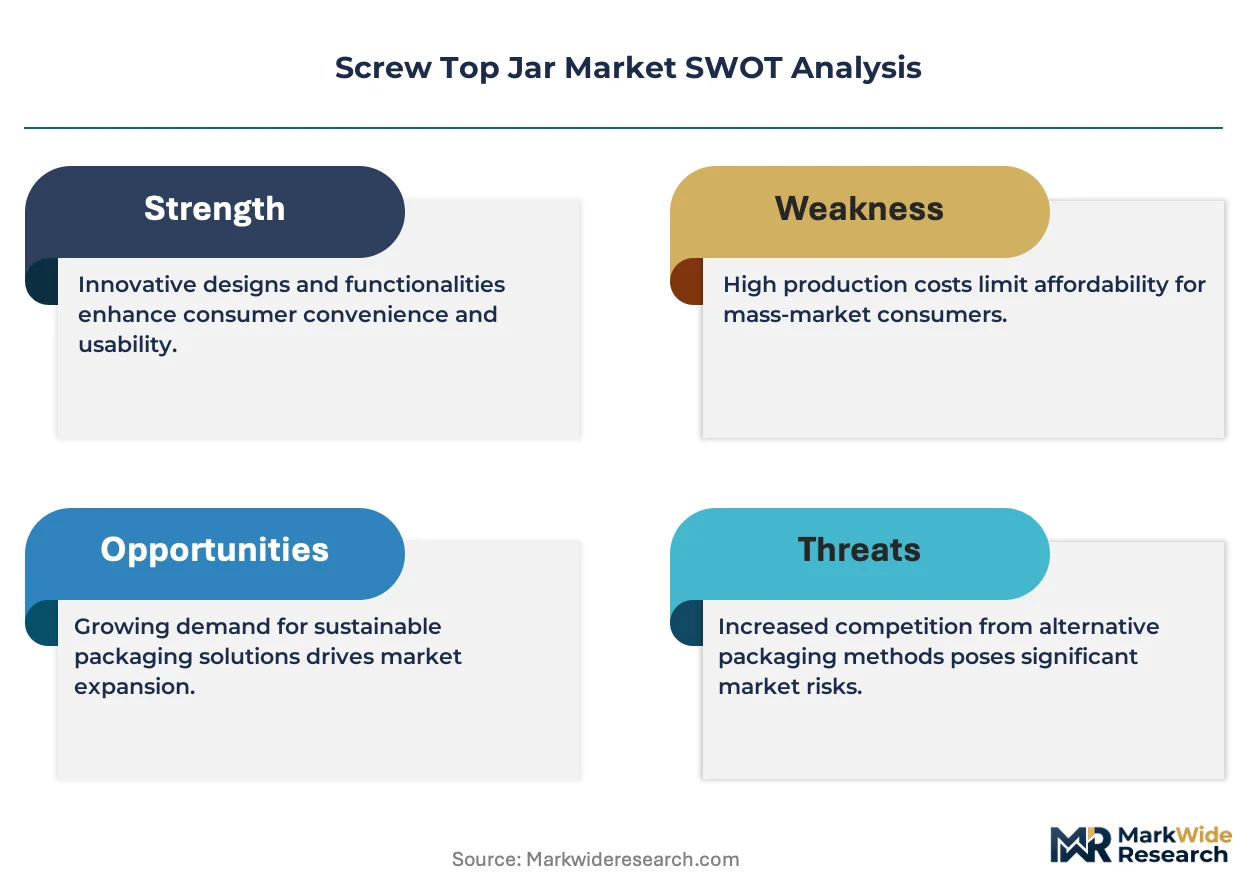
REACH compliance and Europe's F-Gas Regulation are forcing reformulation of decorative coatings and accelerating furnace upgrades across glass manufacturing clusters, compressing margins for mid-tier producers while rewarding capital-rich operators with captive clean energy supply.
Growth Catalysts
- Child-resistant closure mandates:Pharmaceutical and cannabis packaging regulations in multiple jurisdictions now require push-and-turn mechanisms, expanding the addressable hardware market for precision-threaded neck designs.
- Reusable packaging premiums:Food storage applications are capturing margin pools as consumers trade single-use containers for durable glass and polymer alternatives with extended reuse cycles.
- Lightweighting technology diffusion:Thread integrity preservation at reduced wall thickness is enabling material savings without sacrificing capping equipment compatibility in high-speed filling lines.
Market Restraints
- Energy cost volatility:Glass melting furnace operations face input cost pressure from natural gas and electricity price swings, particularly affecting producers without renewable energy offtake agreements.
- Raw material concentration:High-purity silica sand supply concentrates in specific mining districts, creating geographic dependency risk for container glass manufacturers.
- Substitution by flexible pouches:Stand-up pouches with spouted closures are displacing rigid jars in certain food and personal care segments where drop resistance and shipping cube efficiency dominate purchase criteria.
Strategic Opportunities
- Underpenetrated pharmaceutical serialization:Track-and-trace mandates in emerging markets create demand for jars with integrated RFID-enabled closures and tamper-evident features.
- Cosmetic refill systems:Premium beauty brands are piloting jar-plus-pod architectures that separate durable outer vessels from replaceable inner cartridges, extending product lifecycle value.
- Extended producer responsibility tailwinds:Deposit-return schemes and packaging levies in multiple European jurisdictions incentivize design-for-recycling investments that command preferential shelf placement.
Industry Challenges
- Mold fabrication skill scarcity:Precision helical thread machining for glass and polymer necks requires specialized tooling expertise that is concentrating among aging technician cohorts in Germany and Italy.
- Multi-jurisdiction certification timelines:Simultaneous FDA 21 CFR compliance, REACH substance screening, and national pharmaceutical regulator approvals extend product launch cycles for global brand owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screw Top Jar Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Plastic, Metal, Wood Capacity: 50ml, 100ml, 250ml, 500ml Use Case: Food Storage, Craft Supplies, Cosmetics, Laboratory Use Closure Type: Standard, Child Resistant, Tamper Evident, Airtight |
| Companies Covered | Kilner, Infinity Jars, PacZone, SKS Bottle & Packaging, Xuzhou Wan Xuan Import & Export Trading, Owens-Illinois, Berry Global, Ardagh Group, Silgan Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screw Top Jar Market Evolving Landscape
Active thread-forming methods and closure automation are compressing the traditional separation between container production and sealing system integration, blurring historical procurement boundaries between jar manufacturers and capping equipment suppliers.
Modular mold systems for injection-blown PET jars is modularizing production economics for mid-volume personal care runs. Cosmetic contract manufacturers in South Korea and France are adopting quick-change cavity configurations that slash changeover downtime. This flexibility is modularizing the traditional tradeoff between scale economies and SKU proliferation, enabling smaller batch sizes without sacrificing unit cost competitiveness.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon use in foam insulation for cold-chain distribution packaging. Refrigerated jar shipments for temperature-sensitive pharmaceuticals and probiotics now require alternative thermal barrier materials. German logistics providers are responding with vacuum-insulated panel systems that maintain cold chain integrity while eliminating regulated blowing agents.
Direct-to-consumer subscription models are fragmenting historical bulk purchasing patterns for household food storage containers. Brand owners are unbundling multi-unit retail packs into single-jar shipments with customized labeling, compressing packaging specifications toward lighter-weight designs. This channel shift is most visible in North American and British markets where pantry organization content drives viral purchase cycles.
Screw Top Jar Market Segmentation
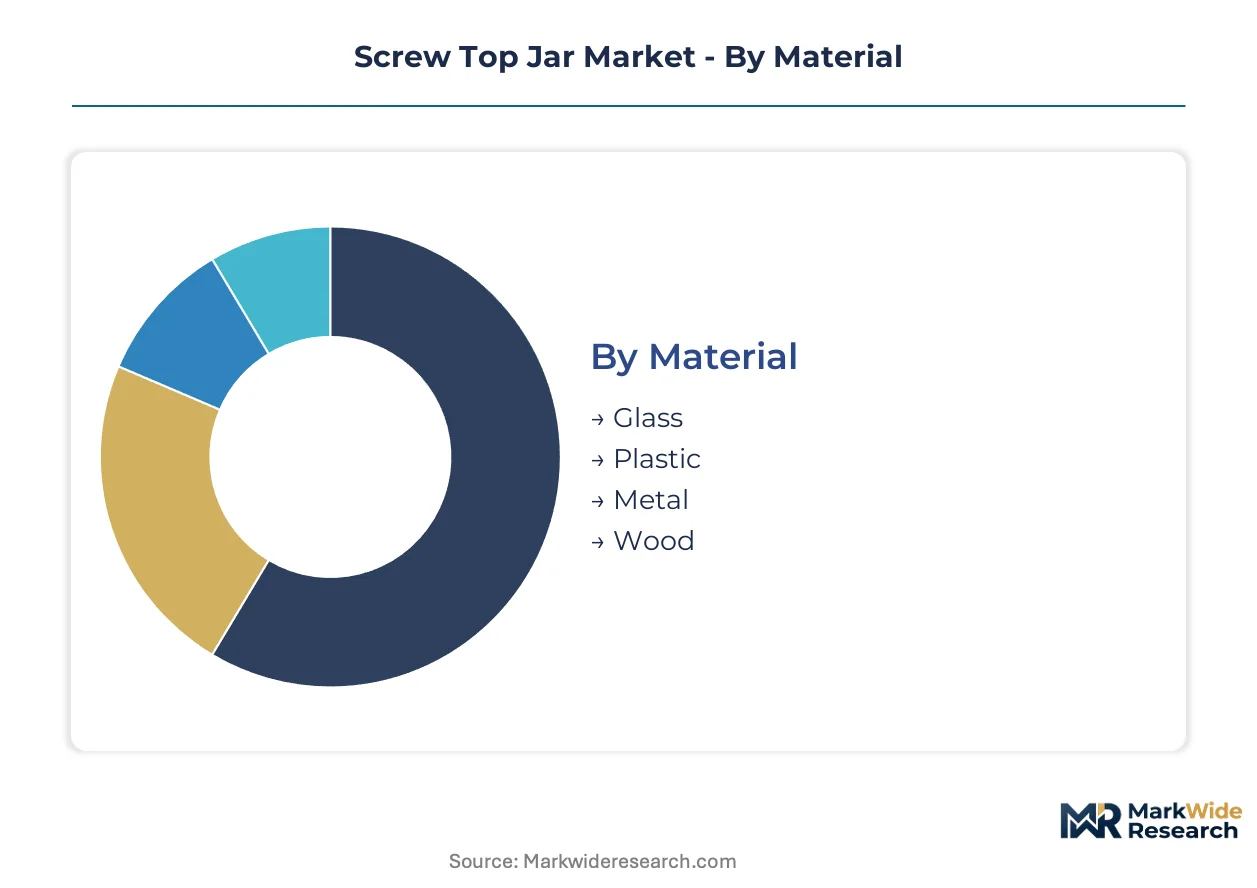
Screw top jar procurement decisions cascade from material selection through closure specification, with each tier imposing distinct technical and regulatory requirements. Understanding segment boundaries enables suppliers to align furnace capacity, mold investments, and coating formulations with actual demand concentration.
Material:
Volume production concentrates in plastic extrusion and blow-molding corridors, while premium positioning accrues to glass manufacturers with precision thread machining capabilities.
- Glass:Borosilicate and soda-lime formulations deliver chemical inertness and visual clarity for pharmaceutical and cosmetic applications. Demand clusters in Germany's precision manufacturing corridor, where REACH compliance and F-Gas Regulation furnace upgrades filter out mid-tier competitors.
- Plastic:PET, HDPE, and PP resins dominate high-volume food storage through drop resistance and lightweight logistics economics. Berry Global and similar operators scale blown-jar capacity across North American polymer processing hubs to serve pantry organization retail trends.
- Metal:Aluminum and tinplate configurations serve specialty food and industrial chemical segments requiring oxygen impermeability.
- Wood:Bamboo and hardwood vessels capture artisanal cosmetic and gift packaging niches with biodegradable positioning.
Today's leader: Plastic. Tomorrow's challenger: Glass, climbing fastest as reusable packaging premiums expand.
Capacity:
SKU proliferation in personal care and pharmaceutical sampling drives demand toward smaller formats, while pantry storage and bulk food retail anchor larger-volume procurement.
- 50ml:Miniature jars for cosmetic samples, pharmaceutical single-dose packaging, and travel-size personal care. South Korean contract manufacturers deploy modular injection-blown systems to compress changeover economics for micro-batch premium beauty runs.
- 100ml:Mid-range cosmetic and probiotic supplement containers balancing portability with sufficient volume for multi-use cycles.
- 250ml:Standard food storage format for preserves, sauces, and dry goods, where thread integrity under thermal processing stress determines supplier selection.
- 500ml:Bulk pantry and laboratory reagent storage, with lightweighting technology preserving capping equipment compatibility despite reduced wall thickness.
250ml commands current procurement volume. 50ml shows steepest expansion trajectory as direct-to-consumer sampling models fragment bulk purchasing patterns.
Use Case:
Regulatory intensity varies sharply across applications, with pharmaceutical and food contact mandates imposing certification burdens that consumer craft segments avoid.
- Food Storage:FDA 21 CFR compliance governs resin migration limits and thermal stability for plastic jars, while EPA furnace emissions rules constrain domestic glass supply. Reusable packaging consumer preferences are extending product lifecycle value and commanding shelf placement premiums.
- Craft Supplies:Bead, button, and small hardware organization with minimal regulatory overlay and price-sensitive procurement through mass retail channels.
- Cosmetics:Premium beauty brands pilot jar-plus-pod refill architectures separating durable outer vessels from replaceable cartridges. France and South Korea lead pilot adoption.
- Laboratory Use:Autoclavable borosilicate glass with chemically resistant coatings for reagent storage, where thread precision under thermal cycling determines performance.
Food Storage anchors supplier revenue. Cosmetics is gaining share fastest as refill system architectures extend customer lifetime value.
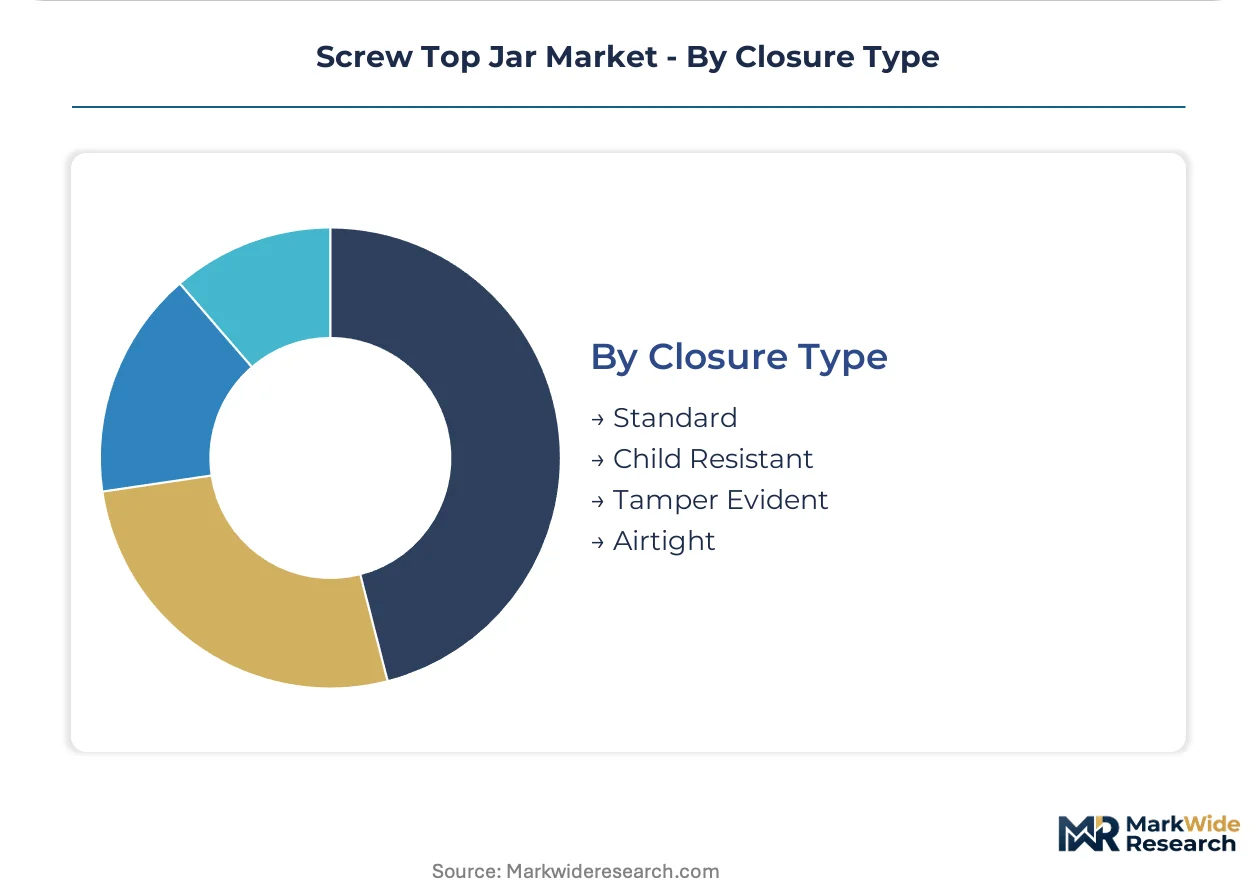
Closure Type:
Regulatory mandates are accelerating specification upgrades from basic sealing toward child-resistant and tamper-evident integrated systems.
- Standard:Basic helical thread closures for general food and craft storage with minimal security requirements.
- Child Resistant:Push-and-turn mechanisms mandated by pharmaceutical and cannabis packaging regulations across multiple state and national jurisdictions. Precision-threaded neck designs from German and Italian mold fabrication clusters capture expanding hardware demand.
- Tamper Evident:Break-ring or shrink-band integration for food safety and pharmaceutical integrity verification.
- Airtight:Gasketed or liner-equipped seals for oxygen-sensitive contents including probiotics, coffee, and volatile chemicals.
Standard closures dominate unit volume. Child Resistant is expanding most quickly as serialization mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision glass manufacturing corridor filters mid-tier competitors through REACH compliance and F-Gas Regulation furnace upgrades, concentrating premium cosmetic and pharmaceutical jar supply among capital-rich operators with captive clean energy.
United States
Pantry organization content drives viral purchase cycles for household food storage containers, fragmenting historical bulk purchasing into single-jar direct-to-consumer shipments. FDA 21 CFR governs resin migration limits for plastic jars while EPA furnace emissions rules constrain domestic glass supply. Berry Global anchors blown plastic jar capacity across North American polymer processing hubs.
Germany
Precision-threaded neck designs for child-resistant closures capture expanding hardware demand from pharmaceutical and cannabis packaging mandates. ECHA REACH substance screening restricts decorative coatings and colorants, forcing reformulation of finishes. The country's precision manufacturing corridor clusters mold fabrication expertise that is concentrating among aging technician cohorts.
China
Modular injection-blown PET jar systems compress changeover economics for mid-volume personal care runs serving premium beauty contract manufacturers. GB standards and SAMR oversight govern food-contact material compliance for export-oriented producers. Xuzhou Wan Xuan Import & Export Trading represents the export-trading archetype connecting regional manufacturing to international brand owners.
France
Premium beauty brands pilot jar-plus-pod refill architectures separating durable outer vessels from replaceable inner cartridges, extending product lifecycle value. ANSM pharmaceutical packaging regulations mandate serialization features for track-and-trace compliance. Cosmetic contract manufacturers in the Île-de-France region adopt quick-change cavity configurations that slash changeover downtime.
South Korea
Direct-to-consumer sampling models fragment bulk purchasing patterns, driving steepest expansion trajectory for 50ml miniature jars in cosmetic and pharmaceutical applications. MFDS pharmaceutical regulator approvals extend product launch cycles alongside multi-jurisdiction certification requirements. Seoul-based contract manufacturers deploy modular systems for micro-batch premium beauty runs.
Screw Top Jar Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular quick-change systems and refillable architectures. The market structures around three tiers: capital-rich glass operators with captive energy supply, scaled plastic blow-molders serving high-volume food storage, and specialized mold fabricators concentrated in European precision corridors. Dominant competitive moves include lightweighting technology licensing and backward integration into silica sand mining to secure raw material concentration risk.
Among North American-based operators, Owens-Illinois exemplifies the furnace-integrated glass archetype with upstream control over mold fabrication, while Berry Global anchors the blown plastic jar segment scaled for pantry organization retail trends. Ardagh Group occupies a position within the lightweighting technology tier, representing precision thread integrity preservation at reduced wall thickness. Kilner and Infinity Jars sit within the premium reusable positioning tier, reflecting consumer trade toward durable alternatives with extended reuse cycles.
| Leading Market Players |
|---|
| Kilner |
| Infinity Jars |
| PacZone |
| SKS Bottle & Packaging |
| Xuzhou Wan Xuan Import & Export Trading |
| Owens-Illinois |
| Berry Global |
| Ardagh Group |
| Silgan Holdings |
| Others |
Value Network & Pricing Analysis
Precision mold fabrication expertise concentrated among aging technician cohorts in Germany and Italy feeds labor-cost differentials that separate premium glass pricing from commodity plastic tiers. REACH compliance investments and F-Gas Regulation furnace upgrades compress margins for mid-tier European producers while rewarding capital-rich operators with captive clean energy supply.
Pricing Analysis
Input-cost pass-through from natural gas and electricity price volatility runs through glass melting furnace operations, forcing energy-uncovered producers to absorb margin compression while renewable-powered competitors maintain pricing stability. Three-tier pricing structure across premium, standard, and economy levels separates precision-threaded pharmaceutical glass from high-volume food storage plastics and generic craft containers. Pricing pressure stems from lightweighting technology diffusion that preserves thread integrity at reduced material weights. Food storage buyers exhibit highest price sensitivity; pharmaceutical and cosmetic brand owners accept premium positioning for serialization-ready and refill-system architectures.
Supply Chain Analysis
Single-source vulnerability sits with high-purity silica sand mining districts concentrated in specific geographic clusters, creating dependency risk for container glass manufacturers without diversified sourcing. Manufacturing gravity centers on Germany for precision glass, China for modular injection-blown PET systems, and the United States for blown plastic jar capacity serving pantry organization retail. Raw material feeds draw from polymer resins, borosilicate formulations, and specialized mold steel alloys. Tariff exposure on Chinese-manufactured components presents structural risk amid trade policy uncertainty. Distribution runs through direct-to-consumer subscription channels fragmenting historical bulk purchasing patterns alongside traditional retail and contract manufacturing pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Europe diverge from GB standards oversight in China, creating cost-structure differentials for export-oriented producers.
For Market Incumbents: Extend lightweighting technology licensing agreements to capture royalty streams as thread-integrity preservation becomes table stakes across high-speed filling lines. Deepen backward integration into silica sand mining to hedge raw material concentration risk. Child-resistant closure mandates from pharmaceutical and cannabis regulators threaten hardware suppliers without precision-threaded neck capabilities; invest in German and Italian mold fabrication apprenticeships to offset technician cohort aging.
For New Entrants and Emerging Players: Extended producer responsibility laws in European jurisdictions open a window for design-for-recycling investments that command preferential shelf placement under deposit-return schemes. Target cosmetic refill system architectures in France and South Korea where jar-plus-pod pilots separate durable outer vessels from replaceable cartridges. Pursue modular quick-change cavity configurations for mid-volume personal care runs as contract manufacturers seek changeover flexibility without sacrificing unit cost competitiveness.
For Investors and Strategic Acquirers: Packaging conglomerates with captive blow-molding capacity are the most active acquirer in this space, seeking precision glass capabilities to complete premium portfolio coverage. Long-term viability hinges on exposure to reusable packaging premiums and pharmaceutical serialization mandates rather than commodity food storage cyclicality. Monitor adoption velocity of RFID-enabled closures and tamper-evident features in emerging market track-and-trace programs as inflection indicator for hardware demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Sand Mining | Secures raw material supply against geographic concentration risk for glass furnace operators. |
| Lightweighting Technology Licensing | Captures royalty revenue as thread-integrity preservation becomes standard across filling lines. |
| Modular Quick-Change Cavity Systems | Enables South Korean and French contract manufacturers to compress changeover economics for micro-batch runs. |
| Design-for-Recycling Investment | Commands preferential shelf placement under European extended producer responsibility deposit-return schemes. |
| Pharmaceutical Serialization Capability Buildout | Addresses underpenetrated RFID-enabled closure demand from emerging market track-and-trace mandates. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with glass furnace operators, polymer procurement leads at blown-jar manufacturers, cosmetic contract manufacturing executives, and pharmaceutical packaging regulatory specialists with secondary validation. Customs and trade data, SEC filings from packaging conglomerates, ECHA substance screening databases, and FDA 21 CFR guidance documents anchored supply-side and regulatory dimensions. Bottom-up capacity assessments across furnace and blow-molding corridors triangulated against top-down demand segmentation by use case and closure type.
Segment-weighting approaches distributed value and volume across material tiers, capacity formats, use case applications, and closure specifications throughout the projection horizon. Analytical frameworks modeled substitution dynamics between rigid jars and flexible pouches, reusable packaging premium capture rates, and regulatory compliance cost pass-through. CAGRs derived from elasticity-adjusted demand curves incorporating channel shift toward direct-to-consumer subscription models and serialization mandate proliferation across pharmaceutical jurisdictions.
Revisions become necessary when energy price volatility exceeds modeled bands, trade policy disrupts silica sand or polymer resin flows, or regulatory timelines for pharmaceutical track-and-trace programs accelerate or delay. Forecasts reflect documented assumptions about lightweighting technology diffusion rates and child-resistant closure mandate geographic expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Container Stacking Machine Market
Containers
Laboratory Sample Container Market
Containers
Feeder Containers Market
Containers
HDPE Containers Market
Containers
Straight Sided Glass Jar Market
Containers
Lever Lid Cans Market
Containers
Cups and Lids Market
Containers
Bulk Containers Market
Containers
Flexible Water Tanks Market
Containers
Corrugated Bin Boxes Market
Containers
Takeout Containers Market
Containers
Packaging Bins Market
Containers
Light Resistant Containers Market
Containers
Car Lube Container Market
Containers
Container Mouth Inner Seal Market
Containers
Belgium Container Glass Market