
 Packaging Bins Market | 2026-2036
Packaging Bins Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Bins Market Analytics
China is reconfiguring regional supply patterns through expanded injection-molding capacity for plastic bulk containers. Greif Inc. leverages its steel drum heritage to anchor industrial packaging networks across North American manufacturing corridors. Mondi Group competes through paper-based corrugated bins that target food service compliance requirements. Berry Global Inc. differentiates via multi-layer polymer formulations that sustain chemical resistance in agricultural applications.
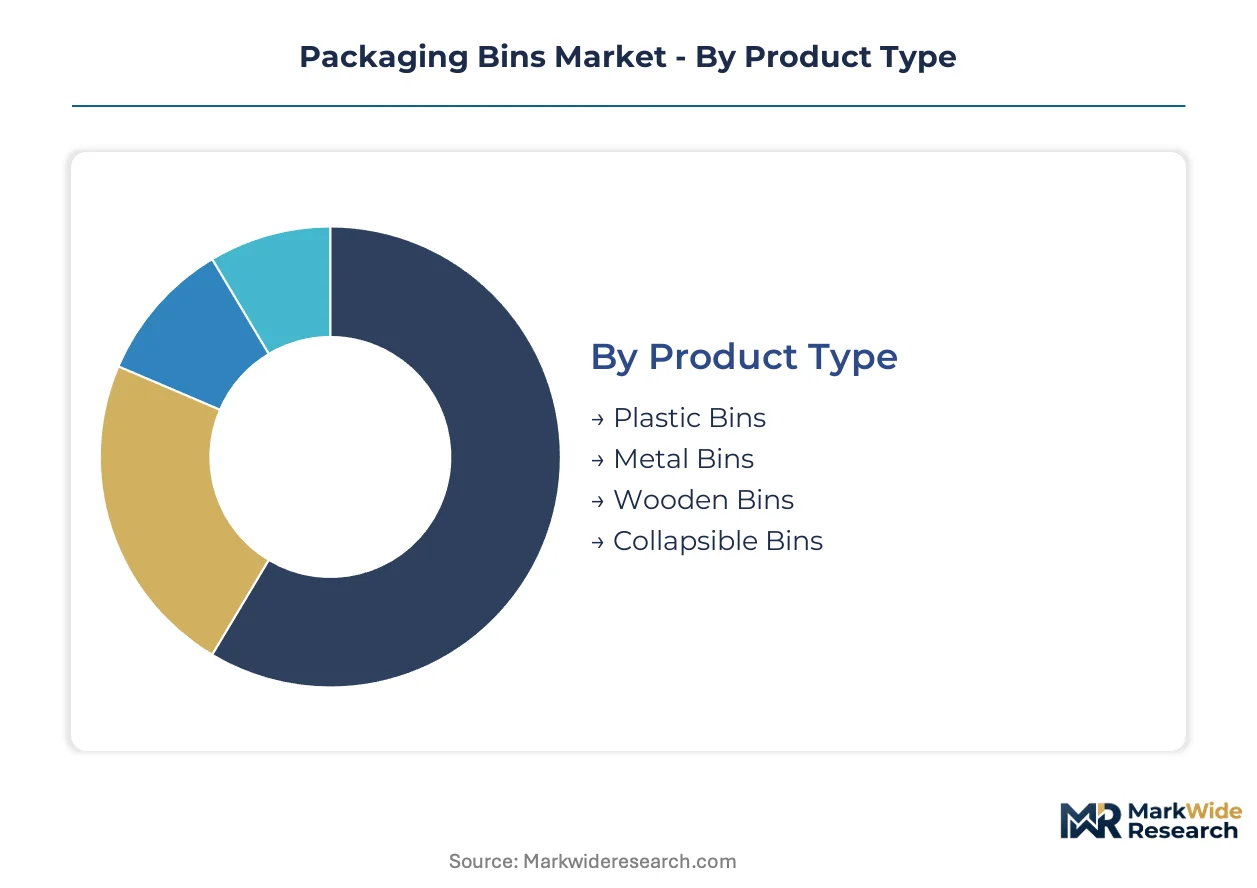
Packaging bins are rigid or semi-rigid containers engineered from thermoplastics, steel, aluminum, or engineered wood composites, typically featuring fork-entry bases, stacking lugs, and volumetric ratings from 20 to 1,500 liters for material handling and storage. Plastic bins dominate unit volume due to rotational molding advances that yield uniform wall thickness and impact resistance for warehouse automation systems. Metal bins retain margin concentration in chemical and pharmaceutical end uses where UN-certified hazardous material containment is mandatory. Collapsible bins represent the fastest-expanding product configuration as retail stores prioritize cube utilization in reverse logistics loops.
The EPA regulates industrial container reuse thresholds under RCRA hazardous waste protocols, while OSHA mandates load-bearing labeling for material handling equipment interoperability. ISO 6780 pallet bin dimensional standards shape cross-border compatibility for exporters serving automated European distribution hubs. Stakeholders must monitor how California SB 54 extended producer responsibility rules cascade into bin take-back and recycled content specifications.
Market Dynamics
E-commerce fulfillment networks are compressing order-to-delivery windows, forcing warehouse operators to redesign material handling flows around collapsible bin architectures that maximize cube density in automated storage and retrieval systems.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability mandates across member states are accelerating demand for mono-material polymer bins that simplify end-of-life sorting and reprocessing.
- Automotive cluster concentration in Germany:Just-in-sequence production lines require standardized intermediate bulk containers with RFID traceability for component tracking from supplier to assembly.
- Rotational molding advances:Uniform wall thickness technology is expanding plastic bin penetration into automated warehouse systems previously served by metal alternatives.
Market Restraints
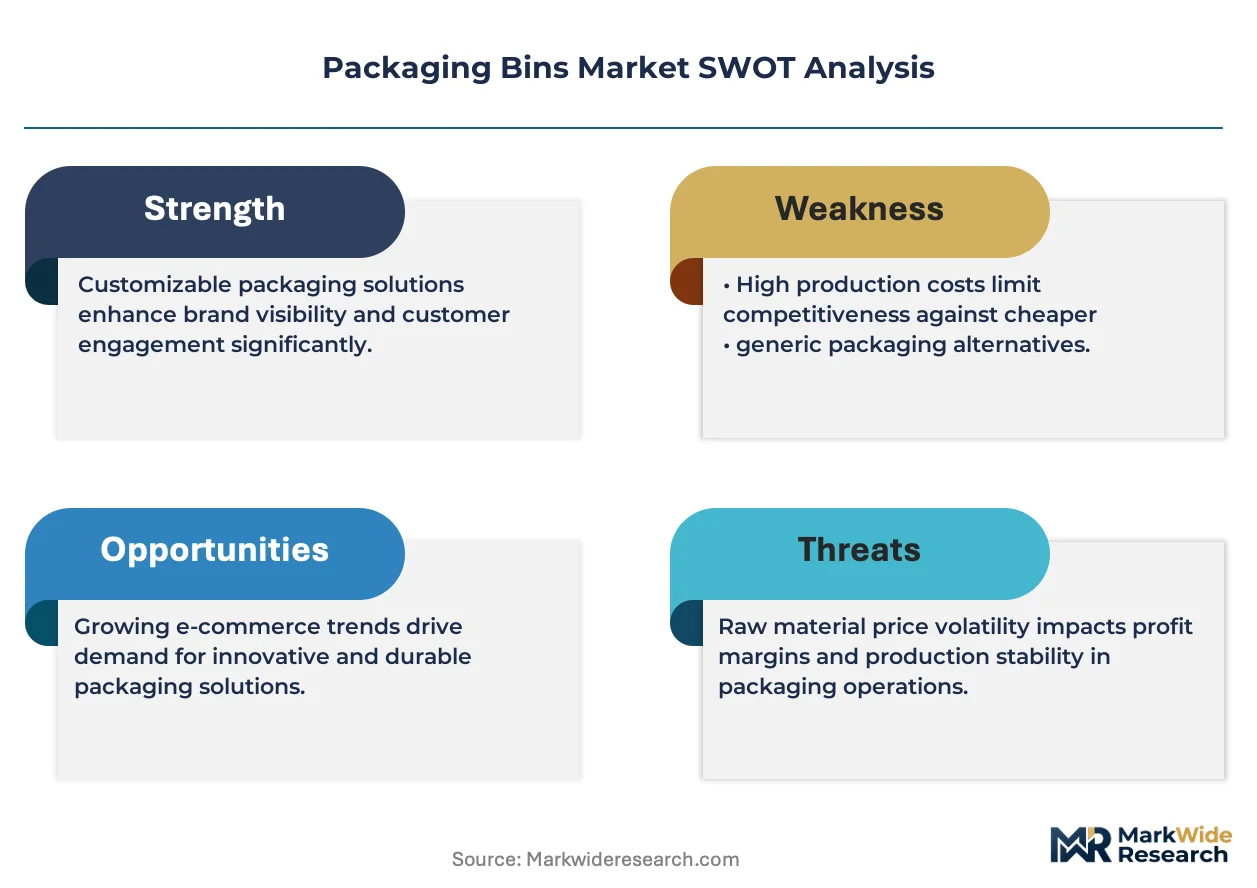
- Polypropylene feedstock volatility:Crude oil price swings directly compress margins for injection-molded bulk container manufacturers serving price-sensitive agricultural buyers.
- Steel drum supply concentration:UN-certified hazardous material containment capacity clusters in legacy industrial corridors, creating bottlenecks for chemical shippers seeking certified metal bins.
- Legacy pallet dimensional incompatibility:ISO 6780 standard adoption gaps between North American and European automation infrastructure force dual inventory holdings for exporters.
Strategic Opportunities
- Reverse logistics white space in retail:Empty collapsible bin return loops remain underoptimized, creating openings for pooling service operators to capture value from big-box store networks.
- California SB 54 extended producer responsibility:Take-back mandates and recycled content floors are creating first-mover advantages for manufacturers with closed-loop collection infrastructure.
- Sensor-embedded bin convergence:Integration of weight and fill-level IoT modules with existing fork-entry bases enables predictive replenishment for pharmaceutical cold chain distributors.
Industry Challenges
- Automation integration complexity:Warehouse management system interoperability gaps force custom API development for bin tracking in multi-vendor robotic environments.
- UN certification timeline compression:Hazardous material testing protocols for new metal bin designs extend product launch cycles beyond customer procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Bins Market |
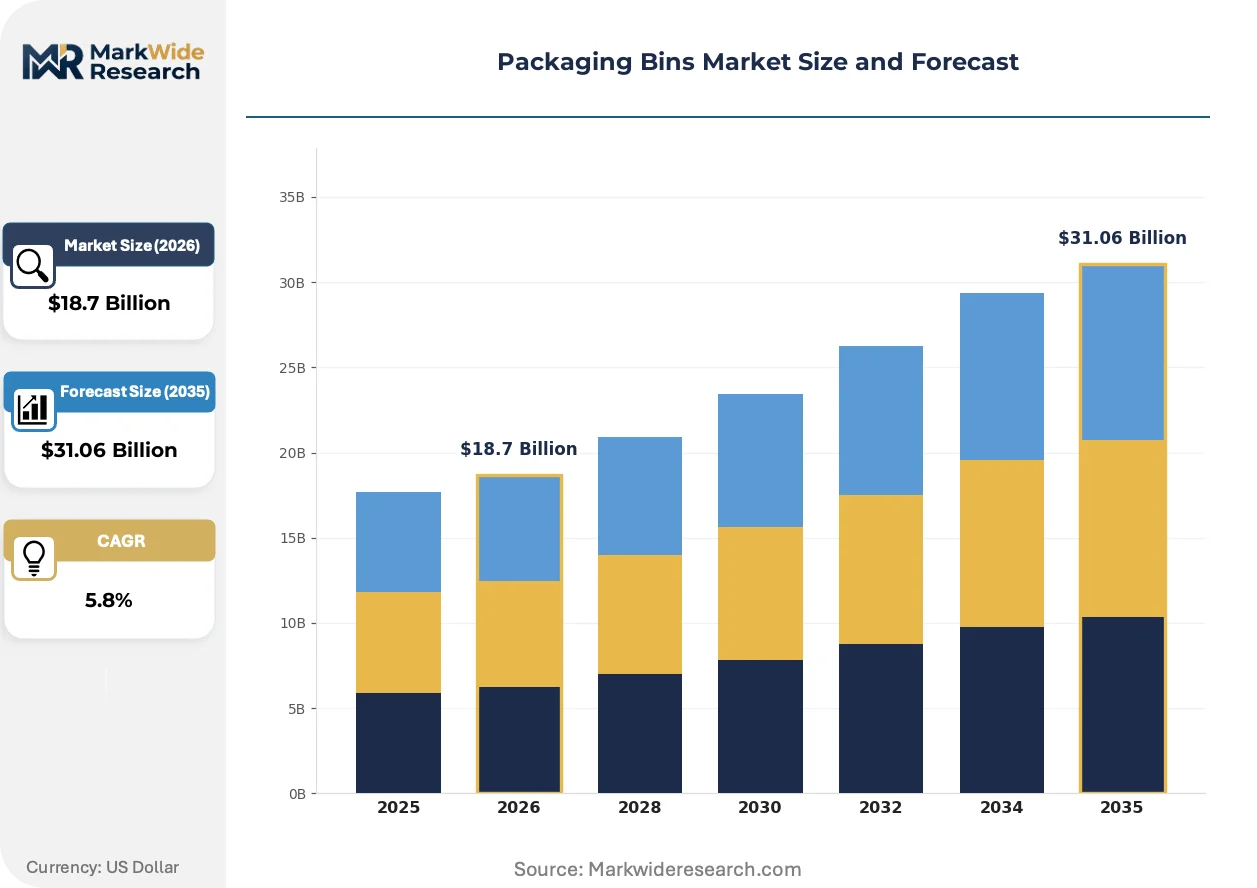
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bins, Metal Bins, Wooden Bins, Collapsible Bins End User: Retail Stores, Warehouses, Manufacturing Facilities, Food Service Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores Size: Small Bins, Medium Bins, Large Bins, Customized Bins |
| Companies Covered | Greif Inc., Berry Global Inc., Mondi Group, Braid Logistics, SIA Flexitanks Ltd., Bemis Company Inc., Signode Industrial Group, National Bulk Equipment, TechnipFMC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Bins Market Evolving Landscape
Material science breakthroughs and regulatory stringency are converging to redefine performance benchmarks across the packaging bins sector, with sustainability metrics now embedded in procurement specifications.
Multi-layer polymer formulations are hybridizing chemical resistance properties with post-consumer recycled content integration, enabling agricultural chemical distributors to meet EPA container management regulations while reducing virgin resin dependence. Formulators are stacking barrier layers with compatibilized regrind cores that maintain UN certification for pesticide transport. The resulting cost-performance profile is compressing market share for single-material alternatives in crop protection logistics.
REACH substance restrictions are forcing reformulation of plasticizers and stabilizers used in high-density polyethylene bins, compelling compounders to validate alternative additive packages against migration limits for food-contact applications. EFSA safety assessments now drive substitution timelines faster than traditional product development cycles. European dairy processors are accelerating supplier qualification processes to lock in compliant container sources ahead of enforcement windows.
Rental and pooling models are displacing outright purchase arrangements among grocery retailers managing seasonal produce volume swings, with third-party operators assuming asset tracking and sanitation liability. This service-layer unbundling shifts capital allocation from balance-sheet bins to per-trip handling fees. German discount supermarket chains are piloting these programs for imported fruit distribution, testing scalability before broader rollout across fresh categories.
Packaging Bins Market Segmentation
Packaging bins serve divergent operational requirements across material handling ecosystems, with product architecture, end-use intensity, and procurement channel each reshaping supplier-customer relationships. Segmentation reveals where standardization yields economies of scale versus where customization commands premium positioning.
Product Type:
Use cases span from lightweight consumer goods handling to hazardous material containment, with material properties dictating automation compatibility and regulatory compliance pathways.
- Plastic Bins:Thermoplastic constructions—primarily high-density polyethylene and polypropylene—deliver uniform wall thickness through rotational molding, yielding impact resistance for automated storage and retrieval systems. Demand concentrates in e-commerce fulfillment centers across Germany and the Netherlands, where cube utilization requirements favor stackable, nestable designs over metal alternatives.
- Metal Bins:Steel and aluminum fabrications provide structural integrity for UN-certified hazardous material transport, with welded seam construction meeting EPA RCRA containment protocols. Chemical manufacturers in the US Gulf Coast and German Rhine-Ruhr corridor require certified intermediate bulk containers for solvent and reagent logistics, creating procurement bottlenecks where testing capacity lags design innovation.
- Wooden Bins:Engineered wood composites and hardwood plywood constructions serve agricultural produce handling where breathability reduces moisture accumulation. European fruit exporters favor ISPM-15 compliant heat-treated designs for phytosanitary clearance.
- Collapsible Bins:Fold-flat designs with hinged side walls maximize return-trip density in reverse logistics loops. Retail grocery networks in California pilot pooling programs to reduce empty-haul costs.
Established volume favors plastic bins; emerging adoption favors collapsible configurations.
End User:
Operational scale and inventory velocity determine durability specifications and replacement cadence across customer categories.
- Retail Stores:Big-box and supermarket operators prioritize lightweight, nestable designs for seasonal merchandise and promotional displays. German discount chains are expanding rental arrangements to convert capital expenditure into per-trip handling fees.
- Warehouses:Automated distribution centers specify dimensional tolerances within millimeters for robotic handling compatibility. Amazon and Zalando fulfillment networks in Poland and Czechia drive standardization around Euro-pallet footprints.
- Manufacturing Facilities:Automotive and electronics assembly lines require RFID-traceable containers for just-in-sequence component delivery. Volkswagen's Wolfsburg operations mandate standardized intermediate bulk containers across Tier-1 supplier networks.
- Food Service:Commercial kitchens and catering operations demand NSF-certified materials with temperature resistance for hot-fill applications. US restaurant chains specify color-coded bins for allergen segregation protocols.
Procurement scale concentrates in warehouses; specification complexity peaks in manufacturing facilities.
Distribution Channel:
Channel selection reflects purchase frequency, technical support requirements, and geographic coverage needs.
- Online Retail:Alibaba and Amazon Business platforms capture standardized, small-lot orders from SMEs seeking rapid delivery without sales engagement. Product content quality and review density drive conversion.
- Direct Sales:Manufacturer account teams manage enterprise contracts with custom specification development, volume pricing, and dedicated inventory programs. Greif and Mondi maintain direct relationships with Fortune 500 industrial accounts.
- Distributors:W.W. Grainger and RS Components stock breadth across sizes and materials, capturing maintenance-repair-operations demand with next-day fulfillment. Geographic density determines market share.
- Specialty Stores:Regional material handling dealers provide application consulting and local service for fleet management and refurbishment. Family-owned distributors in the US Midwest retain loyalty through embedded technical support.
Transaction velocity favors online retail; contract value concentrates in direct sales.
Size:
Volumetric ratings align with handling equipment capacity and storage density optimization.
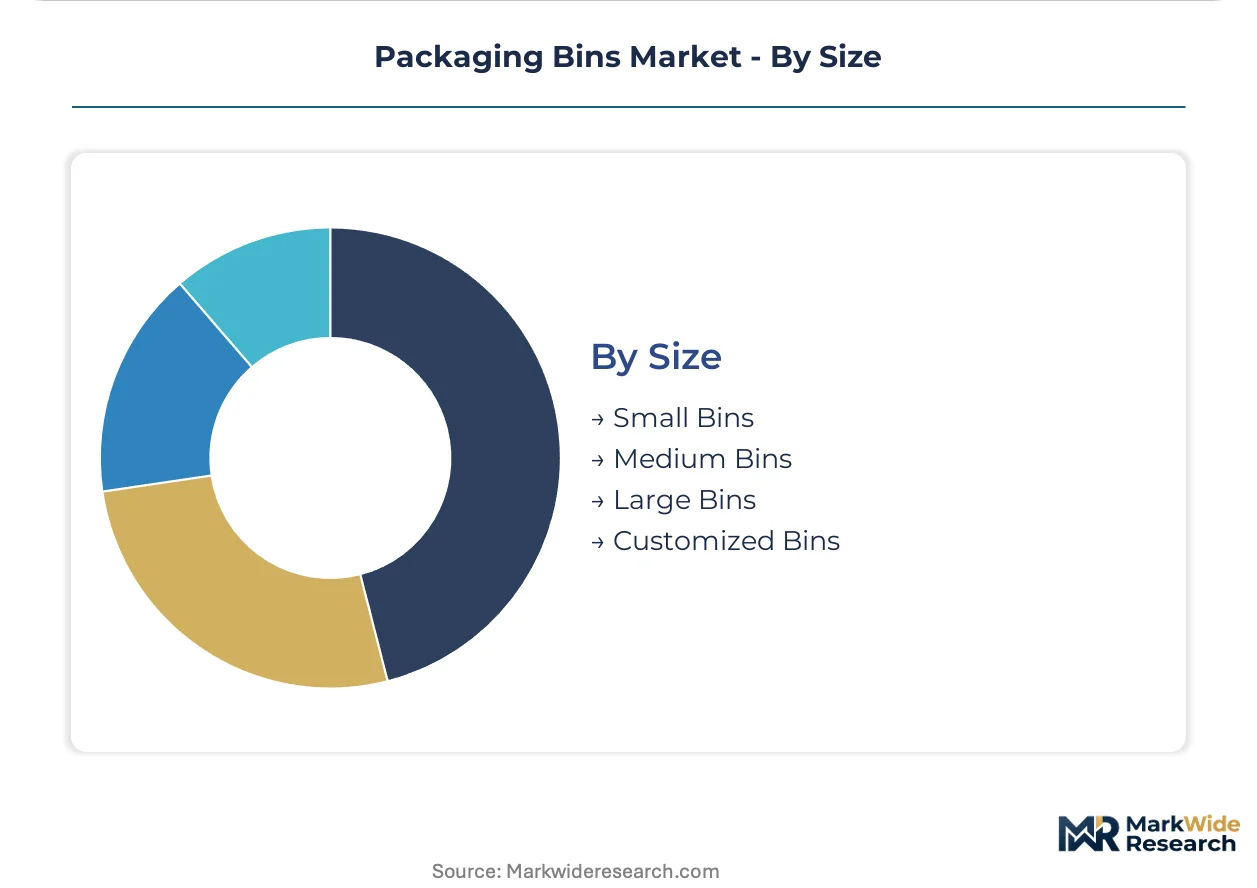
- Small Bins:20-100 liter capacities serve picking operations for high-SKU, low-cube inventory. Pharmaceutical distributors specify small footprints for temperature-controlled van loading.
- Medium Bins:100-500 liter ratings dominate general merchandise handling, balancing manual ergonomics with forklift efficiency. ISO 6780 pallet bin standards govern dimensional compatibility.
- Large Bins:500-1,500 liter intermediate bulk containers handle bulk solids and liquids in chemical and agricultural supply chains. UN certification requirements extend procurement cycles.
- Customized Bins:Application-specific dimensions, apertures, and internal fittings address unique material flow requirements. Aerospace component manufacturers specify anti-static formulations and precision-molded inserts.
Standard sizes capture procurement volume; customization commands engineering engagement premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA container management protocols under RCRA establish the regulatory baseline for industrial packaging reuse thresholds, while EU Packaging and Packaging Waste Regulation recyclability mandates reshape procurement specifications across member states. Demand geography clusters in manufacturing corridors where automotive, chemical, and e-commerce fulfillment networks concentrate.
United States
Gulf Coast chemical manufacturers require UN-certified intermediate bulk containers for solvent logistics, creating procurement bottlenecks where testing capacity lags design innovation. EPA RCRA protocols govern industrial container reuse thresholds and hazardous waste containment standards. Houston and Baton Rouge industrial corridors anchor steel drum demand for petrochemical supply chains.
Germany
Automotive just-in-sequence production lines mandate RFID-traceable standardized containers for component tracking from supplier to assembly. EU Packaging and Packaging Waste Regulation recyclability mandates accelerate mono-material polymer bin adoption. The Rhine-Ruhr corridor and Wolfsburg operations concentrate intermediate bulk container procurement across Tier-1 supplier networks.
China
Expanded injection-molding capacity for plastic bulk containers reconfigures regional supply patterns and export competitiveness. MIIT industrial standards and GB certification requirements shape domestic manufacturing specifications. Yangtze River Delta manufacturing hubs drive rotational molding advances for automated warehouse system compatibility.
Netherlands
E-commerce fulfillment centers prioritize collapsible bin architectures that maximize cube density in automated storage and retrieval systems. REACH substance restrictions force reformulation of plasticizers in high-density polyethylene bins. Rotterdam logistics corridors and Amsterdam distribution hubs concentrate warehouse automation procurement.
India
Agricultural chemical distributors seek cost-performance profiles that balance UN certification requirements with virgin resin reduction targets. BIS standards and FSSAI safety assessments drive supplier qualification timelines. Maharashtra and Gujarat industrial clusters expand injection-molding capacity for domestic bulk container production.
Packaging Bins Market Competitive Landscape
Capability concentration sits with specialized fabricators holding UN certification and automated manufacturing expertise; scale advantage sits with diversified packaging conglomerates leveraging cross-product procurement relationships. The market structures around three tiers: legacy metal drum specialists with hazardous material heritage, polymer compounders with rotational molding scale, and corrugated converters targeting food service compliance. Consolidation pressure runs through M&A activity targeting pooling service operators and capacity expansion in injection-molding for e-commerce fulfillment specifications.
Among North American industrial packaging incumbents, Greif Inc. anchors steel drum networks across manufacturing corridors, while Berry Global Inc. occupies a position within polymer formulation specialists serving agricultural chemical resistance requirements. Mondi Group exemplifies the paper-based corrugated tier targeting food service compliance mandates. These three represent distinct capability anchors: metal heritage, polymer science, and fiber-based sustainability positioning.
| Leading Market Players |
|---|
| Greif Inc. |
| Berry Global Inc. |
| Mondi Group |
| Braid Logistics |
| SIA Flexitanks Ltd. |
| Bemis Company Inc. |
| Signode Industrial Group |
| National Bulk Equipment |
| TechnipFMC |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp logistics corridors transmit freight cost volatility directly into procurement negotiations, compressing margins for injection-molded bulk container suppliers while amplifying price differentiation between UN-certified metal bins and standardized plastic alternatives. Polypropylene feedstock swings and steel drum fabrication bottlenecks concentrate pricing power among legacy hazardous material specialists.
Pricing Analysis
Geographic price spreads between German automotive clusters and US Gulf Coast chemical corridors exceed transportation cost differentials alone, reflecting certification backlog premiums. Three-tier pricing structure across premium UN-certified, standard ISO-compliant, and economy non-certified levels segments buyer willingness-to-pay. Pricing pressure stems from Chinese injection-molding capacity expansion flooding European spot markets with undifferentiated bulk containers. Agricultural distributors exhibit highest price sensitivity due to commodity crop margin compression, while pharmaceutical cold chain operators absorb premiums for sensor-embedded traceability.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculations for rotational molding equipment and virgin resin feedstocks. Manufacturing gravity centers on China, Germany, and the United States for finished bin production, with South Korea and Saudi Arabia anchoring polypropylene pellet supply. Raw material dependencies encompass high-density polyethylene, steel coil, and engineered wood composites. Single-source vulnerability concentrates in UN-certified testing laboratory capacity for metal drum validation. Distribution runs through manufacturer-direct enterprise contracts, distributor stocking programs, and emerging pooling service operators managing collapsible bin fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Packaging bins constitute a defensible moat market where regulatory certification entrenchment and customer switching costs protect incumbent positions. Network effects concentrate among pooling service operators achieving critical mass in return-loop density.
For Market Incumbents: Pre-empt Chinese import competition by accelerating backward integration into recycled resin compounding for California SB 54 compliance. Capture pooling service operators through targeted acquisition before independent networks achieve return-loop density thresholds. Prioritize RFID-traceable container certification for automotive just-in-sequence contracts. For New Entrants and Emerging Players: Build out collapsible bin pooling infrastructure in Netherlands-Belgium e-commerce corridors where cube utilization premiums justify per-trip pricing models. Target mid-sized German automotive Tier-2 suppliers underserved by Greif and Berry Global direct sales organizations. Differentiate through rapid custom tooling turnaround for application-specific dimensions. For Investors and Strategic Acquirers: Sensor-embedded cold chain bin specialists with pharmaceutical validation represent the most attractive acquisition archetype for strategic buyers seeking IoT convergence exposure. Long-term viability hinges on extended producer responsibility regulation proliferation creating closed-loop collection infrastructure value. Watch California SB 54 enforcement intensity and EU Packaging and Packaging Waste Regulation implementation timelines as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Resin Compounding | Secures California SB 54 compliance feedstock ahead of recycled content floor enforcement. |
| Pooling Service Network Expansion | Captures reverse logistics value from Dutch and German retail grocery empty-haul optimization. |
| UN Certification Capacity Addition | Resolves testing bottlenecks for US Gulf Coast chemical manufacturer procurement windows. |
| Sensor-Embedded Bin Development | Enables pharmaceutical cold chain predictive replenishment through weight and fill-level IoT modules. |
| Rotational Molding Automation Investment | Matches Chinese injection-molding cost structures for European automated warehouse penetration. |
Research Methodology
A spread of perspectives from plant managers at automotive assembly facilities, procurement leads at agricultural chemical distributors, technical R&D directors at polymer compounders, and channel partners at industrial supply distributors converged on the working assumptions. Primary interview insights combined with secondary validation from customs and trade data, SEC 10-K filings, and ACC industry reports. Bottom-up shipment data triangulated against top-down manufacturing capacity assessments.
Demand-supply balance dynamics across material grades, end-use industries, and regional production hubs anchored the analytical framework. Segmentation modeling incorporated product architecture, volumetric ratings, and certification tiers throughout the forecast period. CAGRs derived from historical shipment trajectories, capacity expansion announcements, and regulatory enforcement timelines. Industry-specific inputs included e-commerce fulfillment center buildout pipelines and automotive production sequence requirements.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-subsidized injection-molding entrants or rapid pooling service consolidation would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
High Density Polyethylene (HDPE) Bottles Market
Containers
Global Food Storage Container Market
Containers
Collapsible Sleeve Containers Market
Containers
Straight Sided Glass Jar Market
Containers
Multi-Layer Blow Molded Containers Market
Containers
Trays Market
Containers
Carboy Market
Containers
Americas Container Technology Market
Containers
PVC Container Market
Containers
HDPE Containers Market
Containers
Jars Market
Containers
Container Liner Market
Containers
Aluminum Foil Containers Market
Containers
Lever Lid Tinplate Containers Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Slotted Containers Market