
 Foldable Large Containers Market | 2026-2036
Foldable Large Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Foldable Large Containers Market Analytics
Automotive parts logistics is restructuring demand for foldable large containers as just-in-sequence delivery tightens turnaround requirements. ORBIS Corporation leverages proprietary resin formulations to sustain temperature stability across Midwest distribution networks. Schoeller Allibert anchors European automotive supply chains through closed-loop pooling systems. CHEP competes via its shared container network spanning multiple manufacturing corridors.
Foldable large containers are collapsible intermediate bulk handling units, typically engineered from high-density polyethylene or steel framing with composite panel inserts, designed to reduce empty return freight volume by 60-80% versus rigid alternatives. Their primary purpose centers on protecting high-value components through multi-modal transit while minimizing backhaul cube utilization. Plastic containers lead product type adoption due to chemical resistance and weight advantages in food-grade and pharmaceutical logistics, though metal containers retain margin pools in heavy industrial and hazardous material segments. Logistics use cases dominate volume throughput, yet retail display-ready configurations represent the fastest-growing structural opportunity as store replenishment cycles compress.
The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility frameworks that directly incentivize reusable container deployment across member states. FDA food contact material standards govern polyethylene formulations serving North American agriculture and processed food distribution, while ISO 8611 pallet-based testing protocols define load-bearing certification thresholds for international trade acceptance. Stakeholders must monitor evolving mechanical recycling infrastructure capacity and polymer traceability requirements as these regulatory layers increasingly determine market access and total cost of ownership calculations.
Market Dynamics
Automotive OEMs in Germany and China are compressing just-in-sequence delivery windows, forcing container pooling networks to collapse turnaround cycles from weeks to days while maintaining ISO 8611 load-bearing certification across multi-modal handoffs.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility frameworks mandate reusable container deployment across member states, directly accelerating closed-loop adoption in food-grade logistics corridors.
- High-density polyethylene resin formulations:Advanced polymer blends deliver chemical resistance and temperature stability required by FDA food contact material standards, displacing metal alternatives in pharmaceutical distribution.
- East Asian export manufacturing corridors:Concentrated electronics and automotive component production generates sustained demand for collapsible units reducing empty return freight volume by 60-80% versus rigid alternatives.
Market Restraints
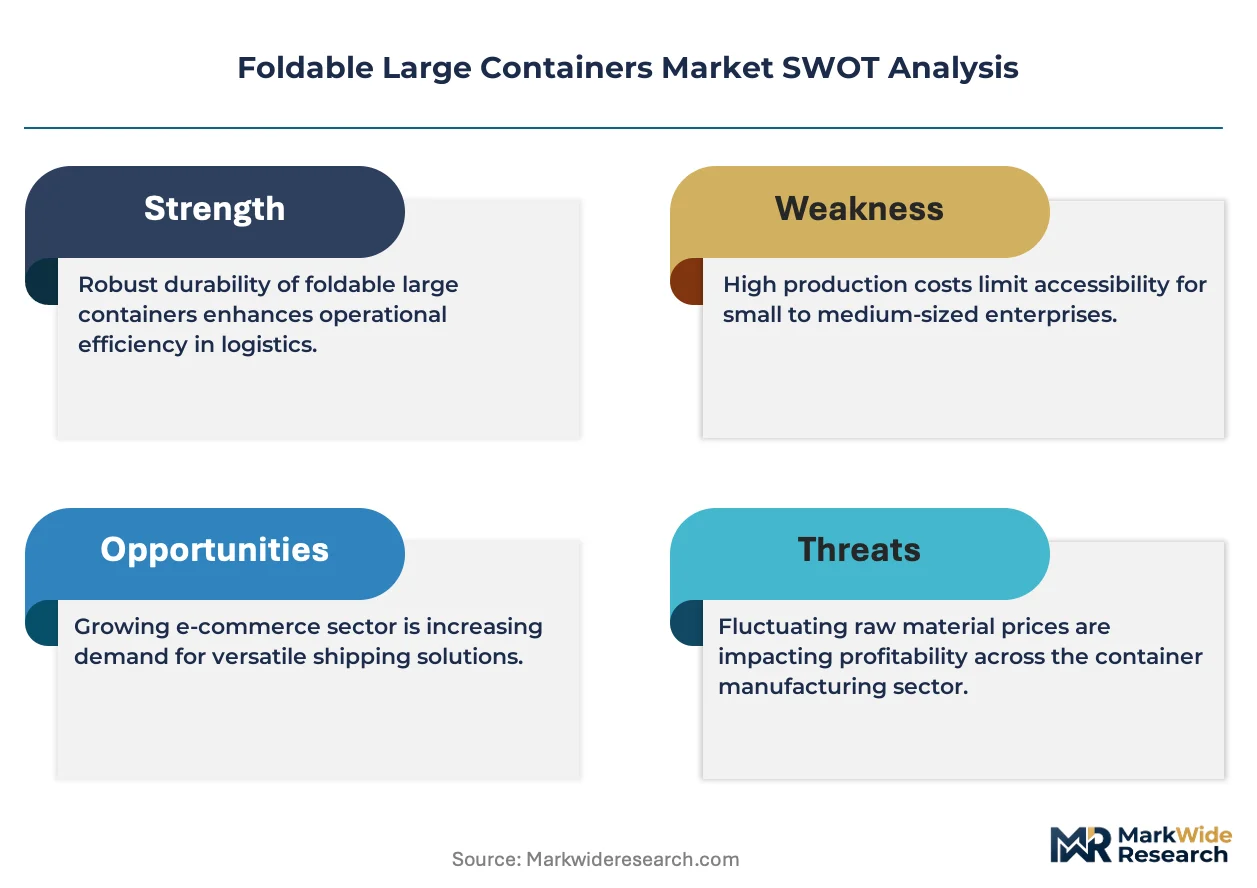
- Polymer feedstock volatility:Crude oil price swings directly compress HDPE resin margins, forcing container manufacturers to absorb input cost spikes or risk contract losses with pooled fleet operators.
- Mechanical recycling infrastructure gaps:Inadequate polymer traceability systems and limited post-consumer reprocessing capacity constrain circular economy claims under tightening EU material recovery targets.
- Steel-framed container substitution in hazardous materials:UN-certified metal units retain regulatory preference for chemical and flammable liquid transport, capping plastic penetration in heavy industrial segments.
Strategic Opportunities
- Retail display-ready configurations:Store replenishment cycle compression creates white space for collapsible units that transition directly from backroom to floor, eliminating secondary handling in grocery and mass merchandise channels.
- India's PLI scheme for logistics infrastructure:Production-linked incentives for cold chain and warehousing investments position the country for foldable container adoption in agricultural export corridors.
- RFID-embedded inventory tracking convergence:Integration of passive sensor arrays with container fleets enables real-time location and condition monitoring, unlocking outcome-based pooling contracts.
Industry Challenges
- ISO 8611 certification timeline compression:Accelerated product development cycles strain testing laboratory capacity, delaying market entry for new container geometries.
- Legacy warehouse management system integration:Container tracking data formats often conflict with established ERP protocols, requiring middleware investment that erodes pooling economics.
- Multi-jurisdiction regulatory divergence:Simultaneous compliance with FDA food contact rules, EU REACH substance restrictions, and China GB standards fragments product line standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foldable Large Containers Market |
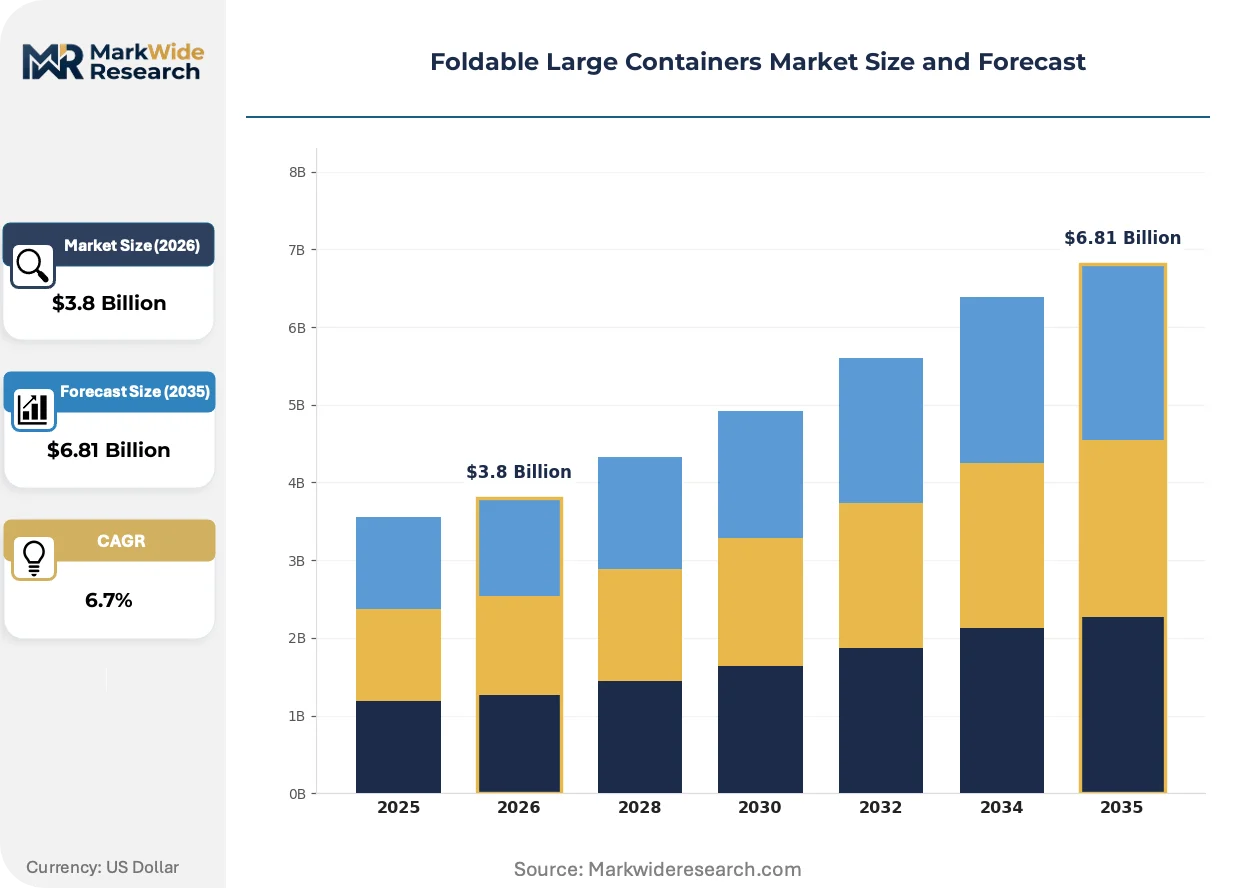
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Containers, Metal Containers, Wooden Crates, Fabric Bags Use Case: Logistics, Retail, Manufacturing, Storage Material: Polyethylene, Steel, Plywood, Composite Materials Distribution Channel: Online Sales, Retail Outlets, Direct Sales, Distributors |
| Companies Covered | Schoeller Allibert, ORBIS Corporation, CHEP, Rehrig Pacific Company, WestRock Company, Compact Container Systems (CCS), RPP Containers, TranPak Inc., SSI SCHÄFER, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foldable Large Containers Market Evolving Landscape
Container architecture is fragmenting into specialized configurations as end-use requirements diverge, with pooling operators and OEM captive fleets pursuing fundamentally different engineering priorities.
Composite panel inserts bonded to steel framing are modularizing container construction, enabling rapid field replacement of damaged sidewalls without full unit retirement. Automotive tier-one suppliers in Stuttgart and Wolfsburg are adopting these hybrid designs for powertrain component circuits. This modularity is compressing total cost of ownership calculations by extending fleet service life beyond traditional replacement cycles.
REACH substance restrictions on persistent organic pollutants are forcing reformulation of flame-retardant additives in polypropylene containers serving electronics manufacturing. Industrial consequences include accelerated R&D spending among European resin compounders and qualification delays for new material grades. Food-contact and pharmaceutical logistics segments are responding fastest, prioritizing additive-free HDPE alternatives to preempt regulatory scrutiny.
Buyers are consolidating container procurement under fleet management contracts that bundle equipment supply with reverse logistics and sanitization services. Third-party pooling operators are displacing direct OEM ownership in German and Chinese automotive supply chains. This consolidation is most visible in Bavaria's dense supplier networks, where CHEP and Schoeller Allibert now manage combined container pools exceeding single OEM captive fleets.
Foldable Large Containers Market Segmentation
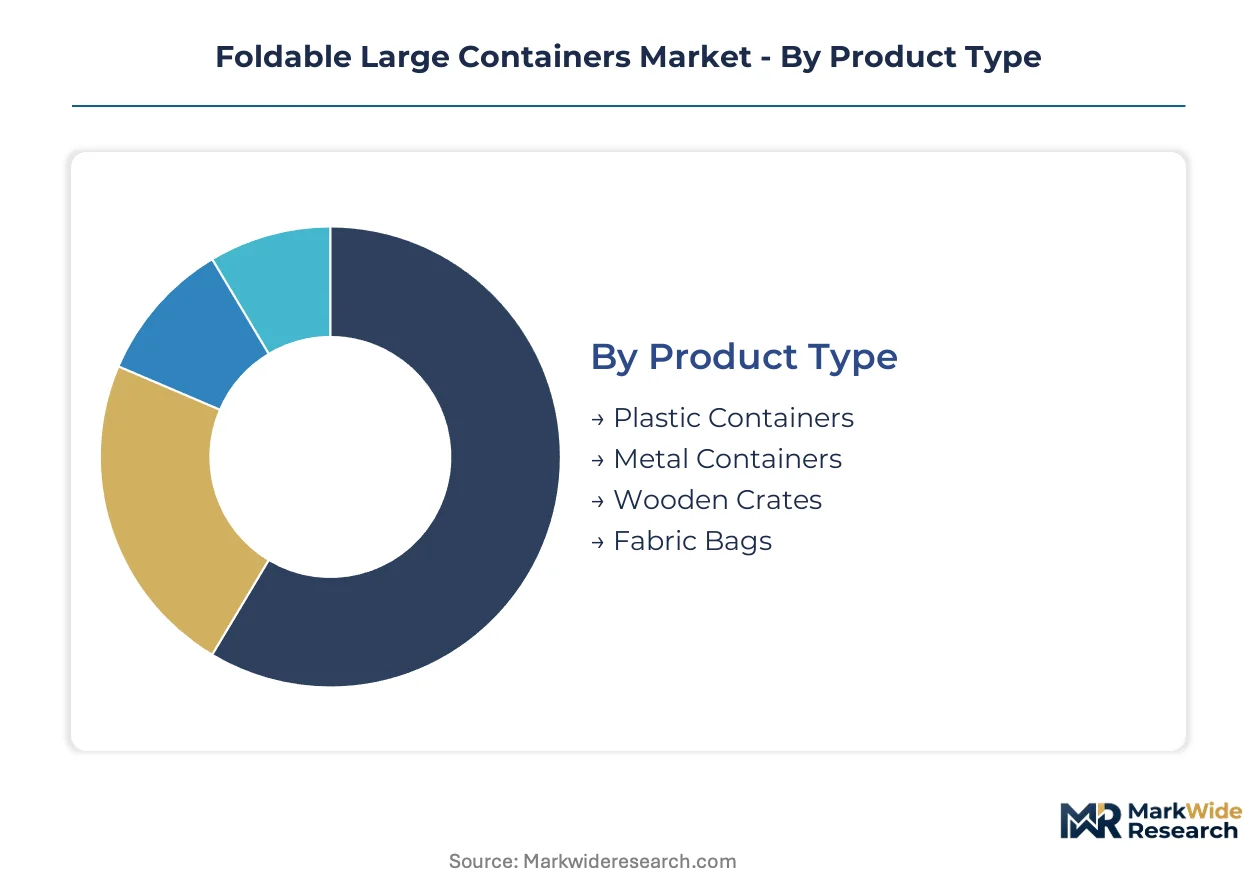
Container procurement patterns diverge sharply across end-use requirements, with pooling operators prioritizing durability cycles while captive OEM fleets optimize for just-in-sequence compatibility. Understanding these segment boundaries clarifies why material formulations and distribution channel strategies vary so dramatically across customer profiles.
Product Type:
Buyers differentiate primarily by load-bearing certification needs and chemical resistance thresholds rather than upfront unit economics.
- Plastic Containers:High-density polyethylene formulations deliver FDA-compliant food contact surfaces and temperature stability across Midwest distribution networks. Automotive OEMs in Germany and China are expanding reusable packaging programs around these units to meet compressed just-in-sequence delivery windows. Plastic containers lead volumes today; metal containers are gaining share fastest in hazardous material segments.
- Metal Containers:Steel framing with composite panel inserts provides UN-certified containment for chemical and flammable liquid transport under REACH substance restrictions. Heavy industrial procurement in Stuttgart and Wolfsburg favors modular hybrid designs enabling rapid sidewall replacement without full unit retirement.
- Wooden Crates:Plywood construction serves agricultural export corridors requiring ISPM-15 phytosanitary compliance for cross-border shipment.
- Fabric Bags:Woven polypropylene collapsible units address lightweight bulk commodity handling in grain and mineral logistics.
Plastic containers dominate pooled fleet deployments; metal variants command premium positioning in regulated industrial corridors.
Use Case:
Application context determines whether containers require RFID-embedded tracking or sanitization protocols between cycles.
- Logistics:Multi-modal transit corridors demand ISO 8611 pallet-based certification for international trade acceptance. East Asian export manufacturing generates sustained demand for units reducing empty return freight volume by 60-80% versus rigid alternatives.
- Retail:Display-ready configurations eliminate secondary handling as store replenishment cycles compress. Grocery and mass merchandise channels in Bavaria's dense supplier networks are transitioning from backroom storage to floor-ready presentation.
- Manufacturing:Powertrain component circuits in Wolfsburg require hybrid steel-composite construction with modular field repair capability.
- Storage:Static warehousing applications prioritize cube utilization over turnaround velocity, accepting heavier wooden or metal alternatives.
Logistics commands the largest installed base; retail configurations are climbing the fastest as omnichannel fulfillment tightens cycle requirements.
Material:
Regulatory jurisdiction directly constrains formulation choices, with EU REACH restrictions diverging from FDA food contact standards.
- Polyethylene:Advanced HDPE resin blends displace metal alternatives in pharmaceutical distribution corridors requiring chemical resistance. REACH substance restrictions on persistent organic pollutants are forcing reformulation of flame-retardant additives in electronics manufacturing segments.
- Steel:Framed construction retains regulatory preference for hazardous material transport under UN certification protocols. Composite panel inserts bonded to steel supports are modularizing field repair economics.
- Plywood:ISPM-15 heat treatment requirements govern agricultural export applications from India and Brazil.
- Composite Materials:Glass-reinforced thermoplastics bridge weight and durability requirements in aerospace component logistics.
Polyethylene dominates food-grade and pharmaceutical volumes; composite materials are expanding most quickly in specialized industrial applications.
Distribution Channel:
Procurement scale and fleet management sophistication determine whether buyers source direct or through intermediaries.
- Online Sales:Digital platforms serve small-lot buyers requiring rapid specification comparison across standardized container geometries. Middleware integration challenges with legacy warehouse management systems constrain adoption among larger operators.
- Retail Outlets:Physical distribution points support immediate replacement needs in agricultural and construction sectors with fragmented demand patterns.
- Direct Sales:OEM captive fleets and third-party pooling operators negotiate fleet management contracts bundling equipment supply with reverse logistics and sanitization services. CHEP and Schoeller Allibert have consolidated procurement under direct relationships in German automotive supply chains.
- Distributors:Regional intermediaries maintain local inventory for construction and food processing segments with irregular replenishment cycles.
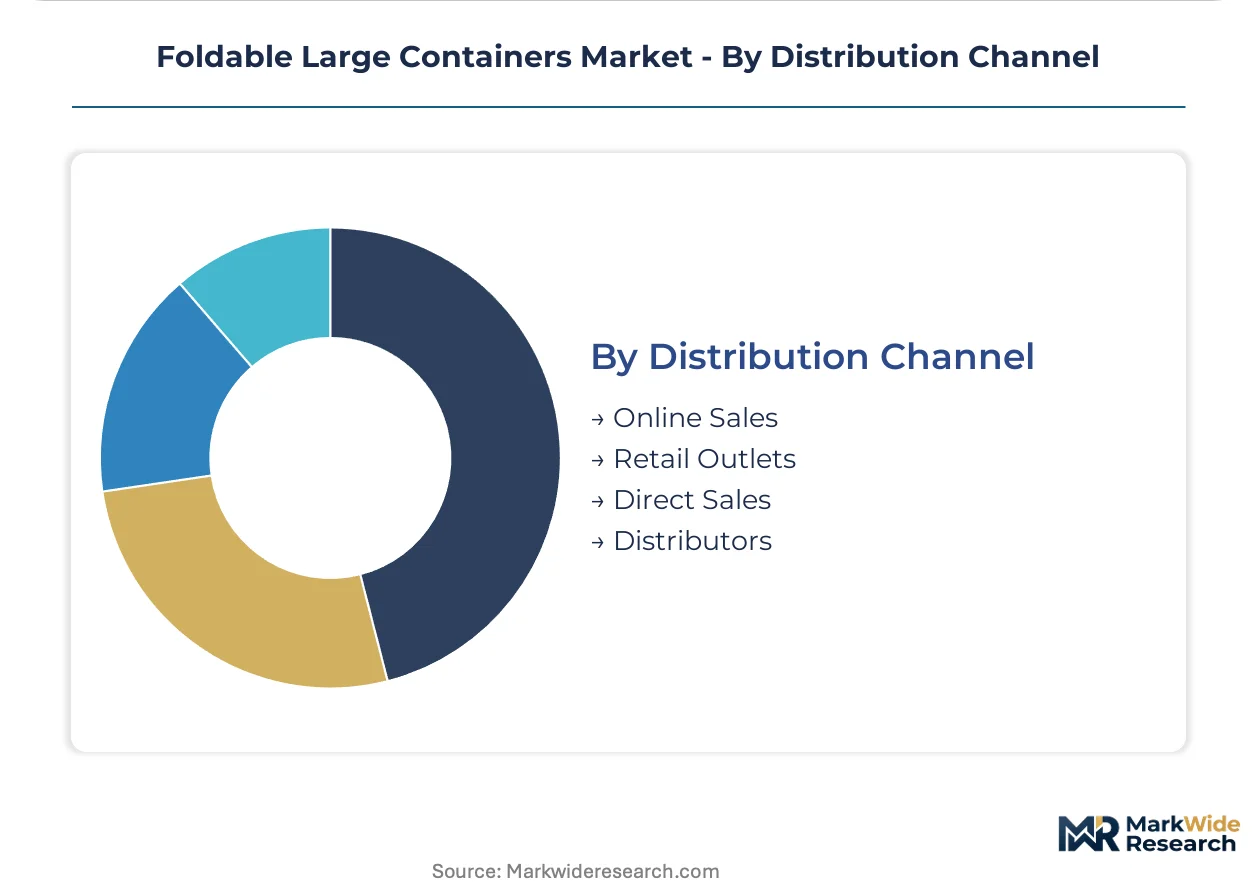
Direct sales anchor large fleet deployments; online channels are gaining traction fastest among mid-market buyers seeking procurement efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian export manufacturing corridors generate sustained demand for collapsible units that reduce empty return freight volume by 60-80% versus rigid alternatives. Automotive OEMs in Germany and China are compressing just-in-sequence delivery windows, forcing container pooling networks to collapse turnaround cycles from weeks to days.
China
Electronics and automotive component production in the Pearl River Delta and Yangtze River Delta sustains dense container pooling networks. GB standards for load-bearing certification govern multi-modal transit acceptance across domestic corridors. Shenzhen and Suzhou manufacturing clusters are transitioning from rigid to foldable units to optimize backhaul cube utilization in export logistics.
Germany
Automotive OEMs in Stuttgart and Wolfsburg are expanding reusable packaging programs to meet compressed just-in-sequence delivery requirements. EU Packaging and Packaging Waste Regulation mandates extended producer responsibility frameworks that directly accelerate closed-loop adoption. Bavaria's dense supplier networks now host combined container pools exceeding single OEM captive fleets.
United States
Midwest distribution networks serving processed food and pharmaceutical corridors demand FDA food contact material compliance in polyethylene formulations. Temperature stability requirements across seasonal freight cycles favor proprietary resin blends. Chicago and Detroit logistics hubs are consolidating procurement under fleet management contracts bundling equipment supply with reverse logistics services.
India
Agricultural export corridors are positioning for foldable container adoption through PLI scheme incentives for cold chain and warehousing investments. BIS standards for material certification are converging with international trade acceptance protocols. Maharashtra and Gujarat agricultural processing clusters are piloting collapsible units for grain and processed food distribution to reduce secondary handling costs.
Japan
Precision electronics manufacturing in Kanto and Kansai regions generates demand for additive-free HDPE alternatives that preempt REACH-style regulatory scrutiny. METI guidelines on circular economy infrastructure are accelerating polymer traceability system deployment. Osaka automotive tier-one suppliers are adopting hybrid steel-composite designs with modular field repair capability for powertrain component circuits.
Foldable Large Containers Market Competitive Landscape
Strategic partnerships dominate the current landscape as pooling operators and resin compounders align to secure formulation supply and fleet management contracts. The vendor base clusters around three distinct strategic archetypes: third-party pooling networks, OEM captive fleet operators, and specialized resin formulation suppliers. Consolidation pressures are intensifying as CHEP and Schoeller Allibert displace direct OEM ownership in dense automotive supply chains. Portfolio diversification into retail display-ready configurations represents the second dominant competitive vector as store replenishment cycles compress.
Within the European pooling operator tier, Schoeller Allibert anchors closed-loop systems across German automotive supply chains. ORBIS Corporation exemplifies the resin-integrated North American fabricator archetype, while CHEP occupies the scale-driven shared network position spanning multiple manufacturing corridors. These three entities represent fundamentally different competitive positions: formulation control versus geographic density versus pooled asset velocity.
| Leading Market Players |
|---|
| Schoeller Allibert |
| ORBIS Corporation |
| CHEP |
| Rehrig Pacific Company |
| WestRock Company |
| Compact Container Systems (CCS) |
| RPP Containers |
| TranPak Inc. |
| SSI SCHÄFER |
| Others |
Value Network & Pricing Analysis
Resin formulation advances in high-density polyethylene are simultaneously compressing production costs and concentrating supplier power among compounders with proprietary temperature-stability blends. Automotive OEMs in Germany and China now bundle fleet management contracts that internalize pricing volatility through long-term offtake agreements.
Pricing Analysis
Input-cost pass-through from crude oil-linked HDPE resin feeds directly into contract renegotiation cycles between container manufacturers and pooled fleet operators. Pricing stratifies across ISO 8611-certified premium tiers, FDA food-contact standard tiers, and uncertified economy tiers. Cost compression in economy-grade plastic containers is intensifying because polymer feedstock volatility forces margin absorption. Small-lot buyers through online channels exhibit highest price sensitivity; third-party pooling operators with fleet management contracts show lowest sensitivity due to bundled service economics.
Supply Chain Analysis
Workforce availability constraints in German automotive manufacturing clusters and Chinese electronics corridors are pushing container fabrication toward automated molding facilities in Poland and Vietnam. Raw material supply draws from Saudi Arabian and U.S. Gulf Coast ethylene crackers, German automotive-grade steel mills, and Chinese composite panel manufacturers. Single-source vulnerability concentrates in specialized resin formulations serving FDA-compliant pharmaceutical logistics. Distribution feeds from regional molding facilities through third-party pooling operators and direct OEM captive fleet contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in foldable large containers rests on premium-tier consolidation in automotive just-in-sequence applications and resin cost-down curves displacing metal alternatives.
For Market Incumbents: Anchor closed-loop pooling density in Bavaria's automotive supplier networks against displacement by CHEP's shared asset velocity. Defend formulation control through backward integration into HDPE resin compounding. Prioritize ISO 8611 certification investment to compress testing laboratory bottlenecks delaying competitor market entry. For New Entrants and Emerging Players: Mid-market retail grocery buyers seeking display-ready configurations represent the most penetrable white-space target. India's PLI-scheme cold chain investments offer geographic entry with lower incumbent saturation. Pursue outcome-based pooling contracts bundling RFID-embedded tracking with equipment supply. For Investors and Strategic Acquirers: Roll-up economics work for regional pooling operators with captive automotive relationships because OEM consolidation is displacing direct fleet ownership. Five-to-ten year viability favors assets with reverse logistics infrastructure and sanitization service capabilities. Monitor EU Packaging and Packaging Waste Regulation enforcement intensity as inflection indicator for closed-loop adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Resin Formulation Backward Integration | Proprietary HDPE blends lock in temperature stability margins against commodity resin volatility. |
| RFID-Embedded Fleet Deployment | Passive sensor arrays enable real-time location contracts with automotive OEMs in Stuttgart. |
| Retail Display-Ready Configuration Launch | Floor-ready units eliminate secondary handling in Bavaria's grocery replenishment corridors. |
| India PLI Scheme Cold Chain Partnership | Production-linked incentives accelerate agricultural export container adoption in Maharashtra. |
| EU Closed-Loop Pooling Network Expansion | Extended producer responsibility mandates directly accelerate reusable container deployment. |
Research Methodology
Coverage spans Germany, China, the United States, India, and Japan, with primary inputs from each market's automotive OEM procurement directors, third-party pooling fleet managers, resin compounder technical R&D leads, and retail grocery supply chain planners. Secondary validation draws from EU Packaging and Packaging Waste Regulation filings, FDA food contact material guidance documents, ISO 8611 testing protocol records, and customs trade data on HDPE resin flows. Bottom-up container shipment estimates triangulate against top-down automotive production and retail square footage expansion metrics.
Rate-of-change decomposition separates volume growth into replacement cycle compression, new fleet penetration, and average container size expansion across the projection horizon. Segmentation dimensions include product type, use case, material formulation, and distribution channel complexity. CAGRs derive from logistic curve fitting to historical adoption patterns in automotive and retail verticals, with explicit modeling of EU regulatory phase-in schedules and India's PLI scheme disbursement timelines.
Underlying measurement precision varies by segment; automotive OEM captive fleet data carry tighter precision than fragmented agricultural buyer estimates. Forecasts reflect assumptions on resin price normalization, ISO laboratory capacity expansion, and RFID sensor cost curves. Material deviation in EU enforcement intensity, crude oil volatility spikes, or India's cold chain buildout pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Compartment Take-Out Container Market
Containers
Thin Wall Plastic Containers Market
Containers
Latin America Intermediate Bulk Container Liner Market
Containers
Dispensing Jug Market
Containers
Laminated Bulk Bins Market
Containers
Metal Cans and Glass Jars Market
Containers
Pinch Grip Jars Market
Containers
Wire Containers Market
Containers
HDPE Containers Market
Containers
Container Stacking Machine Market
Containers
Pail Lids Market
Containers
Rotomolded Containers Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
Cylindrical Cans Market
Containers
Sanitary Cans Market
Containers
Snap-Lock Container Market