
 Mobile Phone Accessories Packaging Market | 2026-2036
Mobile Phone Accessories Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Phone Accessories Packaging Market Outlook
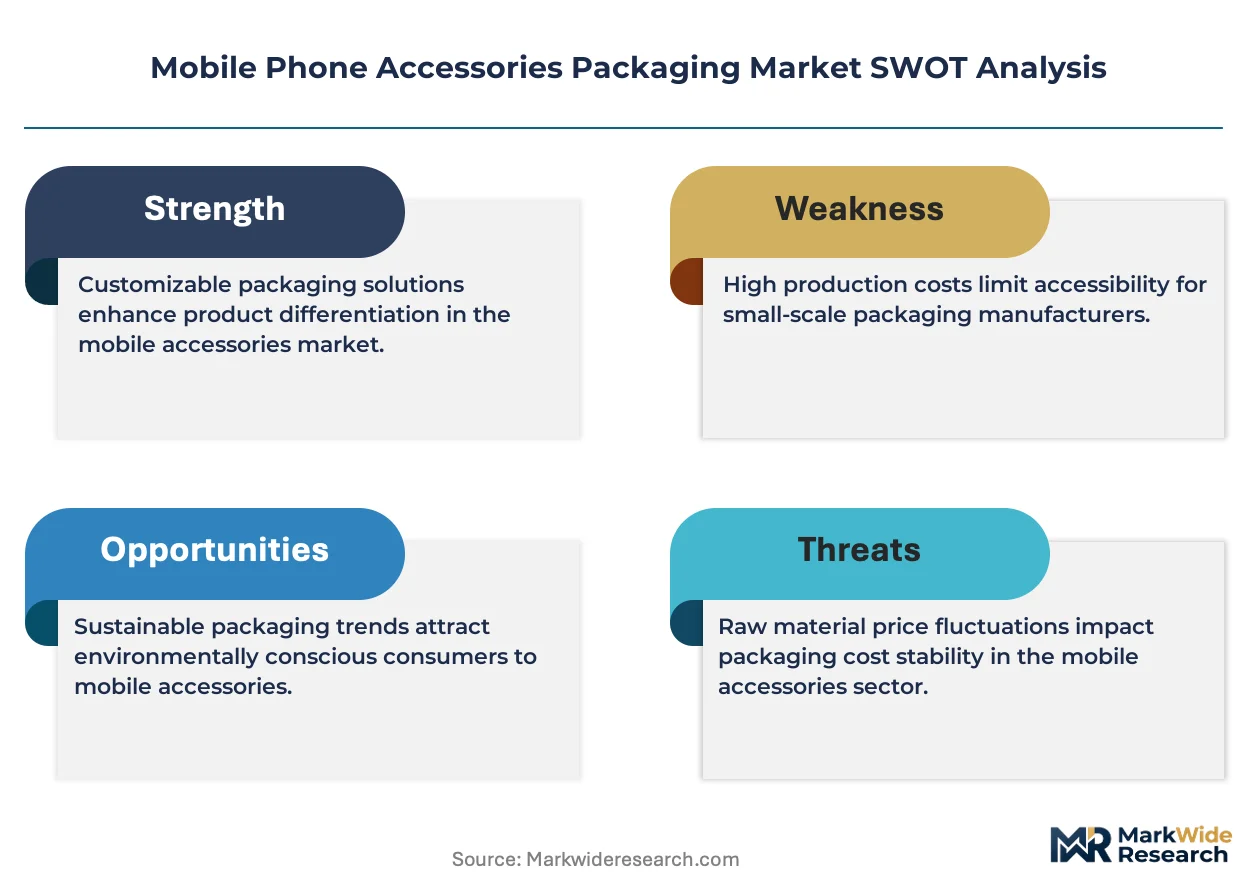
E-commerce buyers are rotating toward premium unboxing experiences that reduce return damage rates. PakFactory specializes in customizable rigid box formats for direct-to-consumer brands. WestRock dominates North American corrugated supply with integrated paperboard mills. Sealed Air extends its protective packaging portfolio through engineered foam inserts tailored for fragile accessories.
Mobile phone accessories packaging encompasses protective enclosures designed to shield chargers, cables, cases, and earbuds during transit and retail display, typically employing multi-layer constructions with specified burst strengths and die-cut precision for dimensional stability. Blister pack formats retain dominance in big-box retail for their theft-deterrent visibility and hanging display compatibility, while pouch configurations capture fastest growth in e-commerce fulfillment for their weight reduction and postal efficiency. Paperboard substrates command the largest material share among sustainability-oriented brands, though metalized film maintains premium positioning for luxury accessory lines requiring moisture and oxidation barriers.
FDA guidelines for indirect food-contact materials influence packaging specifications for accessories bundled with edible promotional items, while EPA frameworks on recycled content thresholds shape domestic supplier qualification requirements. California's extended producer responsibility statutes and New York's pending packaging reduction mandates add state-level compliance layers beyond federal baselines. Stakeholders must monitor how fragmented state regulations consolidate into de facto national standards that reshape material sourcing and design specifications.
Market Dynamics
E-commerce fulfillment networks are compressing packaging specifications toward gram-level weight targets while China's GB standards and EU packaging waste directives tighten material compliance across export supply chains.
Growth Catalysts
- EU Green Deal packaging mandates:Brussels' 2030 recyclability targets are forcing brands to redesign accessory enclosures for mono-material recovery streams.
- Guangdong electronics cluster density:Shenzhen and Dongguan manufacturers generate continuous procurement pull for protective formats serving 400+ million annual smartphone accessory shipments.
- Molded fiber engineering:Advanced pulp molding is displacing petroleum-based trays in premium unboxing experiences for direct-to-consumer brands.
Market Restraints
- Aluminum oxide price volatility:Metalized film barrier layers face input cost swings that compress margin on luxury accessory lines.
- Guangdong supplier concentration:Seventy percent of rigid box capacity sits within 200 kilometers of Shenzhen, creating single-point vulnerability.
- REACH SVHC disclosure thresholds:European chemical registration complexity extends compliance timelines for printed substrates by four to six months.
Strategic Opportunities
- India BIS packaging standards harmonization:New Delhi's alignment with ISO 14021 self-declared environmental claims creates first-mover advantage for certified suppliers.
- Pharmacy retail channel expansion:CVS and Walgreens are adding mobile accessory aisles requiring theft-deterrent blister formats with child-resistant features.
- Near-infrared sortable inks:Integration of NIR-detectable pigments with paperboard substrates enables automated recycling separation at European MRFs.
Industry Challenges
- Structural packaging engineer scarcity:Finite talent pools in folded carton design and finite element analysis constrain rapid format development.
- GB standards transition timelines:China's 2024 packaging intensity limits require retroactive redesign of 12,000+ SKUs within 18-month windows.
- Legacy ERP integration friction:Specification management systems lack API connectivity to supplier sustainability certification databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Phone Accessories Packaging Market |
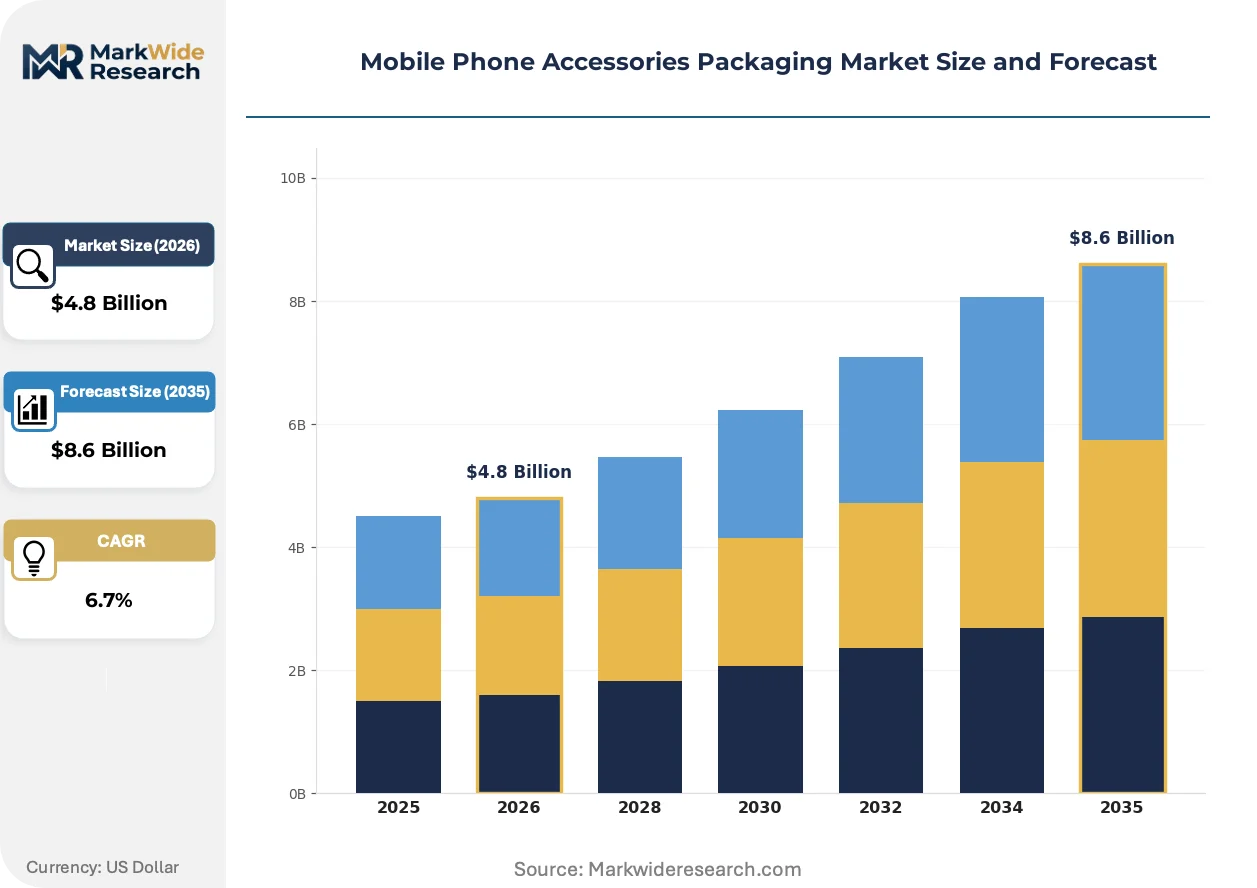
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Blister Pack, Box Packaging, Pouch, Sleeve Material: Plastic, Paperboard, Foam, Metalized Film End User: Retailers, Distributors, Manufacturers, E-commerce Design Type: Eco-friendly, Customizable, Promotional, Standardized |
| Companies Covered | Sealed Air, PakFactory, International Paper Co., Sticker Mule, Packlane, WestRock, Impack, Bespoke Boxes Co., Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Phone Accessories Packaging Market Strategic Shifts
Active reshaping in this market centers on material science breakthroughs, regulatory compliance automation, and fulfillment-network optimization driving format miniaturization.
Water-based barrier coatings are decomposing the historical dominance of polyethylene-laminated paperboard in moisture-sensitive accessory packaging. Amazon's vendor certification program is accelerating adoption among third-party sellers facing ISTA 3A drop-test requirements. This chemistry shift is compressing capital allocation toward aqueous dispersion R&D while marginalizing extrusion lamination equipment.
Brussels' Packaging and Packaging Waste Regulation revision is mandating design-for-recycling criteria across all EU-placed goods by 2030. The industrial consequence forces accessory brands to eliminate dark pigments and adhesives that contaminate repulping streams. Premium audio and wearable segments are responding fastest, with Bang & Olufsen and Apple suppliers already submitting mono-material prototypes for PRE recyclability assessment.
Direct-to-consumer brands are consolidating procurement around packaging-as-a-service models that bundle design, inventory, and fulfillment logistics. This displaces traditional spot-buying of pre-made boxes through wholesale distributors. The shift is most visible in North American e-commerce, where Shopify-integrated 3PLs now specify dimensional weight-optimized formats at contract inception.
Mobile Phone Accessories Packaging Market Segmentation
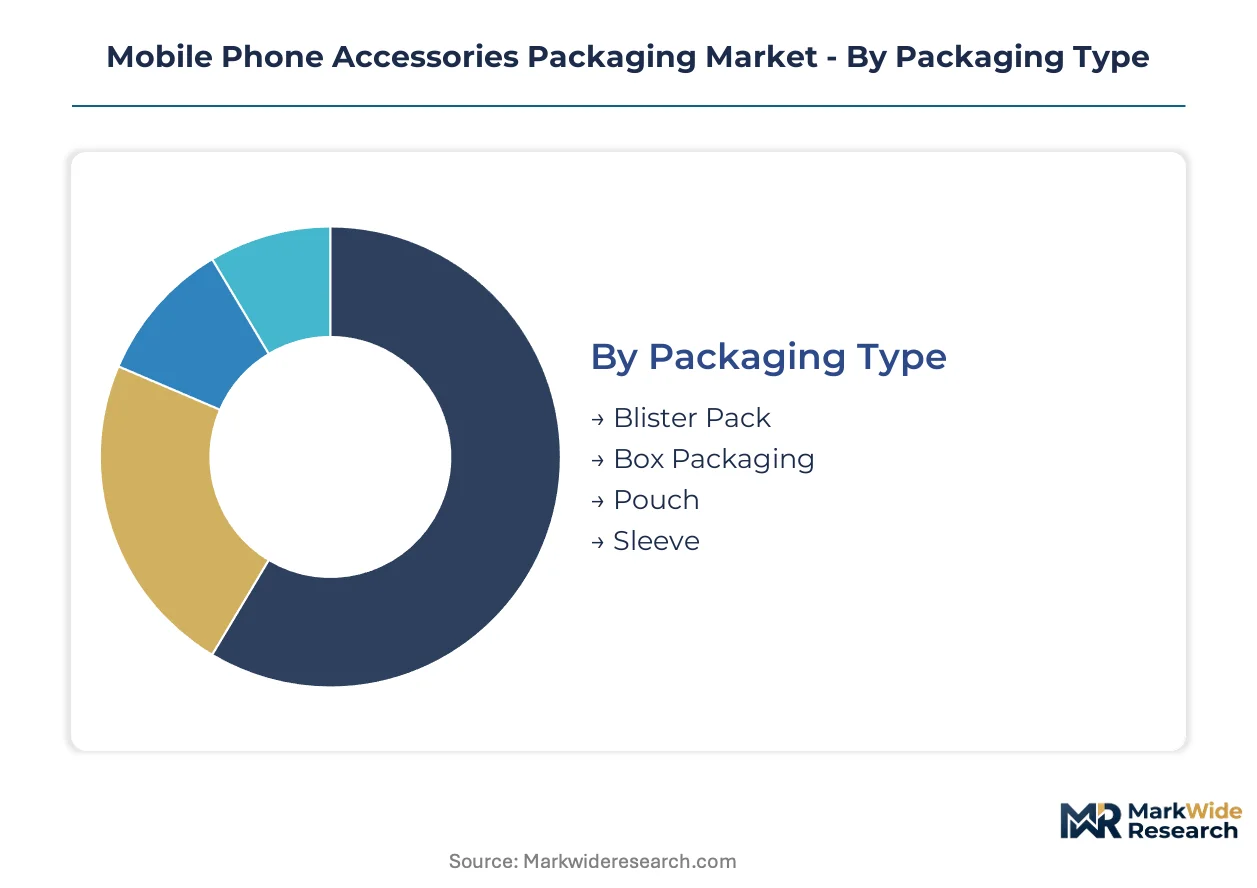
Format selection in mobile phone accessories packaging determines damage rates, unboxing conversion, and regulatory compliance across divergent fulfillment channels. Material and design specifications must reconcile e-commerce gram-weight targets with retail theft-deterrence requirements.
Packaging Type:
Blister pack formats face acute substitution pressure from pouch configurations as Amazon and Shopify-integrated 3PLs compress dimensional weight specifications.
- Blister Pack:Thermoformed PVC or PET cavities bonded to printed card stock deliver theft-deterrent visibility and hanging display compatibility. Walmart and Target electronics aisles in the US sustain procurement volumes despite e-commerce headwinds.
- Box Packaging:Rigid or folding carton constructions with specified burst strengths protect premium accessories during international transit. Guangdong manufacturers specify die-cut precision for 400+ million annual smartphone accessory shipments.
- Pouch:Flexible film or kraft constructions minimize postal weight for direct-to-consumer fulfillment. Amazon's vendor certification program accelerates adoption among third-party sellers facing ISTA 3A drop-test requirements.
- Sleeve:Partial enclosures for cable and charger bundling with minimal material overhead. Electronics OEMs in Shenzhen specify sleeve formats for accessory kits bundled with device purchases.
Blister pack retains volume leadership in big-box retail; pouch holds the steepest expansion curve in e-commerce fulfillment.
Material:
Cost tier stratification separates commodity substrates from engineered barrier solutions serving luxury positioning.
- Plastic:Polyethylene and polypropylene films dominate blister thermoforming and flexible pouch constructions. EU Packaging and Packaging Waste Regulation revisions are forcing redesign for mono-material recovery streams.
- Paperboard:Uncoated and clay-coated grades command procurement pull from sustainability-oriented brands. Water-based barrier coatings are displacing polyethylene-laminated constructions in moisture-sensitive applications.
- Foam:Polyethylene and polyurethane inserts deliver engineered protection for fragile accessories. Sealed Air extends portfolio development through molded foam geometries tailored for earbuds and chargers.
- Metalized Film:Aluminum oxide barrier layers provide moisture and oxidation protection for premium audio lines. Input cost volatility compresses margin on luxury accessory packaging.
Paperboard captures procurement volume from sustainability mandates; metalized film maintains the highest margin tier.
End User:
Customer type determines specification complexity, with e-commerce platforms imposing the most stringent dimensional weight and drop-test protocols.
- Retailers:Big-box chains specify theft-deterrent formats with hanging tab compatibility and shelf-ready presentation. CVS and Walgreens pharmacy expansions into mobile accessories require child-resistant blister features.
- Distributors:Wholesale intermediaries prioritize palletization efficiency and mixed-SKU container loading. Procurement concentrates on standardized box dimensions for cross-brand consolidation.
- Manufacturers:OEM bundling operations specify accessory kit configurations matched to device launch cycles. Guangdong cluster density generates continuous packaging procurement pull.
- E-commerce:Direct-to-consumer fulfillment networks drive gram-level weight minimization and automated packaging line compatibility. Packaging-as-a-service models consolidate design, inventory, and logistics procurement.
E-commerce end users are expanding procurement fastest; retailers sustain the largest absolute volume.
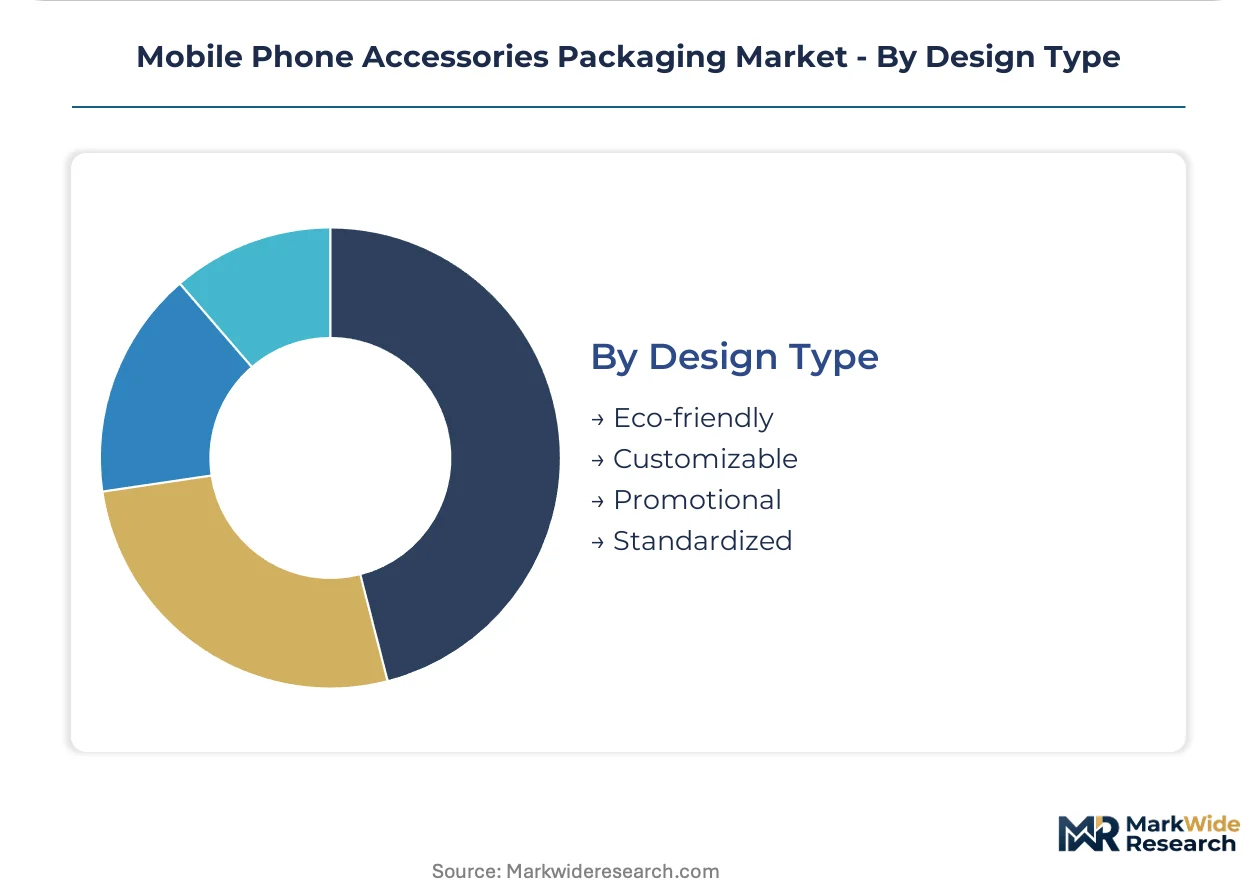
Design Type:
Maturity gradients separate established eco-friendly specifications from emerging customizable formats serving unboxing economics.
- Eco-friendly:Recycled content thresholds and mono-material constructions address EU Green Deal recyclability targets. California extended producer responsibility statutes add compliance layers beyond federal baselines.
- Customizable:Rigid box formats with premium finishing support direct-to-consumer brand differentiation. PakFactory specializes in configurable constructions for Shopify-integrated merchants.
- Promotional:Limited-edition graphics and bundled gift configurations serve seasonal campaign cycles. FDA indirect food-contact guidelines influence specifications for edible promotional item pairings.
- Standardized:Generic formats minimize unit costs for commodity accessory lines. WestRock corrugated supply dominates North American volume procurement through integrated paperboard mills.
Standardized design retains cost-driven volume leadership; customizable formats are climbing the fastest as unboxing experience investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-commerce fulfillment networks and electronics manufacturing clusters concentrate buyer procurement across distinct geographies, with regulatory frameworks diverging sharply between export-oriented production zones and consumption-heavy import markets.
China
Guangdong province generates the densest packaging procurement pull globally, with Shenzhen and Dongguan manufacturers shipping 400+ million smartphone accessories annually. GB standards from SAMR impose 2024 packaging intensity limits requiring retroactive redesign of 12,000+ SKUs within compressed 18-month windows. The Pearl River Delta cluster anchors rigid box capacity, with seventy percent of specialized production sitting within 200 kilometers of Shenzhen.
United States
Amazon's vendor certification program and ISTA 3A drop-test requirements reshape procurement specifications for third-party sellers. EPA frameworks on recycled content thresholds filter domestic supplier qualification, while California's extended producer responsibility statutes and New York's pending packaging reduction mandates add state-level compliance layers. WestRock's integrated paperboard mills dominate corrugated supply through captive fiber sourcing.
Germany
EU Green Deal packaging mandates from Brussels force accessory brands toward mono-material recovery streams and PRE recyclability assessment. ECHA's REACH SVHC disclosure thresholds extend compliance timelines for printed substrates by four to six months. Industrial concentration in Baden-Württemberg and North Rhine-Westphalia supports premium audio packaging engineering for Bang & Olufsen suppliers.
India
BIS packaging standards harmonization with ISO 14021 self-declared environmental claims creates first-mover positioning for certified suppliers. The PLI scheme for electronics manufacturing is pulling accessory production away from pure import dependence. Maharashtra and Gujarat industrial corridors are developing domestic rigid box capacity to serve emerging smartphone assembly operations.
Japan
METI circular economy guidelines and JIS standards shape high-barrier packaging specifications for premium wearable segments. Domestic brands prioritize mono-material constructions ahead of anticipated regulatory alignment with EU design-for-recycling criteria. Kanto and Kansai manufacturing zones maintain specialized molded fiber engineering for unboxing experience differentiation.
Mobile Phone Accessories Packaging Market Competitive Environment
Player mix skews toward integrated paperboard producers and specialized protective packaging engineers, with tiered competitive positioning separating scale-driven corrugated suppliers from boutique rigid box configurators. Market structure exhibits moderate consolidation at the substrate level alongside fragmentation in value-added finishing and fulfillment-integrated services. Three archetypes dominate: multinational integrated paperboard mills, regional protective packaging specialists, and direct-to-consumer-focused configurators. Competitive moves center on aqueous barrier coating R&D substitution and packaging-as-a-service model expansion.
Within the integrated mill tier, WestRock and International Paper Co. occupy positions defined by captive fiber supply and North American corrugated dominance. Sealed Air anchors the protective engineering archetype, extending portfolio development through molded foam geometries. Among configurators serving Shopify-integrated merchants, PakFactory exemplifies the customizable rigid box specialization that supports premium unboxing economics.
| Leading Market Players |
|---|
| Sealed Air |
| PakFactory |
| International Paper Co. |
| Sticker Mule |
| Packlane |
| WestRock |
| Impack |
| Bespoke Boxes Co. |
| Berry Global |
| Others |
Value Chain & Pricing Dynamics
Water-based barrier coatings displacing polyethylene-laminated paperboard simultaneously shift procurement geography toward aqueous dispersion R&D hubs in Germany and Japan while compressing extrusion lamination equipment valuations in China's Pearl River Delta. This substitution dynamic redistributes margin capture from legacy machinery owners to chemistry specialists and forces Guangdong suppliers into accelerated retooling cycles.
Pricing Analysis
Cost-plus contracts with aluminum oxide indexation dominate metalized film procurement for premium audio packaging lines. Three-tier pricing structure across premium, standard, and economy levels separates luxury accessory brands specifying Bang & Olufsen-tier barrier performance from commodity cable pouch producers. Pricing pressure stems from ISTA 3A certification requirements compressing margins for uncertified third-party Amazon sellers. E-commerce merchants exhibit highest price sensitivity due to dimensional weight optimization mandates; luxury audio OEMs demonstrate lowest sensitivity given oxidation protection requirements.
Supply Chain Analysis
Inventory strategy preferences split between just-in-time raw material flows for aqueous coating operations and strategic stockpiling of aluminum oxide by metalized film specialists hedging against input volatility. Supply concentrates in China, Germany, and India, with Guangdong anchoring rigid box capacity, Baden-Württemberg housing premium audio packaging engineering, and Maharashtra developing domestic molded fiber lines. Raw material dependencies center on pulp feedstock, polyethylene resin, and engineered foam formulations. Single-source vulnerability concentrates in Shenzhen's 200-kilometer rigid box radius. Distribution runs through Amazon vendor certification channels, Shopify-integrated 3PLs, and CVS pharmacy retail expansions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal packaging mandates are accelerating format obsolescence cycles, creating high-growth disruption as 12,000+ SKUs face forced redesign within compressed compliance windows.
For Market Incumbents: Shield market position by securing captive aqueous coating capacity through backward integration into German chemistry partnerships before raw material allocation tightens. Add molded fiber engineering headcount in Kanto manufacturing zones to capture Apple supplier unboxing specifications. Defensive consolidation around PRE recyclability certification creates switching costs against emerging mono-material competitors. For New Entrants and Emerging Players: Lead with NIR-detectable pigment integration for European MRF compatibility, targeting the fastest-penetrable pharmacy retail channel where CVS and Walgreens expansion creates theft-deterrent blister demand without incumbent lock-in. White-space exists in India BIS-certified sustainable packaging for PLI-scheme electronics manufacturers shifting from pure import dependence. Go-to-market angle emphasizes ISO 14021 environmental claim verification ahead of harmonized standards. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed aqueous coating specialists in Germany possessing ECHA REACH pre-registration databases that accelerate compliance timelines. Long-term viability across the analysis window hinges on mono-material recovery stream positioning ahead of Brussels' 2030 design-for-recycling enforcement. Acquisition target archetype: regional rigid box configurators with Shopify API integration and Guangdong supplier relationships. Signal to watch: Amazon vendor certification program expansion into mandatory ISTA 3A tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aqueous Coating Chemistry | Captures margin from polyethylene displacement while securing ECHA-compliant supply chains for EU market access. |
| PRE Recyclability Certification Investment | Enables mono-material prototype submission for Bang & Olufsen and Apple supplier qualification ahead of 2030 mandates. |
| Pharmacy Retail Channel Expansion | Positions theft-deterrent blister formats with child-resistant features for CVS and Walgreens mobile accessory aisle growth. |
| Packaging-as-a-Service Model Launch | Consolidates design, inventory, and fulfillment procurement for Shopify-integrated 3PLs facing dimensional weight compression. |
| Molded Fiber Engineering Scale-Up | Displaces petroleum-based trays in premium unboxing experiences through advanced pulp molding for direct-to-consumer brands. |
Study Parameters
Operator-level perspectives from packaging procurement directors at electronics OEMs, aqueous coating R&D leads, Amazon vendor certification managers, and pharmacy retail category buyers anchored the qualitative base. Primary interview insights combined with secondary validation from SEC filings of integrated paperboard mills, ECHA REACH SVHC disclosure databases, SAMR GB standards documentation, and EU Packaging and Packaging Waste Regulation revision drafts. Bottom-up SKU-level build and top-down macroeconomic triangulation cross-checked volume assumptions across the analysis window.
Sensitivity analysis framed the analytical approach, testing aluminum oxide price volatility scenarios and aqueous coating adoption curves against base-case projections. Segmentation dimensions modeled include packaging format type, material substrate tier, end-user channel, and design specification complexity. CAGRs derived from historical shipment correlations with smartphone accessory volumes and forward-looking regulatory compliance cost imposition. Industry-specific forecast inputs incorporated ISTA 3A certification penetration rates and BIS harmonization timelines.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce fulfillment growth or accelerated EU regulatory enforcement would require recalibration. Forecasts reflect documented assumptions on substitution elasticity between barrier coating technologies. Revision becomes warranted when aluminum oxide price volatility crosses threshold levels triggering metalized film format abandonment or when China GB standards transition timelines compress beyond modeled windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronics Packaging
Anti-Counterfeit Electrical and Electronics Packaging Market
Electronics Packaging
Electronic Goods Packaging Market
Electronics Packaging
Consumer Electronics Packaging Market
Electronics Packaging
Multi-Chip Module Packaging Market
Electronics Packaging
Europe Consumer Electronics Packaging Market
Electronics Packaging
Industrial Electronics Packaging Market
Electronics Packaging
Fan-Out Wafer Level Packaging Market
Electronics Packaging
Electronic Packaging Market
Electronics Packaging
Power Module Packaging Market
Electronics Packaging
North America Consumer Electronics Packaging Market
Electronics Packaging
Global Display Packaging Market
Electronics Packaging
Electronic Wrapper Market
Electronics Packaging
Asia-Pacific Consumer Electronics Packaging Market
Electronics Packaging
Asia-Pacific Battery Packaging Market
Electronics Packaging
MEMS Packaging Solder Market
Electronics Packaging
Global Mobile Phones Packaging Market