
 Flexible Bottle Market | 2026-2036
Flexible Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Bottle Market Foresight
Outdoor retailers and travel gear brands is redrawing procurement patterns in the flexible bottle landscape. Amcor Limited leverages its global film extrusion footprint to serve collapsible water pouch contracts for adventure sport distributors. Berry Global Inc. sustains volume leadership through blow-molded-to-pouch hybrid lines aimed at single-serve beverage trials. Constantia Flexibles anchors European pharmaceutical blister-to-stand-up-pouch conversions with high-barrier aluminum foil laminates.
Flexible bottles are collapsible or squeezable liquid containers fabricated from multi-layer polymer films, aluminum foil laminates, or biodegradable substrates, typically featuring spouted closures and achieving wall thicknesses below 250 microns for hand compression. Their primary commercial purpose centers on reducing shipping cube, enabling post-use compaction, and replacing rigid PET or glass in mobile consumption occasions. Polyethylene dominates current tonnage due to cost-efficient extrusion and established recycling streams, while biodegradable films represent the fastest-expanding material category as brand owners face EPR compliance deadlines. Stand-up pouches capture the widest margin pool among packaging types because converters command premium pricing for gusseted bottom seals and integrated dispensing fitments.
The EPA regulates volatile organic compound emissions from adhesive lamination processes used in flexible bottle manufacturing, pushing converters toward solventless and water-based bonding systems. REACH restrictions on phthalate plasticizers and the EU F-Gas Regulation on barrier foam alternatives reshape material specifications for European-sourced films. FDA food-contact substance notifications govern spout and film combinations for beverage applications in the United States. Stakeholders must monitor evolving extended producer responsibility fee schedules and recyclability labeling mandates to align capacity investments with compliance thresholds.
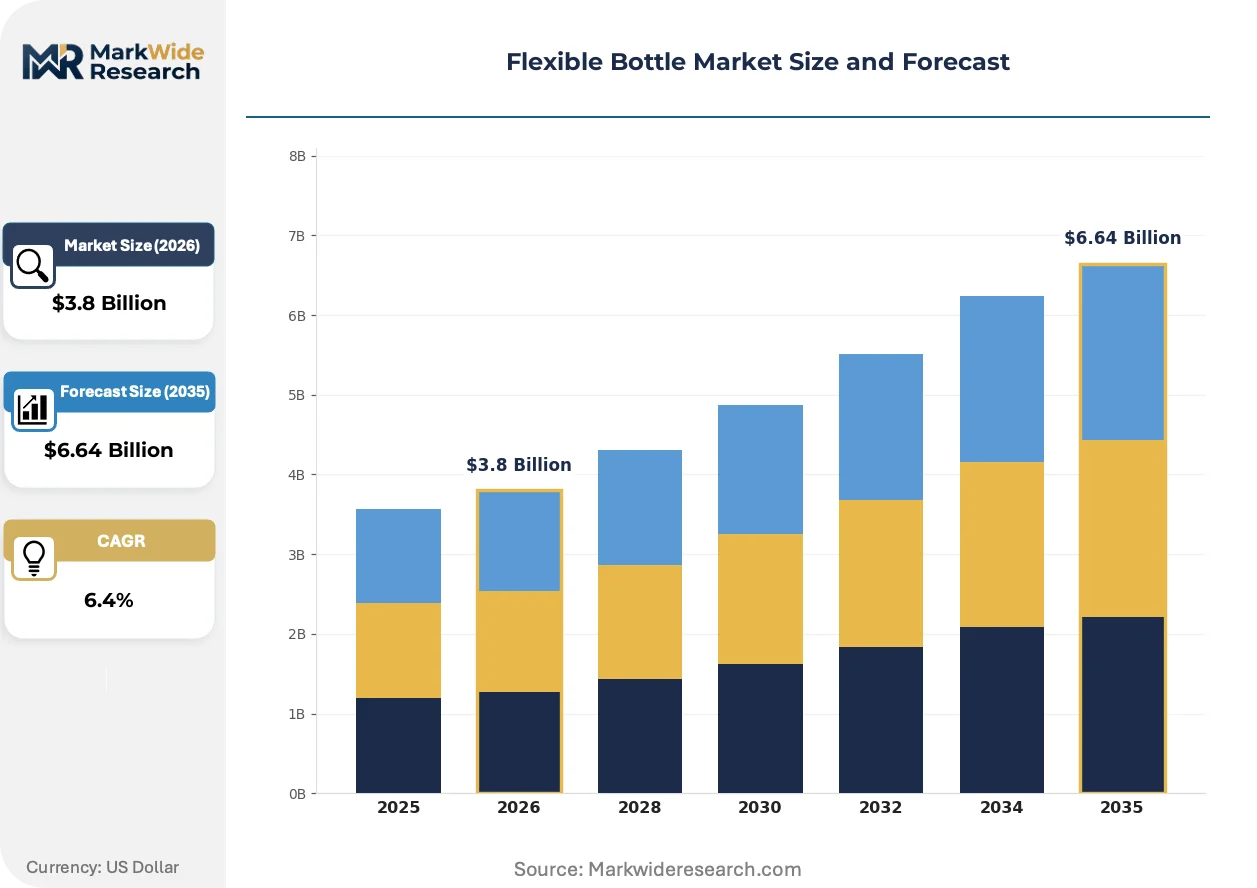
Market Dynamics
The EU Single-Use Plastics Directive is compressing lead times for material substitution, forcing converters to requalify film laminates ahead of 2030 EPR compliance deadlines while outdoor brands accelerate collapsible format trials.
Growth Catalysts
- REACH phthalate restrictions:ECHA limitations on conventional plasticizers are accelerating bio-based polymer validation programs across German packaging clusters.
- Outdoor recreation procurement:Adventure sport distributors are specifying high-barrier stand-up pouches for hydration systems, displacing rigid bottles in trail-running and climbing segments.
- Solventless lamination:Water-based and solvent-free adhesive systems are expanding capacity as EPA VOC regulations tighten on conventional bonding processes.
Market Restraints
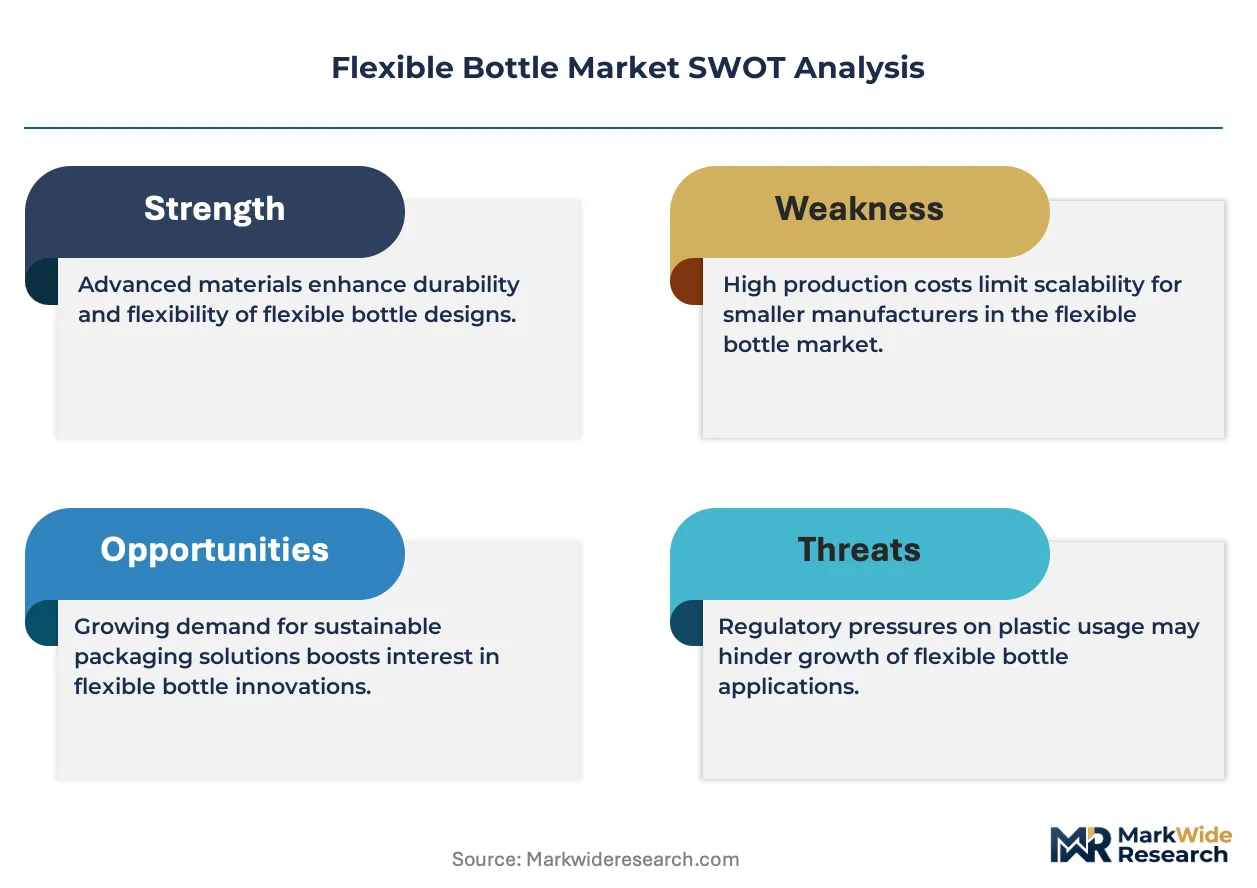
- Aluminum foil supply concentration:High-barrier laminate converters depend on a narrow supplier base for thin-gauge foil, creating input cost volatility when energy prices spike.
- Recyclability certification friction:Extended producer responsibility fee schedules vary by member state, complicating pan-European labeling and sort-stream alignment.
- Rigid PET substitution threat:Mechanical recycling infrastructure for conventional bottles is mature and cost-competitive, slowing flexible format penetration in mainstream beverage.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO-aligned converters can capture blister-to-pouch conversion demand as domestic drug makers seek lightweight export packaging.
- Japan METI circular economy targets:Biodegradable film development grants are accelerating PLA and PHA substrate trials for personal care applications.
- Direct-to-consumer outdoor channels:Subscription hydration services are bypassing traditional retail, creating dedicated pouch specifications for recurring shipment models.
Industry Challenges
- Multi-layer delamination expertise:Converters face acute shortages of process engineers capable of optimizing barrier performance in sub-250-micron film stacks.
- FDA notification timelines:Food-contact substance approvals for novel spout-film combinations extend development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Bottle Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Biodegradable Films, PET, Aluminum Foil Application: Beverages, Personal Care, Household Chemicals, Pharmaceuticals, Food Packaging End User: Food Processing Facilities, Cosmetic Manufacturers, Chemical Plants, Drug Manufacturers, Beverage Producers Packaging Type: Stand-up Pouches, Spouted Pouches, Sachets, Shrink Wraps, Reclosable Bags |
| Companies Covered | Amcor Limited, Berry Global Inc., Sealed Air Corporation, ALPLA Group, Huhtamaki, Gerresheimer AG, Plastipak Holdings Inc., Mondi Limited, Constantia Flexibles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Bottle Market Shifts & Advancements
Film substrate evolution and regulatory chemistry mandates are restructuring converter capabilities. Three developments are compressing incumbent process advantages and opening white space for qualified entrants.
Mono-material polyethylene laminates are supplanting multi-layer aluminum foil constructions in mid-barrier beverage applications. German personal care brands are qualifying these formats for shampoo and conditioner refills. The shift is compressing aluminum foil demand while expanding extrusion capacity for recyclable streams.
EPA enforcement of volatile organic compound limits on adhesive lamination is accelerating water-based system adoption. Converters in Ohio and California are retrofitting coating lines to eliminate solvent recovery infrastructure. The regulatory pressure falls heaviest on mid-tier suppliers lacking capital for dual-process capability.
Adventure travel retailers are consolidating supplier panels around certified circular formats. Specialty outdoor distributors are replacing generic collapsible bottles with converter-branded recyclable pouches bearing EPR-compliant labeling. The behavior change is most visible in German and Austrian alpine sport retail channels where sustainability credentials drive shelf placement.
Flexible Bottle Market Segmentation
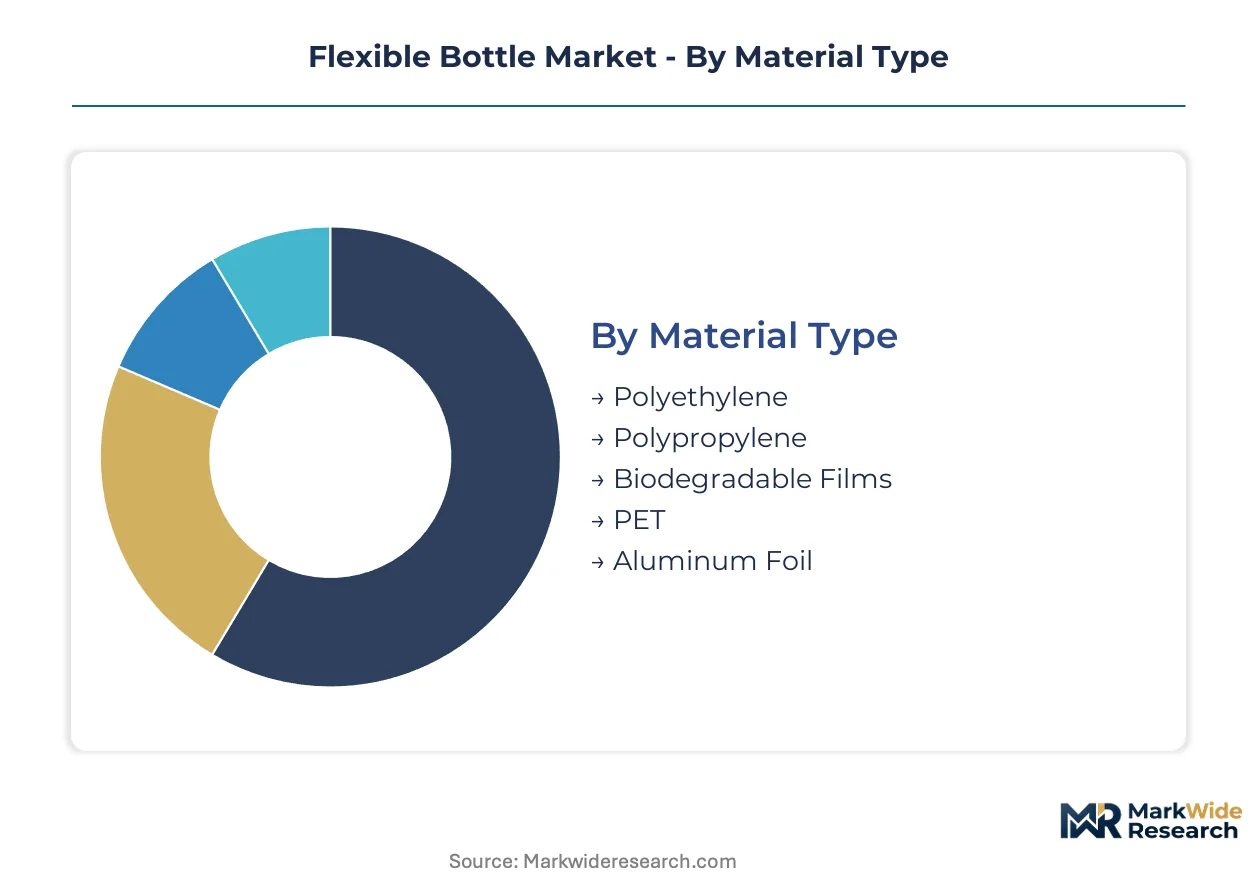
Segmentation in flexible bottles reveals how material chemistry, barrier requirements, and end-use mobility needs fragment converter capabilities across distinct margin pools. Each dimension carries different compliance burdens and technical qualification timelines.
Material Type:
Margin concentration follows barrier performance tiers, with high-barrier laminates commanding premium pricing against commodity extrusion grades.
- Polyethylene:Dominant tonnage substrate formed through blown film extrusion with established mechanical recycling streams. Beverage producers in Germany specify LDPE-rich formulations for collapsible water pouches to meet EPR compliance deadlines.
- Biodegradable Films:PLA and PHA substrates processed through cast film lines with industrial composting certification. Japanese personal care brands under METI circular economy targets are accelerating validation programs for refill sachets.
- Polypropylene:Biaxially oriented constructions offering thermal resistance for hot-fill applications. Cosmetic manufacturers favor PP-rich laminates for shampoo refill systems.
- PET:Metallized or clear film grades providing optical clarity and moderate barrier. Food packaging converters use PET laminates for condiment squeeze bottles.
- Aluminum Foil:Ultra-thin gauge laminates below 7 microns delivering oxygen and moisture barriers. Pharmaceutical blister-to-pouch conversions depend on foil specifications from concentrated European suppliers.
The dominant share belongs to Polyethylene, while Biodegradable Films is closing the gap fastest.
Application:
Volume distribution maps directly to consumption occasion mobility, with outdoor and travel-adjacent uses driving format innovation.
- Beverages:Stand-up and spouted pouches for hydration systems, sports drinks, and alcoholic ready-to-drink formats. Adventure sport distributors in Austria and Germany are displacing rigid bottles with collapsible pouches for trail-running segments.
- Personal Care:Refill pouches for shampoo, conditioner, and body wash with high-barrier requirements. German personal care brands are qualifying mono-material PE formats to simplify recycling streams.
- Household Chemicals:Concentrated cleaner refills requiring chemical resistance and child-resistant closures. Chemical plants specify multi-layer constructions with solvent-resistant adhesive systems.
- Pharmaceuticals:Unit-dose and bulk liquid medications with stringent barrier and sterility standards. CDSCO-aligned converters in India are capturing blister-to-pouch conversion demand from domestic drug exporters.
- Food Packaging:Condiments, sauces, and cooking oils in squeezable formats. Food processing facilities favor gusseted bottom seals for shelf stability.
Beverages holds the volume lead, though Personal Care is expanding most quickly through refill economy adoption.
End User:
Procurement sophistication varies sharply, with pharmaceutical and cosmetic buyers imposing the most rigorous qualification protocols.
- Beverage Producers:Large-scale buyers specifying high-speed filling compatibility and palletization efficiency. Outdoor-focused brands are consolidating supplier panels around certified circular formats.
- Cosmetic Manufacturers:Premium positioning demands drive investment in tactile film surfaces and precision dispensing fitments. German and French cosmetic clusters prioritize mono-material recyclability.
- Drug Manufacturers:Validation-heavy procurement with 18-24 month FDA notification timelines for novel spout-film combinations. European pharmaceutical converters anchor demand for aluminum foil laminates.
- Food Processing Facilities:Cost-sensitive volume buyers with established HACCP systems. Stand-up pouch adoption concentrates in sauce and condiment categories.
- Chemical Plants:Technical specifications prioritize chemical compatibility and regulatory labeling compliance. REACH restrictions on phthalate plasticizers reshape material sourcing.
Beverage Producers command the largest contract values, while Drug Manufacturers are imposing the steepest technical barriers to entry.
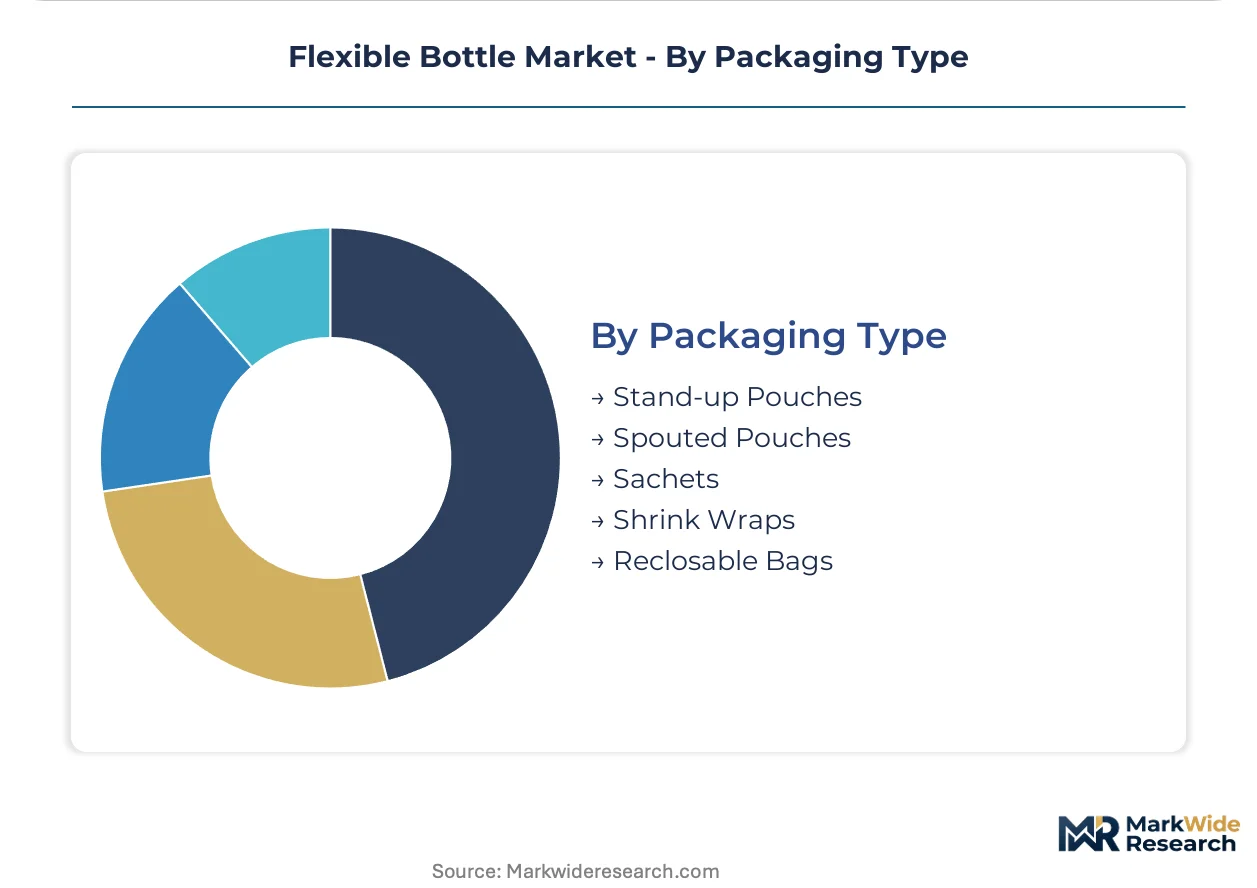
Packaging Type:
Format selection determines converter equipment investment, with gusseted and spouted constructions requiring specialized sealing technology.
- Stand-up Pouches:Gusseted bottom formats with integrated carrying handles and dispensing fitments. Adventure travel retailers in German alpine sport channels are specifying converter-branded recyclable pouches with EPR-compliant labeling.
- Spouted Pouches:Fitment-welded constructions enabling controlled dispensing and reclosure. Personal care refill applications favor large-format spouted designs for bathroom dispensing.
- Sachets:Single-serve flat pouches for samples and travel portions. Cosmetic manufacturers use sachets for premium product trial distribution.
- Reclosable Bags:Zipper-equipped formats for multi-use consumption. Household chemical concentrates specify child-resistant zipper mechanisms.
- Shrink Wraps:Secondary bundling films for multi-pack collation. Beverage producers use printed shrink formats for retail club packs.
Stand-up Pouches generates the widest margin pool, though Spouted Pouches is gaining share fastest through personal care refill adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German packaging converters export high-barrier flexible formats to premium beverage and personal care brands across Austria and Switzerland, establishing a north-south trade corridor that channels technical expertise into alpine sport retail channels.
Germany
Bavarian film extrusion clusters supply collapsible water pouches for adventure sport distributors under REACH phthalate restrictions that accelerate bio-based polymer validation. The EU Single-Use Plastics Directive compresses lead times for EPR-compliant labeling ahead of 2030 deadlines. Stuttgart-area converters serve personal care refill specifications with mono-material PE formats.
United States
Ohio and California converters retrofit coating lines to eliminate solvent recovery infrastructure as EPA VOC regulations tighten on adhesive lamination processes. Beverage producers specify high-speed filling compatibility for outdoor-focused subscription hydration services. Midwestern film extrusion capacity expands for recyclable stand-up pouch streams.
Japan
Personal care brands accelerate PLA and PHA substrate trials under METI circular economy targets for refill sachet applications. Osaka-area converters develop biodegradable film specifications for domestic cosmetic manufacturers. Kanto region packaging engineers optimize barrier performance in sub-250-micron film stacks.
India
CDSCO-aligned converters capture blister-to-pouch conversion demand from domestic drug exporters seeking lightweight pharmaceutical packaging. Maharashtra-based film laminators serve unit-dose medication specifications with stringent barrier requirements. Gujarat packaging clusters expand capacity for food-grade condiment squeeze bottles.
Austria
Alpine sport retailers consolidate supplier panels around certified circular formats bearing EPR-compliant labeling for trail-running and climbing segments. Vienna-area distributors specify converter-branded recyclable pouches displacing rigid bottles. Tyrol region outdoor gear procurement drives gusseted bottom seal adoption for hydration systems.
Flexible Bottle Market Competitive Landscape
Listed leaders compete with private specialists across film extrusion and lamination capabilities, creating a tiered structure where scale advantages in blown film lines contrast with agility in biodegradable substrate trials. Strategic archetypes include diversified packaging conglomerates with global film footprints, regional specialists in high-barrier laminates, and private converters focused on pharmaceutical qualification protocols. Dominant competitive moves center on solventless lamination line retrofits and mono-material PE capacity expansion to capture EPR-compliant demand.
Within the diversified conglomerate tier, Amcor Limited and Berry Global Inc. exemplify scale-driven positioning across multiple substrate categories, while Constantia Flexibles occupies a specialized position in European pharmaceutical and personal care barrier applications. These three anchors represent distinct capability emphases: global film extrusion breadth, hybrid blow-molded-to-pouch integration, and aluminum foil laminate expertise for high-barrier conversions.
| Leading Market Players |
|---|
| Amcor Limited |
| Berry Global Inc. |
| Sealed Air Corporation |
| ALPLA Group |
| Huhtamaki |
| Gerresheimer AG |
| Plastipak Holdings Inc. |
| Mondi Limited |
| Constantia Flexibles |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts between German film extrusion clusters and alpine sport distributors lock in supply access while providing 12-18 month price visibility against aluminum foil volatility. These arrangements concentrate procurement power among beverage producers and personal care brands that can commit to minimum volume thresholds.
Pricing Analysis
Current-generation mono-material polyethylene laminates command 15-25% premiums over prior-generation multi-layer aluminum foil constructions, while next-generation biodegradable PLA substrates remain in pre-qualification pricing. Three-tier pricing structure across premium high-barrier laminates, standard mid-barrier films, and economy-grade single-layer extrusions reflects certification grade and volume scale differentiation. Cost compression in economy tiers is intensifying because REACH phthalate restrictions are forcing rapid material requalification. Beverage producers exhibit the highest price sensitivity due to thin margins on collapsible water pouches, while pharmaceutical drug manufacturers accept premium pricing for validated barrier performance.
Supply Chain Analysis
Germany and Austria anchor high-barrier flexible bottle production through Bavarian film extrusion clusters and Vienna-area lamination facilities serving alpine sport retail channels. Raw material dependencies draw from thin-gauge aluminum foil suppliers concentrated in European energy-intensive smelters, bio-based polymer feedstock from agricultural processors, and specialty adhesive chemistries subject to EPA VOC regulations. Single-source vulnerability in sub-7-micron foil supply creates input cost spikes when energy prices fluctuate. Distribution runs through converter-direct relationships with outdoor gear distributors and pharmaceutical packaging specialists, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified process engineers capable of optimizing sub-250-micron multi-layer delamination represent the critical bottleneck constraining converter expansion, with 18-24 month FDA notification timelines for novel spout-film combinations extending development cycles beyond typical capital planning horizons.
For Market Incumbents: Fortify solventless lamination capabilities through line retrofits in Ohio and California facilities ahead of tightening EPA VOC enforcement, while securing captive supply of thin-gauge aluminum foil through backward integration or long-term offtake agreements with European smelters. The rigid PET substitution threat demands accelerated mono-material PE capacity expansion to capture EPR-compliant demand from German personal care brands. For New Entrants and Emerging Players: Direct-to-consumer subscription hydration services present an under-served service layer where incumbents lack dedicated pouch specifications for recurring shipment models. Target Indian pharmaceutical exporters seeking CDSCO-aligned blister-to-pouch conversions, leveraging 18-24 month FDA notification gaps to establish qualification track records before incumbent requalification cycles complete. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with validated pharmaceutical barrier protocols and long-term supply agreements with alpine sport distributors. Five-to-ten year viability favors specialists with dual-process capability in both solventless lamination and biodegradable substrate trials. Watch for inflection signals in Japan METI grant disbursement rates for PLA and PHA development programs.| Strategic Initiative | Industry Significance |
|---|---|
| Solventless Lamination Line Retrofit | EPA VOC compliance eliminates solvent recovery infrastructure costs for Ohio and California converters. |
| Mono-Material PE Capacity Expansion | German EPR deadlines force personal care brands to qualify recyclable refill pouch formats. |
| Pharmaceutical Barrier Protocol Investment | FDA notification timelines create 18-24 month moats around validated spout-film combinations. |
| Biodegradable Substrate Qualification | Japan METI circular economy grants accelerate PLA and PHA trials for cosmetic refill applications. |
| Direct-to-Consumer Channel Development | Subscription hydration services bypass traditional retail, creating dedicated pouch specifications. |
Research Methodology
A standing panel of film extrusion plant managers, pharmaceutical packaging procurement leads, outdoor gear category buyers, and adhesive R&D directors provided ongoing calibration against secondary validation from EU Single-Use Plastics Directive implementation reports, EPA enforcement action databases, FDA food-contact substance notification logs, and CDSCO pharmaceutical packaging guidance documents. Bottom-up converter capacity surveys combined with top-down trade flow analysis across German-Austrian alpine sport retail channels.
Consistency checks against external benchmarks validated volume and value outputs across material type, application, end user, and packaging format segmentation dimensions. CAGRs were derived from demand elasticity modeling incorporating EPR compliance deadline effects and substitution dynamics between rigid and flexible formats. Industry-specific forecast inputs included REACH phthalate restriction implementation timelines and METI circular economy grant disbursement patterns.
Underlying assumptions cover sustained EPR fee schedule convergence across EU member states, with deviation risk concentrated in aluminum foil energy cost volatility and FDA notification backlog fluctuations. Recalibration cycles align with material shifts in regulatory enforcement priorities and bio-based polymer validation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Latin America Flexible Packaging Market
Flexible Packaging
Benelux Flexible Plastic Packaging Market
Flexible Packaging
Latin America Flexible Plastic Packaging Market
Flexible Packaging
China Flexible Plastic Packaging Market
Flexible Packaging
UK Flexible Plastic Packaging Market
Flexible Packaging
North America Flexible Plastic Packaging Market
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
North America Flexible Packaging Market
Flexible Packaging
Egypt Flexible Plastic Packaging Market
Flexible Packaging
Thermoforming Packaging Market
Flexible Packaging
Flexible Paper for Food & Beverages Packaging Market
Flexible Packaging
Morocco Flexible Packaging Market
Flexible Packaging
India Flexible Plastic Packaging Market
Flexible Packaging
Flexible Film Market
Flexible Packaging
Confectionery Flexible Packaging Market
Flexible Packaging
India Flexible Packaging Market