
 High Density Polyethylene (HDPE) Bottles Market | 2026-2036
High Density Polyethylene (HDPE) Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
High Density Polyethylene (HDPE) Bottles Market Foresight
Polymer engineering talent scarcity is redrawing competitive boundaries among North American packaging converters. Berry Global Inc. leverages captive blow molding capacity across multiple US states to secure long-term personal care contracts. Graham Packaging Company anchors its position through deep relationships with dairy and juice processors requiring FDA-compliant food-grade HDPE. Silgan Holdings Inc. differentiates via rigid packaging integration that bundles metal closures with HDPE bottle supply.
High density polyethylene bottles are hollow containers formed from ethylene polymer resin with density ranging from 0.941 to 0.965 g/cm³, manufactured primarily through extrusion blow molding to achieve moisture barrier properties and chemical resistance for liquid storage. Blow molding dominates production economics due to lower tooling costs and faster cycle times versus injection molding alternatives. Food & Beverage end users command the largest volume share as HDPE jugs replace glass for milk and juice distribution. Personal care applications represent the fastest-expanding segment as brands convert from PET to colored and opaque HDPE for shelf differentiation.
FDA maintains strict food-contact notification requirements for HDPE resin additives and recycling stream integration, while EPA regulations on industrial chemical containment dictate minimum wall thickness and UN certification for drum applications. State regulators in California enforce recycled content thresholds that push converters toward post-consumer regrind integration in non-food bottles. Stakeholders must track how FDA guidance on advanced recycling-derived resins evolves alongside state packaging EPR laws to anticipate material qualification timelines and capital allocation priorities.
Market Dynamics
Recycled content mandates from California's state regulators are forcing converters to requalify resin formulations and reconfigure extrusion blow molding lines for post-consumer regrind integration. This structural pressure cascades through material procurement, colorant compatibility testing, and long-term personal care contract renegotiations.
Growth Catalysts
- Personal care brand conversion:Shampoo and lotion manufacturers are switching from PET to opaque HDPE bottles for shelf differentiation and squeezability. This demand pull concentrates procurement among converters with captive blow molding capacity.
- FDA food-contact compliance:Dairy and juice processors require resin additive documentation and recycling stream traceability. Processors with pre-qualified material libraries capture multi-year supply agreements.
- India manufacturing scale-up:Local converters in Gujarat and Maharashtra serve domestic consumer goods brands plus export markets to Africa and Southeast Asia. Cost-advantaged production and improving mold-making capabilities accelerate regional supply concentration.
Market Restraints
- Ethylene feedstock volatility:Crude oil and natural gas liquid price swings compress converter margins and complicate long-term contract pricing. Naphtha-based crackers in Asia face particular cost pressure.
- Post-consumer regrind supply fragmentation:Collection infrastructure gaps and contamination rates limit food-grade recycled HDPE availability. California's recycled content thresholds outpace domestic regrind supply.
- Advanced recycling resin qualification delays:FDA guidance on chemical recycling-derived HDPE remains pending. Brand owners hesitate to commit capital until regulatory clarity emerges.
Strategic Opportunities
- India domestic demand expansion:Rising per-capita consumption of packaged personal care and edible oils creates white space for blow molding capacity expansion. Local converters can backward integrate into preform manufacturing.
- Metal closure bundling:Rigid packaging integrators can combine HDPE bottle supply with aluminum or steel closures for dairy and juice customers. This convergence reduces supplier management overhead for processors.
- California EPR packaging laws:Extended producer responsibility frameworks create compliance service revenue streams. Converters with lifecycle assessment capabilities can monetize regulatory advisory alongside physical supply.
Industry Challenges
- Polymer engineering talent scarcity:Blow molding process optimization and recycled resin formulation expertise concentrate among aging specialists. North American converters compete for limited candidates with automotive and medical device sectors.
- Multi-site FDA audit coordination:Food-grade HDPE suppliers must maintain consistent additive documentation across geographically dispersed extrusion lines. Audit preparation diverts technical resources from product development.
- Legacy colorant inventory stranding:Opaque personal care formulations require titanium dioxide and pigment masterbatch changes for recycled content compatibility. Existing stockpiles face write-down risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Density Polyethylene (HDPE) Bottles Market |
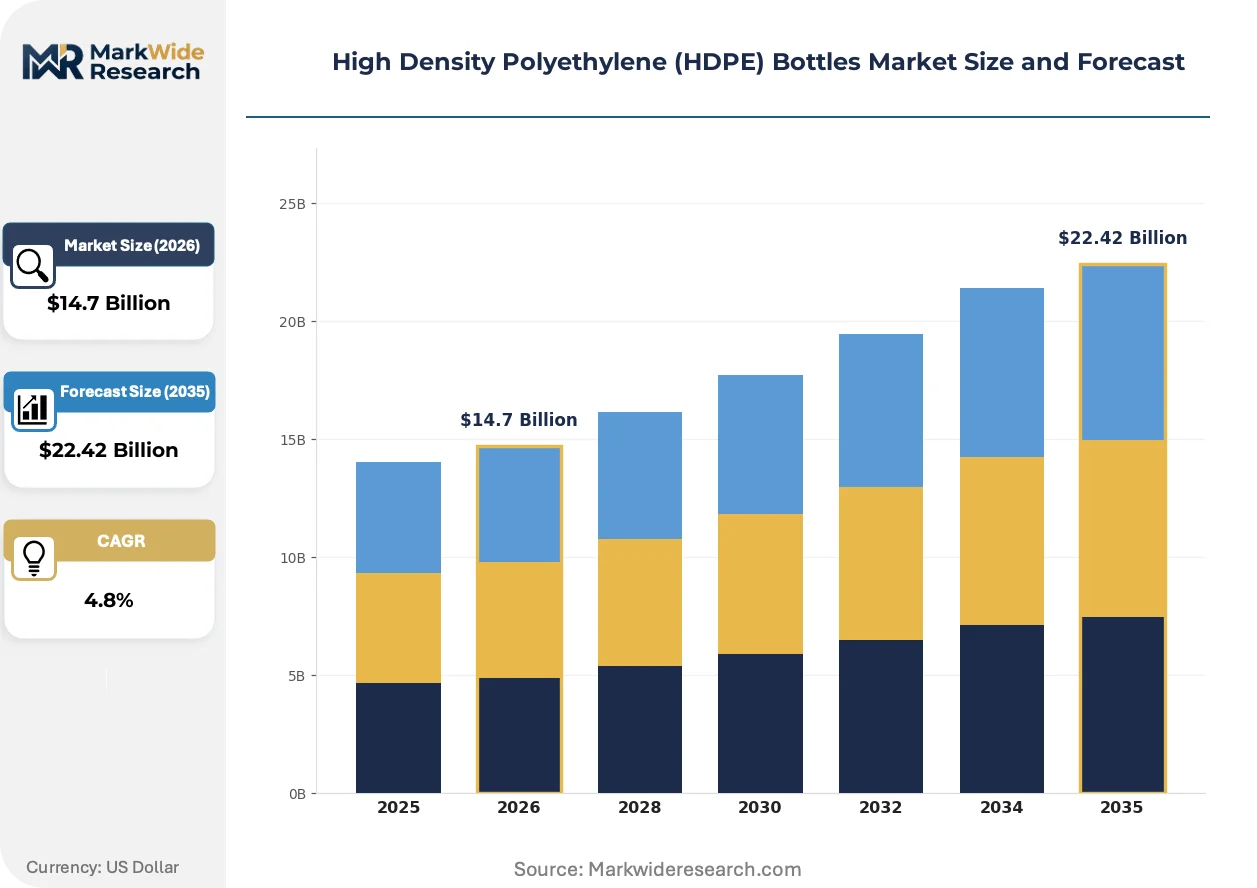
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regrind, Blow Molding, Injection Molding, Extrusion End User: Food & Beverage, Personal Care, Household Products, Industrial Chemicals Packaging Type: Container, Drum, Jug, Bottle Distribution Channel: Direct Sales, Retail, E-commerce, Wholesalers |
| Companies Covered | Amcor plc, Berry Global Inc., Graham Packaging Company, Silgan Holdings Inc., Plastipak Holdings, Inc., ALPLA Group, Canyon Plastics Inc., Indorama Ventures Public Company Limited, Kaufman Container, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Density Polyethylene (HDPE) Bottles Market Shifts & Advancements
Extrusion blow molding equipment and resin formulation science are evolving in parallel, with hardware automation and material circularity advancing together. These technical shifts reshape converter capital allocation and customer qualification timelines.
Advanced recycling-derived HDPE resins are entering commercial qualification pipelines for non-food bottle applications. Personal care brands in North America and Europe are testing chemically recycled material for shampoo and conditioner packaging. Market structure is bifurcating between mechanical recycling specialists serving commodity grades and advanced recycling ventures targeting premium cosmetic applications with virgin-equivalent performance.
California's recycled content mandates for rigid plastic packaging containers tighten compliance thresholds annually. Converters must document post-consumer regrind percentages through certified mass balance systems. Food-grade bottle segments face particular friction as FDA notification requirements for recycled resin additives lag state-level mandates, forcing dual-track qualification efforts.
Direct procurement relationships between personal care brand owners and resin compounders are compressing traditional converter intermediation. Large shampoo and lotion marketers now specify resin grades and colorant systems directly, relegating blow molders to toll manufacturing roles. This disintermediation concentrates margin pressure in North American and European supply chains where brand owner technical staffing is deepest.
High Density Polyethylene (HDPE) Bottles Market Segmentation
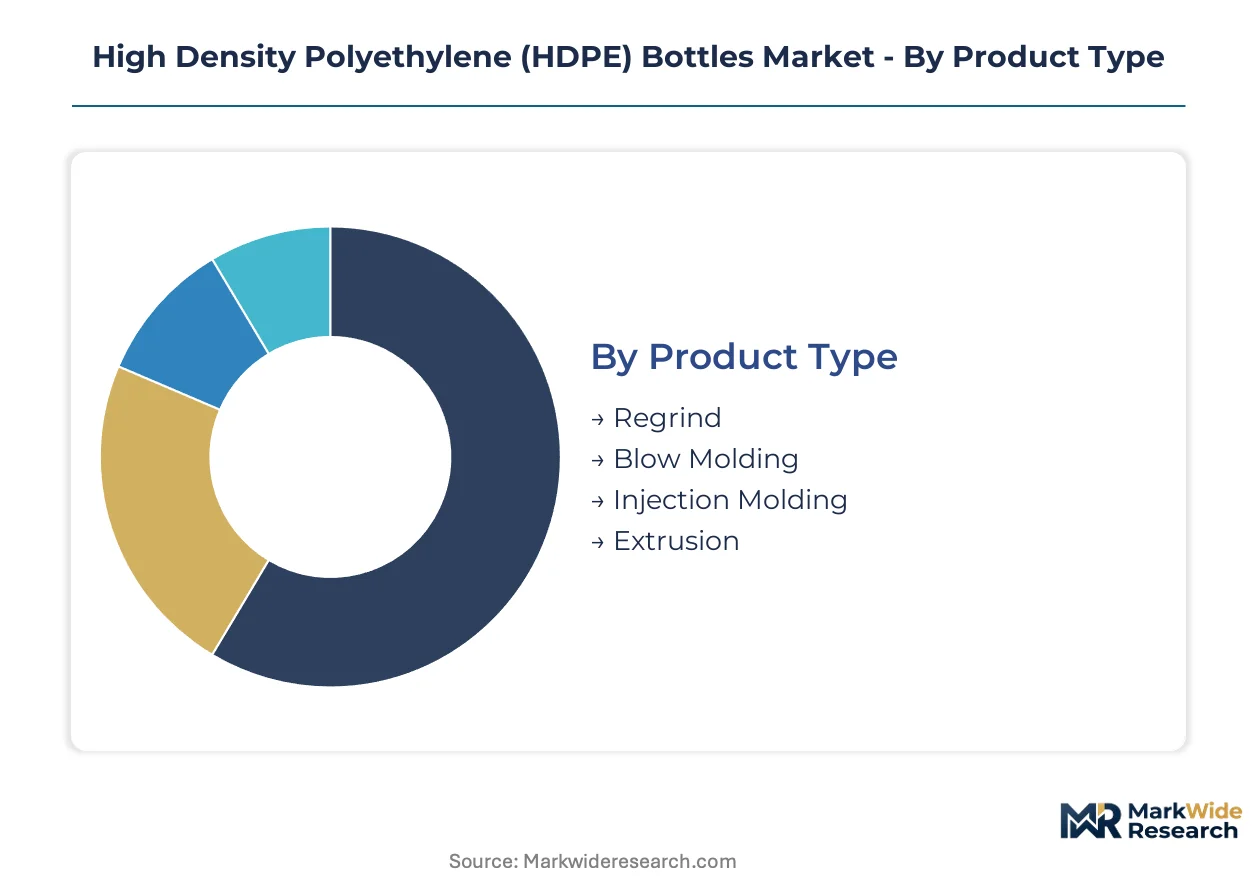
HDPE bottle converters face divergent qualification requirements across end-use segments. FDA food-contact mandates, state recycled content laws, and personal care brand specifications create distinct procurement patterns that reshape converter specialization.
Product Type:
Domestic North American demand concentrates in blow molding and extrusion formats serving dairy and juice processors. Export-oriented converters in India emphasize regrind-compatible injection molding for personal care brands shipping to African and Southeast Asian markets.
- Blow Molding:Extrusion blow molding dominates milk jug and personal care bottle production through lower tooling costs and faster cycle times. Dairy processors in Wisconsin and California require consistent wall thickness and UN certification compliance for distribution networks.
- Regrind:Post-consumer recycled HDPE flake requires specialized screw designs and melt filtration systems for contamination control. California's rigid plastic packaging mandates are accelerating regrind line investments among West Coast converters facing state enforcement deadlines.
- Injection Molding:Produces threaded closures and precision neck finishes for pharmaceutical and cosmetic applications requiring tight dimensional tolerances.
- Extrusion:Sheet and profile extrusion serves industrial drum liners and chemical containment applications with thick-wall specifications.
Blow molding holds the largest share; momentum sits with regrind as state mandates tighten.
End User:
Cost tiers separate commodity food packaging from premium personal care contracts. Food-grade qualification barriers protect incumbent suppliers while personal care brands actively disintermediate converters through direct resin procurement.
- Food & Beverage:Milk and juice processors command the highest volume consumption. FDA food-contact notification requirements for resin additives and recycling stream traceability create multi-year supplier lock-in for qualified converters.
- Personal Care:Shampoo and lotion manufacturers are switching from PET to opaque HDPE for shelf differentiation and squeezability. Brand owners in North America now specify resin grades directly, compressing converter margins to toll manufacturing levels.
- Household Products:Cleaning chemical bottles require chemical resistance and child-resistant closure compatibility. Private label concentration among mass retailers drives volume consolidation.
- Industrial Chemicals:UN-certified drums and intermediate bulk containers face EPA containment regulations. Minimum wall thickness specifications limit lightweighting opportunities.
Food & Beverage anchors volume concentration; Personal Care is expanding most quickly through material substitution.
Packaging Type:
Application-specific performance requirements dictate resin grade selection and wall thickness engineering. Container geometry and closure integration complexity determine converter technical capabilities.
- Bottle:Personal care and beverage bottles dominate unit volume. Opaque formulations with titanium dioxide masterbatch require reformulation for recycled content compatibility.
- Jug:Dairy distribution relies on gallon and half-gallon jug formats with handle integration. Wisconsin and California dairy cooperatives specify minimum post-industrial recycled content thresholds.
- Container:Wide-mouth containers serve food spreads and industrial pastes. Threaded closure torque specifications demand precise neck finish molding.
- Drum:55-gallon industrial drums require UN certification for hazardous material transport. Thick-wall extrusion blow molding limits production line flexibility.
Bottle formats generate the highest unit volumes; jug specifications are tightening fastest under dairy processor sustainability mandates.
Distribution Channel:
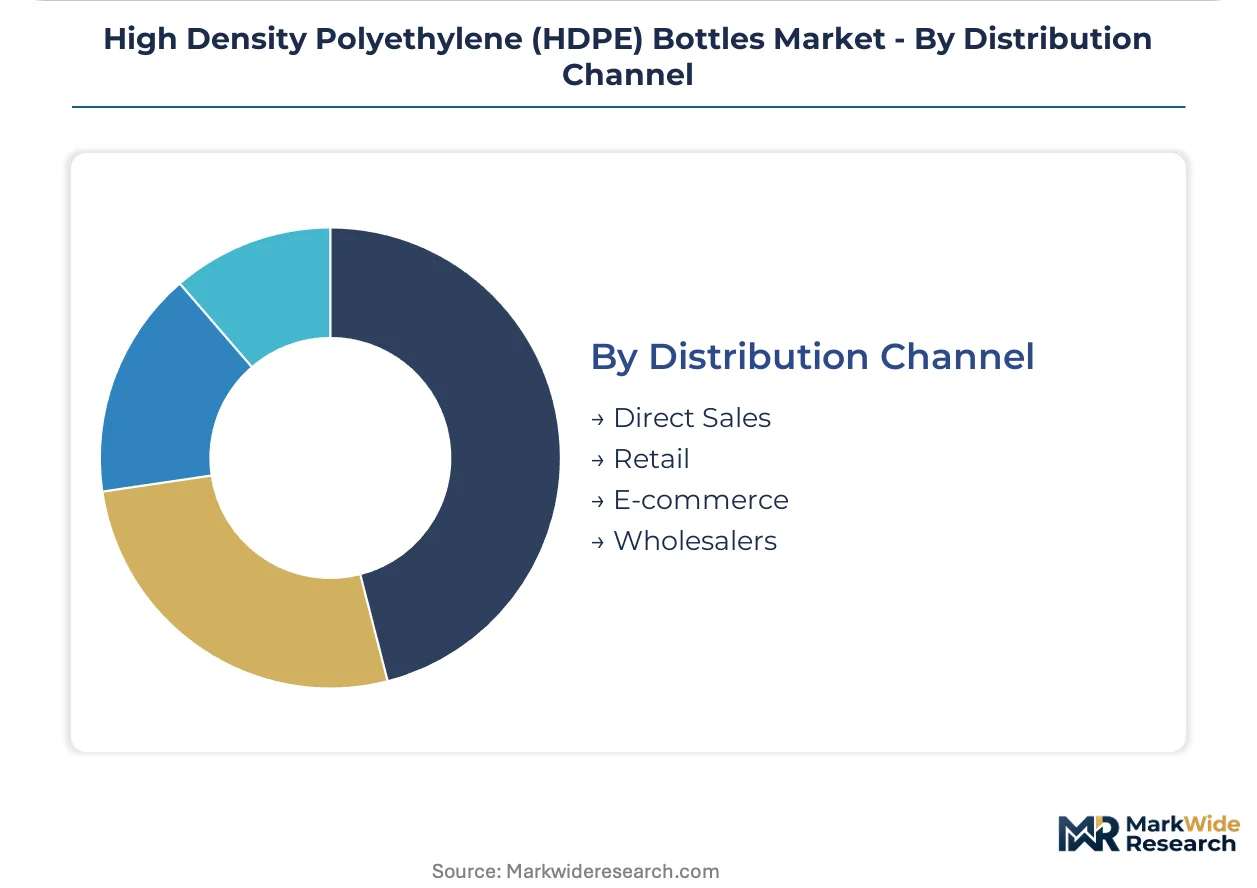
Customer type and order scale determine channel economics. Direct procurement relationships are displacing traditional distributor intermediation among large-volume personal care and food processors.
- Direct Sales:Large shampoo manufacturers and dairy processors negotiate multi-year supply agreements with captive blow molding capacity. Technical staff co-location at converter sites accelerates product development cycles.
- Wholesalers:Regional distributors serve mid-tier personal care brands and private label household products. Inventory pooling reduces working capital requirements for smaller converters.
- Retail:Big-box retailers specify private label packaging through approved vendor programs. Compliance documentation requirements favor established converter relationships.
- E-commerce:Direct-to-consumer personal care brands require smaller minimum order quantities and faster turnaround. Digital-native brands prioritize sustainable packaging credentials for consumer messaging.
Direct Sales commands the premium contract tier; E-commerce is climbing the fastest as digital-native brands scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food-contact regulations anchor the United States as the dominant geography for HDPE bottle qualification standards, while state-level recycled content mandates in California create compliance templates that ripple through international supply chains.
United States
Dairy processors in Wisconsin and California command substantial HDPE jug volumes for milk distribution networks. FDA maintains strict food-contact notification requirements for resin additives and recycling stream traceability. Berry Global Inc. leverages captive blow molding capacity across multiple states to secure long-term personal care contracts.
India
Local converters in Gujarat and Maharashtra serve domestic consumer goods brands plus export markets to Africa and Southeast Asia. Cost-advantaged production and improving mold-making capabilities accelerate regional supply concentration. The country's FSSAI food safety standards and DGFT export promotion schemes support packaging sector expansion.
Germany
Personal care brands headquartered in Düsseldorf and Hamburg drive demand for opaque HDPE bottles with premium shelf differentiation. ECHA REACH regulations govern chemical substance registration in resin formulations. Bavarian converters specialize in pharmaceutical-grade packaging with precise neck finish tolerances.
China
Domestic consumption of packaged edible oils and personal care products fuels blow molding capacity expansion in the Yangtze River Delta. SAMR market supervision and GB standards regulate food-contact plastic safety. Zhejiang and Jiangsu provinces concentrate mold-making and extrusion equipment manufacturing clusters.
Brazil
ANVISA pharmaceutical packaging regulations and growing FMCG consumption in São Paulo state attract HDPE bottle investment. Personal care brands convert from PET to colored HDPE for regional shelf differentiation. Local converters serve both domestic mass retailers and Mercosur export markets.
High Density Polyethylene (HDPE) Bottles Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in HDPE bottle manufacturing. The market structure bifurcates between multinational packaging conglomerates with captive resin supply and regional blow molding specialists serving niche applications. Three archetypes dominate: rigid packaging integrators bundling closures with bottles, dairy-focused food-grade specialists with FDA pre-qualification libraries, and personal care toll manufacturers absorbing direct resin procurement from brand owners. Competitive moves concentrate on vertical integration into preform manufacturing and geographic expansion toward India-based cost positions.
Among North American packaging conglomerates, Berry Global Inc., Graham Packaging Company, and Silgan Holdings Inc. exemplify distinct strategic positioning. Berry Global represents the multi-site blow molding archetype with dispersed U.S. production footprints. Graham Packaging anchors the food-grade specialist tier through deep processor relationships. Silgan Holdings occupies the rigid packaging integrator position combining metal closure supply with bottle manufacturing. These three structures illustrate how qualification barriers, captive capacity, and bundling economics segment competitive terrain.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Graham Packaging Company |
| Silgan Holdings Inc. |
| Plastipak Holdings, Inc. |
| ALPLA Group |
| Canyon Plastics Inc. |
| Indorama Ventures Public Company Limited |
| Kaufman Container |
| Others |
Supply & Pricing Matrix
Sixty-day resin inventory cycles at Gulf Coast ethylene crackers concentrate pricing leverage among integrated producers serving personal care brand direct procurement programs. This lead-time band tightens converter margins when naphtha-based Asian competitors undercut contract rates for export-oriented Indian converters.
Pricing Analysis
Geographic price spreads between US Gulf Coast and Gujarat manufacturing clusters exceed freight-adjusted parity by double-digit percentage points. Three-tier pricing structure across premium FDA-grade, standard food-contact, and economy non-food tiers separates qualified dairy suppliers from toll-manufacturing personal care converters. Price differentiation hinges on certification documentation depth and captive blow molding scale. Cost compression in standard-tier segments is intensifying because brand owners now specify resin grades directly, stripping converter margin to processing fees. Mass retailers and private label household products buyers exhibit highest price sensitivity; dairy cooperatives with multi-year volume commitments show lowest.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes elevate inbound logistics costs for titanium dioxide masterbatch and specialty colorant imports. HDPE bottle manufacturing draws from ethylene feedstock concentration in the United States, Saudi Arabia, and India, with mold-making equipment anchored in Germany and China. Post-consumer regrind supply fragmentation and contamination control requirements rest on collection infrastructure gaps. Single-source vulnerability concentrates in FDA-qualified resin additive suppliers. Distribution runs through direct sales relationships with large personal care processors and dairy cooperatives, bypassing traditional wholesaler intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward personal care brand owners consolidating procurement through direct resin specification, fragmenting converter intermediation across North American and European supply chains.
For Market Incumbents: Consolidate captive blow molding capacity across multiple state jurisdictions to defend against toll-manufacturing margin compression. Deepen FDA food-contact qualification libraries before state recycled content mandates accelerate. Threat of advanced recycling resin qualification delays creates first-mover advantage for converters with pre-approved material databases. Capacity addition in Gujarat and Maharashtra captures cost-advantaged export growth to African markets. For New Entrants and Emerging Players: Lifecycle assessment advisory services represent a service-layer gap where incumbents under-serve California EPR compliance requirements. White space concentrates in certified mass balance documentation and post-consumer regrind sourcing for West Coast converters facing enforcement deadlines. Most penetrable entry point: mid-tier personal care brands requiring sustainable packaging credentials without captive technical staffing. Go-to-market angle partners with regional distributors for inventory pooling and working capital efficiency. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational packaging conglomerates divesting non-core blow molding assets under portfolio rationalization. Long-term viability over the next decade hinges on backward integration into preform manufacturing and advanced recycling resin qualification capabilities. Acquisition archetype: regional specialists with FDA food-grade libraries and India-based cost positions. Signal to watch: FDA guidance finalization on chemical recycling-derived resins triggering brand owner capital commitment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Manufacturing | Captive supply of injection-molded neck finishes reduces dependency on external molders for pharmaceutical-grade tolerances. |
| Advanced Recycling Resin Qualification | FDA notification pathway for chemically recycled HDPE unlocks premium personal care contracts ahead of regulatory clarity. |
| India Manufacturing Footprint Expansion | Gujarat and Maharashtra clusters serve domestic edible oil demand plus export markets to Africa and Southeast Asia. |
| Metal Closure Bundling Integration | Combined HDPE bottle and aluminum closure supply reduces supplier management overhead for dairy and juice processors. |
| California EPR Compliance Service Development | Lifecycle assessment capabilities monetize regulatory advisory alongside physical supply to brand owners facing state mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA food-contact notification databases, state regulatory filings from California, and trade flow records from customs authorities. Primary interviews engaged blow molding plant managers, procurement leads at personal care brand owners, resin compounder technical directors, and dairy cooperative supply chain officers. Secondary validation drew from SEC 10-K filings of packaging conglomerates, American Chemistry Council resin statistics, and European Plastics Association capacity surveys. Bottom-up triangulation across converter production volumes and top-down reconciliation against end-use consumption patterns ensure cross-verified outputs.
Segmentation dimensions modeled include manufacturing process type, end-use industry vertical, packaging format specification, and geographic production hub concentration across the projection horizon. CAGRs derive from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific forecast inputs incorporate ethylene feedstock cost curves and state-level recycled content mandate implementation schedules. The analytical framework weights FDA qualification timelines and brand owner direct procurement adoption rates.
Underlying assumptions cover steady ethylene supply availability and incremental recycled content mandate enforcement, with deviation risk concentrated in advanced recycling resin regulatory approval delays and polymer engineering talent scarcity constraining process optimization. Recalibration cycles align with material shifts in FDA guidance publication and state EPR law implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Pocket Containers Market
Containers
Sandwich Containers Market
Containers
Single Wall Jars Market
Containers
North America Insulated Shipping Containers Market
Containers
Vials Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
Trays Market
Containers
EMEA Container Technology Market
Containers
Trigger Sprayer Market
Containers
Multi Cavity Tray Market
Containers
Snap-Lock Container Market
Containers
Metal IBC Market
Containers
Old Corrugated Containers (OCC) Market
Containers
Composite Ibcs System Market
Containers
Stackable Plastic Trays Market
Containers
USA and Canada Packer Bottle Market