
 Wooden Barrels Market | 2026-2036
Wooden Barrels Market Size, Share, and Industry Trends Forecast 2026-2036
Wooden Barrels Market Analytics
Market Context
Cooperage apprenticeship pipelines is bifurcating the Wooden Barrels Market into supply-constrained premium tiers and volume-driven standard segments. Seguin Moreau leverages its French oak heritage to dominate high-end winery contracts across Bordeaux and Burgundy. Independent Stave Company anchors North American bourbon demand through captive white oak forests and controlled stave seasoning yards in Missouri. Tonnellerie Francois Freres competes on technical customization, offering precise toast-and-char profiles that differentiate craft spirits portfolios.
Technical Definition and Segment Structure
Wooden barrels are cylindrical containers constructed from staves—tapered wooden planks—bound by metal hoops, with capacities typically ranging from 53 gallons for standard American whiskey barrels to 225 liters for Bordeaux-style wine casks; they function as controlled micro-oxidation vessels where lignin and hemicellulose degradation compounds interact with stored liquids to develop color, aroma, and mouthfeel complexity. Oak material sustains the dominant value share due to vanillin and lactone extraction chemistry prized in spirits maturation, while custom barrels command margin premiums through variable stave thickness and alternative toast gradients. Aging usage leads volume absorption across distilleries and wineries, though packaging applications for premium spirits gift formats represent the fastest-growing sub-segment.
Regulatory Framework and Outlook
The EU Timber Regulation and FDA food-contact substance rules shape stave provenance documentation and char residue thresholds for cross-border barrel shipments. France's ANSM and the US TTB enforce divergent labeling and additive restrictions that filter which cooperage techniques qualify for protected origin claims. Stakeholders must monitor emerging sustainability certification schemes and carbon-accounting pressures on long-rotation forestry before committing to multi-decade oak plantation investments.
Market Dynamics
Cooperage apprenticeship pipelines are contracting across France, Missouri, and Kentucky, constraining stave-toasting expertise just as craft distilleries expand aged-spirits programs. This talent scarcity is bifurcating production capacity between heritage cooperages and automated newcomers.
Growth Catalysts
- Craft spirits maturation:Small-batch distilleries in Kentucky and Tennessee are extending aging cycles, multiplying barrel turns per proof gallon. This pulls premium American white oak into multi-year captive contracts.
- EU Timber Regulation traceability mandates:Digitized chain-of-custody documentation now penetrates French oak supply networks, qualifying Limousin-sourced staves for protected-origin wine labeling schemes.
- Toast-gradient customization:Variable char profiling allows distillers to specify lignin extraction rates, creating flavor signatures that differentiate shelf positioning.
Market Restraints
- White oak supply concentration:Missouri and Arkansas forests supply 70% of American cooperage material, exposing buyers to climate-stress mortality and logging-permit volatility.
- Long-rotation forestry economics:80-120 year harvest cycles prevent rapid supply response to demand spikes, locking in fixed-cost plantation structures.
- Steel tank substitution:Stainless-steel vessels with oak-chip infusion systems capture entry-level wine and spirits aging, compressing standard-barrel pricing power.
Strategic Opportunities
- Eastern European oak expansion:Hungarian and Romanian forests offer untapped Quercus robur reserves with comparable tannin profiles to French oak, awaiting certification infrastructure.
- Carbon-accounting integration:EU Green Deal compliance frameworks reward cooperages that document stave-seasoning energy use and transport emissions, creating premium-tier differentiation.
- Direct-to-distillery stave sales:Bypassing finished-barrel fabrication, raw stave producers can capture margin from in-house cooperage operations at scale wineries.
Industry Challenges
- Master cooper skill attrition:France's compagnonnage apprenticeship system graduates fewer stave-bending specialists annually than retirements demand, eroding quality-consistency at heritage houses.
- Multi-jurisdiction compliance layering:FDA food-contact substance rules for char residue diverge from ANSM additive restrictions, forcing dual-testing protocols for cross-Atlantic barrel shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wooden Barrels Market |
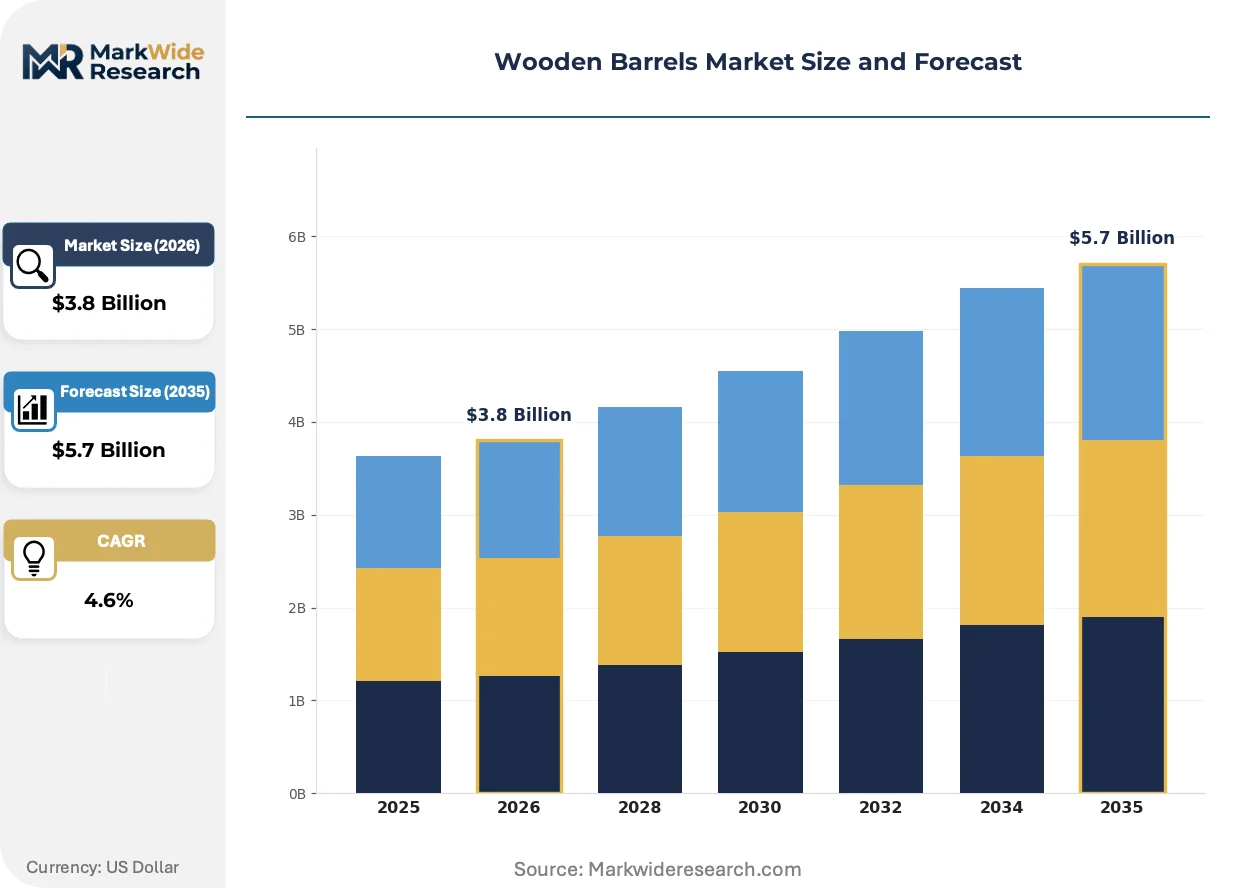
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Barrels, Custom Barrels, Mini Barrels, Oversized Barrels Material: Oak, Pine, Cedar, Birch End User: Distilleries, Breweries, Wineries, Food Manufacturers Usage: Aging, Storage, Transportation, Packaging |
| Companies Covered | Seguin Moreau, McGinnis Wood Products, Independent Stave Company, ZAK Cooperage, Charlois, Tonnellerie Francois Freres, The Barrel Mill, West Virginia Great Barrel Company, Brown-Forman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wooden Barrels Market Evolving Landscape
Thermal modification and precision-toast engineering are rewriting extraction chemistry, while digital traceability and shifting procurement calendars reshape how cooperages contract with distilleries and wineries.
Infrared stave-toasting systems are bifurcating the precision-cooperage segment from traditional open-fire methods. Kentucky bourbon distillers now specify surface-temperature profiles to the degree Celsius, compressing batch-to-batch variance. This thermal control is enabling micro-distilleries to replicate heritage-house flavor signatures without century-old apprenticeship depth.
EU Timber Regulation geolocation requirements now mandate GPS-tagged harvest documentation for every stave entering cross-border trade. French cooperages have restructured supplier relationships around certified forestry management units, absorbing compliance costs into premium pricing. Bordeaux châteaux now audit barrel provenance as a condition of contract renewal, shifting procurement criteria from price-per-unit to chain-of-custody integrity.
Distillery procurement calendars are compressing from annual to quarterly ordering cycles as aged-spirits forecasting tightens. This rhythm change strains cooperage production scheduling, which optimized around vintage-driven winery seasonality. Tennessee whiskey producers now negotiate flexible delivery windows with penalty clauses, transferring inventory-risk upstream to stave suppliers.
Wooden Barrels Market Segmentation
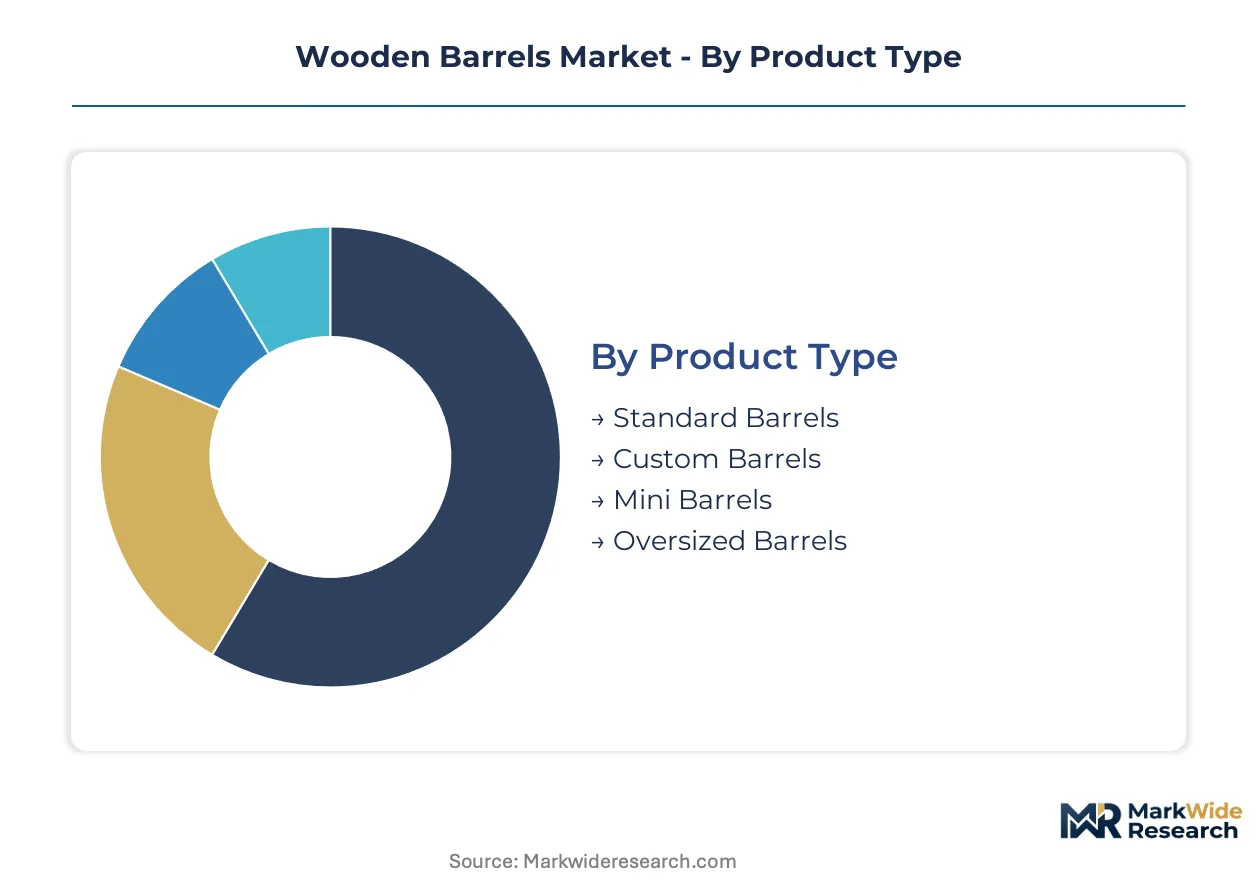
Wooden barrel segmentation reflects divergent compliance burdens across product tiers and end-use applications. FDA food-contact substance rules and EU Timber Regulation traceability mandates filter which material grades and usage modes qualify for cross-border trade.
Product Type:
Regulatory differentiation separates precision-toast custom fabrications from commodity standard barrels, with compliance documentation costs concentrating in premium tiers.
- Standard Barrels:These 53-gallon American whiskey and 225-liter Bordeaux-format vessels dominate volume throughput across Kentucky bourbon houses and French châteaux. Missouri-sourced white oak staves undergo open-fire charring protocols that satisfy TTB additive restrictions but lack the temperature-precision documentation now required for EU Green Deal carbon-accounting claims. Standard barrels handle the majority of throughput; custom barrels are the fastest mover on share.
- Custom Barrels:Variable stave thickness, alternative toast gradients, and proprietary char profiles define this tier, with infrared toasting systems enabling surface-temperature specification to the degree Celsius. Kentucky craft distilleries and Napa Valley wineries specify lignin extraction rates to create differentiated flavor signatures that command protected-origin labeling status under ANSM and TTB frameworks.
- Mini Barrels:Premium spirits gift formats and tasting-room retail drive demand for sub-5-liter capacities, with FDA food-contact rules governing char residue thresholds in direct-consumer packaging applications.
- Oversized Barrels:Bulk wine fermentation and craft beer conditioning utilize capacities exceeding 500 liters, requiring reinforced hoop specifications under OSHA material-handling guidelines.
Cost tier stratification separates captive-contract premium fabrications from spot-market commodity supply.
Material:
Application requirements dictate material selection, with extractive chemistry and durability specifications varying sharply across spirits maturation versus food storage end-uses.
- Oak:American white oak from Missouri and Arkansas forests supplies vanillin and lactone extraction chemistry prized in bourbon and whiskey maturation, while French Limousin oak dominates protected-origin wine aging through centuries-old seasoning expertise. Oak commands the dominant value share; cedar is expanding most quickly in alternative-material niches.
- Pine:Lower tannin content and faster stave production cycles position pine for entry-level wine storage and short-cycle beer conditioning where lignin extraction is undesirable.
- Cedar:Natural insect resistance and aromatic properties suit cedar for specialty food storage and non-liquid containment applications outside FDA food-contact char residue thresholds.
- Birch:Neutral flavor profile and tight grain structure enable birch deployment in craft spirits finishing where oak intensity requires moderation.
Geographic sourcing concentration in specific forestry regions determines material availability and certification compliance pathways.
End User:
Customer type dictates procurement rhythm and specification complexity, with aged-spirits forecasting tightening order cycles across distillery portfolios.
- Distilleries:Kentucky and Tennessee bourbon producers extend aging cycles and multiply barrel turns per proof gallon, pulling premium American white oak into multi-year captive contracts with flexible delivery windows and penalty clauses.
- Breweries:Sour beer programs and barrel-aged stout portfolios drive demand for ex-spirits casks with residual char chemistry, requiring coordination with distillery decommissioning schedules.
- Wineries:Bordeaux châteaux and Burgundy houses audit barrel provenance as a condition of contract renewal, shifting procurement criteria from price-per-unit to chain-of-custody integrity under EU Timber Regulation geolocation mandates.
- Food Manufacturers:Pickle fermentation, sauce aging, and specialty condiment storage utilize neutral-toast barrels outside spirits-specific char protocols, with FDA food-contact substance rules governing direct food contact applications.
Volume concentration in distillery and winery procurement strains cooperage production scheduling optimized around vintage-driven seasonality.
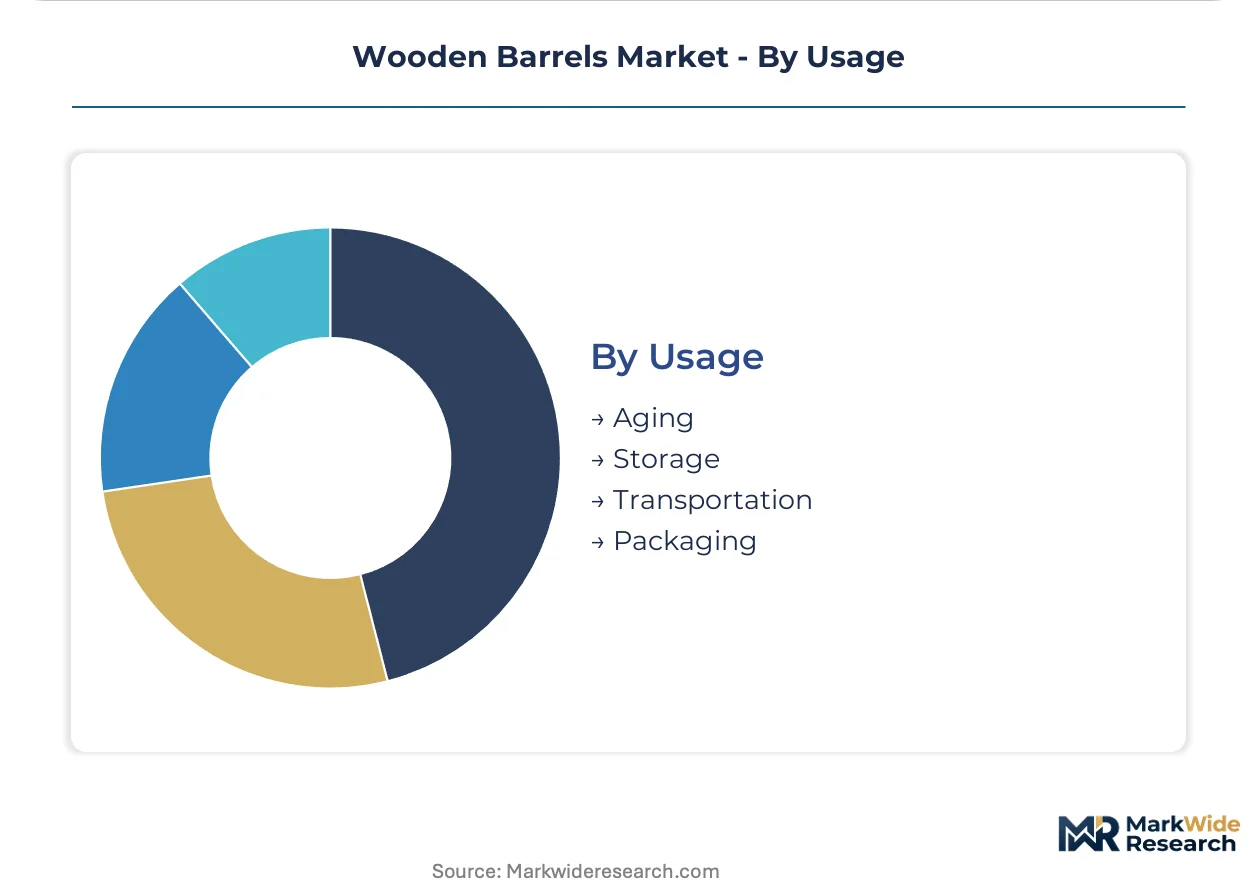
Usage:
Functional mode determines barrel lifecycle and replacement frequency, with aging applications commanding premium pricing against single-use packaging alternatives.
- Aging:Controlled micro-oxidation vessels enable lignin and hemicellulose degradation compound interaction with stored liquids, developing color, aroma, and mouthfeel complexity over multi-year cycles in Kentucky bourbon houses and French wine cooperatives.
- Storage:Bulk liquid containment and intermediate holding applications prioritize structural integrity over extractive chemistry, with stainless-steel substitution pressuring pricing power in this segment.
- Transportation:Historical shipping functions have contracted to specialty craft spirits distribution and museum-grade historical reenactment, with DOT hazardous materials regulations governing residual liquid content in transit.
- Packaging:Premium spirits gift formats and tasting-room retail represent the fastest-growing sub-segment, with mini barrel capacities and custom engraving commanding margin premiums in direct-to-consumer channels.
Maturity differentiation separates decades-long aging investment from single-use packaging consumption, with replacement cycle economics favoring aging applications for cooperage revenue stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US TTB and France's ANSM anchor regulatory frameworks for cross-border barrel trade, with divergent char residue and additive rules shaping procurement strategies across Kentucky bourbon houses and Limousin cooperages.
United States
Kentucky and Tennessee distilleries extend aging cycles for small-batch bourbon programs, multiplying barrel turns per proof gallon. The TTB enforces strict additive restrictions on char protocols that qualify for straight whiskey labeling. Louisville and Bardstown anchor American white oak demand through multi-year captive contracts with Missouri stave suppliers.
France
Bordeaux châteaux and Burgundy houses audit barrel provenance as a condition of contract renewal, prioritizing chain-of-custody integrity. ANSM additive restrictions and EU Timber Regulation geolocation mandates filter which cooperage techniques qualify for protected-origin claims. The Limousin forest region sustains centuries-old oak seasoning expertise for premium wine aging.
Hungary
Quercus robur reserves in Hungarian forests offer comparable tannin profiles to French oak, awaiting full certification infrastructure for EU protected-origin labeling. The country's national forestry regulator oversees sustainable harvest quotas for stave-bound timber. Tokaj wine region cooperatives pilot Eastern European oak maturation programs for regional spirit portfolios.
Romania
Untapped Carpathian oak forests attract interest from cooperages seeking supply diversification beyond Limousin and Missouri concentrations. EU Timber Regulation compliance documentation remains under development for cross-border stave shipments. Transylvanian forestry management units negotiate supplier relationships with French barrel houses.
Spain
Sherry bodegas in Jerez de la Frontera maintain traditional American oak usage for fino and oloroso solera systems, sustaining distinct flavor chemistry from bourbon-centric char protocols. The country's national food safety regulator governs barrel hygiene standards for protected-origin sherry labeling. Andalusian cooperages balance heritage fabrication methods against EU Green Deal carbon-accounting pressures.
Wooden Barrels Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision-toast engineering specialists commanding premium pricing against volume-driven standard barrel fabricators. The market structures around heritage cooperages with compagnonnage-trained master coopers and automated newcomers deploying infrared toasting systems. Two strategic archetypes dominate: captive-forest integrated producers controlling stave seasoning yards, and technical customization houses offering proprietary char profiles. Competitive moves concentrate on multi-year distillery contracts with flexible delivery windows and carbon-accounting documentation for EU Green Deal compliance.
Among heritage French houses, Seguin Moreau and Tonnellerie Francois Freres exemplify the premium-tier archetype through Limousin oak specialization and technical customization capabilities. Independent Stave Company anchors the captive-forest integrated model with controlled white oak reserves and seasoning infrastructure. These three players occupy positions spanning Bordeaux winery contracts, Kentucky bourbon supply, and precision-toast engineering for craft spirits differentiation.
| Leading Market Players |
|---|
| Seguin Moreau |
| McGinnis Wood Products |
| Independent Stave Company |
| ZAK Cooperage |
| Charlois |
| Tonnellerie Francois Freres |
| The Barrel Mill |
| West Virginia Great Barrel Company |
| Brown-Forman Corporation |
| Others |
Value Network & Pricing Analysis
Multi-year captive contracts with flexible delivery windows lock in both American white oak supply access and price visibility for Kentucky bourbon distilleries, insulating premium cooperage tiers from spot-market volatility while compressing margin buffers at standard-barrel fabricators facing steel-tank substitution.
Pricing Analysis
Limousin-sourced French oak commands substantial premiums over Missouri white oak, with price differentiation driven by protected-origin certification status and century-old seasoning expertise. Three-tier pricing structure across premium custom-toast, standard open-fire char, and mini-barrel gift formats stratifies the market. Cost compression in standard-barrel tiers is intensifying because stainless-steel vessels with oak-chip infusion capture entry-level wine aging. Craft distilleries show least price sensitivity, prioritizing precise lignin extraction profiles over per-unit cost.
Supply Chain Analysis
Missouri and Arkansas anchor American white oak stave production, while France's Limousin forest sustains premium Quercus robur seasoning for Bordeaux and Burgundy contracts. The supply chain draws from 80-120 year harvest cycles, captive seasoning yards, and infrared toasting equipment. Single-source vulnerability concentrates in Missouri's 70% market share of cooperage material, exposing buyers to climate-stress mortality. Distribution runs through direct-to-distillery contracts for large producers and cooperage-house intermediaries for smaller wineries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against stainless-steel aging vessels with oak adjunct systems, which threaten standard-barrel pricing power and volume throughput.
For Market Incumbents: Consolidate backward integration into captive white oak forests and controlled seasoning infrastructure to secure multi-decade stave supply. Deepen technical customization capabilities through infrared toasting precision that steel-tank alternatives cannot replicate. Lock in craft distillery contracts with carbon-accounting documentation for EU Green Deal compliance. For New Entrants and Emerging Players: EU Timber Regulation certification fast-track offers entry into French cooperage networks previously closed to unverified stave sources. Target Hungarian and Romanian Quercus robur reserves where comparable tannin profiles await full protected-origin infrastructure. Lead with direct-to-distillery stave sales bypassing finished-barrel fabrication to capture margin from in-house cooperage operations. For Investors and Strategic Acquirers: Capital is best deployed toward heritage cooperages with compagnonnage-trained master coopers and established Limousin oak relationships, given irreplaceable apprenticeship pipelines. Long-term viability hinges on sustained premiumization in aged-spirits portfolios and protected-origin wine labeling schemes. Watch for inflection in EU Timber Regulation enforcement intensity across Eastern European forest regions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Forests | Secures 80-120 year harvest cycles against climate-stress mortality in Missouri and Arkansas. |
| Infrared Toasting Technology Deployment | Enables degree-Celsius precision that differentiates craft spirits from steel-tank competitors. |
| EU Timber Regulation Certification | Qualifies Limousin and Eastern European staves for protected-origin wine labeling schemes. |
| Carbon-Accounting Documentation | Creates premium-tier differentiation under EU Green Deal compliance frameworks. |
| Direct-to-Distillery Stave Sales | Captures margin from scale wineries operating in-house cooperage operations. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with master coopers, distillery procurement directors, and winery cellar masters; and secondary validation through TTB additive filings, ANSM regulatory registers, EU Timber Regulation geolocation databases, and customs stave import records. Bottom-up volume triangulation across cooperage fabrication capacity merged with top-down demand modeling from aged-spirits forecasting and vintage-driven winery procurement cycles.
Across the analysis window, projections incorporated product type segmentation by toast precision, material grade by geographic oak origin, end-user category by spirits versus wine versus food manufacturing, and usage mode by aging versus packaging applications. CAGRs derived from historical capacity expansion rates, plantation establishment timelines, and substitution elasticity estimates for steel-tank alternatives. Industry-specific inputs included apprenticeship graduation rates from French compagnonnage systems and climate-mortality models for white oak stands.
Decision-makers should treat outputs as directional under sustained craft spirits premiumization and EU regulatory enforcement intensity; material deviation in steel-tank adoption curves or Eastern European certification timelines would warrant model refresh. Recalibration cycles align with material shifts in EU Green Deal carbon-accounting requirements and TTB additive restriction amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Stackable Container Market
Containers
Shipping Container Liners Market
Containers
Slotted Containers Market
Containers
Global Flexitanks Market
Containers
Multi Cavity Tray Market
Containers
Wooden Crates Market
Containers
High Density Polyethylene (HDPE) Bottles Market
Containers
Screw Top Lids Market
Containers
Disposable Cups and Lids Market
Containers
North America Plastic Bottles and Containers Market
Containers
Global Container Monitoring Market
Containers
Thermoformed Containers Market
Containers
EPS Shippers Market
Containers
Foldable Large Containers Market
Containers
Grab and Go Containers Market
Containers
HDPE Containers Market