
 Metal Forming Tools Market | 2026-2036
Metal Forming Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Forming Tools Market Intelligence
German precision engineering capacity is pivoting toward high-tonnage servo press lines. TRUMPF Group leverages its laser-hybrid forming portfolio to dominate European automotive tool supply. Schuler AG anchors North American EV battery housing production through its US-based press assembly footprint. Amada Co., Ltd. competes in Asian electronics forming with compact CNC turret punch specialization.
Metal forming tools are mechanical systems that apply controlled force to deform sheet or bulk metal into specified geometries, typically operating at pressures from hundreds to thousands of tons depending on material thickness and part complexity. These systems serve primary industrial purpose in mass-producing dimensionally consistent structural components across transportation, energy, and consumer goods sectors. Stamping tools command the largest installed base among product categories, reflecting decades of automotive body-in-white dependence, while CNC machines represent the fastest-growing technology segment as fabricators replace mechanical presses for programmable flexibility. Bending machines concentrate margin pools in job-shop environments where quick tool-change capability reduces setup downtime.
EU machinery directives and CE marking requirements enforce safety interlocks and ergonomic guarding that elevate equipment cost but filter low-compliance imports from non-European suppliers. EPA and OSHA frameworks in the United States impose noise and occupational exposure limits that push manufacturers toward enclosed, servo-driven press architectures. Stakeholders must monitor how carbon border adjustments and embodied-emissions tracking reshape sourcing decisions for steel-intensive tool frames.
Market Dynamics
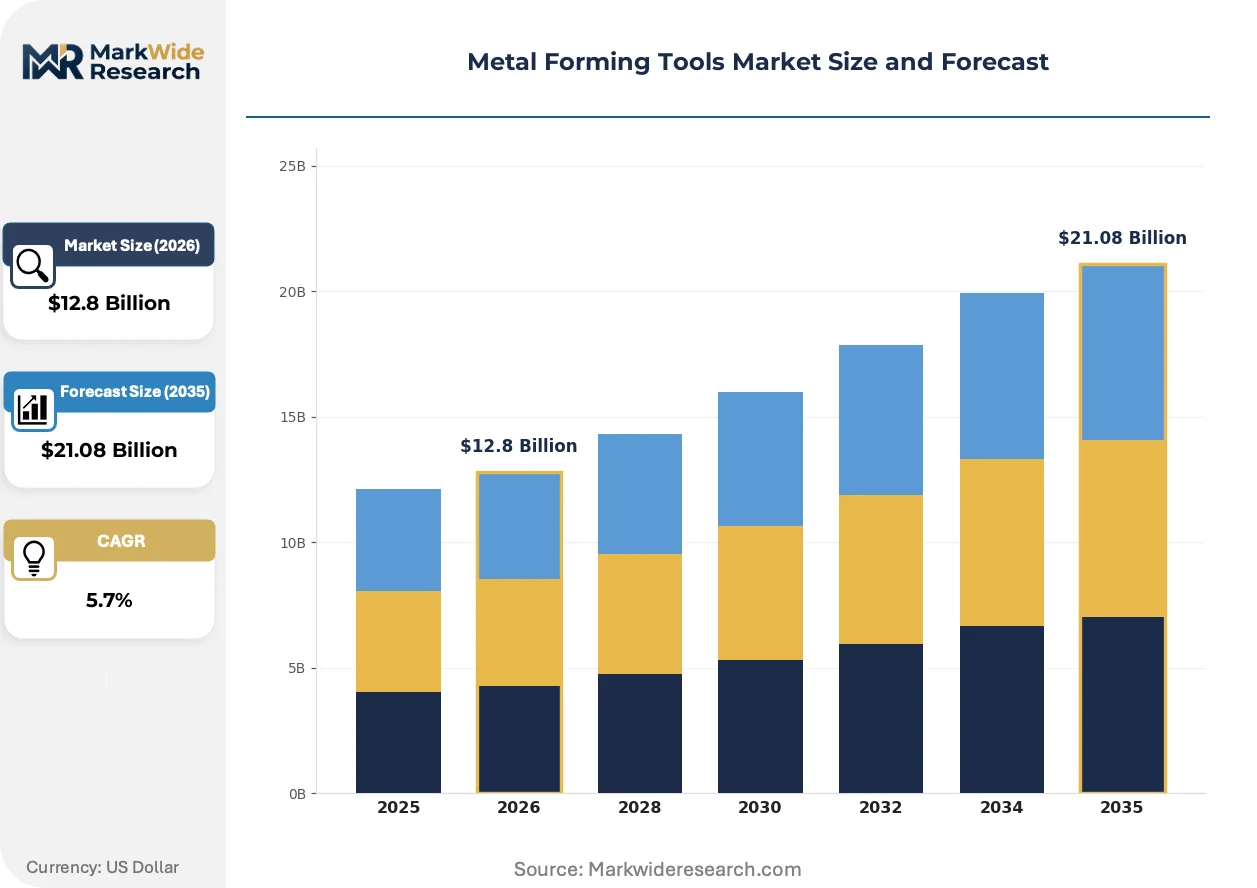
Servo-electric press technology is compressing mechanical press replacement cycles across automotive and appliance manufacturing, while CE marking enforcement under EU machinery directives filters marginal European suppliers from precision forming equipment procurement.
Growth Catalysts
- EU machinery safety mandates:CE marking requirements for interlocked guarding and ergonomic controls are accelerating fabricator upgrades toward enclosed servo press architectures that satisfy compliance without secondary retrofit costs.
- Electric vehicle battery housing demand:Automotive OEMs in Germany and Japan are commissioning high-tonnage press lines specifically for aluminum tray and cover stampings, pulling tool orders from established European suppliers.
- CNC turret punch specialization:Electronics contract manufacturers around Shenzhen are scaling compact programmable forming centers for consumer device chassis production, displacing dedicated hard-tooling setups.
Market Restraints
- Tool steel price volatility:Specialty alloy input costs for die frames and punch inserts fluctuate with nickel and molybdenum commodity markets, compressing margin predictability for mid-size tool builders.
- Supply concentration in German precision components:Critical servo drive systems and linear motion assemblies concentrate among a narrow supplier base in Baden-Württemberg, exposing lead time vulnerability.
- Mechanical press residual life:Decades of installed mechanical press capacity in North American job shops creates substitution inertia against higher-first-cost servo alternatives despite operating efficiency gains.
Strategic Opportunities
- India PLI scheme for auto component manufacturing:Production-linked incentives for advanced automotive parts are attracting press line investments into Pune and Chennai industrial corridors where domestic tool sourcing remains underdeveloped.
- Laser-hybrid forming convergence:Integration of fiber laser cutting with servo press forming in single-cell configurations enables complex part production without transfer die investments, opening mid-volume appliance and agricultural equipment applications.
- Remanufactured tool channels:Certified rebuild programs for mechanical press frames and die sets are emerging as a formal procurement category among cost-constrained tier-two automotive stampers in Mexico and Eastern Europe.
Industry Challenges
- Servo press commissioning expertise:The shift from mechanical to electronically controlled forming systems demands controls engineers and mechatronics technicians that traditional tool-and-die apprenticeship programs have not scaled to produce.
- CE technical documentation burden:Comprehensive risk assessment and notified body involvement for custom press lines extends delivery timelines by four to eight months versus pre-certified standard equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Forming Tools Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stamping Tools, Bending Machines, Forging Equipment, Punching Tools Technology: Hydraulic Systems, Mechanical Presses, CNC Machines, Laser Cutting End User: Aerospace, Automotive Components, Electronics Manufacturing, Construction Material Type: Aluminum, Steel, Copper, Titanium |
| Companies Covered | DMG Mori, LVD Group, TRUMPF Group, Cincinnati Incorporated, Bystronic, Amada Co., Ltd., JIER Machine-Tool Group, Komatsu Ltd., Schuler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Forming Tools Market Strategic Shifts & Innovations
Active tooling intelligence and predictive maintenance integration are redefining how fabricators justify capital expenditure, moving evaluation criteria from throughput metrics to total operational availability guarantees.
Servo-electric press technology is absorbing the forming workload previously allocated to mechanical flywheel presses in automotive body-in-white applications. Tier-one stampers in Germany and Japan are specifying all-electric lines for new EV platform launches, citing programmable slide motion profiles that reduce die wear and enable lightweight material forming. This displacement is compressing the residual value of installed mechanical capacity and accelerating secondary market saturation.
REACH restrictions on hexavalent chromium surface treatments are forcing tool steel suppliers toward alternative hard-coating chemistries for punch and die protection. European tool builders must validate tungsten carbide and physical vapor deposition substitutes through extended wear testing before qualifying for automotive supplier approvals. The transition burden falls heaviest on mid-size job shops serving diversified industrial end-uses where coating specification flexibility remains limited.
Consolidated procurement through automotive OEM direct equipment specification is displacing traditional distributor channels for large press lines. Stamping suppliers in China's Yangtze River Delta now negotiate tooling packages as part of platform sourcing agreements rather than independent capital purchases, compressing vendor margins but securing multi-year service commitments. This channel compression is most visible in battery housing and structural component categories where OEMs enforce process standardization across supplier networks.
Metal Forming Tools Market Segmentation
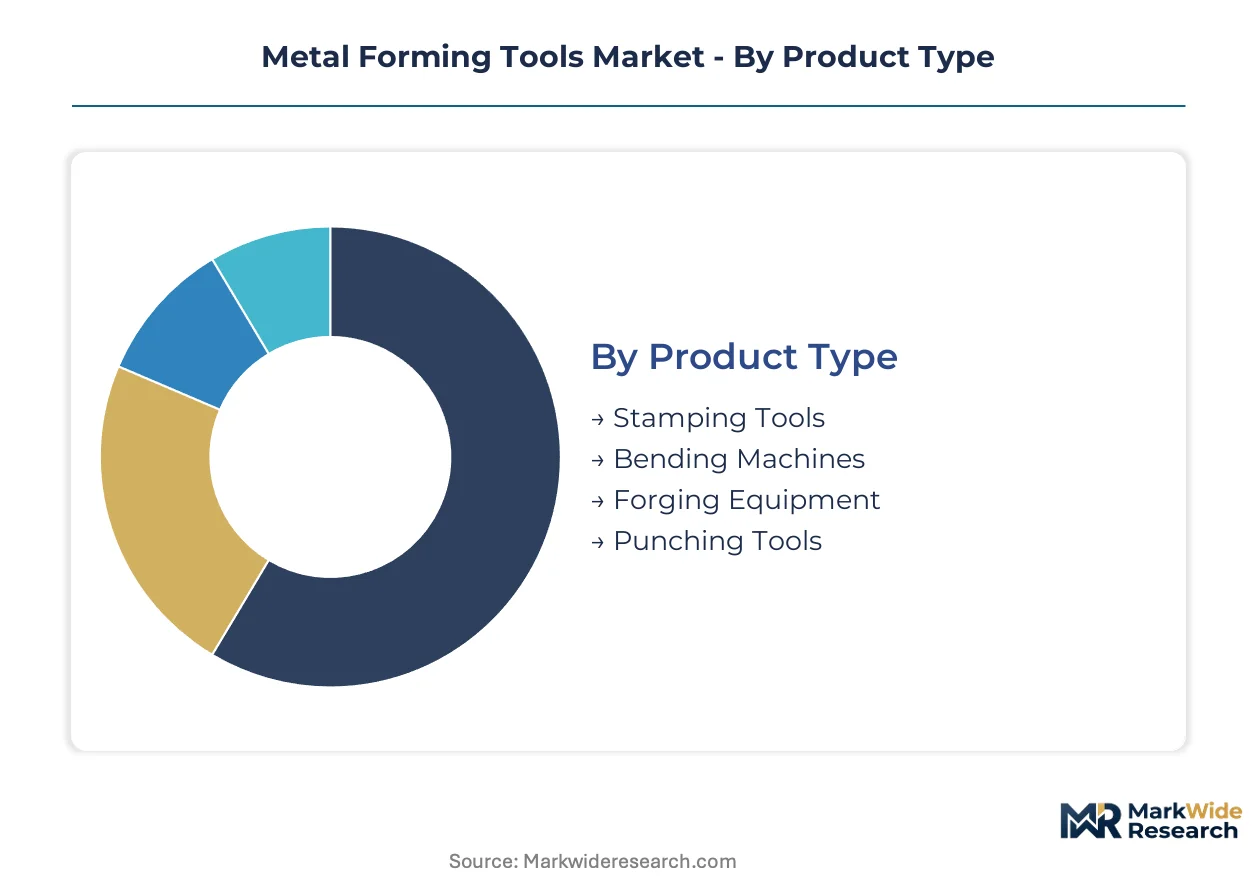
Metal forming tools exhibit distinct performance profiles across product architectures, automation levels, and material compatibility. Procurement decisions increasingly prioritize programmable flexibility over raw tonnage capacity as fabricators adapt to shorter production runs and mixed-material processing requirements.
Product Type:
Replacement cycles diverge sharply across mechanical versus electronically controlled forming architectures, with servo-driven systems commanding accelerated upgrade timelines.
- Stamping Tools:These progressive and transfer die systems process sheet metal through sequential forming stations at cycle rates exceeding 30 strokes per minute. Automotive body-in-white programs in Germany and Japan anchor demand, though battery tray stampings for electric vehicles are pulling aluminum-capable tool orders toward higher tonnage specifications.
- Bending Machines:Press brakes and panel benders apply localized force to achieve angular deformation without material thinning. Job-shop environments in China's Pearl River Delta prioritize quick tool-change configurations that compress setup intervals below 15 minutes for diversified contract manufacturing.
- Forging Equipment:Closed-die and open-die hammer systems shape bulk metal through compressive deformation at elevated temperatures. Aerospace landing gear suppliers specify isothermal forging presses for titanium alloy processing.
- Punching Tools:Turret and single-station configurations perforate sheet stock through hardened punch-and-die assemblies. Electronics chassis manufacturers favor compact CNC turret systems for consumer device production.
Stamping tools sit at the top of the volume ranking, with CNC bending machines climbing the fastest as fabricators replace mechanical press brakes.
Technology:
Capital allocation patterns reveal a structural pivot toward electronically controlled motion systems that reduce energy consumption and enable programmable slide profiles.
- Hydraulic Systems:Fluid-powered actuation delivers consistent force across the full stroke length, accommodating deep-draw applications and variable material thickness. Heavy-gauge appliance and agricultural equipment producers retain hydraulic preferences for forming depths exceeding 300 millimeters.
- Mechanical Presses:Flywheel-driven crank mechanisms convert rotational inertia into linear forming force at high cycle rates. North American job shops exhibit substitution inertia due to decades of installed mechanical capacity and lower first-cost thresholds.
- CNC Machines:Computer-numerical control enables programmable slide motion, real-time position feedback, and integrated part handling. Japanese automotive stampers specify all-electric CNC lines for new EV platform launches citing die wear reduction.
- Laser Cutting:Fiber laser systems integrate with forming cells to enable blank preparation and edge trimming without dedicated hard tooling. European appliance manufacturers adopt laser-hybrid configurations for mid-volume production.
Mechanical presses retain the largest installed base, though CNC machines are expanding most quickly as CE marking compliance accelerates servo press procurement.
End User:
Industry-specific forming requirements drive divergent equipment specifications, from precision tolerances in electronics to structural integrity demands in transportation.
- Aerospace:Titanium and superalloy forming demands isothermal presses with vacuum chamber integration and precise temperature control. Landing gear and engine component suppliers specify equipment validated to NADCAP special process requirements.
- Automotive Components:Body-in-white stampings and battery housing production consume the highest tonnage capacity. German OEMs commission high-speed transfer press lines for aluminum-intensive EV architectures.
- Electronics Manufacturing:Miniaturized chassis and heat sink components require compact turret punch and precision press brake systems. Shenzhen contract manufacturers scale programmable forming centers for rapid product changeovers.
- Construction:Structural steel profiles and facade systems utilize heavy-gauge press brake and roll forming equipment. Infrastructure stimulus programs in India are attracting press line investments into Pune industrial corridors.
Automotive components command the dominant revenue share, with electronics manufacturing gaining share fastest as consumer device production concentrates in Asian manufacturing clusters.
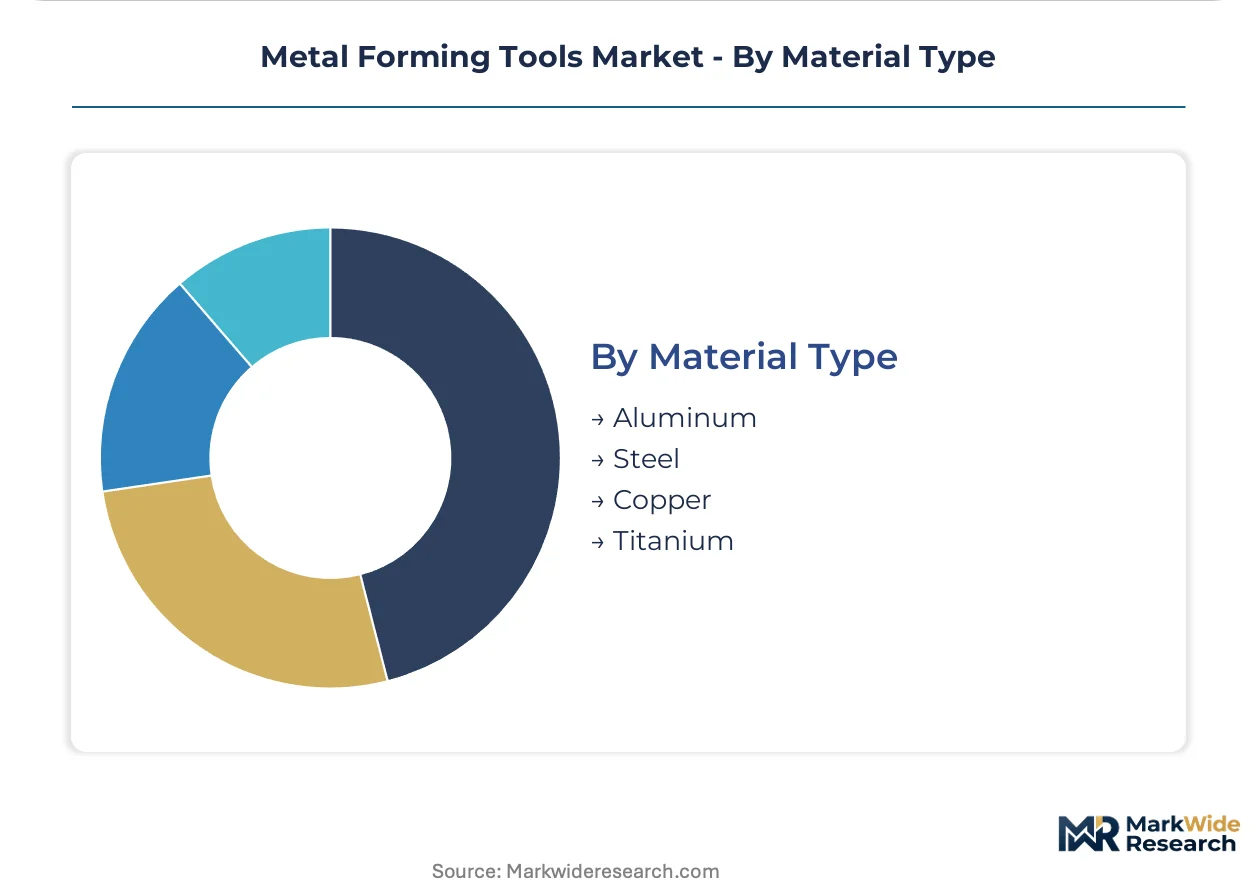
Material Type:
Forming equipment specification varies with workpiece metallurgy, with strength-to-weight ratios and springback behavior dictating press selection and die design.
- Aluminum:Lower yield strength and higher thermal conductivity enable faster forming cycles but demand modified die radii to prevent cracking. EV battery tray stampings are pulling aluminum-capable press investments.
- Steel:High-strength and advanced high-strength grades require elevated forming pressures and precision slide control to manage springback. Automotive structural components remain the dominant steel forming application.
- Copper:Excellent ductility permits deep drawing and complex geometries for electrical conductor and heat exchange applications. Busbar and connector manufacturers specify dedicated forming cells.
- Titanium:High strength-to-weight ratio and temperature sensitivity necessitate isothermal forming presses with controlled heating systems. Aerospace fastener and structural component suppliers dominate titanium forming demand.
Steel processing retains the largest equipment installed base, with aluminum forming capacity expanding most quickly as automotive lightweighting accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration toward jurisdictions with streamlined machinery certification is reshaping capital allocation. Fabricators in lower-compliance-cost environments capture contract manufacturing overflow from European and Japanese OEMs. This regulatory arbitrage concentrates new press line investments in specific industrial corridors.
China
Electric vehicle battery housing demand drives high-tonnage press orders. MIIT domestic equipment incentives favor local tool builders over imports. Shenzhen and Shanghai industrial clusters scale CNC turret punch capacity for consumer electronics chassis production.
Germany
Automotive OEM tool replacement programs prioritize servo-electric press architectures. CE marking enforcement under EU machinery directives filters marginal suppliers from precision equipment procurement. Baden-Württemberg concentration in servo drive components creates lead time vulnerability for European fabricators.
United States
EPA noise limits and OSHA occupational exposure frameworks push manufacturers toward enclosed press designs. North American job shops exhibit substitution inertia against servo alternatives due to decades of installed mechanical capacity. Midwest automotive stamping corridors see selective EV platform investments.
Japan
METI technology roadmaps prioritize energy-efficient forming systems. Japanese automotive stampers specify all-electric CNC lines for aluminum-intensive EV architectures. Nagoya and Osaka manufacturing belts concentrate compact programmable forming center production.
India
PLI scheme production-linked incentives attract press line investments into automotive component manufacturing. Domestic tool sourcing remains underdeveloped, creating procurement gaps for tier-one stampers. Pune and Chennai industrial corridors emerge as primary investment destinations.
Metal Forming Tools Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue laser-hybrid and servo-electric specializations. The vendor base spans German precision engineering houses, Japanese electronics-focused fabricators, and Chinese state-backed equipment groups. Three archetypes dominate: integrated press-line specialists, compact CNC specialists, and diversified machine-tool conglomerates. Competitive moves concentrate on technology licensing partnerships and geographic assembly footprint expansion.
Among German-based fabricators, TRUMPF Group and Schuler AG exemplify the integrated press-line archetype, anchoring European automotive supplier relationships through domestic engineering depth and North American assembly presence. Amada Co., Ltd. occupies a distinct position as a Japanese specialist in compact CNC forming systems, representing the electronics manufacturing tier where programmable flexibility commands premium positioning.
| Leading Market Players |
|---|
| DMG Mori |
| LVD Group |
| TRUMPF Group |
| Cincinnati Incorporated |
| Bystronic |
| Amada Co., Ltd. |
| JIER Machine-Tool Group |
| Komatsu Ltd. |
| Schuler AG |
| Others |
Cost & Logistics Intelligence
EU carbon border adjustment mechanisms and embodied-emissions tracking protocols are gating qualified supply access for steel-intensive tool frames, with fabricators demonstrating compliance commanding premium-tier pricing while non-certified imports face margin compression from secondary verification costs.
Pricing Analysis
Distributor margin layers in European markets face compression as automotive OEMs consolidate procurement through direct equipment specification, bypassing traditional channels for large press lines. Three-tier pricing structure across premium, standard, and economy levels stratifies by CE marking certification depth and servo-electric versus mechanical architecture. Price differentiation hinges on programmable flexibility and after-sales service bundling. Cost compression in mid-size job-shop segments is intensifying because REACH-compliant coating substitutes extend qualification timelines. Tier-two automotive stampers in Mexico and Eastern Europe exhibit highest price sensitivity, while German OEMs prioritize total operational availability over first-cost thresholds.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for EV battery housing press lines, while distributor networks retain relevance in job-shop environments. Geographic supply concentration centers on Germany for precision servo drive systems, Japan for compact CNC forming centers, and China for domestic equipment scaling under MIIT incentives. Raw material dependencies draw from specialty alloy tool steels, linear motion assemblies, and fiber laser source modules. Single-source vulnerability in Baden-Württemberg servo component suppliers exposes European fabricators to lead time volatility. Distribution runs through platform sourcing agreements in China's Yangtze River Delta and independent capital purchases in North American Midwest corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Metal Forming Tools Market functions as a stable compounder, with automotive lightweighting mandates and EV platform launches generating sustained equipment replacement cycles across multiple geographies.
For Market Incumbents: Acquire servo-electric press technology portfolios to counter substitution pressure from laser-hybrid forming convergence. Consolidate aftermarket service networks in North American Midwest automotive corridors where decades of installed mechanical capacity create captive upgrade demand. Certification investment in REACH-compliant coating validation defends margin position against mid-size European job shops facing extended qualification timelines. For New Entrants and Emerging Players: Digital-channel routes through remanufactured tool platforms offer lowest-friction entry into cost-constrained tier-two automotive stampers. White-space targets concentrate in India's Pune and Chennai industrial corridors where PLI scheme incentives attract press line investments but domestic tool sourcing remains underdeveloped. Laser-hybrid forming specialization for mid-volume appliance and agricultural equipment applications bypasses entrenched automotive supplier relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional press-line service specialists because fragmented aftermarket maintenance networks lack scale to offer total operational availability guarantees. Target acquisition archetypes include certified rebuild program operators in Mexico and Eastern Europe and compact CNC turret punch specialists serving Shenzhen electronics clusters. Watch for inflection in carbon border adjustment enforcement tightening as the signal for premium-tier pricing power consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Technology Acquisition | TRUMPF Group and Schuler AG anchor European automotive supply through laser-hybrid and high-tonnage press portfolios. |
| CE Marking Certification Investment | Compliance with EU machinery directives filters marginal suppliers and extends delivery timelines for custom press lines. |
| India Manufacturing Footprint Expansion | PLI scheme incentives attract press line investments into Pune and Chennai where domestic tool sourcing gaps persist. |
| Remanufactured Tool Channel Development | Certified rebuild programs emerge as formal procurement category among tier-two stampers in Mexico and Eastern Europe. |
| Laser-Hybrid Forming Integration | Single-cell fiber laser and servo press configurations enable complex part production without transfer die investments. |
Research Approach
Direct dialogue with plant engineers, OEM procurement teams, aftermarket service heads, and controls engineering specialists grounded qualitative findings, validated against customs trade records, SEC equipment manufacturer filings, MIIT domestic equipment incentive disclosures, and automotive production databases. Bottom-up and top-down triangulation cross-checked equipment shipment data against end-user capital expenditure patterns across German, Japanese, Chinese, and North American manufacturing clusters.
Bottom-up modeling aggregated segment-level equipment demand by product type, technology architecture, and end-use industry, while top-down analysis calibrated aggregate market sizing against macro industrial production indices. Segmentation dimensions across the analysis window span stamping versus bending versus forging equipment, hydraulic versus mechanical versus CNC versus laser systems, and automotive versus electronics versus aerospace versus construction end-uses. CAGRs derived from regression analysis of historical replacement cycles and projected EV platform launch timelines, with aluminum forming capacity expansion and servo press adoption curves as industry-specific forecast inputs.
Tool steel commodity volatility, CE marking documentation timeline extensions, and India PLI scheme implementation pace are the dominant revision risks that could shift equipment procurement patterns. Forecasts reflect documented assumptions regarding automotive lightweighting penetration rates and electronics manufacturing migration trends. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Thread Milling Machine Market
Tools
China Power Tools Market
Tools
Air Drills Market
Tools
Floor Scraper Market
Tools
Global DC Torque Tool Market
Tools
Tool Pliers Market
Tools
Aluminum Folding Ladders Market
Tools
Garden Digging Tools Market
Tools
Industrial Ladder Market
Tools
Quick Release Pins Market
Tools
Spray Gun Market
Tools
Core Shooter Machine Market
Tools
Hydraulic Tools and Equipment Market
Tools
Turning Tools Market
Tools
Brushcutter Market
Tools
Floor Saw Market