
 Hydraulic Tools and Equipment Market | 2026-2036
Hydraulic Tools and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Tools and Equipment Market Foresight
ISO 19859-grade tool specifications is collapsing the gap between premium and mid-tier product lines across the hydraulic tools sector. Enerpac Tool Group Corp. leverages its captive forging capacity to control input costs on high-pressure cylinders. Atlas Copco North America LLC anchors its position through dense rental-service depots across the Great Lakes manufacturing belt. LUKAS Hydraulik GmbH specializes in rescue-tool certifications that competitors struggle to replicate for European emergency-response procurement.
Hydraulic tools and equipment encompass force-multiplying devices that transmit pressurized fluid through sealed circuits to generate linear or rotational mechanical output, typically operating at pressures from 700 bar to 3,000 bar depending on application criticality. These systems serve primary industrial purposes including heavy-lift positioning, bolt-tensioning, structural pressing, and emergency extrication where electromechanical alternatives cannot deliver comparable power density. Jacks and cylinders occupy the mature volume core of the product mix, with margin pools concentrating in torque wrenches where calibration certification creates switching costs for buyers. Electric-hybrid technology is gaining fastest among technology categories as workshops seek to reduce pneumatic infrastructure dependency, while manual systems retain durable share in field-construction applications where power access remains unreliable.
FDA equipment-validation guidelines shape hydraulic tool deployment in pharmaceutical manufacturing cleanrooms, where fluid-seal integrity directly impacts contamination risk. EPA spill-prevention regulations under SPCC protocols mandate secondary containment for hydraulic fluid reservoirs above threshold capacities, altering reservoir design specifications for construction and marine applications. OSHA lockout-tagout standards enforce redundant pressure-relief verification on maintenance tooling, creating compliance-driven replacement cycles for older single-valve systems. Stakeholders must monitor how emerging state-level right-to-repair legislation affects OEM channel control over proprietary hydraulic tool calibration services.
Market Dynamics
Electric-hybrid hydraulic systems are compressing replacement cycles for pneumatic infrastructure across industrial maintenance facilities, forcing capital allocation decisions toward integrated power units rather than standalone tool purchases.
Growth Catalysts
- Infrastructure Rehabilitation Mandates:Water utility modernization programs in the United States and Canada are expanding procurement of high-pressure hydraulic pumps for pipeline integrity testing and valve maintenance operations.
- REACH Substance Restrictions:European hydraulic fluid formulations face phased compliance deadlines, creating replacement demand for sealed-system tools that minimize exposure risks in manufacturing environments.
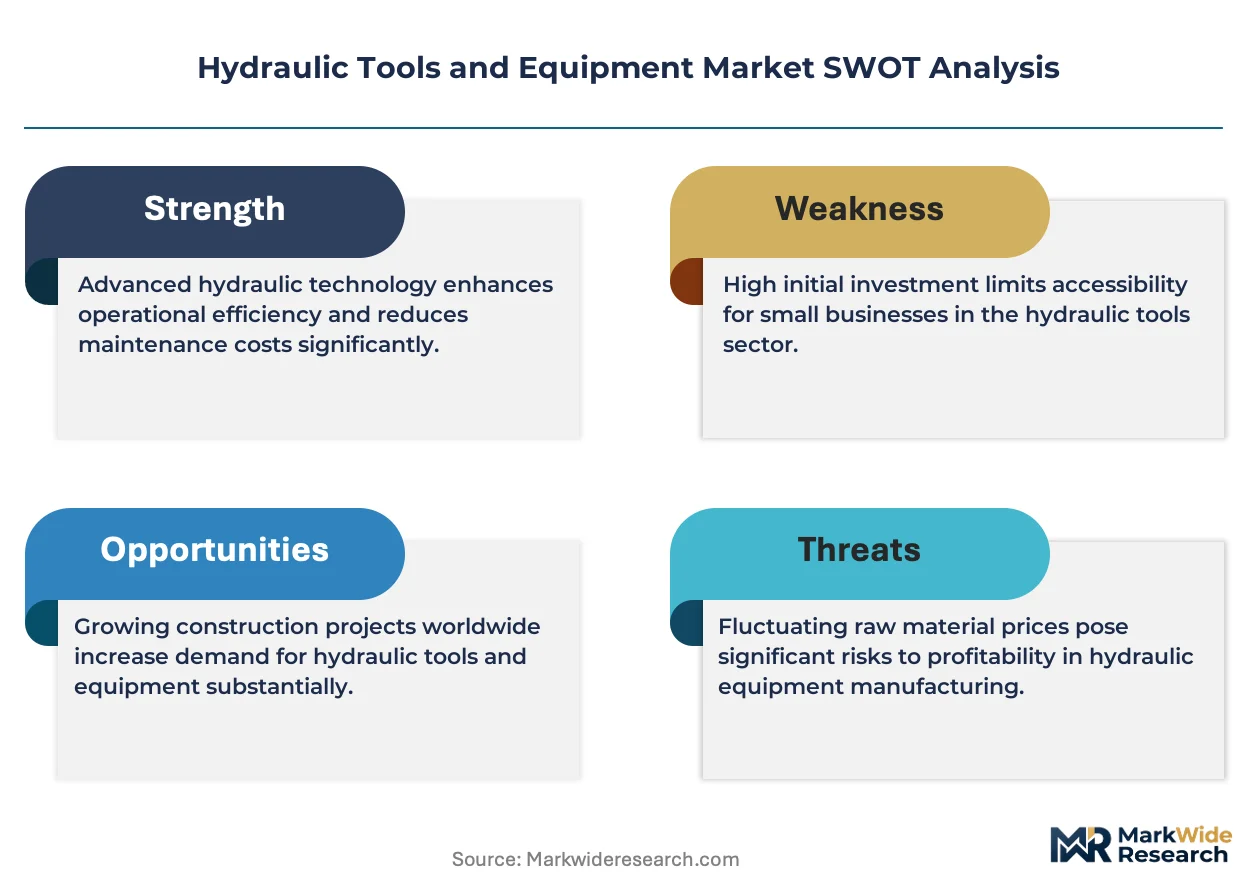
- Torque Calibration Standards:ISO 19859-grade specifications are elevating certified equipment requirements across wind turbine assembly lines and precision manufacturing facilities.
Market Restraints
- Specialized Steel Input Volatility:High-grade alloy sourcing for cylinder forgings concentrates among a limited supplier base, exposing production costs to commodity price swings.
- Electromechanical Substitution:Battery-powered torque tools achieve sufficient precision for mid-range applications, eroding addressable volume in automotive assembly maintenance.
- OSHA Compliance Friction:Lockout-tagout verification requirements extend procurement timelines for maintenance departments seeking rapid tool deployment.
Strategic Opportunities
- India Manufacturing Corridors:PLI scheme incentives for heavy machinery production are expanding domestic demand for calibrated assembly tools in Gujarat and Tamil Nadu industrial zones.
- Marine Decommissioning:North Sea platform retirement schedules are generating specialized cutting and lifting tool requirements for substructure dismantling contractors.
- Telematics Convergence:IoT-enabled pressure monitoring integrated with predictive maintenance platforms creates recurring revenue attachment for equipment fleets.
Industry Challenges
- Certified Technician Scarcity:Hydraulic system diagnostics and high-pressure seal maintenance require specialized training pipelines that vocational programs have not scaled to match equipment deployment rates.
- Legacy System Integration:Field-construction sites running decades-old pump architectures face compatibility barriers when incorporating modern electronic control interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Tools and Equipment Market |
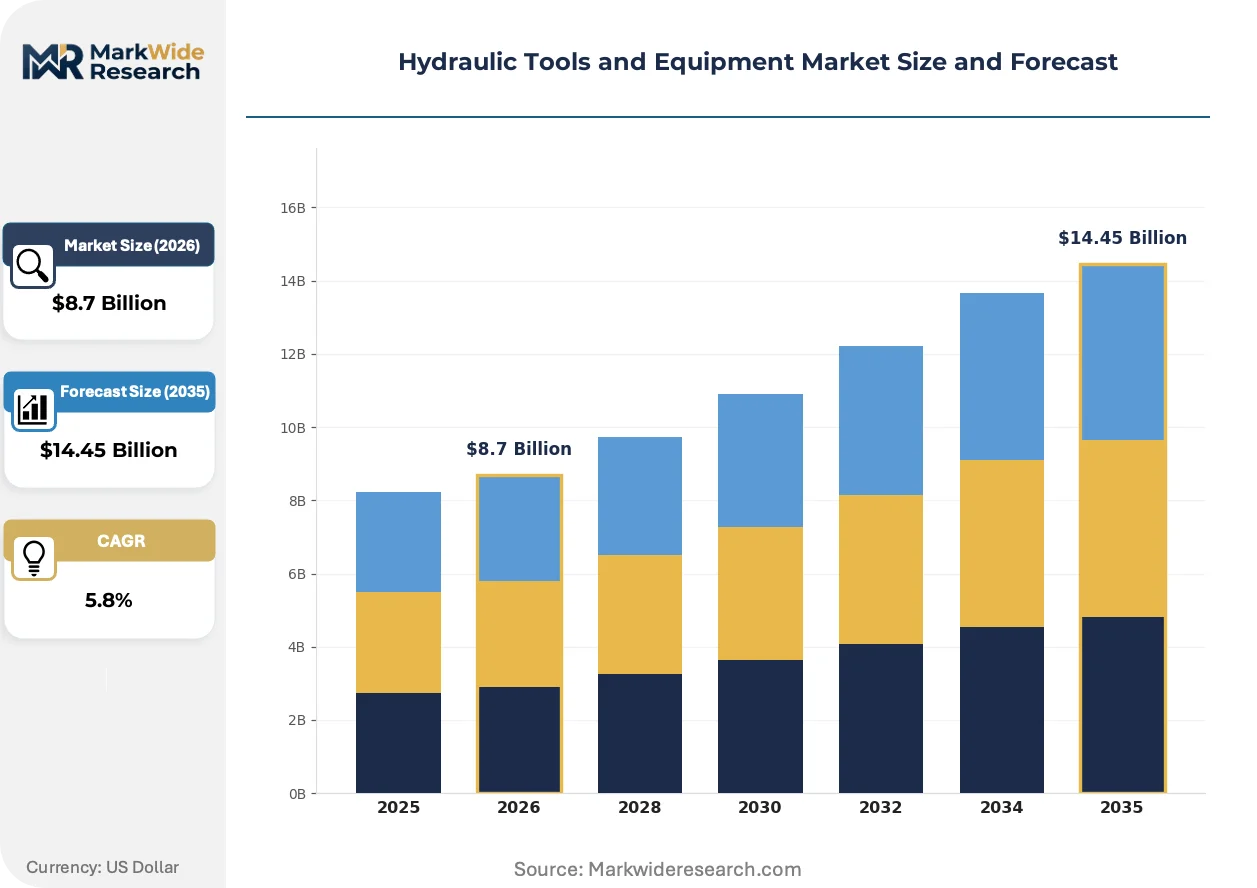
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jacks, Pumps, Cylinders, Torque Wrenches Application: Aerospace, Construction, Manufacturing, Automotive End User: Contractors, OEMs, Workshops, Service Providers Technology: Electric, Pneumatic, Manual, Hybrid |
| Companies Covered | Enerpac Tool Group Corp., Atlas Copco North America LLC, LUKAS Hydraulik GmbH, BVA Hydraulics, Hi-Force Limited, HTL Group Ltd., Hangzhou WREN Hydraulic Equipment Manufacture Co. Ltd., SPX Flow Inc., Cembre S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Tools and Equipment Market Shifts & Advancements
Digital instrumentation and electrified power sources are restructuring how force-multiplying equipment delivers value, shifting competitive differentiation from raw pressure capacity toward data-enabled precision and energy efficiency.
Electric-hybrid hydraulic power packs are decomposing the traditional separation between workshop and field applications. Maintenance contractors in German automotive clusters now deploy single power units across multiple tool heads, eliminating pneumatic line infrastructure. This convergence is compressing the addressable market for standalone manual pumps while expanding margins on integrated system sales.
EPA SPCC spill-prevention protocols are mandating secondary containment specifications for hydraulic fluid reservoirs above threshold capacities. Construction and marine equipment manufacturers now engineer modular reservoir designs with integrated spill trays, altering component footprints and procurement specifications for fleet operators. Gulf Coast offshore service providers face the most acute compliance-driven replacement pressure.
Rental-service depots are displacing direct equipment ownership among mid-sized industrial maintenance departments. The Great Lakes manufacturing belt shows the most pronounced channel shift, with facilities accessing calibrated torque equipment through short-term lease arrangements rather than capital expenditure. This unbundling compresses manufacturer margins on unit sales while expanding recurring service revenue attachment.
Hydraulic Tools and Equipment Market Segmentation
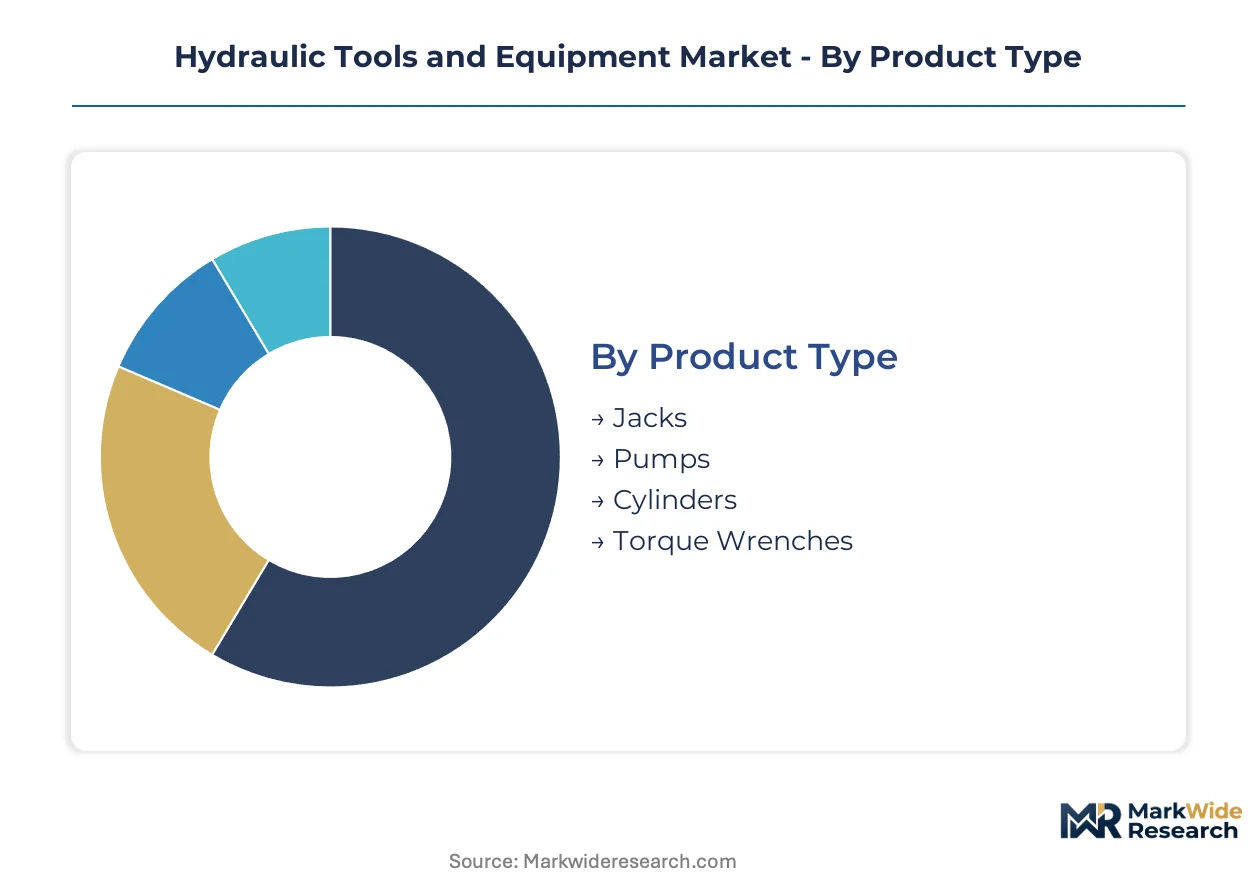
Segmentation in hydraulic tools reveals where margin pools concentrate versus where volume ships. Product type splits expose the tension between commodity cylinders and certified torque equipment. Application and end-user dimensions determine whether procurement flows through rental depots or direct capital expenditure.
Product Type:
Margin pools concentrate in torque wrenches where calibration certification creates switching costs, while jacks and cylinders compete on volume throughput.
- Jacks:These force-multiplying devices operate at 700-1,000 bar for heavy-lift positioning in construction and maintenance. Demand concentrates in German automotive clusters and Gulf Coast offshore service yards where OSHA lockout-tagout requirements extend replacement cycles for older single-valve systems.
- Torque Wrenches:Precision assembly tools requiring ISO 19859-grade calibration certification for wind turbine assembly lines. The Great Lakes manufacturing belt shows pronounced channel shift toward rental-service depots, compressing manufacturer margins on unit sales while expanding recurring service revenue attachment.
- Pumps:High-pressure fluid delivery systems powering attached tool heads across industrial maintenance facilities.
- Cylinders:Linear actuators transmitting pressurized force for structural pressing and heavy positioning applications.
Jacks hold installed capacity across legacy construction fleets. Torque wrenches are rotating up the share rankings as precision manufacturing expands certification requirements.
Application:
Cost tier differentiation separates aerospace procurement with validation documentation from field construction with price-sensitive spot purchasing.
- Manufacturing:Precision assembly lines in Germany's industrial corridor require calibrated torque equipment with traceable certification chains. FDA equipment-validation guidelines shape deployment in pharmaceutical cleanrooms where fluid-seal integrity impacts contamination risk, creating compliance-driven specification premiums.
- Construction:Field applications spanning infrastructure rehabilitation and building assembly where power access remains unreliable. EPA SPCC spill-prevention protocols mandate secondary containment for hydraulic fluid reservoirs above threshold capacities, altering reservoir design specifications for fleet operators.
- Aerospace:Critical fastening operations demanding documented torque traceability for airframe assembly and maintenance.
- Automotive:Battery-powered torque tools now achieve sufficient precision for mid-range assembly maintenance, eroding addressable volume for traditional hydraulic alternatives.
Manufacturing commands specification premiums. Construction maintains volume leadership despite regulatory friction extending procurement timelines.
End User:
Customer type determines whether procurement flows through capital expenditure approval or operating lease arrangements with service bundling.
- Contractors:Project-based operators across North American utilities expanding purchases of high-pressure hydraulic pumps for pipeline integrity testing. Rental-service depots displace direct ownership among mid-sized maintenance departments, unbundling equipment access from capital commitment.
- OEMs:Original equipment manufacturers integrating hydraulic systems into machinery platforms facing Tier-4 emissions compliance deadlines in European construction equipment.
- Workshops:Fixed-facility maintenance operations deploying electric-hybrid power packs to eliminate pneumatic line infrastructure.
- Service Providers:Specialized operators offering calibrated tool access with technician certification for high-stakes assembly operations.
Contractors dominate transaction velocity. OEMs are rotating up the share rankings through integrated system specification.
Technology:
Volume concentrates in mature manual and pneumatic systems while technology investment flows toward electrification and hybrid architectures.
- Electric:Battery-powered units gaining fastest among technology categories as workshops seek to reduce pneumatic infrastructure dependency. German automotive clusters now deploy single power units across multiple tool heads, compressing replacement cycles for standalone compressor systems.
- Hybrid:Electric-hydraulic power packs decomposing the traditional separation between workshop and field applications. These systems combine electric motor efficiency with hydraulic force multiplication, serving maintenance contractors requiring portable high-pressure output without permanent air line installation.
- Pneumatic:Compressed-air systems retaining share in established industrial facilities with sunk infrastructure investment.
- Manual:Hand-operated pumps and tools retaining durable share in field-construction applications where power access remains unreliable and equipment weight constrains transport.
Manual systems hold installed capacity across legacy field operations. Electric technology is rotating up the share rankings through workshop electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-grade alloy forging capacity clusters in Germany's industrial corridor and the Great Lakes manufacturing belt, with demand dispersing across utility rehabilitation programs and precision assembly lines. This supply-side geography shapes where specification premiums concentrate versus where volume procurement flows.
United States
Water utility modernization programs across the Midwest and Southeast are expanding procurement of high-pressure hydraulic pumps for pipeline integrity testing. EPA SPCC spill-prevention protocols mandate secondary containment for reservoirs above threshold capacities, altering fleet specifications for Gulf Coast offshore service providers. The Great Lakes manufacturing belt shows pronounced channel shift toward rental-service depots for calibrated torque equipment.
Germany
Precision assembly lines in Baden-Württemberg and North Rhine-Westphalia require ISO 19859-grade calibrated torque equipment with traceable certification chains. REACH substance restrictions on hydraulic fluid formulations create replacement demand for sealed-system tools minimizing exposure risks. German automotive clusters now deploy electric-hybrid power packs across multiple tool heads, eliminating pneumatic line infrastructure.
India
PLI scheme incentives for heavy machinery production are expanding domestic demand for calibrated assembly tools in Gujarat and Tamil Nadu industrial zones. The country's national industrial regulator enforces equipment standards for manufacturing facility certifications. Maharashtra's automotive component suppliers are upgrading maintenance tooling to meet export-market quality requirements.
Canada
Infrastructure rehabilitation mandates across Ontario and Quebec utilities are accelerating replacement cycles for aging hydraulic systems. Health Canada equipment-validation guidelines shape deployment in pharmaceutical manufacturing cleanrooms where fluid-seal integrity impacts contamination risk. Alberta's oilfield service sector maintains durable demand for high-pressure cylinders in maintenance operations.
United Kingdom
North Sea platform decommissioning schedules are generating specialized cutting and lifting tool requirements for substructure dismantling contractors in Aberdeen and the Scottish coast. The country's national environmental regulator enforces marine equipment standards for offshore operations. Midlands manufacturing facilities are transitioning from pneumatic to electric-hybrid hydraulic systems for workshop efficiency.
Hydraulic Tools and Equipment Market Competitive Landscape
Concentration sits with integrated system providers and specialized certification holders rather than commodity cylinder fabricators. The competitive landscape shows moderate fragmentation at the volume tier while premium torque equipment concentrates among calibration-certified specialists. Three archetypes dominate: captive forging operators controlling input costs, rental-service network operators, and rescue-tool certification specialists. Competitive moves center on geographic expansion of service depots and technology licensing for hybrid power systems.
Among North American service-network operators, Atlas Copco North America LLC exemplifies the rental-depot expansion archetype. Enerpac Tool Group Corp. occupies a position within the integrated manufacturing tier. LUKAS Hydraulik GmbH represents the specialized certification segment. These three anchors illustrate how competitive positioning stratifies across service density, vertical manufacturing control, and regulatory compliance depth rather than raw pressure capacity alone.
| Leading Market Players |
|---|
| Enerpac Tool Group Corp. |
| Atlas Copco North America LLC |
| LUKAS Hydraulik GmbH |
| BVA Hydraulics |
| Hi-Force Limited |
| HTL Group Ltd. |
| Hangzhou WREN Hydraulic Equipment Manufacture Co. Ltd. |
| SPX Flow Inc. |
| Cembre S.p.A. |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for high-grade alloy forgings lock in supply access for German and Great Lakes manufacturers while anchoring price visibility against commodity volatility. These arrangements concentrate pricing power with captive forging operators and compress margins for spot-market purchasers facing OSHA compliance-driven replacement cycles.
Pricing Analysis
ISO 19859 calibration standards dictate the pricing tier structure across torque wrench categories, separating certified premium equipment from standard-grade alternatives. Price differentiation hinges on traceable certification chains and after-sales service bundling, with rental-service depots capturing recurring revenue that compresses manufacturer unit margins. Cost compression in mid-tier pneumatic systems is intensifying because battery-powered torque tools achieve sufficient precision for automotive assembly maintenance. Contractors show highest price sensitivity due to project-based procurement timelines, while pharmaceutical manufacturers accept specification premiums driven by FDA equipment-validation requirements.
Supply Chain Analysis
Port congestion on trans-Atlantic trade lanes elevates inbound logistics costs for alloy cylinder forgings sourced from German industrial corridors. Manufacturing concentration centers on Germany, the United States, and China, with high-grade steel inputs drawing from specialized foundries in North Rhine-Westphalia and the Great Lakes region. Supply chain risk rests on single-source vulnerability for REACH-compliant hydraulic fluid formulations facing phased compliance deadlines. Distribution runs through rental-service depot networks across the Great Lakes manufacturing belt and direct OEM procurement channels for integrated system specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-powered torque tools present a substitution threat that hydraulic equipment incumbents must navigate through calibration certification moats and integrated system bundling.
For Market Incumbents: Shield margin pools by deepening captive forging capacity for high-pressure cylinders and accelerating ISO 19859 certification coverage across torque equipment lines. Electromechanical substitution pressure in automotive assembly demands defensive certification investment rather than price competition. For New Entrants and Emerging Players: Rescue-tool certification fast-tracks offer penetrable entry into European emergency-response procurement where LUKAS Hydraulik GmbH holds established position. Target India's Gujarat and Tamil Nadu industrial zones through PLI scheme-aligned partnerships for calibrated assembly tools, leveraging domestic heavy machinery production incentives. For Investors and Strategic Acquirers: Rental-service network operators with dense depot footprints represent the priority acquisition archetype, capturing recurring revenue attachment as channel shift accelerates. Monitor telematics convergence adoption rates as inflection indicator for predictive maintenance platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Certification Investment | ISO 19859-grade specifications create switching costs for wind turbine assembly procurement. |
| Electric-Hybrid Power Pack Development | German automotive clusters deploy single units across multiple tool heads, eliminating pneumatic infrastructure. |
| Rental-Service Depot Expansion | Great Lakes manufacturing belt shows pronounced channel shift toward short-term lease arrangements. |
| REACH-Compliant Fluid Formulation | Sealed-system tools minimize exposure risks and capture replacement demand across European manufacturing. |
| Telematics Platform Integration | IoT-enabled pressure monitoring creates recurring revenue attachment for equipment fleets. |
Research Methodology
Initial hypotheses were tested against primary input from maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads and refined through secondary validation. Data synthesis combined maintenance director interviews with customs records, SEC filings, industrial equipment trade databases, and regional utility procurement disclosures. Bottom-up demand modeling triangulated against top-down market sizing across product type, application, technology, and end-user dimensions.
Variance-decomposition framing isolated volume and value drivers across the projection horizon. Segmentation dimensions modeled include product type, application, technology tier, end-user category, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis, infrastructure rehabilitation program timelines, and compliance-driven procurement patterns. Forecast inputs incorporated REACH substance restriction deadlines and Tier-4 emissions compliance replacement schedules.
Underlying assumptions cover sustained infrastructure rehabilitation funding, stable alloy input pricing, and regulatory enforcement continuity, with deviation risk concentrated in state-level right-to-repair legislation affecting OEM channel control. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Gear Honing Machines Market
Tools
Cordless Power Drill Market
Tools
Water Pump Pliers Market
Tools
Chainsaw Market
Tools
Tool Hammer Market
Tools
Vise-Grip Pliers Market
Tools
Pruning Saw Market
Tools
Rotary Tools Market
Tools
Cordless Fillet Weld Grinder Market
Tools
Global Cutting Discs Market
Tools
Assembly Fastening Tool Market
Tools
3D Milling Machines Market
Tools
Machining Centers Market
Tools
Nut Runner Market
Tools
Brazing Torch Market
Tools
Global Staple Gun Market