
 Spray Gun Market | 2026-2036
Spray Gun Market Size, Share, and Industry Trends Forecast 2026-2036
Spray Gun Market Analysis
Aftermarket service revenue is fragmenting across the spray gun value chain as OEMs and distributors compete for recurring maintenance spend. Graco Inc. leverages its global distribution network to capture replacement parts demand. SATA GmbH and Co. KG differentiates through premium calibration services that lock in professional body shop loyalty. Anest Iwata Corp. specializes in precision nozzle refurbishment programs that extend equipment lifecycles.
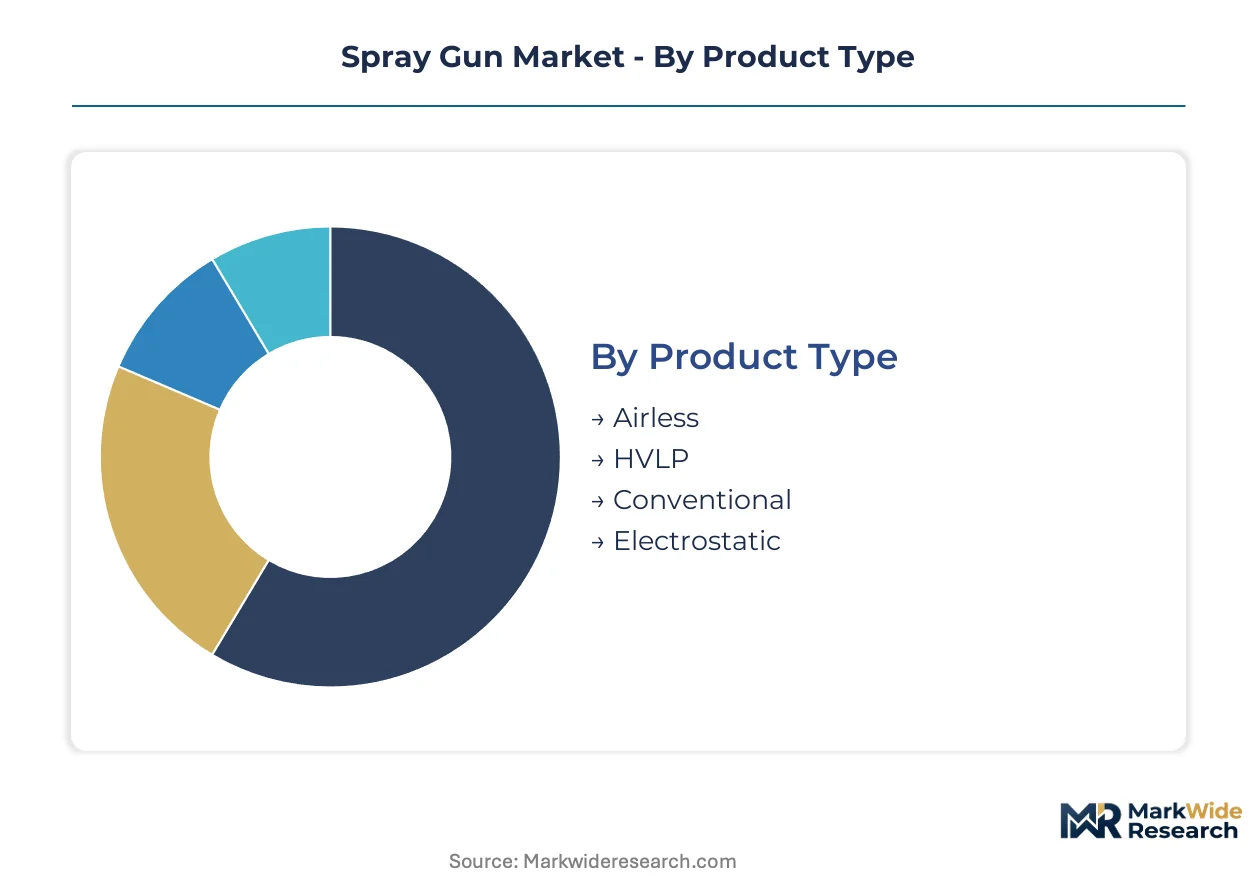
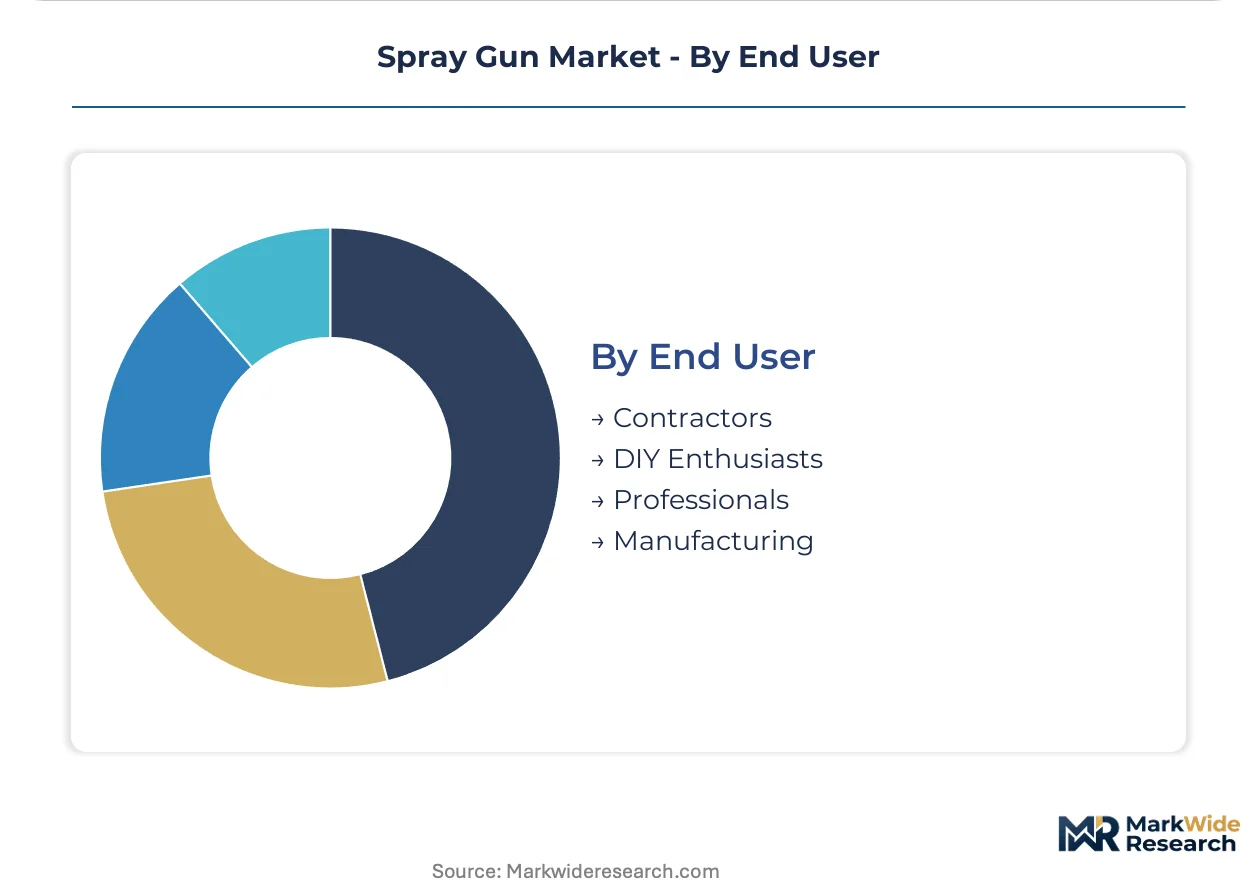
A spray gun is a pneumatic or hydraulic device that atomizes paint, coating, or finishing material through a controlled orifice, typically operating at pressures from 10 to 3,000 PSI depending on technology type, to deliver uniform surface coverage across industrial and commercial substrates. HVLP technology commands the largest product type position due to regulatory alignment with low-VOC application mandates, while electrostatic systems represent the fastest-expanding segment as manufacturers pursue transfer efficiency above 85 percent. Contractors dominate end user demand volume, though DIY enthusiasts represent an emerging channel as retail-grade turbine systems narrow the performance gap with professional equipment.
EPA rules under the National Emission Standards for Hazardous Air Pollutants shape automotive refinishing equipment specifications, while REACH compliance in Europe restricts solvent-based coating chemistries that downstream spray systems must accommodate. OSHA ventilation requirements govern commercial spray booth configurations, directly influencing gun selection criteria. Stakeholders must monitor regulatory tightening on per- and polyfluoroalkyl substances, as coating formulation bans will cascade into equipment compatibility requirements and replacement cycles.
Market Dynamics
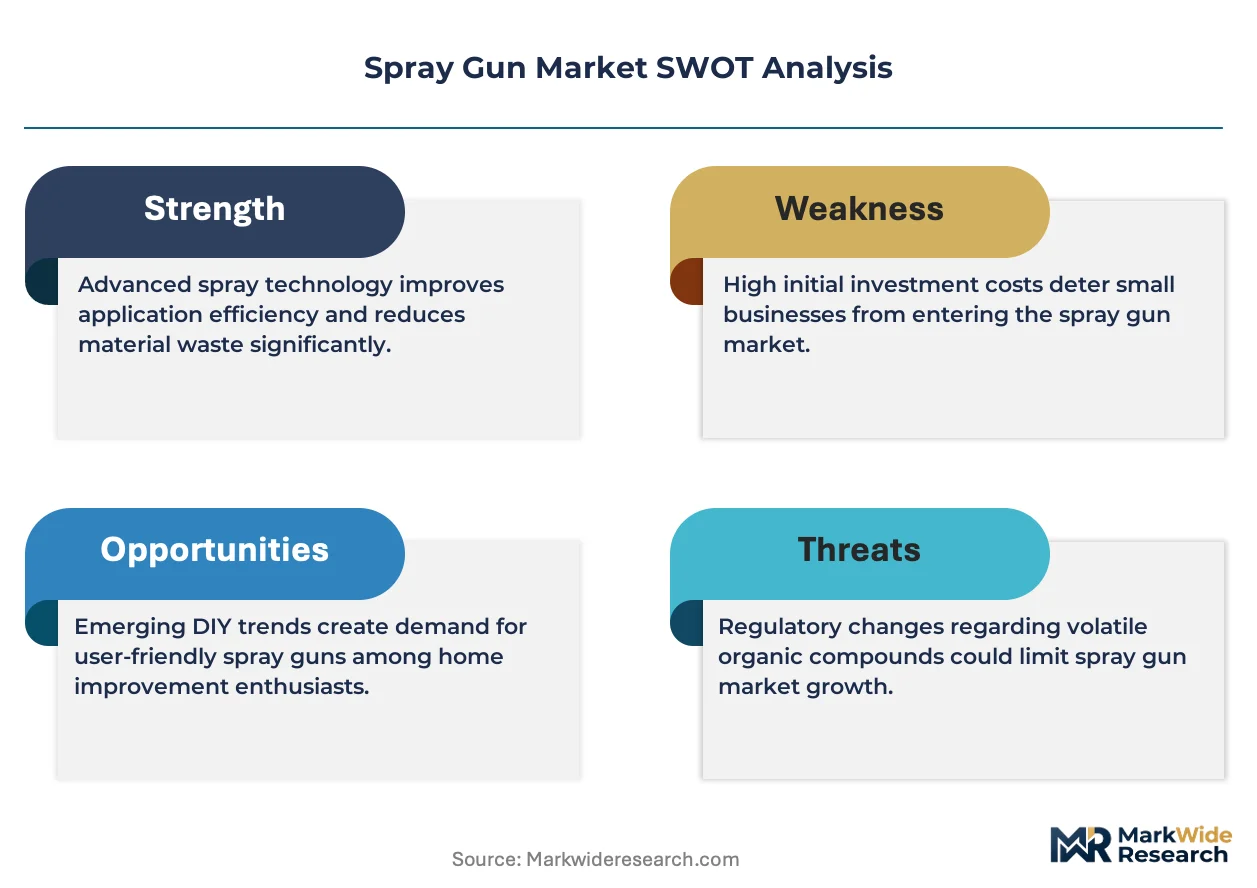
EPA VOC emission rules and REACH solvent restrictions are forcing coating equipment manufacturers to redesign atomization systems around low-transfer-efficiency chemistries, compressing replacement cycles and fragmenting aftermarket service revenue across OEMs and distributors.
Growth Catalysts
- Automotive refinishing volume:Collision repair demand in Germany, China, and the United States sustains equipment procurement for precision color-matching systems.
- REACH solvent restrictions:European coating chemistry bans accelerate HVLP and electrostatic gun adoption to maintain application performance with waterborne formulations.
- OSHA ventilation mandates:Commercial spray booth specifications in the United States tighten gun selection criteria toward compliant low-pressure systems.
Market Restraints
- Precision nozzle supply concentration:Specialized ceramic and tungsten carbide machining capacity clusters in Germany and Japan, creating single-source vulnerabilities.
- Electrostatic system capex intensity:Grounding infrastructure and isolation equipment requirements price out smaller commercial operators.
- DIY turbine substitution:Retail-grade portable systems narrow the performance gap with professional HVLP equipment in residential refinishing applications.
Strategic Opportunities
- India commercial body shop expansion:Underpenetrated precision refinishing infrastructure in Mumbai and Delhi creates demand for mid-tier HVLP systems.
- Per- and polyfluoroalkyl substance bans:Coating formulation restrictions in the United States and Europe will cascade into equipment replacement cycles for incompatible legacy guns.
- IoT-enabled calibration services:Connected nozzle monitoring and predictive maintenance platforms create recurring revenue streams beyond hardware sales.
Industry Challenges
- Certified applicator scarcity:EPA 6H compliance training requirements for automotive refinishing operators create workforce bottlenecks in high-volume markets.
- Legacy pneumatic integration:Shop air infrastructure incompatibility with next-generation low-pressure systems forces costly facility retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spray Gun Market |
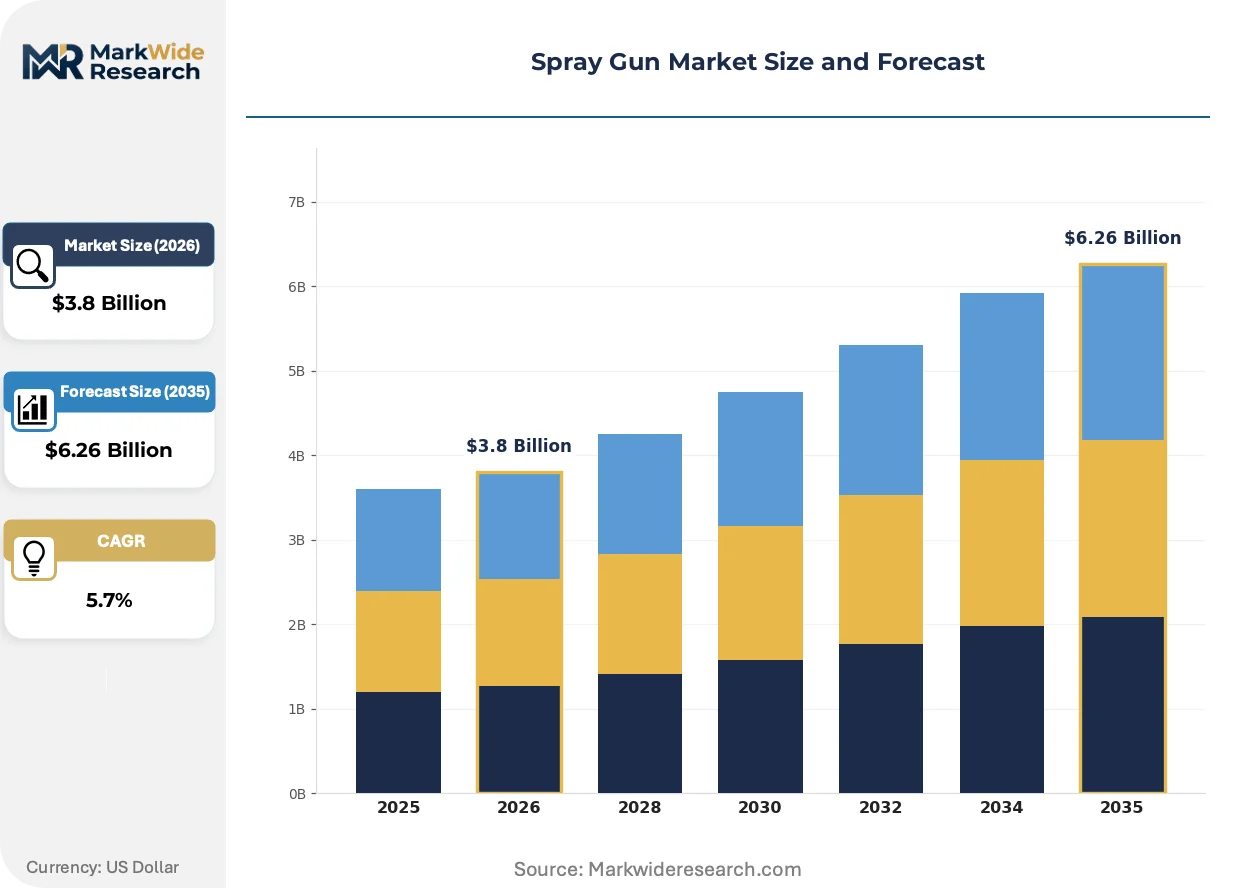
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airless, HVLP, Conventional, Electrostatic Application: Automotive, Industrial Coating, Lawn Care, Home Improvement Technology: Low Pressure, High Volume, Ultra-High Pressure, Specialty End User: Contractors, DIY Enthusiasts, Professionals, Manufacturing |
| Companies Covered | Graco Inc., 3M Co., Anest Iwata Corp., SATA GmbH and Co. KG, Nordson Corp., Fuji Industrial Spray Equipment Ltd., Binks, Wagner SprayTech, DeVilbiss Automotive Refinishing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spray Gun Market Emerging Trajectories
Atomization technology is converging with digital control systems and connected service platforms, reshaping how coating equipment is specified, operated, and maintained across professional and commercial segments.
Electrostatic rotary bell atomization is hybridizing with robotic trajectory programming in automotive OEM paint shops, enabling transfer efficiency above 85 percent while reducing overspray waste. Tier 1 suppliers in Stuttgart and Detroit are retrofitting existing lines with hybrid electrostatic-pneumatic modules rather than full replacement. This convergence is compressing the technology refresh cycle from ten-year intervals to six-year equipment planning horizons.
EPA National Emission Standards for Hazardous Air Pollutants are mandating closed-loop solvent recovery in high-volume refinishing operations, forcing gun manufacturers to redesign fluid passages for compatibility with reclaimed coating chemistries. California Air Resources Board district rules extend these requirements to smaller commercial shops. Equipment vendors are responding with modular gun architectures that separate atomization air from pattern air to accommodate variable solvent loads.
Aftermarket service unbundling is fragmenting the traditional OEM-distributor relationship in North American body shop channels. Gravitating toward independent calibration specialists, mid-sized operators are bypassing factory-authorized service networks for faster turnaround on nozzle refurbishment and pressure testing. This behavioral shift is most visible in Texas and Florida metro markets where independent collision repair chains concentrate purchasing power.
Spray Gun Market Segmentation
Spray gun specification varies dramatically across coating viscosity, substrate complexity, and regulatory jurisdiction. Equipment selection hinges on transfer efficiency mandates, air compressor infrastructure, and operator certification requirements that differ by end-use environment.
Product Type:
Use-case spectrum spans high-volume industrial coating to precision automotive refinishing, with atomization technology dictating regulatory compliance and operating cost structure.
- HVLP:High-volume low-pressure systems atomize coating through large air volumes at reduced pressure, achieving transfer efficiency above 65 percent. Collision repair shops in Germany and California specify HVLP equipment to satisfy EPA and REACH volatile organic compound limits without sacrificing finish quality.
- Electrostatic:Charged particle attraction drives coating adhesion to conductive substrates with transfer efficiency exceeding 85 percent. Automotive OEM paint lines in Stuttgart and Detroit are retrofitting hybrid electrostatic-pneumatic modules to compress technology refresh cycles from ten-year to six-year intervals.
- Airless:Hydraulic pressure atomization through hardened orifice tips handles high-viscosity industrial coatings without compressed air dependency.
- Conventional:Standard pneumatic atomization at 40-60 PSI remains prevalent in legacy shop infrastructure with lower capital replacement urgency.
Established volume favors HVLP; emerging adoption favors electrostatic.
Application:
End-use differentiation tracks coating chemistry complexity, substrate value, and regulatory scrutiny intensity across commercial and consumer domains.
- Automotive:Precision color-matching systems dominate equipment procurement in collision repair channels. Refinishing demand in China, Germany, and the United States sustains premium gun deployment despite electrostatic system capex intensity pricing out smaller operators.
- Industrial Coating:High-throughput protective coating application on metal fabrication and infrastructure projects favors airless and ultra-high-pressure configurations for throughput maximization.
- Home Improvement:Residential refinishing applications see retail-grade turbine systems narrowing performance gaps with professional HVLP equipment.
- Lawn Care:Agricultural and turf equipment coating demands corrosion resistance through specialized fluid passage designs accommodating variable solvent loads.
Automotive commands premium pricing power; home improvement shows steepest expansion trajectory.
Technology:
Pressure-volume configuration determines atomization quality, overspray generation, and compatibility with waterborne versus solvent-based coating chemistries.
- Low Pressure:OSHA ventilation mandates in United States commercial spray booths tighten gun selection criteria toward compliant low-pressure systems that reduce ambient vapor concentrations.
- High Volume:Large air-cap designs dominate European adoption patterns as REACH solvent restrictions accelerate equipment replacement for waterborne formulation compatibility.
- Ultra-High Pressure:3,000 PSI hydraulic atomization penetrates thick-film industrial coatings without thinning, serving marine and infrastructure protection segments.
- Specialty:Custom-engineered configurations address niche substrates including powder coating, plural-component polyurethane, and thermoplastic application.
Low pressure anchors regulatory compliance; ultra-high pressure captures industrial thickness specifications.
End User:
Customer segmentation reflects skill certification requirements, equipment utilization intensity, and aftermarket service dependency patterns.
- Contractors:Mobile and fixed-site commercial operators generate highest equipment utilization rates and replacement parts demand. Gravitating toward independent calibration specialists, mid-sized operators bypass factory-authorized networks for faster nozzle refurbishment turnaround.
- Professionals:Certified automotive refinishing operators face EPA 6H compliance training requirements creating workforce bottlenecks in high-volume Texas and Florida metro markets.
- DIY Enthusiasts:Consumer turbine systems expand addressable market through retail channels with simplified setup and reduced compressor dependency.
- Manufacturing:Captive production facilities specify robotic integration and closed-loop solvent recovery compatibility under EPA National Emission Standards for Hazardous Air Pollutants.
Contractors concentrate procurement volume; manufacturing drives specification sophistication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German collision repair shops prioritize precision calibration services, while Chinese operators emphasize throughput volume. Indian markets show equipment specification gaps between metro body shops and tier-two cities.
United States
Collision repair volume in Texas and Florida metro markets sustains premium HVLP procurement despite electrostatic system capex barriers. EPA National Emission Standards for Hazardous Air Pollutants mandate closed-loop solvent recovery in high-volume refinishing operations. California Air Resources Board district rules extend these requirements to smaller commercial shops in Los Angeles and San Diego counties.
Germany
REACH solvent restrictions accelerate equipment replacement cycles as waterborne formulation compatibility becomes mandatory. Stuttgart automotive OEM paint shops retrofit hybrid electrostatic-pneumatic modules rather than full line replacement. Bavarian precision machining clusters supply specialized ceramic and tungsten carbide nozzle components to domestic and export markets.
China
Domestic collision repair demand concentrates in Shanghai and Beijing where precision color-matching systems command premium positioning. MIIT industrial equipment standards shape local manufacturing specifications for spray gun producers. Pearl River Delta coating equipment assemblers serve both domestic refinishing channels and Southeast Asian export markets.
India
Commercial body shop expansion in Mumbai and Delhi creates demand for mid-tier HVLP systems as precision refinishing infrastructure penetrates beyond legacy markets. BIS certification requirements for pneumatic equipment influence import specifications and local assembly partnerships. Tamil Nadu automotive manufacturing corridors generate captive demand for robotic integration-compatible spray systems.
Japan
Precision nozzle refurbishment programs extend equipment lifecycles in cost-sensitive operator segments. METI energy efficiency guidelines for industrial equipment shape atomization technology selection criteria. Nagoya automotive supplier clusters specify electrostatic rotary bell systems for transfer efficiency above 85 percent in OEM paint operations.
Spray Gun Market Vendor Landscape
Capability concentration sits with specialized precision manufacturers; scale advantage sits with diversified industrial equipment conglomerates. The vendor base organizes around three strategic tiers: premium calibration service providers, volume distributors with global logistics networks, and regional fabrication specialists serving price-sensitive segments. Competitive positioning hardens through M&A activity consolidating aftermarket service channels and technology licensing agreements accelerating electrostatic system penetration.
Within the premium service tier, SATA GmbH and Co. KG and Anest Iwata Corp. exemplify archetypes built around calibration expertise and precision refurbishment programs respectively. Graco Inc. anchors the scale-driven distributor category with extensive replacement parts logistics. These three occupy positions that illustrate how aftermarket revenue fragmentation is reshaping traditional OEM-distributor relationships across North American and European body shop channels.
| Leading Market Players |
|---|
| Graco Inc. |
| 3M Co. |
| Anest Iwata Corp. |
| SATA GmbH and Co. KG |
| Nordson Corp. |
| Fuji Industrial Spray Equipment Ltd. |
| Binks |
| Wagner SprayTech |
| DeVilbiss Automotive Refinishing |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on German and Japanese precision nozzle machining capacity exposes the spray gun market to simultaneous pricing tier compression and supply chain restructuring. This concentration forces buyers into long-term offtake contracts for ceramic and tungsten carbide components while accelerating dual-sourcing mandates across tier-one equipment assemblers.
Pricing Analysis
Long-term offtake agreements dominate procurement for precision nozzles, while spot purchasing persists for commodity pneumatic fittings and aluminum castings. Price differentiation rests on certification grade alignment with EPA 6H and REACH compliance tiers, plus after-sales calibration bundling. Cost compression in mid-tier HVLP systems intensifies as Chinese assemblers narrow performance gaps with European equipment. DIY enthusiasts exhibit highest price sensitivity; automotive OEM collision repair chains demonstrate lowest.
Supply Chain Analysis
Extended payment terms from German and Japanese suppliers strain working capital for mid-sized distributors serving North American body shop channels. Manufacturing concentrates in Germany, Japan, and China, drawing from specialized ceramic powders, tungsten carbide blanks, and precision-machined air caps. Single-source vulnerability in Bavarian and Nagoya machining clusters threatens continuity. Distribution runs through authorized dealer networks for professional segments, direct retail for consumer turbine systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from retail-grade turbine systems narrowing performance gaps with professional HVLP equipment in residential refinishing channels. Defense requires locking in aftermarket service revenue before independent calibration specialists capture mid-sized operator spend.
For Market Incumbents: Pre-empt independent service encroachment by acquiring calibration specialists in Texas and Florida metro markets where collision repair chains concentrate purchasing power. Backward integration into ceramic nozzle machining reduces exposure to Bavarian supply bottlenecks. Prioritize EPA 6H training program certification to capture workforce-constrained operator segments.
For New Entrants and Emerging Players: Establish a beachhead in India's Mumbai and Delhi commercial body shop expansion zones where mid-tier HVLP demand outpaces established service infrastructure. Target underpenetrated tier-two Indian cities with simplified waterborne-compatible systems. Pursue BIS certification partnerships to accelerate import approval timelines.
For Investors and Strategic Acquirers: The market sits at a technology refresh acceleration phase that favors precision service platforms over pure hardware manufacturers. Long-term viability centers on recurring calibration revenue streams and IoT-enabled predictive maintenance subscriptions. Monitor EPA per- and polyfluoroalkyl substance rulemaking as inflection signal for legacy equipment replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Platform Acquisition | Captures recurring revenue from Texas and Florida collision repair chains bypassing factory networks. |
| Backward Integration into Nozzle Machining | Reduces single-source dependency on German and Japanese ceramic component suppliers. |
| IoT-Enabled Predictive Maintenance Launch | Creates subscription revenue streams beyond hardware sales for connected spray gun deployments. |
| India Market Entry Partnership | Secures BIS certification pathway and local assembly capacity for Mumbai and Delhi body shop demand. |
| Waterborne Formulation Compatibility Certification | Aligns equipment specifications with REACH solvent restrictions and EPA VOC emission mandates. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and equipment distributor sales data. Primary interviews engaged aftermarket service directors, collision repair shop operators, OEM procurement managers, and calibration specialist technicians. Secondary sources included EPA National Emission Standards for Hazardous Air Pollutants documentation, ECHA REACH substance restriction databases, and MIIT industrial equipment standards. Bottom-up demand modeling triangulated against top-down market sizing across product type, application, technology, and end user segments.
Forecast inputs incorporate automotive refinishing volume trajectories, regulatory compliance deadline schedules, and technology refresh cycle compression patterns. Segmentation dimensions span atomization technology, coating chemistry compatibility, pressure-volume configuration, and operator certification requirements. CAGRs derive from equipment replacement cycle analysis and aftermarket service revenue migration patterns. Industry-specific inputs include collision repair demand concentration in Germany, China, and the United States, plus electrostatic system retrofit penetration in Stuttgart and Detroit automotive OEM paint shops.
Sensitivities concentrate around EPA per- and polyfluoroalkyl substance rulemaking timelines, REACH solvent restriction enforcement intensity, and precision nozzle machining capacity expansion in alternative geographies. Forecasts reflect documented assumptions regarding regulatory compliance adoption curves and technology substitution thresholds. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Pneumatic Marking Machines Market
Tools
Tool Storage Market
Tools
Book Binding Machines Market
Tools
Vinyl Bending Machine Market
Tools
Fine Blanking Tools Market
Tools
2D Laser Cutting Machine Market
Tools
End Milling Machine Market
Tools
United States Machine Tools Market
Tools
Jade Engraving Machines Market
Tools
Power Tool Gears Market
Tools
Digital Laser Levels Market
Tools
Entrenching Tool Market
Tools
Core Shooter Machine Market
Tools
Foldable Ladder Market
Tools
Water Pump Pliers Market
Tools
Mechanical Springs Market