
 Air Drills Market | 2026-2036
Air Drills Market Size, Share, and Industry Trends Forecast 2026-2036
Air Drills Market Analytics
North American pneumatic tool manufacturers is realigning capacity toward brushless and variable-speed platforms to meet tightening workplace safety mandates. Atlas Copco leverages its underground mining heritage to dominate rotary drill configurations for tunnelling contractors. Ingersoll Rand anchors the contractor segment through rental channel density and fleet management services. Chicago Pneumatic competes on price-accessibility in emerging market construction verticals.
Air drills are pneumatic or electrically powered rotary percussive tools designed to bore holes in metal, concrete, masonry, or composite substrates, typically operating at pressures of 90 psi and rotational speeds up to 3,000 RPM for precision fastening and material removal tasks. Pneumatic drills retain structural dominance in heavy construction and mining due to superior power-to-weight ratios and explosion-safe operation in volatile environments, while cordless electric variants capture fastest growth in automotive assembly and aerospace MRO where mobility and torque control matter most. Variable-speed technology commands premium positioning across industrial user segments, whereas single-speed pneumatic platforms occupy commoditized contractor procurement channels.
OSHA vibration exposure limits and EPA stationary source regulations shape product design priorities for manufacturers serving U.S. construction and manufacturing end users. CE marking under the EU Machinery Directive and REACH substance restrictions govern market access for European imports, compelling material substitutions in housing composites and lubricant formulations. Stakeholders must monitor evolving battery-electric interoperability standards and carbon border adjustment mechanisms that will redraw competitive boundaries between pneumatic legacy systems and cordless alternatives.
Market Dynamics
Brushless motor migration and OSHA vibration exposure mandates are forcing pneumatic tool manufacturers to redesign power trains and dampening systems, compressing development cycles while elevating certification costs for legacy platform holders.
Growth Catalysts
- Infrastructure spending acceleration:United States construction contractors are expanding pneumatic tool fleets to meet highway, bridge, and utility project backlogs.
- REACH substance restrictions:European housing composite and lubricant substitutions are creating demand for reformulated air drill platforms that comply with ECHA substance limitations.
- State-led equipment modernization:China's industrial manufacturing corridors sustain procurement volumes through government-directed facility upgrades.
Market Restraints
- Compressed air infrastructure dependency:Pneumatic drill deployment requires capital-intensive compressor installations that limit adoption in mobile and remote construction sites.
- Lithium-ion battery energy density gains:Cordless electric platforms now deliver torque outputs that challenge pneumatic power-to-weight advantages in automotive assembly.
- EPA stationary source permitting:Compressor emissions compliance adds operational friction for manufacturing facilities running large pneumatic tool fleets.
Strategic Opportunities
- Underpenetrated mining automation:Underground operations in Chile and Australia present retrofit demand for remote-operated rotary drill configurations.
- EU Green Deal carbon border adjustments:Pneumatic tool manufacturers with low-carbon supply chains gain competitive positioning against battery-electric imports.
- Variable-speed platform convergence:Integration of electronic torque control with pneumatic power trains opens premium positioning in aerospace MRO segments.
Industry Challenges
- Vibration certification testing capacity:ISO 28927 hand-arm vibration standards require specialized laboratory infrastructure that few manufacturers control in-house.
- Legacy fleet interoperability:Contractors face integration complexity when mixing brushless variable-speed units with existing single-speed pneumatic inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Drills Market |
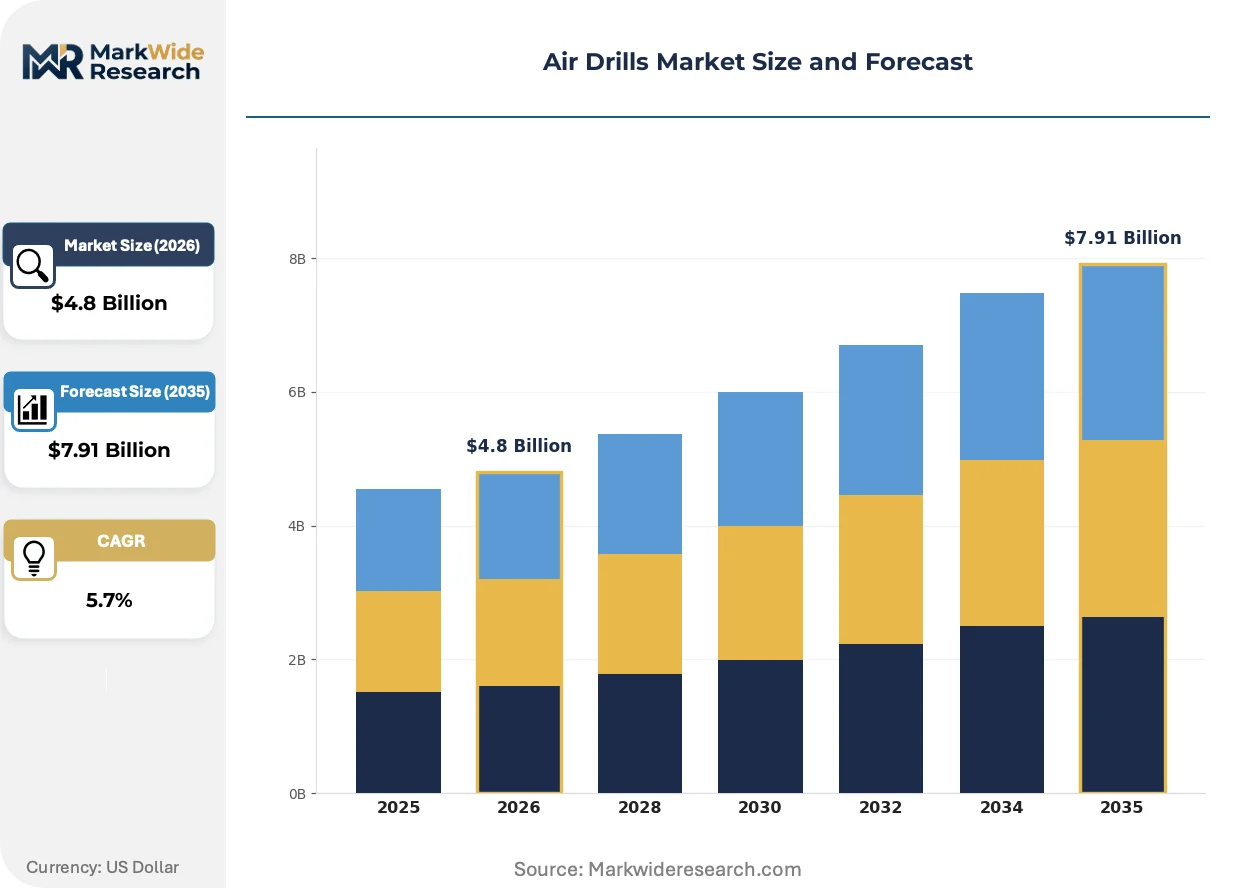
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
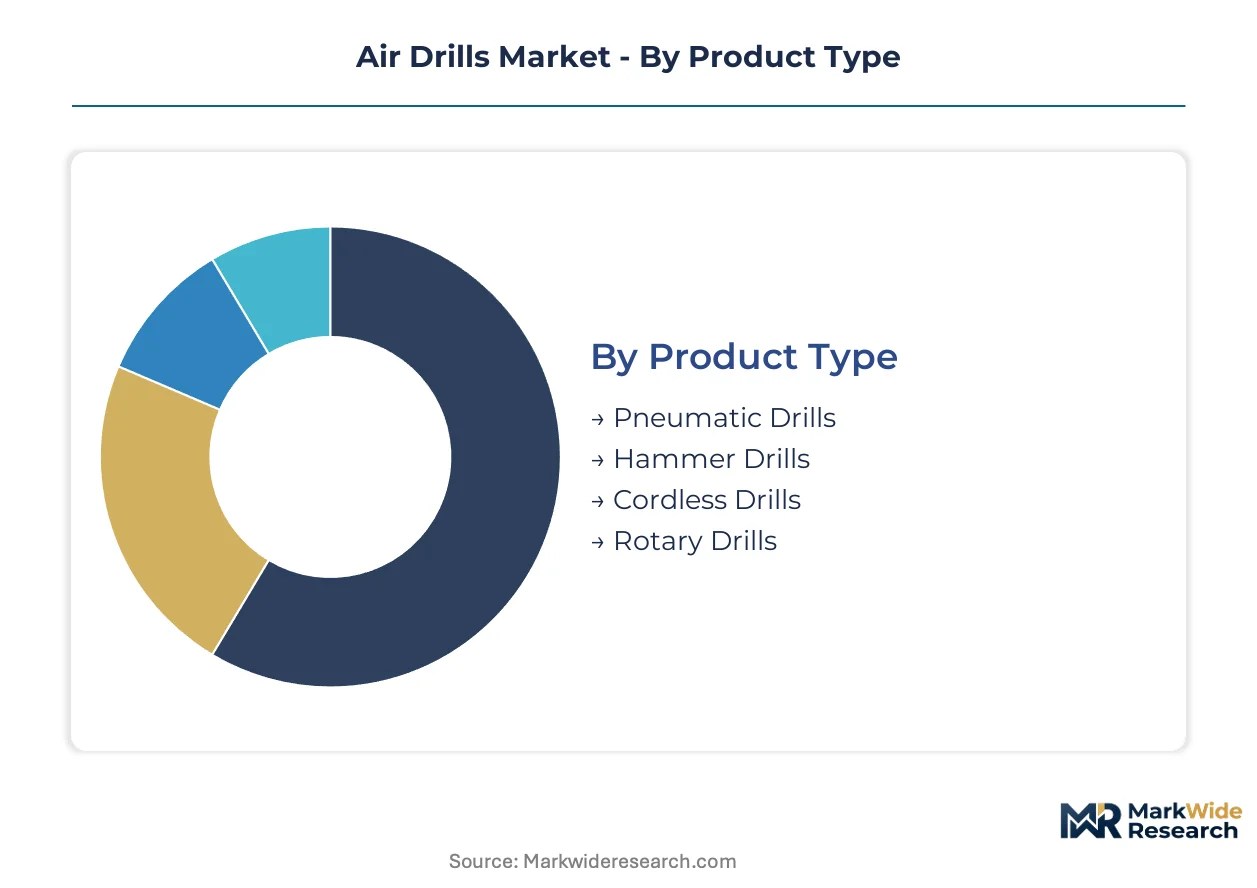
| Segmentation | Product Type: Pneumatic Drills, Hammer Drills, Cordless Drills, Rotary Drills Application: Construction, Automotive, Aerospace, Manufacturing End User: Contractors, DIY Enthusiasts, Industrial Users, Engineers Technology: Single-Speed, Variable-Speed, Brushless, Electric |
| Companies Covered | Atlas Copco, Ingersoll Rand, Chicago Pneumatic, Snap-on, Epiroc AB, Sandvik AB, Stanley Black & Decker, Dynabrade, Desoutter Industrial Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Drills Market Evolving Landscape
Electrification pressures and workplace safety mandates are compressing the technology lifecycle for pneumatic power tools, forcing simultaneous investment in motor innovation and regulatory compliance architecture.
Brushless DC motor architectures are consolidating control precision in cordless electric drill platforms. Automotive assembly plants in Germany and Japan are adopting these systems for torque-critical fastening operations. The technology is consolidating pneumatic market share in applications where rotational speed modulation matters more than raw impact force.
OSHA vibration exposure limits are reshaping product design priorities for manufacturers serving United States construction end users. Hand-arm vibration thresholds now mandate redesigned dampening systems and composite housing materials. Contractors in California and Texas are prioritizing certified low-vibration platforms in fleet procurement specifications.
Equipment-as-a-service contracting is displacing outright purchase in North American contractor segments. Rental channel operators are bundling maintenance and certification compliance into monthly fee structures. This shift is most visible among mid-sized commercial construction firms in Florida and Illinois seeking to offload regulatory compliance burdens.
Air Drills Market Segmentation
Air drill procurement patterns diverge sharply across user sophistication levels and operational environments. Technical specifications, compliance requirements, and total cost of ownership calculations drive fundamentally different purchasing behaviors between industrial fleet operators and intermittent users.
Product Type:
Buyers differentiate primarily by power source availability and duty cycle intensity rather than hole-making capability alone.
- Pneumatic Drills:Compressed-air rotary percussive tools operating at 90 psi deliver superior power-to-weight ratios for continuous heavy-duty boring. Mining contractors in Chile and tunneling specialists across Germany specify these for explosion-safe performance in volatile atmospheres where electrical ignition risks are prohibitive.
- Hammer Drills:Pneumatic or electropneumatic platforms combine rotational motion with axial percussion for concrete and masonry penetration. Infrastructure contractors in Texas and Florida are expanding fleets to address bridge deck rehabilitation and highway expansion backlogs requiring hardened substrate penetration.
- Cordless Drills:Lithium-ion battery platforms with brushless motor architectures are displacing pneumatic alternatives in automotive assembly plants across Japan and Germany where mobility and torque precision outweigh raw impact force requirements.
- Rotary Drills:Atlas Copco dominates underground mining configurations for tunnelling contractors leveraging percussive rotary mechanisms optimized for rock face drilling in Australian and Chilean extraction operations.
Volume sits with pneumatic configurations in heavy construction and mining; growth tilts toward cordless platforms gaining share fastest in precision assembly environments.
Application:
End-use environments dictate durability specifications, certification requirements, and maintenance protocols that reshape supplier selection criteria.
- Construction:Highway, bridge, and utility contractors run pneumatic fleets under severe duty cycles requiring OSHA vibration certification and EPA compressor emissions compliance. Fleet procurement specifications in California and Texas now mandate hand-arm vibration thresholds below ISO 28927 limits.
- Automotive:Assembly plants specify brushless variable-speed platforms for torque-critical fastening where rotational modulation prevents substrate damage. German and Japanese OEM facilities are standardizing cordless electric architectures for underbody and powertrain applications.
- Aerospace:MRO facilities demand electronic torque control integration with pneumatic power trains for airframe fastener installation. Precision requirements in this segment command premium positioning and specialized certification documentation.
- Manufacturing:China's state-led equipment modernization programs sustain procurement volumes across industrial manufacturing corridors where facility upgrades drive replacement cycles for legacy single-speed pneumatic inventories.
Construction commands current installed base; aerospace MRO climbs the fastest as torque precision requirements intensify.
End User:
Procurement sophistication and compliance burden tolerance separate commercial operators from intermittent purchasers.
- Contractors:Mid-sized commercial construction firms in Florida and Illinois are shifting toward equipment-as-a-service contracting to offload OSHA compliance and maintenance burdens onto rental channel operators.
- DIY Enthusiasts:Price-sensitive intermittent users drive commoditized demand for single-speed pneumatic platforms through retail channels, with purchasing decisions driven by initial acquisition cost rather than lifecycle economics.
- Industrial Users:Manufacturing facilities running large pneumatic fleets face EPA stationary source permitting friction for compressor emissions, accelerating evaluation of battery-electric alternatives with lower regulatory overhead.
- Engineers:Technical specification authority in aerospace and automotive segments demands detailed vibration certification documentation and torque calibration traceability that only specialized suppliers provide.
Industrial users represent replacement demand concentration; contractor segments show steepest expansion trajectory through rental channel migration.
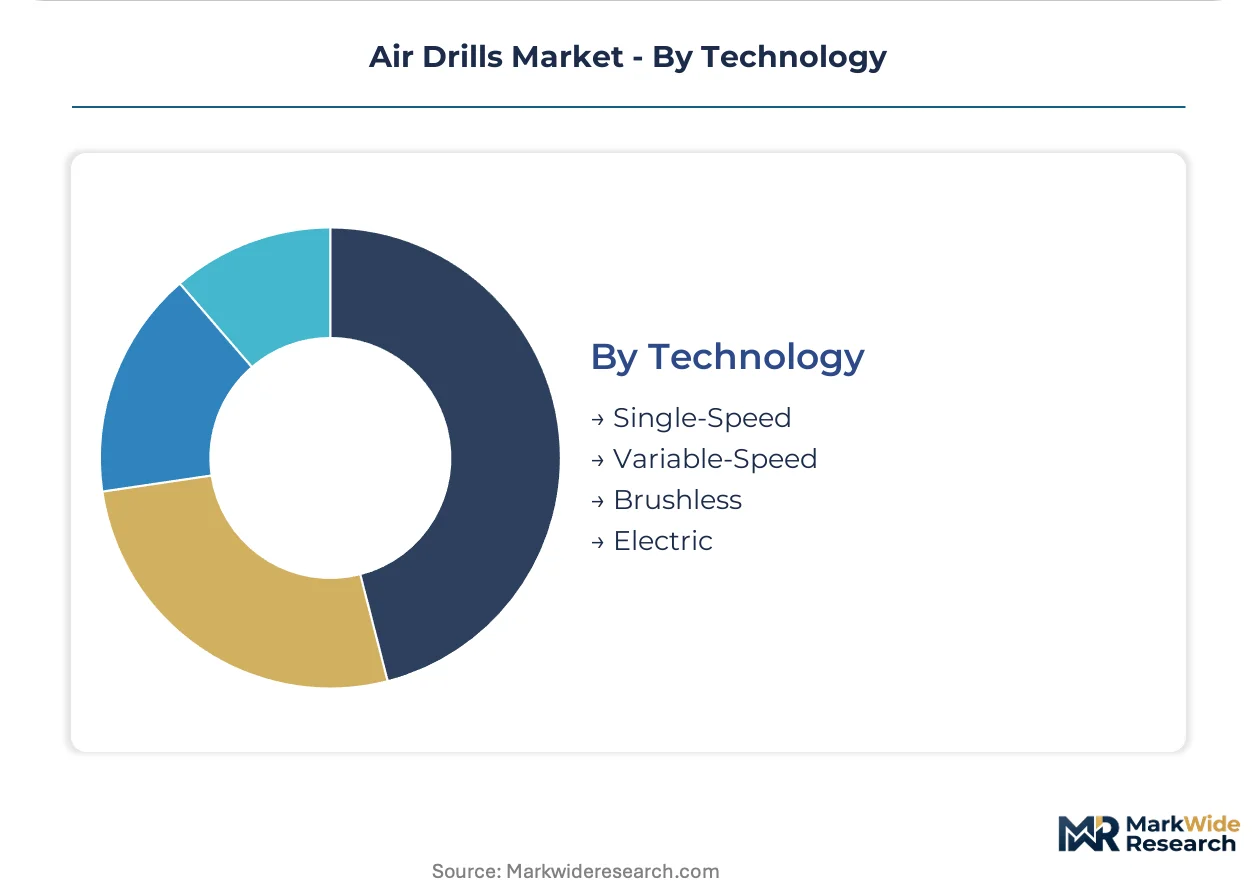
Technology:
Control precision and energy efficiency now rival raw power metrics in procurement evaluations across advanced manufacturing environments.
- Single-Speed:Legacy pneumatic platforms occupy commoditized contractor procurement channels where capital constraints override performance differentiation. These systems dominate emerging market construction verticals on price accessibility.
- Variable-Speed:Electronic torque modulation commands premium positioning across aerospace MRO and automotive assembly segments where substrate damage prevention justifies acquisition cost premiums.
- Brushless:DC motor architectures consolidate control precision in cordless platforms, with automotive plants in Germany and Japan adopting these systems for fastening operations requiring rotational speed modulation.
- Electric:Corded and battery platforms challenge pneumatic power-to-weight advantages as lithium-ion energy density improves, particularly in applications where compressed air infrastructure deployment is capital-prohibitive.
Single-speed retains volume in cost-constrained segments; brushless variable-speed configurations gain share fastest in torque-critical precision applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel and aluminum feedstock availability in Pittsburgh anchors North American pneumatic tool manufacturing, while compressor component clusters in Shanghai and Stuttgart shape regional supply architectures.
United States
Highway and bridge rehabilitation backlogs drive fleet expansion among Texas and Florida contractors. OSHA hand-arm vibration thresholds now mandate ISO 28927 certification for procurement eligibility. California construction firms in Los Angeles and San Francisco Bay Area prioritize low-vibration platforms to meet workplace safety mandates.
Germany
Automotive assembly plants in Stuttgart and Wolfsburg specify brushless variable-speed architectures for torque-critical fastening operations. REACH substance restrictions under ECHA compel housing composite and lubricant reformulations. Industrial manufacturing corridors in Bavaria and North Rhine-Westphalia sustain replacement demand for precision assembly tools.
China
State-led equipment modernization programs sustain procurement volumes across Yangtze River Delta manufacturing clusters. MIIT industrial upgrading directives accelerate facility replacement cycles for legacy pneumatic inventories. Shanghai and Suzhou industrial zones concentrate demand for high-duty rotary drill configurations.
Australia
Underground mining operations in Western Australia and Queensland present retrofit demand for remote-operated rotary drill systems. The country's national workplace safety regulator enforces vibration exposure standards comparable to ISO 28927. Perth and Brisbane serve as distribution hubs for Chilean and Indonesian mining contractor supply chains.
Japan
Automotive OEM facilities in Toyota City and Yokohama standardize cordless electric platforms for underbody assembly applications. METI energy efficiency guidelines favor brushless motor adoption in manufacturing facilities. Precision engineering clusters in Aichi and Kanagawa prefectures command specialized torque calibration documentation.
Air Drills Market Competitive Landscape
Global majors compete with regional champions across technology licensing and distribution density, producing a tiered structure where scale-driven conglomerates anchor premium positioning while specialized fabricators capture niche verticals. The vendor base separates into three archetypes: diversified industrial conglomerates with mining heritage, pneumatic tool specialists with rental channel dominance, and emerging market price competitors. Consolidation pressures intensify through M&A activity targeting vibration certification capabilities and backward integration into compressor system compatibility.
Within the diversified industrial tier, Atlas Copco and Ingersoll Rand occupy positions shaped by underground mining heritage and contractor fleet management density respectively. Chicago Pneumatic represents the price-accessibility archetype targeting emerging market construction verticals. These three anchors exemplify how geographic origin and corporate structure correlate with strategic positioning across premium, standard, and economy market tiers.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Chicago Pneumatic |
| Snap-on |
| Epiroc AB |
| Sandvik AB |
| Stanley Black & Decker |
| Dynabrade |
| Desoutter Industrial Tools |
| Others |
Value Network & Pricing Analysis
Brushless motor migration across pneumatic tool platforms is compressing cost structures while redistributing manufacturing gravity toward motor-controller clusters in Germany and Japan. This technology transition simultaneously elevates R&D amortization burdens and fragments supplier bargaining power across legacy compressor-component networks.
Pricing Analysis
Warranty and ISO 28927 vibration certification bundling separates premium pneumatic platforms from unbundled economy-tier alternatives in contractor procurement channels. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service depth, with California and Texas construction firms showing lowest price sensitivity for certified low-vibration fleets. Cost compression in single-speed pneumatic tiers is intensifying because Chinese manufacturers are expanding export capacity. DIY enthusiasts through retail channels exhibit highest price sensitivity, prioritizing initial acquisition cost over lifecycle vibration exposure compliance.
Supply Chain Analysis
Dual-sourcing mandates from Australian and Chilean mining contractors require qualified suppliers for both rotary drill mechanisms and composite housing materials across China, Germany, and the United States. Raw material dependencies center on high-grade aluminum alloys, rare-earth magnets for brushless motors, and specialty lubricants reformulated for REACH compliance. Single-source vulnerability concentrates in rare-earth magnet supply from China. Distribution runs through rental channel operators in North America and direct OEM relationships in German automotive assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into vibration testing laboratories and brushless motor controller production is becoming the decisive competitive lever as certification costs escalate and electronic torque modulation captures premium positioning.
For Market Incumbents: Acquire ISO 28927 certification testing capacity to internalize compliance costs that currently bottleneck development cycles. Defend against cordless electric substitution by integrating electronic torque control with pneumatic power trains for aerospace MRO segments. Anchor backward integration into rare-earth magnet supply chains to mitigate China concentration risk. For New Entrants and Emerging Players: Begin with underpenetrated mining automation retrofit demand in Western Australia and Queensland, where remote-operated rotary drill configurations face limited qualified suppliers. Target equipment-as-a-service contracting models for mid-sized Florida and Illinois construction firms seeking to offload OSHA compliance burdens. Pursue white-label partnerships with established rental channel operators rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking vibration certification capabilities and mining heritage assets. Long-term viability favors targets with captive brushless motor controller development and established EPA emissions compliance architecture for compressor system integration. Watch lithium-ion energy density announcements from Japanese and South Korean battery suppliers as the inflection signal for cordless electric displacement velocity in automotive assembly applications.| Strategic Initiative | Industry Significance |
|---|---|
| Vibration Certification Laboratory Acquisition | OSHA compliance mandates in California and Texas construction procurement specifications elevate in-house testing from cost center to competitive barrier. |
| Brushless Motor Controller Integration | German automotive OEM facilities in Stuttgart and Wolfsburg prioritize torque precision over raw pneumatic impact force in fastening operations. |
| Rental Channel Partnership Expansion | Equipment-as-a-service contracting displaces outright purchase among Florida and Illinois mid-sized commercial construction firms seeking regulatory burden offload. |
| REACH-Compliant Lubricant Reformulation | ECHA substance restrictions compel housing composite and lubricant substitutions that create product differentiation for compliant European imports. |
| Remote-Operated Mining Configuration Development | Underground operations in Chile and Australia present retrofit demand for specialized rotary drill systems with explosion-safe certification. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with maintenance directors at mining operations, plant engineers in automotive assembly facilities, OEM procurement teams specifying pneumatic fleets, and aftermarket service heads managing rental channel compliance. Secondary sources included OSHA enforcement databases, ECHA REACH substance registries, EPA stationary source permitting records, and MIIT industrial upgrading directives. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Reconciliation of production volume data from Chinese industrial zones, import statistics from German and Japanese customs authorities, and end-user procurement surveys from Texas and California construction firms informed the analytical framework. Segmentation dimensions spanned power source configuration, application environment, end-user sophistication tier, and technology control architecture. CAGRs derived from elasticity-adjusted demand projections incorporating infrastructure spending trajectories and regulatory compliance cost curves. Industry-specific forecast inputs included compressor fleet depreciation schedules and lithium-ion battery energy density improvement curves.
Regulatory enforcement intensity shifts, rare-earth supply disruption events, and cordless electric torque output breakthroughs are the dominant revision risks to the outlook presented. Deviation in OSHA vibration standard adoption velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Surface Planer Market
Tools
High-Speed Steel Metal Cutting Tools Market
Tools
Nut Runner Market
Tools
Mechanical Hand Tools Market
Tools
Manual Cutting Equipment Market
Tools
Press Machine Market
Tools
Lathe Machines Market
Tools
Handheld Engraving Machine Market
Tools
Metal Cutting Tools Market
Tools
Woodworking Power Tools Market
Tools
Laser Engraving Machine Market
Tools
Drill Bit Market
Tools
Stationary Wood Planer Market
Tools
Cutting Equipment Market
Tools
Construction Anchors Market
Tools
Step Ladder Market