
 Core Shooter Machine Market | 2026-2036
Core Shooter Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Core Shooter Machine Market Insights
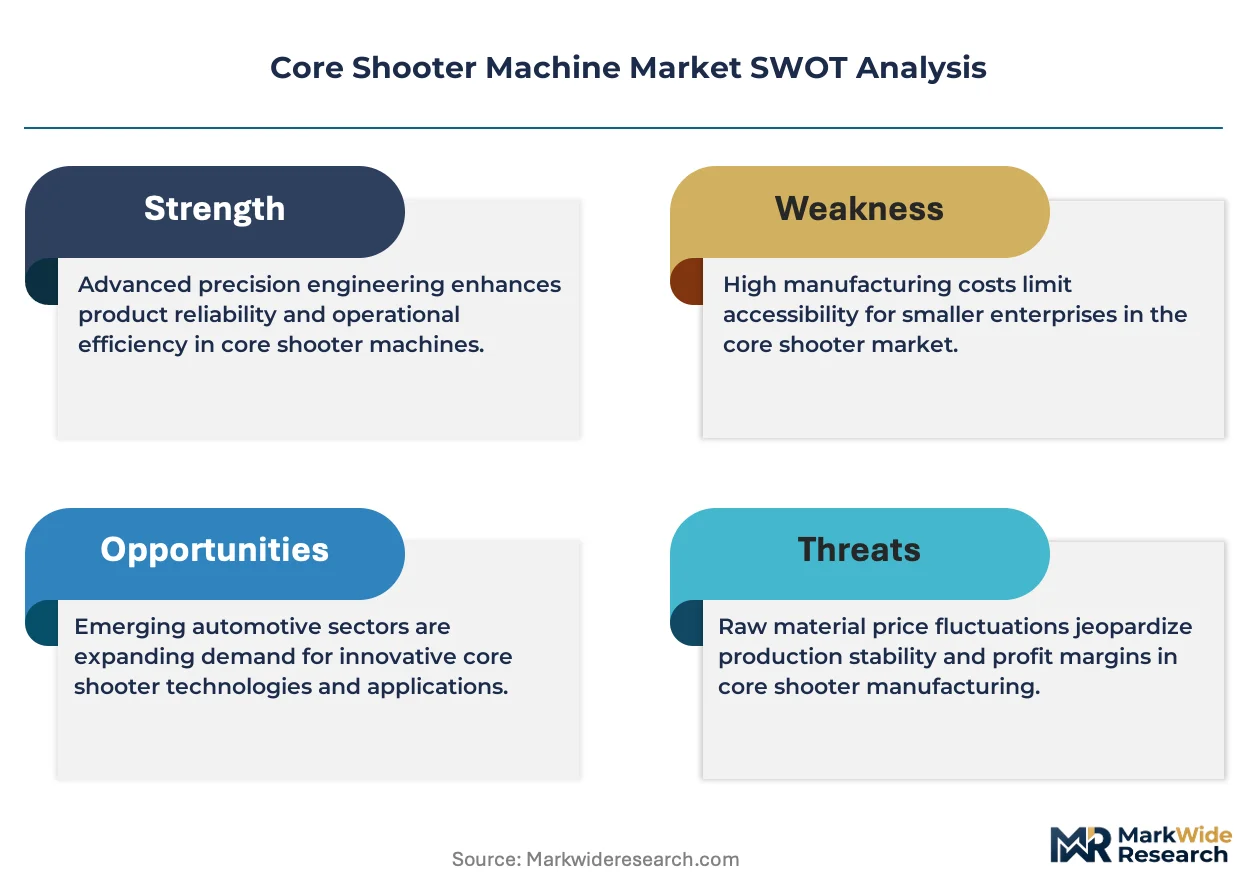
The EU Green Deal's embedded carbon tracking requirements for industrial equipment is hardening demand for energy-efficient core shooters across European foundry networks. Laempe Mössner Sinto GmbH leverages its German engineering base to dominate high-precision cold box installations for automotive OEMs. Sintokogio sustains competitive positioning through integrated foundry automation systems that extend beyond standalone core shooters. EMAG Group anchors its presence in servo-driven electric technology, where precision control reduces resin waste and energy draw.
A core shooter machine is a foundry molding device that blows sand mixed with chemical binders into heated or ambient tooling cavities to form sand cores, typically achieving compaction pressures of 6-25 bar depending on the process. These cores create internal cavities in metal castings for engine blocks, cylinder heads, and hydraulic valve bodies. Cold box core shooters command the largest product type position due to their speed and compatibility with aluminum casting workflows, while servo-driven technology represents the fastest-expanding segment as foundries replace hydraulic units to cut energy consumption and improve repeatability. Engine components and valve manufacturing applications concentrate margin pools because aerospace and automotive buyers specify certified process control.
Germany's KBA enforces emissions standards on foundry equipment that influence core shooter ventilation and binder handling designs, while REACH compliance through ECHA restricts certain phenolic resin formulations used in hot box processes. The EU F-Gas Regulation indirectly shapes equipment specifications as foundries retrofit climate-controlled core storage to protect chemically bonded sand from humidity degradation. Buyers must monitor how evolving carbon border adjustments and machinery efficiency mandates reshape total cost of ownership calculations for new core shop investments.
Market Dynamics
Foundry electrification is compressing equipment replacement cycles as servo-driven core shooters displace hydraulic systems to meet tightening energy efficiency mandates and resin waste reduction targets across European automotive supply chains.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Foundries in Germany's Baden-Württemberg cluster are retrofitting core shops with low-emission cold box systems to comply with formaldehyde emission caps on resin binders.
- Aluminum powertrain casting demand:Automotive OEMs specify cold box core shooters for cylinder head and engine block production, driving equipment orders from tier-one suppliers.
- Servo-electric technology maturation:Precision motion control reduces energy draw and improves shot-to-shot repeatability, accelerating adoption among mid-sized European foundries.
Market Restraints
- Phenolic resin input volatility:REACH compliance through ECHA restricts certain hot box resin formulations, forcing foundries to qualify alternative binder chemistries at elevated cost.
- Equipment supply concentration:German and Japanese machinery builders dominate high-precision cold box manufacturing, limiting buyer negotiating leverage.
- 3D-printed sand core substitution:Binder jetting systems for prototype and low-volume production are capturing applications below 5,000-unit annual volumes.
Strategic Opportunities
- India's PLI scheme for automotive components:Domestic foundry modernization programs are creating first-mover advantage for cold box technology transfer partnerships.
- Carbon border adjustment mechanism:EU importers of cast components face embedded carbon tracking requirements, incentivizing energy-efficient core shop investments.
- Machine vision integration:Real-time core quality inspection converges with servo-driven shooting control to enable closed-loop process automation.
Industry Challenges
- Process control specialist scarcity:Cold box chemistry optimization requires hybrid mechanical-chemical engineering expertise that outpaces vocational training pipelines.
- Legacy hydraulic system integration:Retrofitting servo-electric shooting units into existing core shop layouts demands custom mechanical engineering and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Core Shooter Machine Market |
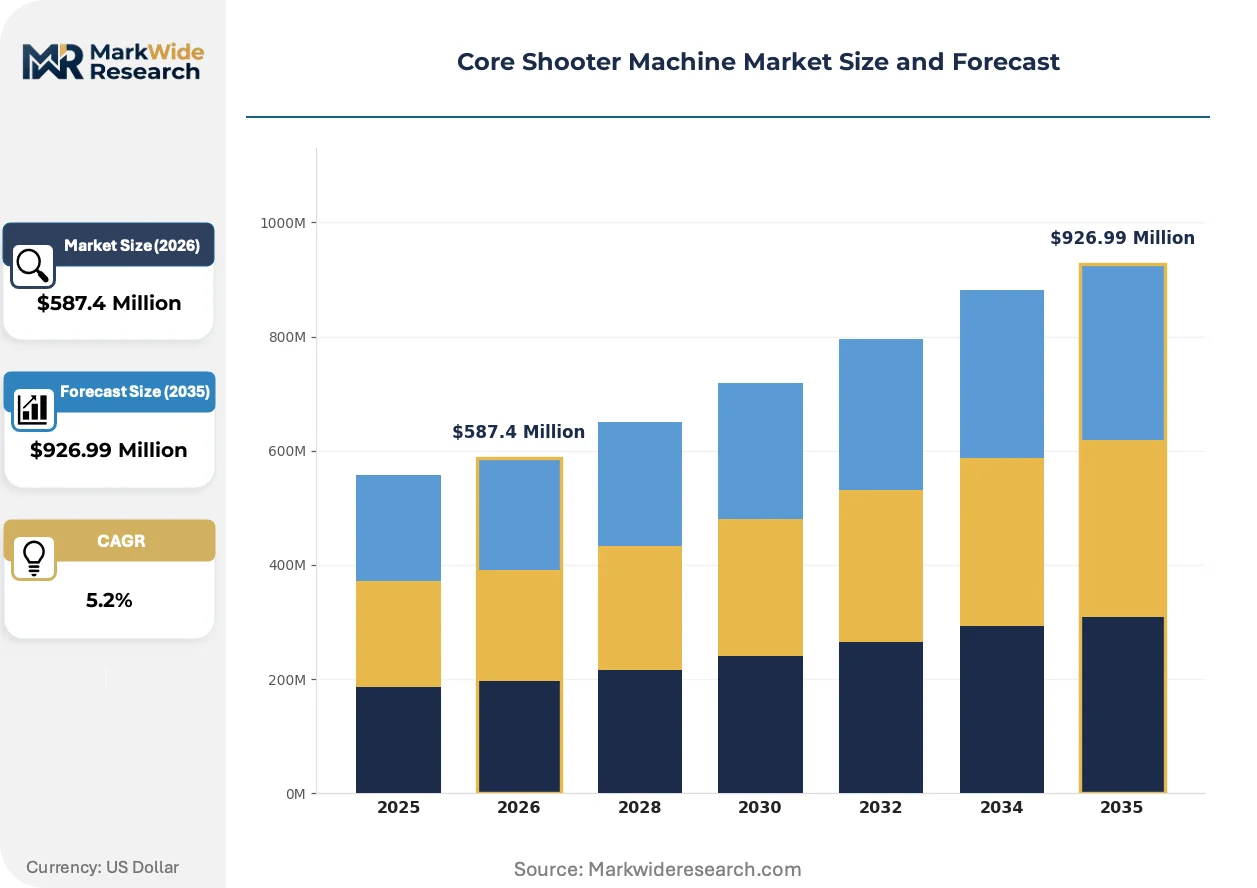
| Market Size in 2026 | $587.4 Million |
| Market Size in 2035 | $926.99 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Box Core Shooter, Hot Box Core Shooter, Air Set Core Shooter, Resin Coated Core Shooter, Shell Molding Core Shooter Technology: Hydraulic, Pneumatic, Electric, Mechanical, Servo-driven Application: Foundry, Engine Components, Industrial Machinery, Heavy Equipment, Valve Manufacturing End User Industry: Metal Casting, Mining Equipment Fabricators, Construction Equipment Manufacturers, Power Generation Plants, Agricultural Machinery Producers |
| Companies Covered | Laempe Mössner Sinto GmbH, Sintokogio, EMAG Group, Mitsubishi Heavy Industries Machine Tool, Hanwha Precision Machinery, ATHI Group, EMP Industrial Group, Yizumi Precision Machinery Co., Ltd., Xi'an Fushun Automation Intelligent Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Core Shooter Machine Market Trends and Innovations
Digital thread integration and electrification are redefining core shooter architecture as foundries prioritize measurable process control over throughput maximization alone.
Servo-electric shooting and clamping systems are modularizing core shooter design, allowing foundries to configure machine specifications to specific core geometries without hydraulic infrastructure. Tier-one automotive suppliers in Germany and Japan are specifying these architectures for new greenfield installations. The technology is modularizing competitive differentiation around energy consumption metrics and shot repeatability rather than maximum compaction pressure ratings.
The EU F-Gas Regulation is tightening climate-controlled storage requirements for chemically bonded sand cores, forcing foundries to retrofit humidity-controlled core warehouses or risk binder degradation. This industrial consequence elevates total cost of ownership calculations for core shop investments. Cold box operations in Northern Europe are responding with integrated environmental management systems that link shooting parameters to warehouse climate data.
Buyer specifications now mandate certified process data packages for each core batch, displacing traditional acceptance sampling. Foundry procurement departments are unbundling equipment purchases from aftermarket service contracts, selecting specialized maintenance providers independent of original equipment manufacturers. This behavioral shift is most visible in Germany's Bavaria automotive supplier cluster, where multi-site foundry groups standardize on open-architecture control systems to enable third-party service competition.
Core Shooter Machine Market Segmentation
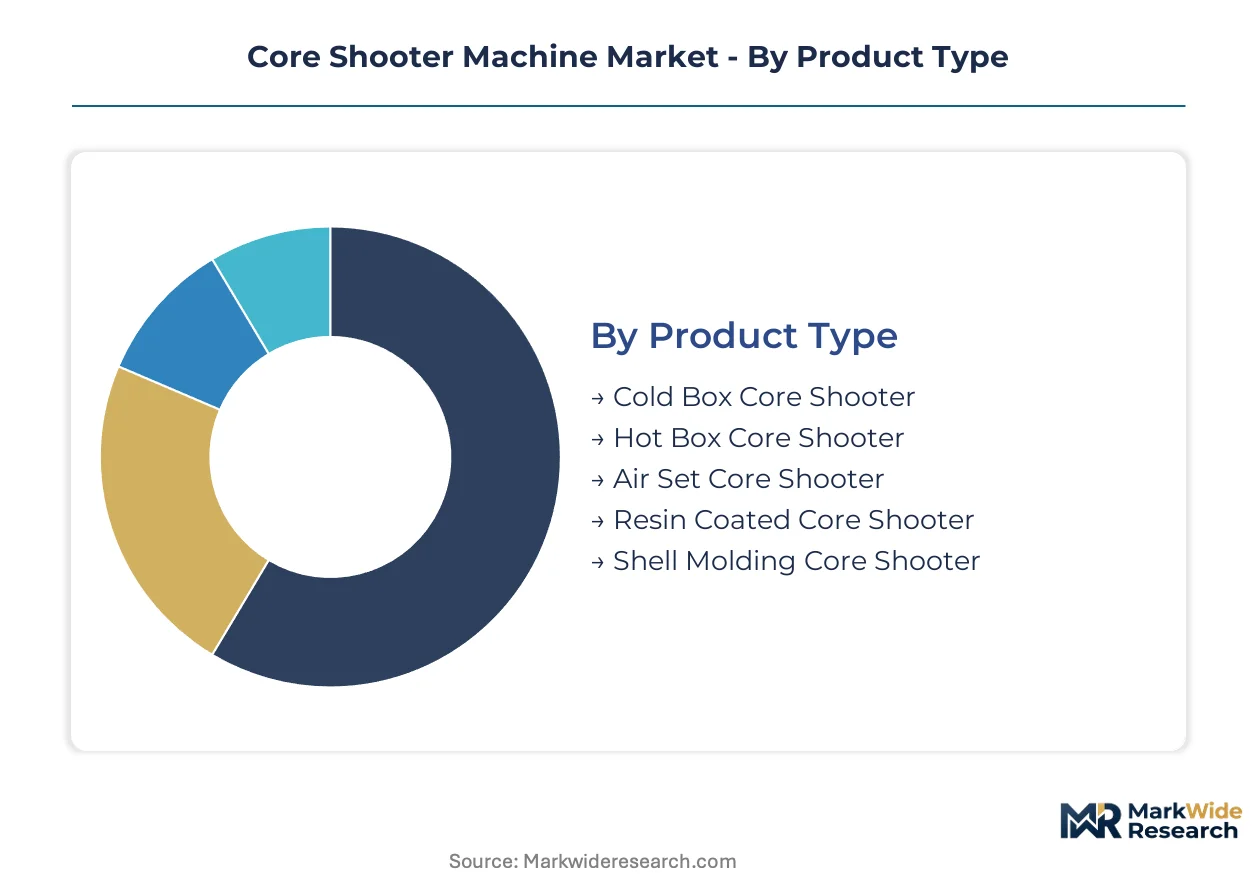
Core shooter machine segmentation reveals how foundries balance precision requirements against energy constraints and production scale. Technology choices and application specifications determine equipment architecture, maintenance intensity, and total cost of ownership across automotive and industrial supply chains.
Product Type:
Cold box chemistry and thermal process specifications define the competitive axis across product architectures.
- Cold Box Core Shooter:Ambient-temperature curing with amine gas catalysts enables rapid cycle times under 30 seconds per core. German automotive foundries in Baden-Württemberg specify these systems for aluminum cylinder head production where dimensional tolerance demands exceed ±0.3 millimeters.
- Hot Box Core Shooter:Heated tooling cavities accelerate phenolic resin polymerization for ferrous casting applications. REACH compliance through ECHA restricts certain formaldehyde-emitting resin formulations, forcing foundries to qualify alternative binder chemistries at elevated validation cost.
- Air Set Core Shooter:No-bake binder systems suit heavy-section castings where core strength must withstand prolonged metal static pressure.
- Resin Coated Core Shooter:Pre-coated sand eliminates on-site binder mixing for specialized aerospace and defense casting programs.
- Shell Molding Core Shooter:Phenolic resin-coated sand baked against heated metal patterns produces high-definition surfaces for valve body and pump housing applications.
Mature deployment sits with hot box systems in traditional ferrous foundries. Newer deployment is concentrated in cold box configurations serving aluminum powertrain casting expansion.
Technology:
Actuation architecture determines energy draw, repeatability, and integration complexity with downstream automation.
- Servo-driven:Precision motion control eliminates hydraulic fluid maintenance while reducing energy consumption. EMAG Group and Japanese builders specify these architectures for greenfield installations where EU Ecodesign for Sustainable Products Regulation compliance is mandatory.
- Hydraulic:Established high-force compaction systems dominate legacy core shops with existing infrastructure. Retrofit complexity and energy efficiency mandates are compressing replacement cycles toward servo-electric alternatives.
- Electric:Simplified drivetrains reduce mechanical maintenance intervals compared to hydraulic equivalents.
- Pneumatic:Compressed air systems serve low-volume foundries with limited capital budgets and intermittent production schedules.
- Mechanical:Cam-driven architectures persist in developing markets where spare parts availability outweighs efficiency optimization.
Installed base concentration favors hydraulic and mechanical systems. Steepest expansion trajectory belongs to servo-driven configurations as carbon border adjustment mechanisms harden energy accounting requirements.
Application:
Dimensional precision and batch volume requirements stratify equipment specification across end-use categories.
- Engine Components:Cylinder block and head cores demand certified process control with full batch traceability. Automotive OEMs specify cold box servo-driven systems for aluminum powertrain programs where porosity defects trigger scrap rates above 2 percent.
- Valve Manufacturing:Hydraulic and pneumatic valve bodies require complex internal passages with surface finish specifications below Ra 6.3 micrometers. Aerospace and energy sector buyers mandate AS9100 or equivalent quality system certification.
- Foundry:General-purpose core production serves diverse casting portfolios with flexible tooling changeover capabilities.
- Industrial Machinery:Structural castings tolerate wider dimensional tolerances, enabling mechanical and pneumatic system deployment.
- Heavy Equipment:Large-section cores for mining and construction machinery prioritize compaction force over cycle speed.
Margin concentration aligns with engine components and valve manufacturing where certification requirements limit supplier pools. Volume concentration sits with general foundry applications serving dispersed industrial demand.
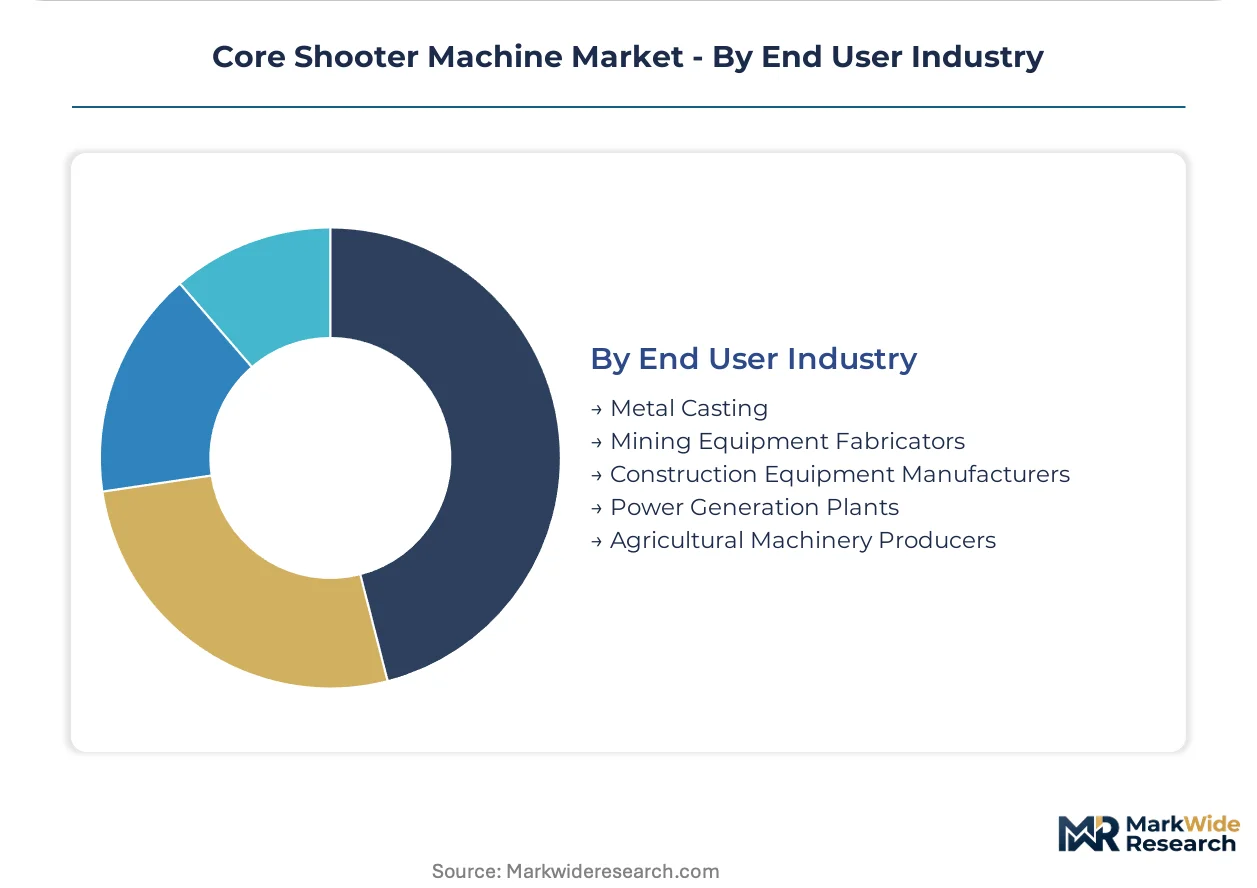
End User Industry:
Production scale and casting alloy specifications determine equipment procurement patterns across industrial sectors.
- Metal Casting:Dedicated foundries serving automotive and industrial supply chains represent the primary equipment demand source. Germany's Bavaria cluster modernization programs are accelerating cold box servo-driven adoption among mid-sized tier-one suppliers.
- Construction Equipment Manufacturers:In-house captive foundries for excavator and loader components prioritize reliability and maintenance simplicity over maximum throughput.
- Mining Equipment Fabricators:Abrasion-resistant alloy castings require specialized core strength for thick-section geometries.
- Power Generation Plants:Turbine and boiler component casting programs demand high-integrity cores for nickel and cobalt superalloys.
- Agricultural Machinery Producers:Seasonal production patterns favor flexible equipment configurations with rapid tooling changeover.
Procurement scale concentrates in metal casting specialists with multi-customer portfolios. Emerging equipment demand is surfacing among construction equipment manufacturers verticalizing foundry operations to secure supply chain control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's automotive foundry corridor anchors equipment demand as tier-one suppliers modernize core shops for aluminum powertrain casting programs.
Germany
KBA emissions standards drive ventilation and binder handling redesigns in core shooter specifications across Bavaria's supplier cluster. The EU Ecodesign for Sustainable Products Regulation enforces formaldehyde emission caps that accelerate cold box retrofits. Mid-sized foundries in Stuttgart and Munich regions are replacing hydraulic systems with servo-driven architectures to meet carbon border adjustment requirements.
China
Dual carbon goals under MEE directives compress energy efficiency mandates for foundry equipment procurement in the Yangtze River Delta. GB standards for industrial machinery emissions shape core shooter import specifications. Foundry modernization programs in Shanghai and Jiangsu province concentrate demand for electric and servo-driven shooting systems serving domestic automotive supply chains.
United States
EPA foundry air toxics standards influence core shop ventilation investments across the Great Lakes automotive belt. NHTSA fuel economy regulations sustain aluminum engine block casting demand that specifies cold box precision. Michigan and Ohio foundry clusters are upgrading hydraulic equipment to reduce energy draw and resin waste in high-volume production.
India
The PLI scheme for automotive components funds domestic foundry capability expansion in Maharashtra and Gujarat. BIS machinery safety standards shape equipment qualification protocols for imported core shooters. Pune and Ahmedabad foundry zones are establishing first cold box installations to serve OEM localization programs.
Japan
METI energy efficiency benchmarks for industrial equipment accelerate servo-electric adoption in Nagoya's automotive supplier network. JIS standards for foundry machinery quality certification limit supplier pools for precision applications. Toyota City and Hamamatsu foundry clusters maintain process leadership through integrated automation systems.
Core Shooter Machine Market Competitive Landscape
The competitive structure tilts toward precision engineering specialists with deep automotive foundry relationships. German and Japanese machinery builders concentrate high-specification cold box manufacturing, limiting buyer leverage on pricing and delivery timelines. Two strategic archetypes dominate: integrated foundry automation providers and standalone core shooter precision specialists. Capacity expansion in servo-electric architectures and technology licensing partnerships for emerging markets represent the primary competitive moves.
Among German engineering specialists, Laempe Mössner Sinto GmbH and EMAG Group exemplify the precision-automation archetype with established positions in automotive OEM supply chains. Sintokogio anchors the integrated-systems approach through its foundry automation portfolio. These three occupy positions that reflect the market's bifurcation between standalone equipment excellence and full-line integration capabilities.
| Leading Market Players |
|---|
| Laempe Mössner Sinto GmbH |
| Sintokogio |
| EMAG Group |
| Mitsubishi Heavy Industries Machine Tool |
| Hanwha Precision Machinery |
| ATHI Group |
| EMP Industrial Group |
| Yizumi Precision Machinery Co., Ltd. |
| Xi'an Fushun Automation Intelligent Technology |
| Others |
Pricing and Supply Chain Analysis
Tier-one automotive suppliers in Germany's Baden-Württemberg cluster concentrate procurement volume, anchoring value-based pricing tied to certified process yield guarantees rather than equipment list prices alone. This buyer concentration forces machinery builders to bundle performance warranties with servo-electric core shooter sales, shifting revenue recognition toward uptime-based service contracts.
Pricing Analysis
Value-based pricing anchored to core dimensional yield and energy consumption metrics dominates German and Japanese manufacturer quotations. Price differentiation separates AS9100-certified aerospace configurations from general foundry equipment, with premium tiers commanding substantial markups for full batch traceability systems. Cost compression in mid-range hydraulic retrofits is intensifying because REACH compliance forces binder chemistry requalification expenses onto foundries. Small-scale job shops in India and Southeast Asia exhibit highest price sensitivity, while German automotive OEMs prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Direct-to-OEM channels handle tier-one automotive demand in Germany and Japan, while distributor networks serve fragmented foundry demand across India and Southeast Asia. Manufacturing concentration sits in Germany, Japan, and China, with precision cold box assemblies drawing from specialized servo-motor suppliers in Japan and control system providers in Germany. Single-source vulnerability in high-precision ball screw and linear motion components creates supply chain risk. Raw material dependencies span specialty steel for tooling frames, rare-earth magnets for servo motors, and phenolic resin precursors subject to ECHA restrictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The core shooter machine market is becoming a vertical-integration race as equipment builders capture margin from aftermarket service and resin chemistry optimization. Foundries are pursuing backward integration into core storage and climate control to meet EU F-Gas Regulation requirements.
For Market Incumbents: Lock in automotive OEM relationships through certified process data packages that embed core shooters into broader foundry automation architectures. Defend against 3D-printed sand core substitution by emphasizing throughput economics above 5,000-unit annual volumes. Prioritize capacity expansion in servo-electric architectures to capture carbon border adjustment-driven replacement cycles across European foundry networks. For New Entrants and Emerging Players: The premium-to-economy price gap in certified aerospace valve manufacturing equipment creates entry opportunity for mid-tier challengers. Target India's PLI-funded automotive foundry modernization in Maharashtra and Gujarat with technology licensing partnerships rather than direct equipment sales. Pursue go-to-market angles through open-architecture control systems that unbundle aftermarket service from OEM contracts. For Investors and Strategic Acquirers: The window for entry favors servo-electric technology specialists with hybrid mechanical-chemical engineering capabilities. Long-term viability hinges on process control software integration rather than standalone hardware manufacturing. Watch for inflection signals in carbon border adjustment enforcement stringency, which will accelerate replacement demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Technology Licensing | Enables emerging market foundries to bypass hydraulic infrastructure investments while meeting EU Ecodesign compliance. |
| Resin Chemistry Optimization Partnership | Captures margin from REACH-compliant cold box binder formulations that reduce formaldehyde emissions. |
| Machine Vision Integration Development | Links real-time core quality inspection with servo-driven shooting control for closed-loop automation. |
| Climate-Controlled Core Storage Expansion | Addresses EU F-Gas Regulation requirements while generating recurring service revenue from humidity management systems. |
| Automotive Tier-One Supply Chain Certification | Qualifies equipment for aluminum powertrain casting programs where porosity defect rates drive OEM specifications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this core shooter machine market analysis. Primary interviews with foundry plant managers, OEM procurement teams, aftermarket service heads, and resin chemistry specialists combined with secondary validation from KBA emissions standards documentation, ECHA REACH substance restrictions, and EU Ecodesign implementing measures. Foundry automation trade association statistics, machinery import-export databases, and tier-one automotive supplier sustainability reports provided demand-side triangulation against bottom-up equipment shipment analysis and top-down foundry capacity modeling.
Data-stream reconciliation across shipment volumes, installed base estimates, and replacement cycle assumptions shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type (cold box, hot box, shell molding), technology architecture (servo-driven, hydraulic, pneumatic), application precision requirements (engine components, valve manufacturing, general foundry), and end-user industry vertical (automotive metal casting, construction equipment, power generation). CAGRs derived from equipment replacement elasticity to carbon border adjustment mechanisms and foundry electrification mandates, with specific inputs from EU Green Deal embedded carbon tracking requirements and automotive aluminum casting expansion programs.
Inputs from German and Japanese machinery builder order backlogs were available through the study window; gaps in emerging market foundry modernization disclosure introduce uncertainty bands around India and Southeast Asia demand trajectories. Forecasts reflect assumptions regarding REACH compliance timeline adherence and PLI scheme disbursement continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Hydraulic Tools and Equipment Market
Tools
Woodworking Tools Market
Tools
Hacksaw Blades Market
Tools
Fiber Laser Cutting Machines Market
Tools
Entrenching Tool Market
Tools
Pruning Saw Market
Tools
Masonry Cleaners Market
Tools
Vise-Grip Pliers Market
Tools
Rotary Knife Cutters Market
Tools
Chainsaw Market
Tools
Bandsaw Market
Tools
Wood Router Market
Tools
Blowing Torch Market
Tools
Bearing Installation Tool Kit Market
Tools
Broaching Tools Market
Tools
Cutting Tool Inserts Market