
 Floor Saw Market | 2026-2036
Floor Saw Market Size, Share, and Industry Trends Forecast 2026-2036
Floor Saw Market Analysis
Specialized equipment distribution is narrowing as regional dealers consolidate around full-service contracts and factory-authorized service centers. Husqvarna AB leverages its captive rental network and aftermarket parts infrastructure to sustain repeat revenue from municipal fleet operators. Hilti Corporation anchors its position through direct-to-contractor sales teams and tool fleet management subscriptions that reduce customer capital outlay. Makita Corporation competes on cordless platform compatibility, extending its battery ecosystem into lighter-duty concrete cutting applications.
A floor saw is a walk-behind or handheld powered cutting machine engineered to slice through cured concrete, asphalt, or masonry using diamond-segmented or abrasive blades, typically operating at blade speeds between 3,000 and 5,000 RPM with water suppression systems for dust control. Its primary industrial purpose is to create controlled joints, remove damaged pavement sections, or trench utility channels without fracturing surrounding substrate. Gas-powered saws still dominate heavy-duty asphalt cutting for highway contractors, though electric variants are gaining share among indoor concrete specialists where emissions compliance and noise ordinances restrict combustion equipment. Diamond blade technology commands the premium tier of the technology split, as wet cutting configurations extend blade life and reduce respirable silica exposure compared to dry cutting alternatives.
OSHA enforces silica exposure limits through its Respirable Crystalline Silica standard, compelling contractors to specify water-fed cutting systems or invest in supplemental dust collection. The EPA regulates engine emissions for non-road equipment under Tier 4 Final standards, while the EU F-Gas Regulation and CE marking requirements constrain hydraulic system refrigerants and machine safety certifications for European market access. Stakeholders must weigh the capital cost of electric platform migration against the regulatory compliance burden and total cost of ownership over equipment lifecycle.
Market Dynamics
The floor saw market is pivoting around the tension between combustion-engine dominance in heavy asphalt cutting and the regulatory squeeze toward electrification for indoor concrete applications. Tier 4 Final compliance costs and silica exposure mandates are accelerating platform diversification among equipment fleets.
Growth Catalysts
- Federal highway spending:United States infrastructure appropriations sustain fleet renewal cycles for state transportation departments and runway refurbishment contractors.
- EU Green Deal:Emissions standards under the F-Gas Regulation push municipal procurement toward battery-adapted platforms for urban construction zones.
- Diamond blade wet cutting:Extended blade life and reduced respirable silica exposure drive specification preference among safety-conscious contractors.
Market Restraints
- Battery energy density limits:Lithium-ion cell chemistry constrains runtime for continuous heavy-duty asphalt trenching applications.
- Hydraulic fluid supply concentration:Specialized refrigerant-dependent systems face sourcing friction under EU F-Gas phase-down schedules.
- Capital cost asymmetry:Electric platform premiums stretch municipal procurement budgets compared to gas-powered unit replacement cycles.
Strategic Opportunities
- Service-center consolidation:Factory-authorized maintenance hubs capture aftermarket revenue streams from fragmented dealer networks.
- Tool fleet subscriptions:Hilti Corporation's direct-to-contractor model demonstrates capital-outlay reduction through usage-based equipment access.
- Cordless platform extension:Battery ecosystem compatibility opens lighter-duty concrete cutting segments to multi-tool construction fleets.
Industry Challenges
- Silica compliance technician training:OSHA Respirable Crystalline Silica standard enforcement requires certified operators for water-fed system deployment.
- CE marking timeline compression:European safety certification delays for new electric platform introductions extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor Saw Market |
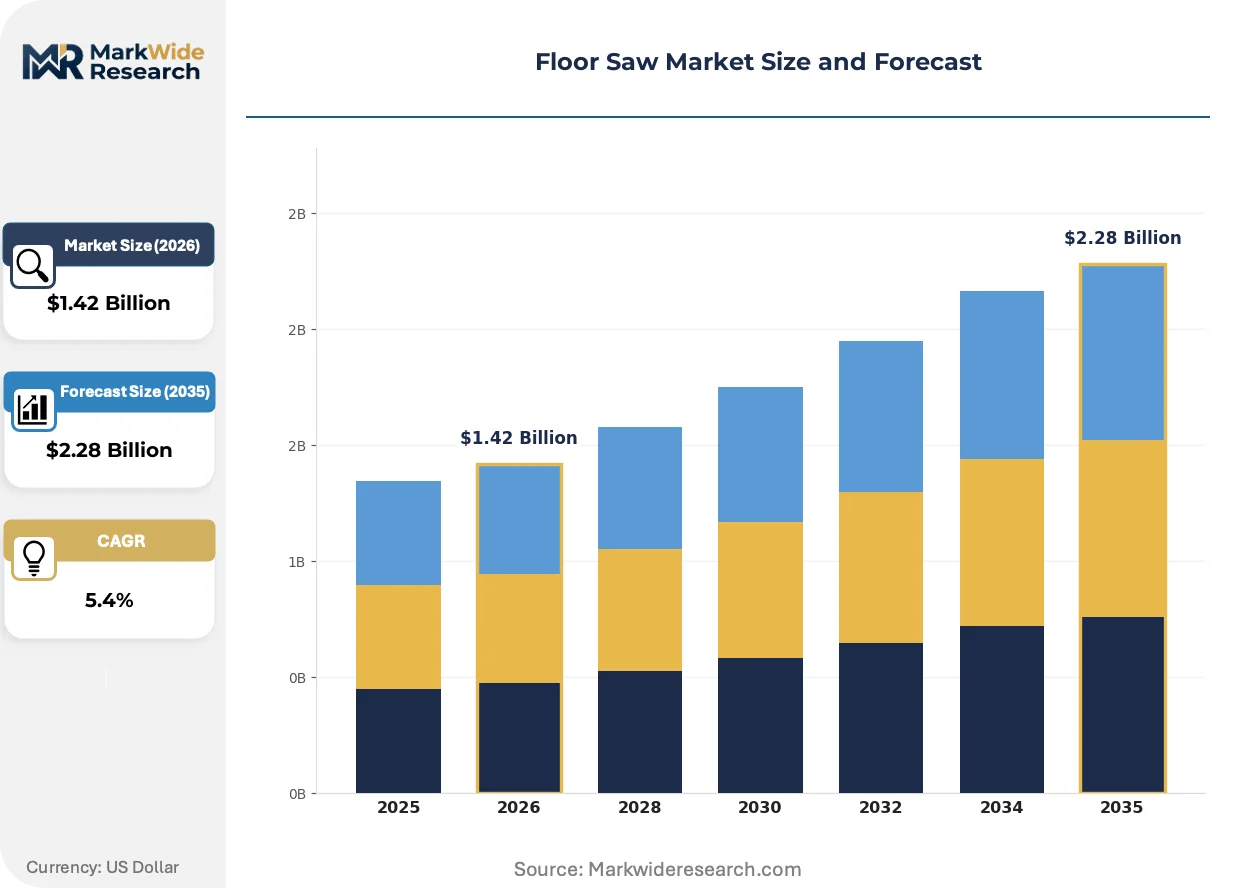
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Saws, Gas-Powered Saws, Hydraulic Saws, Handheld Saws Application: Concrete Cutting, Asphalt Cutting, Tile Cutting, Masonry Cutting End User: Construction Companies, Landscaping Services, Municipalities, DIY Enthusiasts Technology: Circular Blade, Diamond Blade, Wet Cutting, Dry Cutting |
| Companies Covered | Husqvarna AB, Hilti Corporation, STIHL, Makita Corporation, Fairport Construction Equipment Ltd, Wacker Neuson, Tyrolit, Diamond Products, Chicago Pneumatic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor Saw Market Emerging Trajectories
Equipment intelligence and powertrain substitution are compressing traditional product lifecycles. Manufacturers now compete on total cost of ownership metrics rather than upfront unit economics.
Brushless motor controllers paired with high-density battery packs are virtualizing the torque delivery profiles once exclusive to gas-powered engines. Indoor concrete specialists in Germany and the Netherlands specify these configurations to satisfy noise ordinances and emissions restrictions. The technology is virtualizing the historical performance gap between combustion and electric platforms for mid-duty cutting depths.
The EPA Tier 4 Final non-road engine standards impose after-treatment hardware costs that erode margins on compact gas-powered saws. Highway contractors absorb these premiums through fleet standardization, while rental yards delay replacement cycles. California Air Resources Board amendments extend these constraints to older equipment retrofit requirements.
Subscription-based tool fleet management is displacing outright purchase for municipal maintenance departments. State-level concrete runway programs in Texas and Florida pilot usage-based billing to preserve capital budgets. Germany's municipal infrastructure agencies negotiate full-service contracts bundling equipment, blades, and maintenance through consolidated regional dealers.
Floor Saw Market Segmentation
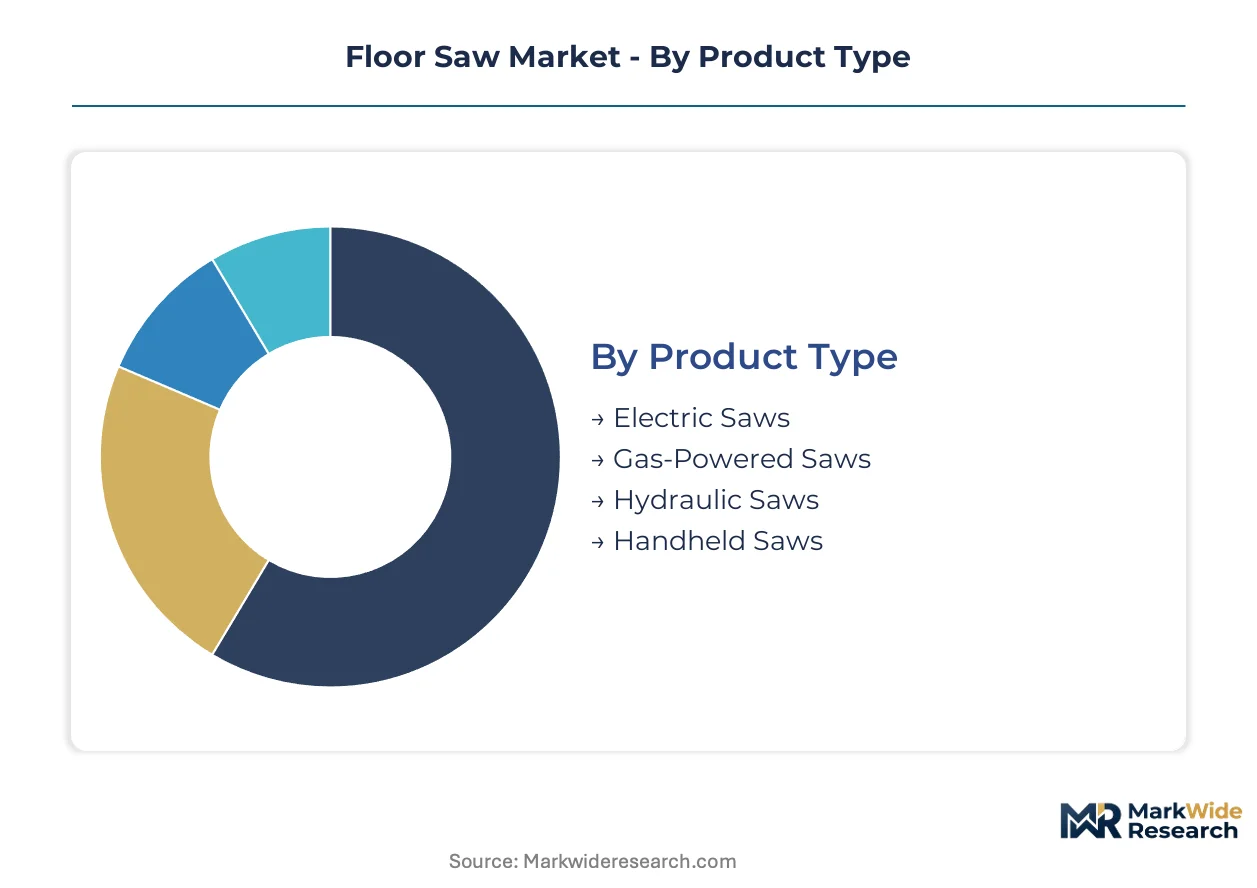
Floor saw procurement patterns diverge sharply across powertrain configurations, material applications, and operator sophistication. Equipment specification decisions cascade through blade technology selection, maintenance contracting terms, and regulatory compliance obligations.
Product Type:
Cost tier stratification separates premium hydraulic systems from commoditized handheld units, with powertrain chemistry driving total cost of ownership calculations.
- Electric Saws:Brushless motor controllers paired with high-density battery packs deliver torque profiles matching gas engines for mid-duty cutting depths. Demand concentrates among indoor concrete specialists in Germany and the Netherlands where noise ordinances and EU F-Gas Regulation emissions restrictions constrain combustion equipment.
- Gas-Powered Saws:Two-stroke and four-stroke combustion engines operating at 3,000-5,000 RPM dominate heavy-duty asphalt trenching for highway contractors. United States federal highway spending sustains fleet renewal cycles, though EPA Tier 4 Final after-treatment hardware costs erode margins on compact units.
- Hydraulic Saws:Fluid-driven powertrains attach to external pumps for continuous high-torque applications without engine weight. Specialized refrigerant-dependent systems face sourcing friction under EU F-Gas phase-down schedules.
- Handheld Saws:Compact portable units serve utility trenching and confined-space cutting where walk-behind machines cannot maneuver.
Gas-powered saws hold installed capacity. Electric saws are rotating up the share rankings.
Application:
Material hardness and aggregate composition determine blade specification, water suppression requirements, and equipment vibration tolerance.
- Concrete Cutting:Cured concrete with limestone or granite aggregate demands diamond-segmented blades operating at controlled feed rates to prevent spalling. OSHA Respirable Crystalline Silica standard enforcement compels water-fed system deployment among certified operators.
- Asphalt Cutting:Bituminous pavement rehabilitation requires aggressive tooth patterns and continuous cooling to prevent binder smearing. State transportation departments in Texas and Florida sustain demand through runway refurbishment programs.
- Tile Cutting:Ceramic and porcelain materials specify continuous-rim diamond blades with minimal chipping. Residential renovation contractors in suburban United States markets drive replacement demand.
- Masonry Cutting:Brick, block, and stone applications combine abrasive and diamond blade technologies depending on bond hardness.
Concrete cutting anchors equipment utilization rates. Asphalt cutting is climbing the fastest as infrastructure appropriations accelerate.
End User:
Customer type determines procurement modality, service contract attachment rates, and capital budget cycle timing.
- Construction Companies:General and specialty contractors balance equipment ownership against rental yard access for project-specific capacity surges. Tiered pricing structures separate premium fleet purchases from standard rental agreements.
- Landscaping Services:Hardscape installation crews require portable equipment for paver cutting and edging applications with lower duty cycles than commercial construction.
- Municipalities:Public works departments negotiate full-service contracts bundling equipment, blades, and maintenance through consolidated regional dealers. Germany's municipal infrastructure agencies exemplify this procurement consolidation.
- DIY Enthusiasts:Consumer-grade electric units serve residential renovation projects with intermittent usage patterns and minimal maintenance capability.
Construction companies command the largest equipment installed base. Municipalities are gaining share fastest through fleet standardization initiatives.
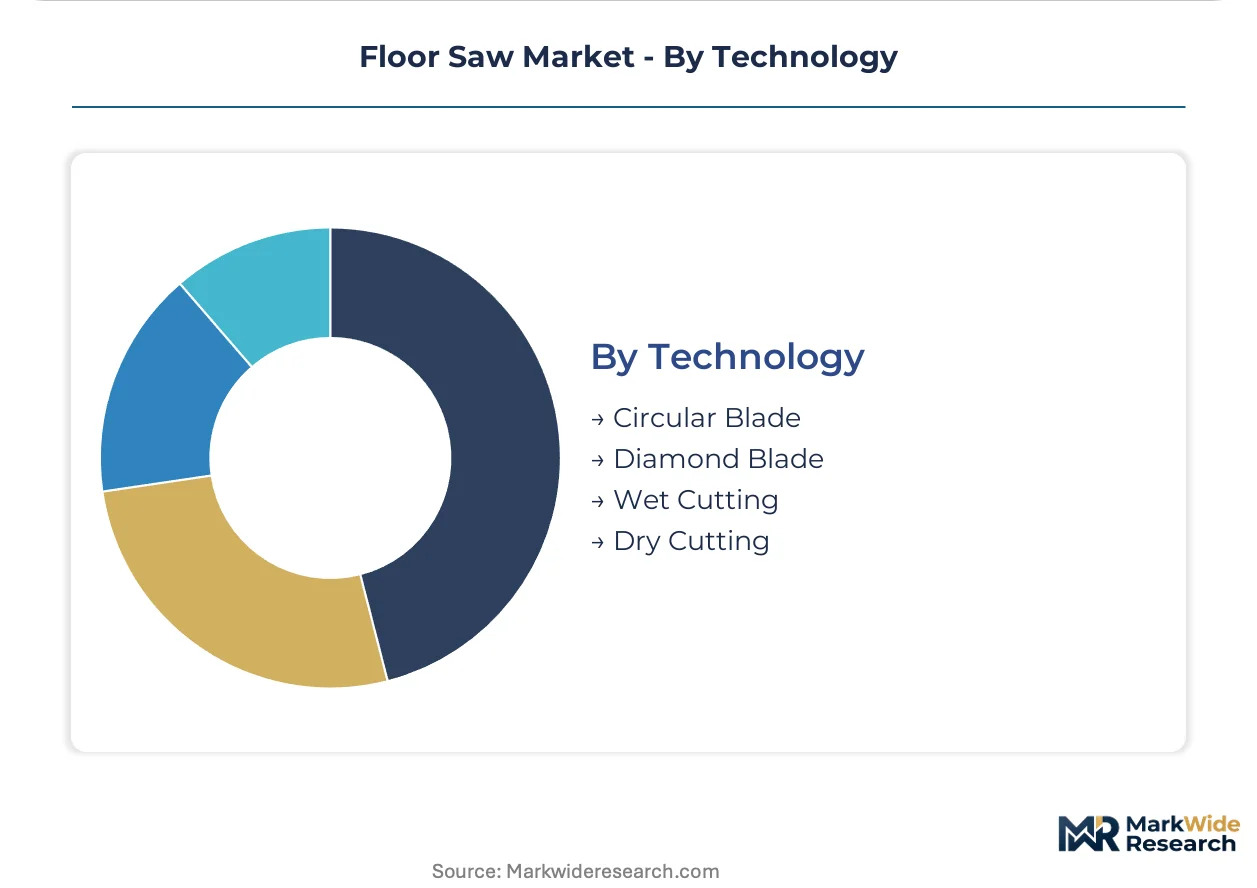
Technology:
Blade geometry and cooling methodology segment by performance tier, operator safety exposure, and consumable replacement economics.
- Circular Blade:Abrasive and carbide-tipped steel discs serve lower-cost dry cutting applications with shorter service intervals. Rental yards stock these for price-sensitive contractors.
- Diamond Blade:Sintered metal matrices with synthetic diamond grit command premium positioning for extended cutting life and precision. Wet cutting configurations extend blade life and reduce respirable silica exposure compared to dry alternatives.
- Wet Cutting:Water suppression systems control dust generation and cool blade-matrix interfaces during continuous operation. OSHA enforcement drives specification preference among safety-conscious contractors.
- Dry Cutting:Vacuum-assisted or uncontrolled dust generation suits outdoor applications where water supply constraints or freezing temperatures prohibit wet methods.
Diamond blade wet cutting dominates specification for professional applications. Dry cutting retains niche positioning in cold-climate geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German procurement channels where full-service municipal contracts command premiums, while United States fleet operators absorb Tier 4 Final compliance costs through standardized highway contractor purchasing. This asymmetry shapes regional platform preferences and service attachment rates.
United States
Federal highway appropriations and state-level concrete runway refurbishment programs in Texas and Florida sustain gas-powered fleet renewal cycles. EPA Tier 4 Final standards impose after-treatment hardware costs that erode margins on compact combustion units. California Air Resources Board amendments extend retrofit requirements to older equipment in the Los Angeles-Long Beach industrial corridor.
Germany
Municipal infrastructure agencies in Bavaria and North Rhine-Westphalia negotiate consolidated procurement of gas-powered and hydraulic units for asphalt rehabilitation. EU F-Gas Regulation phase-down schedules constrain hydraulic fluid supply chains for specialized refrigerant-dependent systems. Stuttgart's construction equipment cluster hosts factory-authorized service centers capturing aftermarket revenue from fragmented dealer networks.
Netherlands
Indoor concrete specialists in Randstad metropolitan areas specify brushless electric configurations to satisfy strict noise ordinances and emissions restrictions. CE marking requirements for new electric platform introductions extend product launch windows for manufacturers. Eindhoven's industrial machinery ecosystem supports battery pack integration for mid-duty cutting applications.
China
Infrastructure investment in Yangtze River Delta and Pearl River Delta regions drives demand for diamond blade wet cutting systems in commercial construction. National standards under MIIT govern equipment safety certifications for domestic market access. Shanghai's manufacturing base supplies abrasive blade technologies for price-sensitive dry cutting applications.
Japan
Precision cutting requirements in dense urban construction zones favor compact handheld units for utility trenching and confined-space operations. METI industrial standards shape equipment efficiency benchmarks for professional-grade machinery. Osaka-Kobe manufacturing clusters produce carbide-tipped steel discs serving lower-cost dry cutting segments across Asia-Pacific markets.
Floor Saw Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying blade matrices and motor controllers to branded assemblers. The vendor base organizes around three strategic archetypes: captive rental networks bundling equipment with aftermarket service, direct-to-contractor sales organizations reducing customer capital outlay through subscription models, and cordless ecosystem builders extending battery platforms across multi-tool construction fleets. Dominant competitive moves include factory-authorized service center consolidation to capture maintenance revenue, and geographic expansion through regional dealer acquisition to secure municipal procurement channels.
Within the integrated platform tier, Husqvarna AB and Hilti Corporation exemplify divergent route-to-market strategies. Husqvarna anchors its position through captive rental infrastructure and parts distribution serving municipal fleet operators. Hilti occupies a position in direct contractor engagement through tool fleet management subscriptions that convert capital expenditure to operational budgets. Makita Corporation sits within the cordless ecosystem archetype, leveraging battery platform compatibility to penetrate lighter-duty concrete cutting segments.
| Leading Market Players |
|---|
| Husqvarna AB |
| Hilti Corporation |
| STIHL |
| Makita Corporation |
| Fairport Construction Equipment Ltd |
| Wacker Neuson |
| Tyrolit |
| Diamond Products |
| Chicago Pneumatic |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation phase-down schedules for hydraulic refrigerant-dependent systems determine both the premium spread between electric and gas-powered platforms and the geographic reshaping of component sourcing. Municipal procurement in Germany absorbs configured-to-order pricing for full-service contracts, while standard unit transactions dominate United States highway contractor fleets.
Pricing Analysis
The customization-premium spread separates configured-to-order municipal bundles from standard walk-behind unit transactions. Three-tier pricing structure across premium, standard, and economy levels reflects blade matrix quality, CE marking certification tier, and after-sales service attachment. Cost compression in compact gas-powered segments is intensifying because EPA Tier 4 Final after-treatment hardware erodes manufacturer margins. DIY enthusiasts exhibit highest price sensitivity; German municipal agencies demonstrate lowest sensitivity due to budget cycle insulation.
Supply Chain Analysis
Contract manufacturing concentration for brushless motor controllers sits with industrial electronics specialists in Germany, China, and Japan. Diamond grit supply draws from synthetic production facilities in China and Russia; lithium-ion cell chemistry sources from South Korea and Japan. Single-source vulnerability runs through specialized refrigerant formulations constrained by EU F-Gas quotas. Distribution runs through factory-authorized service centers capturing aftermarket revenue from fragmented regional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a switching-cost fortress. Regulatory entrenchment around OSHA silica compliance and EPA Tier 4 Final certification creates sticky customer relationships that resist displacement.
For Market Incumbents: Build captive aftermarket infrastructure as the defensive moat. Deepen blade matrix backward integration to secure diamond grit supply against sourcing friction. Expand factory-authorized service center density in Texas and Florida to preempt municipal procurement consolidation. Battery energy density limits threaten electric platform margins; anchor gas-powered fleet standardization before substitution accelerates. For New Entrants and Emerging Players: Establish a beachhead in cordless platform compatibility for lighter-duty concrete cutting segments. Target landscaping services and hardscape installation crews where duty cycles remain below commercial construction thresholds. Penetrate through battery ecosystem partnerships that reduce customer capital outlay versus traditional ownership models. CE marking timeline compression favors agile product development cycles over incumbent certification queues. For Investors and Strategic Acquirers: EPA Tier 4 Final enforcement milestones reshape the acquisition landscape toward electric platform specialists with certified wet-cutting portfolios. Long-term viability centers on equipment-as-a-service revenue streams that convert capital expenditure to operational budgets. Acquire regional dealers with consolidated municipal contracts in Germany and the Netherlands. Monitor California Air Resources Board amendments as the signal indicating accelerated retrofit demand and stranded gas-powered asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Factory-Authorized Service Center Expansion | Captures aftermarket parts revenue from municipal fleet operators in Stuttgart's industrial corridor. |
| Battery Platform Ecosystem Extension | Opens lighter-duty concrete segments to multi-tool construction fleets through cordless compatibility. |
| Backward Integration into Diamond Matrix Production | Secures blade supply against synthetic grit sourcing friction from concentrated producers. |
| Full-Service Contract Bundling | Converts German municipal procurement toward usage-based equipment access with maintenance inclusion. |
| CE Marking Fast-Track Certification | Compresses product launch windows for electric platforms targeting Netherlands noise ordinances. |
Methodological Framework
A spread of perspectives from municipal fleet managers, highway contractor procurement leads, aftermarket service directors, and diamond blade manufacturing engineers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through equipment registration databases, customs trade records for diamond grit imports, and SEC filings from listed machinery manufacturers. Bottom-up unit economics triangulated against top-down infrastructure spending appropriations.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include powertrain configuration, material application hardness, end-user procurement modality, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and fleet standardization initiative tracking. Industry-specific forecast inputs incorporated OSHA silica enforcement intensity and EU F-Gas phase-down schedule adherence.
Stress conditions across battery energy density improvement trajectories, hydraulic refrigerant supply disruptions, and municipal budget cycle compressions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about infrastructure appropriation continuity and regulatory enforcement persistence. Quarterly review of CARB amendment adoption rates and CE marking approval velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Wire Cutters Market
Tools
Bandsaw Machines Market
Tools
Cordless Power Drill Market
Tools
Diamond Core Drilling Market
Tools
Cordless Wood Planer Market
Tools
Drill Bit Market
Tools
Post Drivers Market
Tools
Entrenching Tool Market
Tools
Cold and Hot Tool Steel Market
Tools
Land Survey Equipment Market
Tools
Wood-Burning Tool Market
Tools
Mechanical Springs Market
Tools
Horizontal Milling Machine Market
Tools
Riveting Tools Market
Tools
Reamer Market
Tools
Theodolite Market