
 UAE Facade Market | 2026-2036
UAE Facade Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Facade Market Analytics
Specification channels between architects, developers, and specialty contractors is reconfiguring as mega-project procurement centralizes through design-build consortia. Permasteelisa leverages its vertical integration across engineering, manufacturing, and installation to capture bundled contracts on signature towers. Schüco Middle East anchors its position through localized extrusion capabilities and technical service proximity to Dubai's consultant corridor. Emirates Glass LLC differentiates via tempering and coating specialization that aligns with the UAE's stringent solar heat gain requirements.
A facade constitutes the exterior envelope system of a building, comprising curtain walls, cladding panels, and glazing assemblies engineered to manage thermal insulation, air infiltration, structural wind loads, and aesthetic expression while spanning 2.5 to 4.5 meters per floor height in typical high-rise configurations. Glass facade systems dominate commercial tower specifications due to their daylighting optimization and prestige signaling, yet metal cladding gains traction in institutional projects seeking lower embodied carbon profiles. Modular installation approaches represent the fastest-expanding category as labor cost pressures and site logistics constraints push fabrication offsite. Composite materials command premium positioning in finish-sensitive developments where natural stone aesthetics must meet weight restrictions.
MOHAP oversees construction product conformity assessment, while the UAE's civil defense authorities enforce fire resistance ratings that directly determine aluminum composite panel specifications and insulation core selections. The Emirates Green Building Council's technical guidelines and Dubai Municipality's green building regulations are tightening operational energy thresholds, forcing envelope U-value improvements that cascade into glazing specification upgrades. Stakeholders must monitor how evolving embodied carbon accounting rules reshape material sourcing decisions between regional aluminum smelters and imported systems.
Market Dynamics
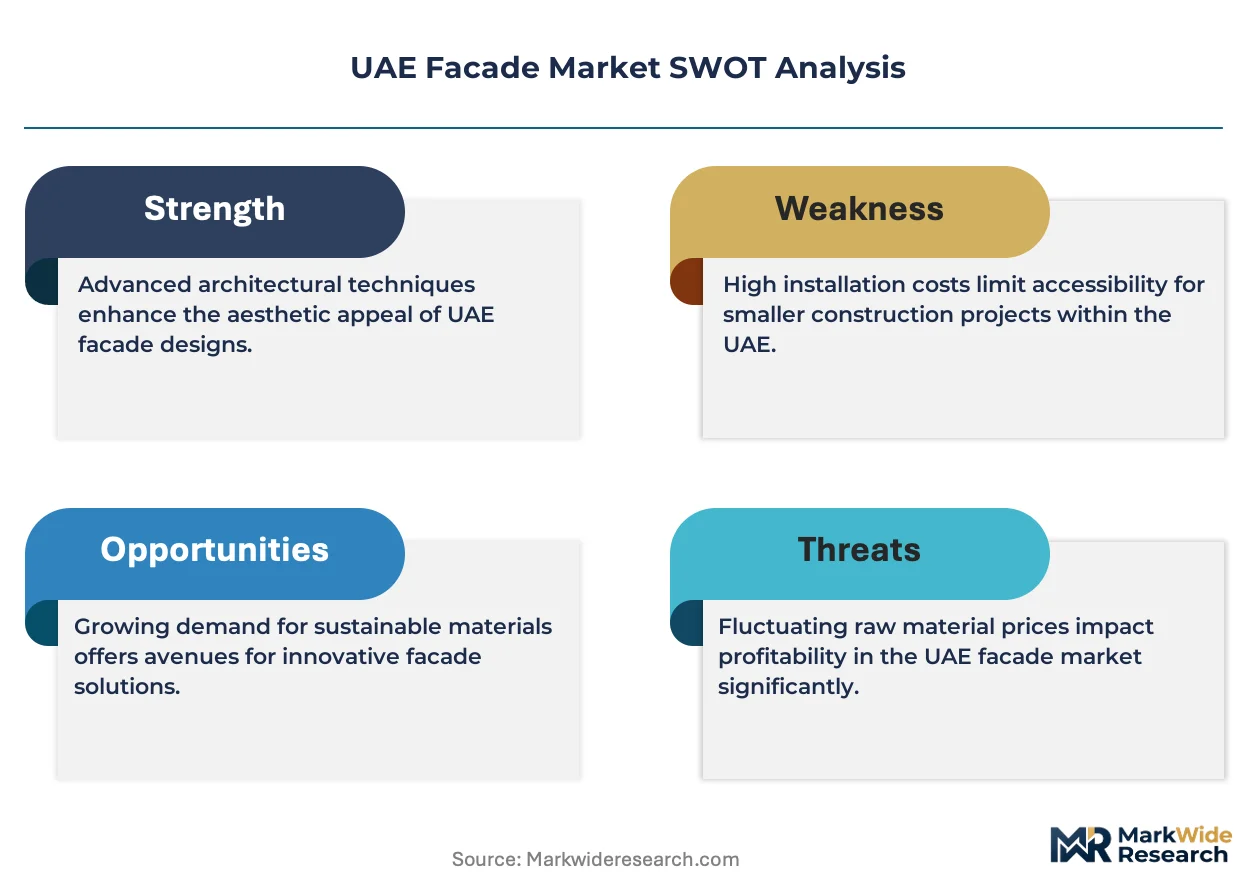
Mandatory green building codes under Al Sa'fat regulations are compressing specification timelines as developers scramble to meet thermal performance thresholds before permit deadlines, forcing envelope consultants into earlier design-phase involvement.
Growth Catalysts
- Al Sa'fat Green Building Regulations:Dubai Municipality's escalating energy efficiency mandates are accelerating replacement cycles for non-compliant curtain wall systems in existing commercial stock.
- Super-tall construction clusters:Saadiyat Island and Dubai Design District developments are concentrating procurement volumes that justify dedicated fabrication facilities and specialized installation crews.
- Photovoltaic glazing integration:Building-integrated photovoltaics are capturing specification share as developers seek to offset operational carbon under Emirates Green Building Council guidelines.
Market Restraints
- Aluminum ingot price volatility:Regional smelter output fluctuations in the GCC are transmitting cost instability into extrusion and curtain wall system pricing.
- Specialized installation labor scarcity:Certified facade installation technicians are concentrating among a handful of Dubai-based specialty contractors, creating bottleneck risk during peak construction phases.
- Fire resistance rating escalation:UAE civil defense authorities are tightening aluminum composite panel core specifications, disqualifying legacy material inventories and forcing premature system redesigns.
Strategic Opportunities
- Abu Dhabi healthcare infrastructure:Hospital and medical city developments are specifying infection-control-optimized facade systems with enhanced air-sealing and pressure-management capabilities.
- Retrofit envelope upgrades:Existing commercial towers built before 2010 Al Sa'fat implementation are creating recurring revenue streams for recladding and glazing replacement specialists.
- Modular offsite fabrication:Factory-based panel assembly is compressing site installation schedules and reducing labor exposure to extreme summer temperatures.
Industry Challenges
- Facade engineering talent pipeline:Building physics modeling and thermal bridge analysis expertise is concentrating among senior consultants approaching retirement age.
- Multi-party warranty coordination:System performance guarantees spanning glass suppliers, aluminum extruders, sealant manufacturers, and installation contractors are creating liability fragmentation.
- Embodied carbon accounting readiness:Project teams lack standardized methodologies to document cradle-to-gate emissions for envelope materials under emerging procurement requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Facade Market |
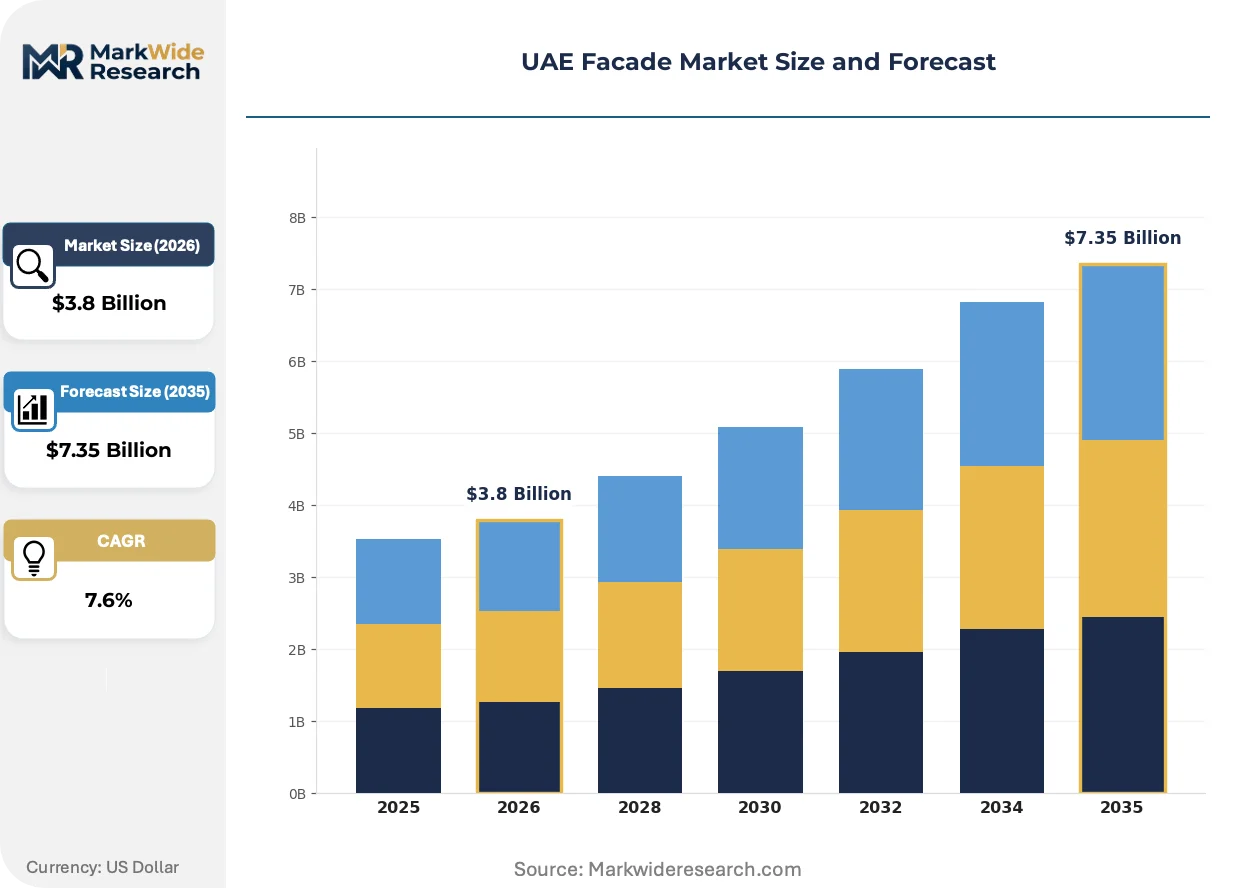
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass, Metal, Wood, Composite Installation Type: New Construction, Renovation, Retrofit, Modular Building Type: Residential, Commercial, Institutional, Industrial Finish Type: Coated, Natural, Laminated, Textured |
| Companies Covered | Permasteelisa, Schüco Middle East, Emirates Glass LLC, Fibrex Construction Group, Bouygues SA, Al Abbar Group (Arabian Aluminium), Lindner Group, Seele Middle East FZE, ALICO (Aluminium & Light Industries Co.), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Facade Market Evolving Landscape
Computational design tools and performance simulation software are compressing the iteration cycle between architect intent and constructible envelope solutions. Three developments are restructuring how facade systems are specified, fabricated, and deployed across the Emirates.
Building information modeling combined with parametric design algorithms is digitizing the interface between architectural geometry and structural engineering validation. Dubai-based design consultants are adopting these workflows for complex tower geometries that would exceed manual calculation timelines. This digitizing of the design-to-fabrication pipeline is collapsing the traditional sequential handoff between architect, engineer, and contractor into concurrent model-based collaboration.
Dubai Municipality's progressive tightening of envelope U-value maximums under Al Sa'fat is forcing triple-glazing and warm-edge spacer specifications that were previously confined to European markets. The industrial consequence is a supply chain scramble for qualified insulating glass unit fabricators capable of meeting argon fill and edge seal longevity requirements. High-rise residential towers in the Marina district are experiencing the most acute specification pressure, with developers substituting European system suppliers for regional alternatives to secure performance documentation.
Design-build consortia are consolidating procurement authority that previously fragmented across separate architect, engineer, and contractor contracts. Signature tower developments in the Design District are now awarding bundled envelope packages to single entities responsible for performance guarantees. This concentration of buyer power is most visible in Dubai's super-tall segment, where developers trade design flexibility for schedule certainty and single-point accountability.
UAE Facade Market Segmentation
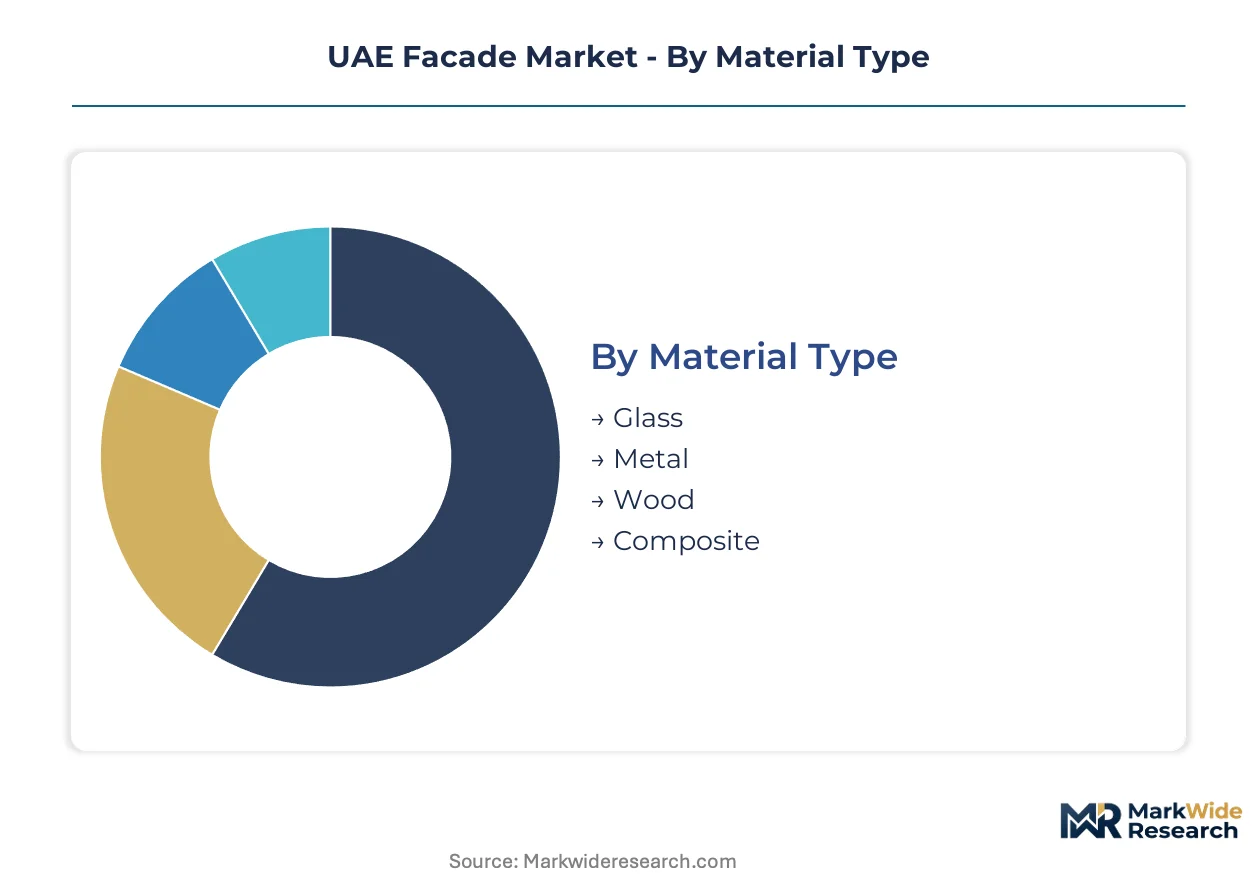
UAE facade procurement splits across four distinct category axes, each reshaping how envelope systems are specified, fabricated, and installed across Dubai and Abu Dhabi's development corridors. Material selection and installation methodology now dominate early-phase design decisions as Al Sa'fat compliance compresses project timelines.
Material Type:
Mature specifications dominate high-rise commercial stock, while emerging alternatives gain traction under embodied carbon pressures and thermal performance mandates.
- Glass:Insulating glass units with low-emissivity coatings and argon fill now anchor super-tall tower specifications across Saadiyat Island and Dubai Marina. Dubai Municipality's escalating U-value maximums under Al Sa'fat are disqualifying single-pane legacy systems and forcing triple-glazing adoption in premium residential developments.
- Metal:Aluminum curtain wall systems with thermally broken frames concentrate procurement volumes in commercial office towers, yet regional smelter output fluctuations in the GCC are transmitting cost instability into extrusion pricing and specification decisions.
- Wood:Engineered timber facades occupy niche positioning in low-rise hospitality and wellness developments where biophilic design priorities override fire resistance constraints.
- Composite:Aluminum composite panels with mineral core fire ratings are displacing polyethylene-cored legacy inventory following UAE civil defense authority tightening.
Glass handles the majority of throughput across high-rise commercial and residential towers; Composite is climbing the fastest as fire code compliance forces system redesigns.
Installation Type:
Cost tier stratification separates site-intensive traditional methods from capital-intensive offsite approaches that trade upfront investment for schedule compression.
- New Construction:Stick-built curtain wall installation retains dominance in bespoke super-tall projects where architectural geometry exceeds standardized panel dimensions. Design-build consortia in Dubai's Design District are bundling engineering, fabrication, and installation under single-performance guarantees.
- Renovation:Partial envelope replacement targets aging commercial stock built before Al Sa'fat implementation, with recladding specialists capturing recurring revenue from towers requiring thermal performance upgrades to maintain occupancy permits.
- Retrofit:Over-cladding systems with integrated insulation are gaining specification share in existing residential towers where full curtain wall replacement proves structurally or economically prohibitive.
- Modular:Factory-assembled unitized panels are compressing site installation schedules and reducing labor exposure to extreme summer temperatures, though specialized fabrication capacity concentrates among a handful of Dubai-based facilities.
New Construction absorbs the largest capital allocation; Modular is expanding most quickly as labor scarcity and site logistics constraints accelerate offsite migration.
Building Type:
Application-driven specification divergence separates prestige-sensitive commercial developments from performance-optimized institutional and industrial envelopes.
- Commercial:High-performance glazing systems dominate office tower specifications where daylighting optimization and brand visibility command premium positioning. Dubai Design District and Business Bay developments are concentrating procurement volumes that justify dedicated technical service teams.
- Residential:High-rise towers in the Marina district are experiencing acute specification pressure as developers substitute European system suppliers for regional alternatives to secure Al Sa'fat performance documentation.
- Institutional:Hospital and medical city developments in Abu Dhabi are specifying infection-control-optimized facade systems with enhanced air-sealing and pressure-management capabilities.
- Industrial:Metal cladding with minimal glazing ratios anchors warehouse and logistics facility specifications where embodied carbon reduction and capital efficiency override aesthetic priorities.
Commercial commands the dominant share of facade expenditure; Institutional is gaining share fastest as healthcare infrastructure investment accelerates across the Emirates.
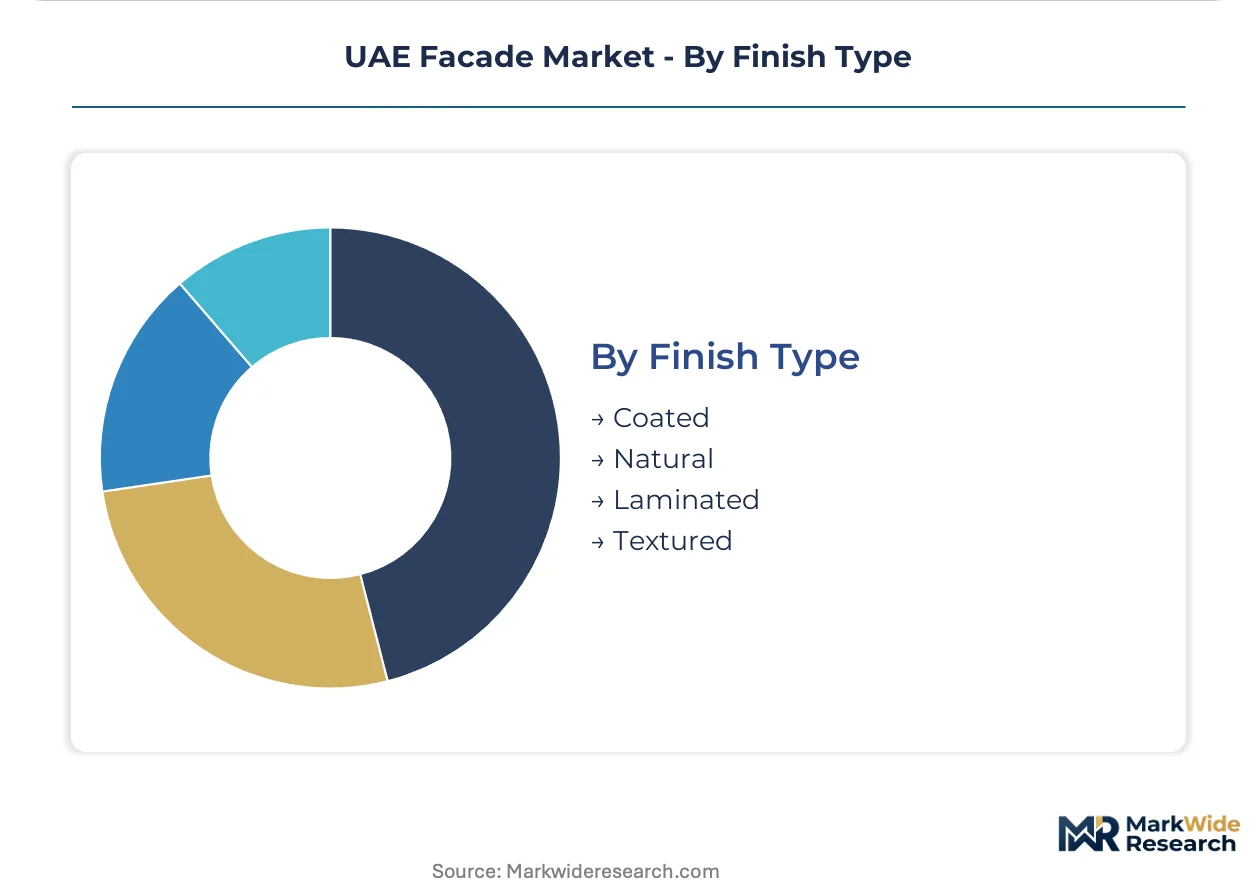
Finish Type:
Margin stratification separates premium coated and laminated specifications from economy natural and textured alternatives in finish-sensitive developments.
- Coated:PVDF and powder-coated aluminum surfaces dominate commercial tower specifications where color consistency and UV degradation resistance justify 20-year performance warranties.
- Natural:Anodized aluminum and untreated metal finishes occupy selective positioning in institutional projects where lifecycle maintenance minimization outweighs initial aesthetic impact.
- Laminated:Safety and acoustic interlayers are capturing specification share in residential towers proximate to transportation corridors and airport flight paths.
- Textured:Mechanical and chemical surface treatments are expanding in hospitality developments where tactile differentiation supports brand identity objectives.
Coated finishes handle the majority of commercial and high-end residential volume; Laminated is expanding most quickly as acoustic performance becomes a mandatory specification criterion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Abu Dhabi commands premium specification pricing for healthcare and institutional facades, while Dubai's volume-driven commercial towers compress margins through design-build bundling. This pricing-power asymmetry concentrates engineering talent in the capital and fabrication capacity in Dubai's industrial zones.
Dubai
Super-tall commercial towers in Business Bay and the Design District anchor procurement volumes for high-performance glazing systems. Dubai Municipality's Al Sa'fat regulations are disqualifying single-pane legacy systems and forcing triple-glazing adoption in premium residential developments. The Jebel Ali corridor concentrates modular fabrication facilities serving design-build consortia.
Abu Dhabi
Hospital and medical city developments on Saadiyat Island and Yas Island are specifying infection-control-optimized facade systems with enhanced air-sealing capabilities. MOHAP oversees construction product conformity assessment for healthcare envelope materials. The capital's procurement centralization through sovereign wealth-backed developers creates bundled contract opportunities.
Sharjah
Mid-rise residential and educational institutional projects are driving demand for cost-optimized metal cladding systems. The emirate's civil defense authorities enforce fire resistance ratings that determine aluminum composite panel core specifications. Industrial zones near Sharjah International Airport are attracting secondary fabrication facilities serving Northern Emirates projects.
Northern Emirates
Ras Al Khaimah and Fujairah hospitality developments are specifying composite material finishes where natural stone aesthetics must meet seismic weight restrictions. Federal-level green building guidelines are beginning to compress specification timelines for new resort construction. Port-adjacent logistics facilities are reducing material inbound costs for remote project sites.
UAE Facade Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in glazing and extrusion. The vendor base concentrates among European-origin system houses with regional manufacturing presence and Gulf-based fabricators with installation scale. Three archetypes dominate: vertically integrated design-build consortia, regional extrusion specialists with technical service proximity, and glass processors with tempering and coating capabilities. Competitive moves center on capacity expansion in modular fabrication and strategic partnerships to secure performance documentation for Al Sa'fat compliance.
Among European-origin platform integrators, Permasteelisa and Schüco Middle East exemplify the design-build bundling archetype that captures signature tower contracts through single-point accountability. Emirates Glass LLC anchors the component-specialist tier with tempering and coating capabilities aligned to the UAE's stringent solar heat gain requirements. These three companies represent the spectrum from system integration to materials specialization that defines procurement channel structure.
| Leading Market Players |
|---|
| Permasteelisa |
| Schüco Middle East |
| Emirates Glass LLC |
| Fibrex Construction Group |
| Bouygues SA |
| Al Abbar Group (Arabian Aluminium) |
| Lindner Group |
| Seele Middle East FZE |
| ALICO (Aluminium & Light Industries Co.) |
| Others |
Value Network & Pricing Analysis
Overcapacity in GCC aluminum smelting is compressing extrusion margins while concentrating procurement leverage among Dubai-based design-build consortia. This utilization dynamic forces regional fabricators into price-competitive bidding for bundled envelope contracts, even as Al Sa'fat compliance costs escalate specification complexity.
Pricing Analysis
Configured-to-order glazing systems command spreads of 40-60% above standard curtain wall unit pricing, reflecting engineering customization and performance documentation burdens. Pricing stratifies across premium, standard, and economy tiers, with differentiation anchored in thermal certification grade and installation methodology. Cost compression in the metal cladding segment is intensifying because GCC smelter output fluctuations transmit volatility into aluminum ingot pricing. Developer-led consortia exhibit lowest price sensitivity, while mid-rise residential contractors in Sharjah face acute budget constraints.
Supply Chain Analysis
Contract manufacturing concentration among Jebel Ali-based modular fabrication facilities and European-origin system houses with regional extrusion partnerships defines supply-side structure. Geographic supply draws from UAE domestic facilities, Italian and German engineering hubs, and Chinese aluminum component sources. Raw material dependencies center on primary aluminum ingot, low-iron silica sand for glass production, and polyamide thermal break profiles. Single-source vulnerability concentrates in qualified insulating glass unit fabricators capable of argon fill and warm-edge spacer specifications. Distribution runs through design-build consortia that bundle engineering, fabrication, and installation under single-performance guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facade engineering expertise constitutes a defendable moat against substitution by standardized building envelope systems. Incumbents must navigate the threat of modular offsite fabrication commoditizing traditional stick-built installation margins.
For Market Incumbents: Harden technical service proximity to Dubai's consultant corridor through embedded facade engineering teams and thermal bridge analysis capabilities. Deepen backward integration into tempering and coating operations to secure Al Sa'fat performance documentation without third-party dependency. Defensive moves must address the emerging threat of European system suppliers capturing specification share in premium residential towers.
For New Entrants and Emerging Players: Northern Emirates hospitality developments present geographic underpenetration with lower competitive density than Dubai's super-tall corridor. Target Ras Al Khaimah and Fujairah resort construction where seismic weight restrictions favor composite material expertise over legacy curtain wall systems. White-space entry should emphasize infection-control-optimized facade systems for Abu Dhabi's healthcare infrastructure, leveraging MOHAP conformity assessment pathways as differentiation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across modular fabrication as factory-assembled unitized panels displace site-intensive installation. Long-term viability favors platform integrators with captive engineering and installation scale over pure-play component suppliers. Acquisition targets should exhibit bundled contract capabilities and Al Sa'fat compliance documentation. Monitor aluminum ingot price volatility and civil defense authority fire rating escalations as inflection indicators for margin compression events.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fabrication Capacity Expansion | Jebel Ali facilities compress site schedules and reduce summer labor exposure. |
| Backward Integration into Tempering Operations | Emirates Glass LLC model secures solar heat gain compliance without external dependency. |
| Healthcare Specialization Certification | MOHAP conformity assessment opens Abu Dhabi medical city procurement channels. |
| Design-Build Consortium Formation | Single-point accountability captures signature tower contracts in Dubai Design District. |
| European System Supplier Partnership | Regional extrusion licensing addresses Al Sa'fat documentation gaps in premium residential. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with facade engineering consultants, design-build consortium procurement directors, and MOHAP regulatory compliance officers; and secondary validation through Dubai Municipality building permit databases, Emirates Green Building Council technical guidelines, and GCC aluminum trade flow records. Bottom-up project pipeline aggregation triangulated against top-down envelope expenditure estimates across commercial, residential, and institutional building stock.
Forecast inputs encompassed material type substitution elasticities, Al Sa'fat regulatory phase-in timelines, and super-tall construction cluster development schedules across the analysis window. Segmentation modeling addressed material type, installation methodology, building application, and finish specification dimensions. CAGRs derived from volume-weighted average growth across these segments, incorporating aluminum price cycle assumptions and labor scarcity constraints specific to certified facade installation technicians.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by European system suppliers or accelerated modular fabrication adoption by regional entrants would shift outcomes. Quarterly review of Dubai Municipality permit issuance velocity, GCC smelter output fluctuations, and civil defense authority fire rating bulletins is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Middle East & Africa Infrastructure Construction Market
Building Construction
China Building Construction Market
Building Construction
Asia Pacific Modular Construction Market
Building Construction
Scandinavia Construction Market
Building Construction
Europe Modular Construction Market
Building Construction
GCC Green Buildings Market
Building Construction
China Modular Construction Market
Building Construction
Australia Construction Market
Building Construction
Egypt Residential Construction Market
Building Construction
United States Commercial Construction Market
Building Construction
India Construction Market
Building Construction
Indonesia Prefabricated Buildings Market
Building Construction
US Modular Construction Market
Building Construction
Japan Prefabricated Buildings Market
Building Construction
Energy-Efficient Building Market
Building Construction
GCC Advanced Buildings Materials Market