
 Floor Scraper Market | 2026-2036
Floor Scraper Market Size, Share, and Industry Trends Forecast 2026-2036
Floor Scraper Market Analytics
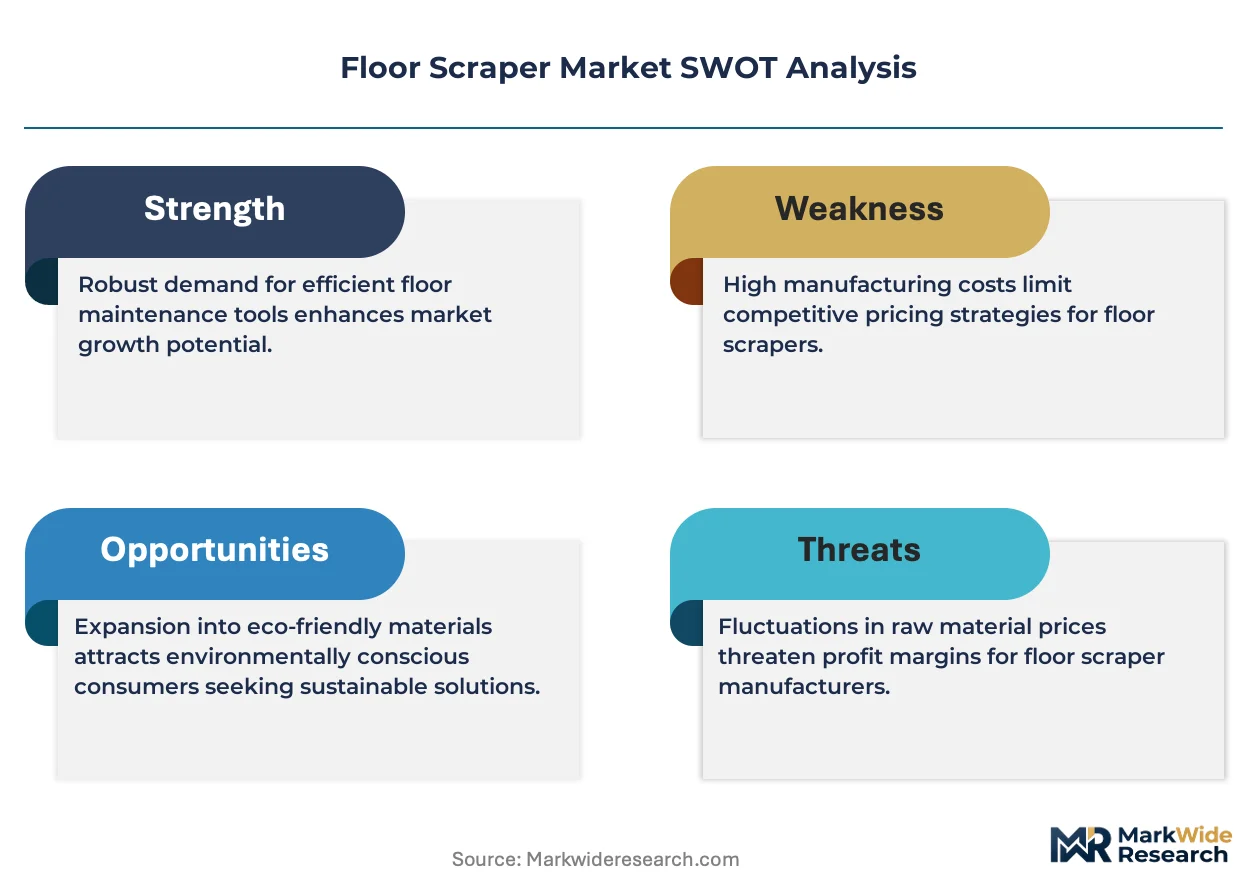
OSHA's Respirable Crystalline Silica Standard is rebalancing the cost-of-entry calculus for surface preparation contractors by mandating enhanced dust collection and worker protection systems. National Flooring Equipment leverages its engineering depth to sustain premium positioning in ride-on scraper categories. EDCO anchors its competitive stance through specialized propane and electric walk-behind units for rental channels. Blastrac differentiates via integrated shot blasting and scraping systems that control silica generation at the source.
Floor scrapers are powered surface preparation machines engineered to remove resilient flooring, adhesives, and coatings from concrete and wood substrates, typically operating at blade widths from eight to thirty-six inches and delivering impact forces measured in foot-pounds per minute. Electric scrapers dominate commercial contractor fleets where consistent power access and lower operating costs offset mobility constraints, while battery-powered scrapers represent the fastest-expanding technology segment as lithium-ion energy density improvements enable cord-free operation across full work shifts. Manual scrapers retain share in restoration projects and tight-access residential environments where precision outweighs productivity metrics.
FCC equipment authorization governs radio-enabled fleet management attachments, OSHA's silica standard dictates ventilation and PPE bundling, and EPA emissions regulations constrain engine specifications for propane and gasoline-powered units. Compliance with this regulatory triad shapes procurement criteria for industrial facilities and maintenance providers, particularly those serving government and healthcare contracts. Stakeholders must evaluate whether battery platform standardization or engine emission upgrades offer the more durable competitive moat as enforcement intensity escalates across jurisdictions.
Market Dynamics
OSHA's silica exposure standard is compressing replacement cycles for surface preparation equipment as contractors face mandatory dust containment upgrades. Equipment fleets aged beyond seven years now trigger compliance penalties that exceed replacement capital outlay.
Growth Catalysts
- Healthcare Infrastructure Refurbishment:Aging hospital and clinic flooring systems in the United States require adhesive removal and substrate preparation for infection-control surfaces. Specialized scraper configurations with HEPA containment address Joint Commission facility standards.
- Battery Energy Density Gains:Lithium-ion cell improvements enable cordless scrapers to match corded runtime across full eight-hour shifts. Commercial contractors in power-constrained renovation sites adopt these platforms to eliminate generator fuel costs and trip hazards.
- REACH Chemical Restrictions:European adhesive formulation changes are shortening flooring bond lifecycles, accelerating removal frequency. Surface preparation contractors face expanded project pipelines as substrate replacement outpaces new construction.
Market Restraints
- Steel Alloy Price Volatility:Blade and chassis fabrication depends on specialty high-carbon steel grades subject to scrap metal commodity swings. Chinese export quota adjustments transmit directly to OEM cost structures.
- Propane Engine Certification Backlogs:EPA Tier 4 Final compliance timelines for small off-road engines extend product development cycles. Propane-powered walk-behind units face eighteen-month homologation delays that freeze rental fleet refresh schedules.
- Manual Scraper Substitution:Precision restoration in historic buildings and residential tight-access zones retains manual blade methods. Motorized units cannot displace hand tools where substrate preservation outweighs productivity metrics.
Strategic Opportunities
- India Commercial Real Estate Expansion:Shopping mall and office stock in Mumbai and Bangalore requires Western-standard flooring maintenance protocols. Local contractors lack equipment depth, creating import channel openings for mid-size electric scrapers.
- Rental Channel Digitization:IoT-enabled fleet tracking attachments transform equipment utilization transparency. United Rentals and regional independents pilot telematics bundling to optimize blade-wear scheduling and reduce unplanned downtime.
- IRA Clean Energy Tax Credits:Battery-powered equipment qualifies for commercial clean vehicle incentives in federal contracting zones. Government facility maintenance providers face procurement preference mandates favoring zero-emission surface preparation.
Industry Challenges
- Silica Competency Certification:OSHA's competent person requirements mandate specialized training for dust exposure assessment. Contractor labor pools lack certified technicians, constraining fleet deployment velocity during peak renovation seasons.
- Legacy Equipment Integration:Existing propane and gasoline scraper fleets require retrofit dust collection attachments to achieve compliance. Aftermarket engineering complexity fragments warranty coverage and elevates total cost of ownership calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor Scraper Market |
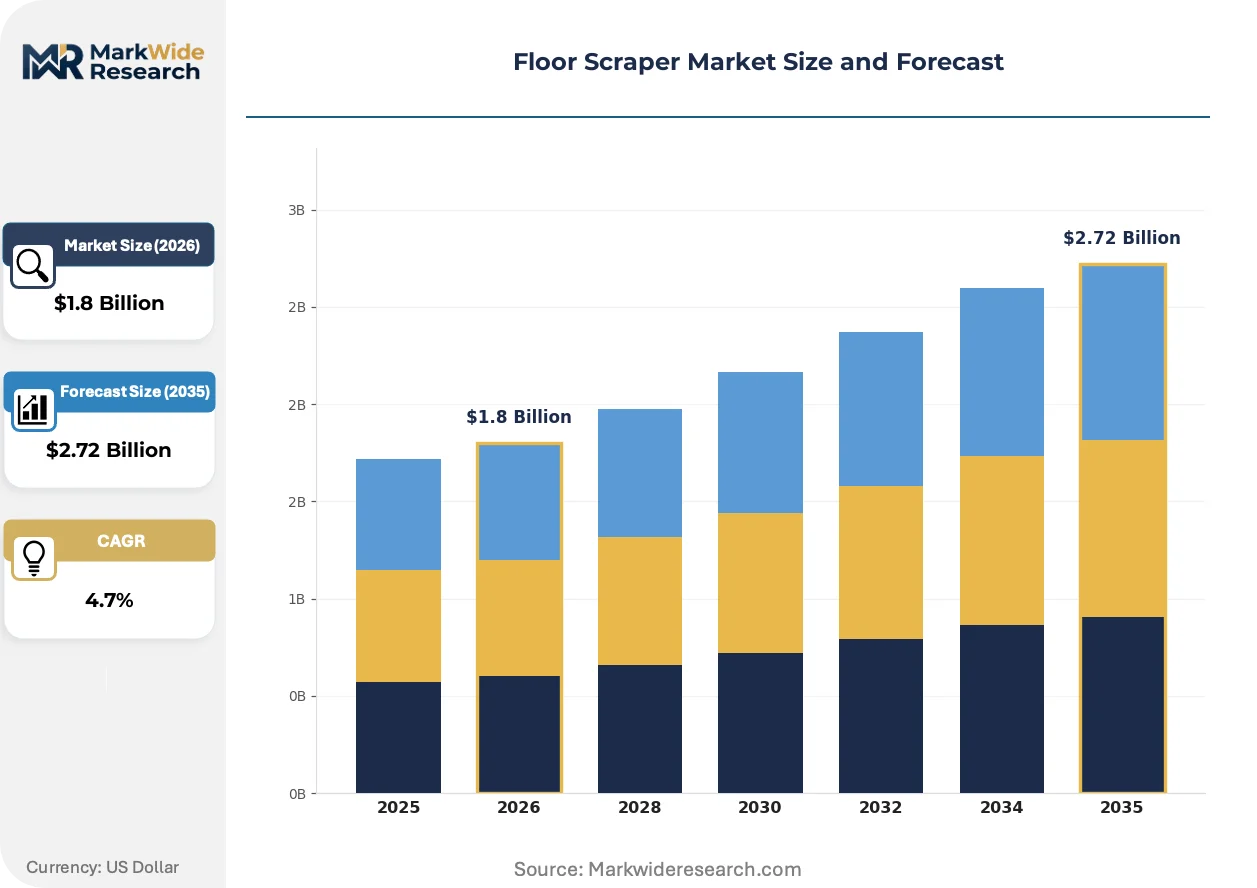
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Scrapers, Electric Scrapers, Battery-Powered Scrapers, Pneumatic Scrapers End User: Contractors, Homeowners, Industrial Facilities, Maintenance Providers Application: Residential Flooring, Commercial Flooring, Industrial Flooring, Restoration Projects Technology: Hydraulic Technology, Mechanical Systems, Cordless Designs, Ergonomic Designs |
| Companies Covered | National Flooring Equipment, General Equipment Company, EDCO, Blastrac, Blast It All Mfg, Janser, Bartell Global, ROLL GmbH, MK Diamond, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor Scraper Market Evolving Landscape
Equipment intelligence and emissions compliance are converging to redefine competitive positioning in surface preparation. Vendors now engineer for regulatory endurance rather than raw performance metrics.
Autonomous guidance systems are integrating machine vision and proximity sensors to enable semi-automated floor stripping in warehouse and retail environments. Third-party logistics operators with standardized concrete slab configurations pilot these units to reduce labor dependency in overnight maintenance windows. The technology is integrating route optimization algorithms that compress square-footage completion rates while maintaining OSHA-mandated dust perimeter controls.
EPA small off-road engine emission standards are forcing propane powertrain redesigns with closed-loop fuel injection and catalytic aftertreatment. Engine block thermal management requirements add chassis weight that compromises maneuverability in walk-behind form factors. Rental channel procurement committees in California and Texas now exclude non-certified equipment from qualified supplier lists, accelerating fleet turnover.
Equipment-as-a-service contracting is displacing capital purchase models among multi-site retail chains and healthcare systems. National flooring maintenance providers bundle scraper deployment with blade consumption and dust disposal under unit-rate pricing. This arrangement concentrates most visibly in the United States where property management firms seek to transfer compliance liability to specialized contractors.
Floor Scraper Market Segmentation
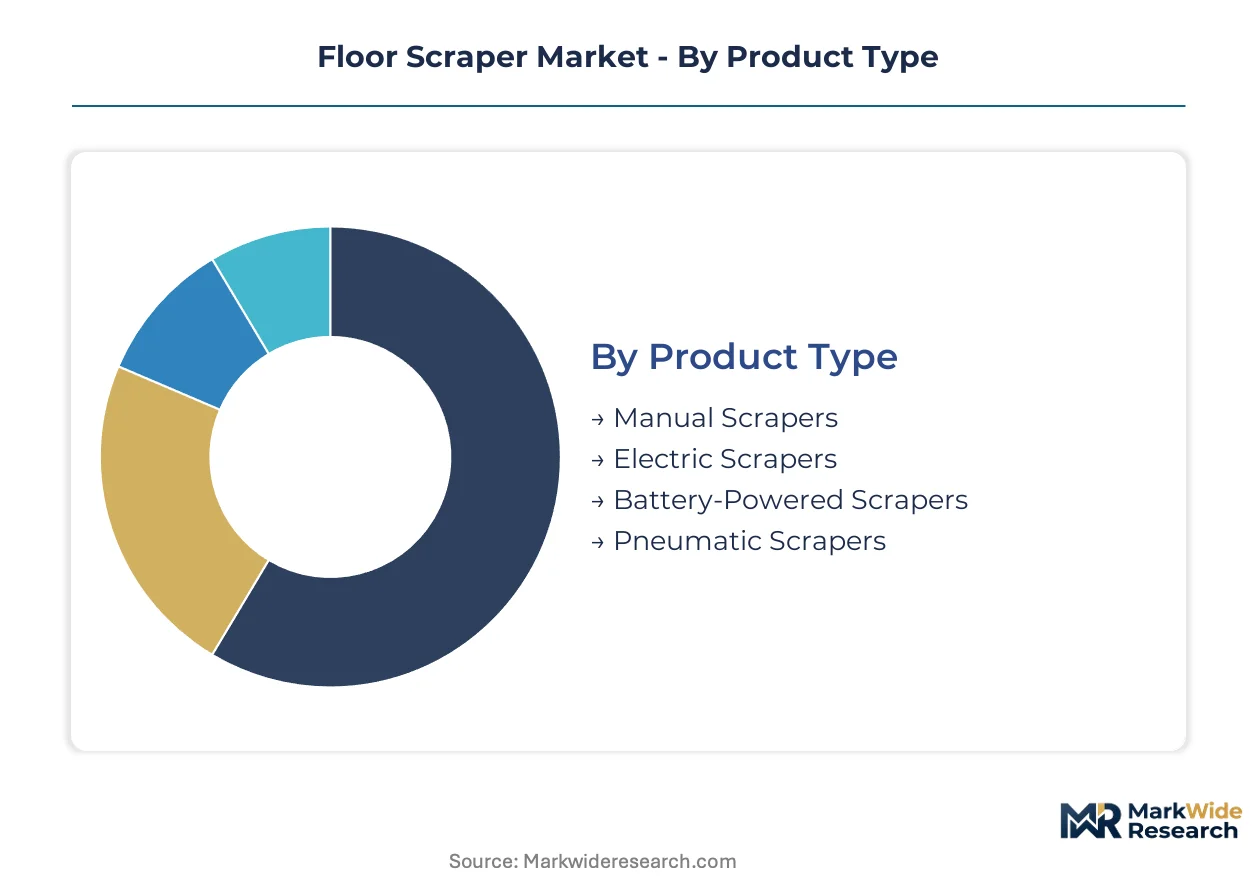
Floor scraper segmentation reveals distinct capital requirements across powertrain technologies and end-use applications. Procurement patterns diverge sharply between rental fleet operators seeking durability and contractors prioritizing silica compliance.
Product Type:
Capital intensity peaks with battery-powered platforms requiring lithium-ion cell integration and thermal management systems, while manual tools demand minimal upfront investment.
- Electric Scrapers:Corded units deliver consistent torque through direct grid connection, eliminating battery replacement cycles. Commercial contractors in United States metropolitan markets favor these for hospital and retail refurbishment where OSHA silica containment attachments add capital burden.
- Battery-Powered Scrapers:Lithium-ion energy density improvements now enable full-shift cordless operation. United States government facility contractors leverage IRA clean energy tax credits to offset premium acquisition costs against zero-emission procurement mandates.
- Manual Scrapers:Hand-operated blade systems serve restoration specialists requiring substrate preservation precision.
- Pneumatic Scrapers:Compressed-air units operate in industrial environments with captive compressor infrastructure.
Electric scrapers absorb the bulk of installed capacity; battery-powered scrapers are expanding most quickly.
End User:
Volume concentration aligns with fleet scale, where multi-unit operators achieve blade and attachment economies unavailable to single-machine owners.
- Contractors:Surface preparation specialists maintain diversified equipment portfolios spanning walk-behind and ride-on configurations. OSHA silica competency certification requirements constrain deployment velocity during peak United States renovation seasons.
- Maintenance Providers:National flooring service firms bundle scraper deployment with consumables under equipment-as-a-service contracts. United States retail chains and healthcare systems transfer compliance liability through unit-rate pricing structures.
- Industrial Facilities:In-house maintenance departments prioritize propane and electric units for warehouse and manufacturing floor upkeep.
- Homeowners:Residential users acquire manual or compact electric units for single-project adhesive removal.
Contractors dominate current fleet ownership; maintenance providers are climbing the fastest as outsourcing accelerates.
Application:
Regulatory intensity varies by substrate environment, with healthcare and industrial settings imposing the strictest dust containment protocols.
- Commercial Flooring:Retail and office refurbishment in United States urban centers drives replacement cycles as aging adhesive systems fail. Joint Commission facility standards in healthcare sub-segments mandate HEPA-equipped scraper configurations.
- Industrial Flooring:Warehouse and manufacturing environments demand ride-on scrapers with high blade-width coverage. Third-party logistics operators pilot semi-automated guidance systems to compress overnight maintenance windows.
- Residential Flooring:Single-family and multi-family renovation projects favor compact walk-behind or manual tools.
- Restoration Projects:Historic building preservation requires precision blade control that motorized units cannot replicate.
Commercial flooring commands the largest equipment base; industrial flooring is gaining share fastest through automation adoption.
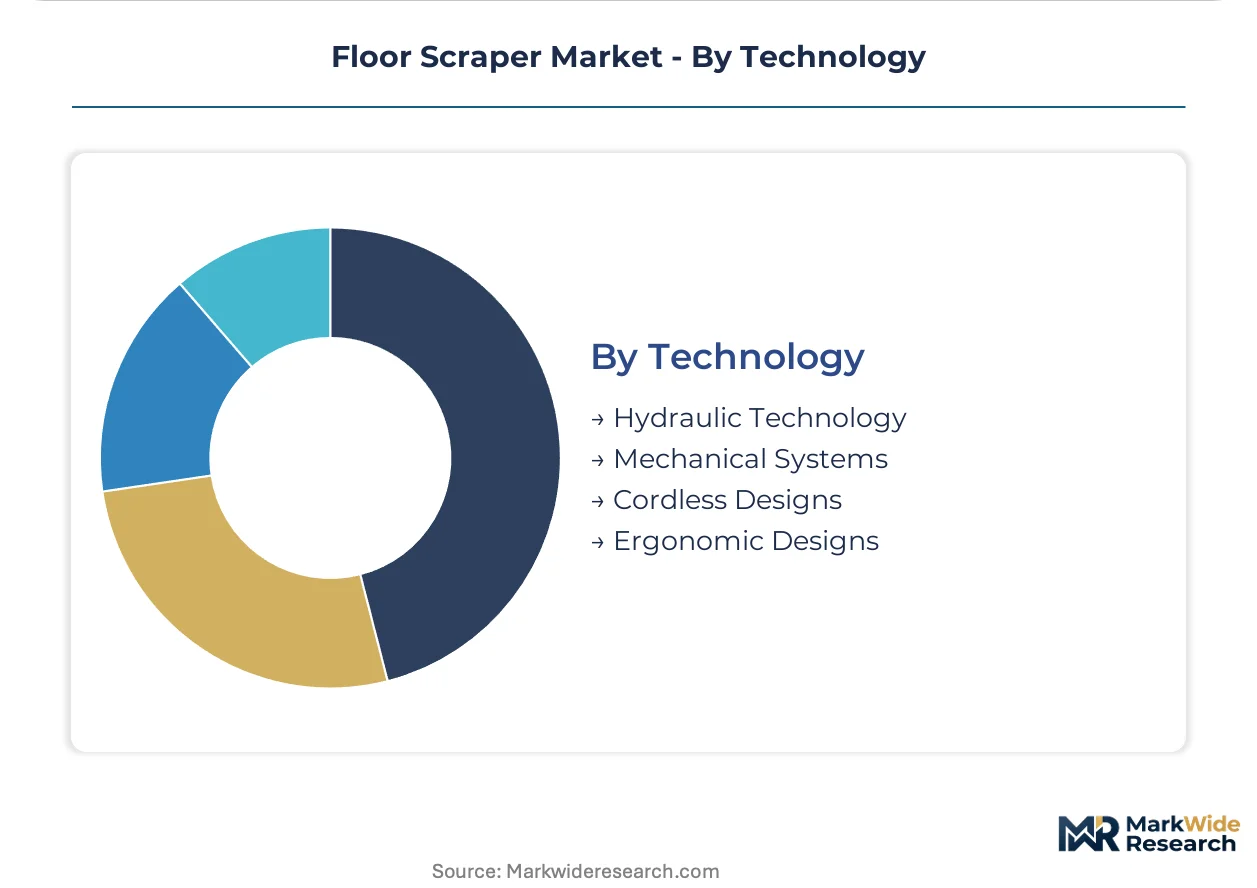
Technology:
Engineering differentiation centers on emissions compliance and operator ergonomics rather than raw performance metrics.
- Hydraulic Technology:Fluid-power systems deliver high-impact force for thick coating removal in industrial applications. EPA Tier 4 Final certification backlogs for small off-road engines extend development cycles for propane-hydraulic hybrid units.
- Cordless Designs:Battery-electric architectures eliminate generator fuel costs and trip hazards in power-constrained renovation sites. FCC equipment authorization governs radio-enabled fleet management attachments for telematics integration.
- Mechanical Systems:Direct-drive configurations minimize maintenance complexity for rental channel operators.
- Ergonomic Designs:Vibration-dampening handles and adjustable blade angles reduce operator fatigue during extended shifts.
Hydraulic technology retains the deepest installed base; cordless designs are expanding most quickly as lithium-ion costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States where aging retail and healthcare infrastructure drives refurbishment spending. Equipment procurement patterns diverge sharply between mature markets with stringent silica compliance and emerging economies building contractor capacity.
United States
Hospital and clinic flooring systems require adhesive removal for infection-control surfaces. OSHA's Respirable Crystalline Silica Standard mandates enhanced dust collection systems that compress replacement cycles. Texas and California rental channels now exclude non-EPA-certified equipment from qualified supplier lists.
Germany
Industrial flooring maintenance in manufacturing corridors sustains walk-behind and ride-on scraper demand. REACH chemical restrictions on adhesive formulations shorten flooring bond lifecycles. The Ruhr industrial cluster sees expanded substrate replacement projects outpacing new construction.
China
Commercial real estate stock in Shanghai and Shenzhen requires Western-standard flooring maintenance protocols. MIIT equipment standards and GB certification requirements shape import substitution dynamics. Yangtze River Delta contractors build equipment depth for shopping mall refurbishment.
India
Mumbai and Bangalore shopping mall expansion creates import channel openings for mid-size electric scrapers. BIS certification requirements and DGFT import regulations govern equipment market access. Maharashtra contractor fleets lack surface preparation equipment depth.
United Kingdom
London commercial property refurbishment accelerates equipment replacement cycles. HSE silica exposure guidance aligns with tightening European dust containment norms. The Southeast England logistics corridor pilots semi-automated guidance systems for overnight warehouse maintenance.
Floor Scraper Market Competitive Landscape
United States producers anchor the premium tier; European specialists hold compliance-engineered positions. The vendor base spans diversified surface preparation conglomerates and single-product fabricators. Three archetypes dominate: engineering-intensive ride-on specialists, rental-channel walk-behind suppliers, and integrated shot-blasting system providers. Competitive moves center on battery platform standardization and silica-containment retrofit engineering.
Within the ride-on engineering tier, National Flooring Equipment exemplifies premium positioning sustained through blade-width coverage and dust-system integration. EDCO anchors the rental-channel archetype with specialized propane and electric walk-behind configurations. Blastrac occupies the integrated-systems position, representing shot-blasting and scraping convergence that controls silica generation at the source.
| Leading Market Players |
|---|
| National Flooring Equipment |
| General Equipment Company |
| EDCO |
| Blastrac |
| Blast It All Mfg |
| Janser |
| Bartell Global |
| ROLL GmbH |
| MK Diamond |
| Others |
Value Network & Pricing Analysis
Rental fleet operators in Texas and California anchor pricing power through qualified supplier list exclusions that penalize non-EPA-certified equipment. Their procurement concentration forces OEMs to absorb certification cost burdens rather than pass through premium pricing.
Pricing Analysis
Short lead-time premiums dominate contractor procurement decisions, with silica-compliant units commanding immediate availability pricing over spot inventory discounts. Three-tier pricing structure across premium, standard, and economy levels separates HEPA-integrated ride-on configurations from basic walk-behind units and manual tool alternatives. Price differentiation hinges on OSHA certification tier and after-sales service bundling. Cost compression in the standard tier is intensifying because Chinese steel alloy export quotas elevate blade fabrication expenses. Maintenance providers show least price sensitivity due to equipment-as-a-service liability transfer, while independent contractors face acute margin pressure.
Supply Chain Analysis
Domestic-content mandates in India and China are reshaping sourcing patterns for mid-size electric scraper assemblies. Manufacturing concentrates in the United States, Germany, and China, with chassis fabrication drawing from specialty high-carbon steel grades sourced from Japanese and Korean mills. Supply chain risk centers on single-source vulnerability for lithium-ion cell thermal management systems. Distribution runs through United Rentals and regional independent rental channels with telematics-enabled fleet tracking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-powered scraper architectures are displacing propane and corded electric legacy fleets across commercial contractor segments. This technology transition compresses replacement cycles and reconfigures competitive moats around energy density and silica containment integration.
For Market Incumbents: Anchor defensive positioning through backward integration into lithium-ion battery platform standardization and captive blade alloy supply. Invest in OSHA competent person certification programs to constrain deployment velocity for non-certified competitors. Prioritize HEPA containment retrofit engineering for legacy fleet compatibility to extend aftermarket service revenue. For New Entrants and Emerging Players: Launch via equipment-as-a-service contracting models targeting United States healthcare systems seeking compliance liability transfer. Target the Indian commercial real estate expansion corridor where Maharashtra contractor fleets lack surface preparation equipment depth. Pursue mid-size electric scraper import channels before BIS certification requirements harden market access barriers. For Investors and Strategic Acquirers: The window for entry favors battery-electric platform specialists with integrated silica control engineering. Long-term viability rests on regulatory endurance rather than raw performance metrics, positioning compliant-systems vendors for durable margin structures. Watch EPA Tier 4 Final homologation timelines as inflection indicators for propane powertrain obsolescence acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | United States government contractors leverage IRA clean energy tax credits for zero-emission procurement compliance. |
| Silica Containment Retrofit Engineering | OSHA's competent person requirements create aftermarket service revenue from legacy propane fleet upgrades. |
| Rental Channel Telematics Integration | FCC equipment authorization governs IoT-enabled fleet tracking attachments for blade-wear optimization. |
| Backward Integration into Blade Alloys | Chinese scrap metal quota adjustments transmit directly to OEM cost structures, favoring captive supply. |
| Equipment-as-a-Service Contracting | National flooring maintenance providers bundle scraper deployment with dust disposal under unit-rate pricing. |
Research Methodology
Independent corroboration across surface preparation contractors, rental fleet procurement managers, and OEM engineering directors underwrites the qualitative findings. Primary interviews with maintenance directors at third-party logistics operators, plant engineers in healthcare facility management, and aftermarket service heads at regional independents combined with secondary validation from OSHA enforcement databases, EPA certification registries, and customs/trade flow records. Bottom-up equipment shipment analysis and top-down construction spending triangulation anchored volume estimates.
Rate-of-change decomposition across powertrain technology transitions, regulatory compliance phase-ins, and regional construction cycles structured the analytical framework. Segmentation dimensions modeled include powertrain architecture, end-user procurement model, application substrate environment, and regional regulatory intensity tier. CAGRs derived from equipment replacement cycle compression analysis and silica standard enforcement trajectory. Lithium-ion energy density improvement curves and steel alloy commodity price volatility informed technology adoption and cost structure projections.
EPA engine certification delays, OSHA enforcement intensity variations across state jurisdictions, and Chinese export quota policy shifts are the dominant revision risks. Forecasts reflect documented assumptions regarding regulatory timeline adherence and commodity price stabilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Machine Bench Vices Market
Tools
Water Pump Pliers Market
Tools
Yard Scraper Market
Tools
Wood Floor Grinding Machine Market
Tools
Fine Blanking Tools Market
Tools
Global Cutting Discs Market
Tools
Mechanical Puller Market
Tools
Orbital Recip Saw Market
Tools
Bandsaw Market
Tools
Foldable Ladder Market
Tools
Sand Control Tools Market
Tools
Lathe Machines Market
Tools
Friction Washer Market
Tools
Wood-Burning Tool Market
Tools
Asia Pacific Power Tools Market
Tools
Woodworking CNC Tools Market