
 Industrial Ladder Market | 2026-2036
Industrial Ladder Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Ladder Market Foresight
Aftermarket service revenue is rewriting how ladder manufacturers capture lifetime value from industrial accounts. Werner Co. leverages its direct-to-contractor channel network to sustain replacement-cycle predictability. Louisville Ladder anchors its position through backward integration into aluminum extrusion operations. ZARGES GmbH differentiates via modular platform systems that extend into confined-space access equipment.
An industrial ladder is a portable, self-supporting or leaning access device engineered to specific duty ratings, typically fabricated from aluminum alloys, fiberglass-reinforced polymer, or carbon steel with load capacities ranging from 250 to 375 pounds. Its primary purpose is to provide temporary vertical or inclined access for personnel, tools, and materials in industrial, commercial, and utility settings where permanent stair access does not exist. Fiberglass ladders command premium positioning due to their dielectric properties and chemical resistance in electrical utility applications. Platform ladders are gaining structural share in warehouse and maintenance segments where two-handed work at height requires OSHA-compliant standing surfaces. Aluminum remains the volume base for construction and commercial indoor use, though margin pools concentrate in specialized fiberglass and multi-position configurations.
OSHA standards govern duty ratings, slip resistance, and labeling requirements for ladders sold into US industrial channels, while the EU Machinery Directive and CE marking enforce structural testing protocols for European market access. These frameworks elevate compliance costs for new entrants but protect incumbent manufacturers with established certification infrastructure. Stakeholders must monitor evolving state-level fall-protection mandates and electrification safety standards that could reshape material specifications and replacement timelines.
Market Dynamics
OSHA fall-protection mandates are compressing replacement cycles and elevating duty-rating specifications across industrial procurement channels, forcing manufacturers to recertify product lines faster than historical baselines.
Growth Catalysts
- Data center maintenance expansion:Hyperscale facility buildouts in Virginia and Texas are driving fleet purchases of platform ladders for overhead cable management and cooling system access.
- EU Machinery Directive enforcement:CE marking requirements for structural testing are filtering out uncertified imports and consolidating demand toward established European manufacturers.
- Fiberglass dielectric properties:Electrical utilities facing live-line work protocols are specifying fiberglass-reinforced polymer ladders for transmission and distribution maintenance crews.
Market Restraints
- Aluminum ingot volatility:Primary aluminum price swings directly compress margin pools on volume ladder categories, forcing hedging costs onto mid-tier manufacturers.
- Chinese supply concentration:Die-cast hardware and extrusion tooling sourcing clusters in Zhejiang province create single-point vulnerability for global supply chains.
- Permanent access substitution:Fixed stair installations and mobile elevated work platforms are displacing ladder purchases in new warehouse automation deployments.
Strategic Opportunities
- Confined-space access convergence:Modular platform systems that integrate with tripod entry equipment open adjacent revenue pools in chemical processing and municipal utilities.
- India manufacturing buildout:PLI scheme incentives for industrial infrastructure are creating first-mover advantage for duty-rated ladder suppliers establishing local assembly.
- Smart fleet tracking integration:RFID and NFC-enabled ladder tagging enables predictive replacement scheduling and sticky service contract attachments with large facility operators.
Industry Challenges
- Welding certification scarcity:Qualified aluminum TIG welders for structural repair and custom fabrication command premium wages that inflate regional production costs.
- Multi-jurisdiction labeling complexity:Simultaneous compliance with OSHA duty-rating labels, ANSI color codes, and EU machinery safety symbols strains packaging and SKU management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Ladder Market |
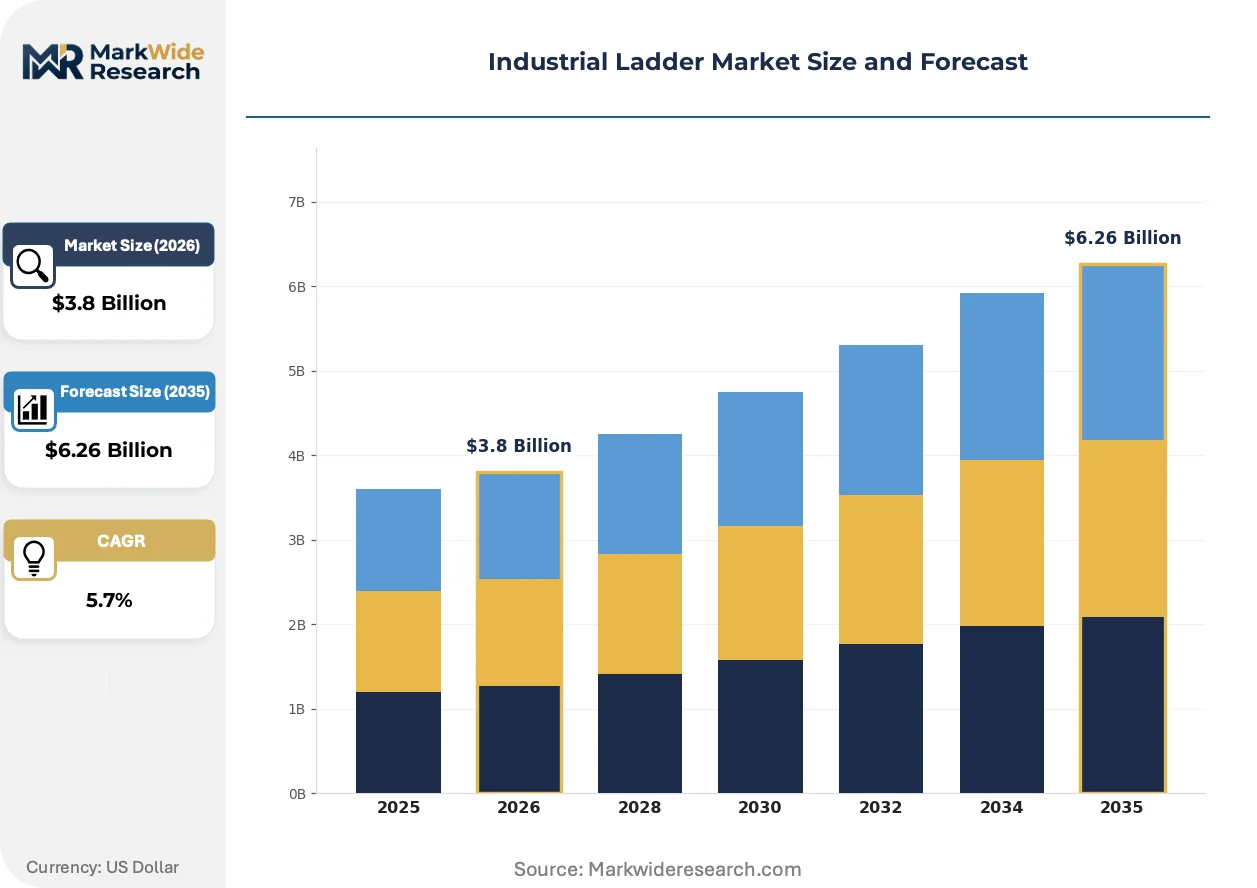
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Step Ladder, Extension Ladder, Platform Ladder, Multi-Position Ladder Material: Aluminum, Fiberglass, Steel, Wood End User: Construction, Maintenance, Warehouse, Utilities Application: Indoor, Outdoor, Industrial, Commercial |
| Companies Covered | ZARGES GmbH, Hailo, Werner Co., Alaco Ladder Company, O'Keeffe's Inc., Louisville Ladder, Gorilla Ladders, Sam Carbis, Little Giant Ladder Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Ladder Market Shifts & Advancements
Material science advances and connected equipment protocols are collapsing the traditional segmentation between commodity access hardware and specialized safety systems, forcing manufacturers to choose between premium engineering investments or margin compression.
Carbon fiber-reinforced polymer construction is collapsing the weight-to-strength ratio that historically favored aluminum in portable ladder categories. Wind turbine maintenance crews and telecommunications tower technicians are specifying carbon fiber extension ladders for 40-foot-plus reach requirements where manual carry access is mandatory. The structural performance gap is collapsing price premiums that fiberglass and aluminum suppliers previously commanded in height-critical applications.
REACH chemical substance restrictions are compelling reformulation of powder coatings and anodizing chemistries used in aluminum ladder finishing. Manufacturers serving EU industrial channels must substitute chromate conversion coatings with trivalent chromium or zirconium-based alternatives that alter surface durability profiles. German and French facility managers are now specifying coating compliance documentation as a procurement gate, shifting supplier qualification timelines.
Integrated inspection and asset management software is displacing paper-based ladder tagging and manual compliance tracking in multi-site industrial operators. Large manufacturing conglomerates and third-party facility management providers are mandating digital fleet registries that automate duty-rating verification and damage incident logging. This behavioral shift is most visible in US automotive assembly plants and food processing networks where OSHA audit frequency has intensified.
Industrial Ladder Market Segmentation
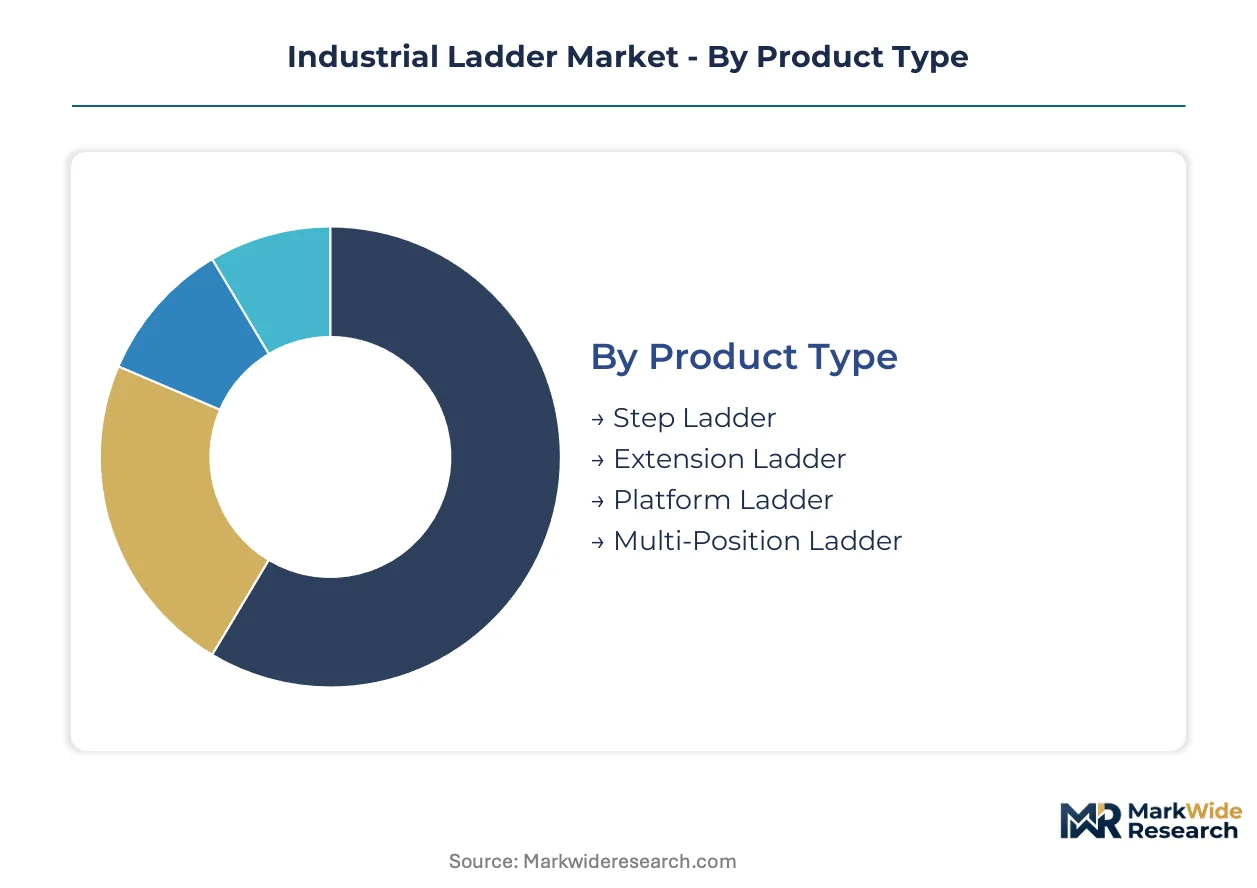
Industrial ladder procurement patterns diverge sharply across material specifications and duty ratings, with replacement-cycle predictability varying by installed base complexity. Segmentation clarity enables manufacturers to align service contract structures with the technical lifespan of each ladder category.
Product Type:
After-sales-service intensity escalates with structural complexity, as modular platform systems demand recurring inspection protocols that step ladders rarely require.
- Platform Ladder:OSHA-compliant standing surfaces with guardrails support two-handed overhead work in warehouse maintenance bays. Fleet purchases by hyperscale data center operators in Virginia and Texas concentrate procurement volume for this category.
- Extension Ladder:Telescoping aluminum or fiberglass rails enable variable reach up to 40 feet for utility pole access. Electrical transmission crews specify dielectric fiberglass variants under live-line work protocols.
- Step Ladder:Self-supporting A-frame designs dominate commercial indoor maintenance where portability outweighs height requirements.
- Multi-Position Ladder:Hinge-locking configurations convert between step, extension, and scaffold modes for contractor fleet versatility.
Platform ladders hold the largest share; momentum sits with multi-position configurations gaining contractor adoption.
Material:
Cost tier stratification separates premium dielectric grades from commodity aluminum volume, with margin pools concentrating where certification requirements elevate technical barriers.
- Fiberglass:Glass-reinforced polymer construction delivers electrical non-conductivity and chemical resistance for utility and petrochemical applications. REACH chemical restrictions are forcing coating reformulations that alter surface durability profiles in EU channels.
- Aluminum:Extruded 6061-T6 alloy rails provide strength-to-weight ratios for construction and commercial indoor use. Primary ingot price volatility compresses margin pools on volume categories, forcing hedging costs onto mid-tier suppliers.
- Steel:Carbon steel construction serves heavy-duty industrial applications where weight penalties are acceptable for load capacity.
- Wood:Traditional timber ladders persist in specialty electrical applications where historical specifications remain embedded in procurement standards.
Aluminum dominates procurement volume; fiberglass commands the steepest expansion trajectory as electrification safety standards tighten.
End User:
Customer type determines fleet scale and replacement cadence, with multi-site operators driving standardization demands that reshape manufacturer channel strategies.
- Utilities:Electrical transmission and distribution maintenance crews specify dielectric ladders under OSHA live-line work mandates. Asset management software integration is displacing paper-based compliance tracking in US automotive assembly and food processing networks.
- Construction:General contractor fleets prioritize aluminum step and extension ladders for job-site portability and rapid deployment cycles.
- Warehouse:Automation buildouts in Germany are driving platform ladder adoption for overhead cable management and cooling system access.
- Maintenance:Facility management providers mandate digital fleet registries that automate duty-rating verification and damage incident logging.
Construction absorbs the highest unit volume; utilities generate the strongest pricing power through specification-driven procurement.
Application:
Volume concentration splits between indoor commercial maintenance and outdoor industrial access, with environmental exposure dictating material selection and coating durability requirements.
- Industrial:Heavy-duty configurations with enhanced load ratings serve manufacturing floors and processing facilities where permanent stair access is impractical.
- Outdoor:UV-resistant finishes and weather-sealed hardware extend service life for utility and telecommunications tower applications.
- Commercial:Aesthetic finishes and compact storage profiles dominate retail, hospitality, and office building maintenance procurement.
- Indoor:Lightweight aluminum designs prevail in climate-controlled environments where corrosion resistance is secondary to portability.
Industrial applications anchor replacement revenue; outdoor specifications are climbing fastest as infrastructure maintenance backlogs expand.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum extrusion capacity clusters in Germany, the United States, and China shape regional supply availability for industrial ladder fabrication. Duty-rating certification requirements vary by jurisdiction, fragmenting procurement standards across major industrial economies.
United States
Hyperscale data center construction in Virginia and Texas drives fleet purchases of platform ladders for overhead cable management. OSHA fall-protection mandates compress replacement cycles and elevate duty-rating specifications across industrial procurement channels. The Southeast manufacturing corridor anchors domestic aluminum ladder production.
Germany
Warehouse automation buildouts concentrate ladder demand in Baden-Württemberg and Bavaria industrial zones. EU Machinery Directive enforcement through CE marking requirements filters out uncertified imports and consolidates demand toward established European manufacturers. ZARGES GmbH anchors modular platform system supply from its Stuttgart-region operations.
China
Die-cast hardware and extrusion tooling sourcing clusters in Zhejiang province create single-point vulnerability for global supply chains. GB standards and MIIT industrial safety protocols govern domestic ladder certification requirements. Yangtze River Delta manufacturing bases serve both export markets and domestic infrastructure buildout.
India
PLI scheme incentives for industrial infrastructure create first-mover advantage for duty-rated ladder suppliers establishing local assembly. BIS certification requirements elevate technical barriers for imported equipment. Maharashtra and Gujarat industrial corridors concentrate manufacturing facility expansion.
Japan
Wind turbine maintenance crews specify carbon fiber extension ladders for height-critical applications. METI industrial safety standards and JIS certification protocols shape procurement specifications. Kanto region utilities drive dielectric ladder replacement cycles under live-line work protocols.
Industrial Ladder Market Competitive Landscape
Vertically integrated specialists and regional fabricators split the market into distinct capability tiers. Incumbent manufacturers with established certification infrastructure capture premium positioning where compliance costs filter new entrants. Two strategic archetypes dominate: backward-integrated aluminum extruders controlling material cost volatility, and modular platform system engineers extending into confined-space access equipment. Competitive moves concentrate on M&A for channel network expansion and smart fleet tracking technology licensing.
Among German fabricators, ZARGES GmbH exemplifies the modular platform engineering archetype, while Louisville Ladder anchors the backward-integrated tier through captive aluminum extrusion operations. Werner Co. occupies a position bridging both vectors through direct-to-contractor channel density. These three entities represent the structural fault lines around which mid-tier competitors must position.
| Leading Market Players |
|---|
| ZARGES GmbH |
| Hailo |
| Werner Co. |
| Alaco Ladder Company |
| O'Keeffe's Inc. |
| Louisville Ladder |
| Gorilla Ladders |
| Sam Carbis |
| Little Giant Ladder Systems |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese aluminum extrusion facilities is compressing input costs for ladder manufacturers while simultaneously eroding pricing power across commodity-grade product lines. This utilization dynamic forces mid-tier suppliers to absorb hedging expenses or cede volume to backward-integrated competitors with captive material supply.
Pricing Analysis
OSHA duty-rating mandates dictate the pricing tier structure across industrial procurement channels, with certification-grade differentiation separating premium fiberglass platforms from standard aluminum step configurations. Price differentiation hinges on dielectric certification level and after-sales inspection bundling, with electrical utilities showing lowest sensitivity due to live-line safety protocols. Cost compression in aluminum categories is intensifying because primary ingot volatility transfers directly to spot-market purchasers. Warehouse operators and general contractors exhibit highest price sensitivity, driving procurement toward multi-position configurations that collapse SKU requirements.
Supply Chain Analysis
Primary aluminum ingot and fiberglass-reinforced polymer resin feed from concentrated extraction and polymerization bases in China, the United States, and Germany. Raw material dependencies center on 6061-T6 aluminum alloy billet, glass fiber roving, and zinc-alloy die-cast hardware. Single-source vulnerability clusters in Zhejiang province extrusion tooling create chokepoint exposure for global fabrication networks. Distribution runs through direct-to-contractor channel networks and industrial supply houses serving multi-site facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and regional compliance regimes creates niche entry points for specialists. Data center fleet standardization demands and utility electrification protocols are splintering procurement into specification-driven segments that reward focused capability over scale.
For Market Incumbents: Pre-empt margin erosion in aluminum categories by accelerating RFID-enabled fleet tracking integration that locks large operators into predictive replacement contracts. Anchor position through upstream control over extrusion capacity in the Southeast manufacturing corridor, insulating against ingot volatility that threatens mid-tier competitors. Defend against carbon fiber substitution in height-critical applications by emphasizing dielectric certification breadth that emerging materials have not yet matched. For New Entrants and Emerging Players: India's PLI-scheme industrial corridors offer underpenetrated assembly opportunities where BIS certification barriers filter out uncertified imports. Establish local fabrication presence in Maharashtra or Gujarat to capture infrastructure buildout demand before incumbent channel networks solidify. Target modular platform system configurations for chemical processing utilities, where confined-space access convergence opens adjacent revenue pools with lower competitive density than commodity ladder segments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with inspection-service contracts and digital fleet registry subscriptions tied to multi-site industrial operators. Long-term viability favors acquisition targets with established CE marking infrastructure and EU Machinery Directive testing capabilities that protect premium positioning. Monitor OSHA state-level fall-protection mandate expansion as the signal indicating accelerated replacement cycle compression and duty-rating specification upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive 6061-T6 alloy supply insulates Louisville Ladder from primary ingot volatility compressing mid-tier margins. |
| RFID-Enabled Fleet Tracking Integration | Werner Co. leverages predictive replacement scheduling to attach sticky service contracts with hyperscale data center operators. |
| CE Marking Certification Investment | ZARGES GmbH filters out uncertified imports through EU Machinery Directive compliance infrastructure in Stuttgart-region operations. |
| Modular Platform System Extension | Confined-space access convergence opens adjacent revenue pools in chemical processing and municipal utility segments. |
| India Local Assembly Establishment | PLI scheme incentives in Maharashtra and Gujarat create first-mover positioning ahead of BIS certification requirement tightening. |
Research Methodology
A spread of perspectives from maintenance directors at hyperscale data center operators, electrical utility fleet managers, aluminum extrusion plant engineers, and industrial supply house procurement leads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against OSHA regulatory filings, EU Machinery Directive enforcement records, customs trade data for aluminum ladder imports, and SEC 10-K disclosures from publicly traded access equipment manufacturers. Bottom-up unit demand estimates triangulated against top-down industrial construction spending allocations across the analysis window.
Demand-supply balance modeling anchored volume projections, with segmentation across material type, product configuration, end-use industry, and regional certification cluster informing price and mix assumptions. CAGRs derived from replacement cycle analysis, infrastructure spending correlations, and electrification safety standard adoption curves throughout the forecast period. Industry-specific inputs included live-line work protocol expansion rates, data center buildout pipelines in Virginia and Texas, and warehouse automation deployment trajectories in German industrial zones.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese extrusion specialists or accelerated carbon fiber adoption by wind turbine maintenance crews would shift outcomes. Cross-checking against regional industrial construction indices and utility capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Global Punch and Die Storage Cabinet Market
Tools
Rebar Cutter Market
Tools
Europe Paint Spray Guns Market
Tools
Auger Drill Bits Market
Tools
Nut Runner Market
Tools
US Chalk Reel and Line Market
Tools
3D Milling Machines Market
Tools
Cordless Multi Rotary Tools Market
Tools
Hand Saw Market
Tools
Bottle Jack Market
Tools
Power Drill Market
Tools
Air Drills Market
Tools
Power Tools Market
Tools
Coil Fed Punching and Cutting Machines Market
Tools
Power Tool Gears Market
Tools
Riveting Tools Market