
 Tool Hammer Market | 2026-2036
Tool Hammer Market Size, Share, and Industry Trends Forecast 2026-2036
Tool Hammer Market Analytics
Residential construction is consolidating its position as the dominant demand vertical for tool hammers, while automotive repair and DIY enthusiast segments retreat in relative share. Stanley Black & Decker leverages its brand architecture to control retail shelf space across North American home improvement channels. Estwing Manufacturing Company anchors the premium forged-steel segment with its proprietary one-piece construction technique. Hultafors Group AB competes through specialized ergonomic designs targeting professional Scandinavian contractors.
A tool hammer is a percussive hand tool consisting of a weighted striking head fixed to a handle, typically manufactured from drop-forged carbon steel with hardness ratings between 45 and 60 HRC, designed to deliver concentrated impact force for driving nails, shaping metal, or demolishing materials. The claw hammer category dominates value generation due to its ubiquity in residential framing and finish carpentry, while the sledge hammer segment sustains margin pools through industrial demolition and mining applications. Fiberglass-handled variants are displacing traditional wood in professional channels where vibration dampening and weather resistance command price premiums.
OSHA enforces workplace safety standards that mandate tool inspection protocols and impact-resistant specifications for commercial construction sites, while ISO publishes dimensional and performance benchmarks that facilitate cross-border trade in European and Asian markets. The EU Green Deal's embodied carbon requirements are beginning to shape raw material sourcing decisions for steel and fiberglass components. Stakeholders must monitor evolving alloy formulations and regulatory thresholds for recycled content to align procurement strategies with emerging compliance frameworks.
Market Dynamics
Residential construction consolidation is compressing demand into professional contractor channels while OSHA workplace safety standards and ISO 15601 testing protocols intensify certification requirements for commercial-grade tool hammers.
Growth Catalysts
- Infrastructure refurbishment cycles:Aging housing stock in the United States sustains replacement demand for claw and framing hammers among professional remodelers. Federal infrastructure spending accelerates commercial construction starts requiring certified impact tools.
- ISO 15601 harmonization:Cross-border performance benchmarks facilitate trade in European and Asian markets, reducing technical barriers for forged-steel hammer exports. Standardized hardness ratings between 45 and 60 HRC enable supplier interchangeability.
- Fiberglass handle substitution:Vibration-dampening composites are displacing traditional wood in professional channels where weather resistance commands price premiums and reduces workplace injury claims.
Market Restraints
- Carbon steel price volatility:Drop-forged carbon steel input costs fluctuate with scrap metal and energy pricing, squeezing margin pools for mid-tier manufacturers dependent on commodity feedstocks.
- DIY segment erosion:Casual enthusiast demand is retreating as residential construction concentrates among licensed contractors, shrinking addressable volume for economy-grade product lines.
- Embodied carbon compliance:The EU Green Deal's raw material sourcing requirements are adding audit costs and supplier qualification friction for steel and fiberglass component procurement.
Strategic Opportunities
- Ergonomic certification premium:Specialized designs targeting repetitive strain injury prevention can capture price premiums in professional Scandinavian and German contractor markets.
- Recycled content positioning:Stakeholders aligning alloy formulations with emerging recycled steel thresholds can differentiate within public procurement frameworks prioritizing circular material flows.
- Digital channel expansion:Direct-to-contractor e-commerce platforms are bypassing traditional retail shelf-space constraints, enabling margin recovery for specialized forged-steel producers.
Industry Challenges
- Multi-standard compliance timelines:Simultaneous OSHA workplace safety enforcement and ISO 15601 certification processes extend product launch cycles and strain quality assurance resources.
- Skill gap in forged-steel craft:One-piece construction techniques require specialized heat-treatment expertise that is concentrating among aging workforces in traditional manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tool Hammer Market |
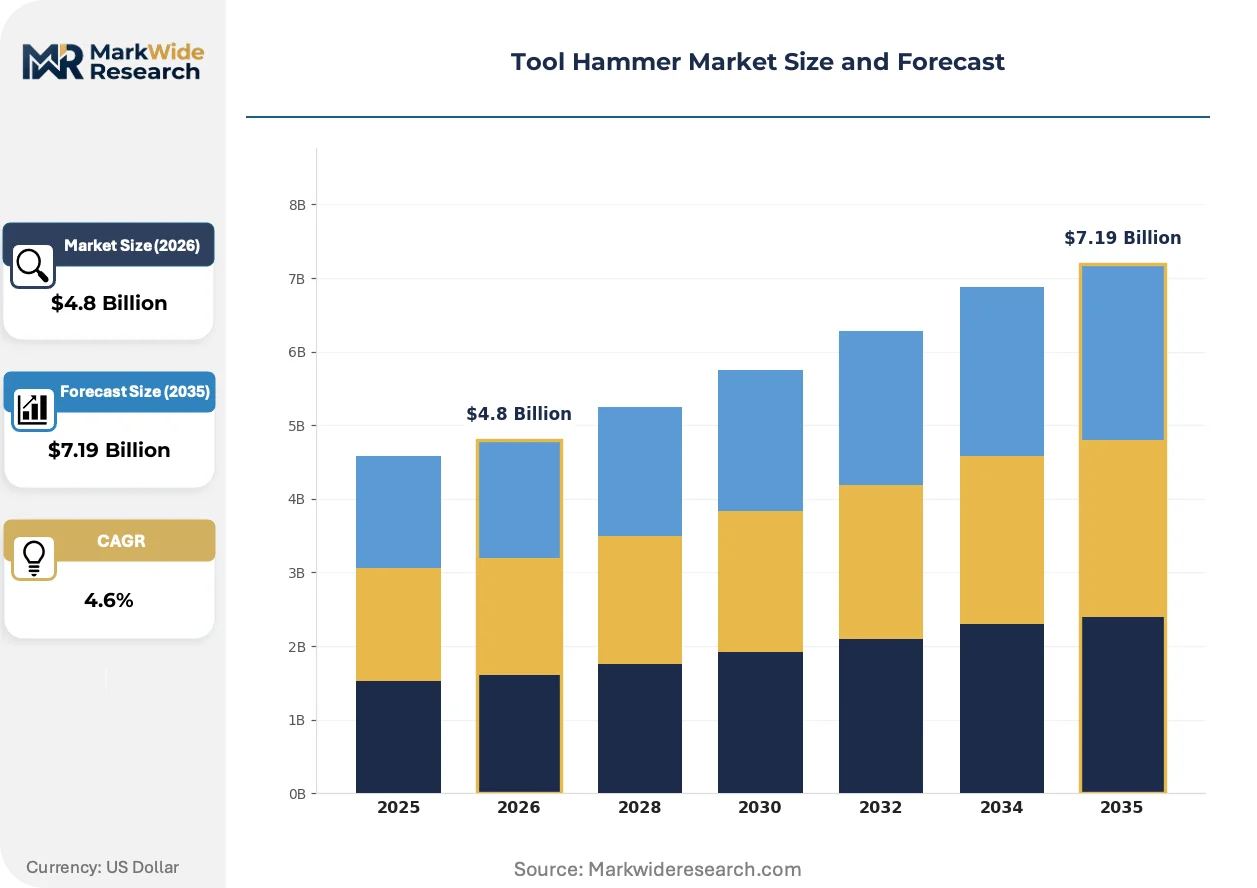
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tool Type: Claw Hammer, Sledge Hammer, Ball Peen Hammer, Framing Hammer Material: Steel, Fiberglass, Wood, Alloy End User: Construction, Automotive, DIY Enthusiasts, Manufacturing Size: Small, Medium, Large, Extra-Large |
| Companies Covered | The AMES Companies Inc, Irwin Industrial Tools, Stanley Black & Decker, Klein Tools Inc, Snap-on Incorporated, Estwing Manufacturing Company, Hultafors Group AB, Apex Tool Group, Vaughan & Bushnell Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tool Hammer Market Evolving Landscape
Material science advances and regulatory stringency are restructuring competitive advantage around certified durability and operator safety rather than commodity pricing power.
Composite handle technology is electrifying professional-grade hammer design through integrated vibration-dampening cores that reduce repetitive strain injuries. Commercial framing contractors in the United States and Germany are specifying fiberglass-overmolded shafts for multi-hour daily use. This specification shift is electrifying margin pools away from traditional hickory-handle suppliers toward engineered-material specialists.
REACH chemical restrictions and the EU Green Deal's embodied carbon framework are forcing reformulation of fiberglass resins and steel alloy sourcing decisions. Manufacturers serving European markets must document supply chain carbon intensity and eliminate restricted substances from polymer handle coatings. The sledge hammer segment for industrial demolition faces the steepest compliance cost escalation due to higher material volumes per unit.
Certification-driven procurement now dominates commercial construction purchasing, with project specifications mandating OSHA-compliant impact ratings and traceable hardness testing. General contractors are consolidating supplier lists to pre-qualified vendors with documented ISO 15601 test results, displacing informal hardware store purchasing. This specification lock-in is most visible in United States metropolitan housing markets where liability exposure drives risk-averse tool selection.
Tool Hammer Market Segmentation
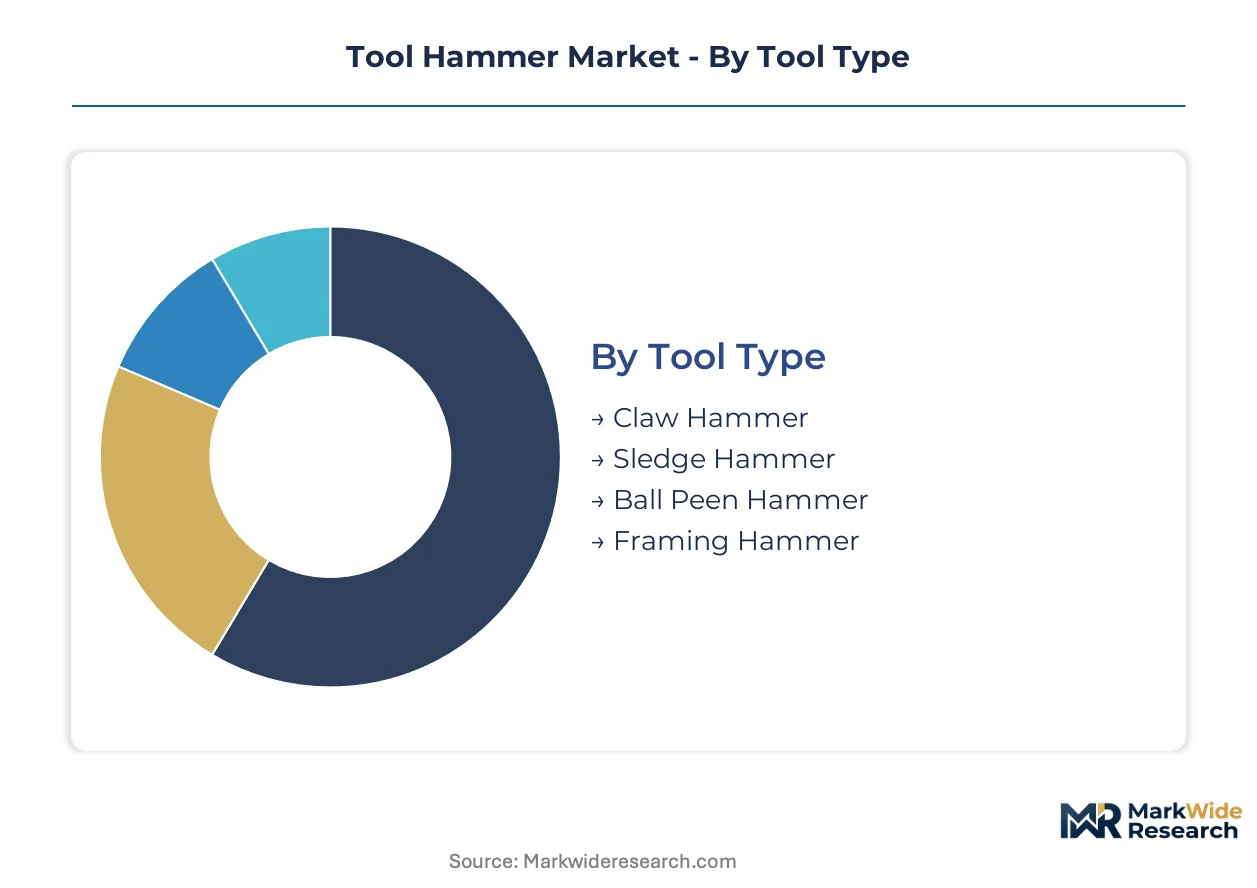
Tool hammer segmentation reveals how product specifications align with distinct operational demands across professional and consumer channels. Material composition and tool geometry determine pricing tiers, certification requirements, and replacement cycles in ways that reshape procurement patterns.
Tool Type:
Integration depth varies sharply across hammer categories, with claw and framing hammers functioning as standalone essentials while ball peen variants embed within specialized metalworking systems.
- Claw Hammer:Drop-forged carbon steel head with curved claw for nail extraction, hardness-rated between 45 and 60 HRC. Demand concentrates among United States residential framers where housing starts sustain replacement cycles for curved-claw and straight-claw variants.
- Sledge Hammer:Double-faced striking head weighing 8–20 pounds mounted on long handle for maximum momentum. Industrial demolition and mining applications in Germany and Australia sustain margin pools through certified impact specifications.
- Ball Peen Hammer:Rounded peen for metal shaping tasks in automotive and machinery repair. Compact head geometry suits bench-mounted fabrication workflows.
- Framing Hammer:Extended handle and milled face for high-velocity nail driving in structural carpentry. Checkered grip patterns reduce slippage during multi-hour use cycles.
Volume placements concentrate in claw hammer specifications; the faster expansion belongs to framing hammer variants as professional residential construction consolidates.
Material:
Cost tier stratification separates premium forged-steel constructions from economy-grade alternatives, with composite handles commanding price premiums in weather-exposed applications.
- Steel:Drop-forged carbon or alloy steel delivering hardness ratings between 45 and 60 HRC for impact durability. One-piece forged construction dominates professional channels in the United States where OSHA compliance mandates traceable hardness testing.
- Fiberglass:Composite handle cores with vibration-dampening properties and weather resistance. Scandinavian contractors and German commercial framers specify fiberglass-overmolded shafts for repetitive daily use.
- Wood:Traditional hickory handles valued for shock absorption and replaceability. Economy-grade residential DIY channels in India and Brazil retain wood specifications for cost-sensitive purchasers.
- Alloy:Specialized titanium or aluminum alloys reducing weight for extended overhead work. Aviation maintenance and confined-space construction applications drive niche adoption.
Steel retains dominant volume placement; fiberglass is climbing the fastest as ergonomic certification requirements intensify across European and North American professional markets.
End User:
Customer type determines specification stringency, with commercial construction mandating certified impact ratings while DIY channels tolerate lower-grade alternatives.
- Construction:Licensed contractors and commercial builders requiring OSHA-compliant tools with documented hardness testing. United States metropolitan housing markets drive specification lock-in through liability-conscious general contractor procurement.
- Automotive:Repair shops and manufacturing facilities utilizing ball peen and soft-face hammers for metal forming. German and Japanese automotive clusters sustain demand for precision-weighted variants.
- DIY Enthusiasts:Casual homeowners undertaking intermittent repair and renovation projects. Retail home improvement channels in the United States and United Kingdom serve this contracting segment.
- Manufacturing:Industrial fabrication facilities requiring specialized hammers for assembly and maintenance tasks. Heavy machinery production lines in China and South Korea utilize custom-specified striking tools.
Construction channels dominate absolute volume; manufacturing applications are gaining share fastest as industrial automation maintenance expands tool replacement schedules.
Size:
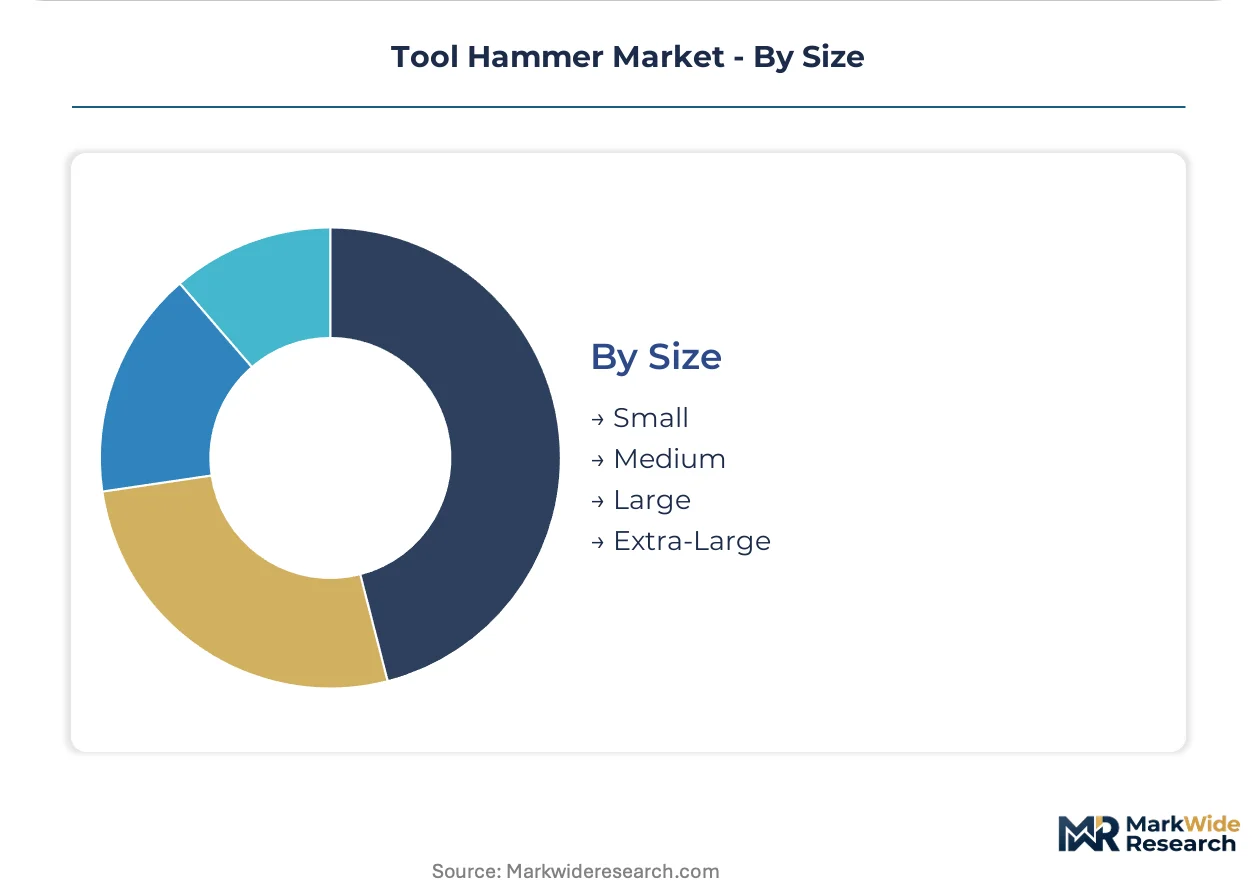
Application scale dictates size selection, with residential carpentry centering on medium specifications while infrastructure and demolition tasks require oversized variants.
- Small:Compact heads under 16 ounces for finish carpentry and confined-space work. Cabinet installation and trim carpentry in Japan and Italy utilize precision-weighted small hammers.
- Medium:16–20 ounce heads balancing velocity and control for general framing tasks. United States residential construction concentrates demand in this specification band.
- Large:22–28 ounce heads delivering maximum driving force for structural lumber and engineered beams. Commercial framing contractors in Canada and Australia specify large hammers for heavy timber construction.
- Extra-Large:Heads exceeding 28 ounces for demolition, railroad work, and mining applications. Industrial sledge configurations in South Africa and Chile utilize extra-large specifications for rock-breaking tasks.
Medium sizes capture dominant volume placement; extra-large variants show steepest expansion trajectory as infrastructure refurbishment intensifies across mineral extraction and transportation sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Guangdong and Zhejiang provinces concentrate forged-steel hammer production capacity, while United States housing starts and German infrastructure refurbishment sustain replacement demand cycles across professional contractor channels.
United States
Metropolitan housing markets in Texas, Florida, and Arizona drive claw hammer replacement volumes among commercial framing contractors. OSHA workplace safety standards mandate documented hardness testing for tools deployed on federal infrastructure projects. Milwaukee and Chicago industrial clusters host heat-treatment specialists serving one-piece forged construction requirements.
Germany
Commercial construction in Bavaria and North Rhine-Westphalia specifies ergonomic fiberglass-handle hammers for multi-hour daily use. REACH chemical restrictions and the EU Green Deal's embodied carbon framework shape fiberglass resin formulations and steel alloy sourcing decisions. Stuttgart automotive clusters sustain precision-weighted ball peen demand for metalworking applications.
China
Yangtze River Delta manufacturing zones supply drop-forged carbon steel heads for export markets across Asia-Pacific and Europe. GB standards and MIIT industrial policy guide domestic quality certification processes. Ningbo and Jinhua forging clusters specialize in mid-tier contract production for international tool brands.
India
Maharashtra and Gujarat construction markets retain wood-handle specifications for cost-sensitive residential contractor segments. BIS quality standards and central government infrastructure spending accelerate commercial-grade tool adoption. Pune manufacturing corridors develop heat-treatment capabilities for domestic forged-steel production.
Japan
Finish carpentry and precision manufacturing in Osaka and Nagoya industrial zones sustain demand for compact, lightweight hammer specifications. METI industrial standards and JIS certification requirements govern professional-grade tool procurement. Tokyo metropolitan housing refurbishment cycles drive replacement timing for residential applications.
Tool Hammer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated shelf-space control in North American retail channels contrasting fragmented forging capacity across Asian industrial zones. Three archetypes dominate: vertically integrated brand houses controlling distribution, specialized forged-steel craftsmen emphasizing one-piece construction heritage, and contract foundries serving private-label programs. Capacity expansion and ergonomic certification investments represent the dominant competitive vectors as professional procurement shifts toward specification-driven purchasing.
Within the premium-forged tier, Estwing Manufacturing Company and Hultafors Group AB exemplify specialized craftsmanship positioning, while Stanley Black & Decker occupies the scale-driven branded portfolio archetype across North American home improvement channels. These three anchors illustrate how geographic origin and corporate structure shape strategic options: the American manufacturer and Swedish limited company emphasize construction-heritage positioning, whereas the incorporated conglomerate leverages retail access breadth.
| Leading Market Players |
|---|
| The AMES Companies Inc |
| Irwin Industrial Tools |
| Stanley Black & Decker |
| Klein Tools Inc |
| Snap-on Incorporated |
| Estwing Manufacturing Company |
| Hultafors Group AB |
| Apex Tool Group |
| Vaughan & Bushnell Manufacturing |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between OSHA-compliant forged-steel hammers and economy-grade alternatives manifests in both pricing premiums and supply chain configurations. Professional contractors absorb documented hardness testing costs through pre-qualified vendor lists, while commodity channels face margin compression from carbon steel volatility and informal procurement patterns.
Pricing Analysis
Short lead-time availability commands pricing premiums in professional channels where project specifications mandate immediate tool replacement. Three-tier pricing structure across premium forged-steel, certified standard-grade, and economy DIY levels reflects hardness rating traceability and handle material composition. Price differentiation centers on ISO 15601 certification status and fiberglass-overmold construction versus traditional hickory. Cost compression in economy-grade segments is intensifying because DIY demand erosion concentrates volume among price-sensitive casual purchasers. Commercial construction buyers exhibit lowest price sensitivity due to liability-driven specification lock-in.
Supply Chain Analysis
Dual-sourcing requirements from United States general contractors mandate multi-supplier qualification across Chinese forging clusters and domestic heat-treatment specialists. Geographic supply concentration centers on Guangdong and Zhejiang provinces for drop-forged carbon steel heads, with German and Swedish manufacturers anchoring premium ergonomic designs. Raw material dependencies rest on scrap steel feedstocks, fiberglass resin formulations, and hickory lumber imports. Single-source vulnerability concentrates in specialized one-piece construction expertise concentrated among aging workforces. Distribution runs through direct-to-contractor e-commerce platforms and home improvement retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where OSHA workplace safety standards create a barrier-to-entry moat for forged-steel producers with documented hardness testing capabilities.
For Market Incumbents: Hedge carbon steel exposure through backward integration into scrap metal sourcing or long-term offtake agreements with Yangtze River Delta forging clusters. Reinforce specification lock-in by embedding ergonomic certification into project bid documentation. Defend against fiberglass-handle substitution threats by acquiring composite material specialists with REACH-compliant resin formulations. For New Entrants and Emerging Players: EU Green Deal embodied carbon requirements in Germany open a window for recycled-content positioning among public procurement frameworks. White-space targets include ergonomic designs for Scandinavian contractor markets and digital channel expansion bypassing retail shelf-space constraints. Target direct-to-contractor e-commerce platforms with specialized forged-steel variants as the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with specialized forged-steel craftsmen given certification-driven procurement consolidation among United States commercial framers. Long-term viability favors producers with heat-treatment expertise and documented ISO 15601 compliance. Watch for inflection signals in federal infrastructure spending allocation timing and carbon border adjustment mechanism implementation.| Strategic Initiative | Industry Significance |
|---|---|
| Ergonomic Certification Investment | REACH-compliant fiberglass-overmold designs capture German and Swedish contractor premiums. |
| Recycled Steel Sourcing Program | EU Green Deal alignment differentiates within public procurement frameworks favoring circular flows. |
| Direct-to-Contractor E-commerce Launch | Bypassing retail shelf-space constraints enables margin recovery for specialized forged-steel producers. |
| Heat-Treatment Capability Expansion | One-piece construction expertise concentrates among aging workforces in Milwaukee and Chicago clusters. |
| Dual-Sourcing Supplier Qualification | United States general contractors consolidate pre-approved vendor lists reducing informal hardware purchasing. |
Research Methodology
Document review covered SEC filings from Stanley Black & Decker and Apex Tool Group, complemented by interviews with commercial framing contractors, heat-treatment facility operators, and home improvement retail category managers. Secondary validation drew from OSHA enforcement databases, ISO 15601 testing protocol documentation, and EU Green Deal regulatory filings. Bottom-up demand modeling from housing start projections and infrastructure spending allocations triangulated against top-down forged-steel production capacity estimates.
Cross-referencing historical replacement cycle data with contractor panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include tool type, material composition, end-user channel, and size specification. CAGRs were derived from elasticity-adjusted demand curves incorporating carbon steel price volatility assumptions. Industry-specific forecast inputs encompass federal infrastructure spending trajectories and REACH chemical restriction phase-in schedules.
The model assumes a particular technology adoption path; alternative pathways for composite handle substitution would alter the outlook for traditional hickory suppliers. Forecasts reflect assumptions around OSHA enforcement intensity and ISO 15601 harmonization progress. Deviation in carbon steel scrap pricing or EU carbon border adjustment implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Drill Bit Market
Tools
Edge Bending Machine Market
Tools
Reamer Market
Tools
Taps and Dies Market
Tools
Europe Stump Cutter/Grinder Market
Tools
Surface Levelling Equipment Market
Tools
China Power Tools and Hand Tools Market
Tools
Collated Screws Market
Tools
Global Punch and Die Storage Cabinet Market
Tools
Leather Embossing Machine Market
Tools
Fine Blanking Tools Market
Tools
Gas Cutting Machine Market
Tools
Global Diamond Tools Market
Tools
Brazing Torch Market
Tools
Chainsaw Market
Tools
Ultra Hard Material Cutting Machines Market