
 Brushcutter Market | 2026-2036
Brushcutter Market Size, Share, and Industry Trends Forecast 2026-2036
Brushcutter Market Analytics
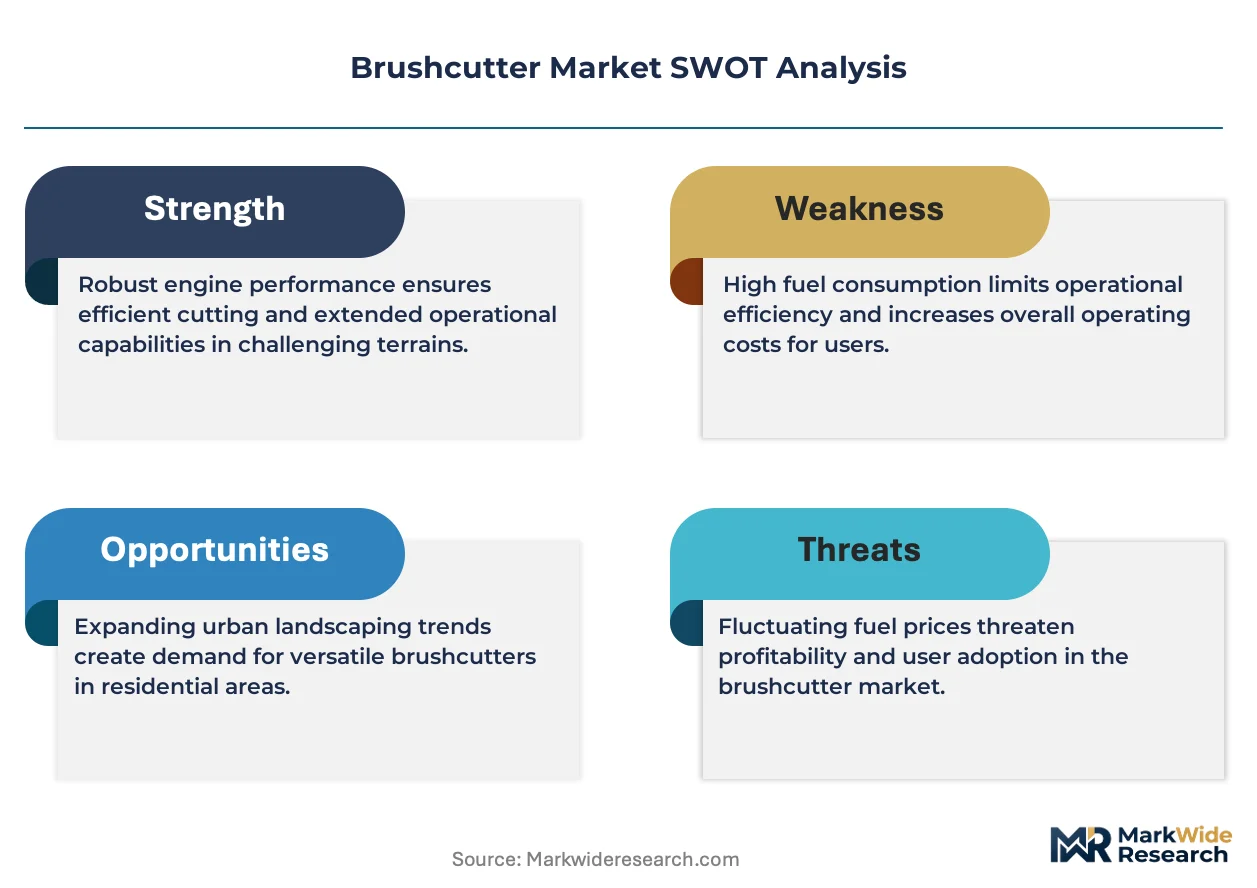
Lithium-ion battery platforms is reconfiguring power-to-weight ratios across handheld outdoor equipment. Stihl leverages captive cell sourcing to stabilize supply chains for professional-grade units. Husqvarna anchors its position through connected fleet management software bundled with commercial machines. ECHO competes aggressively on price in the North American rental channel while maintaining two-stroke expertise.
A brushcutter is a handheld motorized tool employing a rotating cutting head with nylon line, metal blade, or flail attachment to clear vegetation, typically operating at engine speeds of 7,000–12,000 RPM and power outputs from 0.7 kW for consumer units to 2.5 kW for professional clearing. Its primary commercial purpose spans roadside maintenance, agricultural field edge management, forestry undergrowth control, and precision landscaping where mower access proves impractical. Battery-operated brushcutters now capture the fastest expansion as brushless motor efficiency narrows the performance gap with two-stroke engines, though gas-powered units still dominate margin pools in professional forestry applications. Municipal end users represent an emerging demand node as European cities adopt stricter noise ordinances that restrict traditional motor operation during daylight hours.
EPA Phase 3 small nonroad engine standards in the United States compel manufacturers to redesign combustion systems or accelerate electrification timelines, while EU F-Gas Regulation and REACH chemical restrictions shape lubricant and component material choices across European supply chains. OSHA noise exposure limits in commercial landscaping operations push rental fleet operators toward lower-decibel equipment categories. Stakeholders must monitor how pending carbon border adjustments and evolving battery recycling mandates in the European Union reshape total cost-of-ownership calculations for fleet procurement decisions.
Market Dynamics
Brushless motor architecture and lithium-ion cell chemistry are compressing the performance gap with two-stroke combustion engines, forcing incumbents to reconfigure R&D allocation between electrification and emissions compliance investments.
Growth Catalysts
- EPA Phase 3 small nonroad engine standards:Tightened emissions thresholds in the United States accelerate equipment replacement cycles among landscaping contractors seeking compliant gas-powered units.
- Municipal green procurement policies:German cities prioritize low-noise battery-operated equipment for urban maintenance, creating a concentrated demand node for silent-operation brushcutters.
- Brushless motor efficiency gains:Improved power-to-weight ratios in handheld platforms expand addressable applications for battery units previously limited to consumer-grade clearing.
Market Restraints
- Lithium cell supply concentration:Cathode material processing and cell manufacturing cluster in East Asian supply chains, exposing OEMs to geopolitical disruption and input cost volatility.
- Two-stroke engine residual performance:Professional forestry applications retain gas-powered dominance due to sustained power density requirements in dense undergrowth clearing.
- REACH chemical restrictions:European lubricant formulation constraints raise compliance costs and limit cross-border component sourcing flexibility.
Strategic Opportunities
- Connected fleet management software:Commercial landscaping operators in North America seek telematics-enabled asset tracking bundled with equipment procurement.
- Rental channel expansion:Equipment rental fleets represent an underpenetrated distribution vector for mid-tier battery platforms targeting seasonal demand spikes.
- EU battery recycling mandates:Pending regulatory frameworks create first-mover advantages for OEMs establishing closed-loop cell recovery infrastructure.
Industry Challenges
- Small engine technician scarcity:Two-stroke repair expertise concentrates among aging workforce cohorts, complicating service network maintenance for legacy gas-powered fleets.
- Dual certification timelines:Simultaneous EPA and EU type-approval processes extend product launch cycles and fragment engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brushcutter Market |
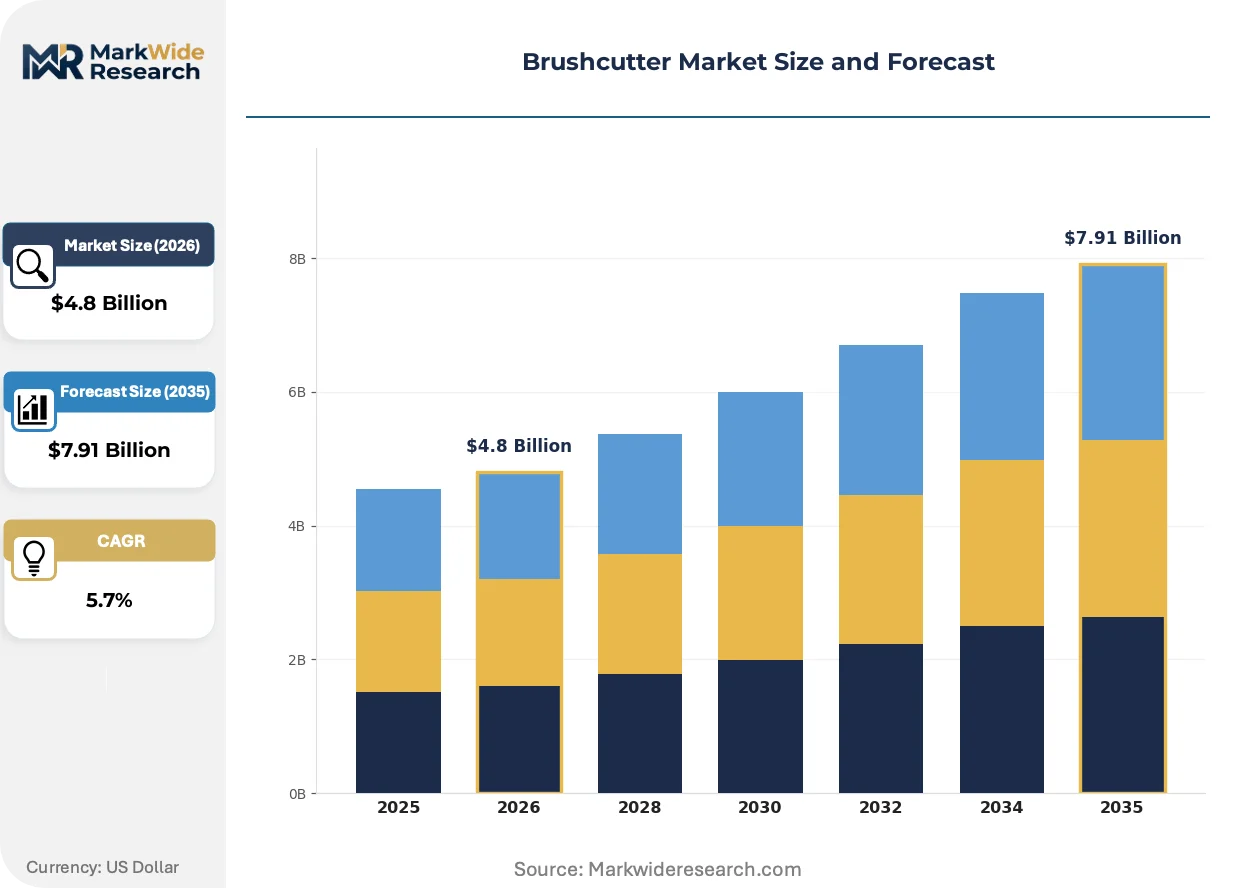
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
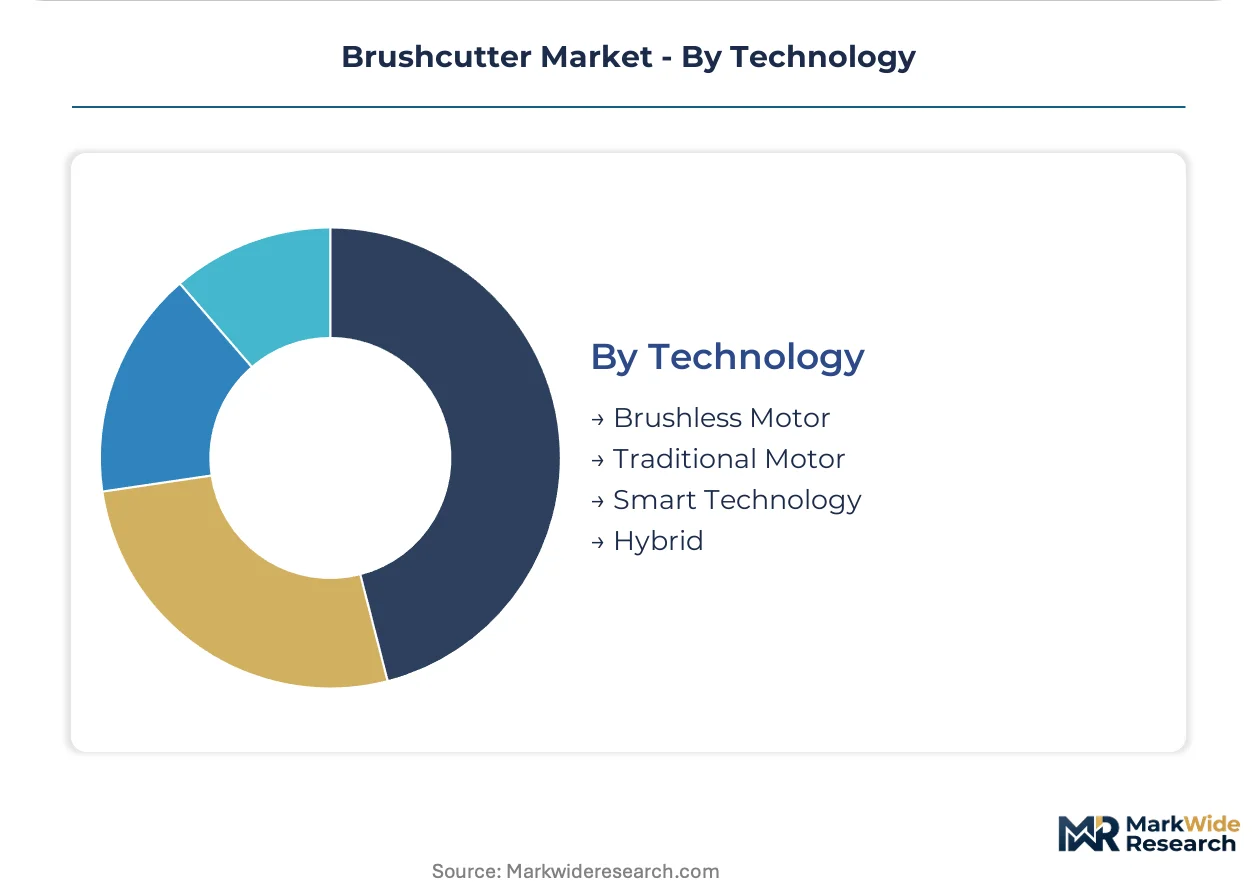
| Segmentation | Product Type: Gas-powered, Electric, Battery-operated, Robotic End User: Landscapers, Homeowners, Agricultural Workers, Municipalities Application: Residential, Commercial, Agricultural, Industrial Technology: Brushless Motor, Traditional Motor, Smart Technology, Hybrid |
| Companies Covered | Stihl, Husqvarna, ECHO, Makita, Black & Decker, Ryobi, Bosch, Greenworks, Briggs & Stratton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brushcutter Market Evolving Landscape
Digital integration, regulatory compression, and procurement rationalization are converging to reshape how brushcutter manufacturers design, distribute, and service equipment across professional and consumer tiers.
Brushless motor control systems paired with smart battery management platforms is digitizing power delivery optimization in professional-grade units. Landscaping contractors in Germany and the Netherlands adopt these systems fastest, integrating them with route-planning software. This convergence compresses the traditional separation between power tool hardware and fleet logistics infrastructure.
EU F-Gas Regulation amendments restrict fluorinated greenhouse gas use in manufacturing processes and component cooling, forcing OEMs to retool casting and molding operations. The industrial consequence falls heaviest on magnesium alloy housing production for lightweight professional units. Manufacturers serving the European market accelerate alternative material qualification programs to maintain CE marking eligibility.
Equipment-as-a-service contracting is displacing outright purchase in North American municipal procurement, bundling maintenance and replacement cycles into multi-year agreements. State transportation departments in California and Texas pilot these arrangements for roadside vegetation management. This shift compresses vendor selection criteria toward total cost-of-ownership analytics and away from unit price benchmarking.
Brushcutter Market Segmentation
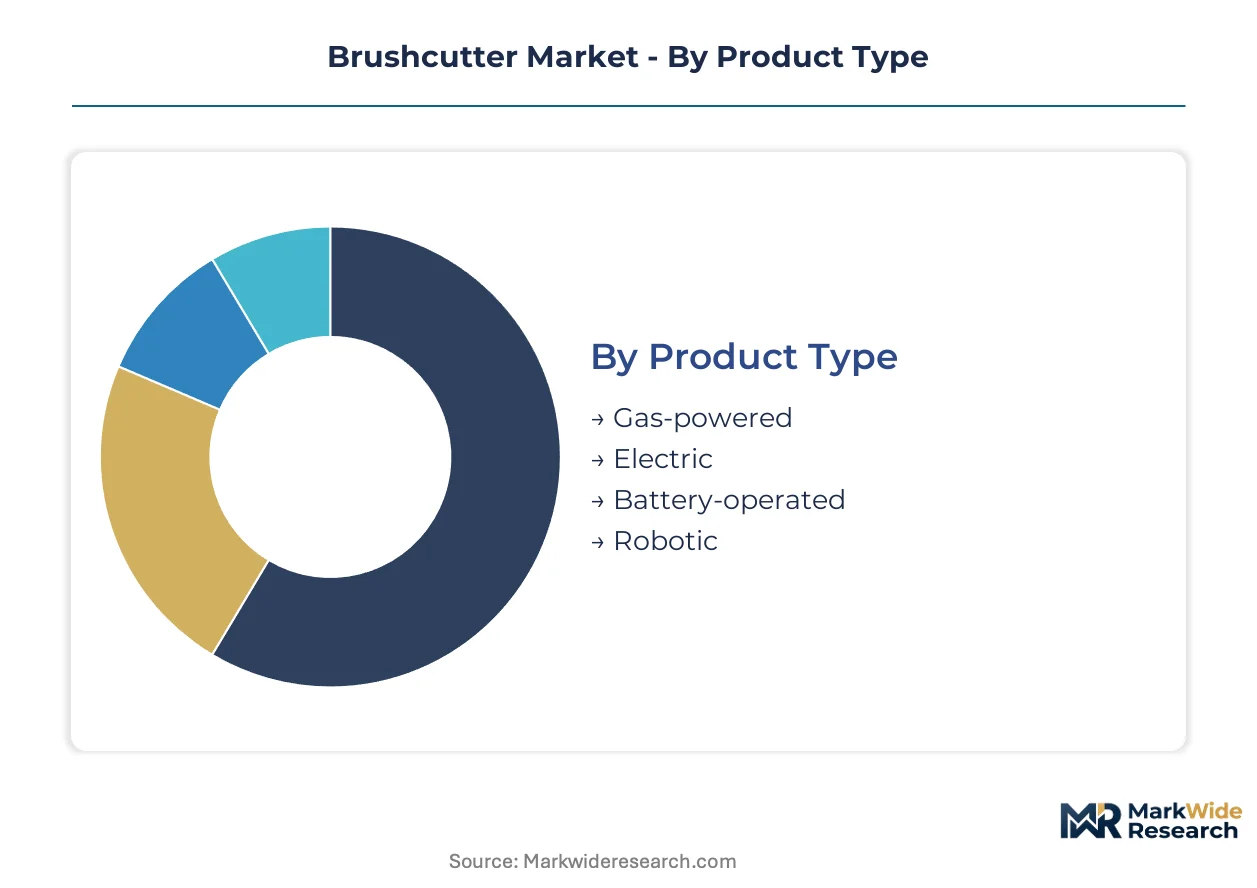
Brushcutter procurement patterns diverge sharply across power platforms and operator profiles, with replacement cycles stretching from 3-year consumer turnover to decade-long municipal fleet amortization. Understanding these segment dynamics clarifies where manufacturers must prioritize R&D investment versus channel maintenance.
Product Type:
Gas-powered units carry the longest replacement cycles in professional forestry, while battery platforms turn over fastest as cell chemistry improvements render two-year-old hardware obsolete.
- Gas-powered:Two-stroke and four-stroke combustion engines deliver sustained power density above 2 kW for dense undergrowth clearing. Landscaping contractors in the United States face EPA Phase 3 compliance deadlines that compress replacement timelines for aging fleet stock.
- Battery-operated:Lithium-ion cell packs paired with brushless motors now achieve runtime parity for 45-minute municipal maintenance shifts. German cities prioritize these units under green procurement mandates that restrict noise emissions below 75 dB during daylight operations.
- Electric:Corded AC motor designs persist in fixed-location agricultural settings where tethered operation eliminates battery weight constraints.
- Robotic:Autonomous navigation systems with RTK-GPS positioning target large-scale solar farm and airport perimeter vegetation management.
Gas-powered equipment dominates installed base volume. Battery-operated configurations are where expansion concentrates.
End User:
Commercial operators segment by fleet scale and technical sophistication, with price sensitivity inversely tracking equipment utilization intensity.
- Landscapers:Professional crews demand 8-hour runtime reliability and rapid blade interchangeability for mixed-terrain contracts. OSHA noise exposure limits push North American operators toward lower-decibel equipment categories to reduce hearing conservation compliance costs.
- Municipalities:European urban maintenance departments bundle fleet telematics with procurement specifications, requiring connected asset tracking for route optimization. REACH chemical restrictions shape lubricant choices across their cross-border equipment pools.
- Homeowners:Consumer-grade purchasers prioritize sub-5 kg weight and single-button start simplicity for intermittent residential edge trimming.
- Agricultural Workers:Field-edge clearing operations favor modular attachment systems compatible with existing tractor PTO infrastructure.
Landscapers anchor manufacturer margin pools. Municipalities are climbing the fastest as procurement rationalization accelerates.
Application:
Intensity of vegetation density and access constraints determine blade specification and power-to-weight requirements across use environments.
- Commercial:Roadside maintenance and precision landscaping demand metal blade durability for woody stem cutting. California Department of Transportation pilots equipment-as-a-service contracts that bundle replacement cycles into multi-year vegetation management agreements.
- Industrial:Forestry undergrowth control and utility right-of-way clearing require professional-grade power outputs above 2.5 kW sustained operation.
- Residential:Suburban lawn edging and fence-line trimming utilize nylon line heads for grass and soft weed removal.
- Agricultural:Orchard floor management and irrigation channel maintenance prioritize low-ground-pressure operation to protect root systems.
Commercial applications concentrate equipment value. Industrial use is gaining share fastest as infrastructure maintenance backlogs expand.
Technology:
Motor architecture and control systems differentiate performance tiers, with electronic integration creating new service revenue streams for OEMs.
- Brushless Motor:Permanent magnet rotor designs eliminate commutator friction losses, improving efficiency to 85% versus 65% for brushed alternatives. Dutch landscaping contractors integrate these systems with route-planning software for fleet logistics optimization.
- Smart Technology:Bluetooth-enabled battery management platforms transmit cell health data and geolocation to centralized fleet dashboards. Texas municipal pilots validate predictive maintenance algorithms for roadside equipment deployment.
- Traditional Motor:Brushed DC and universal AC motor designs persist in price-sensitive consumer segments where electronic control complexity adds unacceptable cost.
- Hybrid:Range-extender configurations pairing small combustion generators with electric drivetrains target remote agricultural applications beyond grid or charging infrastructure reach.
Brushless motor platforms dominate professional procurement. Smart technology integration is expanding most quickly as fleet telematics standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in brushcutter equipment reveal asymmetric regional specialization, with Germany and the United States running persistent trade surpluses in professional-grade units while China dominates component sourcing for lithium-ion cell integration.
United States
Landscaping contractors in California and Texas drive replacement demand as EPA Phase 3 compliance deadlines approach for aging two-stroke fleets. OSHA noise exposure limits push commercial operators toward lower-decibel equipment categories to reduce hearing conservation program costs. The Southeast manufacturing corridor around Georgia hosts assembly operations serving North American rental channel distribution.
Germany
Municipal green procurement policies in Berlin, Munich, and Hamburg prioritize battery-operated units with noise emissions below 75 dB for urban maintenance contracts. EU F-Gas Regulation amendments restrict fluorinated greenhouse gas use in magnesium alloy housing production, forcing retooling of lightweight professional unit manufacturing. The Baden-Württemberg industrial cluster concentrates brushless motor R&D integration with fleet telematics platforms.
China
Domestic demand concentrates in agricultural field-edge clearing applications across Shandong and Henan provinces where modular PTO-compatible attachments dominate. The country's national environmental regulator enforces dual carbon goals that accelerate electrification timelines for export-oriented manufacturers. The Yangtze River Delta hosts cathode material processing facilities supplying cell packs to European OEMs.
Japan
Precision landscaping contractors in the Kanto region adopt connected fleet management systems integrating route-planning software with brushless motor diagnostics. METI efficiency standards for small motor equipment shape domestic product specifications that subsequently export to Southeast Asian markets. The Nagoya industrial corridor maintains specialized production of high-RPM cutting heads for professional forestry applications.
India
Orchard floor management in Maharashtra and Karnataka drives demand for low-ground-pressure brushcutters compatible with existing tractor infrastructure. The central government's PLI scheme for advanced chemistry cell manufacturing attracts investment in domestic lithium-ion pack assembly. The Delhi-NCR region serves as the primary distribution node for equipment rental fleets targeting seasonal agricultural labor cycles.
Brushcutter Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: integrated powertrain specialists, battery platform licensors, and regional fabrication houses serving price-sensitive channels. Strategic archetypes include captive cell sourcing operations, connected fleet software bundlers, and rental channel pure-plays. Dominant competitive moves span backward integration into motor winding operations and strategic partnerships with municipal procurement consortia for equipment-as-a-service contracting.
Among European-anchored power equipment manufacturers, Stihl and Husqvarna occupy positions within the professional-grade tier, with the former exemplifying captive supply chain strategies and the latter representing connected fleet management integration. ECHO sits within the North American rental channel specialization archetype, competing on price positioning while maintaining combustion engine expertise. These three company structures illustrate how geographic origin and organizational form shape competitive positioning without requiring identical strategic postures.
| Leading Market Players |
|---|
| Stihl |
| Husqvarna |
| ECHO |
| Makita |
| Black & Decker |
| Ryobi |
| Bosch |
| Greenworks |
| Briggs & Stratton |
| Others |
Value Network & Pricing Analysis
Cathode material processing clusters in China's Yangtze River Delta directly determine margin capture for European OEMs assembling professional-grade brushcutters, as lithium-ion cell costs constitute the dominant variable in battery platform pricing. This upstream concentration forces manufacturers to absorb volatility or pass through costs to municipal buyers with long procurement cycles.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation stems from brushless motor certification grade and fleet telematics bundling. Cost compression in the mid-tier is intensifying because REACH compliance raises lubricant formulation expenses for gas-powered units. Rental channel operators exhibit highest price sensitivity, while municipal procurement offices prioritize total cost-of-ownership metrics over unit price.
Supply Chain Analysis
Lithium carbonate and nickel sulfate feedstock extraction concentrates in Australia, Chile, and Indonesia, with downstream refining anchored in China and South Korea. Brushcutter OEMs draw from East Asian cell manufacturing for battery platforms and German magnesium alloy suppliers for lightweight professional housings. Single-source vulnerability in cathode precursor chemicals exposes assembly operations to geopolitical disruption. Distribution runs through North American rental fleet operators and European municipal procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against robotic autonomous clearing systems targeting solar farm and airport perimeter applications. Incumbents must navigate electrification timelines while preserving two-stroke service revenue from aging professional fleets.
For Market Incumbents: Pre-empt robotic displacement by accelerating brushless motor efficiency gains beyond 85% and embedding predictive maintenance algorithms in fleet telematics bundles. Backward integration into motor winding operations reduces exposure to East Asian component volatility. Prioritize EPA Phase 3 certification investment to capture replacement demand from non-compliant competitor fleets.
For New Entrants and Emerging Players: Pursue equipment-as-a-service white space in North American state transportation departments, where California and Texas pilot multi-year vegetation management contracts. The rental channel represents the most penetrable vector for mid-tier battery platforms targeting seasonal demand spikes. Lead with total cost-of-ownership analytics rather than unit price positioning.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rental fleet operators consolidating regional landscaping equipment pools. Five-to-ten year viability hinges on electrification capex execution and software bundling capabilities. The signal to watch is municipal procurement mandate acceleration in German cities beyond current 75 dB noise thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Cell Sourcing Partnership | Stabilizes lithium-ion supply chains against Yangtze River Delta concentration risk. |
| Connected Fleet Management Platform | Integrates brushless motor diagnostics with Dutch and German route-planning software. |
| Equipment-as-a-Service Contracting | Bundles maintenance cycles for California Department of Transportation roadside pilots. |
| Closed-Loop Battery Recovery Infrastructure | Positions OEMs for EU battery recycling mandate compliance and first-mover advantage. |
| Magnesium Alloy Alternative Qualification | Maintains CE marking eligibility under EU F-Gas Regulation housing production restrictions. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with landscaping fleet managers, municipal procurement officers, aftermarket service technicians, and OEM product development leads; and secondary validation against EPA engine certification databases, EU F-Gas Regulation amendment filings, customs trade records for lithium-ion cell imports, and SEC equipment manufacturer disclosures. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction across power platform segments.
Forecast inputs span gas-powered, battery-operated, electric, and robotic product categories; commercial, industrial, residential, and agricultural applications; and brushless motor, smart technology, traditional motor, and hybrid technology tiers. CAGR derivation incorporated equipment replacement cycle compression from EPA Phase 3 compliance deadlines and municipal green procurement policy adoption curves. Brushless motor efficiency trajectories and lithium cell cost decline curves anchored the projection horizon.
Sensitivities concentrate around lithium carbonate price volatility, REACH chemical restriction expansion, and robotic autonomous system cost parity achievement. Forecasts reflect assumptions regarding fleet telematics adoption rates and municipal procurement rationalization timelines. Cross-checking against IEA critical minerals supply forecasts and EU battery recycling mandate implementation schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Broaching Tools Market
Tools
Structural Wood Screws Market
Tools
Assembly Fastening Tool Market
Tools
Tile Saw Market
Tools
Gas Cutting Machine Market
Tools
Taps and Dies Market
Tools
Automatic Heat Press Machines Market
Tools
Portable Pressure Washer Market
Tools
Extensometer Market
Tools
Fatigue Testing Machine Market
Tools
Global Table Saws Market
Tools
Sand Control Tools Market
Tools
Laser Engraving Machine Market
Tools
Multi Wire Cutting Machine Market
Tools
Machine Vise Market
Tools
Cordless Power Drill Market