
 Tool Pliers Market | 2026-2036
Tool Pliers Market Size, Share, and Industry Trends Forecast 2026-2036
Tool Pliers Market Analytics
Aftermarket service revenue for tool calibration and replacement jaw programs is rewriting margin economics across the pliers value chain. Knipex leverages its captive forging operations in Wuppertal to sustain premium positioning in precision gripping tools. Stanley Black & Decker anchors volume throughput through retail and professional distribution networks spanning North America and Europe. Channellock competes on domestic manufacturing scale with its Meadville, Pennsylvania forging facility, differentiating on made-in-USA positioning for government and industrial procurement channels.
Tool pliers are hand-operated gripping and cutting implements forged from alloy steels or carbon steel, heat-treated to specific Rockwell hardness ratings, designed for material manipulation in mechanical and electrical work. The primary industrial purpose centers on wire cutting, fastener gripping, and component bending across construction, automotive repair, and electrical installation tasks. Needle nose and locking plier categories command premium positioning due to precision machining requirements and specialized jaw geometries, while slip joint variants occupy commoditized volume tiers with thinner margin profiles. Insulated feature segments are gaining structural importance as electrical safety certifications become mandatory for live-circuit work in regulated jurisdictions.
FDA oversight of surgical-grade instrument steels intersects with pliers manufacturing where medical-adjacent tool grades apply, while OSHA electrical safety standards directly mandate insulated tool specifications for qualified electrical worker protection. The EU's REACH regulation restricts hazardous substance content in surface coatings and handle materials, forcing reformulation of dip-coated grips across export-oriented suppliers. Stakeholders must monitor evolving alloy cost volatility and certification reciprocity agreements between national standards bodies to optimize sourcing footprints and product compliance portfolios.
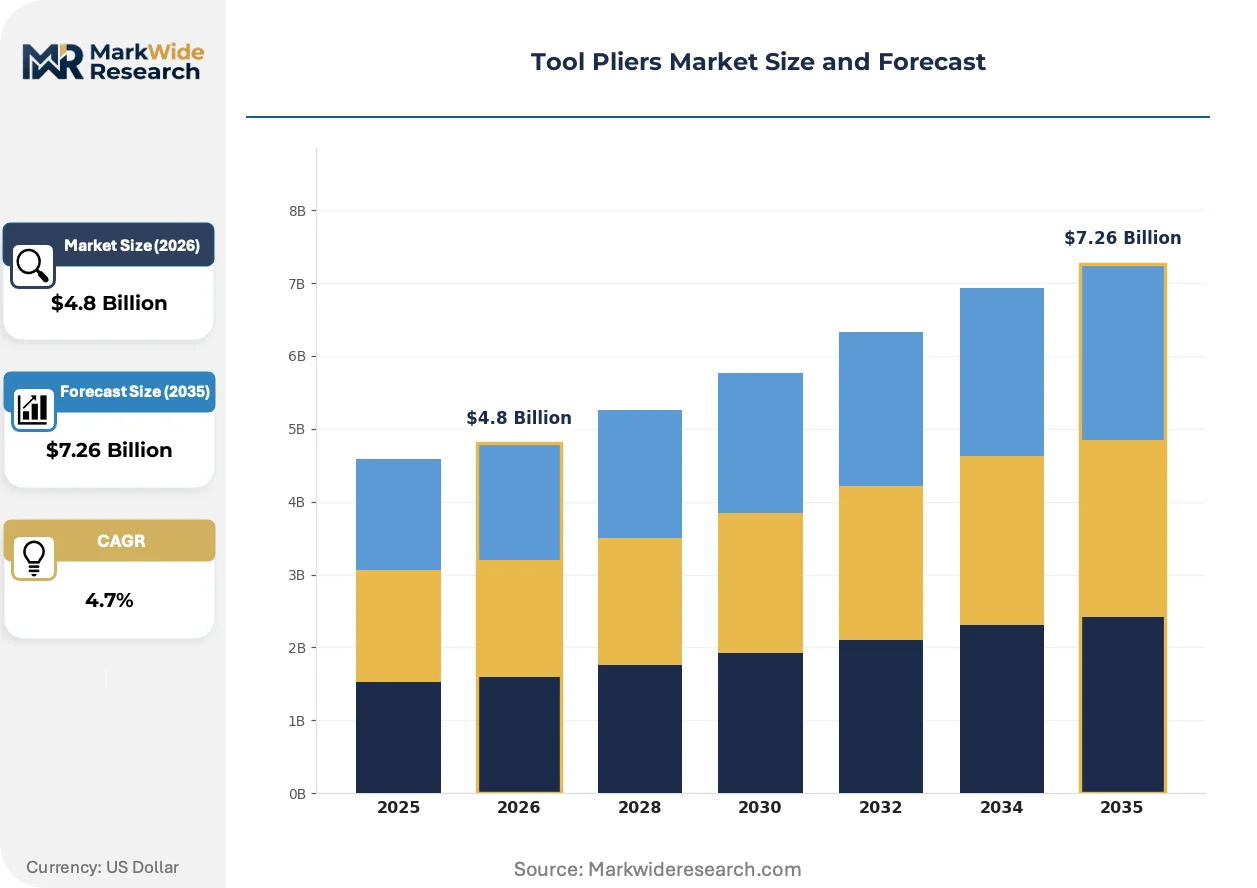
Market Dynamics
The tool pliers market is reconfiguring around precision-forging capability concentration and electrical safety certification mandates that now govern professional procurement specifications across industrialized economies.
Growth Catalysts
- REACH chemical compliance:The EU's REACH regulation is forcing surface coating reformulations that favor suppliers with in-house materials science capabilities, advantaging forged-alloy specialists over commodity assemblers.
- Live-circuit electrical work:OSHA electrical safety standards now mandate insulated tool specifications for qualified electrical workers, creating certified product demand that commands 40-60% price premiums over standard variants.
- Wuppertal-Meadville forging corridor:Captive forging operations in Germany's Bergisches Land and Pennsylvania's Crawford County are concentrating high-precision jaw production capacity that export-oriented manufacturers cannot replicate without decade-long capability buildouts.
Market Restraints
- Alloy steel input volatility:Nickel and chromium price swings from Indonesian and South African supply concentration directly compress forging margins, forcing hedging costs that smaller producers cannot absorb.
- Dual-carbon policy divergence:China's MIIT carbon intensity targets and the EU's CBAM are creating divergent compliance cost structures that fragment export pricing coherence for multi-jurisdiction suppliers.
- Power tool substitution:Battery-powered crimping and cutting tools from Milwaukee and DeWalt ecosystems are displacing manual pliers in high-volume electrical contractor workflows.
Strategic Opportunities
- India's PLI scheme for capital goods:India's production-linked incentive scheme for engineering goods is attracting forging investment that could serve Middle East and African export markets with 15-20% cost advantages.
- Medical-adjacent instrument grades:FDA oversight of surgical-grade stainless steels is creating crossover demand for precision pliers in dental and veterinary applications requiring ASTM F899 certification.
- Direct-to-fleet digital channels:Industrial maintenance platforms like Grainger's KeepStock and Amazon Business are disintermediating traditional two-step distribution for high-velocity replacement purchases.
Industry Challenges
- Heat-treatment skill scarcity:Rockwell hardness specification expertise is concentrating among aging technician cohorts in Solingen and Seki City, with apprenticeship pipelines failing to replenish specialized knowledge.
- Multi-standard certification timelines:Simultaneous VDE, UL, and IEC 60900 testing protocols for insulated pliers extend product launch cycles by 8-14 months, freezing working capital in pre-revenue inventory.
- Jaw geometry IP fragmentation:Patent thickets around serrated gripping surfaces and induction-hardened cutting edges are forcing licensing negotiations that delay new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tool Pliers Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Needle Nose, Locking, Slip Joint, Diagonal Cutters Material: Steel, Carbon Steel, Stainless Steel, Alloy Feature: Insulated, Multi-Function, Ergonomic, Heavy-Duty End User: Construction, Automotive, Electrical, DIY |
| Companies Covered | Stanley Black & Decker, Knipex, Channellock, Snap-on, Apex Tool Group, Klein Tools, Irwin Tools, Wiha Tools, Gedore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tool Pliers Market Evolving Landscape
Active reshaping in tool pliers centers on material science convergence with electrical safety engineering, regulatory chemistry constraints, and procurement digitization that is compressing traditional channel structures.
Induction-hardened cutting edges with selective tempering zones are hybridizing traditional carbon steel pliers with performance characteristics previously reserved for cobalt-alloy aviation snips. Electrical contractors in Germany and the Netherlands are specifying these hybridized tools for mixed-material jobsite tasks, collapsing the historical separation between dedicated cutting and gripping implements in professional tool belts.
REACH Annex XVII restrictions on chromium VI in surface coatings are forcing dip-grip reformulations across EU-bound production lines. Manufacturers serving German and French markets are migrating to thermoplastic elastomer overmolds that eliminate hexavalent chromium passivation steps, adding 12-18% to handle material costs while enabling regulatory continuity.
Maintenance procurement through integrated supply contracts is consolidating vendor relationships for facility management groups operating across multiple sites. Siemens Energy and similar industrial operators are reducing approved supplier lists from 15-20 hand tool vendors to 3-4 strategic partners, concentrating volume with forging houses capable of calibration certificate traceability and consignment inventory programs.
Tool Pliers Market Segmentation
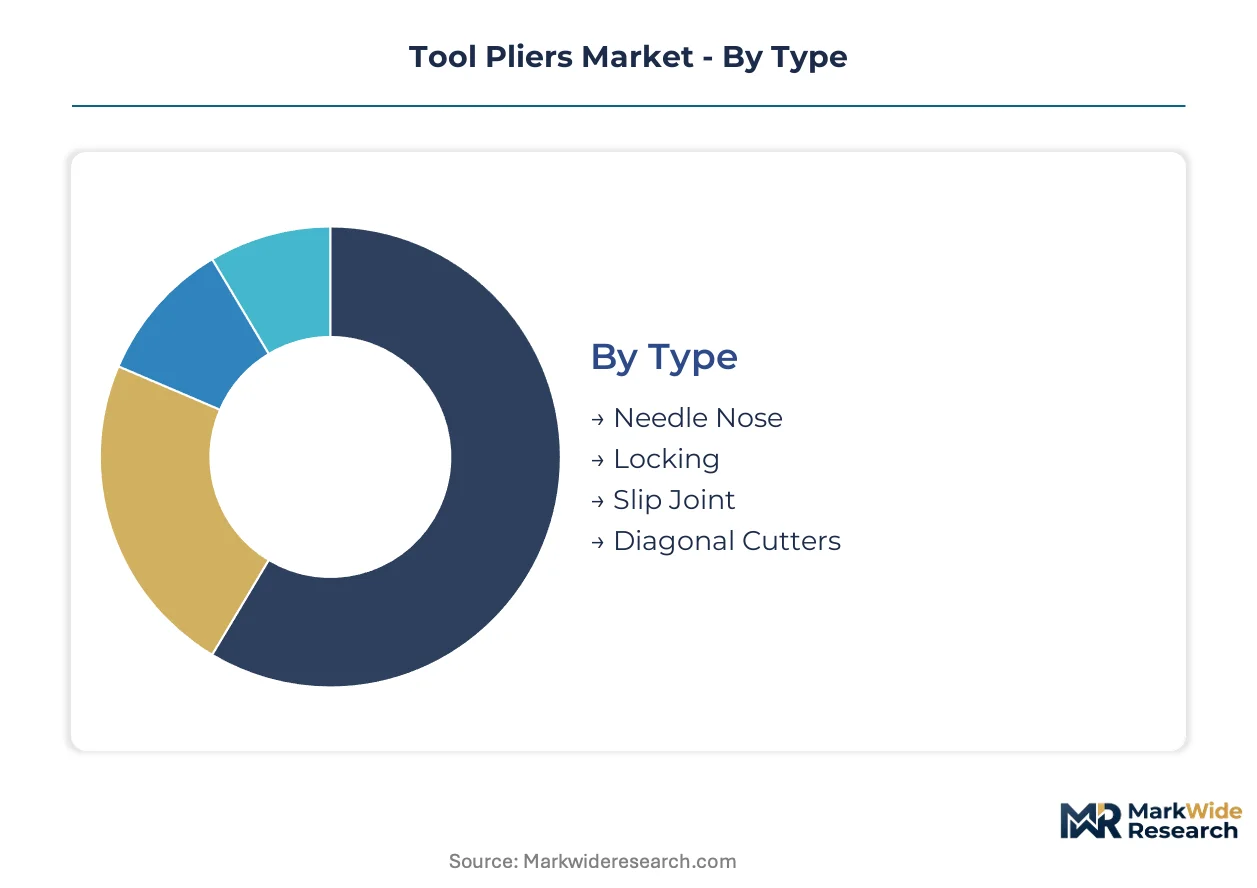
Tool pliers segmentation reflects divergent performance requirements across professional trades and regulatory environments. Jaw geometry, material specification, and electrical safety certification create distinct value tiers that reshape procurement patterns and margin structures.
Type:
Use-case spectrum spans precision electronics work to heavy-gauge industrial cutting, with jaw configuration determining functional specialization and price positioning.
- Needle Nose:Extended tapered jaws with fine serration patterns enable component manipulation in confined electrical enclosures and automotive harnesses. German electrical contractors specify these for control panel assembly where standard plier profiles cannot access terminal blocks.
- Locking:Self-adjusting jaw mechanisms with screw-controlled pressure settings substitute for clamps in welding and fabrication workflows. Construction maintenance crews in Pennsylvania's industrial corridor favor these for pipeline fitting hold-and-turn operations where third-hand assistance is unavailable.
- Slip Joint:Pivot-adjustable jaw widths handle general gripping across fastener sizes without tool changes.
- Diagonal Cutters:Induction-hardened cutting edges sever wire and cable ties flush to surfaces.
The dominant share belongs to Slip Joint, while Locking is closing the gap fastest.
Material:
Cost tier separation tracks alloy complexity against durability requirements and corrosion exposure conditions.
- Alloy:Chromium-vanadium and nickel-molybdenum formulations achieve 58-64 HRC hardness ratings for professional-grade cutting edges that retain sharpness through thousands of cycles. Wuppertal forging houses specialize in these compositions for aviation and energy sector procurement where tool failure carries catastrophic cost.
- Stainless Steel:ASTM F899 surgical-grade variants resist corrosion in medical-adjacent dental and veterinary applications requiring steam sterilization compatibility.
- Steel:Basic carbon formulations serve occasional-use consumers and developing market price-sensitive segments.
- Carbon Steel:Higher carbon content than standard steel enables harder edges at lower cost than alloy grades.
Alloy commands the premium tier by margin, with Stainless Steel gaining share fastest in medical crossover applications.
Feature:
Customer type differentiation separates regulated professional environments from unregulated consumer and light commercial use.
- Insulated:Dual-layer handle construction with VDE and IEC 60900 certification enables live-circuit work up to specified voltage ratings. OSHA mandates these for qualified electrical workers in US commercial and industrial settings, creating non-discretionary demand that withstands price elasticity.
- Ergonomic:Biomechanical handle designs with thermoplastic elastomer overmolds reduce repetitive strain injuries in high-volume assembly operations.
- Multi-Function:Integrated wire stripping, crimping, and gripping capabilities consolidate tool belt inventory for mobile technicians.
- Heavy-Duty:Reinforced pivot joints and thicker jaw stock withstand impact loads in demolition and rigging applications.
Insulated features anchor professional procurement specifications, while Ergonomic variants are climbing the fastest as workplace safety litigation expands.
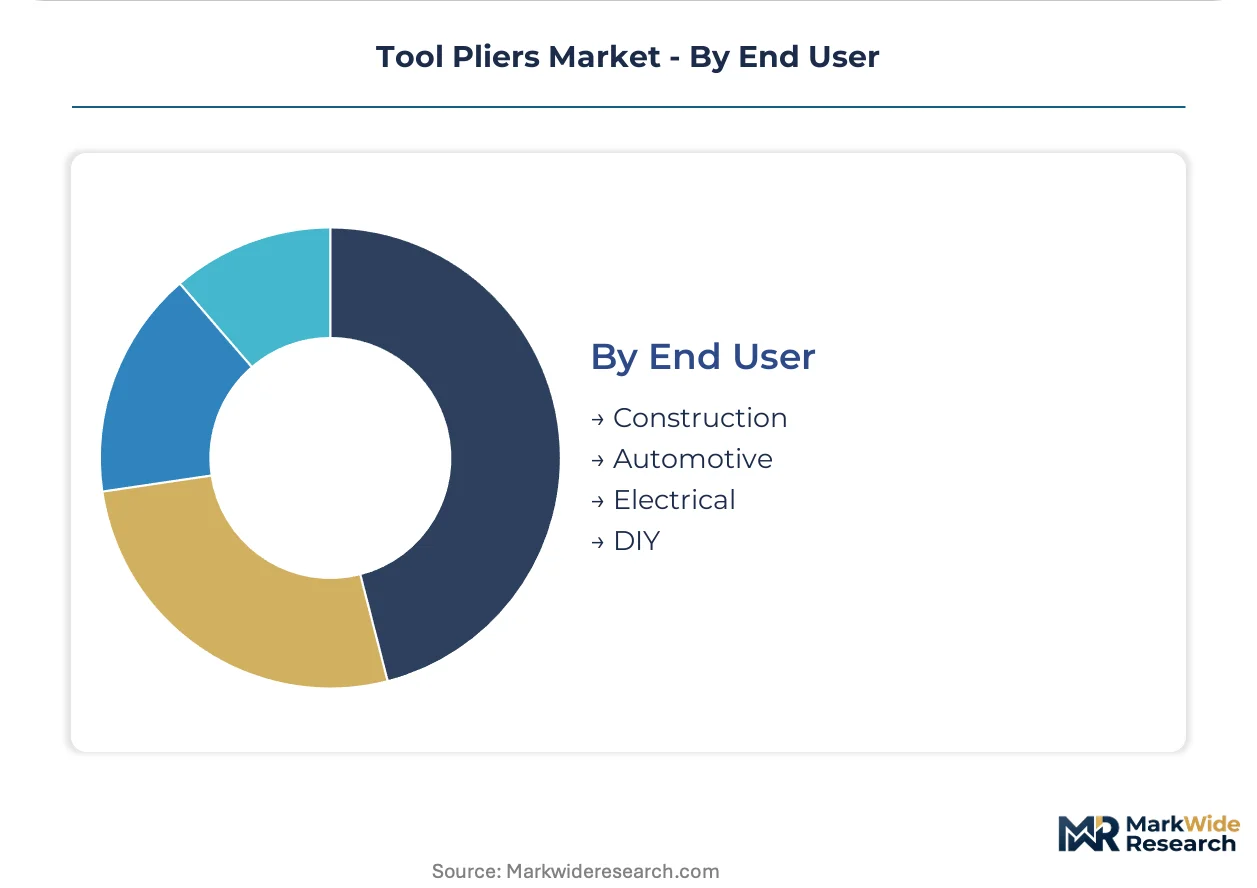
End User:
Volume concentration varies by trade cyclicality, regulatory intensity, and tool replacement frequency.
- Electrical:Code-mandated insulated tool specifications and live-work protocols drive replacement cycles and certification premiums. NECA contractors in Texas and California maintain calibrated tool inventories with documented traceability for liability protection.
- Construction:Framing and finishing crews demand durable gripping and cutting implements across rough material handling and precision trim work.
- Automotive:Assembly line technicians and repair shops require specialized pliers for hose clamp manipulation and cotter pin extraction.
- DIY:Home improvement retail channels serve occasional-use consumers with price-optimized assortments.
Electrical holds the dominant position by value, with Automotive expanding most quickly as electric vehicle assembly complexity multiplies fastener and connector varieties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Captive forging capacity concentrates in Germany's Bergisches Land and Pennsylvania's Crawford County, with China's industrial clusters scaling precision production for export markets. Demand patterns diverge sharply between regulated electrical safety jurisdictions and price-sensitive developing markets.
United States
OSHA electrical safety mandates drive certified insulated tool procurement across NECA contractor networks in Texas and California. The Inflation Reduction Act accelerates grid modernization projects, expanding live-circuit work protocols. Meadville, Pennsylvania anchors domestic forging capacity for government and industrial procurement channels.
Germany
REACH Annex XVII chemical restrictions reshape surface coating formulations for EU-bound production. The Machinery Directive tightens product certification protocols for professional-grade implements. Wuppertal forging houses sustain premium positioning through captive alloy steel operations serving aviation and energy sector buyers.
China
MIIT carbon intensity targets and dual-carbon policy goals fragment export pricing coherence for multi-jurisdiction suppliers. Domestic industrial manufacturing clusters scale precision-forging capabilities to serve both local infrastructure buildouts and Middle East export markets. Yangtze River Delta tool producers consolidate volume throughput for cost-optimized tiers.
India
The PLI scheme for capital goods attracts forging investment targeting 15-20% cost advantages for African and Middle East export markets. BIS certification requirements tighten for insulated tool imports competing with domestic production. Maharashtra and Gujarat industrial corridors concentrate new capacity for electrical infrastructure growth.
Japan
METI industrial standards and JIS certification protocols govern professional procurement specifications for precision gripping tools. Aging technician cohorts in Seki City concentrate heat-treatment expertise with failing apprenticeship pipelines. Automotive assembly line demand multiplies fastener variety complexity for specialized plier configurations.
Tool Pliers Market Competitive Landscape
Heritage forging houses and diversified tool conglomerates split the market along capability-depth versus scale-throughput axes. The vendor base arranges into three strategic archetypes: captive-alloy specialists with in-house forging, retail-anchored volume distributors, and regional scale fabricators with domestic manufacturing positioning. Consolidation pressure intensifies around calibration certificate traceability and consignment inventory program capabilities. Multi-standard certification timelines freeze working capital, favoring incumbents with established VDE, UL, and IEC 60900 testing relationships.
Among heritage European specialists, Knipex and Gedore exemplify the captive-forging archetype with Wuppertal and Remscheid origins. Channellock anchors the domestic-manufacturing positioning strategy for North American procurement channels. Stanley Black & Decker occupies the diversified conglomerate tier with retail and professional distribution network scale spanning multiple continents.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Knipex |
| Channellock |
| Snap-on |
| Apex Tool Group |
| Klein Tools |
| Irwin Tools |
| Wiha Tools |
| Gedore |
| Others |
Value Network & Pricing Analysis
Wuppertal's captive forging houses and Meadville's domestic manufacturing corridor anchor supply-side concentration that translates directly into pricing power for certified precision tools. Alloy steel input volatility from Indonesian nickel and South African chromium supply nodes compresses margins for non-integrated assemblers, forcing cost pass-through differentiation across insulation-grade and standard product tiers.
Pricing Analysis
OSHA electrical safety standards dictate the pricing tier structure by mandating insulated tool specifications that command substantial premiums over standard variants. Three-tier pricing structure across premium, standard, and economy levels separates VDE-certified professional grades from uninsulated commercial tiers and basic consumer assortments. Cost compression in economy tiers is intensifying because Yangtze River Delta producers scale volume throughput for export markets. DIY retail channels exhibit highest price sensitivity, while NECA contractors in Texas and California demonstrate inelastic demand for certified live-circuit implements.
Supply Chain Analysis
Alloy steel feedstock draws from German Bergisches Land precision forgers, Pennsylvania's Crawford County domestic fabricators, and China's Yangtze River Delta industrial clusters. Chromium-vanadium and nickel-molybdenum formulations, thermoplastic elastomer handle compounds, and induction-hardened cutting edges constitute critical input dependencies. Single-source vulnerability concentrates in Solingen and Seki City heat-treatment expertise where aging technician cohorts lack apprenticeship replenishment. Distribution runs through Grainger's KeepStock and Amazon Business platforms that disintermediate traditional two-step channels for high-velocity replacement purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rockwell hardness specification expertise and multi-standard certification capabilities constitute scarce assets that fragment competitive positioning between integrated forging houses and volume distributors. Heat-treatment skill scarcity in Solingen and Seki City creates defensive moats for incumbents while constraining new entrant replication timelines.
For Market Incumbents: Entrench certification reciprocity advantages by deepening VDE, UL, and IEC 60900 testing relationships that freeze competitor working capital in 8-14 month launch cycles. Battery-powered crimping tools from Milwaukee and DeWalt ecosystems threaten displacement in electrical contractor workflows; counter through calibration certificate traceability and consignment inventory programs that lock facility management relationships. Captive forging operations in Wuppertal provide upstream control over alloy formulations that commodity assemblers cannot replicate. For New Entrants and Emerging Players: India's Maharashtra and Gujarat industrial corridors offer white-space entry points where PLI scheme incentives generate 15-20% cost advantages for Middle East and African export markets. Medical-adjacent dental and veterinary applications requiring ASTM F899 surgical-grade certification represent the most penetrable segment given FDA oversight crossover demand. Direct-to-fleet digital channels through industrial maintenance platforms enable bypass of entrenched two-step distribution relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors heritage forging houses with captive alloy capabilities over retail-anchored volume distributors facing power tool substitution pressure. Long-term viability hinges on consolidation of calibration traceability and consignment inventory capabilities that Siemens Energy and similar industrial operators now mandate. Watch for apprenticeship pipeline failures in Solingen and Seki City as inflection indicators for heat-treatment capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging | Captive Wuppertal or Meadville alloy operations insulate margin from nickel and chromium price volatility. |
| Multi-Standard Certification Investment | Simultaneous VDE, UL, and IEC 60900 testing relationships accelerate product launch timelines against competitors. |
| Medical-Adjacent Grade Expansion | ASTM F899 surgical-grade positioning opens dental and veterinary channels with sterilization compatibility requirements. |
| Direct-to-Fleet Digital Channel | Grainger KeepStock and Amazon Business integration captures high-velocity replacement purchases from facility management. |
| Heat-Treatment Apprenticeship Pipeline | Solingen and Seki City technician replenishment secures Rockwell hardness specification expertise against generational attrition. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with electrical contractors, plant maintenance directors, OEM procurement teams, and aftermarket service heads. Secondary validation incorporated customs and trade data, SEC 10-K filings from diversified tool conglomerates, and BIS certification records for insulated tool imports. Bottom-up triangulation across forging capacity utilization and top-down demand modeling across construction, automotive, and electrical installation sectors ensured cross-verified outputs.
Calibration against historical alloy price volatility patterns and certification timeline benchmarks anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include jaw geometry type, material specification tier, electrical safety certification status, and end-user trade vertical. CAGRs derived from installed base replacement cycles, infrastructure investment trajectories, and regulatory mandate adoption curves. Induction-hardening technology diffusion and REACH Annex XVII coating reformulation timelines served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery-powered tool ecosystems or state-subsidized Chinese forging scale-ups would shift outcomes beyond modeled ranges. Cross-checking against OSHA enforcement intensity and NECA contractor inventory data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Metal Cutting Tools Market
Tools
Bi-Metal Band Saw Blade Market
Tools
Cutting Tools Market
Tools
Pliers Market
Tools
MIG Guns Market
Tools
Floor Scraper Market
Tools
Rocket Wrench Market
Tools
Log Splitters Market
Tools
Pneumatic Marking Machines Market
Tools
Digital Cutting Machine Market
Tools
Coil Thread Insert Market
Tools
Air Drills Market
Tools
Surface Planer Market
Tools
Oxy-Fuel Torches Market
Tools
Fiber Laser Cutting Machines Market
Tools
Squeegee Market