
 Turning Tools Market | 2026-2036
Turning Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Turning Tools Market Analysis
Subscription-based tool life monitoring is pivoting how cutting tool vendors monetize relationships with aerospace and automotive buyers. Sandvik leverages digital thread integration across its CoroPlus platform to lock in recurring revenue. Kennametal anchors its competitiveness through direct service contracts tied to spindle uptime guarantees rather than per-unit sales.
Turning tools are rotary cutting implements engineered to remove material from a rotating workpiece, typically featuring rake angles between five and fifteen degrees and nose radii measured in tenths of millimeters to control surface finish. Carbide inserts now dominate material segmentation due to their heat resistance at speeds exceeding three hundred surface meters per minute, while ceramic grades capture share in hardened steel applications where thermal shock tolerance outweighs toughness. Application-level demand clusters in aerospace where titanium and Inconel machining requires specialized geometries, with medical device manufacturing representing a faster-growing but smaller volume pool due to micro-turning requirements.
FDA device manufacturing regulations and ISO 13485 quality management standards constrain tool traceability for medical applications, while FAA airworthiness directives propagate material certification requirements through the supply chain. EPA metalworking fluid emissions rules in the United States and REACH chemical restrictions in Europe both elevate demand for minimum quantity lubrication-compatible geometries. Stakeholders must decide whether to build predictive wear analytics in-house or partner with platform providers before retrofit cycles lock in competitor ecosystems.
Market Dynamics
ISO 13399 standardization for tool data exchange is compressing procurement cycles and forcing vendors to restructure digital product catalogs around interoperable formats rather than proprietary specifications.
Growth Catalysts
- Electric drivetrain precision machining:Automotive manufacturers in Germany's Stuttgart cluster demand cutting inserts engineered for motor shaft and rotor component tolerances.
- REACH chemical restrictions:European manufacturers accelerate adoption of minimum quantity lubrication-compatible geometries to comply with ECHA substance limitations on metalworking fluids.
- Ceramic grade thermal tolerance:Heat-resistant ceramic inserts capture hardened steel applications where carbide grades fail under thermal shock conditions above 300 surface meters per minute.
Market Restraints
- Tungsten carbide supply concentration:Raw material dependency on Chinese tungsten concentrate processors creates price volatility and geopolitical exposure for insert manufacturers.
- FAA airworthiness material certification:Extended qualification timelines for aerospace-grade tooling propagate through supply chains, delaying revenue recognition by 18-24 months.
- Diamond-like carbon coating substitution:Advanced PVD coatings on standard substrates threaten premium insert pricing in general engineering applications.
Strategic Opportunities
- Medical device micro-turning:FDA device manufacturing regulations and ISO 13485 traceability requirements create premium pricing pools for certified tool suppliers in orthopedic and cardiovascular implant machining.
- Digital thread integration:Convergence of tool life monitoring platforms with machine tool OEM control architectures enables subscription-based recurring revenue models.
- India PLI scheme for precision manufacturing:Production-linked incentives for machine tool adoption in automotive and aerospace component sectors open greenfield tooling contracts.
Industry Challenges
- Grinding and coating technician scarcity:Specialized workforce shortages in precision substrate preparation constrain capacity expansion at mid-tier insert manufacturers.
- ISO 13399 legacy system integration:ERP migration costs and data taxonomy reconciliation delay standardization compliance for established tooling catalogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turning Tools Market |
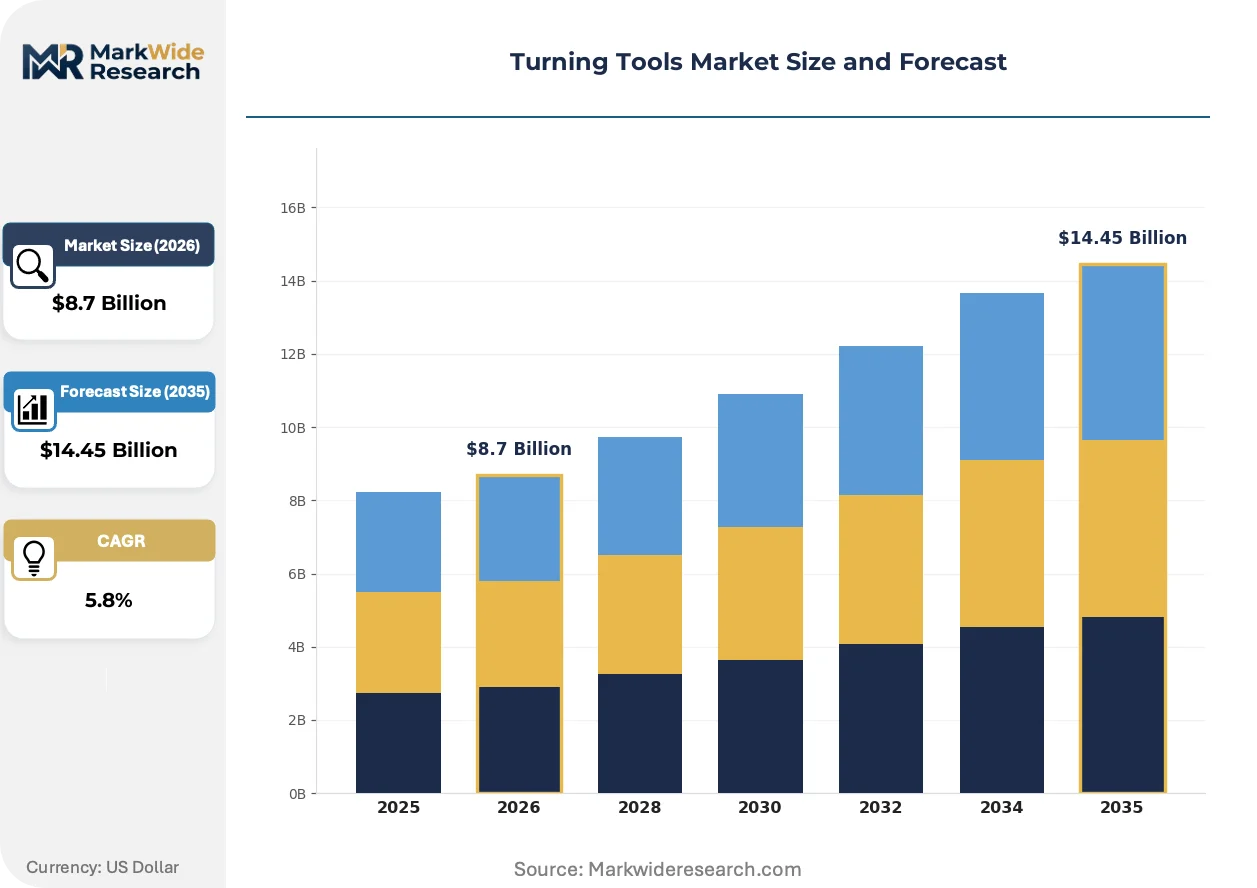
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lathe Tools, Milling Tools, Boring Tools, Tool Holders Material: High-Speed Steel, Carbide, Ceramic, Polycrystalline Diamond Application: Aerospace, Automotive, Electronics, Medical Devices End User: Manufacturers, Metalworkers, Hobbyists, Industrial Sectors |
| Companies Covered | Sandvik, Kennametal, Seco Tools, Mitsubishi Materials, Iscar, Walter, Gühring, Tungaloy, Kyocera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turning Tools Market Emerging Trajectories
Digital platform integration is restructuring how cutting tool vendors capture value, shifting revenue from unit sales toward performance-guaranteed service relationships anchored in real-time wear analytics.
Multi-layer CVD-PVD hybrid coatings are consolidating competitive positioning in high-speed steel turning applications. Aerospace tier-one suppliers in Germany and Japan adopt these grades for Inconel turbine disk machining. The technology is consolidating vendor margins by extending tool life intervals beyond what single-layer alternatives achieve, compressing price competition at the premium tier.
EPA metalworking fluid emissions rules in the United States mandate mist collection and fluid recycling infrastructure investments. Machine shops respond by specifying through-tool coolant geometries that reduce external flood coolant volumes. California and Michigan-based automotive suppliers lead this specification shift, driving geometry redesigns at major insert producers.
Subscription-based tool life monitoring is displacing traditional per-insert procurement in high-volume automotive and aerospace contracts. Sandvik's CoroPlus platform and Kennametal's direct spindle uptime guarantees exemplify this model. Germany's machine tool cluster around Stuttgart and Aachen exhibits the fastest adoption velocity, with buyers prioritizing total cost-per-part over unit tool pricing.
Turning Tools Market Segmentation
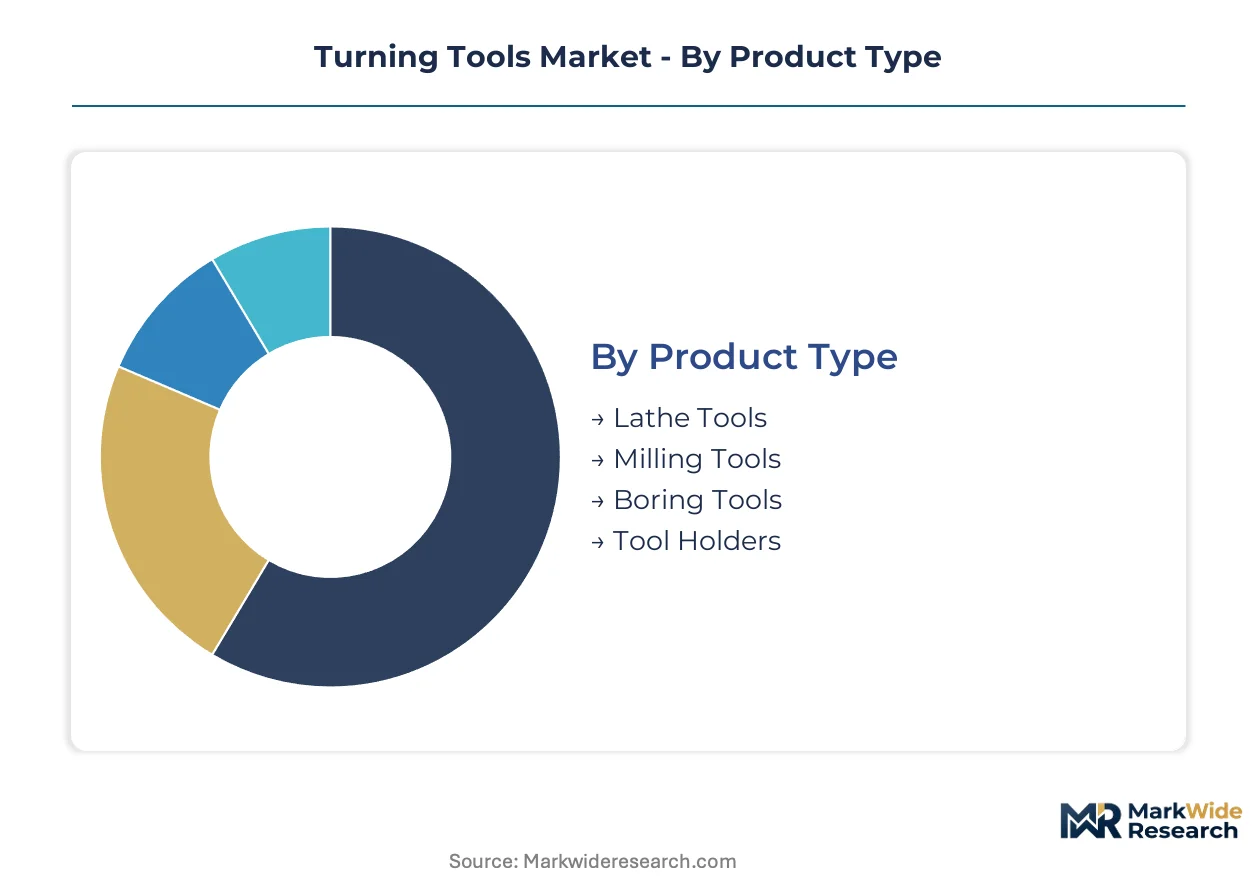
Turning tool procurement decisions hinge on matching material certification requirements to specific application tolerances. Buyers segment purchases across product geometry, substrate composition, and end-use regulatory burden rather than treating cutting implements as interchangeable commodities.
Product Type:
FAA airworthiness directives and FDA device manufacturing regulations propagate distinct qualification timelines across each tool geometry, compressing procurement cycles for certified formats while extending validation periods for specialized configurations.
- Lathe Tools:Rotary cutting implements with rake angles between five and fifteen degrees engineered for external diameter machining. Automotive manufacturers in Germany's Stuttgart cluster specify these for electric drivetrain motor shaft finishing where surface tolerances dictate nose radius selection.
- Milling Tools:Multi-point cutting geometries designed for peripheral and face milling operations on rotating workpieces. Aerospace tier-one suppliers adopt these for titanium and Inconel turbine disk roughing where throughput outweighs finish requirements.
- Boring Tools:Internal diameter cutting systems with adjustable insert pockets for precision hole enlargement.
- Tool Holders:Clamping interfaces integrating ISO 13399 data exchange compatibility for digital procurement workflows.
Lathe Tools sits at the top of the volume ranking, with Milling Tools climbing the fastest.
Material:
Cost tier stratification separates premium ceramic and diamond substrates from standard carbide and economy high-speed steel grades, with coating compatibility driving specification shifts.
- High-Speed Steel:Alloyed tool steel grades retaining hardness at moderate cutting speeds below 50 surface meters per minute. Hobbyists and small metalworking shops in India specify these for general engineering applications where capital constraints limit insert system adoption.
- Carbide:Tungsten carbide-cobalt composite inserts dominating volume share due to heat resistance exceeding 300 surface meters per minute. REACH chemical restrictions in Europe accelerate demand for minimum quantity lubrication-compatible geometries in this substrate class.
- Ceramic:Aluminum oxide and silicon nitride grades capturing hardened steel applications where thermal shock tolerance outweighs fracture toughness.
- Polycrystalline Diamond:Sintered diamond compact inserts for non-ferrous precision finishing in medical device micro-turning.
Carbide captures the largest revenue pool, though Polycrystalline Diamond commands the steepest expansion trajectory in orthopedic implant machining.
Application:
Customer type concentration varies sharply across end-use sectors, with aerospace and medical device buyers demanding direct vendor relationships while automotive and electronics procurement flows through distribution.
- Aerospace:Inconel and titanium machining applications requiring FAA material certification and extended qualification timelines. Japan's METI-supported turbine component manufacturers specify multi-layer CVD-PVD hybrid coatings for disk and blade finishing operations.
- Automotive:High-volume precision turning for powertrain and electric drivetrain components where total cost-per-part metrics dominate supplier selection.
- Electronics:Miniaturized component machining for connector and housing applications.
- Medical Devices:ISO 13485 traceability requirements and FDA regulations constraining tool selection for orthopedic and cardiovascular implant production.
Automotive anchors absolute volume, while Medical Devices gains share fastest on micro-turning precision requirements.
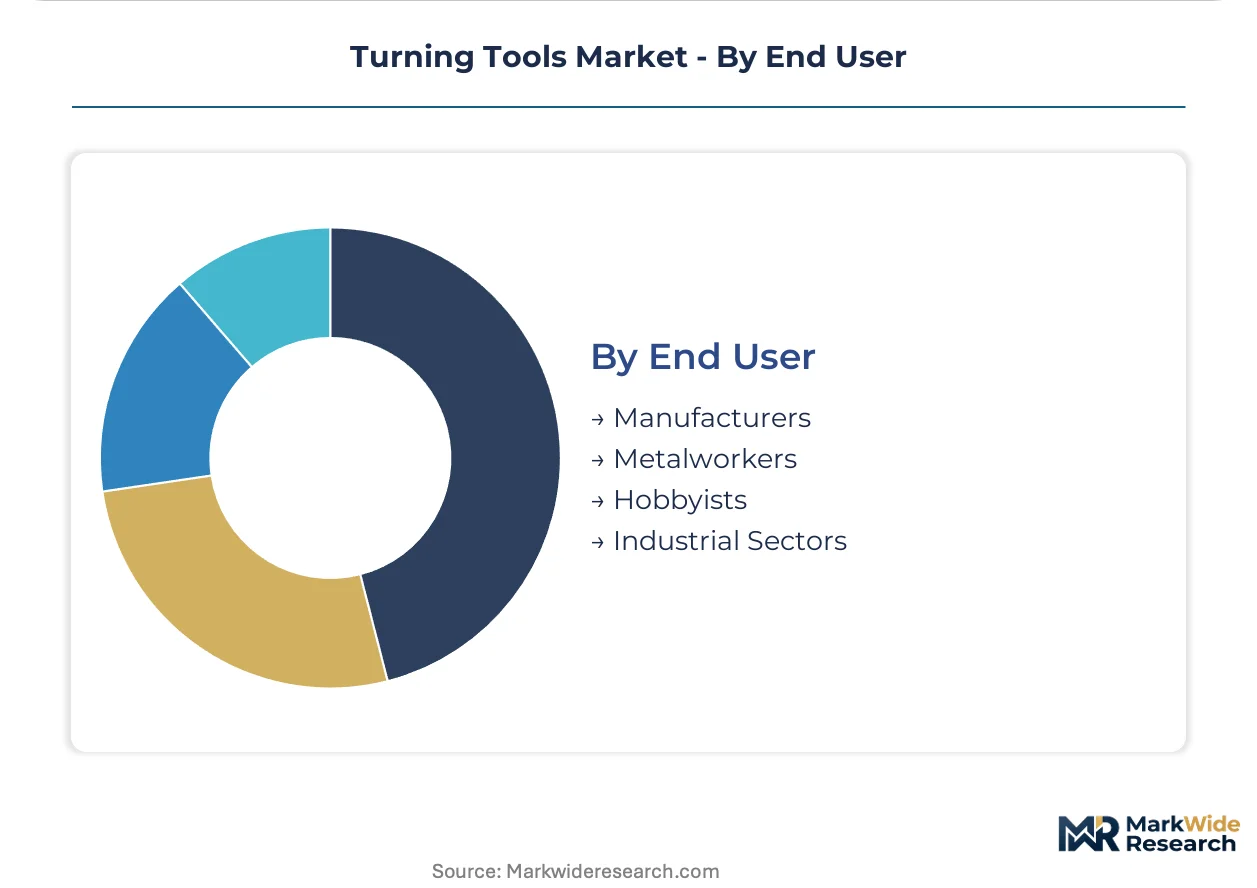
End User:
Supply concentration clusters around industrial manufacturers with captive grinding capabilities, while fragmented metalworking shops and hobbyists access tools through distributor networks with higher markup structures.
- Manufacturers:Tier-one automotive and aerospace producers with direct Sandvik CoroPlus platform subscriptions for tool life monitoring. These buyers negotiate spindle uptime guarantees rather than per-insert pricing in Germany's Aachen machine tool cluster.
- Metalworkers:Independent job shops serving general engineering contracts with variable batch sizes.
- Hobbyists:Small-scale users prioritizing upfront cost over performance metrics in non-production environments.
- Industrial Sectors:Broad category encompassing energy, construction, and agricultural equipment producers with intermittent cutting tool demand.
Manufacturers represent the dominant volume segment, with Metalworkers expanding most quickly as India's PLI scheme for precision manufacturing activates greenfield capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between REACH-regulated Europe and less stringent jurisdictions are redirecting precision tooling capacity toward markets with streamlined environmental permitting. Manufacturers exploit these arbitrage windows to serve automotive and aerospace contracts without absorbing full ECHA compliance burdens.
Germany
Stuttgart and Aachen machine tool clusters anchor European demand for electric drivetrain precision inserts. ECHA REACH substance restrictions on metalworking fluids accelerate minimum quantity lubrication geometry adoption. Tier-one automotive suppliers in Baden-Württemberg negotiate spindle uptime guarantees rather than per-unit pricing.
United States
EPA metalworking fluid emissions rules mandate mist collection infrastructure investments across Michigan and California automotive suppliers. FAA airworthiness directives propagate material certification requirements through aerospace supply chains. Through-tool coolant geometries gain specification share as shops reduce external flood coolant volumes.
Japan
METI-supported turbine component manufacturers specify multi-layer CVD-PVD hybrid coatings for Inconel disk machining. JIS standards govern substrate quality specifications for domestic aerospace tier-one contracts. Nagoya-area precision manufacturers anchor regional demand for ceramic-grade thermal tolerance inserts.
India
PLI scheme production-linked incentives activate greenfield tooling contracts in automotive and aerospace component sectors. BIS standards constrain import specifications for precision manufacturing equipment. Tamil Nadu and Gujarat precision manufacturing corridors attract capacity expansion from mid-tier insert producers.
China
MIIT dual carbon goals elevate energy efficiency requirements for domestic machine tool operations. GB standards govern cutting tool interchangeability specifications for state-supported automotive programs. Yangtze River Delta precision manufacturing clusters concentrate tungsten carbide processing capacity despite raw material import dependency.
Turning Tools Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated premium tiers contrasting fragmented mid-market supply. European and Japanese incumbents anchor high-performance aerospace and medical device applications through direct service relationships. Three archetypes dominate: integrated materials-to-coating specialists, platform-centric digital service providers, and regional scale fabricators. Competitive moves concentrate on backward integration into tungsten carbide substrate production and subscription-based performance contracting.
Among platform-centric digital service providers, Sandvik and Kennametal exemplify the subscription-model archetype through recurring revenue frameworks. Seco Tools occupies a position within the European specialist tier alongside Walter and Gühring. Japanese scale fabricators including Mitsubishi Materials and Tungaloy represent the Asia-Pacific production anchor. These named entities illustrate how geographic origin and corporate structure correlate with strategic positioning rather than determining specific market outcomes.
| Leading Market Players |
|---|
| Sandvik |
| Kennametal |
| Seco Tools |
| Mitsubishi Materials |
| Iscar |
| Walter |
| Gühring |
| Tungaloy |
| Kyocera |
| Others |
Supply Flow & Price Mechanics
Tungsten carbide powder costs cascade through three distinct pricing tiers as raw material from Chinese concentrate processors flows into German precision grinding operations and Indian fabrication facilities. REACH compliance burdens in Europe add regulatory cost layers that mid-tier buyers in North America and Asia-Pacific avoid, compressing margin structures for vendors serving ECHA-regulated markets.
Pricing Analysis
Distributor markups of 25-40 percent separate premium Sandvik and Kennametal catalogs from direct-to-OEM contract pricing negotiated by Stuttgart automotive suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13399 certification status and spindle uptime guarantee bundling rather than substrate alone. Cost compression in standard carbide grades intensifies as diamond-like carbon coating substitution threatens insert premiums. Hobbyists and small Indian metalworking shops exhibit highest price sensitivity, while German tier-one manufacturers prioritize total cost-per-part metrics over unit tool pricing.
Supply Chain Analysis
Grinding and coating technician scarcity in Germany's Stuttgart cluster and Japan's Nagoya region constrains capacity expansion at mid-tier insert manufacturers despite order backlogs. Supply concentrates in China for tungsten carbide substrate processing, Germany for precision finishing, and India for greenfield fabrication under PLI incentives. Raw material dependencies on Chinese tungsten concentrate, cobalt from African sources, and ceramic precursor chemicals from Japanese suppliers create single-source vulnerability exposure. Distribution runs through Sandvik and Kennametal direct service contracts for large manufacturers, with independent distributors serving fragmented metalworking shops at higher markup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical restrictions in Europe create 15-20 percent cost-of-compliance gaps versus Indian and Chinese manufacturing jurisdictions, redirecting precision tooling investment toward greenfield capacity in Tamil Nadu and Gujarat corridors.
For Market Incumbents: Lock in recurring revenue through spindle uptime guarantee contracts before competitor platforms achieve machine tool OEM control architecture integration. Backward integration into tungsten carbide substrate production mitigates Chinese supply concentration risk. Digital thread capabilities anchored in CoroPlus-style platforms defend against diamond-like carbon coating substitution threats in general engineering segments. For New Entrants and Emerging Players: E-commerce direct channels bypass established distributor markups to reach price-sensitive Indian metalworkers and hobbyists underserved by premium catalog vendors. Medical device micro-turning represents the most penetrable white-space target given ISO 13485 certification barriers that slow incumbent response times. Partnership with Indian PLI scheme beneficiaries accelerates greenfield market entry without legacy ERP migration burdens. For Investors and Strategic Acquirers: Consolidation pressure builds where grinding technician scarcity constrains mid-tier capacity expansion in Germany and Japan. Five-to-ten year viability favors platform-centric digital service providers with recurring revenue frameworks over pure-play substrate fabricators. Watch FAA airworthiness qualification timeline compression as signal for aerospace tooling demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Captive tungsten carbide supply reduces Chinese concentrate price volatility exposure for insert manufacturers. |
| Digital Platform Integration | CoroPlus-style tool life monitoring locks in recurring revenue from Stuttgart automotive suppliers. |
| ISO 13485 Certification Investment | Medical device traceability compliance opens premium pricing pools in orthopedic implant machining. |
| Minimum Quantity Lubrication Geometry Development | REACH-compliant designs capture ECHA-regulated European automotive contracts. |
| India PLI Scheme Partnership | Greenfield precision manufacturing corridors in Tamil Nadu offer tariff-advantaged export capacity. |
Methodological Framework
Multiple input streams — primary interviews with insert grinding technicians and procurement directors at Stuttgart automotive suppliers, secondary validation through ECHA REACH substance restriction filings and FAA airworthiness directives, and trade flow analysis from customs data — were reconciled through bottom-up and top-down triangulation. Conversations captured perspectives from plant engineers at tier-one aerospace manufacturers, distributor category managers, and ceramic substrate R&D directors. SEC 10-K disclosures from listed tool vendors, ISO 13399 implementation case studies, and machine tool OEM production statistics provided secondary anchor points.
Historical volume trajectories were cross-referenced against expert panel inputs from Germany, Japan, and India to establish baseline assumptions across the projection horizon. Segmentation modeling incorporated product geometry, substrate material grade, end-use regulatory burden, and regional compliance cost differentials. CAGRs were derived from demand elasticity analysis for electric drivetrain precision machining and medical device micro-turning applications. Forecast inputs included tungsten carbide price volatility scenarios and PLI scheme uptake rates in Indian precision manufacturing corridors.
The model assumes a particular technology adoption path; alternative pathways for multi-layer CVD-PVD hybrid coatings would alter the outlook if single-layer alternatives achieve unexpected thermal tolerance breakthroughs. Forecasts reflect assumptions about FAA qualification timeline stability and ECHA substance restriction enforcement intensity. Material deviation in tungsten supply chain disruption or REACH regulatory scope expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Surface Planer Market
Tools
Striking Tools Market
Tools
GCC Machine Tools Market
Tools
Cutting Tools Market
Tools
Cordless Planer Market
Tools
Nut Runner Market
Tools
Workholding Tools Market
Tools
Woodworking Tools Market
Tools
Industrial Cleaning Equipment Market
Tools
Set Screw Market
Tools
Gear Cutting Machines Market
Tools
Automated Plasma Beveller Market
Tools
Vertical Milling Machine Market
Tools
Rivet Busters Market
Tools
Drilling Tools Market
Tools
Asia Pacific Power Tools Market