
 Global DC Torque Tool Market | 2026-2036
Global DC Torque Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Global DC Torque Tool Market Analysis
Lithium-ion battery chemistry is shifting product economics across the DC torque tool landscape as nickel-manganese-cobalt formulations displace older nickel-cadmium packs. Atlas Copco AB leverages captive R&D in brushless motor architecture to sustain technology leadership in high-precision assembly applications. Robert Bosch GmbH anchors its position through integrated battery management systems that dominate European industrial channels. Stanley Black & Decker competes on manufacturing scale across North American construction and automotive end markets.
A DC torque tool is an electrically powered fastening instrument that delivers calibrated rotational force measured in Newton-meters, typically incorporating brushless DC motors, planetary gearboxes, and electronic clutch mechanisms for repeatable torque output in industrial assembly environments. The primary commercial purpose centers on eliminating fastener variability in safety-critical applications such as aircraft engine mounting and automotive powertrain assembly. Electric tools lead the product type dimension due to superior energy efficiency and compatibility with factory automation protocols, while brushless technology commands the fastest expansion trajectory as maintenance intervals lengthen and thermal performance improves. Aerospace end users represent a concentrated margin pool where calibration accuracy requirements and traceability mandates justify premium positioning.
The European Union's F-Gas Regulation and CE marking directives shape product standards by restricting refrigerant-based cooling in motor housings and mandating electromagnetic compatibility certification for industrial equipment sold within member states. The United States FAA and OSHA frameworks influence demand through airframe assembly traceability requirements and workplace noise exposure limits that favor electronically controlled torque systems over pneumatic alternatives. China's GB standards and MIIT efficiency codes govern market access for imported tools while accelerating domestic substitution in state-backed automotive capacity expansions. Stakeholders must monitor how battery chemistry patent thickets and evolving cybersecurity standards for connected tools reshape supplier qualification criteria across defense and commercial aerospace programs.
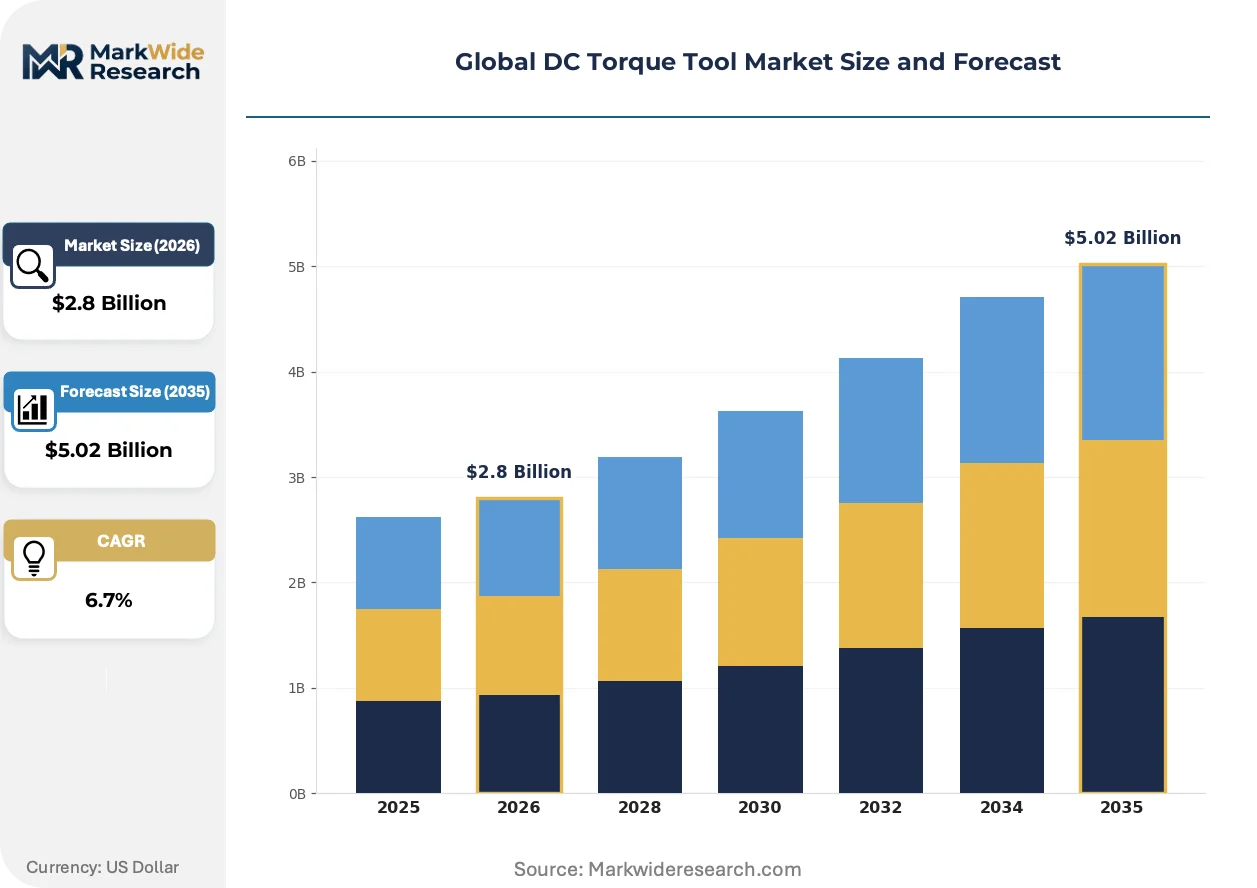
Market Dynamics
The transition from nickel-cadmium to lithium-ion battery chemistries is compressing maintenance cycles and redistributing margin pools across the DC torque tool value chain. Brushless motor architectures now dominate new platform development as thermal efficiency thresholds tighten under industrial energy codes.
Growth Catalysts
- EU Green Deal efficiency mandates:The EU Green Deal and F-Gas Regulation are accelerating factory floor retrofits with digitally connected torque systems that eliminate pneumatic energy losses.
- Aerospace assembly traceability:Aircraft OEMs in Germany and the United States are mandating calibrated rotational force documentation for every fastener in engine mounting applications.
- Lithium-ion chemistry migration:Nickel-manganese-cobalt formulations are displacing legacy packs in high-duty-cycle assembly environments, extending runtime per charge by substantial margins.
Market Restraints
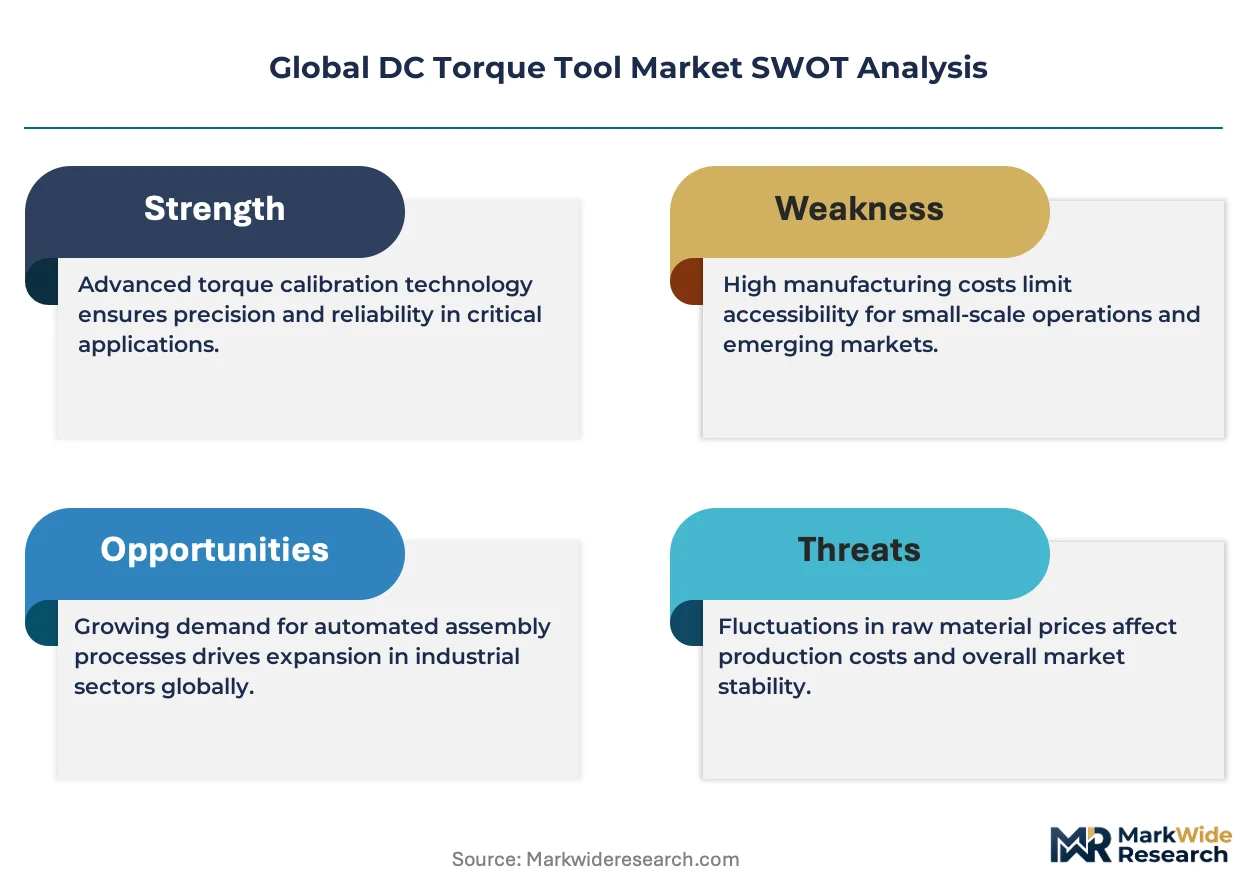
- Battery raw material concentration:Cobalt and lithium refining capacity concentrates in limited geographies, exposing tool manufacturers to input cost volatility and supply disruption.
- Brushless motor IP thickets:Patent portfolios held by established motor architecture specialists create licensing friction for new entrants seeking high-precision torque control.
- Pneumatic tool installed base:Legacy compressed-air systems in mature automotive plants represent a durable substitute threat, delaying electric conversion timelines.
Strategic Opportunities
- China state-backed automotive expansion:MIIT efficiency codes and domestic capacity builds are opening procurement channels for imported digitally connected torque systems.
- Cybersecurity certification for connected tools:Emerging defense and commercial aerospace programs are creating qualification wedges for suppliers with IEC 62443-aligned product architectures.
- Battery-as-a-service models:Tool OEMs are piloting subscription-based power pack programs that shift capital expenditure to operational expenditure for tier suppliers.
Industry Challenges
- Calibration technician scarcity:Precision fastening applications require certified metrology specialists that outpace vocational training pipeline output in Germany and the United States.
- Legacy system integration friction:Retrofitting digitally connected torque tools into existing MES and SCADA architectures demands custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global DC Torque Tool Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Pneumatic, Hydraulic, Manual End User: Aerospace, Automotive, Construction, Manufacturing Technology: Brushless, Brush, Digital, Mechanical Application: Assembly, Maintenance, Calibration, Repair |
| Companies Covered | Atlas Copco AB, Apex Tool Group, Stanley Black & Decker, Robert Bosch GmbH, Ingersoll Rand, Makita Corporation, Hilti Corporation, Techtronic Industries Co. Ltd., Snap-on, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global DC Torque Tool Market Emerging Trajectories
Edge computing architectures are penetrating the DC torque tool segment, enabling real-time torque curve analysis without cloud dependency. This shift is compressing response latency for safety-critical fastening operations while reshaping supplier R&D priorities toward on-device intelligence.
Brushless DC motor platforms with integrated Hall-effect sensors are decentralizing torque calibration authority from central plant metrology labs to individual workstations. Automotive OEMs in Stuttgart and Detroit are deploying these units at scale. The architecture is decentralizing quality control infrastructure and reducing line-stop frequency for recalibration events.
The EU F-Gas Regulation is prohibiting refrigerant-based cooling in industrial motor housings, forcing thermal management redesigns toward passive heat sinks and liquid cooling loops. CE marking directives now mandate electromagnetic compatibility certification for connected tools sold within member states. Aerospace suppliers in Toulouse and Hamburg are prioritizing compliant brushless units to maintain airframe assembly traceability under FAA and EASA frameworks.
Buyers are unbundling after-sales service contracts from initial hardware procurement, selecting third-party calibration providers based on ISO 17025 accreditation rather than OEM captive service networks. Tier suppliers in China's Yangtze River Delta are driving this shift, negotiating per-fastener pricing models that separate tool ownership from metrology responsibility.
Global DC Torque Tool Market Segmentation
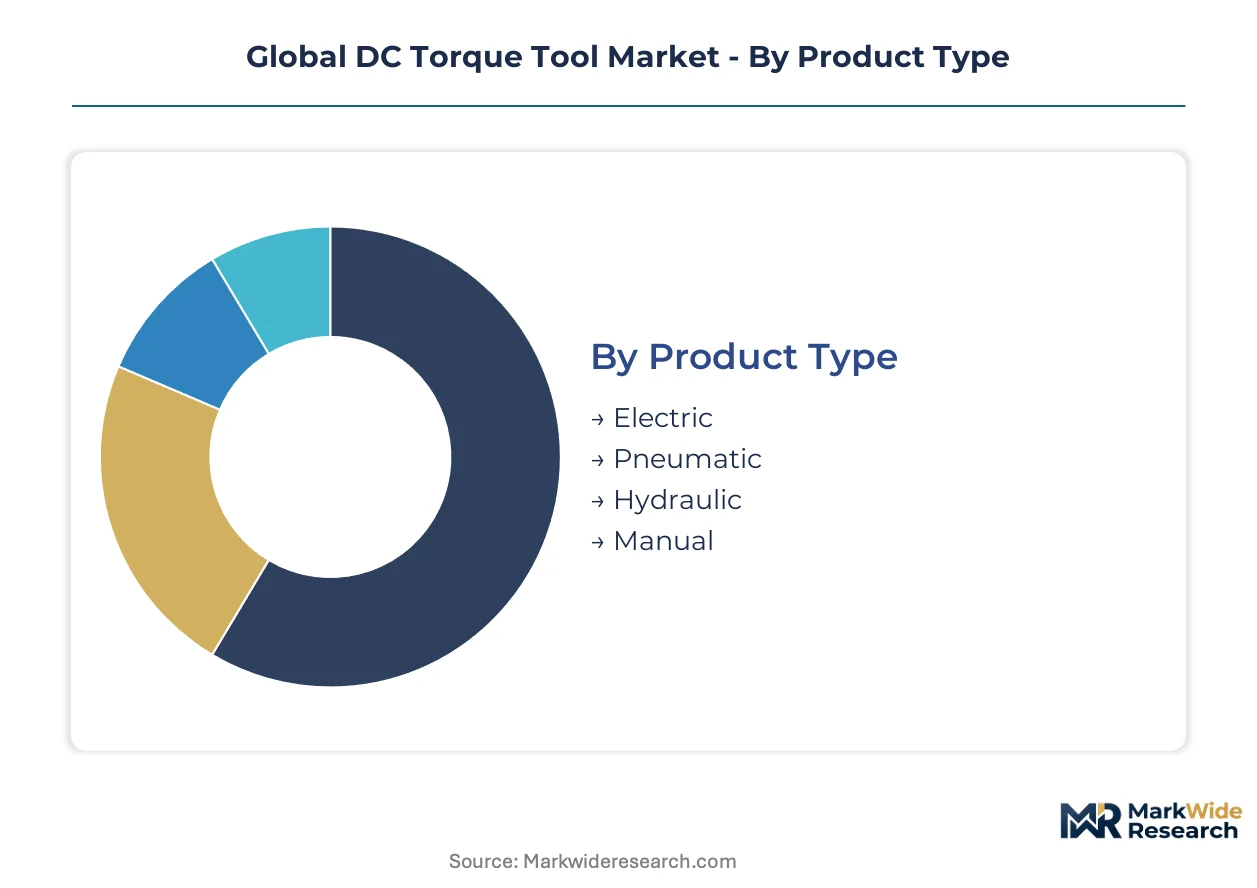
Segmentation in the DC torque tool market reveals how procurement priorities diverge across precision requirements, energy infrastructure, and regulatory exposure. Buyers select tool categories based on thermal performance mandates, traceability obligations, and integration complexity with existing factory automation.
Product Type:
Cost tier separates buyers seeking capital efficiency from those prioritizing total cost of ownership through energy recovery and maintenance reduction.
- Electric:Brushless DC motor architectures deliver calibrated rotational force with programmable torque curves and factory automation protocol compatibility. Automotive OEMs in Stuttgart and Detroit are retrofitting assembly lines with these units to eliminate pneumatic energy losses under tightening efficiency codes. Volume sits with Electric; growth tilts toward this segment as lithium-ion chemistry migrations extend runtime per charge.
- Pneumatic:Compressed-air systems rely on existing shop infrastructure and offer lower upfront capital expenditure for high-torque applications. Legacy installations in mature North American automotive plants create durable substitution friction that delays electric conversion timelines.
- Hydraulic:Fluid-pressure mechanisms generate extreme torque output for heavy machinery assembly and wind turbine construction.
- Manual:Unpowered click-type and beam wrenches serve calibration reference standards and low-volume maintenance operations.
Procurement patterns favor Electric in greenfield facilities; Pneumatic retains share in brownfield environments with sunk compressed-air investment.
End User:
Application maturity and margin concentration determine how buyers value precision certification versus throughput volume.
- Aerospace:Aircraft engine mounting and airframe assembly demand documented rotational force traceability for every fastener under FAA and EASA frameworks. German and US-based OEMs mandate calibrated accuracy that justifies premium positioning and captive metrology infrastructure.
- Automotive:Powertrain and chassis assembly lines in China, Germany, and the United States drive procurement volume for digitally connected torque systems with MES integration. MIIT efficiency codes and EU Green Deal mandates are accelerating brushless electric adoption across tier supplier networks.
- Construction:Structural steel erection and infrastructure projects favor ruggedized tools with simplified maintenance protocols.
- Manufacturing:General industrial assembly spans electronics, appliance, and machinery production with varied torque specification requirements.
Margin pools concentrate in Aerospace; expansion velocity peaks in Automotive as state-backed capacity builds reshape procurement geography.
Technology:
Intellectual property concentration and thermal management sophistication create divergent supplier qualification barriers.
- Brushless:Electronic commutation via integrated Hall-effect sensors eliminates brush wear and enables decentralized torque calibration authority. EU F-Gas Regulation prohibitions on refrigerant-based cooling are forcing thermal redesigns toward passive heat sinks and liquid loops in motor housings.
- Brush:Mechanical commutation with carbon brushes persists in cost-sensitive applications where maintenance interval tolerance remains high.
- Digital:Connected architectures with edge computing capability enable real-time torque curve analysis without cloud dependency for cybersecurity-sensitive defense programs.
- Mechanical:Spring-clutch and cam-over mechanisms provide torque limiting without electronic control for basic assembly tasks.
Technology leadership resides with Brushless; Digital architectures are climbing the fastest as IEC 62443-aligned cybersecurity certification becomes a procurement wedge.
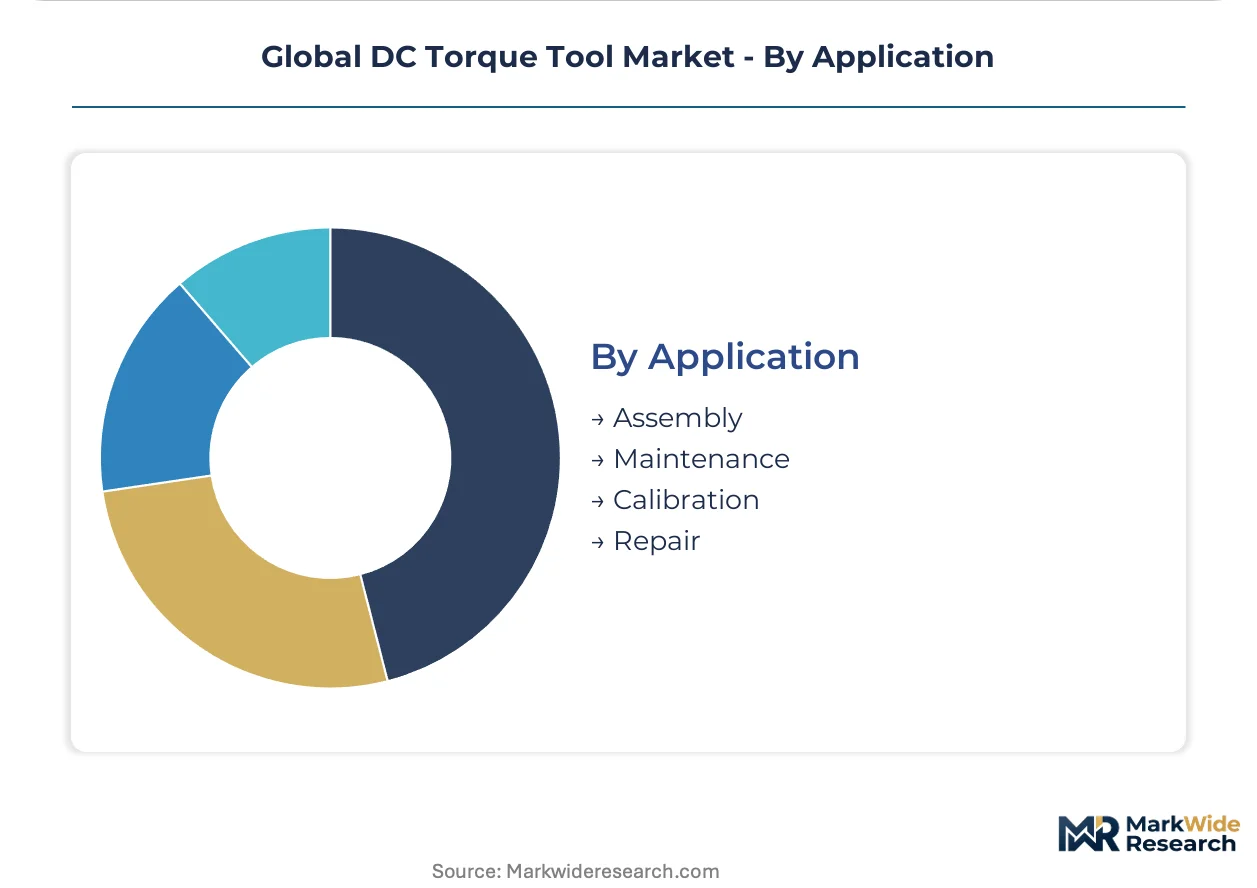
Application:
Frequency of use and error consequence severity shape how buyers weight initial capital outlay against metrology subscription costs.
- Assembly:Original equipment manufacturing lines require repeatable torque output with statistical process control integration. Tier suppliers in China's Yangtze River Delta are unbundling after-sales service contracts and negotiating per-fastener pricing that separates tool ownership from calibration responsibility.
- Maintenance:Repair operations and field service demand portable battery-powered units with rapid charge capability.
- Calibration:Metrology laboratory reference standards and production line audit functions require traceable torque measurement with ISO 17025 accreditation.
- Repair:Disassembly and rework operations utilize torque multiplication and controlled loosening functions.
Assembly commands installed base; Calibration applications are gaining share fastest as unbundled service models reshape supplier economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement clusters in Germany, China, and the United States absorb the majority of digitally connected torque system shipments, while aerospace assembly lines in France and Japan concentrate demand for calibrated precision fastening equipment.
United States
FAA airframe assembly traceability requirements and OSHA workplace noise exposure limits favor electronically controlled torque systems over pneumatic alternatives. Detroit automotive OEMs and tier suppliers are retrofitting powertrain lines with brushless electric units. The Pacific Northwest hosts aerospace fastener calibration facilities serving Boeing supply chains.
Germany
Stuttgart automotive OEMs mandate brushless motor architectures for new platform development under tightening industrial energy codes. The EU Green Deal and F-Gas Regulation prohibit refrigerant-based cooling in motor housings, forcing thermal redesigns. Hamburg aerospace suppliers prioritize CE-marked compliant units for airframe assembly traceability under EASA frameworks.
China
MIIT efficiency codes and state-backed automotive capacity expansions in the Yangtze River Delta accelerate procurement of imported digitally connected torque systems. GB standards govern market access for foreign tool manufacturers. Tier suppliers in Shanghai and Jiangsu province negotiate per-fastener pricing models that unbundle tool ownership from calibration responsibility.
Japan
METI industrial efficiency guidelines and JIS standards shape product specifications for precision assembly applications. Nagoya automotive clusters drive demand for torque tools with MES integration capabilities. Osaka-based machinery manufacturers source brushless units for export-oriented production lines serving Southeast Asian markets.
France
EASA airworthiness directives and CE marking mandates concentrate aerospace procurement in Toulouse and the Occitanie region. Airbus supply chain traceability requirements justify premium positioning for calibrated fastening systems. The country's national industrial regulator enforces electromagnetic compatibility certification for connected tools deployed in defense programs.
Global DC Torque Tool Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated technology leadership in high-precision aerospace applications and fragmented supply in construction end markets. European and North American incumbents anchor premium positioning through captive R&D in brushless motor architectures, while Asian fabricators compete on manufacturing scale for battery-powered portable units. Two dominant competitive moves define current positioning: strategic partnerships with automotive OEMs for line-fit specifications, and geographic expansion through distributor network consolidation in China's state-backed automotive corridors.
Among the named participants, Atlas Copco AB and Robert Bosch GmbH exemplify the integrated technology archetype with European origins and GmbH/AB corporate structures, while Stanley Black & Decker occupies a position representing North American scale-driven manufacturing. These three entities sit within distinct competitive vectors—Atlas Copco AB anchors precision fastening specialization, Robert Bosch GmbH represents battery management system integration, and Stanley Black & Decker exemplifies construction and automotive channel breadth—collectively illustrating how supplier qualification criteria diverge across aerospace traceability mandates and automotive volume procurement.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Apex Tool Group |
| Stanley Black & Decker |
| Robert Bosch GmbH |
| Ingersoll Rand |
| Makita Corporation |
| Hilti Corporation |
| Techtronic Industries Co. Ltd. |
| Snap-on |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal and F-Gas Regulation are gating qualified supply and premium-tier pricing access by prohibiting refrigerant-based cooling in motor housings and mandating electromagnetic compatibility certification. Buyers seeking CE-marked brushless units for aerospace traceability face constrained supplier pools that command pricing premiums, while automotive OEMs in Stuttgart and Detroit negotiate volume contracts that compress margins for standard-tier electric tools.
Pricing Analysis
Volume procurement in automotive powertrain assembly compresses per-unit margins, while aerospace traceability mandates sustain premium pricing for calibrated fastening systems with ISO 17025 documentation. Three-tier pricing structure across premium, standard, and economy levels separates EASA-compliant brushless units from basic electric tools and legacy pneumatic alternatives. Pricing pressure stems from tier suppliers in China's Yangtze River Delta unbundling after-sales service contracts and negotiating per-fastener models that shift tool ownership economics. Construction end markets exhibit highest price sensitivity; aerospace OEMs in Toulouse and Hamburg demonstrate lowest sensitivity due to fastener failure liability exposure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart and Detroit automotive clusters, while specialized distributors serve aerospace calibration facilities in the Pacific Northwest and Toulouse. Cobalt and lithium refining capacity concentrates in China, Democratic Republic of Congo, and Australia, exposing tool manufacturers to input cost volatility and supply disruption. Brushless motor architectures draw from rare-earth magnet supply anchored in China and processed in Japan, creating single-source vulnerability for Hall-effect sensor integration. Distribution runs through captive OEM service networks for aerospace traceability requirements and third-party calibration providers for tier supplier unbundling trends.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DC torque tool market sits in a technology-transition phase as brushless DC motor architectures with integrated Hall-effect sensors displace brushed mechanical commutation across automotive and aerospace assembly lines.
For Market Incumbents: Cement technology leadership in brushless motor IP by deepening R&D investment in thermal management redesigns toward passive heat sinks and liquid cooling loops mandated by EU F-Gas Regulation. Secure captive battery management system integration to defend against emerging Asian fabricators competing on manufacturing scale for portable units. Prioritize IEC 62443-aligned cybersecurity certification to maintain qualification status in defense and commercial aerospace programs. For New Entrants and Emerging Players: Tier 1 automotive suppliers in China's Yangtze River Delta represent the most penetrable channel partner type for digitally connected torque systems with MES integration capabilities. Target per-fastener pricing models that separate tool ownership from calibration responsibility, exploiting unbundling trends among procurement teams in Shanghai and Jiangsu province. Pursue white-space in battery-as-a-service subscription programs that shift capital expenditure to operational expenditure for tier suppliers retrofitting production floors. For Investors and Strategic Acquirers: MIIT efficiency code revisions accelerating domestic substitution timelines are the leading indicator that Chinese state-backed automotive capacity expansions will reshape procurement geography for imported torque systems. Mid-cap specialists with captive brushless motor R&D and established calibration infrastructure represent prime acquisition targets for platform consolidation. Monitor cobalt and lithium refining capacity announcements in Indonesia and Argentina for early signals of input cost volatility abatement.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless Motor Platform Standardization | Atlas Copco AB and Robert Bosch GmbH anchor precision fastening specialization through captive R&D architectures. |
| Battery Supply Agreement Restructuring | Lithium-ion chemistry migrations toward nickel-manganese-cobalt formulations extend runtime per charge for high-duty-cycle assembly. |
| Cybersecurity Certification Investment | IEC 62443-aligned product architectures create qualification wedges for defense and commercial aerospace programs. |
| Geographic Manufacturing Footprint Expansion | State-backed automotive corridors in China's Yangtze River Delta open procurement channels for imported digitally connected systems. |
| Aftermarket Service Unbundling | Third-party calibration providers with ISO 17025 accreditation reshape supplier economics away from OEM captive networks. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and calibration facility directors with validation against EASA airworthiness directives, FAA assembly traceability requirements, and MIIT efficiency codes. Bottom-up shipment data from brushless motor manufacturers and top-down automotive production capacity estimates triangulated market sizing across the analysis window.
Granularity-level modeling segmented the market by product type, end user, technology, and application dimensions, with additional disaggregation by regional regulatory cluster and buyer procurement archetype. CAGRs derived from fitted growth curves incorporating lithium-ion chemistry migration timelines, factory automation protocol adoption rates, and aerospace assembly line expansion announcements. Industry-specific forecast inputs included tier supplier unbundling velocity and brushless motor IP licensing friction indices.
Caveats apply where battery raw material supply disruptions, cybersecurity standard revisions, or pneumatic tool installed base persistence could materially shift the outlook. Practitioners should monitor cobalt refining capacity announcements and IEC 62443 certification adoption rates among defense contractors for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Spray Painting Machine Market
Tools
Coil Fed Punching and Cutting Machines Market
Tools
Hand Saw Market
Tools
Edge Bending Machine Market
Tools
Cordless Bandsaw Sander Market
Tools
Cordless Long Neck Grinder Market
Tools
End Mill Holder Market
Tools
Grinding Discs Market
Tools
Global Swaging Machine Market
Tools
Portable Grinders Market
Tools
Tile Saw Market
Tools
United States Machine Tools Market
Tools
Cutting Tool Inserts Market
Tools
Press Machine Market
Tools
Screw Fastener Market
Tools
Fatigue Testing Machine Market