
 China Power Tools Market | 2026-2036
China Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
China Power Tools Market Insights
Professional contractors and industrial fleet buyers is reorganizing procurement patterns away from entry-level equipment toward brushless cordless systems. Positec Tool Corporation leverages its vertical integration in motor manufacturing to control cost curves across the mid-market. Techtronic Industries anchors premium positioning through lithium-ion battery platform standardization. Jiangsu Dongcheng Power Tools dominates domestic distribution via captive wholesale networks in eastern provinces.
China power tools encompass electrically, pneumatically, or battery-driven handheld and stationary devices engineered for cutting, drilling, fastening, grinding, or surface finishing operations, typically incorporating brushless DC motors rated between 12V and 54V or compressed air systems operating at 90 PSI. These tools serve construction framing, automotive assembly line fastening torque control, and metal fabrication deburring across factory floors. Cordless tools lead volume shipment growth as lithium-ion cell energy density improvements extend runtime per charge cycle. Pneumatic tools retain durable share in heavy-duty automotive stamping plants where air infrastructure already exists. Electric corded models occupy shrinking but stable demand from price-sensitive DIY users in tier-three cities.
MIIT enforces GB standards on electromagnetic compatibility and motor efficiency that filter non-compliant imports from Southeast Asian suppliers. SAMR product safety certifications and CCC marking requirements shape market access timelines for new entrants. China's dual carbon goals pressure manufacturers toward brushless motor architectures that reduce energy loss. Stakeholders must monitor battery platform interoperability wars and provincial energy intensity audits that could reshape factory tooling upgrade cycles.
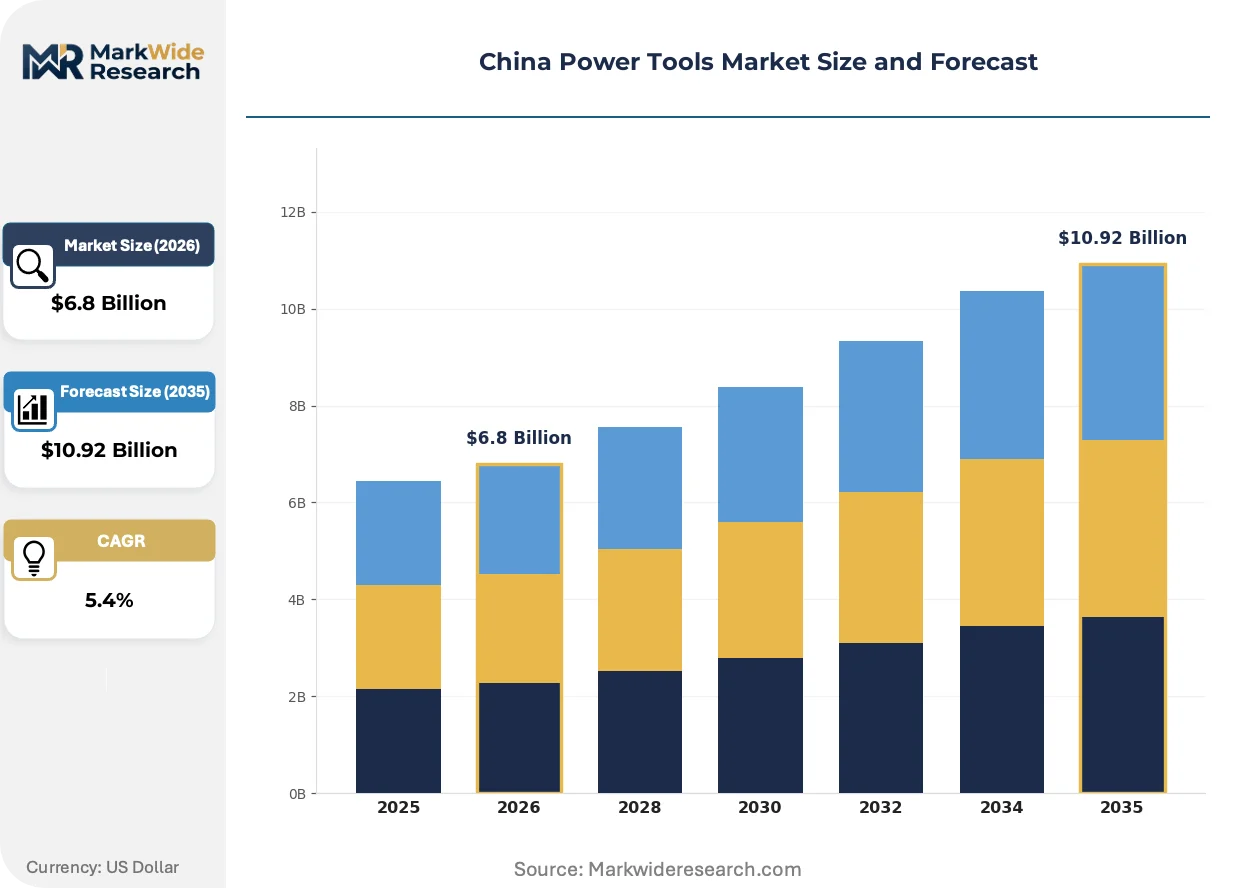
Market Dynamics
The China power tools market is undergoing a fundamental reorganization as MIIT motor efficiency mandates and dual carbon goals force brushless DC architectures to replace brushed motors across professional-grade equipment, compressing legacy supply chains while opening premium positioning for battery-platform specialists.
Growth Catalysts
- MIIT Efficiency Mandates:GB standards on electromagnetic compatibility and motor efficiency are filtering non-compliant imports, creating protected domestic demand for certified brushless systems in construction and automotive assembly.
- Lithium-Ion Energy Density Gains:Cell chemistry improvements extending runtime per charge cycle are pulling cordless tool adoption into heavy-duty metal fabrication and industrial maintenance applications previously reserved for pneumatic equipment.
- Yangtze River Delta Cluster:Concentrated manufacturing ecosystems around Shanghai and Suzhou are shortening supplier lead times and enabling rapid prototype-to-production cycles for new motor and battery platform launches.
Market Restraints
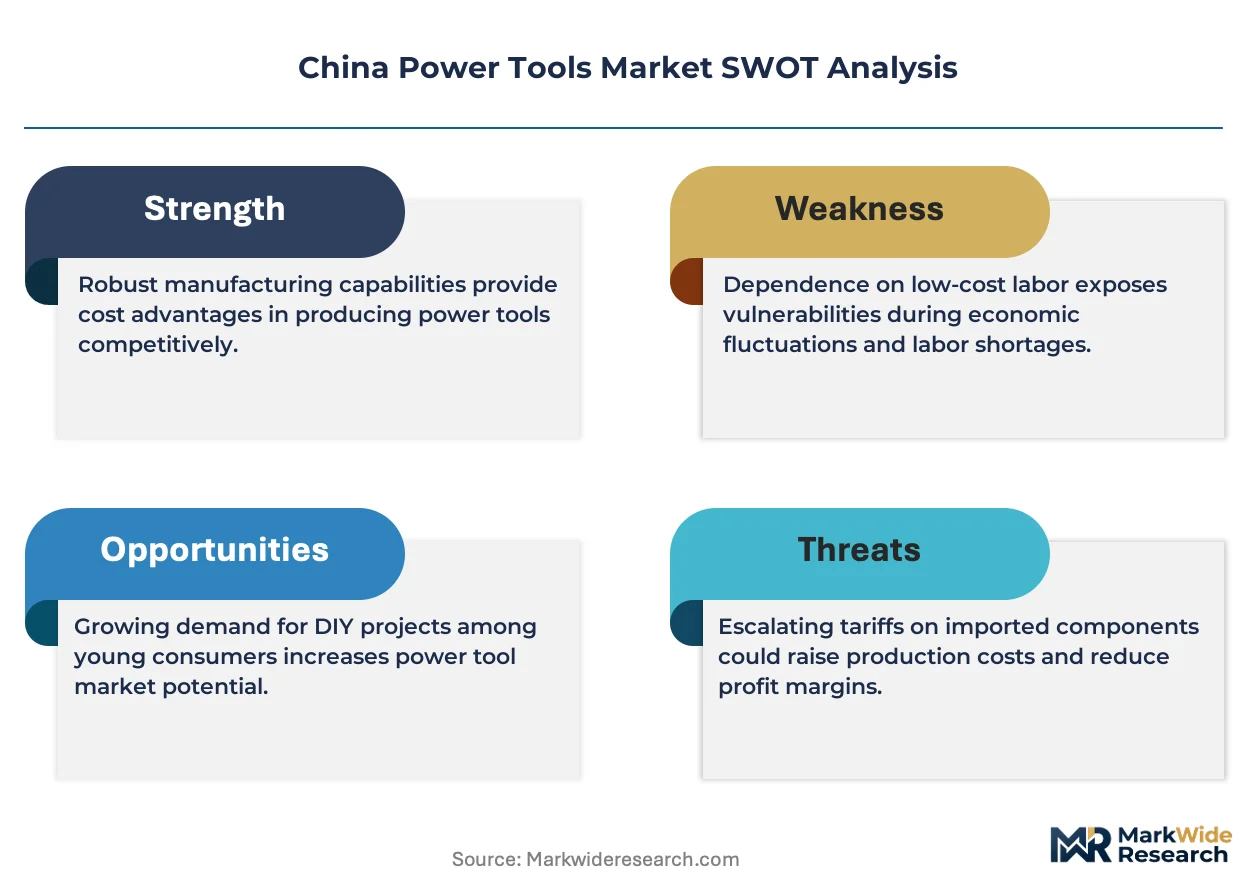
- Lithium Supply Concentration:Cathode material and cell production concentration creates input cost volatility and geopolitical exposure for domestic battery pack assemblers dependent on imported raw materials.
- Pneumatic Infrastructure Lock-In:Heavy-duty automotive stamping plants retain durable air compressor networks that slow cordless displacement despite runtime improvements, preserving legacy equipment replacement cycles.
- SAMR Certification Timelines:Product safety certifications and CCC marking requirements extend market access timelines for new entrants, creating regulatory friction against rapid technology refresh.
Strategic Opportunities
- Tier-Three DIY Penetration:Price-sensitive residential users in inland provinces remain underpenetrated by cordless platforms, presenting white space for simplified brushless tools at economy positioning.
- Battery Platform Interoperability:Cross-brand battery standardization gaps create openings for ecosystem plays where single-platform tools serve multiple power classes across drilling, fastening, and grinding.
- Provincial Energy Intensity Audits:Factory energy efficiency inspections under dual carbon implementation are accelerating tooling upgrade cycles in metal fabrication and automotive component plants.
Industry Challenges
- Brushless Motor Engineering Talent:Scarcity of power electronics and motor control firmware specialists constrains R&D velocity for mid-tier manufacturers competing against vertically integrated leaders.
- Legacy Pneumatic Integration Complexity:Hybrid fleet management combining cordless and air-powered tools creates maintenance training burdens and inventory duplication for industrial buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Power Tools Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cordless Tools, Electric Tools, Pneumatic Tools, Hand Tools End Use Industry: Construction, Manufacturing, Automotive, DIY Technology: Brushless, Lithium-Ion, Air-Powered, Hydraulic Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Direct Sales |
| Companies Covered | Positec Tool Corporation, MaxXT, Techtronic Industries, BODA, FIXTEC, Chervon Holdings, KYNKO, Geakita, Jiangsu Dongcheng Power Tools, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Power Tools Market Trends and Innovations
Brushless motor architectures and intelligent battery management systems are compressing the performance gap between cordless and corded tools, while regulatory pressure on energy efficiency accelerates obsolescence of legacy brushed motor platforms across professional segments.
Brushless DC motor technology incorporating rare-earth permanent magnets and field-oriented control algorithms is displacing brushed universal motors in 18V to 54V cordless platforms. Professional construction crews and industrial fleet buyers are standardizing on these systems for torque-critical fastening and sustained grinding applications. The displacement is compressing aftermarket parts revenue for carbon brush and commutator suppliers while shifting value capture toward semiconductor and magnet producers.
MIIT GB standards on motor efficiency and electromagnetic compatibility are tightening compliance thresholds for both domestic production and import entry. Manufacturers must redesign stator laminations and switching circuits to meet loss-reduction targets, raising engineering costs but creating regulatory moats against Southeast Asian competitors. Professional-grade cordless tools face the steepest redesign burden due to higher power density requirements.
Fleet procurement contracts are consolidating vendor relationships around single-battery-platform ecosystems rather than tool-by-tool purchasing. Industrial maintenance teams and construction contractors are negotiating multi-year supply agreements with platform-locked pricing, displacing fragmented spot buying through wholesale distributors. This concentration is most visible in the Yangtze River Delta manufacturing corridor where enterprise buyers leverage scale for dedicated technical support and training bundles.
China Power Tools Market Segmentation
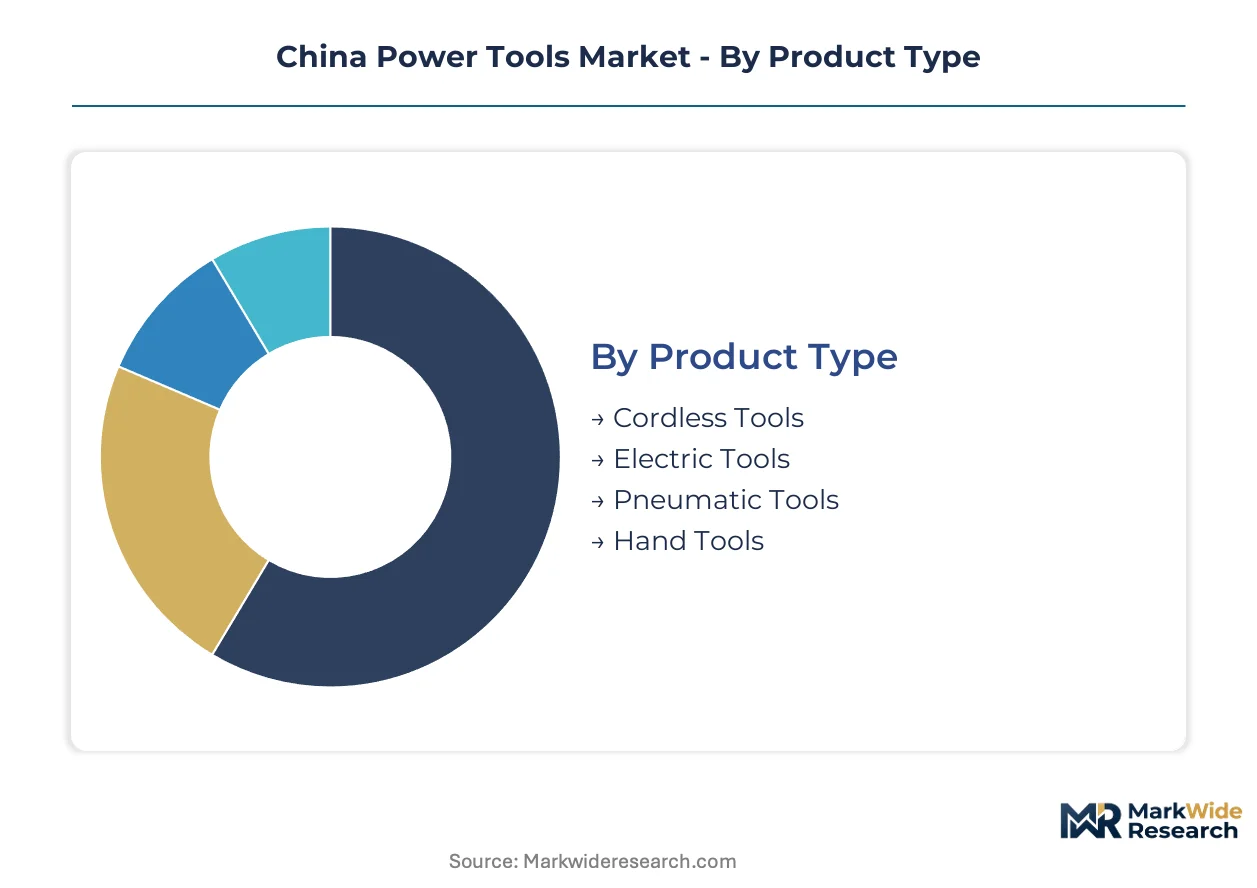
Segmentation in the China power tools market reveals how MIIT efficiency mandates and lithium-ion substitution pressures are reshaping procurement patterns across professional and consumer tiers. Distinct technology and channel preferences separate Yangtze River Delta industrial buyers from inland DIY users.
Product Type:
Cordless platforms are displacing pneumatic systems in heavy-duty applications where air infrastructure once dominated, while electric corded models face substitution risk from brushless battery architectures.
- Cordless Tools:Brushless DC motor systems operating at 18V to 54V with rare-earth permanent magnets and field-oriented control algorithms. Demand concentrates among professional construction crews in Shanghai and Suzhou for torque-critical fastening, driven by MIIT motor efficiency mandates that filter non-compliant imports.
- Electric Tools:AC-powered corded devices with brushed universal motors for sustained high-load grinding and cutting. Stable demand persists among price-sensitive DIY users in tier-three cities where battery platform costs remain prohibitive.
- Pneumatic Tools:Compressed air systems operating at 90 PSI retain durable share in heavy-duty automotive stamping plants where existing compressor infrastructure slows cordless displacement despite runtime improvements.
- Hand Tools:Manual mechanical devices for fastening, cutting, and measuring tasks requiring no power source. Budget-conscious residential users in inland provinces favor these for intermittent home repair work.
Cordless tools retain volume leadership; electric corded models hold the steepest contraction trajectory as lithium-ion energy density gains accelerate substitution.
End Use Industry:
Construction and manufacturing procurement patterns diverge sharply on battery platform standardization versus pneumatic fleet retention.
- Construction:Framing, concrete work, and finishing operations demanding portable high-torque equipment. Professional crews in the Yangtze River Delta are consolidating vendor relationships around single-battery-platform ecosystems with multi-year supply agreements.
- Manufacturing:Metal fabrication deburring and assembly line operations across factory floors. Provincial energy intensity audits under dual carbon implementation are accelerating tooling upgrade cycles in component plants.
- Automotive:Stamping plant fastening and torque control applications. Air compressor network lock-in preserves pneumatic tool share despite cordless runtime improvements extending into heavy-duty categories.
- DIY:Residential repair and home improvement tasks by non-professional users. Simplified brushless tools at economy positioning present white space for penetration in underdeveloped inland markets.
Construction leads absolute volume; manufacturing displays the steepest expansion curve as factory energy audits drive replacement demand.
Technology:
Motor architecture choices determine compliance eligibility under tightening GB efficiency standards and electromagnetic compatibility requirements.
- Brushless:Electronically commutated DC motors with permanent magnet rotors and semiconductor switching circuits. MIIT mandates on motor efficiency are forcing redesign of stator laminations and switching circuits, raising engineering costs but creating regulatory moats.
- Lithium-Ion:Rechargeable cell chemistries with energy density improvements extending runtime per charge cycle. Cell production concentration creates input cost volatility for domestic battery pack assemblers dependent on imported cathode materials.
- Air-Powered:Pneumatic actuation through compressed air distribution networks. Heavy-duty automotive plants retain these systems where existing infrastructure investment slows platform migration.
- Hydraulic:Fluid power transmission for extreme torque applications in specialized industrial settings. Niche demand persists in mining and heavy machinery maintenance where electric alternatives lack sufficient power density.
Brushless systems retain volume leadership; lithium-ion battery platforms are gaining share fastest as cell chemistry advances compress performance gaps with corded alternatives.
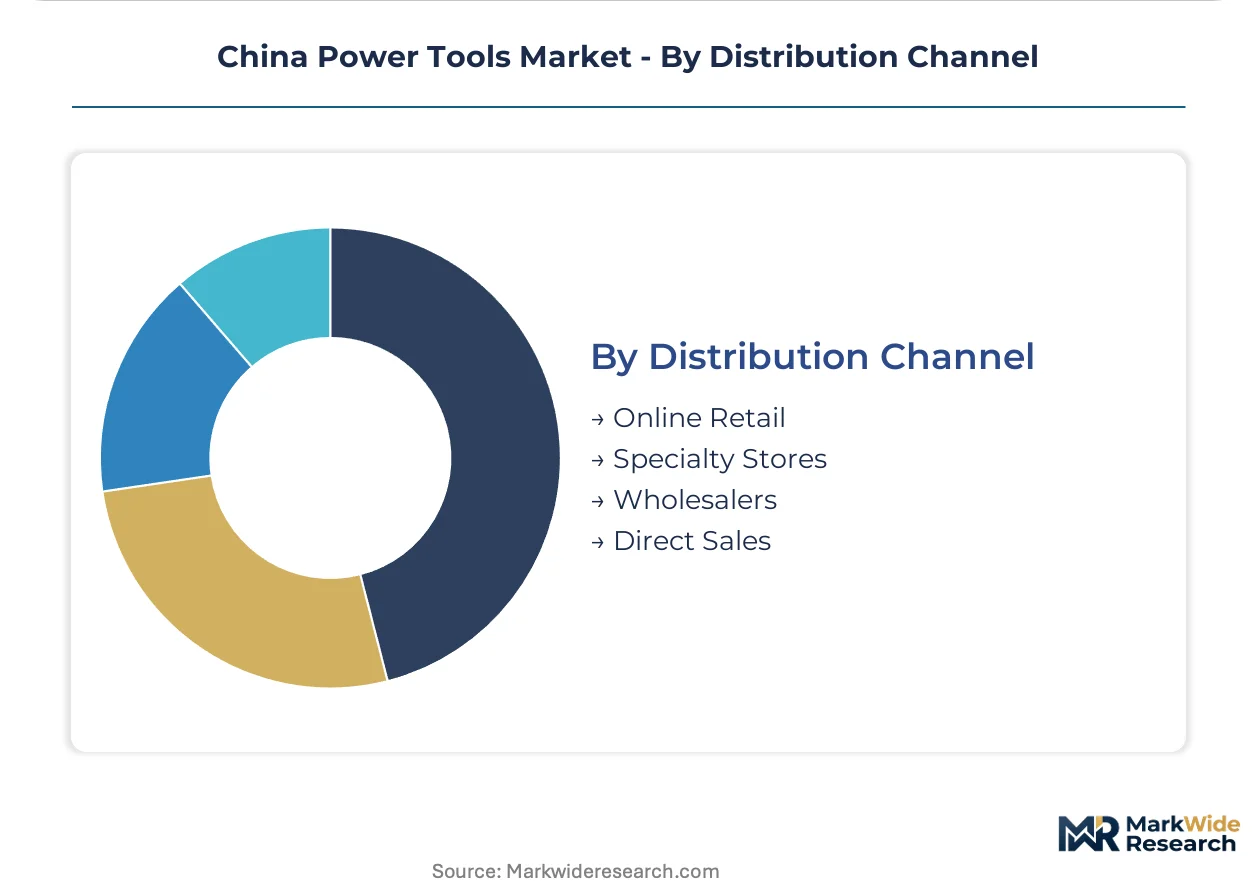
Distribution Channel:
Channel selection reflects customer scale and technical support requirements, with enterprise buyers bypassing traditional wholesale layers.
- Online Retail:E-commerce platforms serving price-comparing DIY users and small contractors. Tier-three city penetration remains underdeveloped for cordless platforms, presenting expansion opportunity.
- Specialty Stores:Dedicated tool retailers with technical consultation and after-sales service. Professional buyers in eastern provinces value hands-on product evaluation and immediate parts availability.
- Wholesalers:Distributor networks with inventory depth and credit terms for smaller trade customers. Captive wholesale networks in Jiangsu and Zhejiang provinces dominate domestic distribution for mid-market brands.
- Direct Sales:Manufacturer-to-end-user contracts with platform-locked pricing and bundled training. Industrial maintenance teams in the Yangtze River Delta manufacturing corridor leverage scale for dedicated technical support agreements.
Wholesalers retain volume leadership; direct sales channels are expanding most quickly as fleet procurement consolidates around single-vendor ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German toolmakers export precision-engineered cordless systems to Chinese construction consortiums, establishing a trade corridor that shapes competitive dynamics in the Yangtze River Delta.
Yangtze River Delta
Professional construction crews in Shanghai and Suzhou drive brushless cordless adoption for torque-critical fastening applications. MIIT GB standards on motor efficiency filter non-compliant imports, protecting domestic certified suppliers. The manufacturing cluster around Suzhou Industrial Park shortens supplier lead times for new motor and battery platform launches.
Pearl River Delta
Automotive stamping plants in Guangzhou and Shenzhen retain pneumatic tool fleets where existing air compressor infrastructure slows cordless displacement. Provincial energy intensity audits under dual carbon implementation accelerate tooling upgrade cycles in component plants. Dongguan's electronics assembly corridors concentrate demand for compact 12V to 18V cordless platforms.
Beijing-Tianjin-Hebei
Industrial maintenance teams in Tianjin port facilities negotiate multi-year supply agreements with platform-locked pricing. SAMR product safety certifications and CCC marking requirements extend market access timelines for new entrants. Beijing's state-owned construction enterprises consolidate vendor relationships around single-battery-platform ecosystems.
Sichuan-Chongqing
Metal fabrication shops in Chongqing's automotive supply chain adopt brushless systems as factory energy efficiency inspections intensify. The region's inland location creates logistics cost disadvantages for imported Southeast Asian equipment. Chengdu's growing electronics manufacturing base generates secondary demand for precision fastening tools.
Shandong Peninsula
Shipbuilding yards in Qingdao and Yantai sustain durable demand for heavy-duty pneumatic grinding equipment in marine fabrication. Price-sensitive DIY users in tier-three cities across the province favor electric corded models where battery platform costs remain prohibitive. Jinan's machinery manufacturing sector sources mid-market cordless tools through captive wholesale networks.
China Power Tools Market Competitive Landscape
Listed leaders compete with private specialists across motor control technology and battery platform development. The vendor base organizes into three tiers: vertically integrated manufacturers with captive motor production, brand marketers reliant on contract assembly, and regional distributors with wholesale network lock-in. Strategic archetypes include platform ecosystem builders, mid-market cost curve controllers, and premium positioning specialists through lithium-ion standardization. Competitive moves concentrate on backward integration into rare-earth magnet supply and direct sales channel expansion bypassing traditional wholesale layers.
Among the named players, Positec Tool Corporation and Techtronic Industries occupy positions on the premium-platform vector, while Jiangsu Dongcheng Power Tools exemplifies the domestic distribution-focused archetype. These three companies represent distinct strategic postures: one emphasizing vertical control over motor manufacturing cost curves, another anchoring premium positioning through battery platform standardization, and the third dominating eastern provincial wholesale networks. Chervon Holdings and KYNKO sit within the mid-market tier alongside FIXTEC and BODA, competing on simplified brushless architectures for price-sensitive professional segments. MaxXT and Geakita represent narrower specialization plays targeting specific voltage classes or application niches.
| Leading Market Players |
|---|
| Positec Tool Corporation |
| MaxXT |
| Techtronic Industries |
| BODA |
| FIXTEC |
| Chervon Holdings |
| KYNKO |
| Geakita |
| Jiangsu Dongcheng Power Tools |
| Others |
Pricing and Supply Chain Analysis
Scale economies in rare-earth magnet processing anchor cost floors across brushless motor tiers, concentrating upstream value capture in Jiangxi and Inner Mongolia while compressing margins for battery pack assemblers downstream. This concentration amplifies pricing power for vertically integrated manufacturers and exposes spot-market buyers to input volatility.
Pricing Analysis
Brushless cordless platforms at 18V-54V command 40-60% premiums over brushed legacy systems, while next-generation solid-state battery architectures threaten further repricing. Three-tier pricing structure across premium, standard, and economy levels separates MIIT-certified professional tools from uncertified imports and DIY-grade corded alternatives. Cost compression in the mid-market intensifies as Positec and Dongcheng exploit captive motor production. Price-sensitive DIY users in tier-three inland provinces resist cordless premiums, while Yangtze River Delta construction crews prioritize platform standardization over unit cost.
Supply Chain Analysis
China dominates cathode material refining and battery cell assembly, while Australia and Chile anchor lithium feedstock extraction. Rare-earth permanent magnets draw from Jiangxi processing hubs and Myanmar ionic clay deposits. Single-source vulnerability concentrates in NMPA-regulated battery management system semiconductors imported from Taiwan and South Korea. Distribution runs through captive wholesale networks in Jiangsu and Zhejiang provinces, with direct sales channels expanding fastest among industrial fleet buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT motor efficiency mandates and dual carbon implementation are compressing technology refresh cycles, creating a high-growth disruption window for brushless platform specialists. The regulatory inflection favors manufacturers with upstream magnet supply and firmware control capabilities.
For Market Incumbents: Secure backward integration into rare-earth magnet supply chains before Jiangxi processors consolidate further. Defend platform ecosystems by locking construction consortiums into multi-year battery interoperability agreements. The threat of cross-brand standardization wars demands preemptive channel control through dedicated technical support bundles.
For New Entrants and Emerging Players: Lead with simplified brushless architectures targeting price-sensitive DIY penetration in Sichuan-Chongqing and Shandong tier-three cities. The most penetrable white space sits in 12V-18V compact platforms for electronics assembly corridors. A go-to-market angle through online retail bypasses captive wholesale networks dominated by incumbents.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors motor control firmware specialists with GB certification pipelines. Long-term viability hinges on dual carbon compliance architecture and provincial energy audit readiness. Acquisition targets should display rare-earth magnet supply relationships and MIIT pre-certification progress. The signal to watch is provincial energy intensity audit enforcement accelerating factory tooling replacement schedules.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Jiangxi processing concentration creates margin capture opportunities for captive magnet sourcing. |
| Battery Platform Standardization | Interoperability wars in the Yangtze River Delta favor ecosystem lock-in over fragmented tool purchasing. |
| MIIT GB Certification Pre-Investment | Pre-certified product pipelines accelerate market access timelines against SAMR regulatory friction. |
| Direct Sales Channel Expansion | Industrial fleet procurement consolidation rewards manufacturer-to-end-user technical support bundling. |
| Brushless Firmware R&D Investment | Scarcity of field-oriented control specialists constrains competitive velocity for mid-tier manufacturers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MIIT regulatory filings, customs trade data, and SAMR certification databases. Primary interviews engaged plant engineers at Yangtze River Delta manufacturing facilities, procurement leads at automotive stamping plants, aftermarket service heads at wholesale distributors, and R&D directors at motor control specialists. Secondary validation drew from GB standards documentation, provincial energy intensity audit reports, and SEC filings of listed toolmakers. Bottom-up shipment estimates triangulated against top-down value projections.
Segmentation dimensions modeled include product type, end-use industry, motor technology architecture, and distribution channel across the analysis window. CAGRs derived from regression analysis of historical shipment trajectories, adjusted for MIIT mandate implementation timelines and lithium-ion energy density improvement curves. Industry-specific inputs incorporated dual carbon policy enforcement intensity and provincial manufacturing cluster concentration indices.
The analysis sits within stated boundaries; outcomes outside sustained MIIT enforcement or lithium supply disruption scenarios would require recalibration. Forecasts reflect documented assumptions on brushless adoption curves and certification timeline elasticity. Recalibration cycles align with material shifts in GB standard revision schedules and provincial energy audit enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
DIY Ball Mill Market
Tools
Industrial Hand Tools Market
Tools
Lathe Machines Market
Tools
Turning Centers Market
Tools
Masonry Cleaners Market
Tools
Caulking Gun Market
Tools
Global Standard Parts for Tool Making Market
Tools
Tile Saw Market
Tools
Bandsaw Market
Tools
Woodworking Tools Market
Tools
Set Screw Market
Tools
Woodworking Router Bits Market
Tools
Digital Cutting Machine Market
Tools
Paint Spray Guns Market
Tools
Bandsaw Machines Market
Tools
Book Binding Machines Market