
 Global Pipe and Tube Bending Machine Market | 2026-2036
Global Pipe and Tube Bending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pipe and Tube Bending Machine Market Outlook
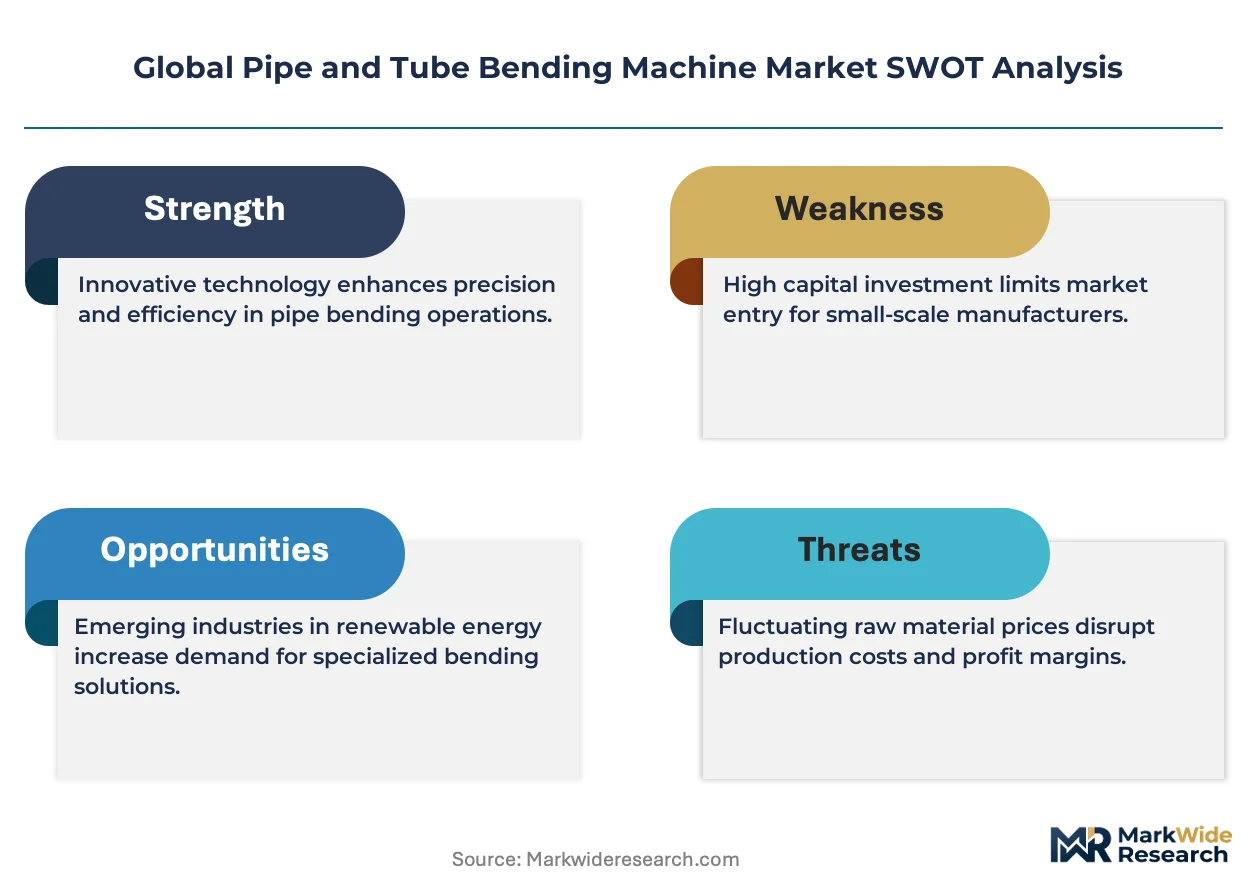
Aluminum is rebalancing product economics across the Global Pipe and Tube Bending Machine Market as automotive and aerospace engineers substitute heavier steel tubing to meet fuel-efficiency targets. BLM GROUP leverages its integrated tube-laser and bending technology portfolio to capture premium contracts in electric vehicle chassis architecture. Schwarze-Robitec anchors its position through deep specialization in heavy-wall, large-diameter systems for shipbuilding and energy infrastructure. YLM Group competes aggressively on cost-engineered CNC platforms serving mid-tier fabricators across Southeast Asian manufacturing clusters.
Pipe and tube bending machines are precision metalforming equipment that apply controlled force through rotating dies, pressure dies, and mandrels to permanently deform hollow sections along specified radii without collapsing the cross-section; modern CNC variants achieve repeatability within 0.1 degree and coordinate multi-axis interpolation for complex spatial geometries. These systems serve primarily to produce fluid conveyance networks, structural frames, and exhaust pathways across capital-intensive industries. Electric bending technology leads in new order intake among European and Japanese OEMs seeking reduced energy consumption and elimination of hydraulic oil contamination risks, while robotic bending cells represent the fastest-expanding technology segment as integrators combine articulated arms with real-time springback compensation for high-mix, low-volume production. CNC controls occupy the deepest margin pools due to software licensing, retrofit upgrades, and proprietary post-processor ecosystems that lock in recurring service revenue.
The US Department of Transportation's NHTSA fuel-economy standards and the EPA's industrial emissions frameworks shape demand by mandating lighter vehicle architectures that require more complex aluminum and composite-reinforced tube geometries. Japan's METI energy-efficiency labeling program and China's GB standards for machinery safety create divergent compliance thresholds that fragment product certification requirements across export destinations. ISO 9001 quality management and CE marking under the EU Machinery Directive establish baseline market-access filters that determine which suppliers qualify for Tier-1 automotive and aerospace vendor lists. Stakeholders must monitor how carbon-border adjustment mechanisms and evolving material-recycling mandates redefine total-cost-of-ownership calculations for bending equipment investments.
Market Dynamics
Electric bending systems are displacing hydraulic architectures across European and Japanese order books as energy-efficiency mandates harden and contamination risks trigger preventive replacement cycles in precision fabrication.
Growth Catalysts
- NHTSA Fuel-Economy Standards:US automotive OEMs are retooling exhaust and chassis lines to accommodate aluminum tube geometries that reduce vehicle mass. Mandate compliance is accelerating capital deployment toward multi-axis CNC platforms.
- EU Green Deal Decarbonization:European fabricators face binding industrial emissions targets that favor electric servo-motor bending systems with eliminated hydraulic oil dependency. German Tier-1 suppliers are modernizing production footprints ahead of enforcement deadlines.
- Aerospace Tolerance Compression:Titanium and aluminum airframe programs demand robotic bending cells with real-time springback compensation. Japanese and French aerospace clusters are expanding procurement of fully automatic systems.
Market Restraints
- Specialized Steel Input Volatility:High-grade tool steel and tungsten carbide die materials expose machine builders to commodity price swings that compress margin predictability on fixed-price contracts.
- Supply-Side Geographic Concentration:Precision ball screw and linear motion component manufacturing concentrates in German and Japanese supplier bases, creating vulnerability to regional logistics disruptions or export licensing friction.
- Technical Limitation on Composite Reinforcement:Carbon-fiber-reinforced polymer tubing exhibits unpredictable delamination under conventional mandrel bending forces, restricting equipment applicability in next-generation lightweight structures.
Strategic Opportunities
- India Manufacturing Expansion:PLI scheme incentives for automotive and aerospace component production are attracting greenfield fabrication investments that require localized bending machine supply with domestic service networks.
- Robotic-Articulated Arm Convergence:Integration of six-axis industrial robots with adaptive force control and machine-vision feedback is opening high-mix, low-volume production segments previously served by manual or semi-automatic equipment.
- Aftermarket Retrofit Channel:Legacy hydraulic machine installed bases in North American and European job shops present upgrade revenue through CNC control replacement and electric servo-kit installation.
Industry Challenges
- Multi-Axis Programming Talent Scarcity:Complex spatial geometry programming for CNC tube benders requires specialized CAM expertise that outstrips vocational training pipeline output in Midwestern US and Northern Italian manufacturing clusters.
- CE Marking and Machinery Directive Compliance Burden:Extended third-party certification timelines for safety-critical control systems delay product launches and tie up engineering resources across European market entry programs.
- Legacy System Integration Complexity:Brownfield installations require mechanical and electrical interfacing with existing material handling and quality inspection infrastructure, inflating commissioning costs and project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pipe and Tube Bending Machine Market |
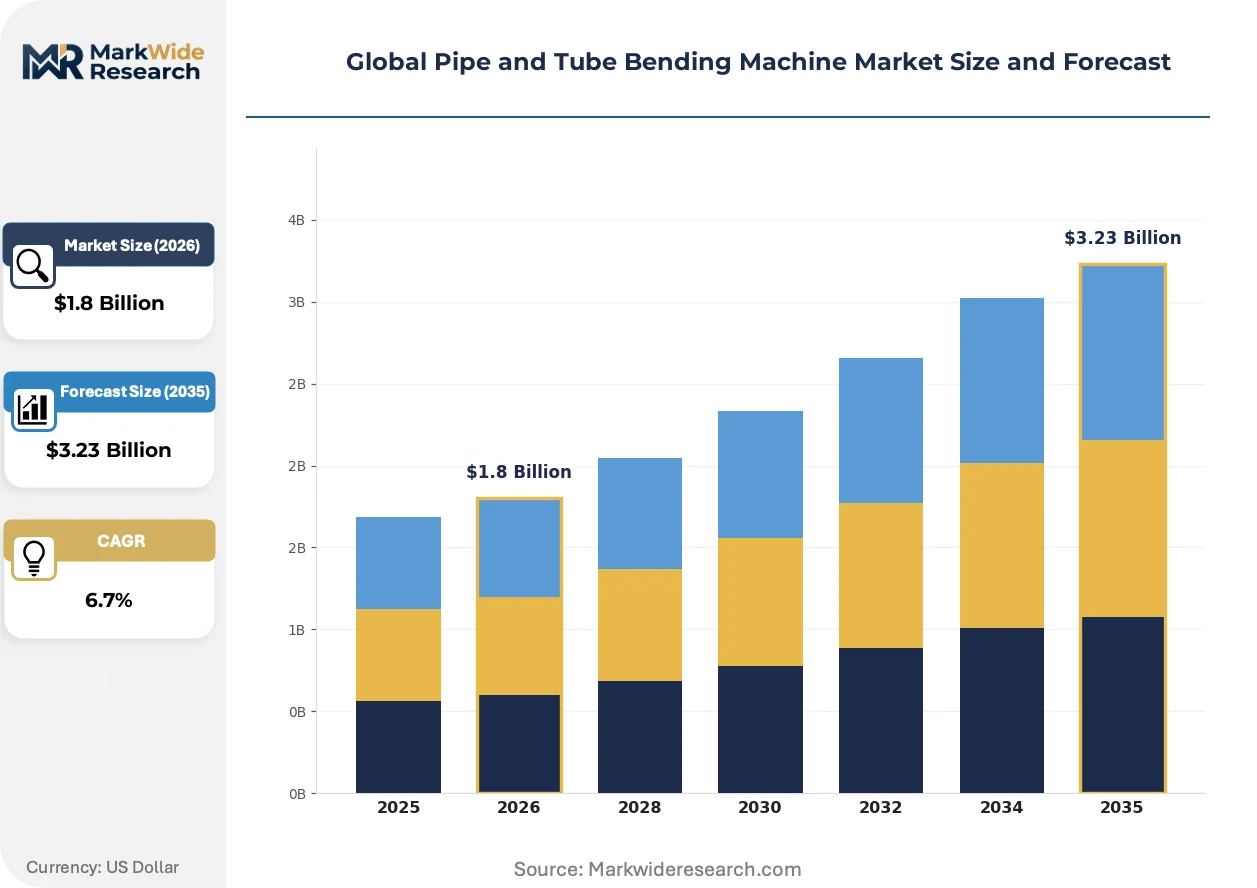
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Hydraulic, Mechanical, CNC Application: Automotive, Aerospace, Construction, Furniture Technology: Manual, Semi-Automatic, Fully Automatic, Robotic End User: OEMs, Tier-1 Suppliers, Contractors, Fabricators |
| Companies Covered | YLM Group, Schwarze-Robitec, BLM GROUP, Ercolina, Herber Engineering AB, Unison Ltd, SOCO Machinery, Numalliance, Hines Bending Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pipe and Tube Bending Machine Market Strategic Shifts
Real-time sensor feedback and predictive maintenance architectures are transforming equipment utilization models while regulatory pressure on energy intensity accelerates technology substitution timelines.
All-electric servo-motor bending technology is rewriting competitive positioning in precision metalforming. These systems eliminate hydraulic power units and oil cooling infrastructure while achieving positioning repeatability within 0.1 degree. German and Japanese automotive OEMs are specifying all-electric platforms for new chassis and exhaust line investments. The technology is compressing total-cost-of-ownership calculations by reducing energy consumption sixty percent versus conventional hydraulic architectures.
REACH substance restrictions and F-Gas Regulation phase-down schedules are tightening coolant and lubricant specifications for European bending operations. Manufacturers must reformulate metalworking fluids or transition to minimum-quantity lubrication systems to maintain compliance. German and Italian machine builders are responding with sealed electric systems that operate dry or with biodegradable lubricants, capturing preference in EU Green Deal-aligned procurement.
Service-unbundling and performance-based contracting are reshaping buyer-supplier relationships in capital equipment. Automotive Tier-1 suppliers in Germany and Japan are separating hardware acquisition from software licensing, training, and predictive maintenance subscriptions. Channel intermediaries face margin compression as OEMs build direct service organizations or partner with specialized integrators for robotic cell deployment.
Global Pipe and Tube Bending Machine Market Segmentation
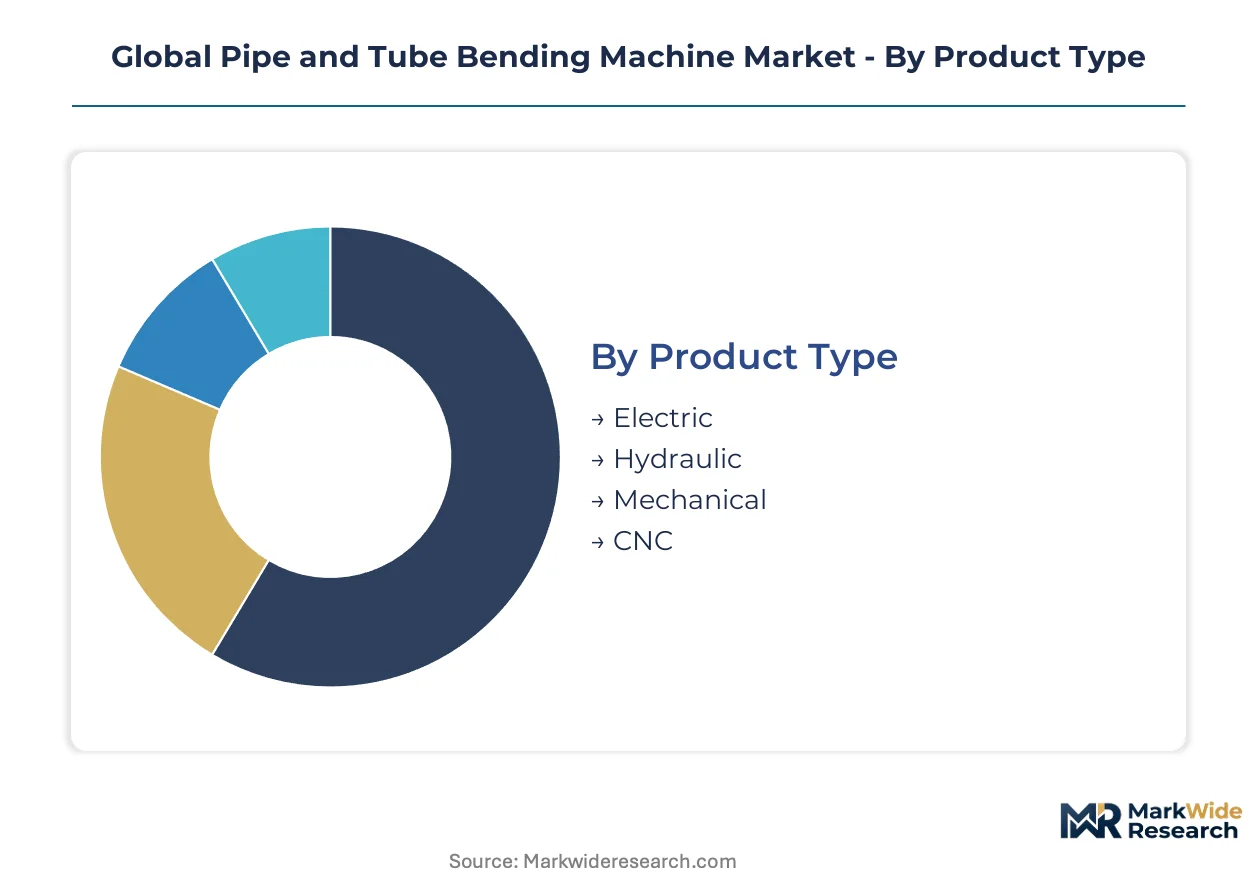
Segmentation in the pipe and tube bending machine market reveals how technology choices cascade through procurement decisions. Electric servo architectures and robotic cells command premium positioning while hydraulic legacy systems sustain volume in cost-sensitive fabrication tiers.
Product Type:
Electric bending systems integrate as standalone precision platforms requiring no hydraulic infrastructure, while mechanical and hydraulic variants embed more easily into existing brownfield shop floors with minimal electrical retrofit.
- Electric:Servo-motor architectures eliminate oil cooling systems and achieve positioning repeatability within 0.1 degree. German and Japanese automotive OEMs specify these platforms for new chassis line investments to meet EU Green Deal energy-efficiency mandates.
- Hydraulic:Conventional power-unit systems dominate installed bases across North American job shops and Southeast Asian fabrication clusters. Operators face preventive replacement cycles as REACH substance restrictions tighten coolant specifications.
- Mechanical:Lever and gear-driven machines serve entry-level workshops with minimal maintenance requirements and lower capital thresholds.
- CNC:Computer-numeric control platforms coordinate multi-axis interpolation for complex spatial geometries. Software licensing and proprietary post-processor ecosystems lock in recurring service revenue streams.
Volume placements concentrate in hydraulic systems; the faster expansion belongs to electric.
Application:
Cost tiering separates aerospace programs demanding robotic cells with real-time springback compensation from furniture producers running manual equipment on thin-wall steel tubing.
- Automotive:Exhaust system and chassis tube production lines absorb multi-axis CNC platforms. NHTSA fuel-economy standards accelerate capital deployment toward aluminum-compatible bending geometries.
- Aerospace:Titanium and aluminum airframe programs require fully automatic systems with adaptive force control. Japanese and French aerospace clusters specify equipment with sub-degree angular precision.
- Construction:Structural steel fabrication for commercial buildings and infrastructure projects utilizes heavy-duty hydraulic systems with large-diameter capacity.
- Furniture:Interior metal framing and seating components employ cost-engineered semi-automatic equipment serving high-volume, low-complexity production.
Revenue concentrates in automotive; aerospace claims the steepest expansion trajectory.
Technology:
Maturity gradients separate established manual operations from emerging robotic-articulated arm convergence that reconfigures production economics for high-mix, low-volume fabrication.
- Manual:Operator-dependent lever and crank systems persist in developing-market workshops with limited capital access and simple geometric requirements.
- Semi-Automatic:Partial mechanization with manual loading serves mid-tier fabricators across Southeast Asian manufacturing clusters where labor cost arbitrage sustains hybrid production models.
- Fully Automatic:Complete process automation with integrated material handling dominates Tier-1 supplier installations in Germany and Japan.
- Robotic:Six-axis industrial arms with machine-vision feedback and adaptive force control enable rapid changeover between part numbers. Integrators combine these cells with real-time springback compensation for precision aerospace contracts.
Installed base concentrates in semi-automatic; robotic configurations are gaining share fastest.
End User:
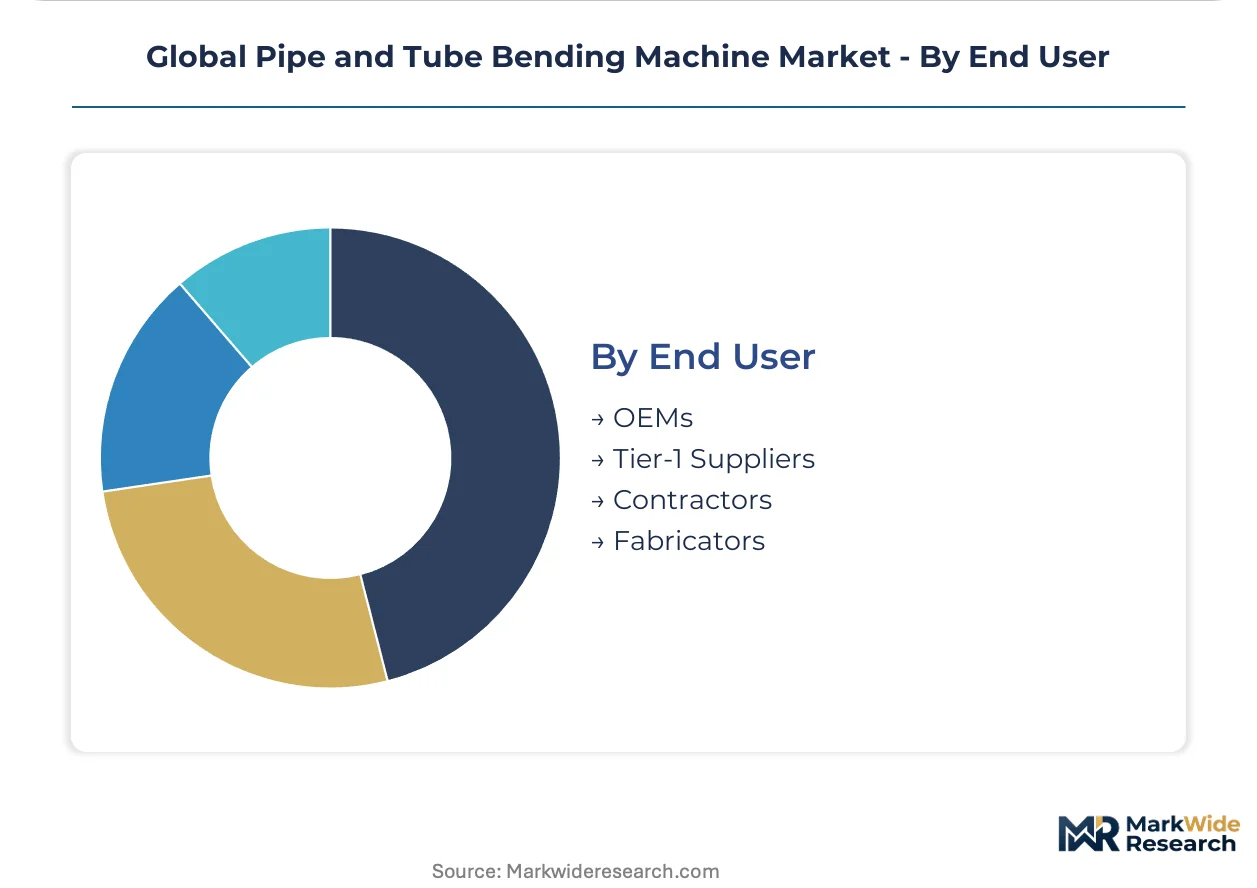
Customer type determines specification intensity and service bundling, with OEMs demanding performance-based contracting while fabricators prioritize equipment cost and local spare parts availability.
- OEMs:Original equipment manufacturers specify integrated bending cells with predictive maintenance architectures and direct service relationships. Procurement separates hardware acquisition from software licensing and training subscriptions.
- Tier-1 Suppliers:Automotive subsystem producers modernize production footprints ahead of EU industrial decarbonization enforcement deadlines. German exhaust and chassis specialists favor electric platforms with eliminated hydraulic oil dependency.
- Contractors:Project-based metal fabricators require equipment mobility and rapid setup capability across dispersed construction sites.
- Fabricators:Independent job shops sustain legacy hydraulic installed bases in North American and European clusters. Aftermarket retrofit channels present upgrade revenue through CNC control replacement and electric servo-kit installation.
Procurement volume concentrates in Tier-1 suppliers; fabricators represent the most price-sensitive tier with highest retrofit potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, Japan, and the United States where automotive OEMs and aerospace manufacturers drive precision equipment procurement. Fabricators in these markets face divergent regulatory compliance thresholds that fragment certification requirements across export destinations.
Germany
Automotive Tier-1 suppliers modernize exhaust and chassis tube production lines ahead of EU Green Deal enforcement deadlines. The EU Machinery Directive and CE marking requirements establish baseline market-access filters for equipment qualification. Stuttgart and Munich industrial clusters anchor procurement of electric servo-motor bending systems with eliminated hydraulic oil dependency.
Japan
METI energy-efficiency labeling programs push fabricators toward reduced energy consumption in metalforming operations. Japanese automotive OEMs specify all-electric platforms for new chassis investments to meet domestic carbon reduction targets. Nagoya and Osaka manufacturing clusters expand procurement of fully automatic systems with sub-degree angular precision.
United States
NHTSA fuel-economy standards mandate lighter vehicle architectures requiring complex aluminum tube geometries. EPA industrial emissions frameworks shape demand for cleaner production technologies across Midwestern fabrication corridors. Detroit and Chicago automotive clusters accelerate capital deployment toward multi-axis CNC platforms for exhaust system retooling.
China
GB standards for machinery safety create compliance thresholds that domestic and foreign suppliers must satisfy for market access. MIIT industrial upgrading programs support domestic equipment manufacturers in precision metalforming segments. Yangtze River Delta fabrication clusters absorb cost-engineered CNC platforms serving mid-tier automotive suppliers.
India
PLI scheme incentives for automotive and aerospace component production attract greenfield fabrication investments requiring localized bending machine supply. BIS certification requirements establish quality benchmarks for equipment import and domestic manufacture. Maharashtra and Gujarat industrial corridors develop domestic service networks for electric and hydraulic system deployment.
Global Pipe and Tube Bending Machine Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated technology providers commanding premium positioning in automotive and aerospace tiers while regional fabricators sustain volume in cost-sensitive markets. The vendor base organizes around three strategic archetypes: precision specialists with proprietary CNC ecosystems, diversified machinery conglomerates with bending as a portfolio vertical, and regional cost-engineered platform providers. Consolidation pressure operates through technology licensing partnerships and geographic expansion into emerging manufacturing clusters rather than horizontal acquisition activity.
Among European precision specialists, Schwarze-Robitec and BLM GROUP exemplify the integrated-technology archetype, with the former representing deep specialization in heavy-wall applications and the latter occupying a position across tube-laser and bending technology portfolios. YLM Group anchors the cost-engineered platform tier, representing aggressive positioning on CNC systems serving mid-tier fabricators across Southeast Asian manufacturing clusters. These three players illustrate how geographic origin and structural focus map to distinct competitive vectors without overlapping positioning.
| Leading Market Players |
|---|
| YLM Group |
| Schwarze-Robitec |
| BLM GROUP |
| Ercolina |
| Herber Engineering AB |
| Unison Ltd |
| SOCO Machinery |
| Numalliance |
| Hines Bending Systems |
| Others |
Value Chain & Pricing Dynamics
Electric servo-motor architectures displacing hydraulic systems across German and Japanese order books simultaneously compress energy costs and concentrate procurement leverage among Tier-1 automotive suppliers. This technology transition tightens margin pools for mid-tier fabricators while elevating pricing power for integrated CNC control vendors with proprietary post-processor ecosystems.
Pricing Analysis
Volume placements concentrate in hydraulic systems serving Southeast Asian fabrication clusters, while margin capture concentrates in electric platforms and robotic cells specified by aerospace and automotive OEMs. Three-tier pricing structure across premium, standard, and economy levels separates fully automatic robotic cells with real-time springback compensation from entry-level mechanical machines. Pricing pressure stems from REACH substance restrictions tightening coolant specifications and forcing preventive replacement cycles in legacy hydraulic installed bases. Independent job shops in North American and European clusters exhibit highest price sensitivity, while Japanese and French aerospace manufacturers demonstrate lowest sensitivity due to tolerance requirements for titanium airframe programs.
Supply Chain Analysis
Workforce availability constraints in Stuttgart and Munich industrial clusters constrain output expansion for precision ball screw and linear motion component manufacturers. Precision component manufacturing concentrates in Germany and Japan, with high-grade tool steel and tungsten carbide die materials sourcing from specialized metallurgical suppliers. Supply chain risk centers on single-source vulnerability for CNC control systems and servo-motor drives subject to export licensing friction. Distribution runs through direct OEM relationships for Tier-1 automotive suppliers, while regional distributors serve independent fabricators with localized spare parts availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Machinery Directive and CE marking requirements establish a cost-of-compliance moat that filters non-qualifying suppliers from Tier-1 automotive and aerospace vendor lists, protecting margin structures for certified incumbents.
For Market Incumbents: Anchor market position through captive supply of precision ball screw components and proprietary CNC post-processor ecosystems that lock in recurring software licensing revenue. Defend against emerging cost-engineered platform providers from Southeast Asia by accelerating electric servo-kit retrofit programs for North American and European legacy hydraulic installed bases. Prioritize certification investment ahead of evolving carbon-border adjustment mechanisms. For New Entrants and Emerging Players: The premium-to-economy price-point gap in robotic bending cells creates white-space opportunity for mid-tier integrators combining six-axis industrial arms with adaptive force control. Target India's Maharashtra and Gujarat industrial corridors where PLI scheme incentives attract greenfield fabrication investments requiring localized bending machine supply with domestic service networks. Pursue partnership-based go-to-market models with established channel intermediaries facing margin compression from direct OEM service organizations. For Investors and Strategic Acquirers: Exit pathways concentrate in technology licensing partnerships and geographic expansion into emerging manufacturing clusters rather than horizontal acquisition activity. Long-term viability favors precision specialists with integrated tube-laser and bending technology portfolios serving electric vehicle chassis architecture programs. Watch for carbon-border adjustment mechanism implementation as an inflection indicator for equipment replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Servo-Kit Retrofit Programs | Captures aftermarket revenue from legacy hydraulic installed bases in North American job shops. |
| Robotic Cell Integration Partnerships | Combines six-axis industrial arms with machine-vision feedback for high-mix aerospace contracts. |
| Domestic Service Network Expansion | Secures PLI-linked automotive and aerospace fabrication investments in Maharashtra and Gujarat corridors. |
| Proprietary CNC Control Development | Locks in recurring software licensing revenue through proprietary post-processor ecosystems. |
| Biodegradable Lubricant System Certification | Maintains EU Green Deal compliance for sealed electric platforms operating dry or with REACH-aligned fluids. |
Study Parameters
Independent corroboration across maintenance directors at Tier-1 automotive suppliers, plant engineers at aerospace fabrication clusters, OEM procurement teams specifying electric platforms, and aftermarket service heads managing legacy hydraulic bases underwrites the qualitative findings. Secondary validation draws from EU Machinery Directive certification databases, SEC filings of diversified machinery conglomerates, German and Japanese industrial production indices, and customs records of precision ball screw imports. Bottom-up equipment shipment tallies and top-down industrial capex surveys were reconciled to establish market sizing boundaries.
Rate-of-change decomposition across product type, application, technology, and end-user segmentation dimensions structured the analytical framework throughout the forecast period. CAGRs were derived from regression analysis against automotive production forecasts, aerospace airframe program announcements, and industrial energy-efficiency mandate timelines. Industry-specific forecast inputs incorporated NHTSA fuel-economy standard compliance deadlines and EU Green Deal industrial decarbonization enforcement thresholds.
Inputs from primary stakeholder interviews and secondary regulatory databases were available through the study window; gaps in real-time springback compensation technology adoption rates and robotic cell deployment timelines introduce uncertainty bands around precision equipment penetration forecasts. A small set of triggers—including carbon-border adjustment mechanism implementation and REACH substance restriction phase-down schedules—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Mill Liner Market
Material Handling Equipment
Europe Conveyors Market
Material Handling Equipment
Global Industrial Lifting Equipment Market
Material Handling Equipment
Industrial Carts Market
Material Handling Equipment
Industrial Static Equipment Market
Material Handling Equipment
Bulk Material Handling System Market
Material Handling Equipment
High-Performance Seals Market
Material Handling Equipment
Robotic Palletizers Market
Material Handling Equipment
Portable Forklift Ramps Market
Material Handling Equipment
Water Hose Market
Material Handling Equipment
Belt Scales Market
Material Handling Equipment
Dewatering Screen Market
Material Handling Equipment
Hi Lift Jack Market
Material Handling Equipment
Europe Port Equipment Market
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
Tube Rotator Market