
 Thread Milling Machine Market | 2026-2036
Thread Milling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Thread Milling Machine Market Analytics
Precision-grade CNC thread milling is rotating toward micron-level tolerance classes as aerospace and medical device OEMs reject conventional tapping for critical bores. DMG Mori leverages its integrated spindle technology to dominate high-value five-axis thread milling cells in European aerospace supply chains. Yamazaki Mazak Corporation anchors the Japanese market with hybrid automation packages that merge robotic loading with in-process gauging. Sandvik Coromant competes through captive supply of coated carbide thread mill inserts paired with application engineering services.
A thread milling machine cuts internal or external threads via a rotating multi-tooth cutter fed along a helical interpolation path, achieving pitch diameters within ISO 965 tolerance bands while managing chip evacuation through through-spindle coolant delivery at pressures exceeding 70 bar. CNC Mills lead product type revenue by commanding premium pricing for simultaneous five-axis thread profiles in titanium and Inconel. Automated Solutions within the technology dimension represent the fastest-expanding margin pool as manufacturers retrofit legacy vertical mills with closed-loop adaptive feed systems. Oil and Gas end users concentrate demand in large-scale custom configurations for subsea connector threading where API specification Q1 compliance is mandatory.
ISO 3408 governs ball screw accuracy grades that directly determine thread milling machine positioning repeatability, while the EU Machinery Directive mandates CE-marked safeguarding for automated tool changing cycles. The US Occupational Safety and Health Administration enforces lockout-tagout protocols during thread mill insert indexing that shape maintenance access design. China's Ministry of Industry and Information Technology promotes domestic GB standard adoption for machine tool accuracy verification. Stakeholders must monitor how dual carbon goals in Beijing and the EU Green Deal's embodied carbon reporting requirements redirect capital toward energy-efficient direct-drive spindle architectures.
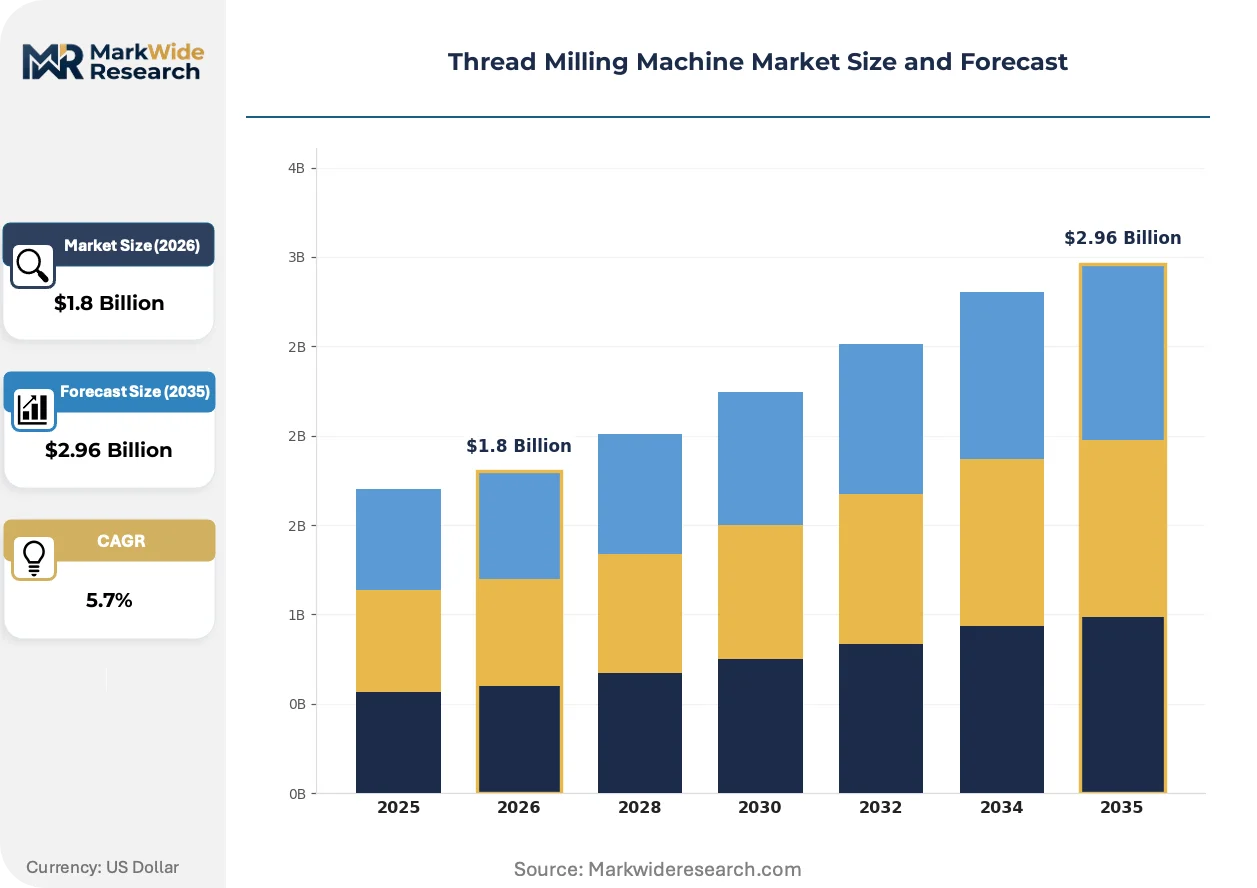
Market Dynamics
Precision tolerance mandates from aerospace OEMs and medical device regulators are compressing acceptable thread pitch deviation windows, forcing machine tool builders to re-engineer spindle positioning systems and thermal compensation algorithms.
Growth Catalysts
- Aerospace Titanium Machining:German engine manufacturers are expanding five-axis thread milling capacity for compressor disc bores, rejecting conventional tapping due to chip evacuation failures in Ti-6Al-4V.
- EU Machinery Directive:CE-marked safeguarding requirements for automated tool changing cycles are accelerating retrofit demand for legacy vertical machining centers with non-compliant guarding.
- ISO 3408 Ball Screw Standards:Tightened accuracy grades for positioning repeatability are pulling machine tool builders toward direct-drive spindle architectures that eliminate mechanical transmission error.
Market Restraints
- Carbide Insert Supply Concentration:Coated carbide thread mill insert production clusters in Sweden and Japan create vulnerability for European and North American machine shops facing allocation constraints.
- High-Pressure Coolant Infrastructure:Through-spindle coolant delivery systems requiring 70+ bar pressure demand capital-intensive pump and filtration retrofits that smaller toolrooms defer.
- Electrical Discharge Machining Substitution:EDM threading of hardened steels above 55 HRC captures applications where carbide tool life economics fail, particularly in mold and die segments.
Strategic Opportunities
- India Defense Localization:The country's PLI scheme for machine tool manufacturing creates white space for thread milling cell suppliers targeting ordnance factory modernization programs.
- Hybrid Automation Convergence:Robotic loading paired with in-process gauging enables unmanned threading of medical implant lots, capturing orthopedic OEM demand for validated process documentation.
- EU Green Deal Embodied Carbon Reporting:Energy-efficient direct-drive spindle architectures qualify for preferential financing under the bloc's sustainable manufacturing incentive frameworks.
Industry Challenges
- Multi-Axis Programming Talent Scarcity:Helical interpolation programming for simultaneous five-axis thread profiles requires CAM expertise that vocational pipelines in manufacturing regions fail to replenish.
- API Q1 Certification Timelines:Oil and gas equipment suppliers face 18-24 month audit cycles for subsea connector threading cells, compressing bid-to-delivery windows and straining working capital.
- Legacy Control Integration Friction:Retrofitting closed-loop adaptive feed systems onto machines with proprietary CNC architectures demands custom macro programming that extends commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thread Milling Machine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Mills, Horizontal Mills, Universal Mills, CNC Mills Technology: Computer Numerical Control, Manual Control, Automated Solutions, Hybrid Technology End User: Aerospace, Automotive, Machinery Manufacturing, Oil & Gas Size: Small Scale, Medium Scale, Large Scale, Custom Size |
| Companies Covered | DMG Mori, Haas Automation, Makino Milling Machine, Yamazaki Mazak Corporation, Okuma Corporation, Hurco Companies, EMAG Group, FANUC Corporation, Sandvik Coromant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thread Milling Machine Market Evolving Landscape
Adaptive process control and spindle thermal compensation are converging to eliminate human intervention in precision threading cycles, compressing the gap between machine capability and aerospace tolerance specifications.
Direct-drive spindle technology is displacing belt-driven and geared headstock configurations in high-value thread milling applications. Aerospace tier-one suppliers in Germany and Japan are specifying integrated motor spindles for titanium engine component cells. The elimination of mechanical transmission elements is compressing thermal drift error bands below two microns over eight-hour production runs.
China's MIIT is accelerating GB standard adoption for machine tool accuracy verification, mandating domestic certification for equipment deployed in state-sponsored automotive toolrooms. The policy is fragmenting procurement specifications between GB-compliant domestic machines and ISO-certified imports. European builders are responding with parallel GB/ISO dual-certification programs for Yangtze River Delta machining clusters.
Buyer consolidation among medical device OEMs is compressing supplier qualification timelines and unbundling after-sales service contracts. Large orthopedic manufacturers in Switzerland and the United States are demanding standalone spare parts pricing and remote diagnostic access rather than bundled maintenance agreements. This pattern is most visible in contract machining hubs serving FDA-regulated implant segments.
Thread Milling Machine Market Segmentation
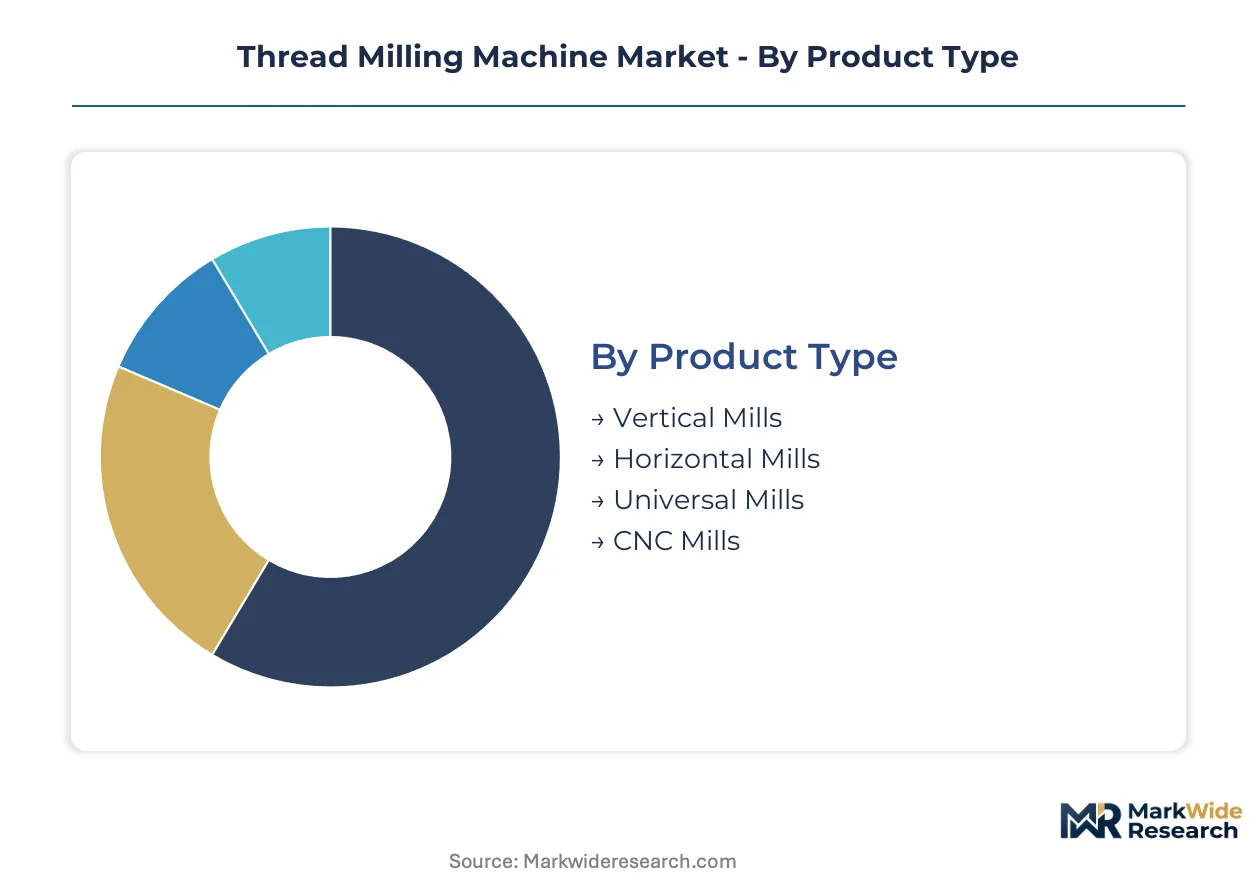
Thread milling machine procurement patterns diverge sharply between domestic toolrooms seeking standardized configurations and export-oriented aerospace suppliers demanding certified precision cells. Segmentation reveals how capital allocation, regulatory compliance, and spindle technology preferences reshape competitive positioning across machine tool categories.
Product Type:
Domestic automotive toolrooms in China's Yangtze River Delta favor locally certified vertical configurations, while German aerospace tier-one suppliers import five-axis horizontal cells for titanium engine component machining.
- Vertical Mills:Fixed-column designs with Z-axis quill feed dominate small-to-medium batch production in contract machining environments. Demand concentrates in China's state-sponsored automotive toolrooms where GB standard certification reduces import duty exposure.
- CNC Mills:Simultaneous five-axis machines with helical interpolation capability command premium positioning in European aerospace supply chains. DMG Mori and Yamazaki Mazak Corporation anchor this segment through integrated spindle architectures that eliminate mechanical transmission error.
- Horizontal Mills:Pallet-based configurations with automatic tool changers serve high-volume production lines.
- Universal Mills:Swiveling headstock designs bridge milling and threading operations for general-purpose job shops.
CNC Mills holds the largest share; momentum sits with Vertical Mills.
Technology:
Cost tiers separate legacy manual installations in price-sensitive toolrooms from adaptive automation packages capturing medical device validation requirements.
- Automated Solutions:Closed-loop adaptive feed systems with in-process gauging enable unmanned threading of orthopedic implant lots. Swiss and US orthopedic OEMs demand validated process documentation that retrofitted legacy mills cannot provide.
- Computer Numerical Control:Programmable helical interpolation with thermal compensation algorithms dominates aerospace tolerance bands. ISO 3408 ball-screw accuracy grades pull builders toward direct-drive spindle architectures that compress positioning drift below two microns.
- Hybrid Technology:Robotic loading merged with automated gauging captures medical device contract manufacturers.
- Manual Control:Handwheel-fed configurations persist in prototype shops and vocational training centers.
Computer Numerical Control holds the largest share; Automated Solutions are climbing the fastest.
End User:
Application-specific requirements from oil and gas subsea connectors to aircraft engine discs create divergent specification clusters across industrial segments.
- Aerospace:Ti-6Al-4V compressor disc bores demand through-spindle coolant delivery exceeding 70 bar for chip evacuation. German engine manufacturers reject conventional tapping due to galling failures, expanding five-axis thread milling capacity.
- Oil & Gas:API specification Q1 compliance mandates 18-24 month certification cycles for subsea connector threading cells. Large-scale custom configurations dominate this segment where working capital constraints compress bid-to-delivery windows.
- Automotive:Domestic toolrooms in China's machining clusters drive volume demand for standardized configurations.
- Machinery Manufacturing:General-purpose threading of alloy steel components serves capital equipment builders.
Aerospace holds the largest share; Oil & Gas shows the steepest expansion trajectory.
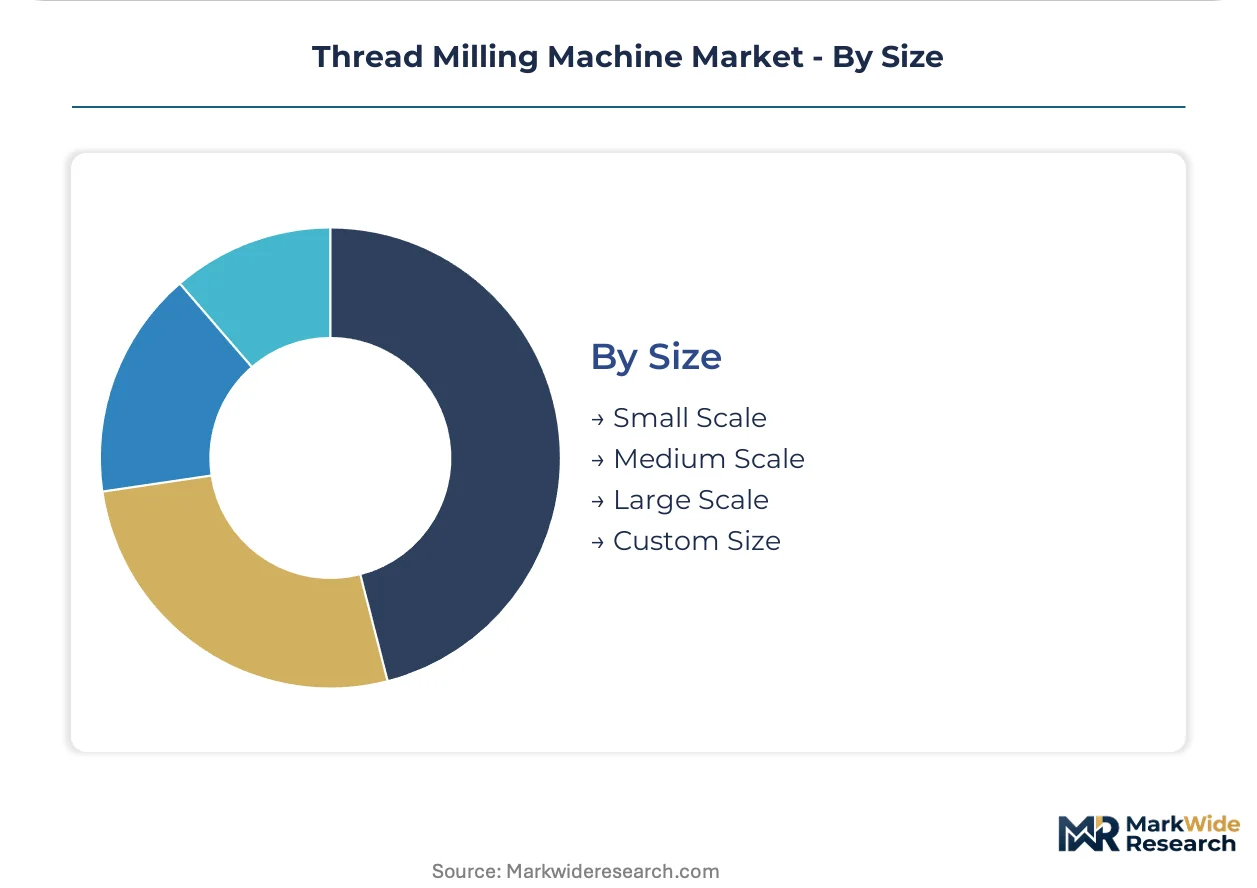
Size:
Volume concentration in medium-scale platforms contrasts with margin capture in custom configurations engineered for specific bore geometries.
- Large Scale:Gantry-mounted machines with 2000mm+ X-axis travel thread subsea wellhead connectors. Oil and gas equipment suppliers in Norway and Brazil specify these configurations for API-compliant offshore installations.
- Custom Size:Application-engineered cells with modified work envelopes capture orthopedic implant manufacturers requiring validated process documentation. Buyer consolidation among Swiss and US medical device OEMs compresses supplier qualification timelines.
- Medium Scale:800-1500mm travel machines dominate general-purpose production environments.
- Small Scale:Benchtop configurations serve precision instrument makers and dental implant machine shops.
Medium Scale holds the largest share; Custom Size gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German machine tool exports supply aerospace threading cells to tier-one suppliers across North America and Asia, while Japanese builders ship five-axis platforms to medical device manufacturers in Switzerland and the United States.
Germany
Aerospace engine manufacturers in Bavaria and Baden-Württemberg are expanding Ti-6Al-4V compressor disc threading capacity. The EU Machinery Directive mandates CE-marked safeguarding for automated tool changing cycles. Stuttgart's precision machining cluster anchors European demand for direct-drive spindle architectures.
China
Domestic automotive toolrooms in the Yangtze River Delta drive volume procurement of GB-standard vertical mills. MIIT accelerates domestic certification requirements for state-sponsored machining clusters. Shanghai and Suzhou machining hubs concentrate demand for locally certified equipment serving BYD and NIO supply chains.
United States
Orthopedic OEMs in the Midwest and Northeast demand validated process documentation for unmanned threading of implant lots. OSHA enforces lockout-tagout protocols during thread mill insert indexing. Greater Boston's medical device corridor concentrates contract machining demand for FDA-regulated titanium components.
Japan
Hybrid automation packages merge robotic loading with in-process gauging for automotive and medical applications. METI promotes JIS standard adoption for machine tool accuracy verification. Nagoya's Chubu region hosts concentrated demand from Toyota and Honda toolrooms seeking micron-level tolerance classes.
India
Defense ordnance factory modernization programs create white space for thread milling cell suppliers. The PLI scheme for machine tool manufacturing offers production-linked incentives for domestic assembly. Tamil Nadu and Maharashtra machining clusters are expanding capacity to serve indigenization mandates.
Thread Milling Machine Market Competitive Landscape
Listed leaders compete with private specialists across spindle technology and automation integration tiers. The vendor base stratifies between integrated builders commanding aerospace premium pricing and regional fabricators serving price-sensitive automotive toolrooms. Three archetypes dominate: full-platform builders with captive spindle technology, automation integrators retrofitting legacy mills, and insert specialists pairing tooling with application engineering. Capacity expansion in Asian machining clusters and strategic partnerships for GB-standard certification represent the dominant competitive vectors.
Within the full-platform builder tier, DMG Mori and Yamazaki Mazak Corporation exemplify integrated spindle architectures that eliminate mechanical transmission error. Among Japanese automation specialists, FANUC Corporation occupies a position in control system supply that shapes retrofit compatibility across third-party installations. Sandvik Coromant represents the tooling-centric archetype, anchoring competitive positioning through coated carbide insert supply paired with process engineering services rather than machine platform ownership.
| Leading Market Players |
|---|
| DMG Mori |
| Haas Automation |
| Makino Milling Machine |
| Yamazaki Mazak Corporation |
| Okuma Corporation |
| Hurco Companies |
| EMAG Group |
| FANUC Corporation |
| Sandvik Coromant |
| Others |
Value Network & Pricing Analysis
Direct-drive spindle substitution for belt-driven configurations is compressing mechanical transmission costs while simultaneously shifting supply geography toward German and Japanese motor-spindle specialists and flattening price premiums for positioning repeatability below two microns.
Pricing Analysis
Technology-generation pricing gaps separate legacy belt-driven vertical mills from integrated direct-drive five-axis platforms and emerging adaptive feed retrofits. Pricing stratifies across premium aerospace cells with ISO 3408 certification, standard automotive toolroom configurations, and economy-grade manual machines for prototype shops. Cost compression in the standard tier is intensifying because Chinese GB-standard domestic mills are eroding import duty advantages for European builders. Aerospace tier-one suppliers in Germany show the least price sensitivity due to tolerance mandates, while Indian defense toolrooms exhibit highest sensitivity under PLI scheme budget constraints.
Supply Chain Analysis
Inbound logistics costs from Shanghai port congestion and container availability constraints on the Asia-Europe trade lane are elevating landed costs for Japanese and Chinese-built machines entering Stuttgart and Chicago machining clusters. Supply concentrates in Germany for high-value aerospace cells, Japan for hybrid automation packages, and China for GB-standard vertical mills. Production rests on coated carbide insert supply from Sweden, high-pressure coolant pump systems from Germany, and ball-screw assemblies from Japan. Single-source vulnerability in coated carbide thread mill inserts creates allocation risk for European and North American machine shops. Distribution runs through OEM-direct channels for certified aerospace cells and regional distributors for automotive toolroom equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities dominate hardware economics as validated process documentation and remote diagnostic contracts expand faster than machine platform sales among orthopedic OEMs and aerospace tier-one suppliers.
For Market Incumbents: Compound defensive positioning by deepening captive supply of coated carbide inserts and application engineering services to offset Sandvik Coromant's tooling-centric model. Expand GB/ISO dual-certification capacity in Yangtze River Delta machining clusters before domestic Chinese builders consolidate state-sponsored automotive toolroom procurement. Vertical integration into direct-drive spindle production insulates against Japanese motor-spindle supply constraints. For New Entrants and Emerging Players: API Q1 certification fast-tracks for oil and gas subsea connector threading cells unlock 18-24 month audit cycles that incumbent suppliers struggle to compress. White space concentrates in India's PLI-scheme defense ordnance factory modernization programs, where domestic assembly incentives reduce import cost disadvantages. Target medical device contract machining hubs in Greater Boston and Switzerland with standalone spare parts pricing and remote diagnostic access rather than bundled maintenance agreements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automation integrators retrofitting legacy vertical mills with closed-loop adaptive feed systems for medical device validation requirements. Long-term viability hinges on recurring revenue from process documentation and aftermarket service contracts rather than one-time machine sales. Watch for inflection when orthopedic OEM buyer consolidation accelerates unbundling of after-sales service contracts across Swiss and US implant manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| GB/ISO Dual-Certification Investment | European builders capture Yangtze River Delta automotive toolroom procurement under MIIT domestic certification mandates. |
| Direct-Drive Spindle Capacity Expansion | Integrated motor architectures eliminate mechanical transmission error for Ti-6Al-4V aerospace threading applications. |
| Application Engineering Service Layer | Coated carbide insert suppliers pair tooling with process documentation to capture medical device validation demand. |
| Hybrid Automation Convergence | Robotic loading merged with in-process gauging enables unmanned threading of orthopedic implant lots. |
| API Q1 Certification Fast-Track | Oil and gas equipment suppliers compress 18-24 month audit cycles for subsea connector threading cells. |
Research Methodology
Initial hypotheses were tested against primary input from aerospace procurement managers, medical device manufacturing engineers, machine tool aftermarket service heads, and automotive toolroom supervisors and refined through secondary validation against SEC filings of listed builders, MIIT policy circulars on GB standard adoption, API specification Q1 documentation, and ISO 3408 ball-screw accuracy grade tables. Bottom-up demand modeling from end-user segment interviews triangulated against top-down supply-side capacity assessments.
Variance-decomposition across the projection horizon isolates volume and value drivers by product type, technology tier, end-use industry, and regional machining cluster. Segmentation dimensions modeled include machine configuration, control architecture, spindle drive technology, and application-specific certification requirements. CAGRs were derived from installed base turnover rates and replacement demand elasticities observed in aerospace and medical device supply chains, incorporating EU Machinery Directive compliance timelines and China's dual carbon policy impacts on capital allocation.
Underlying assumptions cover sustained aerospace titanium machining demand, stable coated carbide insert supply from Swedish and Japanese production clusters, and continued MIIT enforcement of GB standard certification, with deviation risk concentrated in electrical discharge machining substitution for hardened steel applications above 55 HRC. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Automotive Torque Tools Market
Tools
Portable Milling Machine Market
Tools
Europe Stump Cutter/Grinder Market
Tools
Cordless Trim Routers Market
Tools
Industrial Ladder Market
Tools
Cutting Equipment Market
Tools
Tile Cutter Market
Tools
Edge Banding Machine Market
Tools
Woodworking Circular Saw Blades Market
Tools
Rotary Knife Cutters Market
Tools
Fatigue Testing Machine Market
Tools
Core Shooter Machine Market
Tools
L Allen Wrench Market
Tools
Construction Nails Market
Tools
Drain Cleaning Equipment Market
Tools
CNC Metal Cutting Machine Tools Market