
 Aluminum Folding Ladders Market | 2026-2036
Aluminum Folding Ladders Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Folding Ladders Market Insights
OSHA ladder safety standards is rebalancing the cost-of-entry calculus for new manufacturers seeking North American market access. Werner Co. leverages its captive supply of aluminum extrusions to maintain cost discipline across its product lines. Louisville Ladder Inc. anchors its position through deep distribution relationships with industrial supply houses. Little Giant Ladder Systems differentiates via modular platform configurations that address multi-height job site requirements.
Aluminum folding ladders are portable access equipment fabricated from heat-treatable aluminum alloys, typically employing 6061 or 7075 grades with riveted or extruded joint construction to achieve strength-to-weight ratios exceeding comparable steel designs while maintaining sub-forty-pound carry weights for extension configurations. These structures serve commercial and industrial vertical access needs where frequent repositioning, corrosion resistance, and electrical non-conductivity prove operationally critical. Step ladder configurations occupy the mature volume core of the market, while telescoping ladder formats represent the fastest-expanding segment as urban tradespeople prioritize transport efficiency in congested job sites. Platform ladder applications within warehousing and distribution centers concentrate margin pools where fall-protection compliance mandates drive specification toward premium-certified units.
FDA, OSHA, and ISO 14122 standards collectively govern load-rating verification, slip-resistance testing, and access-system design protocols that determine product marketability across jurisdictions. OSHA's updated Walking-Working Surfaces rule specifically mandates ladder inspection documentation and fall-arrest compatibility, redirecting contractor procurement toward certified aluminum platforms with integrated guardrail options. Stakeholders must monitor evolving alloy sourcing regulations and third-party certification reciprocity agreements between national standards bodies to anticipate supply chain repositioning and qualification cost shifts.
Market Dynamics
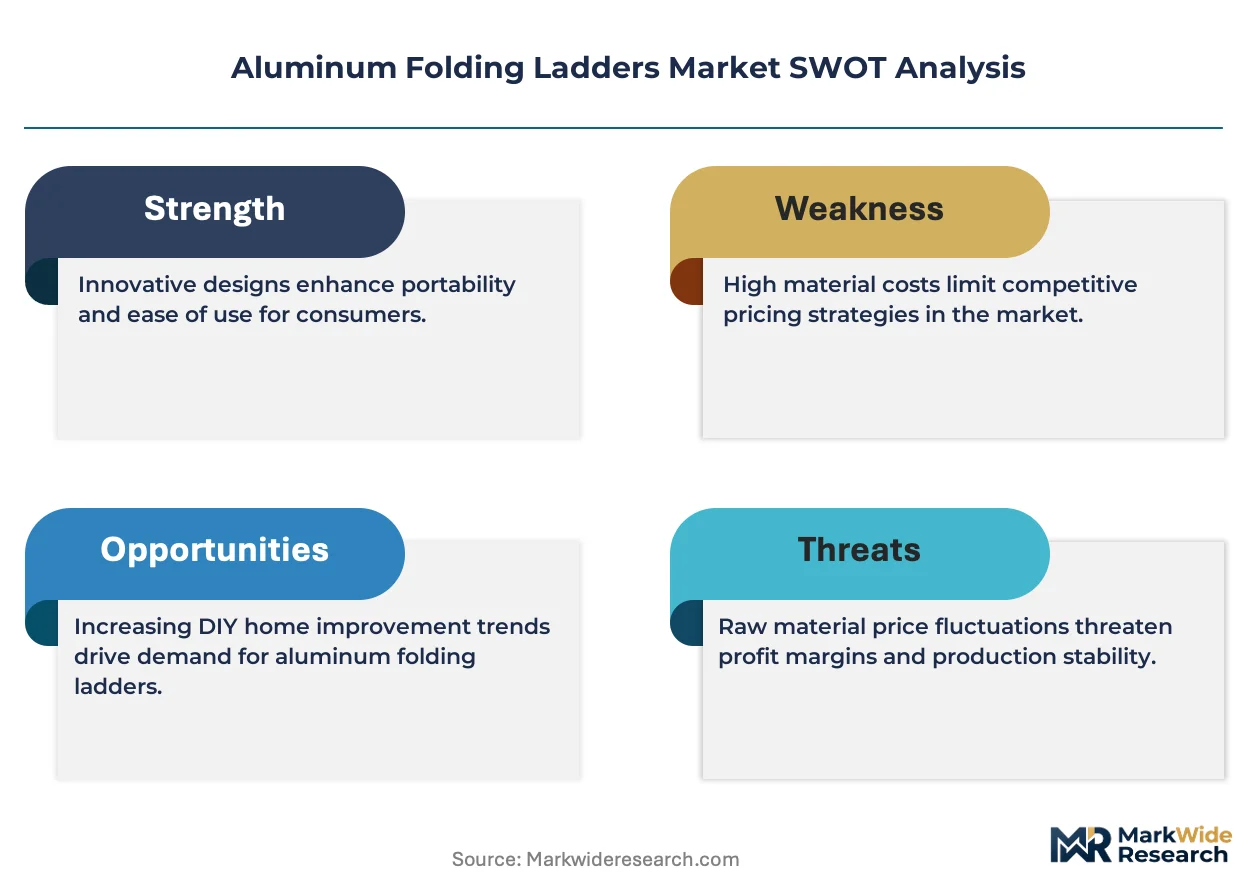
OSHA's updated Walking-Working Surfaces rule is compressing procurement timelines for certified aluminum platforms while simultaneously elevating qualification costs for non-integrated manufacturers.
Growth Catalysts
- Residential maintenance adoption:Contractor firms are standardizing aluminum folding ladders for home renovation work, driven by corrosion resistance and sub-forty-pound transport weights that reduce crew fatigue.
- OSHA ladder safety standards:Tightening certification requirements across North America are redirecting commercial buyers toward premium-rated units with documented inspection protocols.
- Heat-treatable aluminum alloys:6061 and 7075 grade extrusions deliver strength-to-weight ratios exceeding steel alternatives, enabling taller extension configurations without proportional mass penalties.
Market Restraints
- Aluminum input cost volatility:Primary aluminum pricing fluctuations on the London Metal Exchange compress margin predictability for extrusion-dependent fabricators.
- Supply concentration in China:Raw alloy and semi-finished extrusion sourcing clusters create exposure to export duty adjustments and shipping lane disruptions.
- Steel ladder substitution:Budget-sensitive municipal and agricultural buyers continue specifying galvanized steel for static installations where portability is non-critical.
Strategic Opportunities
- Telescoping ladder formats:Urban tradespeople in congested job sites are prioritizing transport-efficient designs that collapse to sub-four-foot lengths for vehicle storage.
- Platform ladder applications:Warehousing and distribution centers in the United States present margin-rich demand where fall-protection compliance mandates specify guardrail-integrated units.
- ISO 14122 certification reciprocity:Emerging mutual recognition agreements between national standards bodies reduce requalification costs for multi-jurisdiction suppliers.
Industry Challenges
- Welding technician scarcity:Heat-treatable aluminum joint fabrication requires specialized TIG certification that outpaces vocational program output in manufacturing regions.
- Third-party testing backlog:OSHA-recognized NRTL certification queues extend lead times for new product introductions, delaying revenue recognition across seasonal demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Folding Ladders Market |
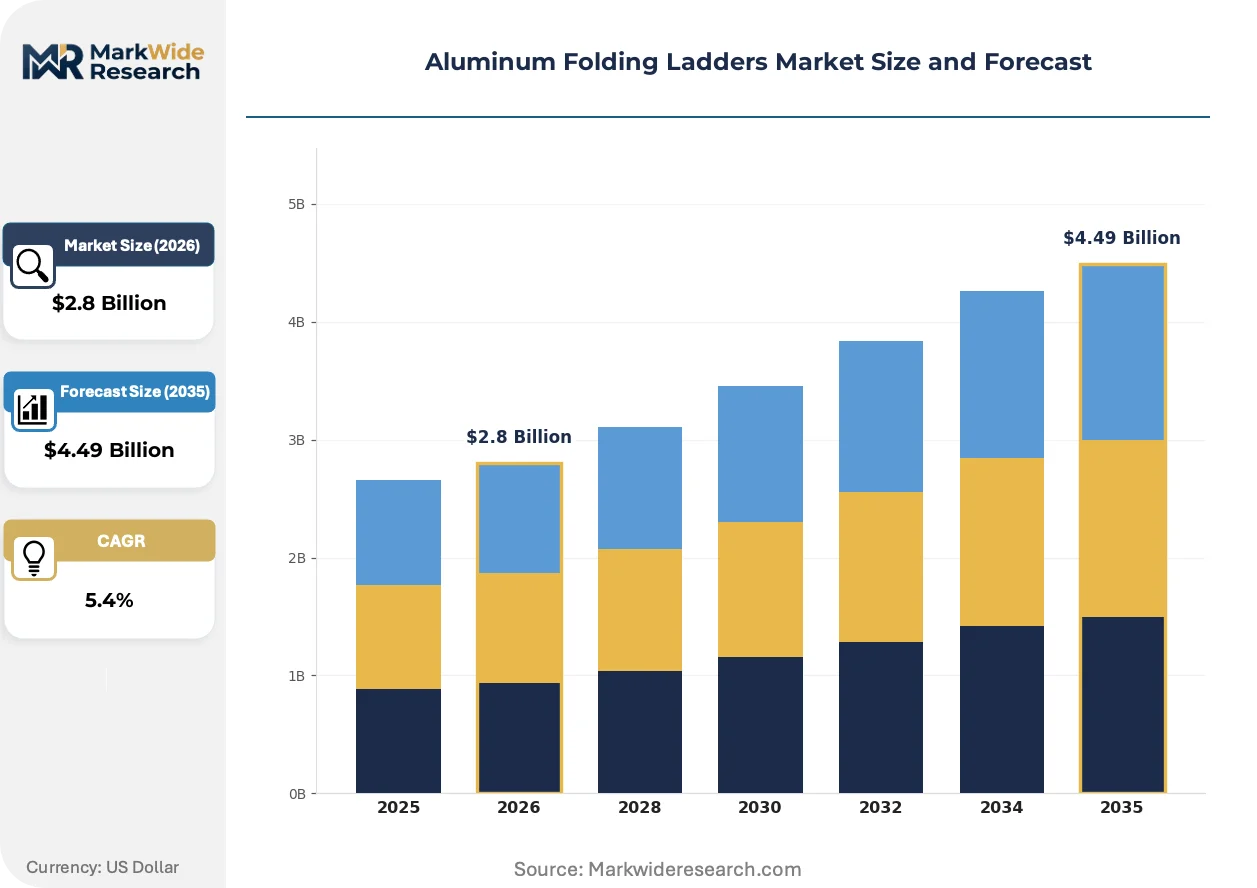
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Step Ladder, Extension Ladder, Platform Ladder, Telescoping Ladder Material Grade: 6061 Alloy, 7075 Alloy, 5052 Alloy, 3003 Alloy Application: Construction Sites, Warehousing, Residential Maintenance, Stage Setup End User: Contractor Firms, Property Management, Event Management, Homeowners |
| Companies Covered | Werner Co., Louisville Ladder Inc., Little Giant Ladder Systems, ZARGES, Hasegawa, Sanma, Bauer Corporation, Jinmao Group Co., Ltd., Altrex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Folding Ladders Market Trends and Innovations
Material science advances and regulatory digitization are restructuring competitive advantage around certified lightweight configurations rather than commodity ladder production.
Modular platform systems with tool-free height adjustment are decentralizing fleet standardization decisions for multi-site contractors. Facilities maintenance teams at logistics operators are adopting these configurations to reduce SKU proliferation across distributed warehouses. The technology is decentralizing purchasing authority from centralized procurement to regional safety managers who specify job-site-appropriate access equipment.
OSHA's electronic injury reporting mandate is accelerating documentation automation for ladder inspection and incident tracking. Industrial buyers now require QR-coded equipment tags that link to digital maintenance logs and fall-arrest compatibility certificates. Facility managers in California and Texas are prioritizing suppliers with integrated compliance software over standalone hardware vendors.
Rental channel penetration is altering ownership economics for seasonal construction crews and event staging operators. Equipment rental firms are expanding aluminum ladder fleets with telematics-enabled inventory tracking that reduces loss rates and optimizes utilization. This pattern concentrates in the United States where project-based employment and gig-economy trade labor normalize temporary equipment access over capital expenditure.
Aluminum Folding Ladders Market Segmentation
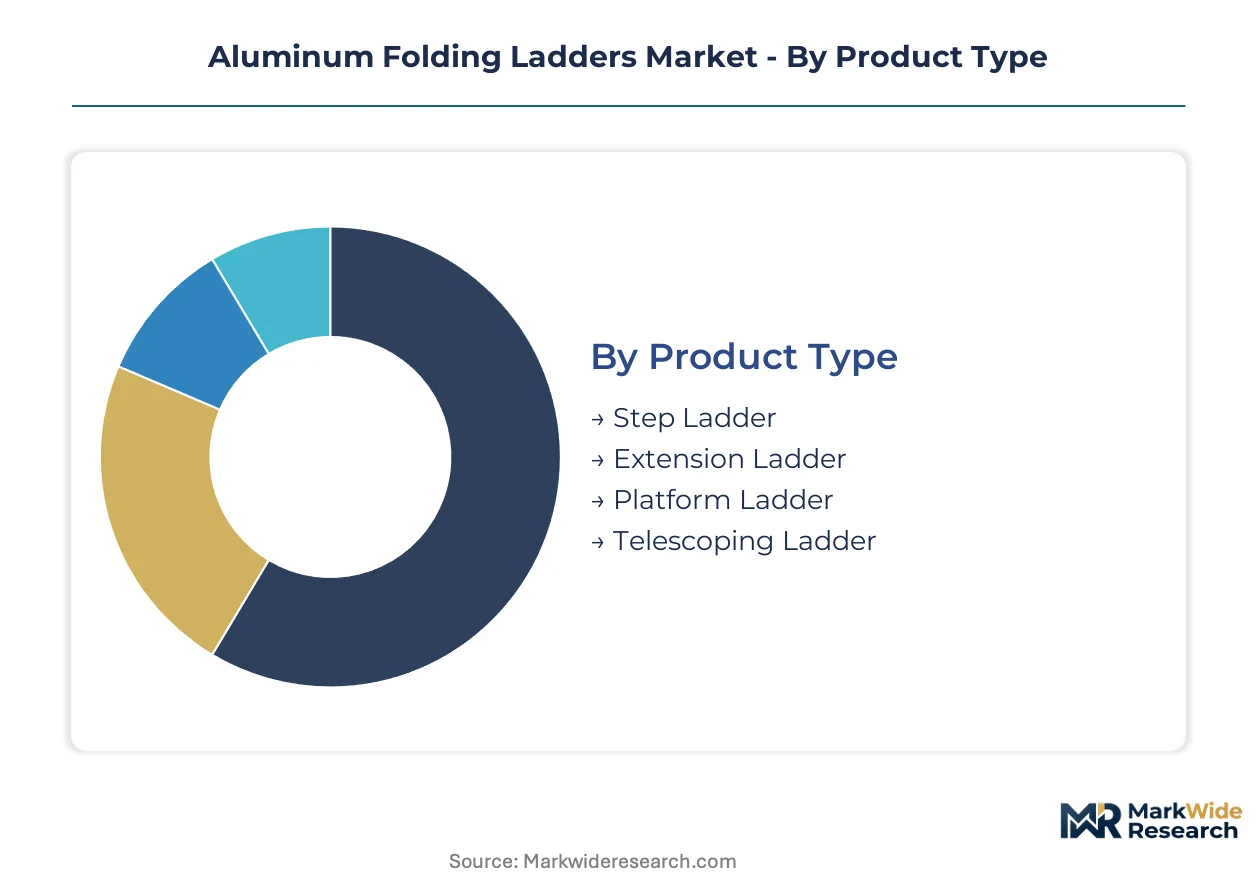
Aluminum folding ladder procurement decisions hinge on load-rating certification, transport weight, and job-site mobility requirements that vary sharply across trade disciplines. Segmentation reveals where margin pools concentrate versus where volume commoditization pressures dominate.
Product Type:
Replacement cycles accelerate where corrosion exposure and daily repositioning wear joint integrity fastest, creating upgrade windows for certified configurations.
- Step Ladder:Riveted A-frame construction using 6061-grade side rails dominates residential electrical and painting contractor fleets. Demand concentrates among property maintenance crews in the United States where OSHA-compliant load ratings command specification premiums over uncertified imports.
- Telescoping Ladder:Collapsible rung-lock mechanisms collapse to sub-four-foot lengths for vehicle storage. Urban tradespeople in congested German and Chinese job sites prioritize these formats where parking constraints and multi-height access needs coincide, driving the steepest expansion trajectory among all product types.
- Extension Ladder:Multi-section fly-and-base configurations achieve forty-foot reach with sub-forty-pound carry weights. Fire departments and utility maintenance specify these for elevated exterior access.
- Platform Ladder:Guardrail-integrated work platforms address fall-protection mandates in warehousing. Distribution centers specify these where OSHA Walking-Working Surfaces compliance requires documented inspection protocols.
Volume placements concentrate in Step Ladder configurations; the faster expansion belongs to Telescoping Ladder formats.
Material Grade:
Cost tier stratification separates specification-grade extrusions from commodity alloy sourcing in price-sensitive channels.
- 6061 Alloy:Heat-treatable T6 temper delivers 40,000 psi yield strength with excellent corrosion resistance. Commercial buyers in construction and warehousing specify this grade for daily-use ladders where fatigue life determines replacement timing.
- 7075 Alloy:Zinc-primary composition achieves 73,000 psi yield strength in T6 temper, enabling thinner wall extrusions that reduce transport weight by fifteen to twenty percent. Aerospace maintenance and military procurement channels in the United States and Germany absorb premium pricing for these high-performance units.
- 5052 Alloy:Marine-grade corrosion resistance suits coastal and chemical-exposure environments. Port maintenance and wastewater treatment facilities specify these where salt spray accelerates degradation.
- 3003 Alloy:General-purpose manganese alloy serves economy-tier residential and light commercial applications. Budget-sensitive homeowners and occasional-use property managers drive demand.
Specification-grade procurement clusters around 6061 Alloy; climbing fastest is 7075 Alloy as weight-critical applications multiply.
Application:
Geographic intensity of infrastructure maintenance cycles determines where premium-certified units displace uncertified alternatives.
- Construction Sites:Daily repositioning and multi-trade coordination require sub-forty-pound extension configurations with slip-resistant feet. Contractor firms in the United States and China specify OSHA or GB-standard certified units where injury liability exposure elevates procurement scrutiny.
- Warehousing:Fall-protection compliance mandates guardrail-integrated platform ladders with documented inspection histories. Third-party logistics operators in Germany and the United States concentrate margin-rich demand here.
- Residential Maintenance:Corrosion-resistant step and telescoping formats serve renovation contractors. Crew fatigue reduction from lightweight transport drives specification toward aluminum over steel.
- Stage Setup:Rapid assembly and strike requirements favor modular platform systems with tool-free height adjustment. Event management firms prioritize these for touring productions and temporary venue installations.
Procurement volume concentrates in Construction Sites; Warehousing applications are expanding most quickly as e-commerce fulfillment infrastructure scales.
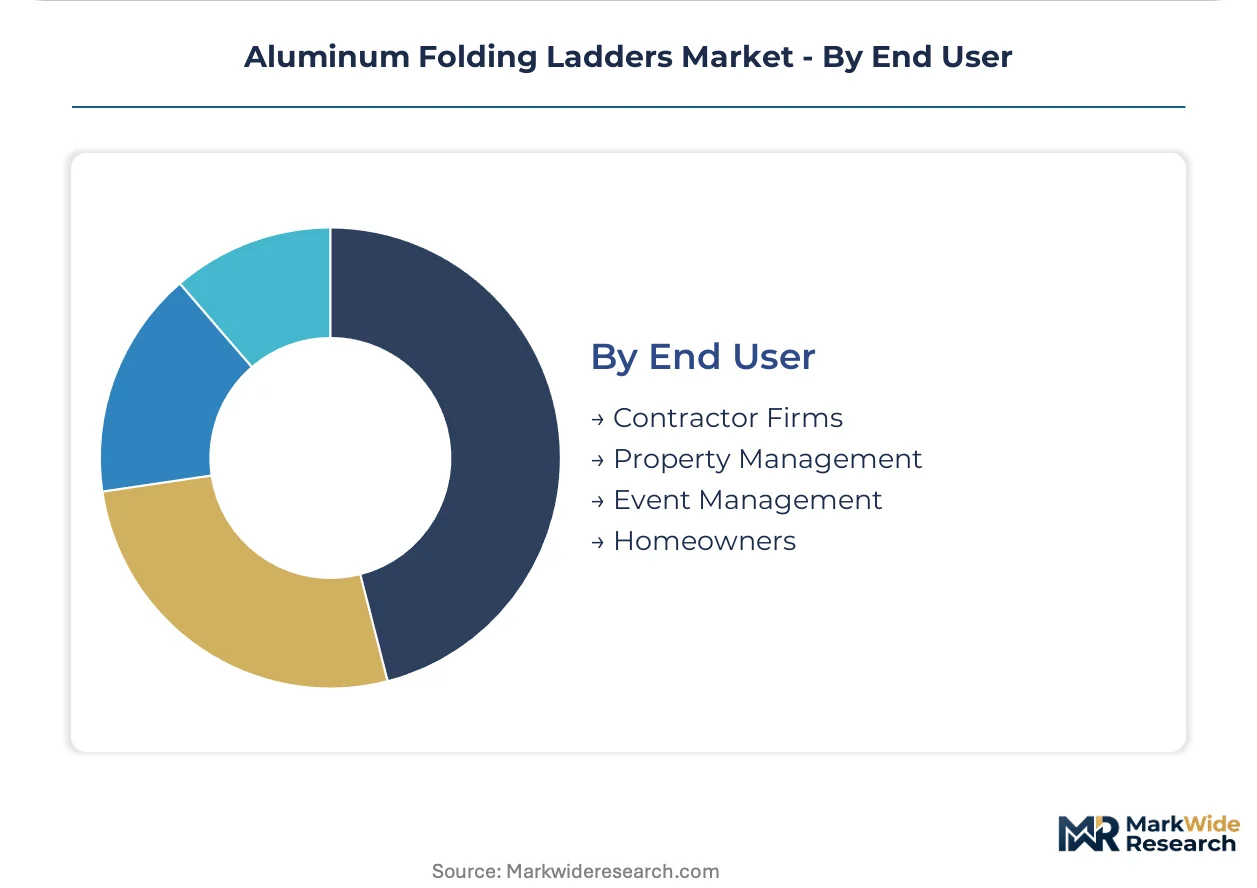
End User:
Customer-type differentiation separates fleet-standardization decisions from individual purchase economics.
- Contractor Firms:Fleet procurement at scale demands SKU consolidation and documented inspection compliance. Multi-site operators in the United States standardize on Werner and Louisville Ladder distribution relationships.
- Property Management:Distributed maintenance teams require corrosion-resistant configurations for varied building ages and exterior conditions. Regional safety managers increasingly specify modular platform systems.
- Event Management:Temporary access needs favor rental channel penetration over capital expenditure. Staging operators prioritize rapid assembly formats with integrated guardrails.
- Homeowners:Occasional-use economics drive big-box retail and e-commerce channel concentration. Price sensitivity sustains 3003 alloy and steel substitution at this tier.
Contractor Firms anchor volume placements; Property Management segments are gaining share fastest as distributed warehousing and multi-family housing maintenance professionalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in the Yangtze River Delta and Shenzhen Special Economic Zone concentrate aluminum extrusion capacity for ladder fabricators serving export markets. Infrastructure maintenance cycles and warehouse construction intensity determine regional demand dispersion.
United States
Third-party logistics operators in Dallas-Fort Worth and Chicago metro areas drive platform ladder procurement for e-commerce fulfillment centers. OSHA's Walking-Working Surfaces rule mandates documented inspection protocols for fall-protection equipment. California's Cal/OSHA maintains stricter guardrail integration standards than federal baselines, elevating specification premiums in West Coast distribution networks.
Germany
Industrial maintenance contractors in the Ruhr Valley and Bavaria specify ISO 14122-certified configurations for manufacturing facility upgrades. REACH regulations govern chemical exposure limits in alloy surface treatments, elevating qualification costs for non-EU suppliers. Stuttgart's automotive supplier ecosystem generates demand for lightweight 7075-grade platforms in final assembly line maintenance.
China
GB-standard certification requirements redirect domestic procurement toward certified manufacturers as construction safety enforcement tightens in tier-one cities. The Pearl River Delta extrusion cluster supplies semi-finished aluminum to ladder fabricators serving Southeast Asian export markets. Shanghai's commercial real estate maintenance sector prioritizes telescoping formats for high-rise facade access in dense urban cores.
India
Bureau of Indian Standards (BIS) certification for portable access equipment is compressing import windows for uncertified Chinese manufacturers. Maharashtra's warehousing expansion around Mumbai and Pune concentrates demand for guardrail-integrated platform ladders. The Delhi-Mumbai Industrial Corridor infrastructure projects specify aluminum extension configurations for electrical transmission maintenance.
Japan
Metropolitan Tokyo's constrained job sites prioritize collapsible telescoping designs for building maintenance contractors. METI's industrial safety guidelines emphasize documented equipment inspection histories, favoring domestic suppliers with integrated compliance systems. Osaka's manufacturing belt sustains demand for corrosion-resistant 5052-grade ladders in coastal chemical processing facilities.
Aluminum Folding Ladders Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price bands defined by certification grade and alloy specification. The vendor base separates into three strategic archetypes: vertically integrated extrusion-to-finished-goods manufacturers, distribution-anchored brand houses, and modular system specialists. Consolidation pressure concentrates among mid-scale fabricators facing alloy cost volatility and NRTL certification queue delays. Dominant competitive moves include backward integration into aluminum extrusion capacity and strategic partnerships with rental channel operators.
Among North American fabricators, Werner Co. and Louisville Ladder Inc. occupy positions within the distribution-anchored tier, while Little Giant Ladder Systems exemplifies the modular configuration specialist archetype. ZARGES represents German engineering-focused positioning in premium-certified access equipment. Chinese manufacturers including Jinmao Group Co., Ltd. and Sanma sit within the scale-driven export supply segment serving price-sensitive channels.
| Leading Market Players |
|---|
| Werner Co. |
| Louisville Ladder Inc. |
| Little Giant Ladder Systems |
| ZARGES |
| Hasegawa |
| Sanma |
| Bauer Corporation |
| Jinmao Group Co., Ltd. |
| Altrex |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange primary aluminum pricing cascades through extrusion-dependent fabricators into three-tier pricing structures across premium, standard, and economy levels, with heat-treatable alloy grades commanding specification premiums that commodity 3003-tier imports cannot match.
Pricing Analysis
Lead-time premiums reward NRTL-certified inventory held in regional distribution centers, while spot-market imports from Chinese extrusion clusters compete on price at the cost of documentation gaps. Price differentiation separates OSHA-compliant platform ladders with integrated guardrails from uncertified step-ladder imports. Pricing pressure stems from alloy input volatility compressing margin predictability for non-integrated fabricators. Municipal procurement teams exhibit highest price sensitivity, while third-party logistics operators absorb premium pricing for fall-protection compliance.
Supply Chain Analysis
OSHA-recognized NRTL certification gates market access for ladder fabricators, creating qualification backlogs that favor incumbent suppliers with established testing relationships. Raw alloy and semi-finished extrusion sourcing clusters in China, Germany, and the United States feed downstream fabrication. Heat-treatable 6061 and 7075 grade extrusions, riveted joint hardware, and slip-resistant foot components constitute critical input dependencies. Single-source vulnerability concentrates in Yangtze River Delta extrusion capacity exposed to export duty adjustments. Distribution runs through industrial supply houses and equipment rental channels that concentrate in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as OSHA certification queues and alloy cost volatility force mid-scale fabricators toward acquisition or exit, rewarding players with captive extrusion supply and established NRTL relationships.
For Market Incumbents: Cement market position through backward integration into aluminum extrusion capacity in domestic supply zones, insulating margin structure from LME volatility. Deepen certification investment to exploit NRTL queue delays that block rival product introductions. Prioritize rental channel partnerships where telematics-enabled fleet tracking creates switching costs against emerging competitors.
For New Entrants and Emerging Players: The gap between premium 7075-grade platforms and economy 3003-tier residential ladders offers white-space entry for mid-tier 6061-grade specialists with modular platform configurations. Target property management segments where distributed maintenance teams prioritize SKU consolidation over brand loyalty. Pursue ISO 14122 certification reciprocity to reduce multi-jurisdiction requalification costs.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated extrusion-to-finished-goods manufacturers with established OSHA relationships and rental channel presence. Acquisition candidates with captive alloy supply and documented inspection software capabilities offer strongest long-term viability. Monitor NRTL certification queue lengths as inflection indicator for incumbent pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Extrusion Capacity | Captive alloy supply insulates margin structure from LME volatility and shipping lane disruptions. |
| NRTL Certification Investment | OSHA-recognized testing relationships accelerate product introductions while blocking rival entries. |
| Rental Channel Partnership | Telematics-enabled fleet tracking creates utilization data advantages and switching costs. |
| Modular Platform System Development | Tool-free height adjustment addresses multi-site contractor SKU consolidation requirements. |
| ISO 14122 Reciprocity Expansion | Mutual recognition agreements reduce requalification costs for multi-jurisdiction suppliers. |
Research Methodology
Document review covered SEC filings, customs and trade databases, and OSHA regulatory dockets, complemented by interviews with plant engineers at ladder fabricators, procurement leads at third-party logistics operators, maintenance directors at distribution centers, and certification specialists at NRTL testing laboratories. Secondary validation drew from industrial supply house inventory data, equipment rental fleet disclosures, and London Metal Exchange aluminum pricing records. Bottom-up demand modeling triangulated against top-down market sizing across product type, material grade, application, and end user segments.
Segment-level projections across the analysis window reflect product mix shifts toward telescoping formats and platform ladder applications, with CAGRs derived from trade flow analysis and replacement cycle timing. Modeled dimensions included step versus telescoping versus extension versus platform configurations, 6061 versus 7075 versus 5052 versus 3003 alloy grades, construction versus warehousing versus residential versus stage setup applications, and contractor versus property management versus event management versus homeowner end users. Forecast inputs incorporated OSHA enforcement intensity indices and e-commerce fulfillment center construction pipelines.
Inputs from primary interviews and regulatory filings were available through the study window; gaps in real-time rental channel utilization data introduce uncertainty bands around fleet expansion assumptions. Forecasts reflect documented assumptions regarding alloy price trajectory and certification queue durations. A model refresh is warranted upon material change in OSHA Walking-Working Surfaces enforcement intensity or aluminum export duty structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Crimping Tool Market
Tools
Jade Engraving Machines Market
Tools
L Allen Wrench Market
Tools
Automatic Heat Press Machines Market
Tools
Collated Screws Market
Tools
Drill Bit Market
Tools
Striking Tools Market
Tools
Fastening Power Tools Market
Tools
Cordless Power Drill Market
Tools
Mechanical Springs Market
Tools
Pipe Alignment Clamps Market
Tools
Spray Painting Machine Market
Tools
Thickness Planers Market
Tools
Europe Machine Tools Market
Tools
Boring Tools Market
Tools
Impact Sockets Market