
 Garden Digging Tools Market | 2026-2036
Garden Digging Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Garden Digging Tools Market Foresight
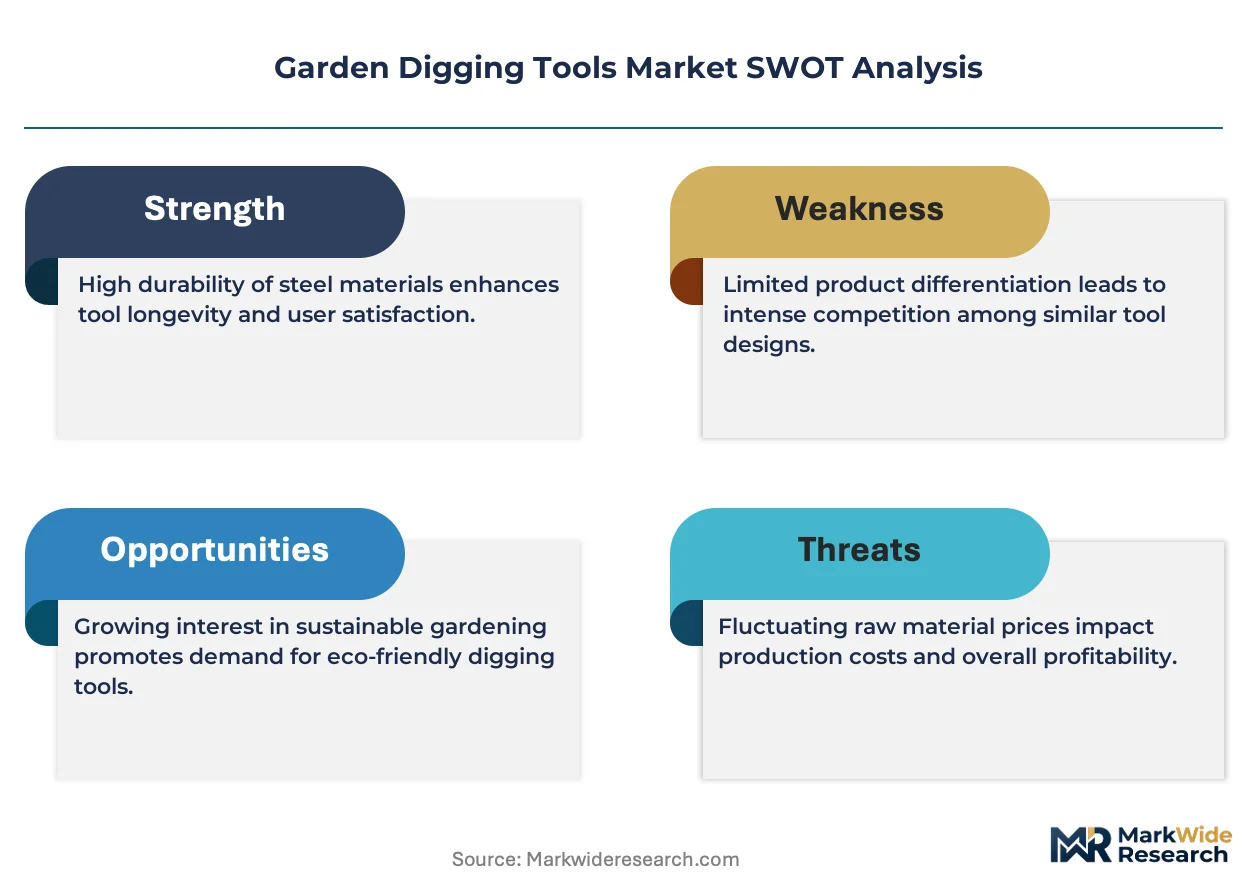
Aftermarket service revenue for tool sharpening and handle replacement is narrowing as manufacturers shift toward durable, corrosion-resistant designs that extend replacement cycles. Stanley Black & Decker leverages its broad distribution network to sustain retail shelf dominance across North American home improvement chains. Fiskars Group anchors its position through ergonomic fiberglass-composite handles that reduce user fatigue during extended digging operations. Husqvarna Group competes in the professional landscaping channel with reinforced carbon steel blades rated for rocky soil conditions.
Garden digging tools encompass manually operated implements designed for soil penetration, lifting, and cultivation, typically featuring heat-treated steel blades with Rockwell hardness ratings between 45-55 HRC and ash or fiberglass handles engineered for leverage transmission. Shovels and spades fabricated from stainless steel command premium positioning due to rust immunity and reduced soil adhesion, while carbon steel variants occupy the volume tier through lower unit costs and superior edge retention. Landscape contractors represent the fastest-growing end user segment as commercial groundskeeping contracts expand across municipal parks and corporate campuses.
EPA regulations on volatile organic compound emissions from metal finishing processes constrain coating chemistries available to domestic manufacturers, while REACH substance restrictions in European markets limit certain chromium-based surface treatments. The EU F-Gas Regulation indirectly affects supply chains through energy costs associated with steel forging operations. Stakeholders must monitor evolving material compliance requirements and carbon border adjustment mechanisms that could restructure sourcing economics for imported forged components.
Market Dynamics
REACH substance restrictions and EPA volatile organic compound limits on metal coatings are compressing available chemistries, forcing manufacturers toward boron-nitride and ceramic-based surface treatments that alter forging economics and supply chain sourcing patterns.
Growth Catalysts
- Suburban residential landscaping:United States homeowners are expanding cultivated acreage per property, driving replacement demand for ergonomic spades and transplanting shovels with fiberglass-composite handles.
- China municipal greening:Provincial urban beautification mandates require community garden infrastructure procurement, concentrating volume orders through state-affiliated landscaping bureaus.
- Carbon steel blade innovation:Heat-treatment protocols achieving 52-55 HRC hardness ratings extend edge retention in rocky soil conditions, reducing professional contractor downtime.
Market Restraints
- Chromium coating phase-out:ECHA REACH Annex XVII restrictions on hexavalent chromium surface treatments eliminate proven corrosion-resistant finishes from European supply chains.
- Natural ash handle scarcity:Appalachian hardwood supply constraints in the eastern United States elevate raw material costs for traditional wooden handle manufacturers.
- Power tool substitution:Battery-operated cultivators and mini-excavators displace manual digging implements in commercial landscaping contracts exceeding five-acre maintenance scopes.
Strategic Opportunities
- India community horticulture:Ministry of Agriculture push for urban kitchen gardens creates untapped demand for lightweight, rust-resistant stainless steel transplanting tools.
- EU F-Gas Regulation energy incentives:Forging operations adopting electric induction heating qualify for carbon border adjustment relief, rewarding early equipment upgrades.
- Direct-to-landscaper e-commerce:Specialized B2B platforms bypass distributor markups for professional groundskeeping contractors seeking bulk replacement blade orders.
Industry Challenges
- Heat-treatment technician shortage:Skilled operators capable of maintaining Rockwell hardness consistency across batch-forged carbon steel blades are retiring faster than apprenticeship programs replace them.
- Dual certification timelines:Manufacturers seeking simultaneous EPA coating compliance and CE marking face extended laboratory testing cycles that delay product launches by 8-14 months.
- Legacy inventory stranding:Pre-REACH chromium-plated stockpiles in European distribution centers require costly reprocessing or disposal under evolving waste framework directives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garden Digging Tools Market |
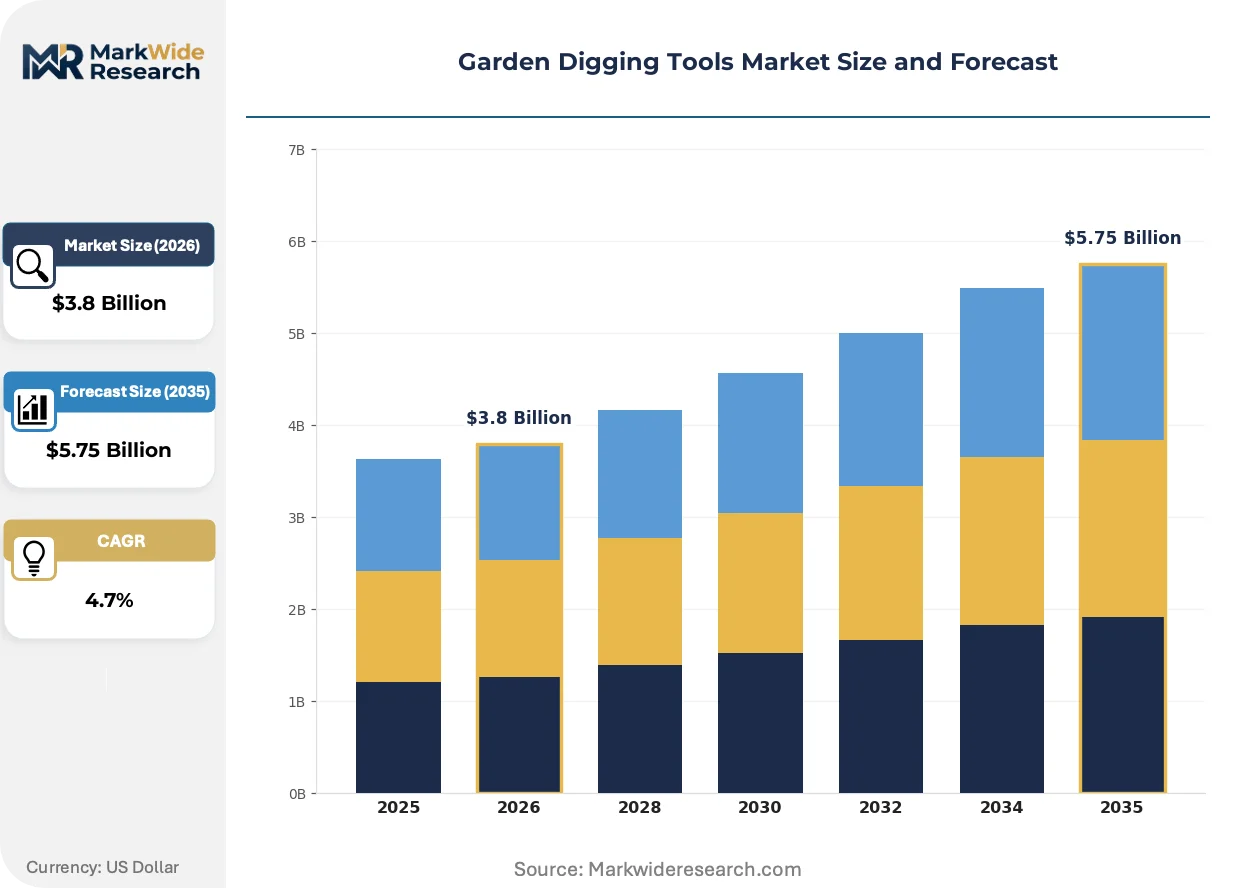
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shovels, Spades, Hoes, Forks, Trowels Material: Stainless Steel, Carbon Steel, Aluminum, Plastic, Wood Application: Landscaping, Horticulture, Agriculture, Gardening, Nursery End User: Home Gardeners, Landscape Contractors, Agricultural Workers, Nursery Operators |
| Companies Covered | Stanley Black & Decker, Fiskars Group, Husqvarna Group, Robert Bosch GmbH, The Ames Companies, Inc., Falcon Garden Tools, STIHL, Spear & Jackson, Zenport Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garden Digging Tools Market Shifts & Advancements
Material science advances and regulatory chemistry constraints are converging to redefine blade durability standards and handle ergonomics across residential and professional user segments.
Fiberglass-composite handle technology is migrating from premium positioning toward mid-market shovel configurations. Landscape contractors operating municipal contracts in Germany and the Netherlands specify vibration-dampening handles for crews executing extended trenching operations. The shift compresses price premiums for ergonomic designs while elevating baseline consumer expectations for fatigue reduction.
EPA metal finishing emission standards now cap volatile organic compound releases from coating bake ovens at thresholds that disqualify conventional solvent-based formulations. Domestic forgers are retrofitting facilities with thermal oxidizer systems or switching to waterborne ceramic coatings. Professional-grade spade manufacturers serving the North American market absorb the steepest compliance capital burdens.
Sharpening service unbundling is altering post-purchase revenue models. Retail chains in the United States are discontinuing in-store blade grinding programs, redirecting tool owners toward manufacturer-direct mail-in services or disposable blade replacement subscriptions. Subscription models concentrate most rapidly among suburban homeowners lacking workshop equipment or technical skill.
Garden Digging Tools Market Segmentation
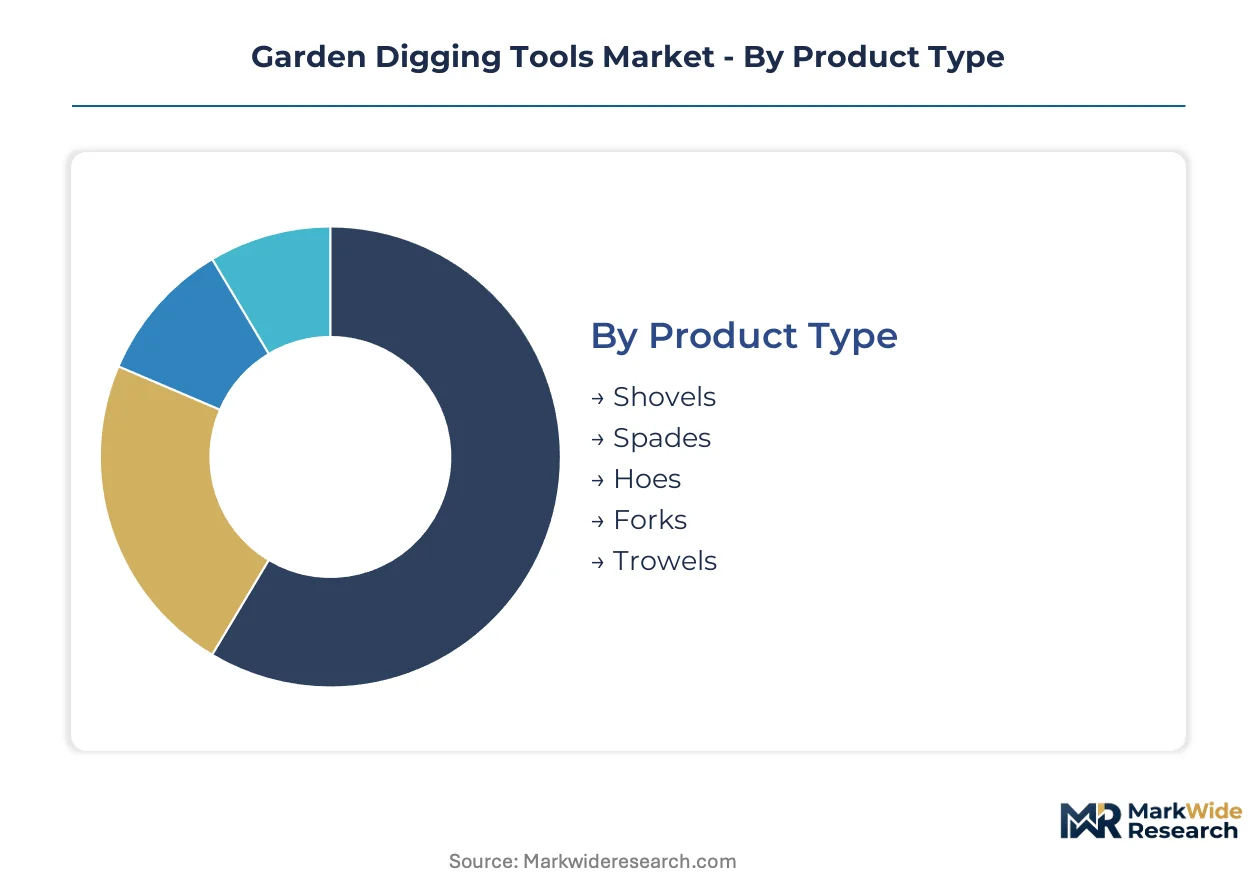
Segmentation in garden digging tools reveals distinct procurement rhythms across user types and material specifications. Residential replacement cycles stretch 7-10 years for premium implements, while commercial contractors rotate inventory every 2-3 seasons under heavy-use contracts.
Product Type:
Shovels and spades turn over fastest in commercial channels where blade geometry degrades under rocky soil abrasion, while trowels and forks persist longest in residential settings.
- Shovels:Round-point and square-point configurations dominate volume, with tempered carbon steel blades rated 48-52 HRC penetrating compacted subsoil. Demand concentrates among United States landscape contractors executing municipal trenching contracts where blade replacement occurs quarterly.
- Spades:Flat, sharpened edges excel at sod cutting and edge definition, with fiberglass-composite handles reducing wrist torque. German and Dutch municipal groundskeepers specify vibration-dampening variants for crews working extended shifts.
- Hoes:Draw and scuffle patterns serve cultivation and weeding operations with lighter duty cycles than digging implements.
- Forks:Four-tine digging forks aerate soil and lift root balls, with stainless steel variants resisting corrosion in humid nursery environments.
- Trowels:Hand-scale implements for transplanting and container work, with aluminum bodies targeting price-sensitive Asian markets.
Shovels anchor the volume base while spades gain share at the steepest rate through ergonomic premium positioning.
Material:
Cost tier stratification separates corrosion-resistant premium grades from commodity carbon steel, with supply concentration in Chinese forging centers shaping regional availability.
- Stainless Steel:Chromium-nickel alloys eliminate rust maintenance and reduce soil adhesion, commanding premium positioning in coastal United States markets where salt air accelerates carbon steel degradation. REACH Annex XVII restrictions on hexavalent chromium surface treatments elevate stainless appeal in European procurement.
- Carbon Steel:Heat-treatable alloys achieve superior edge retention at 52-55 HRC hardness, with lower unit costs driving volume in developing Asian markets. Professional contractors in China prioritize carbon steel for rocky soil penetration despite higher maintenance requirements.
- Aluminum:Lightweight alloys reduce transport costs and user fatigue, with limited edge durability restricting application to sandy loam conditions.
- Plastic:Polypropylene and fiberglass-reinforced composites serve entry-level residential segments with minimal load-bearing demands.
- Wood:Appalachian ash and European beech handles face supply constraints, elevating raw material costs for traditional manufacturers.
Carbon steel commands the highest shipment volumes while stainless steel climbs fastest through regulatory-driven substitution in European markets.
Application:
Customer type determines specification intensity, with commercial operators demanding certified hardness ratings and residential buyers prioritizing ergonomics and aesthetics.
- Landscaping:Commercial groundskeeping contracts specify reinforced blades and replaceable handle systems, with United States municipal parks departments standardizing on fiberglass-composite configurations.
- Horticulture:Precision cultivation requires stainless steel transplanting tools with narrow blade profiles, with Indian urban kitchen garden initiatives driving lightweight demand.
- Agriculture:Broad-acre operations favor durability over refinement, with carbon steel long-handled hoes and shovels dominating subsistence and smallholder contexts.
- Gardening:Residential suburban expansion in the United States elevates ergonomic spade demand, with online subscription blade replacement models gaining traction.
- Nursery:Container production environments specify rust-resistant stainless forks and trowels, with humidity corrosion dictating material selection.
Landscaping generates the highest absolute demand while horticulture expands most quickly through urban agriculture policy support.
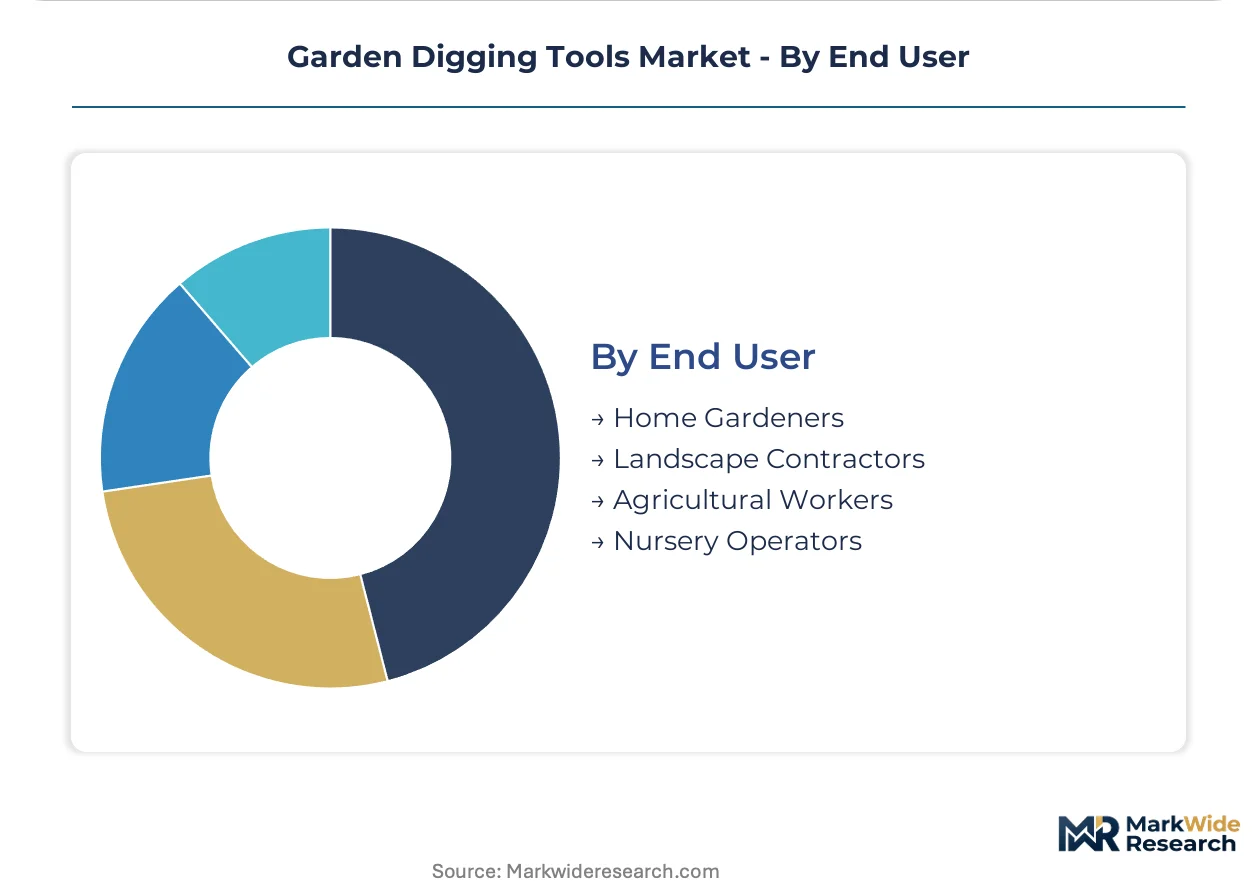
End User:
Procurement scale and specification authority diverge sharply between individual purchasers and institutional buyers with technical sourcing departments.
- Home Gardeners:United States suburban property owners drive replacement demand as cultivated acreage per household expands, with ergonomic fiberglass handles reducing fatigue during weekend projects.
- Landscape Contractors:Professional crews operating municipal and corporate contracts in Germany and the Netherlands require vibration-dampening handles and batch-certified blade hardness, with bulk blade subscription services capturing procurement efficiency.
- Agricultural Workers:Smallholder and commercial farming operations prioritize unit economics over feature sets, with carbon steel durability in rocky soil conditions reducing downtime.
- Nursery Operators:Humid propagation environments demand corrosion-resistant stainless implements, with specialized transplanting tools supporting root ball integrity.
Home gardeners anchor volume through replacement cycles while landscape contractors drive specification innovation and premium tier expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States homeowners exhibit the lowest price elasticity, absorbing ergonomic premiums for fiberglass-composite handles, while Indian smallholders and Chinese municipal buyers drive volume through cost-optimized carbon steel procurement.
United States
Suburban property expansion elevates replacement demand for premium spades and transplanting shovels with fatigue-reducing handles. EPA volatile organic compound caps on metal finishing processes constrain coating bake oven emissions, forcing thermal oxidizer retrofits at domestic forging facilities. Appalachian hardwood supply shortages around West Virginia and Kentucky elevate ash handle raw material costs for traditional manufacturers.
China
Provincial urban beautification mandates concentrate volume orders for community garden infrastructure through state-affiliated landscaping bureaus. MEE enforcement of dual carbon goals raises energy costs for steel forging operations in Hebei and Shandong provinces. Yangtze River Delta forging clusters near Shanghai pivot toward electric induction heating to qualify for carbon border adjustment relief on exported components.
Germany
Municipal groundskeeping contracts in North Rhine-Westphalia and Bavaria specify vibration-dampening spade handles for extended trenching crews. ECHA REACH Annex XVII restrictions eliminate hexavalent chromium surface treatments from European supply chains, elevating stainless steel appeal. Solingen blade manufacturing heritage anchors premium-grade carbon steel heat-treatment expertise, though skilled technician retirements outpace apprenticeship replacements.
India
Ministry of Agriculture urban kitchen garden initiatives generate untapped demand for lightweight transplanting tools across Maharashtra and Karnataka. BIS certification requirements for hand tool safety standards delay import clearance for unmarked carbon steel shipments. Ludhiana metalworking clusters in Punjab supply price-optimized forged blades to domestic horticulture cooperatives and Southeast Asian re-export markets.
Netherlands
Commercial landscaping contractors operating municipal park contracts prioritize ergonomic specifications with batch-certified blade hardness ratings. EU F-Gas Regulation energy incentives reward forging operations adopting electric induction heating over gas-fired furnaces. Rotterdam distribution hubs face legacy inventory stranding as pre-REACH chromium-plated stockpiles require costly reprocessing under evolving waste framework directives.
Garden Digging Tools Market Competitive Landscape
Capability concentration sits with heritage forging specialists possessing heat-treatment expertise; scale advantage sits with diversified tool conglomerates leveraging retail distribution density. The market structures around three tiers: premium ergonomic specialists, mid-market volume fabricators, and entry-level commodity suppliers. Dominant competitive moves include strategic partnerships with municipal procurement departments and portfolio diversification into subscription-based blade replacement services.
Among diversified tool manufacturers, Stanley Black & Decker and Fiskars Group exemplify the scale-driven tier with broad retail shelf presence across North American home improvement chains. Husqvarna Group occupies a position within the professional landscaping channel, anchoring reinforced blade specifications for rocky soil conditions. Heritage specialists like Spear & Jackson represent the capability-concentrated tier, drawing on regional forging traditions without the capital burden of compliance-scale coating facility retrofits.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Fiskars Group |
| Husqvarna Group |
| Robert Bosch GmbH |
| The Ames Companies, Inc. |
| Falcon Garden Tools |
| STIHL |
| Spear & Jackson |
| Zenport Industries |
| Others |
Supply & Pricing Matrix
Yangtze River Delta forging clusters near Shanghai anchor global carbon steel blade capacity, with municipal procurement concentration in China compressing margins for export-bound manufacturers while EPA compliance costs inflate North American premium tier pricing.
Pricing Analysis
Long-term offtake contracts dominate municipal landscaping bureau procurement in China, locking volume pricing for carbon steel implements across 2-3 season cycles. Three-tier pricing structure across premium, standard, and economy levels separates fiberglass-composite ergonomic designs from basic ash-handle configurations and entry-level plastic variants. Cost compression in the carbon steel tier intensifies because Hebei province energy cost inflation erodes forge economics. Landscape contractors in Germany and the Netherlands exhibit the lowest price sensitivity, absorbing batch-certification premiums, while Indian smallholders drive volume through cost-optimized procurement.
Supply Chain Analysis
Ludhiana metalworking clusters in Punjab and Solingen heritage forges in Germany hold specialized heat-treatment capacity for professional-grade blade certification. Raw material flows draw from Appalachian ash forests, European beech plantations, and Chinese chromium-nickel alloy stockpiles. Single-source vulnerability concentrates in skilled heat-treatment technician pools where apprenticeship gaps outpace retirements across German and North American facilities. Distribution runs through home improvement retail chains in the United States, state-affiliated landscaping bureaus in China, and specialized B2B platforms serving Dutch commercial contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-operated cultivators and mini-excavators threaten manual implement incumbents in commercial contracts exceeding five-acre scopes, demanding defensive repositioning around precision and ergonomics.
For Market Incumbents: Insulate core professional channels by deepening captive supply of certified carbon steel blanks from Yangtze River Delta partnerships, while accelerating fiberglass-composite handle R&D to differentiate against power tool substitution in municipal trenching contracts. Lock in long-term offtake agreements with German and Dutch landscaping bureaus before REACH-driven stainless steel conversion elevates input costs. For New Entrants and Emerging Players: Build out direct-to-landscaper e-commerce infrastructure targeting United States suburban homeowners with subscription blade replacement models, bypassing distributor markups that constrain incumbent pricing flexibility. Prioritize lightweight stainless steel transplanting tools for Indian urban kitchen garden initiatives where Ministry of Agriculture policy support creates procurement acceleration. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because heat-treatment technician scarcity and dual certification timeline compression favor scaled manufacturers with compliance infrastructure over fragmented heritage specialists. Target acquisition candidates with existing EPA thermal oxidizer installations and CE marking laboratory relationships. Monitor quarterly heat-treatment apprenticeship enrollment rates as inflection indicator for capability scarcity severity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Steel Forging | Captive blade supply secures hardness consistency certification for German municipal contracts. |
| Subscription Blade Replacement Service Launch | Recurring revenue model captures United States suburban homeowner replacement cycles. |
| Electric Induction Heating Retrofit | EU F-Gas Regulation carbon border adjustment relief rewards early forge equipment upgrades. |
| Direct-to-Landscaper E-Platform Development | Bypasses distributor markups for Dutch commercial groundskeeping contractor bulk orders. |
| Stainless Steel Product Line Expansion | REACH Annex XVII hexavalent chromium restrictions elevate rust-resistant premium positioning. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with heat-treatment facility managers, landscaping procurement officers at municipal bureaus, retail category buyers at North American home improvement chains, and aftermarket service heads at heritage forging specialists; and secondary validation through customs trade data, EPA metal finishing emission filings, ECHA REACH substance restriction updates, and SEC 10-K disclosures from diversified tool manufacturers. Bottom-up shipment triangulation across product type, material specification, and end-user segment converged with top-down macroeconomic elasticity modeling.
Forecast inputs span suburban property expansion rates, municipal greening budget allocations, energy cost trajectories for steel forging operations, and regulatory compliance timeline projections across the analysis window. Segmentation dimensions modeled include product geometry, blade material alloy, handle composition, end-user procurement scale, and regional certification requirements. CAGRs derive from elasticity-adjusted volume projections incorporating substitution effects from power tool penetration.
The forecast holds incumbent behavior within observed patterns; aggressive capacity consolidation by diversified tool conglomerates or rapid power tool cost reduction would shift outcomes beyond projected ranges. Quarterly review of heat-treatment apprenticeship enrollment, REACH substance restriction amendment proposals, and municipal landscaping contract award volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Rebar Cutter Market
Tools
Machine Vise Market
Tools
Drill Bit Market
Tools
Vertical Milling Machine Market
Tools
Automated Plasma Beveller Market
Tools
Fastening Power Tools Market
Tools
Europe Machine Tools Market
Tools
Striking Tools Market
Tools
Floor Scraper Market
Tools
Extensometer Market
Tools
Grabber Pole Market
Tools
Woodworking Tools Market
Tools
Ripper Market
Tools
Cordless Multi Rotary Tools Market
Tools
Deburring Tool Market
Tools
Global Vertical Grinding Machine Market