
 Quick Release Pins Market | 2026-2036
Quick Release Pins Market Size, Share, and Industry Trends Forecast 2026-2036
Quick Release Pins Market Insights
Market Context
Buyer concentration among defense contractors and aerospace OEMs is hardening as procurement consolidates under fewer prime vendors with captive MRO networks. Carr Lane sustains its position through deep product specialization in ball lock and detent configurations for jig and fixture applications. Adolf Würth GmbH & Co. KG leverages its European distribution density to control channel access for industrial maintenance customers. Precision Castparts anchors its presence via in-house production of titanium and superalloy pins for jet engine and airframe assemblies.
Technical Definition and Segment Structure
Quick release pins are mechanical fasteners engineered for rapid manual insertion and removal without tools, typically manufactured from stainless steel, titanium, or aluminum alloy with diametrical tolerances of ±0.001 inches and shear strengths exceeding 50,000 psi for aerospace grades. Their primary purpose is to secure components subject to frequent disassembly, including aircraft cowlings, marine hardware, and industrial tooling fixtures. Ball lock and push button variants occupy the largest share of product type demand due to their positive retention mechanisms and compatibility with automated inspection protocols. Stainless steel and titanium material segments capture the highest margin pools, driven by aerospace equipment and defense contractor specifications requiring corrosion resistance and magnetic transparency. Spring loaded configurations represent the fastest-growing product category, spurred by sports equipment manufacturers seeking one-handed operation for bicycles, fitness machines, and tactical gear.
Regulatory Frame and Outlook
FAA airworthiness directives and EASA Part 21 design approval requirements mandate lot traceability and mechanical testing for quick release pins installed on certified aircraft, elevating compliance costs for non-specialist suppliers. REACH and RoHS frameworks in Europe restrict cadmium plating and hexavalent chromium finishes, pushing manufacturers toward nickel-boron and ceramic coating alternatives. Stakeholders must monitor evolving defense procurement standards from the U.S. Department of Defense and NATO maintenance specifications, as these increasingly dictate dual-use qualification pathways that bridge military and commercial aerospace supply chains.
Market Dynamics
Defense procurement consolidation and FAA-EASA material traceability mandates are compressing supplier margins while elevating entry barriers for non-specialist fastener manufacturers.
Growth Catalysts
- Aerospace MRO Expansion:Fleet renewal cycles at Delta Air Lines and United Airlines are driving aftermarket demand for quick-release cowling pins with full lot traceability.
- REACH Phase-Out Deadlines:European cadmium plating restrictions are forcing specification updates across marine and industrial equipment, opening substitution contracts for nickel-boron coated alternatives.
- Titanium Superalloy Advances:Additive manufacturing of near-net-shape pin geometries is reducing material waste in jet engine bracket assemblies.
Market Restraints
- Raw Material Concentration:Sponge titanium supply from Kroll process operators in Japan and Russia creates input cost volatility for aerospace-grade fasteners.
- Dual-Use Export Controls:ITAR classification of precision shear pins limits supplier pools for defense contractors seeking non-US sources.
- Legacy Fixture Lock-In:Ball lock pin geometries standardized in 1980s-era Boeing tooling manuals resist design updates despite superior push-button alternatives.
Strategic Opportunities
- Urban Air Mobility:eVTOL airframe manufacturers in Germany and California are specifying quick-release battery tray pins with integrated RFID tags for fleet tracking.
- EU Defense Fund Procurement:PESCO collaborative armored vehicle programs are harmonizing NATO maintenance specifications, creating cross-border supplier qualification pathways.
- Digital Thread Integration:Blockchain-enabled material certificates from mill to installation are reducing audit costs for AS9100-certified suppliers.
Industry Challenges
- Metallurgical Talent Scarcity:Heat treatment engineers with titanium beta-annealing expertise are retiring faster than apprenticeship programs in Sheffield and Pittsburgh can replace them.
- Test Cell Bottlenecks:FAA-approved shear and fatigue testing facilities face 14-week backlogs for new pin designs, delaying program milestones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quick Release Pins Market |
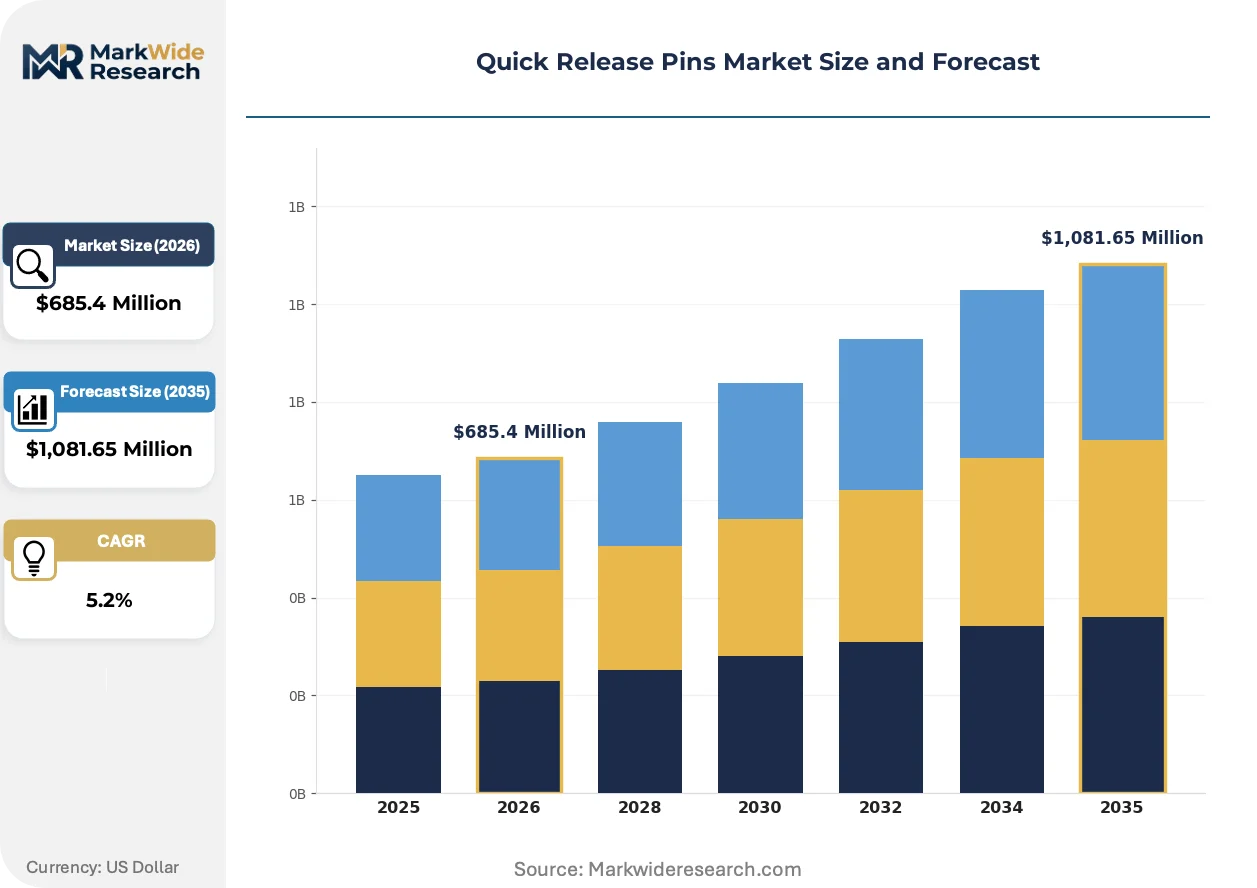
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Push Button, Ball Lock, Lanyard, Detent, Trigger, Spring Loaded Material: Stainless Steel, Aluminum Alloy, Brass, Plastic, Carbon Steel, Titanium Application: Aerospace Equipment, Marine Hardware, Sports Equipment, Construction Tools, Consumer Electronics, Agricultural Machinery End User Industry: Defense Contractors, Shipbuilders, Sports Manufacturers, Industrial Fabricators, Electronics Assemblers, Farm Equipment Producers |
| Companies Covered | Stanley Black & Decker, Carr Lane, Monroe Engineering, Precision Castparts, Globe Industries, Jergens, Pivot Point, Adolf Würth GmbH & Co. KG, LISI Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quick Release Pins Market Trends and Innovations
Additive manufacturing of titanium lattice structures and ceramic coating deposition methods are redrawing cost-performance boundaries for high-cycle aerospace fasteners.
Ceramic physical vapor deposition is replacing hexavalent chromium on stainless steel pins for corrosion protection in salt-spray environments. Gulfstream and Dassault Aviation are qualifying these finishes for exterior latch applications. The technology is modularizing supplier capabilities, separating coating specialists from legacy plating houses.
EASA Part 21 design organization approvals now mandate digital twin documentation for all new fastener submissions, effective across EU member states. This elevates IT infrastructure costs for smaller forges while accelerating approval timelines for integrated OEM-supplier partnerships. German precision engineering clusters are absorbing compliance costs through shared certification consortia.
Defense contractors are unbundling MRO service contracts from original equipment purchases, creating spot-market procurement for replacement pins. Tier 1 primes like Lockheed Martin and Raytheon are building captive parts databases to manage this fragmentation. The shift is most visible in US Army ground vehicle programs, where field-level maintenance units now order directly via FedMall portals.
Quick Release Pins Market Segmentation
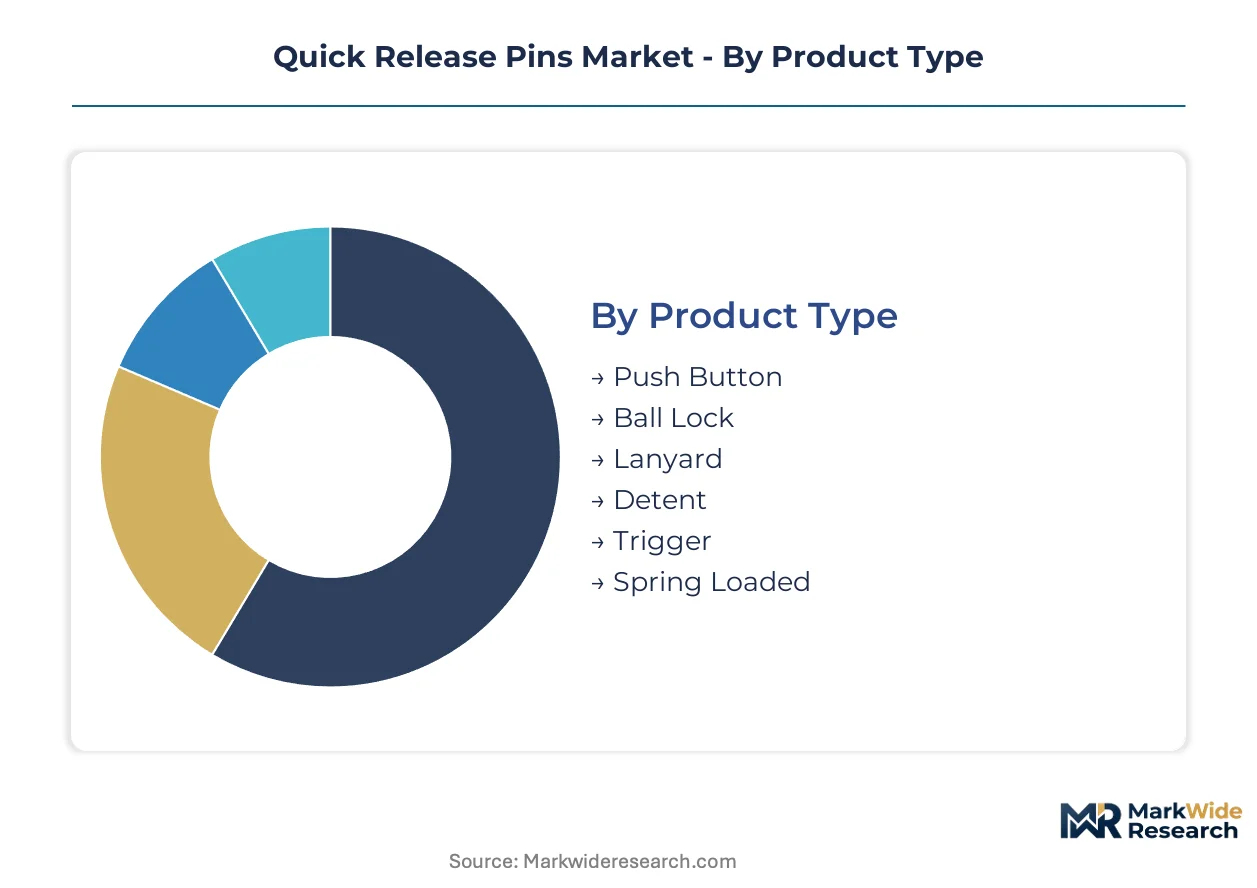
Quick release pins serve radically different performance requirements across aerospace, marine, and industrial applications. Segmentation reveals how material specifications and retention mechanisms align with end-use duty cycles and regulatory exposure. Understanding these splits exposes margin concentration and substitution risks for procurement strategists.
Product Type:
Customization intensity spans from standardized detent pins for mass-market tooling to mission-critical ball lock variants with aerospace lot traceability.
- Ball Lock:Positive retention via spring-loaded balls engages grooves under vibration and shock loads. Defense contractors at Lockheed Martin and Raytheon specify these for tactical vehicle access panels where accidental release risks mission failure.
- Push Button:Single-handed actuation releases the shank through internal cam mechanisms. Dassault Aviation and Gulfstream are qualifying push-button cowling pins with integrated RFID tags for MRO tracking in their Falcon and G-series programs.
- Spring Loaded:These configurations enable rapid cycling without full withdrawal, suiting fitness equipment and bicycle quick-release hubs where users demand one-handed operation.
- Lanyard:Tethered designs prevent loss in marine environments; salt-spray corrosion resistance dictates stainless steel construction for offshore platform maintenance.
- Detent:Simple groove-and-ball retention serves jig and fixture applications where frequent repositioning outvalues positive locking.
- Trigger:Pistol-grip actuation dominates tactical gear and weapon mounting systems requiring gloved-hand operation in combat conditions.
Leading the category by volume: Detent pins for industrial tooling. Growing fastest: Spring loaded variants for sports and tactical equipment.
Material:
Cost tiers separate commodity carbon steel from aerospace-grade titanium with 10x unit price spreads and diverging certification burdens.
- Titanium:Beta-annealed Ti-6Al-4V delivers strength-to-weight ratios critical for jet engine brackets and satellite deployment mechanisms. Precision Castparts controls captive sponge-to-finished-pin supply chains, insulating against Kroll process volatility from Japanese and Russian producers.
- Stainless Steel:Austenitic grades dominate marine hardware and food-processing equipment where magnetic transparency and chloride corrosion resistance matter. EASA Part 21 approvals now mandate ceramic PVD coatings replacing hexavalent chromium finishes.
- Aluminum Alloy:7075-T6 serves weight-sensitive sports equipment and consumer electronics where shear loads remain moderate.
- Carbon Steel:Zinc-plated variants capture construction and agricultural machinery volumes where cost minimization outweighs corrosion exposure.
- Brass:Decorative and low-galling applications in consumer fixtures exploit machinability and aesthetic finishes.
- Plastic:Glass-filled nylon replaces metal in electronics enclosures and temporary fixtures where electrical isolation and cost drive specification.
Highest margin capture: Titanium and stainless steel for certified aerospace. Steepest expansion trajectory: Ceramic-coated stainless alternatives to banned cadmium plating.
Application:
Volume concentration clusters in mature industrial sectors while emerging mobility formats reshape growth vectors.
- Aerospace Equipment:Cowling fasteners, engine mounts, and interior track fittings require full FAA-EASA traceability. Delta and United fleet renewal programs are driving aftermarket pin demand with 14-week test cell backlogs for new designs.
- Marine Hardware:Deck hardware and rigging components face REACH cadmium phase-outs, forcing nickel-boron coating transitions across European shipyards.
- Sports Equipment:Bicycle wheel skewers, fitness machine adjustments, and tactical gear mounts prioritize rapid actuation over ultimate strength.
- Construction Tools:Scaffolding and formwork pins emphasize reusability cycles and impact durability.
- Consumer Electronics:Laptop docking stations and modular device enclosures exploit miniaturized detent mechanisms.
- Agricultural Machinery:Implement attachment pins balance cost pressure with field-replacement accessibility.
Revenue concentration: Aerospace equipment with certification premiums. Gaining share fastest: Urban air mobility battery tray applications.
End User Industry:
Procurement sophistication separates defense primes with captive MRO networks from fragmented agricultural and electronics assemblers.
- Defense Contractors:ITAR-classified shear pins and NATO maintenance specifications create dual-use qualification pathways. US Army ground vehicle programs now route spot-market orders through FedMall portals, unbundling MRO from original equipment contracts.
- Shipbuilders:European yards in Germany and the Netherlands are absorbing REACH compliance costs through shared nickel-boron coating consortia.
- Sports Manufacturers:Brand-driven specification emphasizes user experience and warranty minimization over engineering margins.
- Industrial Fabricators:Jig and fixture builders at Carr Lane's core customer base prioritize interchangeability and catalog breadth.
- Electronics Assemblers:Miniaturization demands push toward plastic and aluminum micro-pins with SMT-compatible footprints.
- Farm Equipment Producers:Deere and CNH specify carbon steel pins with zinc-nickel plating for cost-controlled service parts.
Contract value leadership: Defense contractors with multi-year platform awards. Procurement transformation: Direct field-level ordering bypassing traditional distributor channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kroll-process sponge titanium from Japanese and Russian producers anchors aerospace-grade pin supply chains. Defense procurement consolidation and FAA-EASA traceability mandates are compressing supplier margins across manufacturing clusters. Precision engineering capabilities concentrate where metallurgical heritage intersects with certification infrastructure.
Germany
Adolf Würth GmbH & Co. KG leverages European distribution density to control channel access for industrial maintenance customers. REACH cadmium plating restrictions force specification updates across marine and industrial equipment. Bavarian precision engineering clusters supply Tier 1 aerospace and automotive OEMs with nickel-boron coated alternatives.
United States
Defense contractors at Lockheed Martin and Raytheon are expanding procurement of quick release pins for tactical equipment and vehicle systems. FAA airworthiness directives mandate lot traceability and mechanical testing for certified aircraft installations. Pittsburgh metallurgical talent pools face heat treatment engineer shortages as apprenticeship programs lag retirement rates.
France
Dassault Aviation qualifies push-button cowling pins with integrated RFID tags for MRO tracking in Falcon programs. EASA Part 21 design organization approvals mandate digital twin documentation for all new fastener submissions. Île-de-France aerospace clusters absorb compliance costs through shared certification consortia.
Japan
METI industrial policy supports titanium superalloy advances through additive manufacturing of near-net-shape pin geometries. Kroll process operators create input cost volatility for aerospace-grade fasteners. Nagoya-area precision forges supply jet engine bracket assemblies with reduced material waste.
United Kingdom
Sheffield metallurgical heritage clusters face heat treatment engineer scarcity as beta-annealing expertise retires faster than replacement. EASA REACH frameworks restrict hexavalent chromium finishes, pushing ceramic coating alternatives. Midlands aerospace suppliers build captive parts databases to manage unbundled MRO procurement fragmentation.
Quick Release Pins Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital thread integration and additive manufacturing capabilities. The vendor base stratifies across captive titanium producers, European distribution specialists, and precision engineering houses. Three archetypes dominate: aerospace-grade specialists with in-house superalloy production, industrial maintenance distributors with dense channel control, and precision forges serving jig and fixture applications. Competitive moves concentrate on strategic partnerships for certification consortia and geographic expansion into urban air mobility battery tray specifications.
Among Germany-based fabricators, Adolf Würth GmbH & Co. KG occupies a position exemplifying European distribution density for industrial maintenance customers. Carr Lane Manufacturing Co. represents the precision engineering archetype serving jig and fixture builders with catalog breadth. Precision Castparts Corp. anchors the captive supply tier through in-house production of titanium and superalloy pins. These three entities illustrate how metallurgical control, channel access, and product specialization create defensible positioning against margin compression from defense procurement consolidation.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Carr Lane |
| Monroe Engineering |
| Precision Castparts |
| Globe Industries |
| Jergens |
| Pivot Point |
| Adolf Würth GmbH & Co. KG |
| LISI Aerospace |
| Others |
Pricing and Supply Chain Analysis
Defense contractor procurement consolidation under Lockheed Martin and Raytheon primes compresses supplier pricing power into long-term platform contracts with embedded MRO service bundles. Tier 1 aerospace OEMs extract volume discounts through captive parts databases while specialty fastener producers defend margins via AS9100 certification premiums.
Pricing Analysis
High-volume detent pins for industrial tooling capture thin commodity margins while aerospace-grade titanium ball lock variants command certification premiums. Three-tier pricing structure across premium, standard, and economy levels separates FAA-EASA traceable pins from commercial-grade alternatives and uncoated carbon steel construction pins. Cost compression in the industrial tier intensifies because REACH cadmium phase-outs force coating transitions without price recovery. Agricultural machinery assemblers exhibit highest price sensitivity; defense contractors with ITAR-classified programs show lowest sensitivity due to mission-critical specifications.
Supply Chain Analysis
Sponge titanium supply rests on Kroll process operators in Japan and Russia, creating input cost volatility for aerospace-grade fasteners. Raw material dependencies include beta-annealed Ti-6Al-4V bar stock, austenitic stainless steel rod, and nickel-boron coating chemicals. Single-source vulnerability concentrates in Japanese titanium sponge exports subject to METI export licensing. Distribution runs through Adolf Würth's European industrial maintenance network and Carr Lane's catalog-direct model for jig and fixture builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA-EASA material traceability mandates erect a cost-of-compliance moat that rewards AS9100-certified incumbents while filtering out generalist fastener producers. REACH cadmium plating restrictions compound this barrier by forcing coating technology transitions that demand capital investment.
For Market Incumbents: Lock in titanium sponge supply agreements with Japanese producers to insulate against Kroll process volatility. Deepen captive heat treatment capabilities in Pittsburgh and Sheffield clusters before metallurgical talent scarcity worsens. Defend against additive manufacturing entrants by accelerating digital twin documentation for EASA Part 21 submissions. For New Entrants and Emerging Players: REACH cadmium phase-outs in Europe open a window for nickel-boron coating specialists to capture substitution contracts from marine and industrial equipment OEMs. Target urban air mobility battery tray applications in Germany and California where eVTOL manufacturers lack established supplier relationships. Enter through integrated RFID-tagging capabilities that incumbent forges have been slow to adopt. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision forges with dormant AS9100 certifications in the UK Midlands. Long-term viability hinges on dual-use qualification pathways bridging NATO defense specifications and commercial aerospace. Watch for FedMall portal procurement volume spikes signaling US Army ground vehicle program acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Sponge | Captive supply from Kroll process operators insulates Precision Castparts against Japanese export volatility. |
| Digital Twin Documentation Investment | EASA Part 21 mandates accelerate approval timelines for German precision engineering clusters with shared certification consortia. |
| Nickel-Boron Coating Capacity Expansion | REACH cadmium restrictions force European shipyards to absorb coating transitions through shared supplier networks. |
| RFID-Integrated Pin Development | Dassault Aviation and Gulfstream qualification programs create first-mover advantage for MRO tracking solutions. |
| Urban Air Mobility Supplier Qualification | German eVTOL manufacturers specify quick-release battery tray pins outside legacy aerospace supply chains. |
Research Methodology
Independent corroboration across fastener procurement officers at defense primes, heat treatment engineers at Sheffield and Pittsburgh forges, and regulatory affairs leads at EASA design organizations underwrites the qualitative findings. Primary interviews with Tier 1 aerospace OEM sourcing managers, marine equipment procurement teams at German shipyards, and industrial maintenance distributors supplemented secondary validation through FAA airworthiness directives, EASA Part 21 submission databases, REACH restriction timelines, and US Army FedMall procurement records. Bottom-up segment sizing triangulated against top-down aerospace fleet renewal projections.
Historical reference periods anchored the forecast window to post-pandemic fleet renewal cycles and REACH implementation phases across the analysis window. Modeled segmentation dimensions span product type, material grade, application duty cycle, and end-user procurement sophistication. CAGRs derived from elasticity-adjusted volume projections incorporating titanium sponge price volatility and test cell backlog effects. Industry-specific inputs include Kroll process capacity utilization rates and eVTOL airframe production ramp assumptions.
The model assumes a particular technology adoption path; alternative pathways for additive manufacturing of near-net-shape titanium geometries would alter the outlook. Forecasts reflect assumptions regarding defense procurement consolidation continuity and EASA digital twin mandate adherence timelines. Regulatory enforcement intensity on REACH cadmium restrictions and ITAR classification scope revisions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Gouging Torch Market
Tools
Cordless Long Neck Grinder Market
Tools
Entrenching Tool Market
Tools
Tooling Market
Tools
Tool Pliers Market
Tools
Powder Compacting Pressers Market
Tools
Broaching Tools Market
Tools
Industrial Plate Bending Machines Market
Tools
MIG Guns Market
Tools
Construction Nails Market
Tools
Nut Runner Market
Tools
Rebar Cutter Market
Tools
Bearing Installation Tool Kit Market
Tools
Cordless Multi Rotary Tools Market
Tools
Clamps Market
Tools
Machine Bench Vices Market