
 Global Desktop CNC Machines Market | 2026-2036
Global Desktop CNC Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Desktop CNC Machines Market Analysis
Direct-to-maker online distribution is reshaping how desktop CNC machines reach end users, bypassing traditional industrial equipment dealers. Tormach leverages its domestic manufacturing footprint to sustain short lead times for North American buyers. Carbide 3D competes aggressively on software integration, bundling design-to-cut workflows that reduce operator training thresholds. Roland DG anchors its position in educational channels, where institutional procurement cycles favor established brand recognition.
Desktop CNC machines are compact, computer-controlled subtractive manufacturing systems typically occupying under one square meter of bench space, with spindle speeds ranging from ten thousand to thirty thousand RPM for precision material removal. These systems execute G-code instructions to carve, mill, or cut wood, metal, plastic, and composites for prototyping, small-batch production, and technical education. Router-based systems dominate unit shipments due to lower price points and gentler learning curves for hobbyist and educational buyers, while mill configurations capture stronger margins among prototyping firms demanding tighter tolerances in aluminum and steel. Servo motor technology leads performance-tier positioning for small manufacturers, though stepper motor architectures retain cost advantages in entry-level segments where absolute precision matters less than acquisition price.
CE marking requirements under the EU Machinery Directive and FCC electromagnetic compatibility standards in the United States shape product design cycles, forcing manufacturers to validate safety interlocks and RF emissions before market entry. China's GB standards for industrial equipment and SAMR certification procedures create additional compliance layers for brands targeting manufacturing clusters in Shenzhen and Dongguan. ISO 12100 safety design principles increasingly influence software-controlled hazard mitigation, pushing vendors toward integrated enclosure systems rather than open-frame configurations. Stakeholders must monitor how regional certification divergence affects platform standardization and whether servo motor architectures displace stepper systems in mid-tier price bands.
Market Dynamics
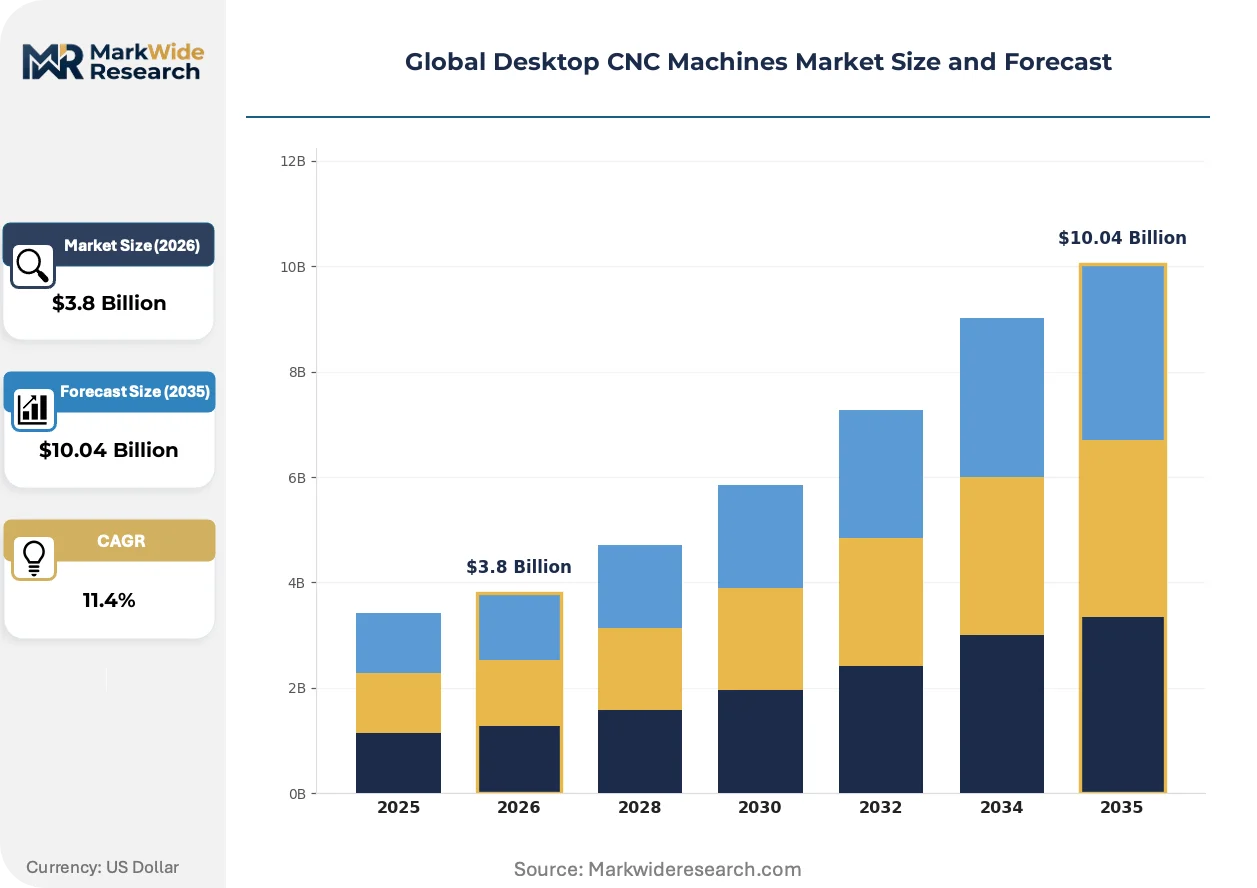
Direct-to-maker distribution is compressing traditional dealer networks while CE marking and FCC compliance costs reshape product architecture decisions for manufacturers targeting cross-border sales.
Growth Catalysts
- Shenzhen Electronics Cluster:Rapid prototyping cycles in China's southern manufacturing corridor generate concentrated demand for compact milling systems that accelerate iteration timelines.
- EU Machinery Directive:CE marking requirements under updated safety frameworks push vendors toward integrated enclosure designs that reduce liability exposure and expand addressable institutional markets.
- Servo Motor Advancement:Performance-tier positioning in small-batch manufacturing favors closed-loop motion control architectures that deliver tighter tolerances in aluminum and steel workpieces.
Market Restraints
- Input Cost Volatility:Ball screw and linear rail components sourced from concentrated Asian suppliers expose margins to shipping rate fluctuations and alloy price swings.
- Technical Ceiling:Thermal expansion in polymer-frame entry systems limits repeatability below the thresholds required for precision metal prototyping applications.
- Substitution Pressure:Desktop additive systems from Formlabs and Prusa Research capture hobbyist budgets with lower training thresholds and reduced material waste.
Strategic Opportunities
- India Manufacturing Corridors:PLI scheme incentives for electronics and medical device production create first-mover openings for compact subtractive tooling in Bangalore and Pune clusters.
- Software-Defined Workflows:Bundled CAD-to-G-code automation reduces operator certification time, opening institutional procurement channels in German vocational schools and Japanese technical colleges.
- GB Standards Alignment:SAMR certification streamlining for industrial equipment enables faster market entry into Dongguan and Suzhou prototyping hubs serving export-oriented SMEs.
Industry Challenges
- G-Code Proficiency Gap:CAM programming expertise scarcity extends commissioning timelines for small manufacturers transitioning from manual to CNC workflows.
- Multi-Standard Certification Burden:Parallel FCC, CE, and GB validation cycles strain engineering resources and delay revenue recognition for new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Desktop CNC Machines Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Router, Mill, Plasma Cutter, Laser Cutter End User: Hobbyists, Small Manufacturers, Educational Institutions, Prototyping Firms Technology: Computer Numerical Control, Stepper Motor, Servo Motor, Hybrid Material: Wood, Metal, Plastic, Composites |
| Companies Covered | Tormach, Carbide 3D, Bantam Tools, Pocket NC, Onefinity, Roland DG, Snapmaker, Inventables, ShopBot Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Desktop CNC Machines Market Emerging Trajectories
Control architecture and distribution mechanics are undergoing parallel transformation. Vendors now compete on software integration depth and certification agility rather than spindle specifications alone.
Closed-loop servo control is migrating from high-end mill configurations into mid-tier router platforms. Prototyping firms in Germany and Japan are adopting these systems to machine aluminum enclosures without thermal drift compensation routines. This capability compression is collapsing the price-performance gap between hobby-grade and professional-grade equipment categories.
ISO 12100 safety design principles are forcing enclosure-integrated hazard mitigation across EU-bound product lines. Manufacturers must validate interlock response times and emergency stop circuits before CE marking approval. Router-based systems with open frames face exclusion from institutional procurement channels where liability protocols demand certified guarding.
Maker-space procurement committees now prioritize bundled training content and cloud-based job monitoring over dealer service networks. Educational buyers in the United States and Netherlands are piloting subscription-based maintenance models that unbundle hardware from software updates. This preference shift favors vendors with domestic assembly footprints that can customize firmware for regional curriculum standards.
Global Desktop CNC Machines Market Segmentation
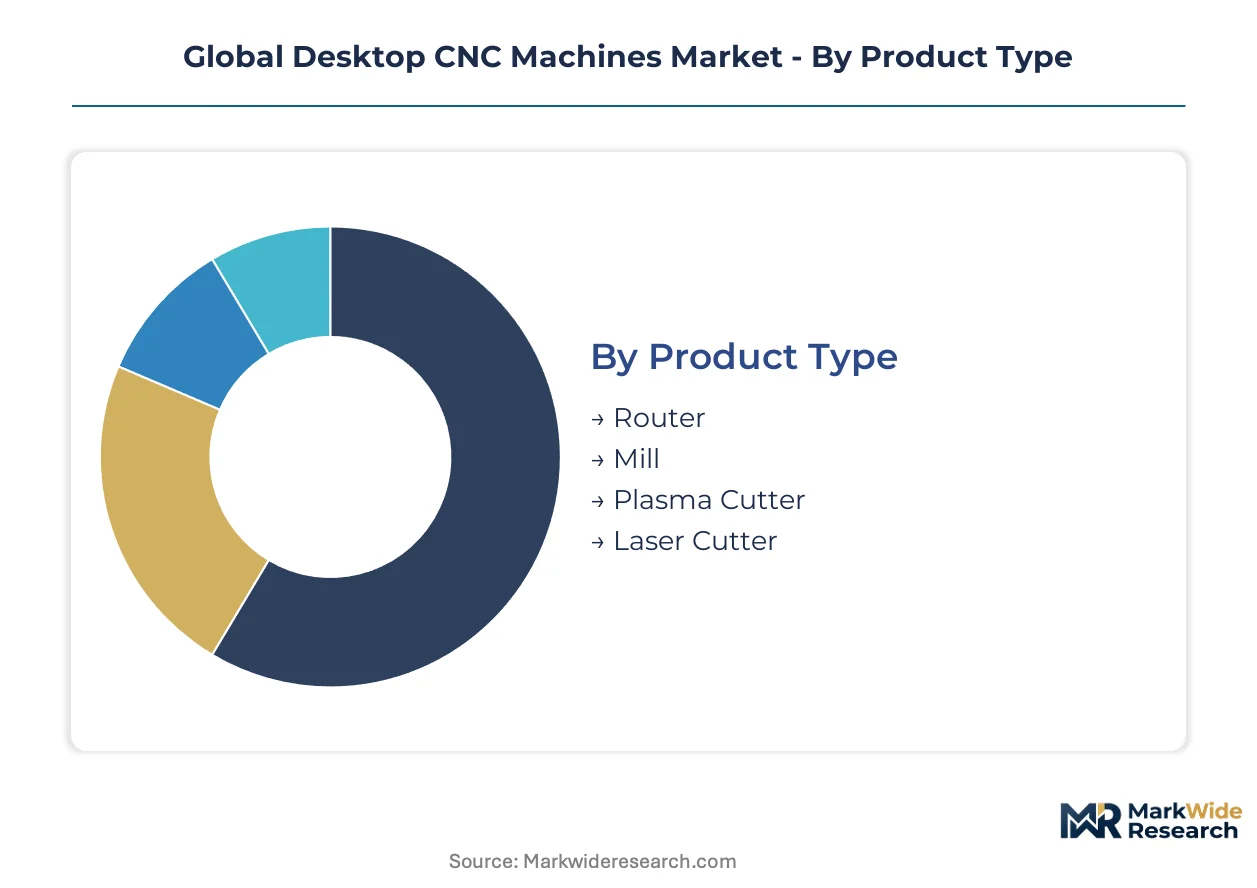
Desktop CNC machine segmentation reveals divergent service intensity across product tiers. Router systems require minimal field support while mill configurations demand calibration expertise that shapes vendor profitability.
Product Type:
After-sales-service intensity varies dramatically across product architectures, with spindle-based systems commanding premium maintenance contracts and consumable-driven platforms operating on razor-thin service margins.
- Router:These systems deploy high-RPM spindles with standardized collet sizes for wood, plastic, and soft metal profiling. Demand clusters in German maker spaces and US vocational programs where entry price points dominate procurement decisions. Service requirements center on bit replacement and dust extraction maintenance rather than precision calibration.
- Mill:Rigid cast-frame constructions with ball screw drives achieve positioning repeatability below 0.01mm for aluminum and steel workpieces. Shenzhen prototyping firms and Japanese precision parts suppliers drive adoption where thermal compensation and periodic ball screw lubrication create recurring service revenue streams.
- Plasma Cutter:Arc-based metal cutting systems require consumable electrode replacement and gas flow calibration.
- Laser Cutter:CO2 and fiber laser platforms demand optical alignment and exhaust filtration maintenance.
Router configurations hold the largest share; momentum sits with Mill systems as servo motor costs decline.
End User:
Customer acquisition cost tiers separate one-time hobbyist purchases from institutional procurement cycles stretching across multiple budget years.
- Hobbyists:Price-sensitive buyers prioritize kit-form assemblies and community-supported firmware over dealer networks. Online forums and YouTube tutorials substitute for formal training, compressing vendor support burdens to warranty claims and spare parts fulfillment.
- Small Manufacturers:Batch production shops in Stuttgart and Osaka require ISO 12100-compliant guarding and documented maintenance logs for insurance coverage. These buyers negotiate service level agreements covering spindle bearing replacement and control software updates.
- Educational Institutions:Curriculum-aligned procurement favors bundled training content and cloud-based job monitoring over raw specifications.
- Prototyping Firms:Rapid iteration cycles demand 24-hour turnaround on technical support and expedited spare parts shipping.
Educational Institutions hold the largest share; momentum sits with Prototyping Firms as electronics development accelerates in southern China.
Technology:
Motion control architectures determine precision ceilings and service technician certification requirements across price tiers.
- Computer Numerical Control:Software-defined motion planning enables multi-axis interpolation for complex geometries. Control firmware customization for GB standards compliance in Dongguan and CE marking in Rotterdam creates engineering service opportunities.
- Servo Motor:Closed-loop encoders eliminate missed steps during aggressive aluminum profiling. German automotive suppliers and Japanese medical device prototypers pay premiums for thermal drift compensation and automatic backlash correction.
- Stepper Motor:Open-loop architectures retain cost advantages in entry-level wood routing applications.
- Hybrid:Mixed motor configurations balance precision and acquisition cost for mid-tier buyers.
Stepper Motor holds the largest share; momentum sits with Servo Motor as aluminum prototyping expands.
Material:
Workpiece material selection dictates spindle power requirements, cutting tool inventories, and dust collection specifications that shape total cost of ownership calculations.
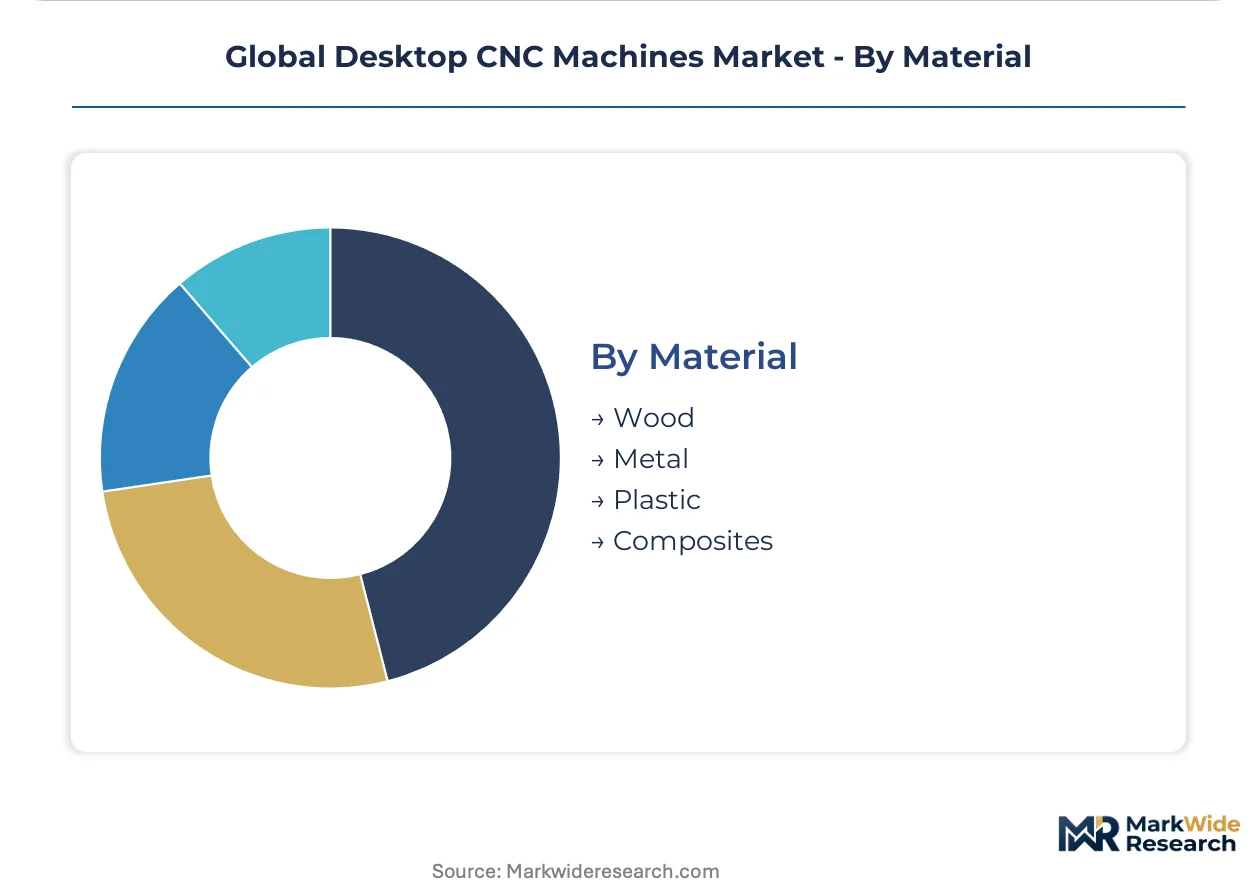
- Metal:Aluminum and steel machining demands rigid frame construction, flood coolant systems, and chip evacuation. Stuttgart precision parts suppliers and Osaka medical device workshops specify these capabilities for production-grade tolerances.
- Wood:Soft and hardwood routing dominates unit shipments with lower spindle power requirements and disposable tooling economics. US cabinetry startups and Netherlands design studios favor these systems for furniture prototyping and custom millwork.
- Plastic:Acrylic and nylon cutting generates specialized chip management and melting prevention protocols.
- Composites:Carbon fiber and fiberglass machining requires dust containment and specialized cutting geometries.
Wood holds the largest share; momentum sits with Metal as small-batch manufacturing professionalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's intermodal connectivity underwrites Benelux distribution networks for compact milling equipment. German rail corridors link Stuttgart manufacturing clusters to Central European prototyping hubs. Shenzhen's container terminals anchor Asia-Pacific supply chains for electronics fabrication tooling.
United States
FCC electromagnetic compatibility standards govern RF emissions validation for control systems entering North American channels. OSHA workplace safety protocols influence enclosure design requirements for educational procurement. Austin hardware startups and Boston-area robotics firms drive adoption of compact subtractive systems for rapid iteration cycles.
Germany
CE marking under the EU Machinery Directive mandates ISO 12100-compliant safety interlocks for institutional buyers. KBA technical standards intersect with industrial equipment certification in automotive supplier networks. Stuttgart precision parts workshops and Munich maker spaces concentrate demand for servo-controlled aluminum machining capabilities.
China
GB standards and SAMR certification procedures create compliance layers for industrial equipment market entry. MIIT industrial policy frameworks support domestic manufacturing of precision motion control components. Shenzhen electronics prototyping clusters and Dongguan export-oriented SMEs generate concentrated demand for compact milling systems.
Japan
METI technology promotion programs accelerate adoption of automated fabrication in small-batch manufacturing. JIS standards govern mechanical precision classifications for industrial equipment procurement. Osaka medical device workshops and Nagoya automotive supplier networks specify closed-loop motion control for tight-tolerance metal workpieces.
India
PLI scheme incentives for electronics and medical device production create openings for compact subtractive tooling. BIS certification requirements shape product adaptation for domestic market entry. Bangalore hardware startups and Pune precision engineering clusters pilot desktop-scale fabrication for export-oriented component manufacturing.
Global Desktop CNC Machines Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying ball screw drives and spindle assemblies. The vendor base spans vertically integrated domestic manufacturers, software-centric bundlers, and educational channel incumbents. Three archetypes dominate: North American assembly operations optimizing lead times, Asian electronics conglomerates leveraging component sourcing scale, and precision equipment legacy players with institutional brand recognition. Geographic expansion and certification agility constitute the primary competitive vectors as cross-border compliance costs reshape product architecture decisions.
Among North American fabricators, Tormach anchors the domestic manufacturing archetype with short lead time positioning for regional buyers. Carbide 3D occupies a position within the software-integrated tier, bundling design-to-cut workflows that reduce operator training thresholds. Roland DG exemplifies the educational channel incumbent, leveraging established brand recognition in institutional procurement cycles where curriculum alignment outweighs raw specifications.
| Leading Market Players |
|---|
| Tormach |
| Carbide 3D |
| Bantam Tools |
| Pocket NC |
| Onefinity |
| Roland DG |
| Snapmaker |
| Inventables |
| ShopBot Tools |
| Others |
Supply Flow & Price Mechanics
The Port of Rotterdam's intermodal freight corridors transmit cost volatility from concentrated Asian component sourcing directly into European distributor pricing tiers, compressing margins for entry-level router systems while insulating premium mill configurations from downstream price erosion.
Pricing Analysis
Volume-discount tiering structures separate hobbyist kit pricing from institutional procurement contracts stretching across multi-year curriculum cycles. Three-tier pricing stratifies across servo-equipped professional mills, closed-frame educational routers, and open-frame entry systems for maker spaces. Price differentiation hinges on CE marking certification status and bundled software maintenance terms. Cost compression in stepper-motor entry segments intensifies because of additive manufacturing substitution, while servo-controlled aluminum-capable platforms command pricing power among Stuttgart precision parts suppliers.
Supply Chain Analysis
Ball screw feedstock and linear rail extrusions draw from concentrated manufacturing in China, Taiwan, and Japan. Spindle motor assemblies, motion control electronics, and cast frame foundries rest on single-source dependencies for high-precision grades. Tariff exposure on Chinese-sourced aluminum extrusions and stepper motor controllers creates margin vulnerability for vendors without alternative Southeast Asian supplier qualification. Distribution runs through direct-to-maker e-commerce platforms and regional industrial equipment distributors serving German vocational schools and Japanese technical colleges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Desktop CNC equipment is shifting toward platform-economics dynamics where software-defined workflows and cloud-based job monitoring create ecosystem lock-in comparable to additive manufacturing ecosystems.
For Market Incumbents: Insulate service revenue streams by embedding predictive maintenance algorithms into control firmware, creating switching costs for Stuttgart small manufacturers already locked into ISO 12100-compliant guarding configurations. Deepen backward integration into ball screw production to offset alloy price volatility from Taiwanese suppliers. Certification investment in streamlined SAMR pathways for Dongguan market entry represents the critical defensive lever against Asian electronics conglomerates. For New Entrants and Emerging Players: Mid-tier servo-controlled router platforms for Indian electronics prototyping corridors under PLI scheme incentives represent the most penetrable entry point for foreign vendors lacking established brand recognition. Bangalore hardware startups and Pune precision engineering clusters lack domestic alternatives for aluminum-capable compact mills. Cloud-native CAD-to-G-code automation with subscription pricing offers the most viable go-to-market angle against entrenched dealer networks. For Investors and Strategic Acquirers: Software-centric bundlers with integrated design-to-cut workflows and established educational channel relationships present the highest-conviction acquisition archetype for portfolio exposure to maker-space procurement shifts. Long-term viability across the analysis window depends on control architecture migration from stepper to servo systems. The signal to monitor is closed-loop encoder cost curves crossing below stepper motor assembly thresholds in mid-tier price bands.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Workflow Integration | Reduces G-code training burdens for German vocational school procurement committees. |
| Servo Motor Architecture Migration | Enables thermal drift compensation for Osaka medical device prototyping tolerances. |
| CE Marking Streamlining | Accelerates institutional channel access under updated EU Machinery Directive frameworks. |
| Direct-to-Maker Distribution Buildout | Bypasses traditional industrial equipment dealer networks serving hobbyist segments. |
| GB Standards Alignment Investment | Unlocks SAMR certification pathways for Dongguan and Suzhou manufacturing cluster entry. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with maintenance directors at Stuttgart precision parts workshops, procurement leads at Japanese medical device prototyping firms, OEM service heads at German automotive supplier networks, and control firmware engineers at Shenzhen electronics clusters. Secondary validation drew from SEC filings of listed precision equipment manufacturers, MIIT industrial policy disclosures, customs records for ball screw and linear rail trade flows, and ISO 12100 safety standard documentation. Bottom-up shipment estimates by product tier and top-down market sizing by end-use application were triangulated against control architecture adoption curves.
Calibration against historical servo motor cost decline trajectories and stepper motor volume shipments anchored the projection framework across the analysis window. Segmentation dimensions modeled include product architecture (router, mill, laser, plasma), motion control technology (stepper, servo, hybrid), end-use vertical (hobbyist, educational, prototyping, small manufacturing), and workpiece material specialization (wood, aluminum, steel, composites). CAGRs were derived from regression analysis of equipment replacement cycles and prototyping firm expansion rates in southern China and southwestern Germany.
Macroeconomic conditions sit as an overlay; deviation in shipping rate indices, aluminum alloy spot prices, or electronics capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline standardization and servo encoder cost curves. Cross-checking against IHS Markit industrial automation equipment databases and MIIT precision machinery output statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Drilling Machine Market
Construction Equipment
Concrete Placing Booms Market
Construction Equipment
North America Welding Equipment Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
Saudi Arabia Construction Equipment Market
Construction Equipment
CNC Lathe Machine Market
Construction Equipment
Global Floor Grinding Machine Market
Construction Equipment
Concrete Pumps Market
Construction Equipment
Australia Concrete Pump Market
Construction Equipment
Compact Electric Construction Equipment Market
Construction Equipment
Commercial Sanitizing Equipment Market
Construction Equipment
Arc Welding Equipment Market
Construction Equipment
China Fire Sprinklers Market
Construction Equipment
Concrete Demolition Professional Equipment Market
Construction Equipment
CNC Machine Market
Construction Equipment
Trenchers Market