
 Metal Casting Market | 2026-2036
Metal Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Casting Market Intelligence
Aluminum is repositioning iron in automotive powertrain and structural applications as OEMs pursue weight reduction targets. Nemak leverages captive die-casting capacity across North American and European automotive corridors. GF Casting Solutions anchors its competitiveness through in-house production of high-pressure aluminum components for premium vehicle platforms. Precision Castparts Corp. specializes in aerospace-grade investment castings that command narrow-tolerance specifications for turbine engine segments.
Metal casting is the process of pouring molten metal into a mold cavity to produce near-net-shape components, typically achieving dimensional tolerances of CT3–CT16 depending on process control and alloy selection. The technique serves as the foundational manufacturing route for complex geometries in automotive, aerospace, and heavy machinery supply chains. Die casting captures the fastest growth trajectory among process types, driven by electric vehicle battery housing and motor enclosure demand. Sand casting retains the largest volume share due to its cost efficiency in producing large iron castings for construction machinery and power generation equipment. Aluminum dominates material type growth as OEMs substitute magnesium and zinc in consumer electronics and automotive heat management applications.
The EPA enforces foundry air emissions standards under the National Emission Standards for Hazardous Air Pollutants, while REACH and the EU Green Deal impose carbon disclosure and substance restriction obligations on European casting imports. China's MEE enforces dual carbon goals that limit coal-fired melting capacity and accelerate electric induction furnace adoption in the Yangtze and Pearl River Delta foundry clusters. Stakeholders must monitor regulatory divergence between carbon-border adjustment mechanisms and domestic scrap availability as determinants of regional cost competitiveness.
Market Dynamics
Die casting is overtaking sand casting in automotive powertrain applications as OEMs prioritize dimensional precision for electric motor housings and battery enclosures, while regulatory pressure from China's MEE and the EU Green Deal forces foundry capacity consolidation across the Yangtze River Delta and Central European industrial corridors.
Growth Catalysts
- EU Green Deal emissions benchmarks:European foundries are retrofitting coal-fired melting capacity with electric induction furnaces to maintain automotive supplier qualifications.
- Electric vehicle battery housing demand:Die-cast aluminum enclosures for lithium-ion packs are pulling capacity expansion across Mexico's Querétaro automotive corridor.
- China's dual carbon goals:MEE enforcement is accelerating scrap-based electric furnace adoption in the Pearl River Delta foundry cluster.
Market Restraints
- Scrap aluminum price volatility:Secondary smelter feedstock costs swing with LME pricing, compressing margin predictability for independent foundries.
- Induction furnace capex barriers:Coal-to-electric conversion requires capital intensity that fragments competitive positioning between integrated and non-integrated producers.
- REACH substance restrictions:ECHA disclosure obligations on imported castings create compliance friction for Asian exporters serving European automotive OEMs.
Strategic Opportunities
- India's Tamil Nadu foundry belt:Underpenetrated die-casting capacity for two-wheeler and passenger vehicle components offers white-space expansion for precision aluminum specialists.
- CSRD carbon disclosure mandates:European corporate sustainability reporting requirements create premium pricing capture for foundries with verified Scope 1-3 emissions data.
- Semi-solid rheocasting convergence:Hybrid processing combining thixotropic metal flow with high-pressure die casting enables thin-wall structural components for EV platforms.
Industry Challenges
- Tooling engineer scarcity:Die design and thermal management expertise concentrates with aging workforces in Germany and Japan, constraining knowledge transfer to emerging production bases.
- CT3-CT6 tolerance certification timelines:Aerospace and medical casting qualifications require 18-24 month validation cycles that delay revenue recognition for new capacity investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Casting Market |
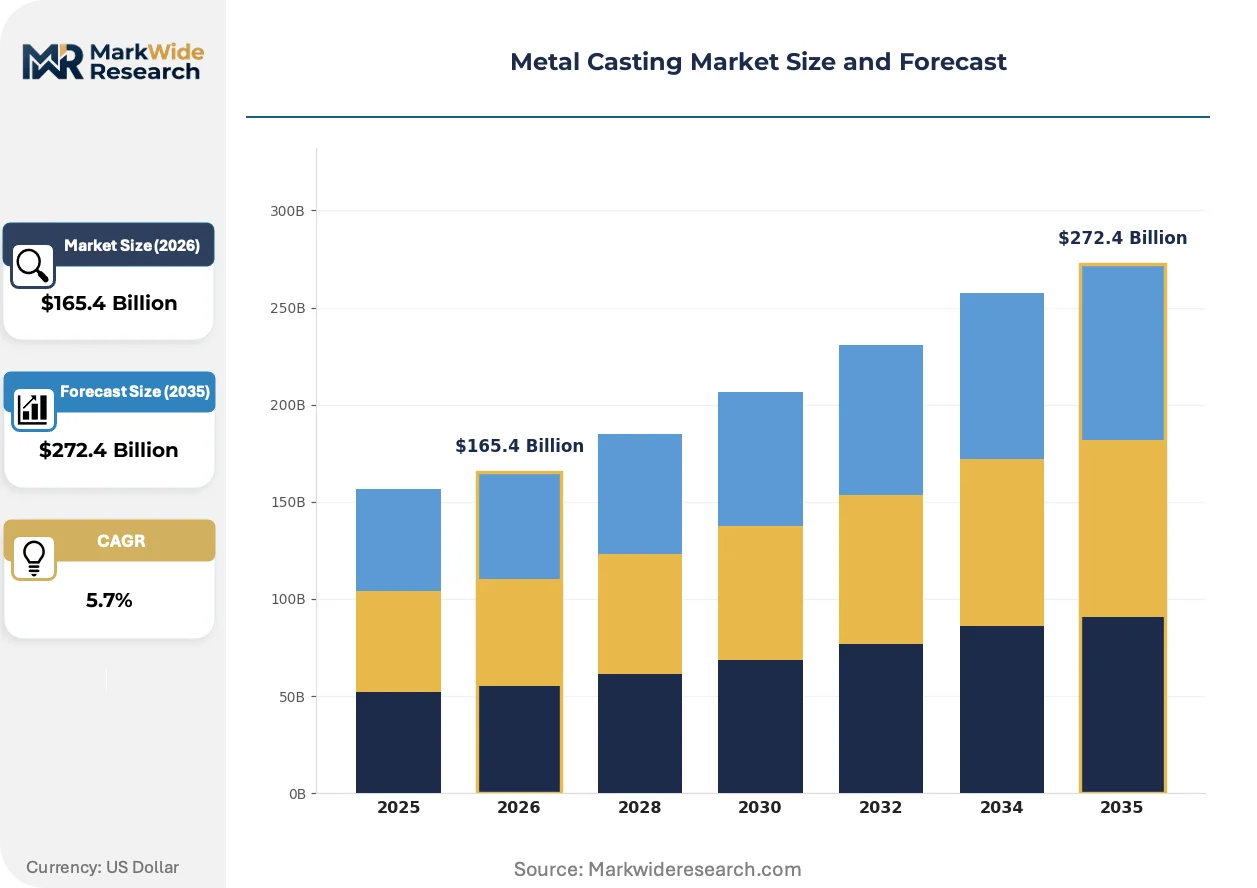
| Market Size in 2026 | $165.4 Billion |
| Market Size in 2035 | $272.4 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Process Type: Sand Casting, Die Casting, Investment Casting, Continuous Casting, Shell Mold Casting, Centrifugal Casting Material Type: Aluminum, Iron, Steel, Copper, Zinc, Magnesium Application: Heavy Machinery, Consumer Electronics, Aerospace Equipment, Construction Machinery, Power Generation Equipment, Marine Engineering End User: OEMs, Aftermarket Suppliers, Heavy Equipment Manufacturers, Marine Builders, Power Plant Operators |
| Companies Covered | Anhui Yingliu Electromechanical, Gibbs Die Casting Group, Precision Castparts Corp., Signicast, GF Casting Solutions, Nemak, Ryobi Limited, Pace Industries, Zhejiang Materials Industry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Casting Market Strategic Shifts & Innovations
Process automation and real-time thermal monitoring are compressing cycle times and defect rates simultaneously, while material substitution patterns and regulatory disclosure requirements reshape competitive positioning across automotive and aerospace supply chains.
High-pressure die casting with vacuum-assisted cavity filling is overtaking conventional gravity casting for structural automotive components. BMW and Mercedes-Benz powertrain divisions specify these processes for front-subframe and motor-housing assemblies. The shift is overtaking sand-cast iron foundries in medium-volume production tiers.
China's MEE dual carbon enforcement limits coal-fired cupola capacity in the Yangtze River Delta cluster. Foundries must retrofit to electric induction melting or face production quota reductions. German automotive Tier 1 suppliers are accelerating supplier audits to verify compliance before contract renewals.
Automotive OEM procurement teams now mandate cradle-to-gate carbon certificates for casting lots, displacing price-only supplier selection. Tier 2 foundries in Mexico's Querétaro corridor are investing in third-party verification to maintain Volkswagen and Nissan supplier status. This behavioral shift is most visible in German and Japanese OEM supply base restructuring.
Metal Casting Market Segmentation
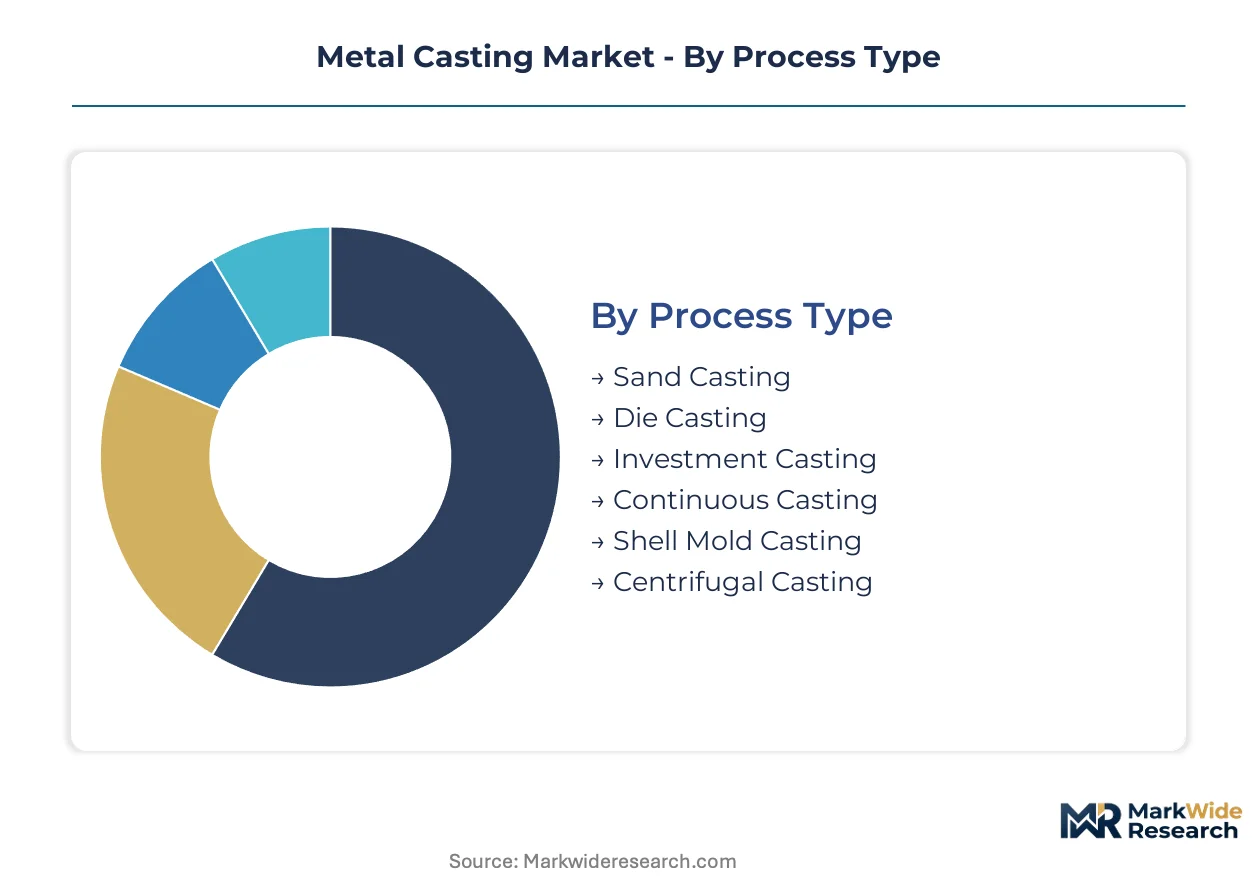
Process certification and dimensional tolerance requirements fragment supplier capabilities across automotive, aerospace, and heavy machinery supply chains. Each segment carries distinct qualification timelines and capital intensity thresholds that determine competitive entry barriers.
Process Type:
Die casting and investment casting demand CT3-CT6 tolerance certification from NADCAP or equivalent aerospace accreditors, while sand casting operates under broader CT10-CT16 specifications with lower regulatory burden.
- Die Casting:High-pressure aluminum injection into hardened steel tooling achieves wall thicknesses below 2mm for electric vehicle battery enclosures. BMW and Mercedes-Benz procurement teams specify this process for motor housings, pulling capacity expansion across Germany and Mexico's Querétaro corridor.
- Sand Casting:Green sand or chemically bonded molds accommodate iron castings exceeding 500kg for construction machinery frames and power generation turbine housings. Cost efficiency sustains dominance in low-volume, heavy-section components where dimensional precision carries lower priority.
- Investment Casting:Ceramic shell processes deliver near-net-shape superalloy components for aerospace turbine blades.
- Continuous Casting:Vertical or horizontal solidification produces semi-finished steel and copper bar stock for downstream machining.
- Shell Mold Casting:Resin-bonded sand shells balance surface finish and cost for medium-complexity steel castings.
- Centrifugal Casting:Rotational metal distribution creates dense, cylindrical geometries for pipes and bearing sleeves.
Leading the category by volume: Sand Casting. Growing fastest: Die Casting.
Material Type:
Alloy selection determines melting technology requirements under China's MEE dual carbon enforcement and the EU Green Deal emissions benchmarks.
- Aluminum:Secondary smelting from scrap feedstock dominates automotive and consumer electronics applications. LME price volatility compresses margin predictability for independent foundries serving Tier 2 supplier networks.
- Iron:Gray and ductile iron grades retain cost advantage in construction machinery and power generation equipment. Coal-to-electric furnace conversion requirements in the Yangtze River Delta cluster accelerate consolidation among non-integrated producers.
- Steel:Carbon and alloy grades serve heavy machinery structural components requiring weldability and fatigue resistance.
- Copper:High thermal and electrical conductivity drives demand for electrical infrastructure and heat exchanger applications.
- Zinc:Low melting point enables thin-wall die casting for consumer electronics housings and hardware.
- Magnesium:Density advantages below aluminum attract aerospace and premium automotive lightweighting programs.
Highest volume concentration: Iron. Steepest expansion trajectory: Aluminum.
Application:
End-use specifications dictate qualification protocols, with aerospace equipment requiring 18-24 month NADCAP validation cycles that delay revenue recognition.
- Heavy Machinery:Large-section iron and steel castings for mining and agricultural equipment frames. OEM procurement in Germany and Japan concentrates orders with foundries holding ISO 3834 welding certification.
- Aerospace Equipment:Nickel-based superalloy investment castings for turbine engine segments. Precision Castparts Corp. and specialized suppliers command narrow-tolerance specifications under FAA and EASA oversight.
- Consumer Electronics:Magnesium and aluminum die castings for laptop chassis and smartphone frames.
- Construction Machinery:High-strength steel and iron components for excavator booms and crane structures.
- Power Generation Equipment:Heat-resistant steel castings for gas and steam turbine housings.
- Marine Engineering:Corrosion-resistant propellers and pump housings in copper alloys and stainless steel.
Dominant revenue share: Heavy Machinery. Climbing the fastest: Aerospace Equipment.
End User:
Customer type determines contract structure, with OEMs mandating cradle-to-gate carbon certificates under CSRD disclosure requirements.
- OEMs:Volkswagen, Nissan, and German automotive procurement teams now require verified Scope 1-3 emissions data for casting lots, displacing price-only supplier selection. Tier 2 foundries in Mexico's Querétaro corridor invest in third-party verification to maintain supplier status.
- Aftermarket Suppliers:Replacement part distributors prioritize inventory flexibility and shorter lead times over dimensional precision.
- Heavy Equipment Manufacturers:Caterpillar and Komatsu specification engineers demand CT8-CT10 tolerance bands for structural weldments.
- Marine Builders:Shipyard procurement in South Korea and Japan emphasizes corrosion testing protocols for seawater exposure.
- Power Plant Operators:Utility maintenance departments source replacement turbine components with 25-30 year service life guarantees.
Largest contract value concentration: OEMs. Expanding most quickly: Heavy Equipment Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Querétaro's special economic zone incentives are concentrating automotive die-casting investment along Mexico's central automotive corridor. Foundry capacity expansion across Germany, China, and India responds to divergent regulatory enforcement timelines for emissions compliance.
China
Electric vehicle battery enclosure demand from BYD and CATL suppliers is pulling aluminum die-casting capacity into the Yangtze River Delta. MEE enforcement of dual carbon goals limits coal-fired cupola operations in Jiangsu and Zhejiang provinces. Foundries in Ningbo and Taizhou are retrofitting to electric induction furnaces to maintain Volkswagen and BMW supplier qualifications.
Germany
BMW and Mercedes-Benz procurement teams specify high-pressure die-cast aluminum motor housings for electric powertrain platforms. EU Green Deal emissions benchmarks force foundry consolidation across Baden-Württemberg and Bavaria. Supplier audits in Stuttgart and Munich industrial corridors now verify cradle-to-gate carbon certificates before contract renewals.
United States
EPA National Emission Standards for Hazardous Air Pollutants enforcement is accelerating coal-to-electric furnace conversions in Ohio and Michigan foundry belts. Ford and General Motors specification engineers mandate CT6-CT8 tolerance bands for transmission housings. Capacity concentrates in Indiana's automotive supplier corridor and Alabama's metalworking cluster.
India
Two-wheeler and passenger vehicle OEMs in Tamil Nadu are sourcing precision aluminum castings for engine blocks and transmission cases. BIS certification requirements and PLI scheme incentives support foundry modernization in Coimbatore and Hosur. The state's foundry belt remains underpenetrated for die-casting capacity relative to projected automotive demand.
Japan
Toyota and Honda procurement teams specify investment-cast superalloy components for hybrid powertrain systems. METI carbon neutrality roadmaps drive electric furnace adoption in Aichi and Shizuoka prefectures. Nagoya's automotive supplier corridor maintains concentration of tooling engineering expertise for high-tolerance die design.
Metal Casting Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated Tier 1 suppliers capturing automotive OEM contracts while independent foundries serve aftermarket and industrial channels. The vendor base organizes around three archetypes: captive die-casters with automotive parent-company relationships, precision investment-casting specialists serving aerospace qualification protocols, and commodity sand-casting operators in construction machinery supply chains. Capacity expansion and backward integration into scrap smelting represent the dominant competitive moves.
Among North American automotive die-casting specialists, Gibbs Die Casting Group and Pace Industries occupy positions within the contract manufacturing tier serving Detroit Three and Japanese transplant OEMs. Precision Castparts Corp. exemplifies the aerospace-grade investment casting archetype, anchoring narrow-tolerance superalloy supply chains under FAA and EASA oversight. GF Casting Solutions represents the European integrated model with in-house high-pressure aluminum production for premium vehicle platforms.
| Leading Market Players |
|---|
| Anhui Yingliu Electromechanical |
| Gibbs Die Casting Group |
| Precision Castparts Corp. |
| Signicast |
| GF Casting Solutions |
| Nemak |
| Ryobi Limited |
| Pace Industries |
| Zhejiang Materials Industry Group |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up die-casting specialists across North America and Europe impose pricing discipline through captive scrap-smelting capacity and long-term OEM offtake agreements, compressing margin volatility for non-integrated competitors while concentrating supply leverage in automotive corridor clusters.
Pricing Analysis
Premium pricing attaches to die-cast aluminum lots with sub-4-week lead times for EV battery enclosure programs, while spot inventory of sand-cast iron components trades at discounts due to demand cyclicality in construction machinery. Three-tier pricing structure across NADCAP-certified aerospace, IATF-automotive, and commodity industrial grades differentiates contract values. Pricing pressure stems from LME aluminum volatility feeding secondary smelter cost bases. Aftermarket distributors exhibit highest price sensitivity; aerospace OEMs prioritize tolerance certification over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Volkswagen and BMW procurement teams, while independent foundries serve Tier 2 supplier networks through distributor intermediaries. Supply concentrates in China's Yangtze River Delta, Germany's Baden-Württemberg corridor, and Mexico's Querétaro automotive belt. Raw material flows draw from scrap aluminum collection networks, iron ore pellet feeds, and nickel-based superalloy ingots. Single-source vulnerability sits with German tooling engineering expertise for high-tolerance die design. Distribution runs through just-in-time sequences to OEM assembly plants and warehouse stocking for aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over scrap-smelting capacity determines cost competitiveness under China's MEE dual carbon enforcement and EU Green Deal emissions benchmarks.
For Market Incumbents: To counter margin compression from LME aluminum volatility, Nemak and GF Casting Solutions should deepen captive scrap-smelting penetration in Mexico's Querétaro corridor. Securing NADCAP certification for additional aerospace turbine blade capacity insulates revenue against automotive demand cyclicality. For New Entrants and Emerging Players: Tier 2 automotive supplier procurement teams in India's Tamil Nadu foundry belt offer white-space entry for precision aluminum die-casters with BIS certification. Targeting two-wheeler engine block programs with semi-solid rheocasting capability bypasses entrenched sand-cast iron incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor electric-induction retrofit specialists in China's Pearl River Delta facing MEE production quota pressure. Foundries with verified Scope 1-3 emissions data command premium multiples under CSRD disclosure mandates. Watch for Volkswagen and BMW supplier audit failures as inflection signals for consolidation targets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Smelting | Captive aluminum feedstock supply locks margin stability against LME volatility for die-casters serving German OEMs. |
| Electric Induction Furnace Retrofit | Coal-to-electric conversion preserves MEE compliance and Volkswagen supplier status in Yangtze River Delta clusters. |
| NADCAP Aerospace Certification | 18-24 month qualification cycles create defensive moats for investment-casting specialists in turbine engine supply chains. |
| Semi-Solid Rheocasting Adoption | Thixotropic metal flow enables thin-wall EV structural components specified by BMW and Mercedes-Benz platform engineers. |
| CSRD Carbon Disclosure Verification | Third-party Scope 1-3 certification secures premium pricing from European OEM procurement teams under EU Green Deal mandates. |
Research Approach
Multi-period observation of foundry capacity utilization rates, MEE enforcement actions, and OEM supplier audit frequencies anchored the trend analysis, supplemented by interviews with die-casting plant managers, automotive Tier 1 procurement directors, aerospace quality engineers, and scrap metal trading specialists. Secondary validation drew from EPA National Emission Standards filings, ECHA REACH substance restriction updates, China MEE dual carbon policy bulletins, and SEC 10-K disclosures from listed foundry operators. Bottom-up capacity modeling and top-down automotive production forecasts were triangulated against alloy consumption patterns.
Input-output matrices mapped process-type capacity by material and application across the projection horizon, with segmentation dimensions covering die-cast versus sand-cast versus investment-cast processes, aluminum-iron-steel-copper alloy tiers, and automotive-aerospace-heavy machinery end-use splits. CAGRs were derived from production-weighted capacity expansion schedules and OEM platform electrification roadmaps. Forecast inputs incorporated induction furnace retrofit capex cycles and scrap aluminum availability projections.
Several conditions sit outside the modeled scope, including unannounced MEE production quota reductions, sudden REACH substance list expansions, and geopolitical disruptions to German automotive export demand. Forecasts reflect base-case assumptions about regulatory enforcement continuity and OEM electrification timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Metal Forging Parts Market
Metals
Zinc Dust Market
Metals
Steel Drums Market
Metals
Brazil Aluminum Market
Metals
Trivalent Chromium Finishing Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
Ruthenium Market
Metals
Europe Aluminium Wire Rod Market
Metals
Stainless Steel Panels Market
Metals
Beryllium Copper Billet Market
Metals
Amorphous Metal Cores Market
Metals
Smelting Chemicals Market
Metals
Nickel Market
Metals
Beryllium Copper for Telecommunication Market
Metals
North America Aluminium Powder Market
Metals
Global Tool Steel Market