
 Zinc Dust Market | 2026-2036
Zinc Dust Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Dust Market Analysis
The EU Green Deal is realigning specifications for anticorrosion coatings across European shipyards and infrastructure contractors. EverZinc leverages vertical integration from mined ore to atomized powder, sustaining cost advantages across multiple purity grades. U.S. Zinc anchors North American supply through dedicated production of ASTM-compliant granular product for hot-dip galvanizers. Toho Zinc Co., Ltd dominates battery-grade flake output in East Asia, where electronics manufacturers require ultra-low lead content.
Zinc dust consists of fine metallic zinc particles produced through distillation or atomization, typically registering 95% to 99.9% purity depending on intended application. The material functions primarily as a sacrificial anode in corrosion protection systems and as a chemical reductant in alkaline battery cathodes. Powder and flake categories command premium positioning in battery and pharmaceutical applications where particle size distribution directly impacts electrochemical performance. Coatings remains the volume anchor, though high-purity grades for electronics end users are expanding fastest as solid-state battery research intensifies.
EPA oversight of zinc manufacturing effluent shapes domestic production economics in the United States, while REACH registration requirements govern import volumes into European chemical markets. China's MEE enforces dual carbon goals that constrain energy-intensive distillation capacity, tightening supply for industrial-grade material. Stakeholders must monitor evolving purity thresholds from battery OEMs and track how regulatory shifts in major producing regions reshape accessible supply pools.
Market Dynamics
China's MEE dual carbon goals are constraining energy-intensive distillation capacity, tightening industrial-grade supply pools while battery OEMs simultaneously escalate purity thresholds for solid-state research.
Growth Catalysts
- EU Green Deal anticorrosion mandates:European shipyards and infrastructure contractors face realigned coating specifications, expanding specification-grade zinc dust procurement for cathodic protection systems in marine applications.
- India's industrial corridor expansion:Domestic galvanizing capacity scaling in Gujarat generates concentrated demand pull for ASTM-compliant granular product across hot-dip operations.
- Solid-state battery research intensification:Electronics manufacturers in East Asia require ultra-low lead content flake material, accelerating premium-grade volume commitments from battery cathode producers.
Market Restraints
- Energy cost volatility:Distillation and atomization processes remain electricity-intensive, exposing producers to power tariff fluctuations that compress margin structures on industrial-grade output.
- Feedstock concentration risk:High-purity zinc ore supply concentrates in select mining jurisdictions, creating vulnerability to export restriction policies or logistics disruptions.
- REACH registration friction:European chemical market entry requires extensive substance dossiers, extending lead times and compliance costs for non-EU producers seeking import access.
Strategic Opportunities
- Underpenetrated pharmaceutical applications:Fine particle zinc dust serves as a chemical reductant in active pharmaceutical ingredient synthesis, with specification-grade supply currently limited to specialty chemical distributors.
- EPA effluent standard alignment:U.S. domestic producers investing in closed-loop water treatment capture preferential positioning with federal contractors requiring domestic content verification.
- Aluminum-zinc coating convergence:Hybrid coating formulations combining zinc dust with aluminum flakes are penetrating automotive underbody applications, opening specification development opportunities for alloy particle producers.
Industry Challenges
- Particle size certification complexity:Battery OEMs demand increasingly narrow distribution curves for electrochemical performance, requiring capital-intensive laser diffraction testing infrastructure that mid-scale atomization facilities lack.
- Cross-regulatory compliance staffing:Simultaneous adherence to China's GB heavy metal standards, EPA effluent protocols, and REACH substance registration creates specialized regulatory affairs capacity constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Dust Market |
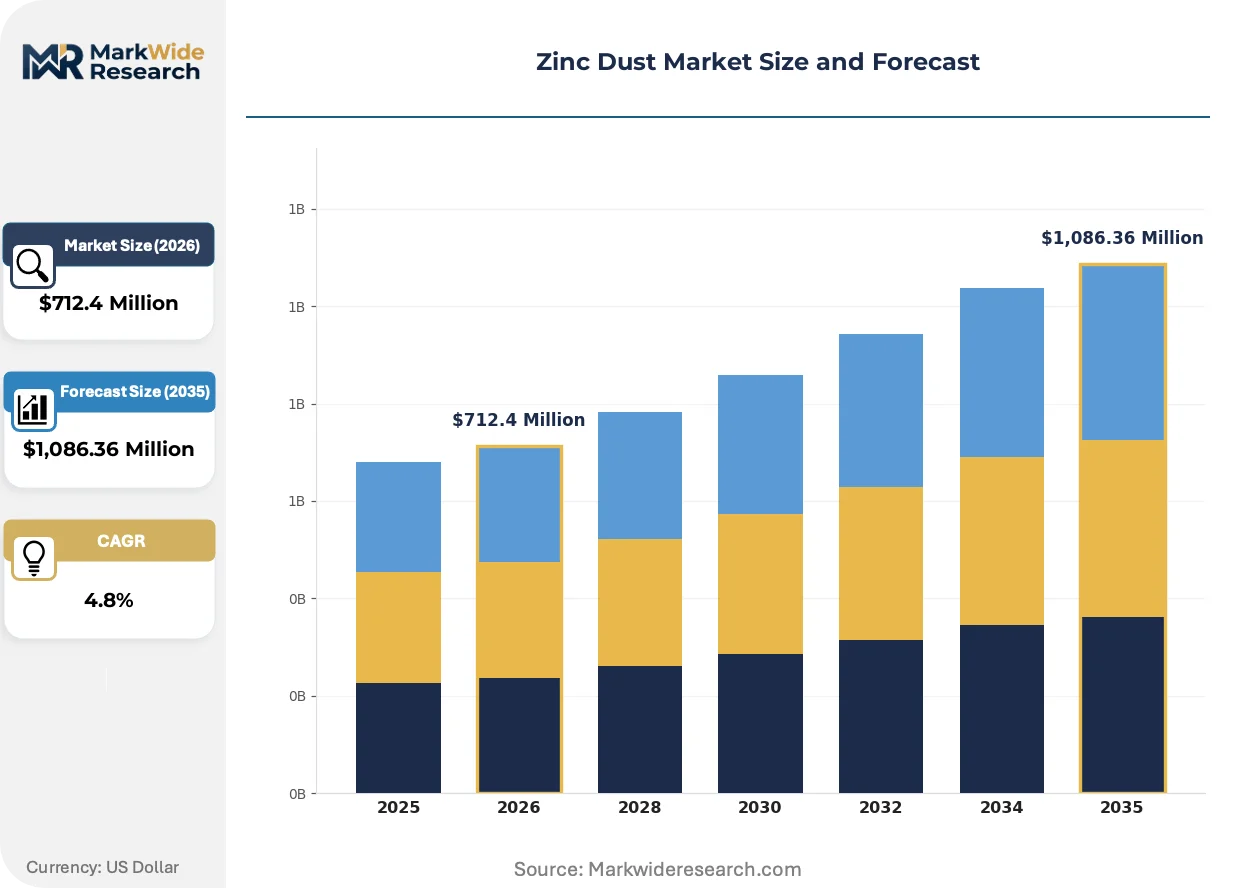
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,086.36 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Flake, Pellet Application: Coatings, Batteries, Rubber, Pharmaceuticals End User: Construction, Automotive, Chemical, Electronics Grade: Industrial, Commercial, High Purity, Others |
| Companies Covered | EverZinc, U.S. Zinc, Zochem, Hanchang, Numinor Chemical Industries Ltd, Pars Zinc Dust Manufacturing Co., Toho Zinc Co., Ltd, Hakusui Tech Co., Ltd, Zochem LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Dust Market Emerging Trajectories
Atomization technology advances and regulatory emission tightening are compressing the viable production technology set while end-use purity requirements stratify across coating, battery, and pharmaceutical applications.
Plasma atomization systems are unifying particle morphology control with energy efficiency gains in high-purity zinc dust production. Battery cathode manufacturers in South Korea and Japan are adopting plasma-processed spherical powder at accelerating rates. This technology is unifying previously separate quality tiers by enabling single-production-line flexibility across standard and battery-grade specifications.
REACH authorization清单 expansion is restricting lead content thresholds in imported zinc dust categories. European coating formulators must now certify sub-50 ppm lead levels for marine infrastructure contracts. Battery-grade flake destined for electronics assembly faces the most stringent enforcement, driving substitution toward electrolytic production methods.
Specification-driven supplier consolidation is compressing qualified vendor lists among multinational galvanizing networks. Large hot-dip operators in Germany and the United States are consolidating annual contracts with single-source atomization specialists capable of ASTM compliance documentation. This concentration is most visible in automotive supply chains where OEM traceability requirements eliminate spot-market procurement flexibility.
Zinc Dust Market Segmentation
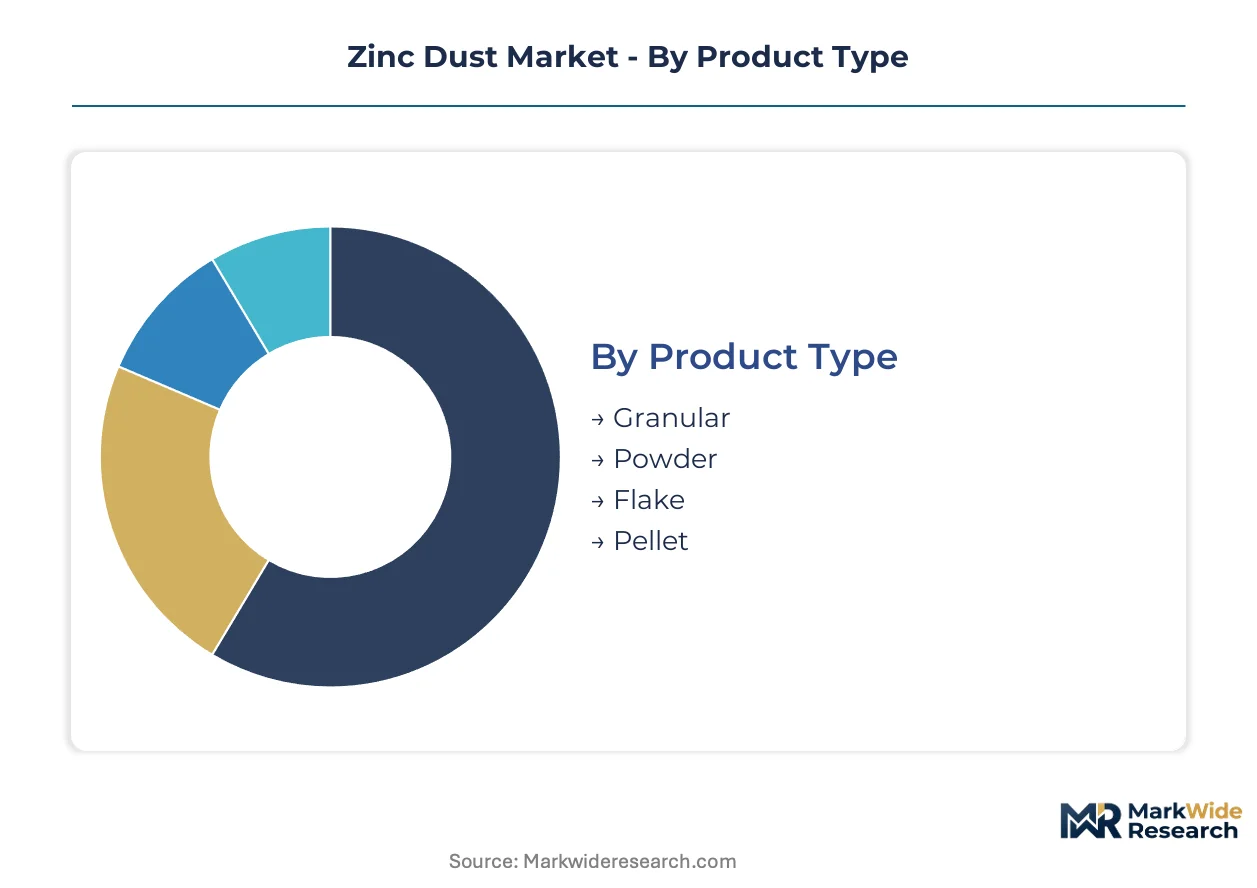
Zinc dust procurement decisions hinge on purity thresholds and particle morphology, with coating formulators prioritizing ASTM-compliant granular grades while battery cathode manufacturers demand ultra-low lead flake. Specification-grade material commands substantial premiums over industrial-grade output, creating tiered supply structures that stratify vendor relationships across end-use verticals.
Product Type:
Particle geometry determines electrochemical performance in battery applications and spray characteristics in coating systems, making morphology the primary technical discriminator in buyer specifications.
- Granular:Coarse spherical particles produced through atomization, typically registering 95-98% purity. Hot-dip galvanizers in India's Gujarat industrial corridor specify this grade for ASTM-compliant coating operations where particle size distribution impacts bath fluidity and adhesion uniformity.
- Powder:Fine particulate material with controlled distribution curves, commanding premium positioning in pharmaceutical synthesis where chemical reductant purity directly impacts active pharmaceutical ingredient yield. Solid-state battery research intensification is accelerating volume commitments for specification-grade powder in South Korean cathode manufacturing.
- Flake:Lamellar morphology with high surface area-to-mass ratio, serving specialty coating applications requiring planar particle orientation.
- Pellet:Compacted spherical agglomerates designed for controlled dissolution rates in chemical processing applications.
Volume sits with Granular; growth tilts toward Powder.
Application:
End-use performance requirements stratify purity thresholds, with coating applications tolerating broader specification bands than electrochemical or pharmaceutical uses where trace contamination degrades functionality.
- Coatings:Sacrificial anode formulations for cathodic protection systems, representing the volume anchor across marine infrastructure and industrial galvanizing. EU Green Deal anticorrosion mandates are expanding specification-grade procurement from European shipyards facing realigned coating standards.
- Batteries:Alkaline and solid-state cathode chemistry applications requiring ultra-low lead content. Electronics manufacturers in East Asia enforce sub-50 ppm thresholds, driving substitution toward electrolytic production methods and plasma atomization systems.
- Rubber:Vulcanization activator and heat stabilizer functions in tire and industrial rubber manufacturing.
- Pharmaceuticals:Chemical reductant in active pharmaceutical ingredient synthesis, with specification-grade supply currently limited to specialty chemical distributors serving contract manufacturing organizations.
Coatings dominates current offtake; Batteries climbs the fastest specification-grade trajectory.
End User:
Customer procurement scale and compliance documentation requirements separate spot-market buyers from annual contract relationships with atomization specialists.
- Construction:Infrastructure contractors and steel fabricators specifying ASTM-compliant material for structural galvanizing. Germany's large hot-dip operators are consolidating annual contracts with single-source suppliers capable of traceability documentation required by automotive OEM supply chains.
- Automotive:Underbody coating and component galvanizing applications where OEM traceability requirements eliminate spot-market procurement flexibility. Hybrid aluminum-zinc formulations are penetrating this segment, opening specification development for alloy particle producers.
- Chemical:Process industry reductant applications and specialty chemical manufacturing.
- Electronics:Battery cathode and semiconductor packaging applications demanding the highest purity grades with ultra-low heavy metal content.
Construction holds the largest contract volume; Electronics posts the steepest purity-premium expansion.
Grade:
Certification tier separates commodity industrial material from specification-grade output requiring capital-intensive laser diffraction testing infrastructure and substance dossier compliance.
- Industrial:Standard purity grades for general galvanizing and chemical processing, facing supply constraints from China's MEE dual carbon goals that restrict energy-intensive distillation capacity.
- Commercial:Mid-tier specification material bridging industrial and high-purity categories.
- High Purity:Battery-grade and pharmaceutical-grade material with documented trace element certification. REACH authorization清单 expansion restricting lead content thresholds is tightening accessible supply pools for European coating formulators and electronics manufacturers.
- Others:Specialty and custom-blended grades serving niche applications.
Industrial grade anchors volume throughput; High Purity captures the fastest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's industrial corridor concentrates India's galvanizing capacity expansion, while China's Yangtze River Delta battery manufacturers drive high-purity flake procurement. Regulatory divergence across major producing regions is fragmenting accessible supply pools and reshaping procurement geography.
China
MEE dual carbon goals constrain energy-intensive distillation capacity in Shandong and Henan provinces, tightening industrial-grade supply. GB standards for heavy metal emissions escalate feedstock requirements for battery-grade material production. Yangtze River Delta electronics manufacturers in Suzhou and Wuxi scale ultra-low lead flake procurement for solid-state battery cathode research.
United States
EPA effluent oversight shapes domestic production economics across Ohio and Pennsylvania atomization facilities. Federal contractors demand domestic content verification for infrastructure galvanizing contracts. Midwest hot-dip operators consolidate annual supply agreements with ASTM-compliant granular producers, eliminating spot-market procurement flexibility.
Germany
EU Green Deal anticorrosion mandates expand specification-grade procurement from Hamburg and Bremen shipyards facing realigned coating standards. REACH authorization expansion restricts lead content thresholds below 50 ppm for marine infrastructure contracts. North Rhine-Westphalia galvanizing networks consolidate qualified vendor lists with single-source atomization specialists.
India
Domestic galvanizing capacity scaling in Gujarat's industrial corridor generates concentrated demand pull for ASTM-compliant granular product. BIS certification requirements tighten import substitution pressure on high-purity grades. Mundra and Hazira port clusters anchor procurement logistics for construction sector hot-dip operations serving national infrastructure buildout.
Japan
Electronics manufacturers in Osaka and Nagoya enforce sub-50 ppm lead thresholds for battery-grade flake. METI industrial decarbonization targets pressure energy-intensive production methods. Kyushu-based chemical processors expand pharmaceutical-grade powder procurement for active pharmaceutical ingredient synthesis applications.
Zinc Dust Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade and particle morphology dimensions. The vendor base stratifies into three tiers: integrated mining-to-powder operators, standalone atomization specialists, and regional trading houses. Strategic archetypes include purity-grade specialists, coating-formulator captive suppliers, and battery-cathode specification developers. Capacity expansion and backward integration into mined ore supply represent dominant competitive vectors.
Among integrated operators, EverZinc and U.S. Zinc exemplify scale-driven archetypes spanning multiple purity grades, while Toho Zinc Co., Ltd occupies the premium-tier position for battery-grade flake production in East Asian electronics supply chains. These three anchors illustrate how geographic concentration in raw material access combines with specification-grade certification capacity to determine competitive positioning.
| Leading Market Players |
|---|
| EverZinc |
| U.S. Zinc |
| Zochem |
| Hanchang |
| Numinor Chemical Industries Ltd |
| Pars Zinc Dust Manufacturing Co. |
| Toho Zinc Co., Ltd |
| Hakusui Tech Co., Ltd |
| Zochem LLC |
| Others |
Supply Flow & Price Mechanics
Battery OEMs' escalating purity thresholds for solid-state cathode research are forcing atomization specialists to retool production lines and absorb capital-intensive laser diffraction testing costs, compressing margins on industrial-grade material while amplifying premiums for specification-grade output.
Pricing Analysis
Value-based pricing anchored to electrochemical yield performance governs battery-grade powder and flake transactions, with South Korean cathode manufacturers paying substantial premiums for plasma-processed spherical material that delivers consistent cathode efficiency. Price differentiation separates ASTM-compliant granular grades for hot-dip galvanizers from ultra-low lead flake certified below 50 ppm for electronics assembly. Cost compression in industrial-grade categories is intensifying because China's MEE dual carbon goals constrain energy-intensive distillation capacity. Construction sector galvanizers in India exhibit the highest price sensitivity, while East Asian electronics manufacturers demonstrate inelastic demand for battery-grade material.
Supply Chain Analysis
Freight cost differentials between containerized atomized powder and bulk granular shipments are reshaping procurement geography for European coating formulators facing REACH registration friction. Raw material supply concentrates in Australia, Peru, and China as the dominant mined zinc ore jurisdictions. Production draws from high-purity ore feedstock, electricity-intensive distillation capacity, and specialized atomization equipment. Single-source vulnerability sits with plasma atomization system suppliers serving battery-grade specification developers. Distribution runs through annual contract relationships with multinational galvanizing networks rather than spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification-grade certification requirements are consolidating the vendor base, with REACH authorization expansion and particle size certification complexity forcing mid-scale atomization facilities toward acquisition or exit.
For Market Incumbents: Lock in annual supply agreements with Germany's automotive OEM supply chains before qualified vendor lists compress further. Invest in backward integration into mined ore supply to secure feedstock cost advantages as China's MEE dual carbon goals tighten industrial-grade supply pools. Prioritize plasma atomization capacity additions in South Korea to capture accelerating battery-grade volume commitments. For New Entrants and Emerging Players: Plasma atomization technology for pharmaceutical-grade powder synthesis offers the most penetrable white-space target, with specification-grade supply currently limited to specialty chemical distributors serving Kyushu-based active pharmaceutical ingredient processors. Enter through toll manufacturing partnerships with established atomization specialists lacking laser diffraction testing infrastructure, rather than greenfield capacity investment. For Investors and Strategic Acquirers: Re-rating potential sits with integrated mining-to-powder operators given battery OEMs' simultaneous escalation of purity thresholds and supplier consolidation mandates. Long-term viability favors archetypes with captive ore supply and multi-grade production flexibility across coating, battery, and pharmaceutical applications. Watch for inflection when solid-state battery research transitions from pilot-scale to commercial cathode procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Atomization Capacity Expansion | Enables single-line flexibility across standard and battery-grade specifications for South Korean cathode manufacturers. |
| Backward Integration into Mined Ore Supply | Secures feedstock cost advantages as China's MEE dual carbon goals constrain distillation capacity. |
| REACH Registration Completion | Unlocks European marine infrastructure contracts requiring sub-50 ppm lead certification. |
| Long-term Supply Agreement with Automotive OEMs | Eliminates spot-market procurement flexibility through traceability documentation requirements. |
| Joint Venture with Pharmaceutical Distributors | Accesses underpenetrated active pharmaceutical ingredient synthesis applications in Kyushu chemical processing clusters. |
Methodological Framework
Independent corroboration across primary interviews with plant managers at atomization facilities, procurement leads at downstream galvanizing networks, distribution channel partners serving coating formulators, and technical R&D directors at battery cathode manufacturers underwrites the qualitative findings. Secondary validation draws from customs and trade data, SEC filings of integrated mining-to-powder operators, GB standards documentation from China's MEE, and REACH substance dossiers. Bottom-up capacity assessments and top-down demand segmentation triangulate volume estimates.
Rate-of-change decomposition across the analysis window separates volume growth into grade-tier substitution effects, end-use industry mix shifts, and regional production hub realignments. The analytical framework models product type, application, end user, and grade dimensions alongside regional regulatory cluster differentiation. CAGRs derive from fitted trend extrapolation adjusted for policy inflection points and technology adoption S-curves. Forecast inputs incorporate China's dual carbon goal implementation pace and solid-state battery research commercialization timelines.
Several conditions sit outside the modeled scope, including abrupt export restriction policies in major ore-producing jurisdictions and unanticipated breakthroughs in zinc-free cathode chemistries. Forecasts reflect assumptions about regulatory enforcement consistency and technology cost curves that could revise materially. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
High Magnetic Induction Grain-Oriented Silicon Steel Market
Metals
Global Brass Rods Market
Metals
Niobium Market
Metals
Rhodium Market
Metals
Global Stretch Spring Wire Market
Metals
Global Nickel Alloy Welding Consumables Market
Metals
Scandium Market
Metals
Potassium Platinochloride Market
Metals
Niobium Oxide Market
Metals
GCC Metal Forging Market
Metals
Recycled Metal Market
Metals
Global Aluminium Wire Rod Market
Metals
North America Aluminum Casting Market
Metals
Medium Carbon Steel Market
Metals
Amorphous Metal Cores Market
Metals
Aluminum Scrap Recycling Market