
 Latin America Construction Chemicals Market | 2026-2036
Latin America Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Construction Chemicals Market Insights
Technical service and application engineering support is rebalancing how construction chemicals are sold in Latin America, shifting value from commodity supply to performance guarantees. BASF SE leverages its regional admixture labs to anchor specification-driven sales across Brazilian infrastructure tenders. Sika AG competes through waterproofing system integration, while MAPEI S.p.A. specializes in tile-setting and grouting solutions for Mexico's residential vertical construction.
Construction chemicals encompass formulated additives, binders, and protective materials designed to enhance concrete workability, durability, and structural integrity through controlled chemical reactions with cementitious substrates. These formulations typically incorporate polymers, surfactants, and corrosion inhibitors to achieve specified compressive strength, permeability resistance, and service-life extension under tropical and seismic loading conditions. Admixtures dominate volume flows due to their embedded position in ready-mix concrete supply chains, while waterproofing coatings capture disproportionate margin pools from infrastructure rehabilitation budgets. Sealants and adhesives occupy narrower but defensible positions in building envelope and finishing applications across Latin American commercial projects.
Brazil's ABNT standards, Mexico's NMX building codes, and Colombia's NSR-10 seismic regulations collectively mandate minimum durability indices and environmental compliance for structural materials. These frameworks elevate demand for certified admixtures and low-VOC coatings while restricting market access for uncertified imports. Stakeholders must monitor evolving green procurement criteria and local content requirements as public infrastructure spending scales across the region.
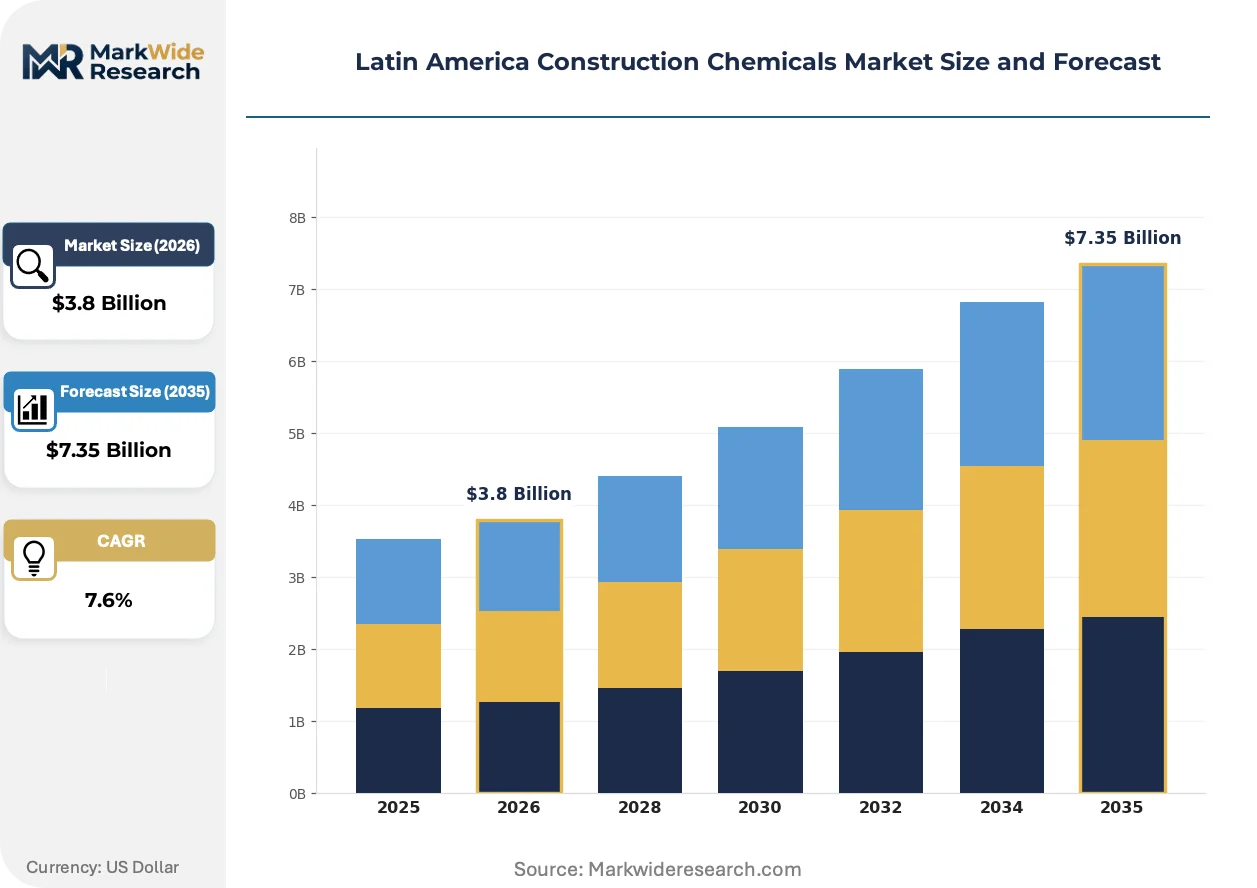
Market Dynamics
Seismic code upgrades across Brazil, Mexico, and Colombia are forcing specification changes for structural admixtures, compressing approval timelines and elevating technical service requirements for formulation suppliers competing in public infrastructure tenders.
Growth Catalysts
- NSR-10 Seismic Mandates:Colombia's updated seismic regulations require enhanced durability indices for concrete structures, driving specification of high-range water reducers and corrosion inhibitors in Bogotá's high-rise construction pipeline.
- Green Building Certification Surge:LEED and GBCI standards are penetrating São Paulo and Mexico City commercial projects, creating demand for low-VOC waterproofing membranes and recycled-content adhesives in certified building envelopes.
- Mega-Project Procurement Scale:Brazil's southeastern urban corridor is consolidating ready-mix concrete demand through bundled admixture supply contracts tied to federal infrastructure concessions.
Market Restraints
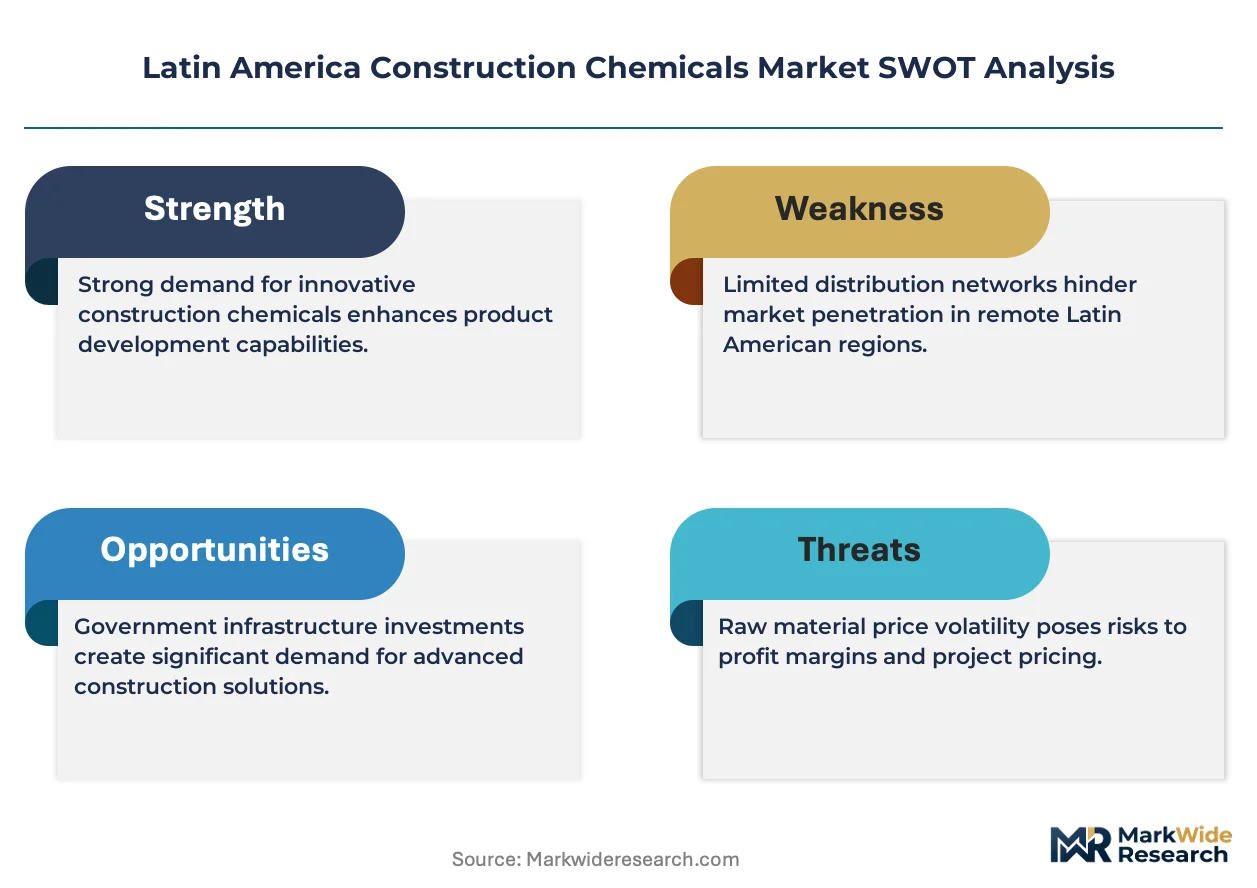
- Petrochemical Feedstock Volatility:Acrylic and epoxy resin prices fluctuate with naphtha cracking margins, compressing formulation margins for waterproofing coating producers serving price-sensitive residential contractors.
- Import Dependency Concentration:Specialty polymers and performance additives concentrate in Asian supply chains, exposing Latin American blenders to ocean freight rate spikes and extended order-to-delivery cycles.
- Substitution Pressure from Alternative Binders:Geopolymer and alkali-activated cement systems are displacing conventional Portland-based admixture applications in select Brazilian precast segments.
Strategic Opportunities
- Peru and Chile Infrastructure Gap:Underpenetrated mining and tunneling sectors in the Andean corridor present white space for shotcrete accelerators and rock-bolt grouting systems absent dominant local suppliers.
- Retrofit Rehabilitation Demand:Carbon fiber-reinforced polymer anchoring adhesives and structural injection resins are capturing margin pools from Mexico City's aging building stock remediation mandates.
- Digital Specification Platforms:BIM-integrated material selection tools are emerging as a channel innovation, enabling admixture suppliers to embed performance data directly into contractor procurement workflows.
Industry Challenges
- Application Engineering Talent Scarcity:Field technical service capacity lags behind specification complexity, particularly for self-consolidating concrete and temperature-controlled curing systems in tropical climates.
- ABNT Certification Timeline Compression:Brazil's national standards body is extending test protocol durations for novel admixture chemistries, delaying market entry for reformulated products targeting updated durability requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Construction Chemicals Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Admixtures, Sealants, Adhesives, Coatings End User: Residential Construction, Commercial Projects, Infrastructure Development, Industrial Facilities Application: Repair, Renovation, New Construction, Waterproofing Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | BASF SE, RPM International Inc, Saint-Gobain, Dow Inc, MAPEI S.p.A, Sika AG, Holcim, Arkema, Henkel AG & Co KGaA, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Construction Chemicals Market Trends and Innovations
Digitalization of concrete quality control and specification workflows is compressing traditional supplier-buyer relationships. Real-time sensing, predictive analytics, and automated dosing systems are converging to reshape how performance guarantees are structured and enforced across Latin American infrastructure markets.
Sensor-embedded concrete maturity monitoring is automating quality assurance protocols on Brazilian megaproject sites. Contractors deploying wireless temperature and strength sensors are reducing core-testing frequency by half. The technology is compressing payment milestone verification cycles and shifting risk allocation from owners to admixture suppliers offering performance warranties.
Brazil's ABNT NBR 15575 residential performance standard and Mexico's evolving NMX energy efficiency codes are mandating lower thermal transmittance and vapor permeability in building envelopes. Waterproofing membrane specifications now require documented service-life predictions under tropical UV and humidity cycling. Formulators are responding with modified bitumen and polyurethane hybrid systems carrying extended certification renewals.
Consolidation among ready-mix concrete producers is compressing supplier negotiation leverage across São Paulo and Mexico City metropolitan markets. Large-scale contractors are unbundling technical service from material supply, awarding separate contracts for application engineering and bulk chemical procurement. This bifurcation is most visible in Brazil's federal highway concession programs, where performance-based specifications dominate tender documentation.
Latin America Construction Chemicals Market Segmentation
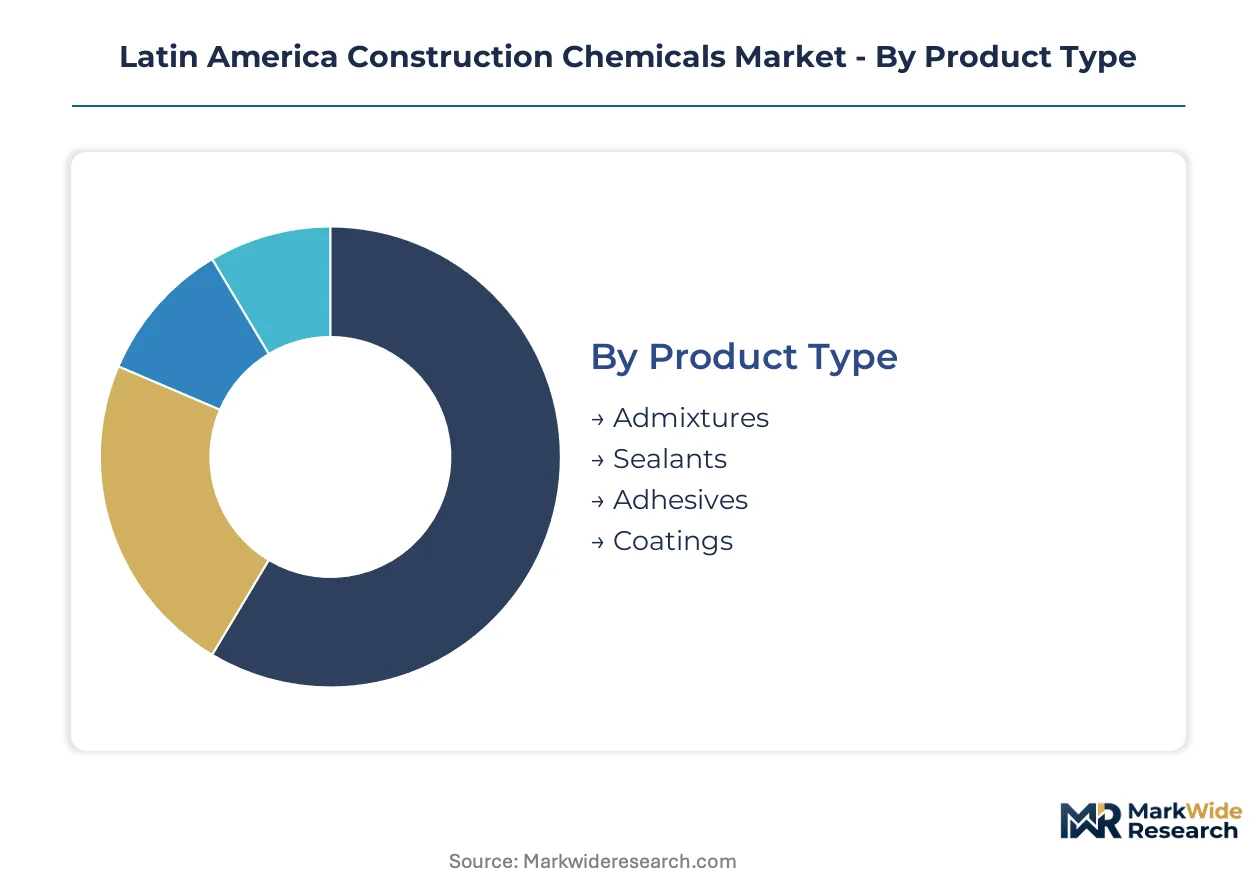
Segmentation reveals how procurement patterns diverge across Latin America's construction chemicals landscape. Specification complexity, project scale, and channel access create distinct buyer profiles that suppliers must address through differentiated service models and technical support architectures.
Product Type:
Buyers in this category separate by performance guarantee requirements versus commodity procurement economics.
- Admixtures:Polymeric and surfactant-based formulations modify concrete rheology, accelerate or retard setting, and enhance freeze-thaw resistance through controlled interaction with cement hydrates. Demand concentrates in Brazil's southeastern urban corridor, where federal highway concessions bundle superplasticizer supply into ready-mix concrete contracts. ABNT certification timelines compress supplier margins while elevating technical service intensity.
- Coatings:Bituminous, polyurethane, and acrylic systems form impermeable barriers against moisture ingress and carbonation. Waterproofing specifications dominate infrastructure rehabilitation budgets across Mexico City's aging building stock, where NSR-10 seismic retrofits mandate extended service-life predictions under tropical UV cycling.
- Sealants:Elastomeric joint fillers accommodate structural movement while maintaining envelope integrity. Building envelope applications in São Paulo commercial towers specify low-VOC formulations meeting LEED certification criteria.
- Adhesives:Cementitious, epoxy, and reactive resin systems bond tile, stone, and structural elements. Residential vertical construction in Mexico drives volume through MAPEI-specialized distribution networks.
Admixtures lead volumes today; coatings are gaining share fastest through infrastructure rehabilitation mandates.
End User:
Project financing structures and specification authority determine procurement behavior across these buyer types.
- Infrastructure Development:Federal concession programs and public-private partnerships drive bulk procurement of certified admixtures and waterproofing systems. Brazil's highway and rail megaprojects consolidate demand through performance-based specifications that shift quality risk to chemical suppliers.
- Residential Construction:Price-sensitive contractors in Colombia's Bogotá high-rise pipeline favor commodity-grade tile adhesives and basic waterproofing membranes. Green building certification penetration remains limited outside São Paulo and Mexico City premium segments.
- Commercial Projects:LEED and GBCI standards reshape specification criteria for low-VOC coatings and recycled-content sealants. Corporate procurement departments unbundle technical service from material supply, awarding separate engineering and bulk chemical contracts.
- Industrial Facilities:Mining and petrochemical operations in Peru and Chile's Andean corridor demand specialized shotcrete accelerators and chemical-resistant grouting systems with limited local supplier presence.
Infrastructure Development captures the dominant revenue pool; Industrial Facilities present the steepest expansion trajectory as mining investment accelerates.
Application:
Life-cycle stage determines whether buyers prioritize installed cost or total cost of ownership in specification decisions.
- New Construction:Greenfield projects embed admixtures directly into ready-mix concrete supply chains. Brazil's ABNT NBR 15575 residential performance standard mandates documented durability indices from pour through service life.
- Waterproofing:Below-grade and envelope systems command premium pricing in tropical climates with intense UV and humidity cycling. Modified bitumen and polyurethane hybrid formulations carry extended certification renewals under evolving NMX energy efficiency codes.
- Repair:Structural injection resins and carbon fiber anchoring adhesives address concrete spalling and rebar corrosion. Mexico City's building remediation mandates create concentrated demand for high-strength epoxy systems.
- Renovation:Building envelope upgrades and facade restoration drive sealant and coating replacement cycles. Commercial property owners in São Paulo specify rapid-cure systems to minimize tenant disruption.
New Construction dominates current volumes; Repair applications are climbing the fastest as urban building stocks age across the region.
Distribution Channel:
Channel selection reflects buyer scale, technical complexity, and geographic proximity to formulation capacity.
- Distributors:Regional blending and warehousing networks serve mid-sized contractors with standardized admixtures and commodity waterproofing products. Inventory positioning in Campinas and Puebla hubs reduces order-to-delivery cycles for time-sensitive concrete pours.
- Direct Sales:BASF and Sika deploy technical service teams to anchor specification-driven procurement in federal infrastructure tenders. Performance warranties and application engineering support justify premium pricing for complex formulations.
- Retail:Big-box construction supply stores capture residential DIY and small contractor demand for basic tile adhesives and brush-applied waterproofing. Price transparency compresses margins on standardized SKUs.
- Online Sales:Digital procurement platforms emerge for standardized products with documented technical data sheets. BIM-integrated material selection tools embed performance specifications directly into contractor workflows.
Distributors lead channel volumes today; Direct Sales is expanding most quickly as performance-based specifications proliferate in public tenders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands construction chemicals volume through federal infrastructure concessions, while Mexico concentrates specification-driven demand in commercial vertical construction. Colombia, Chile, Argentina, and Peru round out regional demand clusters with distinct regulatory and project-mix profiles.
Brazil
Federal highway and rail megaprojects drive bulk admixture procurement through performance-based tender specifications. ABNT certification mandates compress supplier approval timelines while elevating technical service intensity. São Paulo's southeastern urban corridor consolidates ready-mix concrete demand through bundled supply contracts tied to concession programs.
Mexico
LEED and GBCI penetration in commercial towers reshapes specification criteria for low-VOC coatings and sealants. NMX building codes mandate documented thermal performance and vapor permeability in building envelopes. Mexico City metropolitan construction anchors waterproofing membrane demand for below-grade and facade applications.
Colombia
NSR-10 seismic regulations mandate enhanced durability indices for high-rise concrete structures in Bogotá's vertical construction pipeline. High-range water reducers and corrosion inhibitors capture specification share in public infrastructure tenders. Antioquia's mining and tunneling sectors present emerging demand for shotcrete accelerators.
Chile
Copper mining investment and tunneling infrastructure drive specialized grouting system demand in the Andean corridor. Limited local formulation capacity exposes contractors to extended import lead times for performance additives. Santiago's commercial rehabilitation market creates pockets of demand for structural injection resins.
Peru
Mining sector expansion in the central highlands generates procurement scale for rock-bolt grouting and chemical-resistant formulations. Underpenetrated distributor networks constrain product availability outside Lima-Callao. Transport infrastructure gaps between coastal hubs and mountain sites complicate just-in-time concrete delivery.
Latin America Construction Chemicals Market Competitive Landscape
Top-tier vendors anchor specification-driven infrastructure tenders, while mid-scale blenders serve price-sensitive residential contractors through distributor networks. Market structure tilts toward technical service intensity over commodity scale. Three archetypes dominate: integrated multinationals with regional admixture labs, waterproofing system specialists, and tile-setting material experts. Competitive moves concentrate on M&A for formulation capacity and strategic partnerships for local certification acceleration.
Among European-headquartered multinationals, BASF SE, Sika AG, and MAPEI S.p.A. occupy positions exemplifying distinct specialization vectors. BASF SE represents the integrated admixture laboratory model anchoring Brazilian federal tender participation. Sika AG sits within the waterproofing system integration archetype competing on envelope performance guarantees. MAPEI S.p.A. exemplifies tile-setting and grouting specialization serving Mexico's residential vertical construction channels.
| Leading Market Players |
|---|
| BASF SE |
| RPM International Inc |
| Saint-Gobain |
| Dow Inc |
| MAPEI S.p.A |
| Sika AG |
| Holcim |
| Arkema |
| Henkel AG & Co KGaA |
| Others |
Pricing and Supply Chain Analysis
LEED and GBCI certification mandates in São Paulo and Mexico City commercial towers gate qualified supply access and anchor premium-tier pricing power for low-VOC waterproofing membranes and certified admixtures. Contractors without green procurement credentials face exclusion from federal infrastructure tenders, compressing their supplier options while elevating price floors for certified formulations.
Pricing Analysis
Capacity additions in Brazil's southeastern chemical corridor are reshaping price floors for commodity-grade concrete admixtures. Three-tier pricing structure across certified-premium, ABNT-compliant standard, and uncertified economy levels differentiates supplier positioning. Price differentiation rests on technical service bundling and certification grade rather than raw material cost alone. Cost compression in economy-tier tile adhesives is intensifying because residential contractors in Bogotá prioritize unit economics over performance guarantees.
Supply Chain Analysis
Dual-sourcing requirements from Brazil's federal highway concession programs mandate multi-supplier qualification for superplasticizer and corrosion inhibitor procurement. Formulation capacity concentrates in Brazil, Mexico, and the United States, with specialty polymer feedstock anchored in Asian petrochemical hubs. Raw material dependencies include naphtha-derived acrylic resins, epoxy hardeners, and polyether surfactants. Single-source vulnerability from ocean freight concentration exposes blenders to extended order-to-delivery cycles. Distribution runs through regional blending hubs in Campinas and Puebla serving metropolitan ready-mix concrete networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as seismic code upgrades and green building mandates shift procurement authority toward specification-driven buyers willing to pay premium pricing for certified durability.
For Market Incumbents: Anticipate displacement pressure from geopolymer binder systems in Brazilian precast segments by deepening technical service intensity for self-consolidating concrete applications. Backward integration into captive naphtha cracking capacity mitigates margin compression from petrochemical feedstock volatility. Prioritize ABNT certification acceleration for reformulated corrosion inhibitors targeting updated NSR-10 durability indices. For New Entrants and Emerging Players: The mid-tier price gap between Sika-grade waterproofing systems and commodity brush-applied membranes creates entry space for hybrid polyurethane-bitumen formulations. Peru's mining corridor and Chile's tunneling infrastructure present the most penetrable white-space targets given limited local shotcrete accelerator supply. Anchor initial positioning through distributor partnerships in Lima-Callao before scaling direct sales technical teams. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale regional blenders because ABNT certification timelines and technical service requirements create barriers that favor consolidated formulation capacity over fragmented commodity supply. Five-to-ten year viability hinges on exposure to federal infrastructure concession programs rather than residential construction cyclicality. Monitor green procurement criteria adoption rates across Colombian and Peruvian public tenders as the inflection signal for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstock | Captive naphtha cracking capacity insulates Brazilian blenders from acrylic resin price volatility. |
| ABNT Certification Acceleration Program | Compressed approval timelines for novel admixture chemistries unlock federal tender participation. |
| Technical Service Team Expansion | Field engineering density in São Paulo secures specification-driven procurement from ready-mix consolidators. |
| Shotcrete Accelerator Capacity Buildout | Local production in Peru's Andean corridor addresses mining sector procurement scale with reduced import lead times. |
| BIM-Integrated Material Selection Platform | Performance data embedded in contractor workflows shifts specification authority toward suppliers with digital integration. |
Research Methodology
Coverage spans Brazil, Mexico, Colombia, Chile, and Peru, with primary inputs from each market's construction chemicals value chain. The research combines structured interviews with ready-mix concrete procurement directors, admixture technical service managers, federal infrastructure concession operators, and waterproofing specification engineers with secondary validation. Secondary sources include ABNT certification registries, Mexican customs trade data, Colombian NSR-10 compliance filings, and SEC 10-K disclosures from multinational chemical suppliers. Bottom-up volume modeling and top-down market sizing triangulate demand estimates across product categories.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, end-use sector, application life-cycle stage, and distribution channel, with additional granularity on certification tier and technical service intensity. CAGRs derive from historical demand elasticity analysis and forward-projected infrastructure investment pipelines. Industry-specific forecast inputs incorporate federal concession award schedules and green building certification penetration trajectories.
Caveats apply where petrochemical feedstock cost spikes, ABNT protocol extensions, or seismic code revision delays could materially shift the outlook. Forecasts reflect assumptions on infrastructure spending continuity and certification body operational capacity. Deviation in federal concession procurement timelines or ocean freight rate volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Periodic Acid Market
Chemicals
(S)-(+)-2-Amino-1-Propanol Market
Chemicals
Heptaldehyde Market
Chemicals
Calcium Hydroxide Market
Chemicals
Asia-Pacific Methyl Acrylate Market
Chemicals
Methyl Ethyl Ketone Peroxide (MEKP) Market
Chemicals
Inorganic Chemicals Market
Chemicals
Di Nitro Toluene Market
Chemicals
3-Iodoaniline Market
Chemicals
China Amines Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
Thiourea Market
Chemicals
Global Zinc Pyrithione Market
Chemicals
Spirodiclofen Market
Chemicals
Ethanolamine Market
Chemicals
Global P-Phenylenediamine Market