
 Beryllium Copper Billet Market | 2026-2036
Beryllium Copper Billet Market Size, Share, and Industry Trends Forecast 2026-2036
Beryllium Copper Billet Market Insights
Aerospace component demand is realigning beryllium copper billet offtake patterns as commercial aviation output recovers and defense platforms modernize. Materion leverages captive mining and refining assets to secure upstream control over beryllium feedstock. NGK Metals anchors its position through continuous casting expertise serving Japanese electronics and automotive connector markets. IBC Advanced Alloys differentiates via specialized alloy formulations targeting North American defense and nuclear applications.
Beryllium copper billet denotes a cast semifinished product containing copper alloyed with beryllium, typically spanning compositions from alloy 25 through alloy 165, valued for thermal conductivity reaching W/m·K ranges alongside elastic modulus exceeding steel counterparts. These billets undergo hot working into rod, wire, plate, or strip serving electrical connectors, precision springs, and non-sparking tools. Rod billets command the dominant volume position owing to downstream drawability into fine wire for electronic interconnects. High conductivity grades capture widening share as electric vehicle charging infrastructure and renewable energy switchgear expand contact material specifications. Spring contacts represent the fastest-growing application segment, driven by miniaturization trends in consumer electronics and medical device connectors.
OSHA enforces permissible exposure limits for beryllium in US manufacturing environments, compelling fabricators to invest in containment systems and worker protection protocols that elevate processing costs. REACH and RoHS frameworks in Europe restrict hazardous substance content in electrical equipment, shaping alloy certification requirements for billet exporters seeking EU market access. Stakeholders must monitor evolving dual-use export controls and defense procurement specifications that increasingly mandate domestic or allied-country smelting provenance.
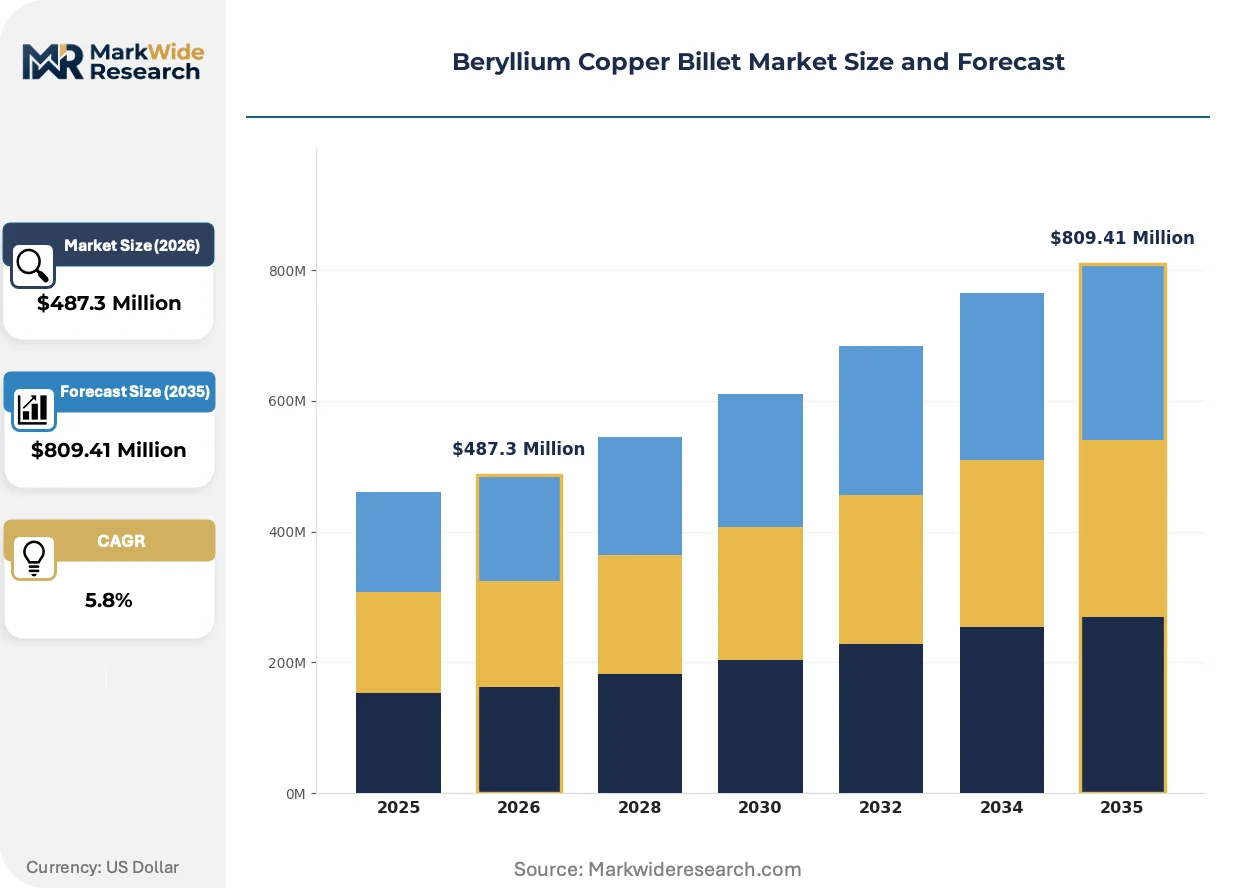
Market Dynamics
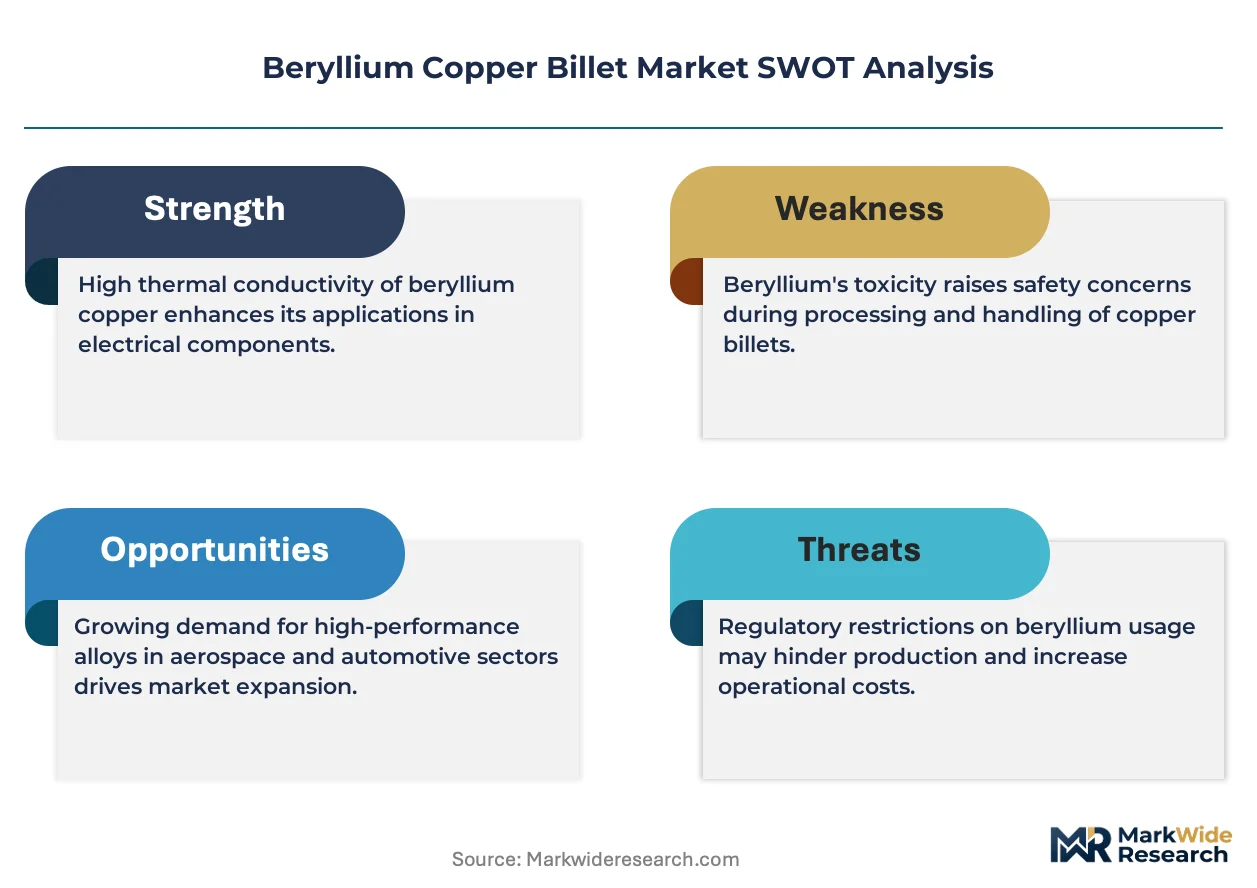
OSHA's tightening permissible exposure limits for beryllium in US manufacturing environments are compelling fabricators to invest in containment systems and worker protection protocols that elevate processing costs across the value chain. This regulatory pressure is reshaping competitive positioning by favoring producers with captive refining assets and advanced powder metallurgy capabilities.
Growth Catalysts
- Commercial aviation recovery:Landing gear and actuator housing procurement from Boeing and Airbus tier-1 suppliers is accelerating billet offtake for high-strength alloy grades.
- REACH compliance migration:European electrical equipment manufacturers are certifying beryllium copper alloys for EU market access, creating specification pull for RoHS-compliant billet exports.
- Miniaturization in medical devices:Spring contact demand for implantable electronics and diagnostic instruments is expanding precision billet requirements.
Market Restraints
- Beryllium feedstock concentration:Utah-based mining operations and Kazakhstani ore processing create geopolitical exposure for non-vertically integrated producers.
- Aluminum bronze substitution:Non-sparking tool manufacturers in oil and gas applications are qualifying lower-cost copper-aluminum alloys for less critical safety applications.
- OSHA compliance costs:Ventilation systems, personal protective equipment mandates, and medical surveillance programs add USD 3-8 per pound to downstream processing economics.
Strategic Opportunities
- Electric vehicle charging infrastructure:High-conductivity alloy 165 billets for contact pins in DC fast charging connectors represent an underpenetrated specification category.
- Defense procurement localization:US Defense Federal Acquisition Regulation Supplement mandates for domestic smelting provenance create captive demand for North American billet producers.
- Renewable energy switchgear:Wind turbine power converters and solar inverter contact assemblies are specifying beryllium copper for arc resistance and thermal cycling durability.
Industry Challenges
- Alloy metallurgist scarcity:Specialized expertise in beryllium copper phase diagram control and hot working parameter optimization is concentrated among retiring technical workforces in Pennsylvania and Ohio manufacturing clusters.
- Dual-use export licensing:Nuclear and aerospace applications trigger International Traffic in Arms Regulations and Export Administration Regulations reviews that extend order-to-delivery cycles by 90-180 days.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beryllium Copper Billet Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rod Billets, Slab Billets, Wire Billets, Plate Billets Grade: Standard Grade, High Conductivity, High Strength, Corrosion Resistant Application: Electrical Connectors, Aerospace Components, Precision Instruments, Spring Contacts End User: Electronics Manufacturers, Aerospace Fabricators, Instrument Makers, Electrical Equipment Producers |
| Companies Covered | Materion, NGK Metals, Kazatomprom, Aviva Metals, IBC Advanced Alloys, Belmont Metals, AMPCO METAL, Wieland-Werke, Mitsubishi Shindoh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beryllium Copper Billet Market Trends and Innovations
Continuous casting technology advancement and powder metallurgy process refinement are compressing lead times for complex alloy formulations while enabling tighter dimensional tolerances for precision electronic applications.
Near-net-shape powder metallurgy billet production is modularizing traditional supply chain configurations by enabling direct-to-component manufacturing pathways. Japanese electronics assemblers are adopting these semifinished forms for connector pin applications, bypassing conventional hot extrusion and drawing stages. This compression is reducing material yield losses and shortening qualification cycles for medical device OEMs.
REACH authorization requirements for beryllium compounds are tightening substance volume tracking and downstream communication obligations across European manufacturing value chains. ECHA's candidate list inclusion processes are forcing alloy importers to establish comprehensive supply chain due diligence systems. German automotive connector suppliers are responding by demanding full material disclosure documentation from billet sources.
Specification-driven vendor consolidation is concentrating procurement authority among tier-1 aerospace and medical device OEMs with dedicated metallurgical engineering teams. Long-term alloy development agreements are displacing spot market transactions for critical safety applications. This pattern is most visible in Southern California and Connecticut defense manufacturing corridors where sole-source qualification locks extend 10-15 years.
Beryllium Copper Billet Market Segmentation
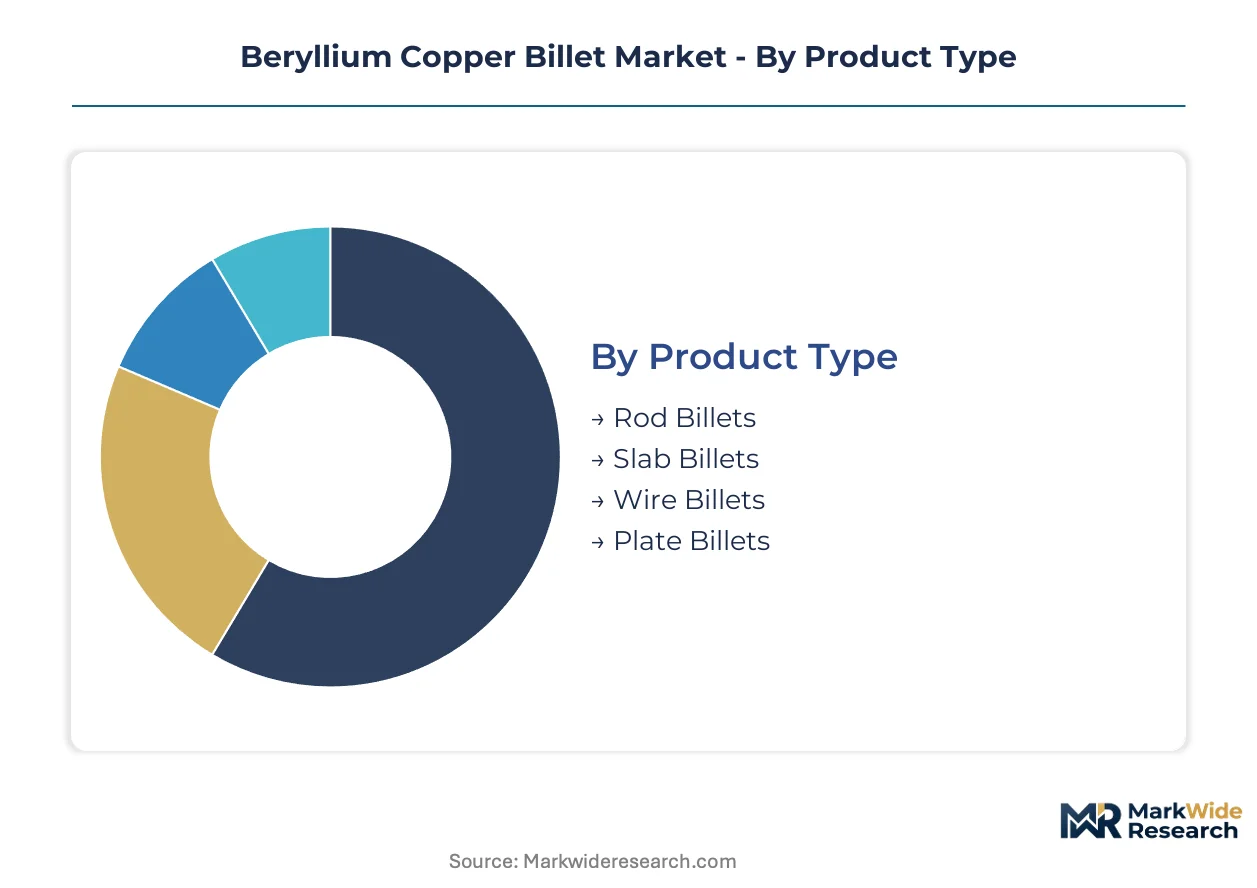
Beryllium copper billet specifications diverge sharply across downstream applications. Alloy composition and dimensional form determine thermal conductivity, elastic modulus, and drawability for precision manufacturing.
Product Type:
Rod billets dominate volume throughput while plate and slab forms capture premium pricing for specialized aerospace fabrications.
- Rod Billets:Cylindrical cast forms ranging from 50mm to 300mm diameter serve as feedstock for hot extrusion and cold drawing into wire. Japanese electronics assemblers in Osaka and Nagoya prefectures are expanding procurement for fine-gauge connector pin applications.
- Slab Billets:Rectangular cross-section castings enable rolling into thin strip and foil for flexible circuit applications. German automotive connector suppliers are qualifying these forms for high-volume EV charging infrastructure deployments.
- Wire Billets:Smaller-diameter continuous cast rod bypasses initial breakdown steps for direct drawing operations. South Korean precision spring manufacturers favor these for medical device contact production.
- Plate Billets:Heavy-section castings support forging of aerospace actuator housings and landing gear components. Boeing tier-1 suppliers in Wichita and St. Louis specify these for defense platform modernization programs.
Today's leader: Rod Billets. Tomorrow's challenger: Slab Billets.
Grade:
Conductivity-performance tradeoffs segment procurement patterns across electrical versus structural applications.
- Standard Grade:Alloy 25 compositions balance strength and conductivity for general-purpose connectors. US electrical equipment producers specify these for industrial switchgear contact assemblies.
- High Conductivity:Alloy 165 and modified formulations achieve thermal conductivity exceeding 200 W/m·K. DC fast charging infrastructure specifications in California and Texas are pulling these grades for high-current contact pins.
- High Strength:Peak-aged conditions deliver yield strengths above 1200 MPa for structural aerospace applications. Airbus landing gear suppliers in Toulouse and Hamburg require these for next-generation narrowbody programs.
- Corrosion Resistant:Modified compositions with cobalt or nickel additions enhance marine and chemical processing durability. Norwegian offshore tool manufacturers specify these for subsea non-sparing applications.
Standard Grade anchors current volume. High Conductivity grades are climbing the fastest as electrification infrastructure scales.
Application:
Miniaturization intensity and safety criticality determine alloy specification stringency across end-use categories.
- Spring Contacts:Miniaturized precision forms for implantable medical devices and consumer electronics interconnects. Swiss medical device OEMs in Basel and Zurich are expanding specifications for diagnostic instrument clusters.
- Electrical Connectors:Power transmission contacts for automotive, industrial, and renewable energy switchgear. Chinese EV charging station builders are qualifying beryllium copper alternatives to silver-plated contacts.
- Aerospace Components:Landing gear bushings, actuator housings, and flight control linkages requiring fatigue resistance. UK defense contractors in Bristol and Preston mandate these for combat aircraft modernization.
- Precision Instruments:Non-magnetic components for MRI equipment and scientific measurement devices. Japanese instrument makers in Tokyo and Kyoto prefectures specify these for semiconductor metrology tools.
Spring Contacts command the steepest expansion trajectory. Aerospace Components defend the highest specification barriers.
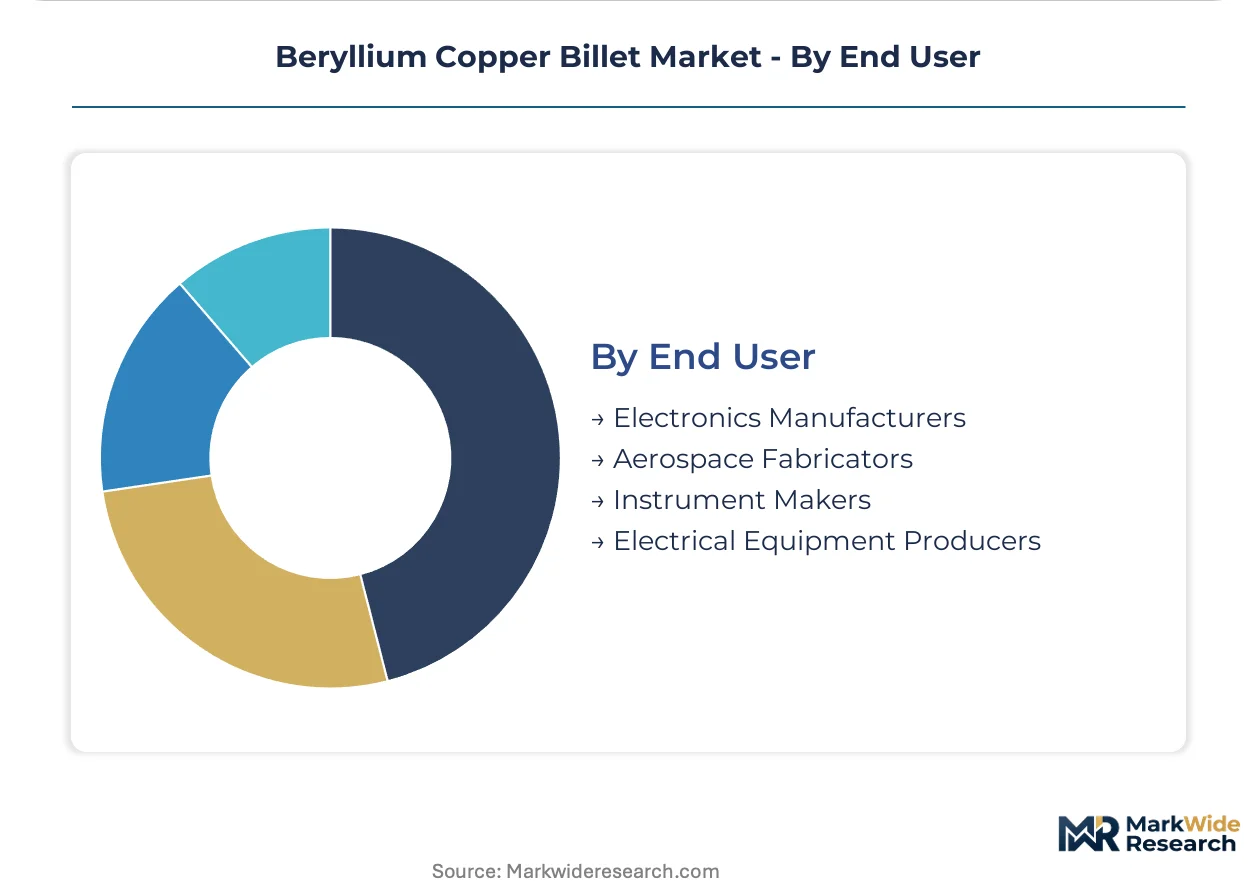
End User:
Procurement sophistication varies from commodity spot purchasing to decade-long alloy development partnerships.
- Electronics Manufacturers:High-volume consumers of rod and wire billet for connector and spring production. Taiwanese ODMs are consolidating supplier bases to secure REACH-compliant material flows.
- Aerospace Fabricators:Safety-critical specifications with extensive qualification protocols and sole-source arrangements. French and Italian tier-1 suppliers enforce full material provenance documentation.
- Instrument Makers:Low-volume, high-mix procurement emphasizing dimensional precision and lot traceability. German microscopy equipment builders in Jena and Oberkochen specify vacuum-melted billet grades.
- Electrical Equipment Producers:Industrial switchgear and power distribution component manufacturers. Brazilian and Mexican producers are expanding specifications for grid modernization programs.
Electronics Manufacturers drive aggregate tonnage. Aerospace Fabricators set the technical specification frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping beryllium copper billet production geography as OSHA compliance costs in the United States push fabricators toward jurisdictions with less stringent workplace exposure protocols. Kazakhstan and Uzbekistan host concentrated beryllium ore processing that feeds Asian and European alloy producers. Japanese and South Korean electronics manufacturers are consolidating procurement around REACH-compliant supply chains to secure EU market access.
United States
Defense procurement localization under DFARS domestic smelting mandates is concentrating demand among Pennsylvania and Ohio manufacturing clusters. OSHA's permissible exposure limits compel fabricators in these regions to invest in containment infrastructure that elevates processing economics. Wichita and St. Louis aerospace suppliers specify heavy-section plate billets for Boeing landing gear programs.
Japan
Precision instrument and electronics connector demand in Osaka and Nagoya prefectures is expanding rod billet procurement for fine-gauge wire applications. METI industrial standards govern alloy composition certifications for medical device exports. Continuous casting expertise in the Chubu region serves domestic automotive connector markets with reduced lead times.
Germany
Automotive connector suppliers in Baden-Württemberg are qualifying slab billets for high-volume EV charging infrastructure deployments. ECHA REACH authorization requirements enforce comprehensive supply chain due diligence for beryllium compound imports. Jena and Oberkochen microscopy equipment builders specify vacuum-melted grades for semiconductor metrology applications.
China
EV charging station builders in Guangdong and Jiangsu provinces are qualifying beryllium copper alternatives to silver-plated electrical contacts. GB standards and MIIT industrial policies shape alloy certification requirements for domestic electrical equipment producers. Yangtze River Delta fabricators are expanding capacity for renewable energy switchgear contact assemblies.
South Korea
Precision spring manufacturers in the Busan-Ulsan corridor favor wire billet forms for medical device contact production. MFDS medical device regulations and KATS standards govern material traceability for implantable electronics applications. Seoul Capital Area electronics assemblers are consolidating supplier bases to secure conflict-free beryllium feedstock documentation.
Beryllium Copper Billet Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated miners and captive refiners commanding upstream positions while regional fabricators compete on alloy formulation specialization. The vendor base concentrates around three strategic archetypes: mining-integrated producers securing feedstock control, continuous casting specialists serving precision electronics, and powder metallurgy innovators compressing supply chain stages. Competitive moves center on backward integration into beryllium refining and geographic expansion to capture defense procurement localization mandates.
Within the mining-integrated tier, Materion exemplifies upstream control through captive Utah-based refining assets that supply North American defense and aerospace specifications. NGK Metals occupies a position among continuous casting specialists serving Japanese electronics and automotive connector markets with tight dimensional tolerance capabilities. IBC Advanced Alloys represents the specialized alloy formulation archetype, anchoring North American defense and nuclear application requirements through customized metallurgical development programs.
| Leading Market Players |
|---|
| Materion |
| NGK Metals |
| Kazatomprom |
| Aviva Metals |
| IBC Advanced Alloys |
| Belmont Metals |
| AMPCO METAL |
| Wieland-Werke |
| Mitsubishi Shindoh |
| Others |
Pricing and Supply Chain Analysis
Captive refining assets in Utah and Kazakhstan anchor supply positions and pricing power for beryllium copper billet producers, concentrating feedstock control among vertically integrated miners while OSHA compliance costs in US fabrication elevate downstream processing economics. This upstream concentration enables alloy-grade premiums for defense-certified material while spot-market volatility in non-integrated channels compresses margins for commodity-grade rod billet.
Pricing Analysis
Distributor margins compress as tier-1 aerospace OEMs consolidate procurement through direct long-term offtake agreements, displacing spot-market intermediation. Three-tier pricing structure across premium, standard, and economy levels separates DFARS-certified defense grades from REACH-compliant commercial alloys and uncertified industrial feedstock. Cost compression in standard-grade rod billet intensifies because Chinese EV charging infrastructure builders are qualifying lower-cost alternatives. Electronics manufacturers in Taiwan and South Korea exhibit highest price sensitivity, while aerospace fabricators in Wichita and Toulouse absorb premiums for sole-source qualified material.
Supply Chain Analysis
Freight costs from Kazakhstani ore processing to Asian alloy producers have elevated regional sourcing advantages for Chubu-region continuous casting specialists. Raw material flows draw from Utah mining operations, Kazakhstani ore concentration, and recycled aerospace scrap. Single-source vulnerability concentrates in beryllium feedstock refining, where two primary facilities supply global alloy production. Distribution runs through direct mill relationships for aerospace tier-1 suppliers and regional distributors serving electronics contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beryllium copper billet functions as a regulatory compounder, with DFARS domestic smelting mandates and REACH authorization requirements driving specification premiums that widen competitive moats for compliant producers.
For Market Incumbents: Extend qualification lock periods with Boeing and Airbus tier-1 suppliers through dedicated alloy development agreements that embed technical teams at customer facilities. Aluminum bronze substitution in oil and gas non-sparking tools demands accelerated R&D investment in cobalt-modified corrosion-resistant grades that defend performance differentiation. Capacity addition in Ohio and Pennsylvania manufacturing clusters reinforces captive supply positions for defense procurement localization mandates. For New Entrants and Emerging Players: Launch via powder metallurgy near-net-shape production pathways that bypass conventional hot extrusion stages, targeting Japanese medical device OEMs in Basel and Zurich with compressed qualification cycles. DC fast charging infrastructure contact pins represent the most penetrable specification category, with alloy 165 high-conductivity grades still underqualified against silver-plated alternatives. Partner with German automotive connector suppliers seeking REACH-compliant material disclosure documentation from non-incumbent sources. For Investors and Strategic Acquirers: Roll-up economics work for specialized alloy formulators because retiring metallurgist expertise in Pennsylvania and Ohio creates acquisition targets with irreplaceable technical know-how. Five-to-ten-year viability hinges on defense procurement localization sustaining premium pricing for domestic smelting provenance. Monitor ECHA candidate list inclusion processes as inflection indicators for supply chain due diligence cost escalation that favors integrated players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beryllium Refining | Captive Utah-based feedstock secures DFARS-compliant supply for defense aerospace specifications. |
| Powder Metallurgy Process Scale-Up | Near-net-shape production compresses lead times for Osaka and Nagoya electronics connector markets. |
| REACH Compliance Certification Investment | Full material disclosure documentation unlocks German automotive EV charging infrastructure procurement. |
| Continuous Casting Capacity Expansion | Tight dimensional tolerance capabilities serve Japanese medical device spring contact miniaturization trends. |
| Long-Term Alloy Development Partnership | Embedded technical teams at Boeing tier-1 suppliers extend sole-source qualification locks. |
Research Methodology
Direct dialogue with alloy metallurgists, aerospace procurement directors, electronics contract manufacturer supply chain leads, and ECHA regulatory consultants grounded qualitative findings in operational reality. Secondary validation drew from OSHA enforcement records, ECHA authorization databases, SEC 10-K filings from listed producers, and US Defense Federal Acquisition Regulation Supplement updates. Bottom-up and top-down triangulation cross-checked alloy-grade shipment data against end-use application demand estimates.
Bottom-up modeling aggregated segment-level volume assumptions across product type, grade, application, and end-user dimensions, while top-down constraints incorporated macroeconomic sensitivity to commercial aviation output cycles. CAGRs were derived from regression analysis of historical alloy consumption patterns against projected electrification infrastructure deployment and defense platform modernization schedules. Forecast inputs included Boeing and Airbus production rate announcements, EV charging station installation targets in California and Texas, and renewable energy switchgear procurement pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden beryllium feedstock supply disruptions or accelerated aluminum bronze substitution in safety-critical applications. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
7075 T6 Aluminum Market
Metals
US Copper Scrap Market
Metals
High Magnetic Induction Grain-Oriented Silicon Steel Market
Metals
Copper Foil Market
Metals
Steel Salvage Drums Market
Metals
Beryllium Market
Metals
Chrome Metal Powder Market
Metals
High Purity Base Metals Market
Metals
Europe Metal Service Centers Market
Metals
Saudi Arabia Aluminum Market
Metals
Titanium Mill Products Market
Metals
High Purity Aluminium Market
Metals
Bismuth Oxide Market
Metals
Silico Manganese Market
Metals
Global Hot Rolled Coil Steel Market
Metals
Flat-Rolled Stainless Steel Market