
 Europe Aluminium Wire Rod Market | 2026-2036
Europe Aluminium Wire Rod Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aluminium Wire Rod Market Foresight
Direct mill-to-cable-plant supply chains is reconfiguring across Europe as energy-intensive smelters seek captive offtake. Norsk Hydro ASA anchors Norwegian production with hydro-powered electrolysis, leveraging renewable credentials to secure long-term utility contracts. TRIMET Aluminium SE sustains German automotive-grade output through integrated casting and rolling, while Lamifil NV specializes in high-purity electrical conductor rod for Benelux grid operators.
Europe aluminium wire rod refers to continuously cast and rolled semi-finished product with diameters typically spanning 9.5 mm to 32 mm, alloyed to EN 573-3 standards for conductivity or mechanical strength. Manufacturers produce it via Properzi or Southwire rolling mill systems to feed downstream drawing into wire for electrical cables, fasteners, and machined components. Round rod dominates volume across cable and conductor applications, while high-strength specification commands premium positioning in automotive harness and aerospace fastener segments. Custom sections occupy niche but defensible margin pools in architectural and specialty industrial channels.
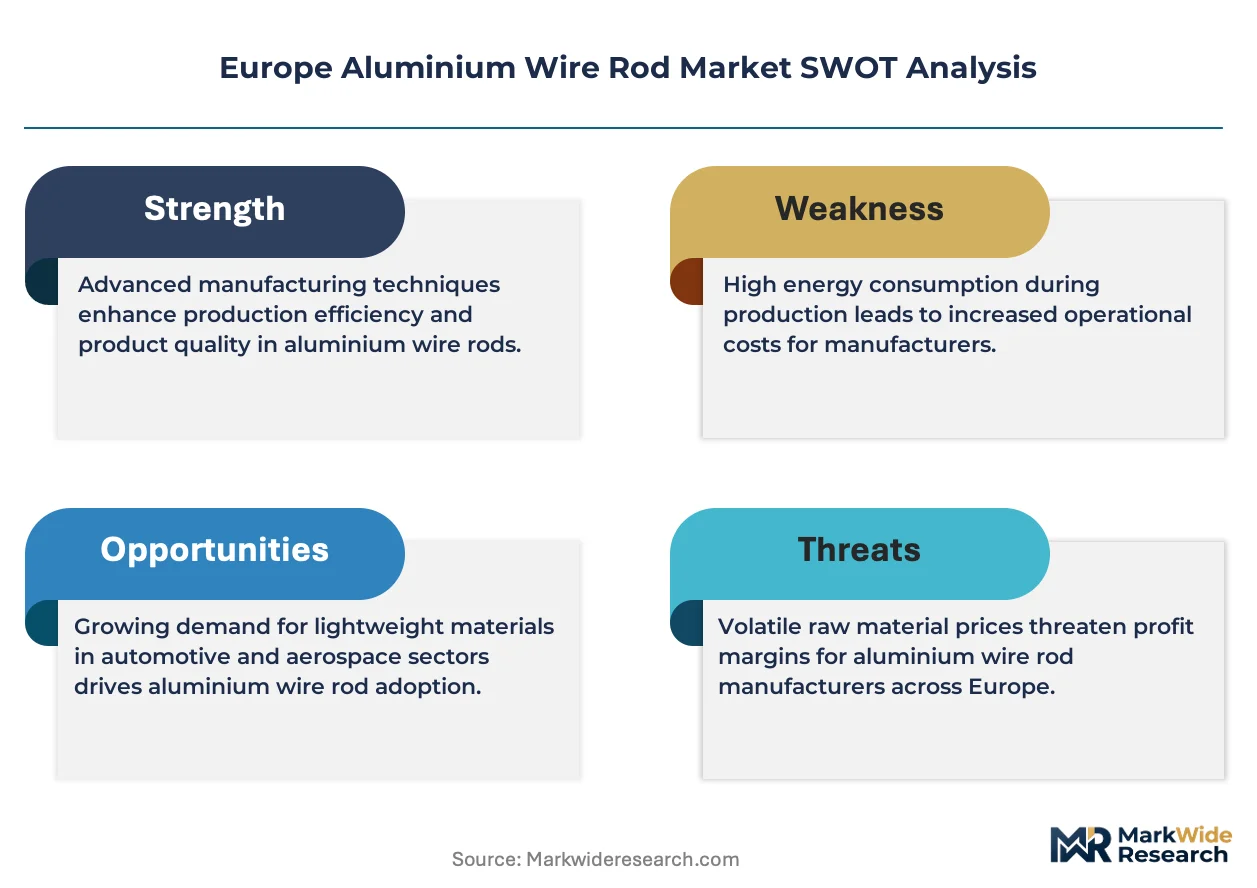
REACH compliance and the EU Green Deal carbon border adjustments shape material sourcing and lifecycle certification requirements for European producers. ECHA substance restrictions and national building codes in France and Germany dictate alloy composition and fire performance standards for construction-grade rod. Stakeholders must monitor electricity price differentials between Nordic hydro regions and continental gas-dependent grids, as power cost arbitrage increasingly determines smelter competitiveness and regional supply allocation.
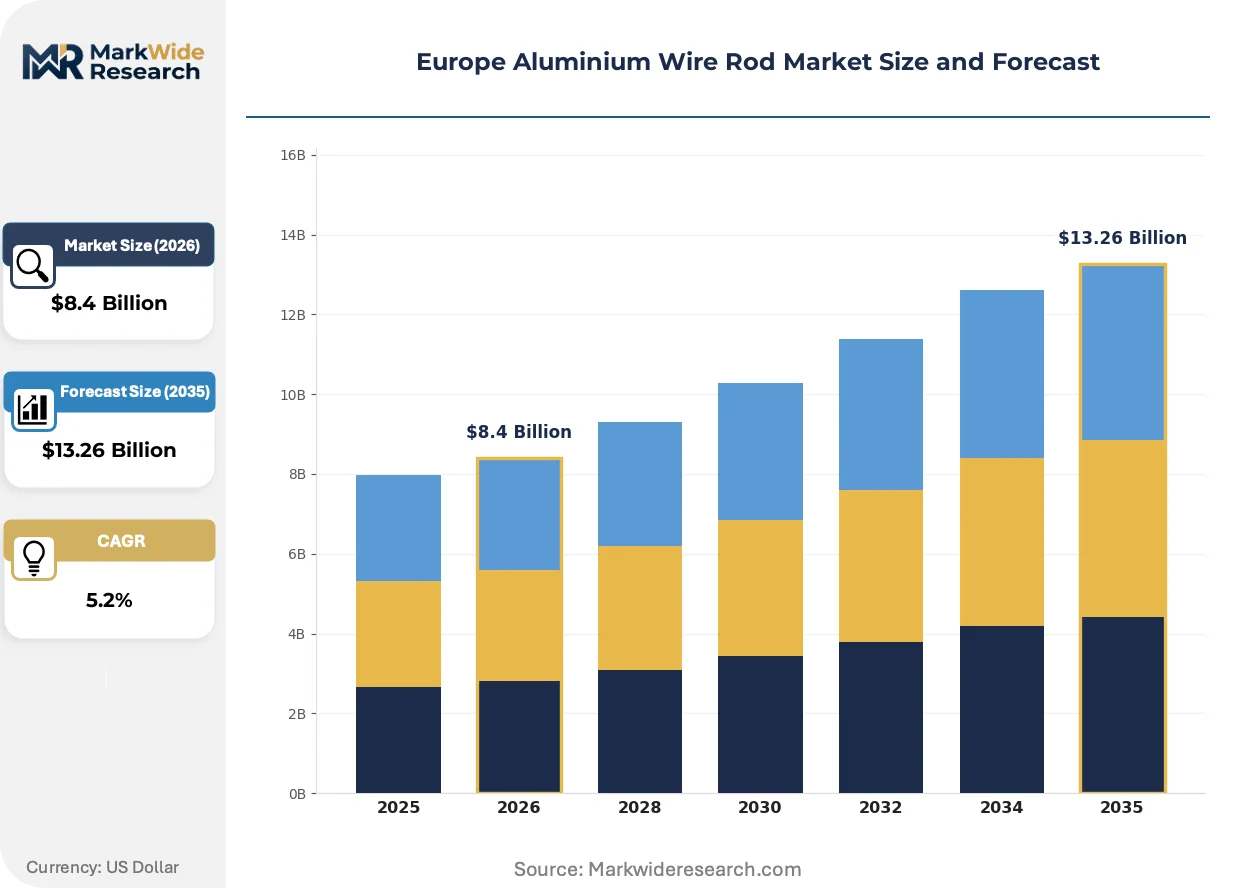
Market Dynamics
The EU Green Deal carbon border adjustments are forcing smelters to reconfigure power sourcing and alloy certification workflows, compressing margins for gas-dependent continental producers while amplifying competitive advantage for Nordic hydro-powered operations.
Growth Catalysts
- Grid Modernization Mandates:Germany's Bundesnetzagentar and France's RTE are accelerating overhead line replacement programs, specifying high-conductivity aluminium alloys for transmission infrastructure.
- REACH-Driven Material Substitution:ECHA substance restrictions on heavy metals in electrical applications are displacing copper-clad steel in favor of certified aluminium conductor rod.
- Automotive Harness Electrification:Battery electric vehicle platforms require lightweight high-strength rod for 800V architecture cabling, concentrating demand in Germany's industrial corridor.
Market Restraints
- Electricity Cost Arbitrage:Continental smelters dependent on German and French gas-indexed power face input cost volatility that Nordic hydro competitors avoid.
- Smelter Concentration Risk:Norwegian and Icelandic primary aluminium capacity dominates European feedstock, creating geographic supply vulnerability for continental wire rod mills.
- Technical Purity Ceilings:Electrical-grade 1350 alloy conductivity specifications limit achievable performance in ultra-high-voltage direct current applications.
Strategic Opportunities
- Benelux Grid Interconnection:Belgium and the Netherlands are expanding cross-border transmission capacity, creating demand for fire-resistant alloy rod in tunnel and urban installations.
- CSRD-Aligned Lifecycle Certification:The EU Corporate Sustainability Reporting Directive rewards producers with verified low-carbon smelting credentials in utility procurement scoring.
- Additive Manufacturing Feedstock:Gas atomization of wire rod offcuts into aluminium powder is converging with aerospace fastener demand for near-net-shape components.
Industry Challenges
- Metallurgical Talent Scarcity:Continuous casting process engineering expertise is concentrating among retiring workforces at legacy Properzi and Southwire installations.
- Dual Certification Timelines:EN 573-3 alloy compliance叠加 ECHA SVHC declarations extends qualification cycles for new product introductions by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aluminium Wire Rod Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Rod, Hexagonal Rod, Square Rod, Custom Sections End User: Electrical, Automotive, Construction, Aerospace Application: Cables, Conductors, Fasteners, Machined Parts Specification: Standard, High Strength, Lightweight, Corrosion Resistant |
| Companies Covered | Hindalco Industries Ltd, TRIMET Aluminium SE, Alcoa Corp, National Aluminium Co. Ltd, Lamifil NV, Norsk Hydro ASA, Vimetco NV, Prysmian Spa, United Company RUSAL, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aluminium Wire Rod Market Shifts & Advancements
Electrification infrastructure buildouts and decarbonization compliance are reshaping how aluminium wire rod is specified, sourced, and certified across European value chains.
Continuous casting technology is migrating from traditional Properzi wheel-and-belt systems to twin-roll thin strip casting for intermediate feedstock. Cable manufacturers in Germany and France are piloting this transition to reduce solidification segregation and improve drawability. The shift is compressing capital intensity for new capacity while raising technical barriers for legacy equipment operators.
The EU Green Deal carbon border adjustment mechanism is restructuring import competition for primary aluminium ingot. Non-EU smelters must now document embedded emissions to avoid tariffs, reshaping sourcing patterns for Spanish and Italian wire rod mills. Russian and Chinese billet suppliers face exclusion risk, redirecting procurement toward Middle Eastern and Canadian primary metal.
Utility procurement departments are consolidating supplier panels around lifecycle carbon intensity metrics. France's Enedis and Germany's TenneT now require ISO 14064-verified emissions declarations for conductor rod contracts, displacing price-only tender evaluation. This behavioral shift concentrates volume with Nordic and hydro-powered producers while marginalizing gas-dependent continental mills.
Europe Aluminium Wire Rod Market Segmentation
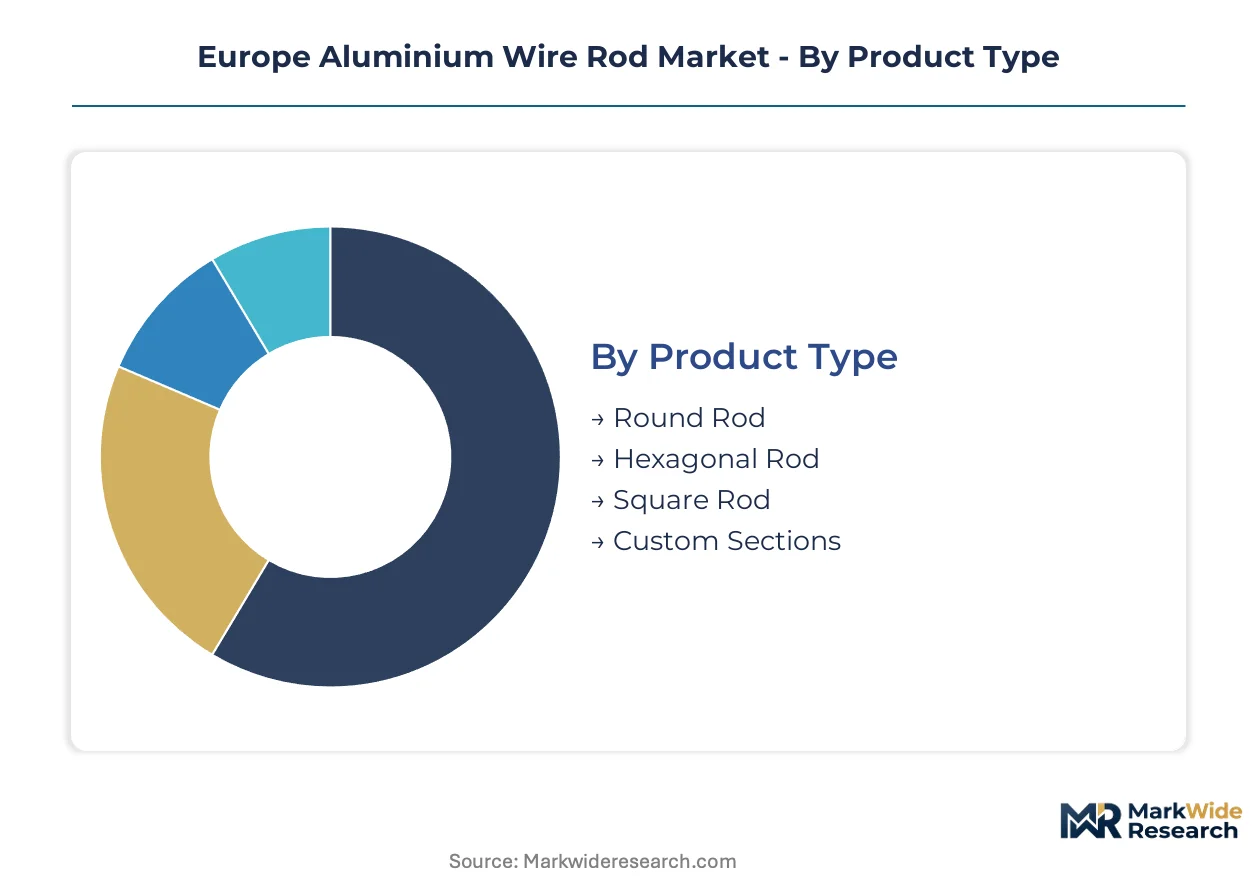
Segmentation in the Europe aluminium wire rod market reveals how alloy specifications and geometric forms align with divergent end-use requirements. Each dimension exposes distinct margin structures and certification barriers that shape supplier positioning across the region's industrial corridors.
Product Type:
Mature geometries dominate volume flows while emerging profiles capture specialty premiums in constrained supply niches.
- Round Rod:Continuously cast circular profiles ranging 9.5-32 mm diameter feed electrical cable drawing and general conductor fabrication. Germany's Bundesnetzagentar grid replacement programs concentrate demand for EN 573-3 certified round rod in high-purity 1350 alloy specifications.
- Custom Sections:Architecturally specified extruded geometries for curtain wall systems and specialty industrial channels command defensible margin pools through design-to-order workflows. French building codes mandate fire-performance certification for facade applications, extending qualification timelines.
- Hexagonal Rod:Six-sided cold-heading feedstock for fastener manufacturing serves automotive and machinery sectors.
- Square Rod:Machining bar stock for milled components in industrial equipment and tooling applications.
Round rod retains volume leadership; custom sections hold the steepest expansion curve.
End User:
Application maturity spreads from established electrical infrastructure through emerging aerospace specifications.
- Electrical:Transmission and distribution cable manufacturers represent the foundational demand pool, with France's RTE and Germany's TenneT specifying high-conductivity alloys for overhead line modernization. EU Green Deal carbon border adjustments favor Nordic hydro-powered feedstock in utility procurement scoring.
- Automotive:Battery electric vehicle platforms require lightweight high-strength rod for 800V architecture harness systems. Germany's industrial corridor concentrates OEM cable plant demand, with REACH compliance on heavy metal content displacing copper-clad alternatives.
- Construction:Building wire and architectural applications face national fire code variations across France, Germany, and Benelux markets.
- Aerospace:Fastener-grade rod for airframe assembly demands aerospace-certified melt practices and lot traceability.
Electrical end-use retains volume leadership; automotive holds the steepest expansion curve.
Application:
Volume concentration versus value capture splits across commodity and precision-engineered consumption channels.
- Cables:Insulated conductor manufacturing consumes the majority of European wire rod output, with cross-border grid interconnection projects in Belgium and the Netherlands expanding specification requirements for fire-resistant alloys in tunnel installations.
- Fasteners:Cold-heading and machining applications for automotive, aerospace, and industrial assembly require tighter dimensional tolerances and surface quality controls than cable-grade material.
- Conductors:Bare overhead transmission wire for utility infrastructure competes on conductivity-to-weight ratios against copper alternatives.
- Machined Parts:Precision-turned components for industrial equipment and consumer goods leverage rod as intermediate feedstock.
Cables retain volume leadership; fasteners hold the steepest expansion curve.
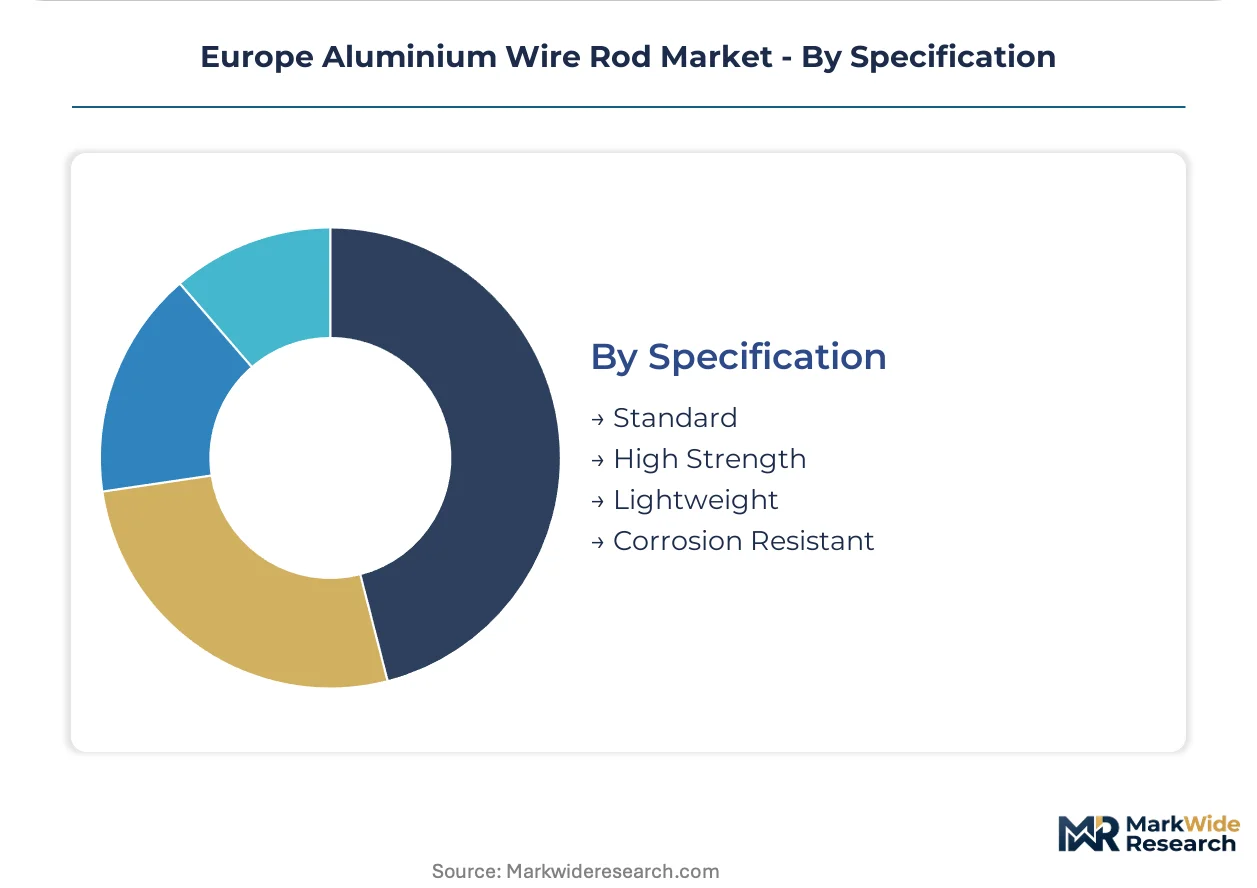
Specification:
Performance tiering separates commodity conductivity grades from engineered mechanical property sets.
- Standard:Electrical-grade 1350 alloy optimized for conductivity in transmission and distribution applications, produced via Properzi or Southwire rolling systems to EN 573-3 chemistry limits.
- High Strength:Alloyed compositions for automotive harness and structural applications where mechanical load-bearing exceeds pure conductivity requirements, commanding premium positioning through additive element control.
- Lightweight:Reduced-density formulations for aerospace and mobility applications where mass reduction justifies material cost premiums.
- Corrosion Resistant:Marine-grade and chemically protected alloys for coastal infrastructure and aggressive environments.
Standard specification retains volume leadership; high strength holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon border adjustments and national decarbonization mandates are redirecting wire rod procurement toward low-carbon smelting regions. Nordic hydro-powered capacity gains competitive advantage over gas-dependent continental producers.
Germany
Bundesnetzagentar grid replacement programs and automotive electrification drive high-conductivity and high-strength alloy consumption. REACH compliance on heavy metal content shapes material specifications for electrical applications. The industrial corridor spanning North Rhine-Westphalia and Bavaria concentrates cable plant demand from TenneT and OEM harness suppliers.
France
RTE overhead line modernization and Enedis distribution upgrades specify certified aluminium conductor rod for transmission infrastructure. National building codes mandate fire-performance certification for construction-grade applications. The Île-de-France and Auvergne-Rhône-Alpes clusters host utility procurement headquarters and specialty alloy fabricators serving nuclear and renewable grid connections.
Norway
Hydro-powered electrolysis delivers renewable credentials that secure long-term utility contracts across continental Europe. ECHA substance restrictions and EU Green Deal embedded emissions reporting favor Norwegian primary metal in procurement scoring. The smelter belt along western fjords anchors captive offtake arrangements with German and Benelux wire rod mills.
Belgium
Cross-border grid interconnection projects with the Netherlands expand demand for fire-resistant alloy rod in tunnel and urban installations. CSRD-aligned lifecycle certification requirements reward verified low-carbon sourcing in utility procurement. The Antwerp-Rotterdam port corridor facilitates import logistics for Middle Eastern and Canadian primary aluminium feedstock.
Italy
Distribution network upgrades and renewable energy connection projects consume standard-grade electrical rod for regional utilities. Carbon border adjustment documentation requirements reshape sourcing patterns away from Russian and Chinese billet suppliers. Northern industrial clusters in Lombardy and Piedmont concentrate downstream cable manufacturing and automotive component fabrication.
Europe Aluminium Wire Rod Market Competitive Landscape
On the supply side, the industry is consolidating around integrated smelter-to-rod operations and specialized electrical-grade producers. Three archetypes dominate: Nordic hydro-powered integrated players with renewable credentials, continental gas-dependent mills with automotive specialization, and Benelux-based grid-focused specialists. Competitive moves center on securing captive primary aluminium supply through long-term offtake agreements and achieving dual EN 573-3 and ECHA certification for utility procurement eligibility.
Among Nordic integrated producers, Norsk Hydro ASA exemplifies the renewable-powered archetype with hydro-based electrolysis positioning. TRIMET Aluminium SE represents German automotive-grade specialization through integrated casting operations. Lamifil NV occupies the Benelux electrical specialist tier serving grid operators with high-purity conductor rod. These three anchors illustrate how geographic energy sourcing and end-use focus stratify competitive positioning across the European value chain.
| Leading Market Players |
|---|
| Hindalco Industries Ltd |
| TRIMET Aluminium SE |
| Alcoa Corp |
| National Aluminium Co. Ltd |
| Lamifil NV |
| Norsk Hydro ASA |
| Vimetco NV |
| Prysmian Spa |
| United Company RUSAL |
| Others |
Supply & Pricing Matrix
The Nordic smelter belt along Norway's western fjords concentrates low-carbon primary aluminium capacity, translating renewable hydro credentials into pricing power over gas-dependent continental mills serving German cable plants.
Pricing Analysis
Certification level creates the primary spread across the European wire rod market, separating ISO 14064-verified low-carbon grades from standard EN 573-3 material. Three-tier pricing structure across premium, standard, and economy levels reflects embedded emissions documentation, alloy purity, and volume commitment scale. Cost compression in standard-grade rod is intensifying because Nordic hydro-powered producers capture utility procurement share from continental gas-indexed competitors. Automotive harness suppliers exhibit lowest price sensitivity due to REACH compliance mandates and lot traceability requirements, while construction distributors remain most responsive to spot price movements.
Supply Chain Analysis
Extended payment terms from German utility procurement departments and supply-chain finance facilities at Antwerp-Rotterdam port operators lubricate working capital for wire rod mills. Primary aluminium feedstock draws from Norway, Iceland, and Canada after EU carbon border adjustments redirected flows away from Russian and Chinese billet. Smelter concentration risk in Nordic hydro regions represents the dominant structural vulnerability for continental European cable manufacturers. Distribution runs through direct mill-to-plant arrangements for high-volume electrical grade, with merchant distributors handling specialty alloy and custom section orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lifecycle certification services and carbon accounting verification represent the fastest-expanding revenue layer in European aluminium wire rod, outpacing underlying metal volume growth as utilities embed CSRD-aligned scoring into procurement contracts.
For Market Incumbents: Pre-empt Nordic hydro-powered competitors by securing captive primary aluminium offtake through long-term power purchase agreements with Icelandic and Norwegian smelters. Deepen backward integration into continuous casting technology to reduce solidification segregation and defend margin position against twin-roll thin strip entrants. Prioritize dual EN 573-3 and ECHA SVHC certification investment to compress the 8-14 month qualification cycle that delays new product introductions.
For New Entrants and Emerging Players: Mid-market automotive harness suppliers in Germany's industrial corridor represent the most penetrable entry point, as 800V architecture cabling demand outpaces incumbent high-strength alloy capacity. Benelux grid interconnection projects for tunnel and urban installations offer second-mover access through fire-resistant alloy specialization. Partner with established cable manufacturers for toll-processing arrangements rather than building greenfield smelter capacity.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors Benelux-based grid specialists with established utility procurement relationships and verified low-carbon sourcing credentials. Five-to-ten year viability hinges on carbon border adjustment mechanism enforcement intensity and Nordic hydro capacity expansion rates. Monitor utility procurement panel consolidation announcements from TenneT and Enedis as the primary inflection indicator for volume concentration trends.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Aluminium | Captive hydro-powered feedstock from Norwegian smelters secures carbon-adjusted cost advantage for German mills. |
| Dual Certification Acceleration | Parallel EN 573-3 and ECHA SVHC workflows compress 14-month qualification cycles to capture automotive harness demand. |
| Twin-Roll Casting Technology Transition | Migration from Properzi systems reduces solidification segregation for improved drawability in high-purity electrical rod. |
| CSRD-Aligned Lifecycle Verification | ISO 14064 documentation unlocks procurement scoring advantages with France's Enedis and Germany's TenneT. |
| Fire-Resistant Alloy Development | Specialized formulations for Benelux tunnel installations address cross-border grid interconnection specification gaps. |
Research Methodology
A standing panel of smelter operations directors, cable plant procurement managers, utility grid planning officers, and ECHA regulatory consultants provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with continuous casting process engineers and aftermarket service heads at legacy Properzi and Southwire installations. Secondary validation drew from EU customs trade data, SEC filings of listed aluminium producers, ECHA substance restriction updates, and Bundesnetzagentar grid investment disclosures. Bottom-up alloy-grade demand modeling and top-down regional consumption estimates were triangulated to anchor volume forecasts.
Scenario-bracketing around electricity price volatility and carbon border adjustment enforcement intensity framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product geometry, end-use application, alloy specification tier, and regional energy sourcing cluster. CAGRs were derived from trend extrapolation of utility procurement volumes and automotive platform electrification timelines, cross-checked against smelter capacity expansion announcements and power purchase agreement flows.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity pricing spreads between Nordic hydro regions and continental gas-indexed grids would shift the trajectory of regional supply allocation. Forecasts reflect documented assumptions regarding EU Green Deal implementation pace and REACH substance restriction timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Prebaked Anodes for Aluminum Market
Metals
Steel Ingots Market
Metals
Steel Drums and Ibcs Market
Metals
Tungsten Metal Powder Market
Metals
Global Galvanized Steel Wire Market
Metals
Copper Smelting Market
Metals
South America Metal Finishing Market
Metals
Base Metals Market
Metals
Metal Injection Molding (MIM) Parts Market
Metals
Ferro Vanadium Market
Metals
Global Stretch Spring Wire Market
Metals
North America Grain Oriented Electrical Steel Market
Metals
Molybdenum Market
Metals
Zinc Plating Market
Metals
Aluminum Flat Products Market
Metals
Metal Finishing Market