
 Stainless Steel Welded Pipes Market | 2026-2036
Stainless Steel Welded Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Stainless Steel Welded Pipes Market Outlook
Aftermarket service revenue for corrosion monitoring and weld integrity inspection is tilting toward higher-margin long-term contracts. Sandvik AB leverages its precision tubing expertise to dominate niche chemical transport segments. ArcelorMittal S.A. sustains manufacturing scale across European flat-rolled stainless operations. Nippon Steel Corporation anchors its position through backward integration into ferrochrome supply.
Stainless steel welded pipes are tubular products formed from flat-rolled strip through electric resistance welding or laser welding, then cold-worked to precise dimensions with chromium content exceeding 10.5 percent for oxidation resistance. These pipes convey corrosive fluids, support structural loads, and maintain hygienic conditions in process industries. The welded category leads volume due to cost efficiency in Schedule 40 and Schedule 10 thickness grades for water supply and gas distribution networks. Heavy-wall segments for oil and gas pressure service capture disproportionate margin pools. Thin-wall applications in food processing equipment represent the fastest-growing specification tier.
ASTM International governs material grades and dimensional tolerances for North American market access, while the EU F-Gas Regulation and REACH compliance shape product specifications for European chemical transport buyers. China's GB standards and SAMR quality certifications dictate import eligibility for foreign welded pipe suppliers. Buyers must monitor divergence between regional pressure equipment codes and evolving low-carbon procurement rules.
Market Dynamics
Dual carbon compliance mandates in China are forcing stainless steel welded pipe mills to retrofit electric arc furnaces and install carbon capture systems, compressing operating margins while reshaping supplier qualification criteria for petrochemical buyers.
Growth Catalysts
- ASTM A312 specification tightening:North American pressure equipment codes now mandate enhanced ferrite content testing for sour service applications, disqualifying legacy suppliers and concentrating procurement among certified mills.
- Yangtze River Delta petrochemical expansion:China's state-backed refinery upgrades require duplex-grade welded pipe for chloride-rich process streams, creating dedicated demand for 2205 and 2507 alloy specifications.
- Laser welding process maturation:Solid-state joining technology enables thinner wall sections with equivalent pressure ratings, reducing material input costs for water distribution network tenders.
Market Restraints
- Ferrochrome supply concentration:South African chromite ore exports face persistent logistics constraints, transmitting volatility through 300-series stainless steel strip pricing to welded pipe converters.
- Seamless pipe substitution in ultra-high pressure:Oil and gas operators above 10,000 psi service specifications specify seamless construction, capping welded pipe penetration in premium upstream segments.
- EU F-Gas Regulation compliance costs:Refrigeration system fabricators must document full material traceability for welded pipe in heat exchanger coils, extending order-to-delivery timelines by 6-8 weeks.
Strategic Opportunities
- India PLI scheme for specialty steel:Production-linked incentives for 300,000 tonnes annual stainless steel capacity create localized welded pipe supply for pharmaceutical and dairy equipment OEMs.
- Hydrogen pipeline infrastructure:Embrittlement-resistant austenitic grades for high-pressure hydrogen transport represent uncaptured specification territory outside existing ASME B31.12 frameworks.
- Digital twin integration with corrosion monitoring:Welded pipe fabricators bundling sensor-embedded tubing with predictive analytics subscriptions capture recurring revenue from chemical plant operators.
Industry Challenges
- ASME IX welder certification backlog:Qualified orbital welding technicians for sanitary tubing applications command 40% wage premiums, constraining expansion for food-grade pipe specialists.
- Legacy ERP integration with MES systems:Mid-scale welded pipe mills struggle to connect shop-floor thickness gauging data to customer portals for real-time order tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stainless Steel Welded Pipes Market |
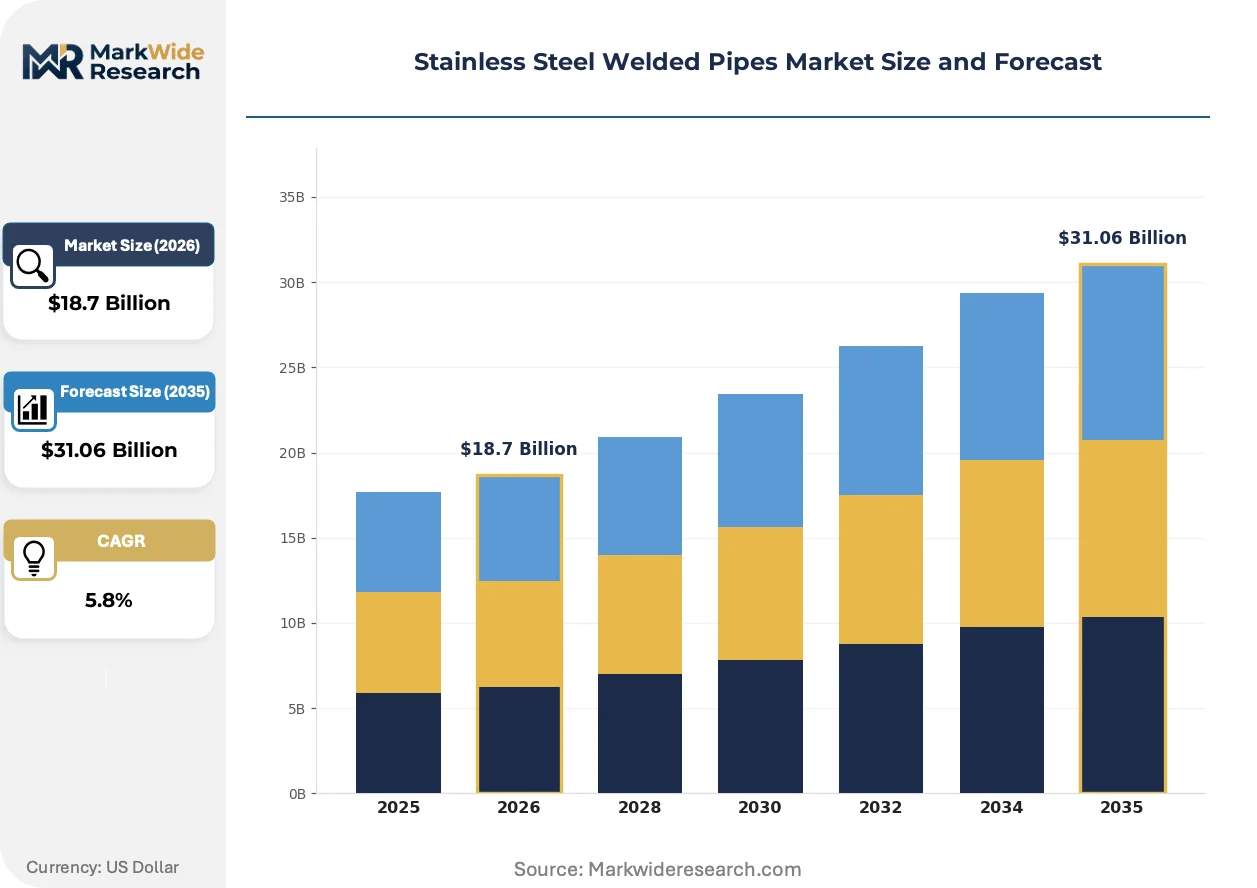
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless, Welded, Spooled, Fabricated End User: Construction, Oil & Gas, Food Processing, Automotive Application: Water Supply, Gas Distribution, Structural, Chemical Transport Thickness: Thin-Wall, Schedule 10, Schedule 40, Heavy-Wall |
| Companies Covered | Sandvik AB, ArcelorMittal S.A., Nippon Steel Corporation, Outokumpu Oyj, ThyssenKrupp AG, Marcegaglia Specialties, H. BUTTING GmbH & Co. KG, Tenaris, Jindal SAW Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stainless Steel Welded Pipes Market Strategic Shifts
Electrification of process industries and tightening material traceability requirements are compressing traditional specification hierarchies, forcing welded pipe suppliers to bundle metallurgical testing data directly with physical deliveries.
Hybrid laser-arc welding is collapsing the quality gap between automated and manual joining processes in heavy-wall pressure service pipe. Offshore platform fabricators in the Gulf of Mexico now specify hybrid-welded 316L for riser applications previously reserved for seamless product. This process convergence is collapsing price premiums for Schedule 80 and Schedule 160 welded categories, redistributing margin toward inspection and documentation services.
REACH authorization list expansion for nickel compounds is compelling European stainless steel producers to accelerate low-nickel ferritic grade development for architectural and automotive exhaust applications. The restriction on nickel sulfate and nickel carbonate classifications is pushing welded pipe inventories toward 400-series alternatives in non-corrosive environments. German automotive Tier 1 suppliers now mandate ferritic welded tubing for exhaust manifolds to preempt downstream liability exposure.
Consolidated procurement through integrated EPC firms is displacing fragmented distributor purchasing in Middle Eastern desalination projects. Saudi Arabia's ACWA Power and UAE's TAQA now specify mill-direct welded pipe contracts with 15-year corrosion performance guarantees, bypassing traditional stock-and-cut intermediaries. This buyer concentration is most visible in Red Sea coastal projects where logistics integration outweighs spot price flexibility.
Stainless Steel Welded Pipes Market Segmentation
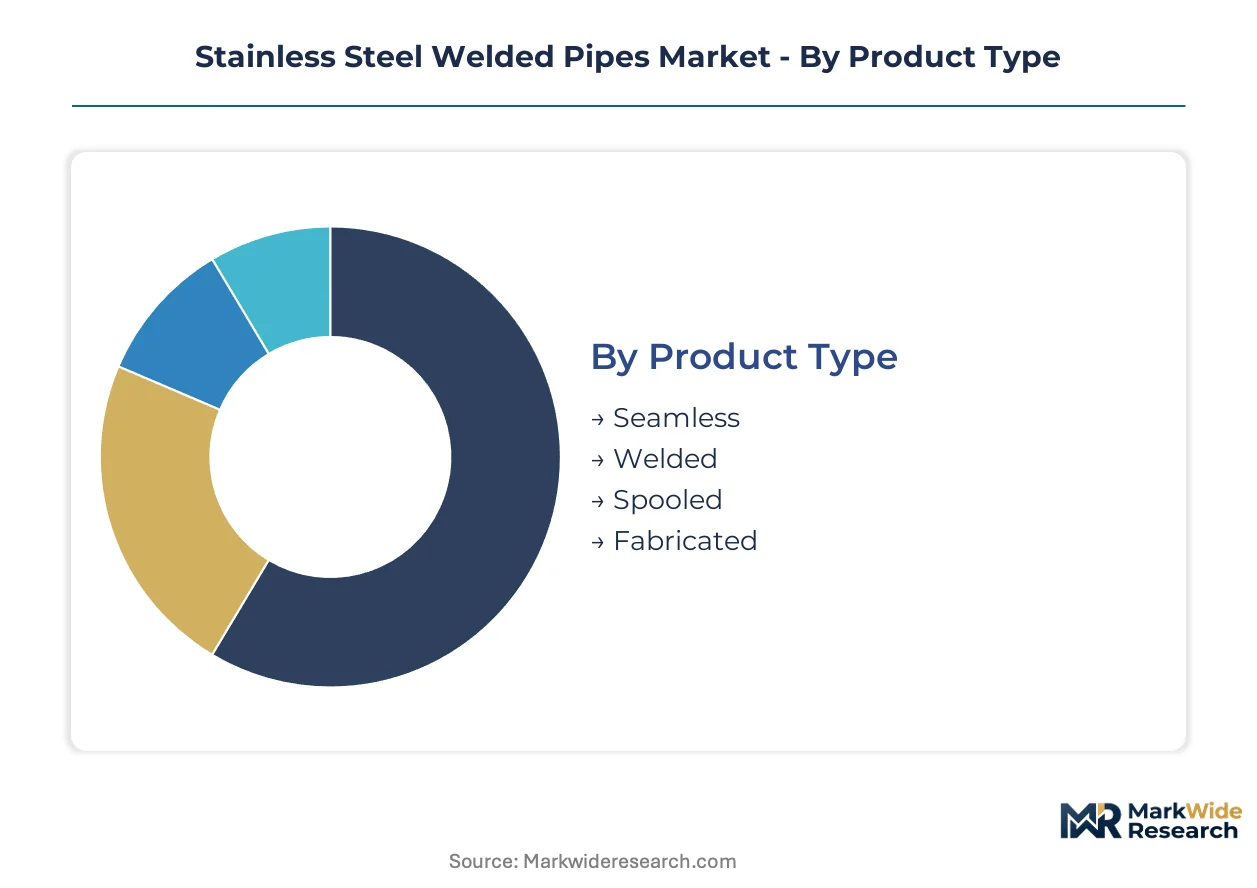
Stainless steel welded pipes serve distinct performance tiers across pressure ratings, corrosion exposure, and fabrication complexity. Specification divergence between Schedule 40 water infrastructure and heavy-wall oilfield service creates parallel supply chains with limited interchangeability.
Product Type:
Mature electric resistance welding dominates volume production while laser-based solid-state joining represents the emerging precision tier.
- Seamless:Hot-extruded or rotary-pierced construction eliminates weld seams entirely, commanding specification for ultra-high-pressure hydrogen and sour gas service above 10,000 psi. North American oilfield procurement now mandates seamless construction for subsea riser applications, displacing welded alternatives in premium upstream segments.
- Welded:Cold-formed strip joined through electric resistance or laser processes delivers cost efficiency for Schedule 10 and Schedule 40 distribution networks. China's Yangtze River Delta petrochemical corridor sources welded duplex pipe for chloride-rich process streams, concentrating demand for 2205 and 2507 alloy specifications.
- Spooled:Continuous-length coiled tubing reduces field joint count in offshore deployment and horizontal directional drilling.
- Fabricated:Custom-cut and pre-assembled spool pieces with welded fittings serve modular plant construction.
Welded construction retains volume leadership; seamless holds the steepest expansion curve in hydrogen infrastructure specifications.
End User:
Cost tier stratification separates commodity construction procurement from premium-certified food and pharmaceutical grades.
- Construction:Architectural cladding and structural support applications utilize 304 and 316 grades with standard mill finish, competing against carbon steel on lifecycle cost rather than upfront material expense.
- Oil & Gas:Sour service mandates under ASTM A312 now require enhanced ferrite content testing, disqualifying legacy suppliers and concentrating procurement among certified mills serving Gulf of Mexico platform fabricators.
- Food Processing:Sanitary tubing with orbital-welded joints and surface finishes below 0.8 micrometers Ra commands 40% wage premiums for ASME IX certified technicians, constraining expansion for specialized fabricators.
- Automotive:German Tier 1 suppliers now mandate ferritic welded tubing for exhaust manifolds to preempt REACH authorization liability on nickel compounds.
Construction absorbs the highest tonnage; food processing climbs fastest on regulatory compliance premiums.
Application:
Volume concentration in fluid transport networks contrasts with margin concentration in structural and chemical service specifications.
- Water Supply:Municipal distribution networks specify Schedule 40 welded pipe for corrosion resistance in aggressive soil conditions, with laser welding enabling thinner wall sections that reduce material input costs.
- Gas Distribution:Medium-pressure utility networks in Europe face EU F-Gas Regulation compliance costs requiring full material traceability documentation, extending order-to-delivery timelines.
- Structural:Load-bearing architectural applications favor 304-grade welded hollow sections with standardized mill tolerances.
- Chemical Transport:Duplex and super-duplex welded pipe conveys chloride-rich process streams in China's state-backed refinery upgrades along the Yangtze River Delta.
Water supply dominates unit volume; chemical transport captures the highest margin per meter.
Thickness:
Wall specification directly determines welding process selection and pressure rating certification pathways.
- Thin-Wall:Sub-2mm sections for food processing equipment and heat exchanger coils require precision laser welding with minimal heat-affected zone distortion.
- Schedule 10:Light-wall commercial piping for low-pressure steam and condensate lines balances material economy with structural integrity.
- Schedule 40:Standard-weight construction for water and gas distribution networks represents the highest-volume specification tier with established ASTM dimensional tolerances.
- Heavy-Wall:Schedule 80 and above for oilfield pressure service now accepts hybrid laser-arc welded construction, collapsing historical price premiums toward seamless alternatives.
Schedule 40 maintains production dominance; thin-wall specifications expand most quickly on food and pharmaceutical equipment demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes welded pipe primarily for chemical transport infrastructure, while the United States and Germany deploy equivalent tonnage across water distribution and food processing applications with stricter certification requirements.
China
State-backed refinery upgrades along the Yangtze River Delta drive duplex-grade demand for chloride-rich process streams. MIIT's dual carbon mandates force electric arc furnace retrofits, compressing mill margins while tightening supplier qualification criteria. The petrochemical corridor between Shanghai and Nanjing concentrates procurement for 2205 and 2507 alloy specifications.
United States
Gulf of Mexico platform fabricators specify hybrid laser-arc welded 316L for riser applications previously reserved for seamless product. ASTM A312 now mandates enhanced ferrite content testing for sour service, disqualifying uncertified mills. Houston-area distributors face consolidation pressure from integrated EPC firms demanding 15-year corrosion performance guarantees.
Germany
Automotive Tier 1 suppliers mandate ferritic welded tubing for exhaust manifolds to preempt REACH authorization liability on nickel compounds. ECHA's restriction on nickel sulfate and nickel carbonate classifications accelerates 400-series grade development. The Ruhr industrial basin anchors fabrication capacity for architectural and automotive exhaust applications.
India
Pharmaceutical and dairy equipment OEMs source localized supply under the PLI scheme for 300,000 tonnes annual stainless steel capacity. BIS certification requirements and DGFT import protocols shape foreign supplier eligibility. Gujarat's specialty steel corridor attracts welded pipe investment targeting food-grade and sanitary tubing segments.
Japan
Precision tubing for semiconductor and chemical process applications maintains specification premiums despite domestic volume constraints. METI's carbon neutrality roadmap pressures stainless mills to document Scope 3 emissions across ferrochrome supply chains. The Chubu region around Nagoya concentrates high-purity welded pipe fabrication for export markets.
Stainless Steel Welded Pipes Market Competitive Environment
Capability concentration sits with precision-grade specialists; scale advantage sits with integrated flat-rolled producers. The market structures around three tiers: multinational stainless steel conglomerates with captive strip supply, regional welded pipe fabricators serving certified niche segments, and commodity converters competing on Schedule 40 water infrastructure tenders. Dominant competitive moves include backward integration into ferrochrome supply and bundling corrosion monitoring services with physical deliveries.
Among European-based producers, ArcelorMittal S.A. and Outokumpu Oyj exemplify the integrated conglomerate archetype with captive stainless steelmaking capacity. Sandvik AB occupies a position within the precision-tier segment, representing specialists in high-performance tubing for chemical and process industries. Nippon Steel Corporation anchors the Asia-Pacific competitive set through upstream control over ferrochrome procurement.
| Leading Market Players |
|---|
| Sandvik AB |
| ArcelorMittal S.A. |
| Nippon Steel Corporation |
| Outokumpu Oyj |
| ThyssenKrupp AG |
| Marcegaglia Specialties |
| H. BUTTING GmbH & Co. KG |
| Tenaris |
| Jindal SAW Ltd. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's Yangtze River Delta strip mills is compressing base material spreads and forcing welded pipe converters toward fixed-price annual contracts to stabilize margin visibility. This utilization dynamic rewards buyers with volume certainty while squeezing spot-market participants exposed to ferrochrome volatility.
Pricing Analysis
Long-term offtake agreements now dominate procurement for Schedule 40 water infrastructure and chemical transport grades, displacing spot purchases above ten-thousand-tonne annual volumes. Price differentiation hinges on ASME IX certification tier and bundled corrosion monitoring services, with uncertified mills facing thirty-percent discounts to qualified suppliers. Cost compression in heavy-wall segments is intensifying as hybrid laser-arc welding collapses historical seamless premiums. Municipal water utilities exhibit highest price sensitivity, while offshore platform fabricators prioritize performance guarantees over unit cost.
Supply Chain Analysis
Ferrochrome feedstock draws from South African chromite ore, Chinese ferroalloy smelters, and Kazakh chromium concentrate, creating geographic concentration risk across three distinct regulatory jurisdictions. Stainless steel strip production rests on nickel cathode, ferrochrome, and molybdenum disulfide inputs, with South African logistics constraints transmitting volatility through three-hundred-series pricing. Single-source vulnerability in chromite ore exposes converters to export permit disruptions. Distribution runs through mill-direct contracts with integrated EPC firms, bypassing traditional stock-and-cut distributors in Middle Eastern desalination and Gulf of Mexico offshore projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orbital welding technician scarcity constrains expansion for food-grade and sanitary tubing specialists, creating asymmetric returns for firms that solve certification bottlenecks before competitors.
For Market Incumbents: Harden ASME IX welder certification pipelines through apprenticeship partnerships with Houston-area technical colleges and Nagoya precision engineering institutes. Defend margin position by bundling sensor-embedded tubing with predictive analytics subscriptions, preempting standalone corrosion monitoring vendors. Capacity consolidation in European flat-rolled operations secures captive strip supply against South African ferrochrome volatility. For New Entrants and Emerging Players: Pursue hydrogen pipeline infrastructure specifications outside existing ASME B31.12 frameworks, where embrittlement-resistant austenitic grades remain uncaptured territory. India's pharmaceutical and dairy equipment OEMs under the PLI scheme offer localized white-space with BIS certification barriers surmountable through Gujarat joint ventures. Lead with digital twin integration capabilities rather than price competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across duplex-grade welded pipe capacity as MIIT dual carbon mandates force electric arc furnace retrofits. Five-to-ten-year viability favors precision-tier specialists with backward integration into ferrochrome supply or captive laser welding IP. Target acquisition profile centers on mid-scale fabricators with unutilized ASME certification scope and stranded ERP assets ripe for MES integration. Watch ferrochrome export permit volumes from South Africa as inflection signal for input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrochrome Supply | Nippon Steel's upstream control insulates margin from South African logistics disruptions. |
| Hybrid Laser-Arc Welding Process Deployment | Gulf of Mexico platform fabricators now specify hybrid-welded 316L for riser applications. |
| Digital Twin Integration with Corrosion Monitoring | Sensor-embedded tubing bundles capture recurring revenue from chemical plant operators. |
| ASME IX Certification Pipeline Investment | Orbital welding technician scarcity commands forty-percent wage premiums in food-grade segments. |
| Mill-Direct EPC Contract Structuring | ACWA Power and TAQA now bypass distributors for fifteen-year performance guarantees. |
Study Parameters
A spread of perspectives from plant managers at welded pipe mills, procurement leads at petrochemical OEMs, EPC contractors in desalination and offshore construction, and aftermarket service heads converged on the working assumptions. Secondary validation drew from customs and trade data, SEC filings of integrated stainless steel producers, ASTM and ASME standards documentation, and MIIT dual carbon policy releases. Bottom-up capacity and utilization estimates triangulated against top-down end-use demand modeling.
Demand-supply balance framing anchored the analytical approach across the analysis window, with segmentation dimensions spanning product type, thickness specification, end-use industry, and regional production hub. CAGRs derived from regression against historical capacity additions, alloy price trajectories, and regulatory compliance cost escalations. Forecast inputs incorporated electric arc furnace retrofit timelines under China's dual carbon mandates and REACH authorization list expansions for nickel compounds.
Macroeconomic conditions sit as an overlay; deviation in Chinese construction investment cycles, South African chromite export logistics, or European carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions on technology adoption curves and regulatory enforcement intensity. Cross-checking against stainless steel strip mill utilization rates and ferrochrome spot price indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Global Butt Weld Fittings Market
Pipes and Tubes
ESR Tubes Market
Pipes and Tubes
Galvanized Iron Pipes Market
Pipes and Tubes
Plastic Pipes and Fittings Market
Pipes and Tubes
Seamless Pipe Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
Glass Reinforced Plastic (GRP) Piping Market
Pipes and Tubes
Germany Acid Proof Lining Market
Pipes and Tubes
FRP Pipes and Tanks Market
Pipes and Tubes
Pipes and Fittings Market
Pipes and Tubes
Steel Pipes and Tubes Market
Pipes and Tubes
GRE Pipes Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
PVDF Pipes Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
Stainless Steel Plumbing Pipes and Fittings Market