
 Brazil Aluminum Market | 2026-2036
Brazil Aluminum Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Aluminum Market Insights
Primary smelter capacity in Pará state is expanding through hydroelectric-powered electrolysis complexes. CBA leverages captive bauxite reserves and integrated refining to anchor its southeastern Brazil operations. Novelis specializes in flat-rolled recycling and competes on closed-loop beverage can supply chains. Votorantim sustains long-term alumina refining dominance through strategic positioning along northern logistics corridors.
Aluminum is a lightweight, corrosion-resistant metal with density of 2.7 g/cm³, extracted from bauxite via the Bayer process and Hall-Héroult electrolysis, serving structural, conductive, and barrier functions across industries. Flat rolled products dominate packaging and transportation applications due to continuous casting efficiency and thin-gauge formability. Extrusions lead building facade and construction demand in southeastern Brazil's urban expansion corridors. Castings retain mature, cost-driven positioning in automotive powertrain components where alloy 6061 and 7075 grades compete on strength-to-weight ratios.
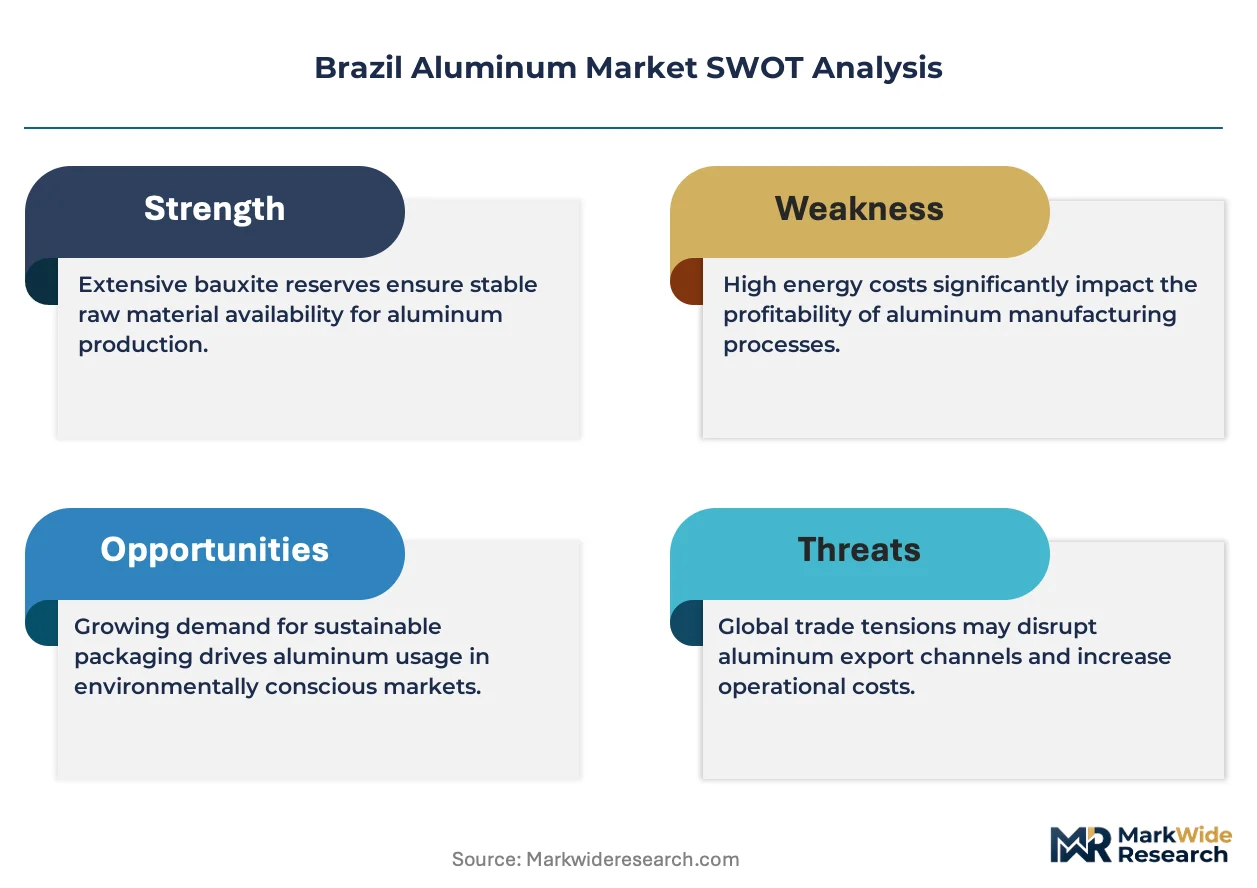
ANVISA governs food-contact aluminum packaging standards, while the Brazilian Institute of Metrology (INMETRO) enforces alloy grade certification and dimensional tolerances for structural applications. Environmental licensing through IBAMA shapes smelter expansion timelines in Amazon basin hydroelectric zones. Stakeholders must monitor grid decarbonization commitments and scrap collection infrastructure investments that determine long-term cost competitiveness against imported primary metal.
Market Dynamics
Hydroelectric-powered smelter expansions in Pará state are redrawing Brazil's aluminum supply geography, concentrating primary metal output near Amazon basin energy reserves while southeastern fabricators face rising logistics premiums to access feedstock.
Growth Catalysts
- Automotive lightweighting mandates:Brazilian OEMs are substituting aluminum for steel in chassis and body-in-white structures to meet evolving fuel efficiency standards, pulling flat-rolled and extruded volumes into São Paulo's assembly corridors.
- ANVISA food-contact packaging rules:Stricter barrier-layer specifications for beverage cans and flexible pouches are disqualifying lower-grade imports, creating captive demand for domestically certified foil and lacquered sheet.
- Construction sector acceleration:Urban expansion across southeastern Brazil is consuming curtain wall extrusions and structural profiles, with Minas Gerais and Rio de Janeiro building codes increasingly specifying aluminum for facade systems.
Market Restraints
- Alumina input cost volatility:Bauxite refining margins swing with natural gas and caustic soda pricing, squeezing smelter economics when northern logistics disruptions delay feedstock delivery to Pará electrolysis complexes.
- Grid concentration risk:Over 70% of primary capacity sits within a single hydroelectric basin, exposing output to drought-induced dispatch curtailments and IBAMA licensing delays for transmission upgrades.
- Steel substitution resilience:Rebar and galvanized sheet retain cost advantages in low-specification construction segments, capping aluminum penetration in residential framing and infrastructure concrete reinforcement.
Strategic Opportunities
- Closed-loop beverage can recycling:Reverse logistics networks for post-consumer UBC collection remain underdeveloped outside São Paulo state, offering first-mover returns for integrated recycler-smelter partnerships.
- Renewable energy mounting systems:Solar tracker and wind tower component demand is emerging in Brazil's northeastern wind corridor, requiring corrosion-resistant extrusions with localized alloy certification.
- INMETRO alloy grade harmonization:Pending convergence with ASTM and EN structural standards would unlock export qualification for southeastern Brazil's extrusion houses, redirecting capacity toward Mercosur infrastructure projects.
Industry Challenges
- Electrolysis technician scarcity:Potline operations and carbon anode management require specialized metallurgical training that Brazilian technical institutes have not scaled to match smelter expansion timelines in Pará.
- Scrap sorting infrastructure gaps:Automated alloy-separation systems for post-consumer automotive and building demolition scrap remain concentrated in São Paulo, limiting feedstock quality for secondary smelters in other states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Aluminum Market |
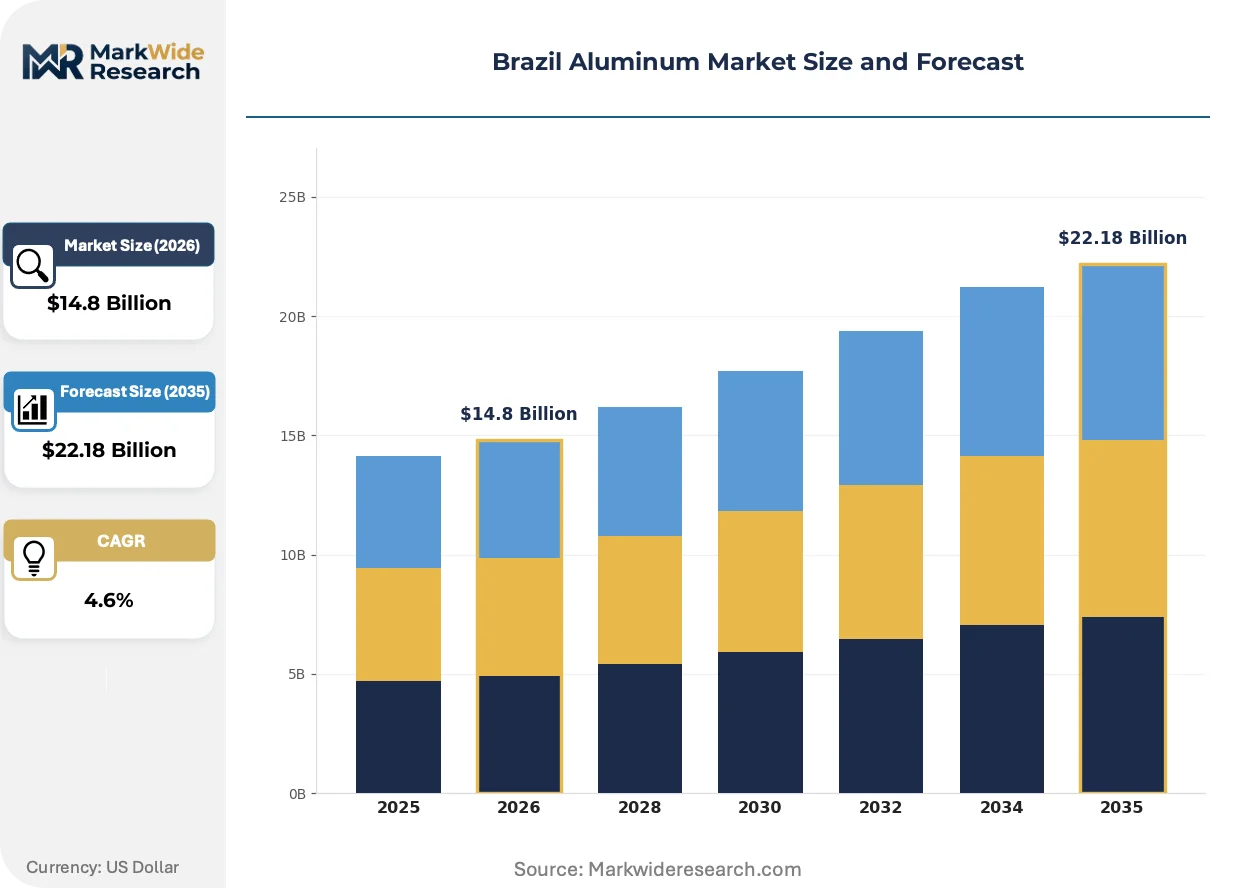
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extrusions, Flat Rolled Products, Forged Products, Castings End User: Construction, Automotive Parts, Consumer Electronics, Aerospace Application: Packaging, Transportation, Electrical Conductors, Building Facades Grade: Aluminum 6061, Aluminum 2024, Aluminum 7075, Aluminum 1050 |
| Companies Covered | Votorantim, South32, Companhia Brasileira de Alumínio (CBA), Albras, Aluminum Corporation of China (Chalco), Alcoa Corporation, Norsk Hydro, Novelis, Rio Tinto, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Aluminum Market Trends and Innovations
Digital twin modeling of electrolysis cells and inert anode pilot programs are converging with circular economy mandates to compress emissions intensity and reshape competitive advantage around energy sourcing rather than scale alone.
Inert anode technology is rewriting the carbon footprint calculus for primary aluminum. Alcoa and Rio Tinto's joint development programs are targeting Brazilian pilot installations by decade-end. This technology is eliminating direct CO2 emissions from smelting, forcing legacy Søderberg and prebake operations to defend position through renewable energy certificates rather than process innovation.
IBAMA's updated environmental licensing protocols for Amazon basin industrial projects are extending approval timelines for new electrolysis capacity. The industrial consequence is a construction backlog that favors brownfield expansions over greenfield sites. Northern Pará smelters are responding by prioritizing efficiency retrofits over capacity additions.
Buyers in Brazil's automotive tier-one supply base are consolidating aluminum procurement through long-term tolling arrangements with CBA and Novelis rather than spot market purchases. This replaces merchant metal trading with integrated supply chain partnerships. The shift is most visible in Minas Gerais, where seating and thermal management component makers have abandoned multi-source strategies for single-supplier qualification models.
Brazil Aluminum Market Segmentation
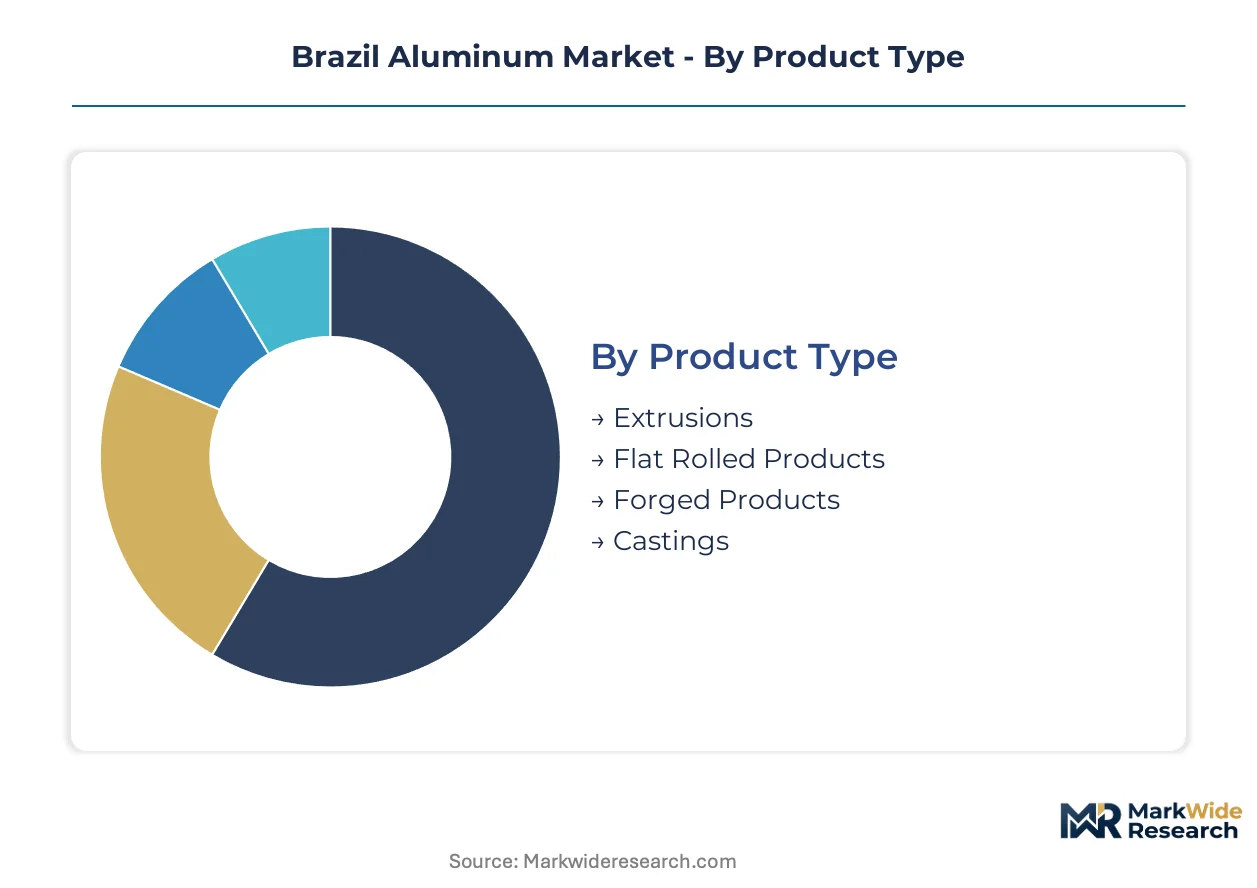
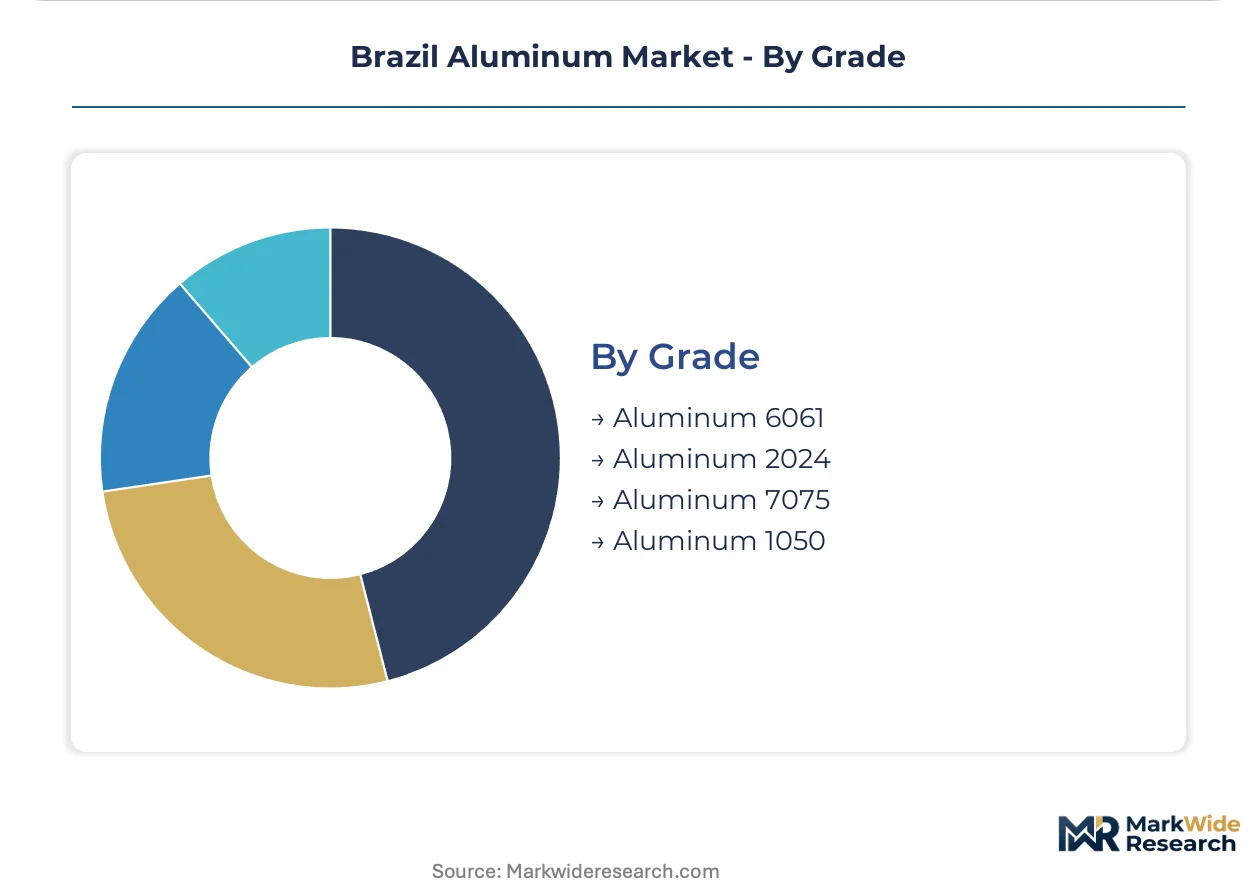
Aluminum segmentation in Brazil reflects divergent technical requirements across hydroelectric-powered primary production and southeastern fabrication clusters. Understanding specification-grade-application linkages reveals where ANVISA certification and INMETRO structural standards create captive demand pockets.
Product Type:
Continuous casting efficiency and thin-gauge formability differentiate product categories serving Brazil's packaging and construction corridors.
- Extrusions:Produced through direct or indirect extrusion of billets into complex cross-sections, these profiles serve curtain wall systems and structural framing. Demand concentrates in São Paulo and Minas Gerais urban expansion zones where building codes specify aluminum for facade systems.
- Flat Rolled Products:Continuously cast and cold-rolled sheet and foil achieve sub-millimeter gauges with precise surface finishes. ANVISA barrier-layer specifications for beverage cans pull certified foil volumes into southeastern Brazil's packaging clusters.
- Forged Products:High-pressure forming of solid billets yields directional grain structures for strength-critical components. Aerospace landing gear and automotive suspension links in São Paulo's tier-one supply base consume these grades.
- Castings:Molten aluminum poured into permanent or sand molds produces near-net-shape powertrain housings. Cost-driven positioning in Brazilian automotive engine blocks faces alloy 6061 extrusion substitution pressure.
Flat rolled products lead on scale; extrusions lead on momentum.
End User:
Customer concentration patterns mirror Brazil's industrial geography, with southeastern states anchoring volume absorption.
- Construction:Curtain wall extrusions and structural profiles dominate material take-off specifications. Minas Gerais and Rio de Janeiro building acceleration consumes alloy 6063 and 6061 grades for corrosion-resistant facade systems.
- Automotive Parts:Chassis substitution programs and body-in-white lightweighting pull flat-rolled and extruded volumes into São Paulo's assembly corridors. OEM fuel efficiency mandates accelerate aluminum-for-steel substitution in structural components.
- Consumer Electronics:Heat sink extrusions and EMI shielding foil serve Brazilian assembly operations for smartphones and laptops. Thin-gauge flat rolled products with anodized finishes dominate this specification-sensitive segment.
- Aerospace:High-strength alloy 7075 and 2024 forgings and plate serve maintenance and limited domestic manufacturing. INMETRO certification alignment with ASTM standards remains incomplete, constraining export qualification.
Construction leads on scale; automotive parts climb the fastest.
Application:
Functional performance requirements segment demand across barrier, conductive, and structural use cases.
- Packaging:Lacquered can sheet and flexible pouch foil require ANVISA food-contact certification. Reverse logistics gaps for post-consumer UBC collection outside São Paulo state constrain closed-loop recycling economics.
- Transportation:Automotive and commercial vehicle applications span cast powertrain housings through extruded bumper beams. São Paulo's tier-one supply base is consolidating procurement through long-term tolling arrangements.
- Electrical Conductors:EC-grade rod and cable shielding exploit aluminum's conductivity-to-weight ratio versus copper. Grid decarbonization commitments in northeastern Brazil's wind corridor pull conductor volumes.
- Building Facades:Anodized and painted extrusions serve curtain wall and window systems. Rio de Janeiro coastal specifications prioritize 6063-T6 alloy for salt spray corrosion resistance.
Packaging leads on scale; electrical conductors gain share fastest.
Grade:
Alloying element composition and heat treatment determine mechanical properties and certification pathways.
- Aluminum 6061:Magnesium-silicide precipitation-hardened alloy balancing strength, corrosion resistance, and extrudability. São Paulo automotive structural components and Minas Gerais building systems specify this grade extensively.
- Aluminum 2024:Copper-primary alloy with high strength-to-weight ratio and fatigue resistance. Aerospace wing and fuselage applications in limited Brazilian manufacturing require import-dependent supply.
- Aluminum 7075:Zinc-magnesium-copper system delivering highest strength among common wrought alloys. Landing gear forgings and high-performance automotive links face INMETRO certification gaps versus ASTM standards.
- Aluminum 1050:Commercially pure grade with 99.5% minimum aluminum content for electrical and chemical applications. Conductor rod and anodized decorative sheet in southeastern Brazil exploit its formability and conductivity.
Aluminum 6061 leads on scale; aluminum 7075 shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing aluminum production geography in Brazil. ANVISA certification requirements and IBAMA environmental licensing create compliance cost gaps that favor established southeastern fabricators over new northern entrants, even as hydroelectric-powered smelter expansions concentrate primary output in Pará state.
São Paulo
Automotive lightweighting mandates and beverage can packaging clusters drive aluminum absorption in São Paulo state's industrial corridors. ANVISA food-contact barrier-layer specifications for lacquered sheet pull certified flat-rolled volumes into Osasco and Guarulhos conversion facilities. Tier-one seating and thermal management component makers in Minas Gerais border zones are consolidating procurement through long-term tolling arrangements with integrated suppliers.
Minas Gerais
Curtain wall extrusions and structural profiles for urban expansion consume alloy 6063 and 6061 grades across Belo Horizonte and Contagem building markets. State building codes increasingly specify aluminum for facade systems, accelerating specification-grade demand. CBA leverages captive bauxite reserves and integrated refining to anchor southeastern Brazil operations from its Poços de Caldas industrial complex.
Pará
Hydroelectric-powered primary smelter capacity is expanding through electrolysis complexes tied to Amazon basin energy reserves. IBAMA environmental licensing protocols extend approval timelines for new capacity, favoring brownfield efficiency retrofits over greenfield sites. Albras and Alcoa Corporation operations near Barcarena concentrate output that faces rising logistics premiums to reach southeastern fabricators.
Rio de Janeiro
Coastal construction specifications prioritize 6063-T6 alloy extrusions for salt spray corrosion resistance in curtain wall and window systems. Building acceleration in Niterói and Duque de Caxias corridor consumes anodized facade materials. State-level infrastructure commitments are pulling structural profile volumes that compete with Minas Gerais suppliers for specification-grade positioning.
Rio Grande do Sul
Automotive component manufacturing in Gravataí and Caxias do Sul industrial zones sources extruded and flat-rolled aluminum for chassis and body-in-white substitution programs. Proximity to Mercosur export corridors positions local fabricators for INMETRO alloy grade harmonization opportunities. Scrap collection infrastructure gaps outside São Paulo state constrain secondary smelter feedstock quality for regional recyclers.
Brazil Aluminum Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue recycling and closed-loop supply chain positioning. The vendor base clusters around three archetypes: integrated primary-smelter-to-fabricator conglomerates controlling captive bauxite and alumina refining; specialized flat-rolled and extrusion houses competing on specification certification and tolling partnerships; and international trading affiliates importing primary metal to bridge northern-southern logistics gaps. Competitive moves center on backward integration into bauxite mining and strategic partnerships for renewable energy offtake agreements that secure low-carbon positioning.
Among Brazil-based integrated producers, Companhia Brasileira de Alumínio and Votorantim exemplify the captive-resource archetype, while Novelis occupies a position within the specialized recycling and flat-rolled tier. Alcoa Corporation represents the multinational primary smelter archetype with established Amazon basin operations. These anchors illustrate how competitive advantage increasingly depends on energy sourcing credentials and ANVISA certification depth rather than scale alone.
| Leading Market Players |
|---|
| Votorantim |
| South32 |
| Companhia Brasileira de Alumínio (CBA) |
| Albras |
| Aluminum Corporation of China (Chalco) |
| Alcoa Corporation |
| Norsk Hydro |
| Novelis |
| Rio Tinto |
| Others |
Pricing and Supply Chain Analysis
IBAMA environmental licensing protocols for Amazon basin smelter expansions gate qualified primary metal supply and tier premium pricing access for certified low-carbon aluminum. Southeastern fabricators face rising logistics premiums to access Pará-state feedstock, compressing margins on standard-grade deliveries while hydroelectric-powered output commands certification-linked premiums.
Pricing Analysis
Distributor margins on imported primary metal range from 8-12% above northern smelter gate prices, with direct-to-OEM tolling arrangements shaving 4-6 points through volume commitments. Pricing stratifies across ANVISA-certified premium grades for food-contact packaging, INMETRO-standard structural extrusions, and uncertified commodity spot metal. Cost compression in standard-grade sheet is intensifying because Brazilian fabricators absorb logistics premiums without pass-through pricing power. Automotive tier-one buyers show lowest price sensitivity due to single-supplier qualification models, while residential construction distributors face acute margin pressure from rebar substitution.
Supply Chain Analysis
Reverse logistics networks for post-consumer used beverage can collection remain concentrated in São Paulo state, constraining closed-loop recycling economics for secondary smelters elsewhere. Primary supply concentrates in Brazil's Pará state, with alumina refining anchored in northern logistics corridors and fabrication clusters in Minas Gerais and São Paulo. The supply chain draws from bauxite mining, caustic soda refining, and carbon anode manufacturing as critical inputs. Single-basin hydroelectric dependency creates drought-induced dispatch curtailment risk. Distribution runs through integrated producer-tollers, merchant metal traders, and direct OEM contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Brazil aluminum market functions as a stable compounder anchored by automotive lightweighting mandates that sustain structural demand growth regardless of commodity cycles.
For Market Incumbents: Deepen captive bauxite integration to insulate refining margins from caustic soda volatility, and accelerate ANVISA certification depth to defend position against lower-grade import substitution. CBA and Votorantim should prioritize brownfield efficiency retrofits over greenfield capacity given IBAMA licensing timelines. For New Entrants and Emerging Players: E-commerce platforms for specification-grade aluminum procurement offer a route to bypass established distributor networks and capture mid-size fabricator accounts. Target northeastern Brazil's wind corridor solar mounting systems and underdeveloped post-consumer scrap collection infrastructure as penetrable white spaces. Lead with alloy-separation technology partnerships to unlock secondary smelter feedstock quality advantages. For Investors and Strategic Acquirers: Roll-up economics work for regional extrusion houses because INMETRO certification gaps fragment competitive positioning and create consolidation value through standardization investments. Five-to-ten year viability hinges on renewable energy offtake agreements and scrap collection infrastructure scale. Watch Alcoa-Rio Tinto inert anode pilot deployment timelines as the inflection signal for carbon-intensity-based pricing premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Mining | CBA's captive reserves at Poços de Caldas anchor southeastern refining economics against northern logistics disruptions. |
| Closed-Loop Beverage Can Recycling Partnership | Novelis leverages São Paulo collection density to secure UBC feedstock for certified low-carbon flat-rolled output. |
| INMETRO Alloy Grade Harmonization Investment | Extrusion houses in Minas Gerais unlock Mercosur export qualification through ASTM convergence. |
| Hydroelectric Power Purchase Agreement | Pará smelters secure renewable energy certificates that defend position against inert anode technology displacement. |
| Digital Twin Electrolysis Cell Deployment | Albras and Alcoa operations compress emissions intensity through predictive potline management. |
Research Methodology
Coverage spans Brazil's southeastern fabrication clusters and northern primary production zones, with primary inputs from each. The analysis combines interviews with electrolysis technicians, automotive tier-one procurement managers, construction specification engineers, and ANVISA regulatory affairs specialists with secondary validation. Secondary sources include IBAMA environmental licensing records, INMETRO certification databases, customs trade data for aluminum ingot and scrap flows, and SEC filings from listed producers. Bottom-up segment sizing triangulates against top-down energy consumption and bauxite production estimates.
Granularity-level modeling disaggregates volume and value across product type, end user, application, and alloy grade dimensions, with additional segmentation by state-level regulatory cluster and hydroelectric basin sourcing. CAGRs derive from trend-line extrapolation of historical production and consumption patterns, adjusted for announced capacity additions and licensing timelines. Forecast inputs include automotive lightweighting content-per-vehicle trajectories and building code specification shifts in Minas Gerais and Rio de Janeiro.
The model assumes a particular technology adoption path for inert anode smelting; alternative pathways for carbon anode continuation would alter the outlook for legacy operation competitiveness. Forecasts reflect assumptions regarding IBAMA licensing velocity, grid decarbonization commitment durability, and scrap collection infrastructure investment scale. Practitioners should monitor drought indices for Amazon basin hydroelectric reservoirs and ANVISA packaging standard revision schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Stainless Steel Foil Market
Metals
Aluminum Wire Market
Metals
Global Superconducting Wire Market
Metals
Silver Sulphate Market
Metals
United States Aluminum Extrusion Market
Metals
South America Metal Finishing Market
Metals
Cold Drawn Wire Market
Metals
Europe Aluminium Wire Rod Market
Metals
North America Aluminum Casting Market
Metals
Aluminum Flat-Rolled Products Market
Metals
Molybdenum Market
Metals
Bismuth Market
Metals
Global Copper Cathode Market
Metals
US Copper Scrap Market
Metals
HSLA Steel Plate Market
Metals
Industrial Silver Market