
 Trivalent Chromium Finishing Market | 2026-2036
Trivalent Chromium Finishing Market Size, Share, and Industry Trends Forecast 2026-2036
Trivalent Chromium Finishing Market Intelligence
The automotive parts sector's demand for functional, corrosion-resistant coatings is rebalancing the end-use mix, shifting focus from purely aesthetic applications. MacDermid Enthone leverages its comprehensive chemical portfolio to meet stringent OEM standards in the United States and Europe. Atotech sustains its market position through specialized electroplating solutions for the high-value electronics sector. Meanwhile, BASF competes on manufacturing scale and its integrated supply chain for plating solution precursors.
Trivalent chromium finishing is a surface treatment applying a chromium layer from an electrolyte where the metal is in its trivalent (+3) state. The process serves as a less toxic alternative to hexavalent chromium, delivering corrosion resistance and a decorative appearance. Decorative coatings for automotive parts represent a high-volume segment, though passivation treatments for corrosion resistance are growing faster. By technology, electroplating remains the dominant method, with immersion coating used for specific complex geometries.
Regulations such as the European Union's REACH directive and rules from the US Environmental Protection Agency (EPA) severely restrict hexavalent chromium use. This regulatory pressure, combined with China's evolving GB standards for industrial pollutants, directly mandates the shift toward trivalent alternatives. Finishers and chemical suppliers must now decide between optimizing existing trivalent chemistries for performance or investing in next-generation non-chromium alternatives.
Market Dynamics
The market's primary structural force is regulatory substitution, where mandates like the EU's REACH regulation are compelling a systemic replacement of hexavalent chromium. This pressure forces a direct technology transition across the entire finishing industry, from chemical suppliers to applicators.
Growth Catalysts
- REACH Regulation:The European Union's directive restricting hexavalent chromium is the principal driver, mandating a switch to trivalent alternatives for finishers supplying the automotive, aerospace, and consumer goods sectors.
- Automotive Sector Demand:The automotive industry's requirement for corrosion-resistant and decorative coatings on parts, especially for electric vehicles and lightweight components, creates high-volume demand for compliant finishing solutions.
- Evolving GB Standards:China's tightening environmental GB standards for industrial pollutants are pushing domestic manufacturers in electronics and hardware to adopt less toxic trivalent chromium processes to meet national compliance targets.
Market Restraints
- Technical Performance Gaps:Certain trivalent finishes exhibit lower hardness and wear resistance compared to their hexavalent counterparts, restricting their use in demanding engineering applications requiring maximum durability.
- Process Control Complexity:Trivalent plating baths are highly sensitive to contamination and require stringent control over pH and chemical concentrations, increasing operational complexity and costs for finishers.
- Substitution by Non-Chrome Alternatives:The development of advanced polymer coatings and physical vapor deposition (PVD) finishes presents a viable substitution threat, particularly in decorative applications where color and appearance are critical.
Strategic Opportunities
- High-Performance Passivates:Developing trivalent-based passivation treatments that exceed 1,000 hours of salt spray resistance for zinc and zinc-alloy substrates opens a high-margin market segment beyond decorative coatings.
- Electronics Applications:Targeting the electronics industry with specialized trivalent finishes for connectors, heat sinks, and EMI shielding components provides a path for diversification away from the automotive sector.
- Sulfate-Free Electrolytes:Formulating next-generation sulfate-free trivalent chemistries can deliver improved plating efficiency and simplified wastewater treatment, offering a clear performance advantage over established systems.
Industry Challenges
- Wastewater Treatment Investment:The presence of strong chelating agents in trivalent chromium wastewater complicates treatment and necessitates significant capital expenditure on specialized chemical or biological purification systems.
- Finish Consistency:Maintaining consistent color and brightness across large or geometrically complex parts remains a significant operational challenge, particularly for chloride-based trivalent systems used in decorative applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trivalent Chromium Finishing Market |
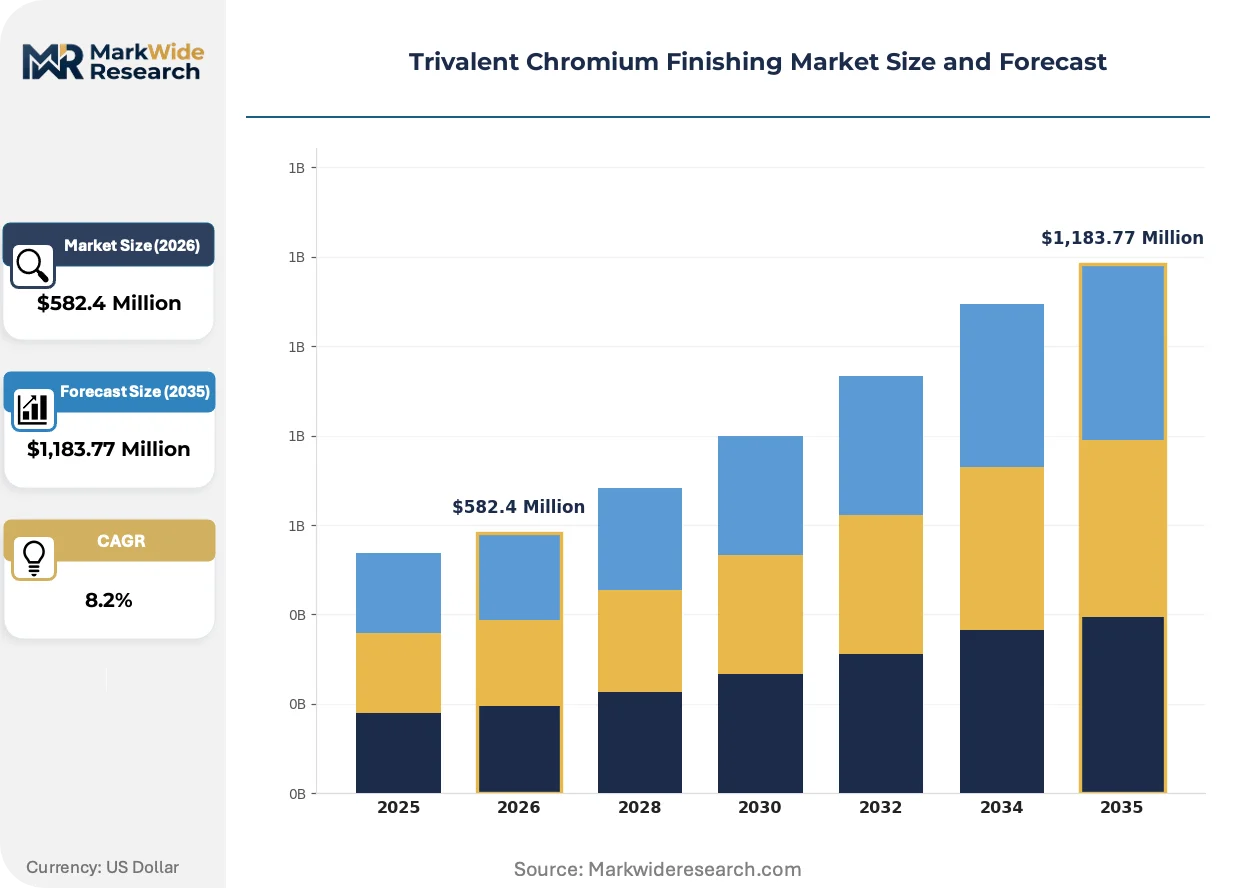
| Market Size in 2026 | $582.4 Million |
| Market Size in 2035 | $1,183.77 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decorative Coatings, Hard Coatings, Passivation Treatments, Plating Solutions End User: Aerospace, Automotive Parts, Electronics, Marine Equipment Application: Corrosion Resistance, Aesthetic Appeal, Electrical Conductivity, Surface Hardness Technology: Electroplating, Chemical Conversion, Spray Coating, Immersion Coating |
| Companies Covered | MacDermid Enthone, Atotech, Chem Processing, Inc., Kakihara Industries Co., Ltd., Ronatec C2C, Inc., Sarrel Group, Columbia Chemical, BASF, Coventya, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trivalent Chromium Finishing Market Strategic Shifts & Innovations
The market is defined by a push for performance parity with legacy hexavalent systems while simultaneously meeting stricter environmental standards. Innovation is focused on enhancing the functional properties of trivalent coatings, moving the technology beyond a simple compliance-driven alternative toward a preferred finishing choice.
New formulations of high-speed trivalent electrolytes deliver faster plating rates and improved current efficiency. Automotive and plumbing fixture manufacturers are adopting these systems to maintain high production throughput. This technology is expanding into high-volume plating-on-plastic applications, directly challenging the cycle times previously achievable only with hexavalent chromium processes.
The European Union's REACH regulation continues to set the global compliance agenda, with its established sunset dates for hexavalent chromium use acting as a non-negotiable deadline. This regulatory finality eliminates incremental adoption strategies, forcing a complete and rapid transition across entire supply chains. The automotive component sector in Germany and Eastern Europe is most acutely affected, driving large-scale requalification of parts and processes.
A notable behavioral shift is occurring in how end-users specify coatings, moving from chemistry-based requests to performance-based requirements. Original equipment manufacturers are increasingly defining needs by hours of neutral salt spray (NSS) survival or specific abrasion resistance values, rather than simply requesting a "trivalent" finish. This trend is most pronounced within the German automotive supply chain and among US defense contractors.
Trivalent Chromium Finishing Market Segmentation
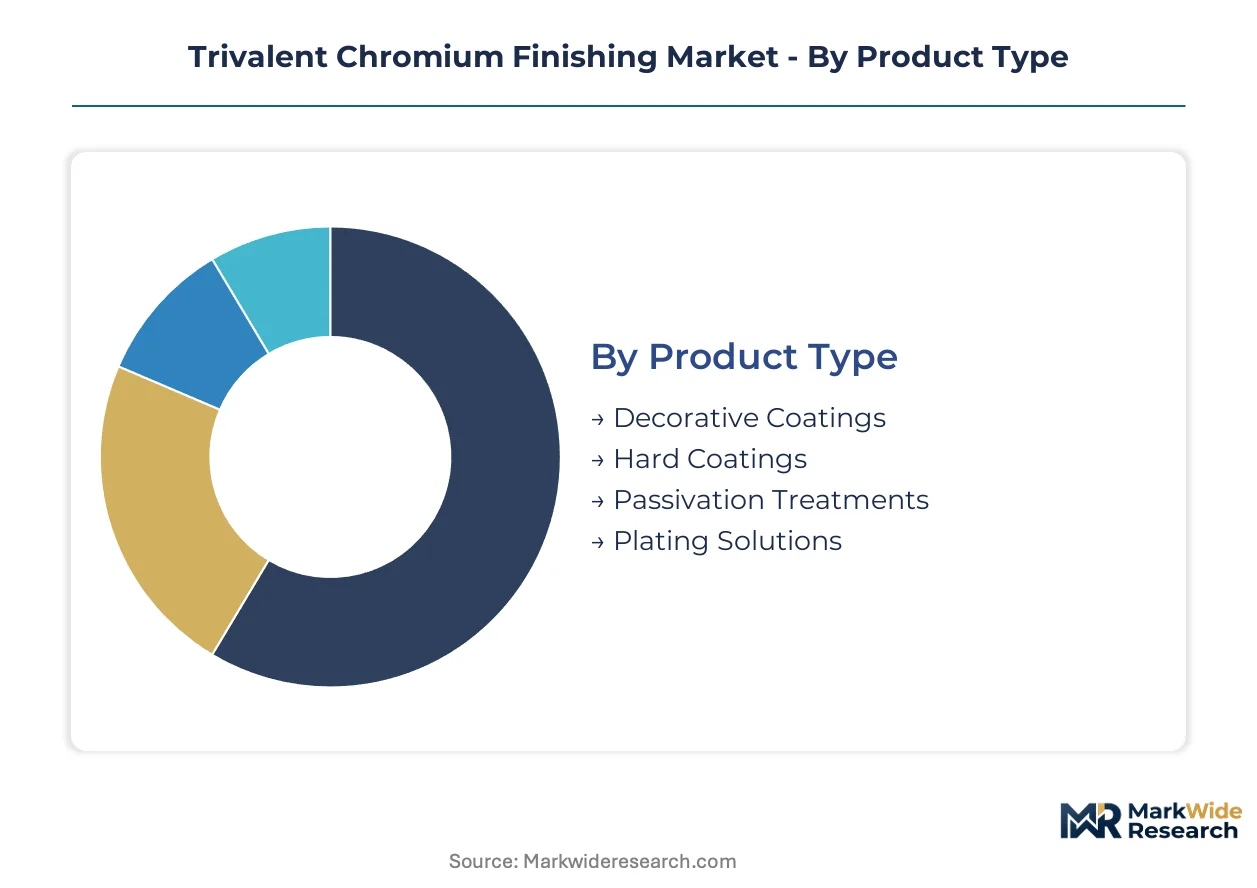
The trivalent chromium finishing market's segmentation highlights the diverse functional requirements and regulatory pressures driving material selection across various industries. Understanding these distinct segments is crucial for chemical suppliers and applicators to tailor solutions and navigate specific compliance pathways.
Product Type:
Segments within product type often require distinct regulatory certifications, influencing market entry and operational costs for finishers.
- Decorative Coatings:This finish provides visual appeal and corrosion protection for consumer goods and automotive trim, with demand concentrating in German automotive component manufacturing. These coatings are often subject to OEM aesthetic and durability standards.
- Hard Coatings:These trivalent chromium layers offer enhanced wear resistance and durability, finding niche applications in demanding engineering components where performance is critical.
- Passivation Treatments:These treatments enhance corrosion resistance for zinc and zinc-alloy substrates, gaining traction in US defense applications and general industrial hardware. The demand for extended salt spray resistance drives product innovation.
- Plating Solutions:This segment includes the specialized chemical formulations and electrolytes essential for the trivalent chromium deposition process, supplied to finishing shops globally.
Decorative Coatings sits at the top of the volume ranking, with Passivation Treatments climbing the fastest.
End User:
End-user segments define specific performance requirements for trivalent chromium finishes, driving material and process innovation across the supply chain.
- Aerospace:This sector demands high-performance, lightweight coatings for critical components, prioritizing corrosion resistance and fatigue life in aircraft structures.
- Automotive Parts:The automotive industry requires corrosion-resistant and decorative finishes for interior and exterior components, particularly for electric vehicles in China and Europe. OEM specifications for durability and appearance are stringent.
- Electronics:This segment utilizes trivalent chromium for connectors, heat sinks, and EMI shielding, valuing electrical conductivity and consistent performance in miniaturized devices. Specialized solutions are critical for high-value applications.
- Marine Equipment:Components exposed to harsh saltwater environments require superior corrosion protection, making trivalent chromium a viable alternative for fittings and hardware.
Automotive Parts drives the largest share of demand, while Electronics presents significant future growth.
Application:
The application landscape for trivalent chromium finishing reflects diverse functional needs, from basic protection to highly specialized surface properties.
- Corrosion Resistance:This application focuses on protecting metal substrates from environmental degradation, a primary driver for industrial and automotive parts in regions with high humidity or road salt use. Regulatory pressure against hexavalent chromium intensifies this demand.
- Aesthetic Appeal:Decorative applications prioritize visual qualities such as brightness and color consistency, critical for consumer products and automotive trim in markets like Germany. These finishes often mimic traditional hexavalent chromium looks.
- Electrical Conductivity:Trivalent chromium can provide a conductive surface for electronic components, ensuring reliable signal transmission and grounding in complex systems.
- Surface Hardness:This application aims to enhance the scratch and wear resistance of components, extending product lifespan in demanding mechanical environments.
Corrosion Resistance remains the most widespread application, though Aesthetic Appeal demonstrates robust expansion.
Technology:
Technology choices in trivalent chromium finishing dictate process efficiency and suitability for complex component geometries, impacting production throughput.
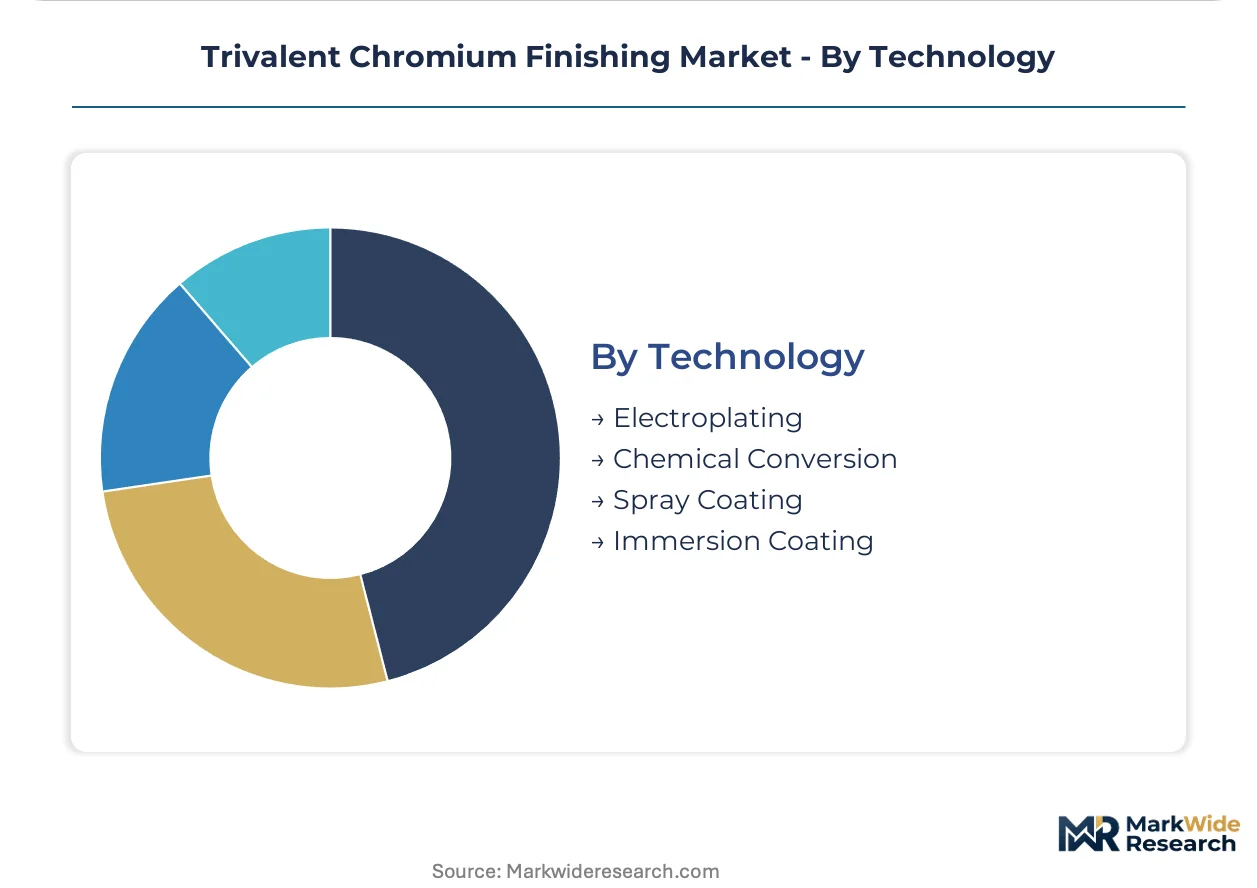
- Electroplating:This remains the dominant method, employing an electric current to deposit a trivalent chromium layer from an electrolyte onto a substrate. High-speed formulations are enhancing throughput for automotive and plumbing fixture manufacturers.
- Chemical Conversion:These processes form a protective layer through a chemical reaction with the substrate, often used as a pre-treatment or for specialized corrosion protection.
- Spray Coating:This technique applies trivalent chromium solutions as a fine mist, suitable for large or irregularly shaped parts that are difficult to immerse.
- Immersion Coating:This method involves submerging parts into a trivalent chromium bath, effective for achieving uniform coverage on complex geometries. It offers a simpler setup for specific applications.
Electroplating holds the largest market share, with Immersion Coating carving out niche but critical roles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage significantly influences the global trivalent chromium finishing market, as stringent environmental mandates compel a shift from hexavalent processes. This regulatory pressure creates a cost-of-compliance gap, impacting manufacturing locations and supply chain decisions. Finishers strategically evaluate regions based on the stringency and enforcement of environmental regulations.
Germany
Demand for aesthetic and corrosion-resistant coatings on automotive parts drives market expansion in Germany. The European Union's REACH regulation mandates the transition away from hexavalent chromium, directly impacting automotive component suppliers. Manufacturing hubs in Bavaria and North Rhine-Westphalia are actively requalifying processes for trivalent alternatives to meet OEM standards.
China
China's robust automotive and electronics sectors generate substantial demand for trivalent chromium finishes. Evolving GB standards for industrial pollutants compel domestic manufacturers to adopt less toxic finishing processes. Industrial clusters in the Yangtze River Delta are rapidly integrating trivalent solutions for both decorative and functional applications.
United States
The United States aerospace and defense sectors require high-performance, corrosion-resistant trivalent coatings for critical components. The US Environmental Protection Agency (EPA) regulations restrict hexavalent chromium, pushing industries toward safer alternatives. Manufacturers in the Midwest and Southeast are investing in new trivalent lines to comply with federal mandates and supply government contractors.
Japan
Japanese electronics and automotive industries seek specialized trivalent finishes for miniaturized devices and high-durability components. Japan's environmental regulations, while distinct from REACH, encourage the adoption of more sustainable industrial practices. Production facilities in the Kanto and Chubu regions are innovating with advanced trivalent electroplating solutions for precision applications.
France
French automotive and consumer goods sectors contribute to stable demand for decorative and protective trivalent chromium finishes. Compliance with the EU's REACH directive ensures a consistent shift towards trivalent chemistries across French industries. Manufacturers in the Auvergne-Rhône-Alpes region are adapting their finishing lines to meet both aesthetic and performance specifications.
Trivalent Chromium Finishing Market Key Industry Players
Portfolio diversification dominates the current competitive landscape, driven by the need for comprehensive solutions across diverse end-use sectors. The market exhibits a tiered structure, with large chemical suppliers competing alongside specialized electroplating solution providers and regional applicators. Strategic partnerships and targeted capacity expansion are common competitive moves, aimed at capturing market share in rapidly transitioning industries. Many players focus on enhancing functional properties of trivalent coatings to achieve performance parity with legacy systems.
Within the comprehensive chemical portfolio tier, MacDermid Enthone leverages its extensive offerings to meet stringent OEM standards in key automotive markets across Europe and the United States. Atotech, a prominent supplier, exemplifies specialization through its advanced electroplating solutions tailored for the high-value electronics sector, providing critical performance in miniaturized devices. BASF, a large chemical company, occupies a significant position through its manufacturing scale and integrated supply chain for plating solution precursors, ensuring consistent material availability. These players anchor different segments of the market by offering distinct value propositions and addressing diverse customer needs.
| Leading Market Players |
|---|
| MacDermid Enthone |
| Atotech |
| Chem Processing, Inc. |
| Kakihara Industries Co., Ltd. |
| Ronatec C2C, Inc. |
| Sarrel Group |
| Columbia Chemical |
| BASF |
| Coventya |
| Others |
Cost & Logistics Intelligence
The performance gap between standard trivalent finishes and high-performance passivation treatments drives a significant tier divergence, manifesting in both pricing structures and specialized supply chain configurations for advanced chemistries.
Pricing Analysis
Direct-to-OEM discounts are common for large automotive suppliers, reflecting long-term contract-based relationships. Pricing stratifies across premium, standard, and economy tiers based on certification level for OEM standards and achieved salt spray resistance. Cost compression in commodity decorative applications is intensifying due to competition among finishers. Automotive OEMs exhibit lower price sensitivity for mission-critical, high-performance parts, while consumer goods applications remain highly price-sensitive.
Supply Chain Analysis
Trivalent chromium chemical supply relies on specialized chemical producers for core formulations and proprietary additives. Geographic supply concentration for advanced chemistries exists in Germany and Japan, driven by strong R&D capabilities. Key raw material dependencies include trivalent chromium salts and complex chelating agents. Regulatory restriction on specific chemical inputs presents a structural supply chain risk. Distribution runs through a hybrid model, with direct sales to large finishing operations and specialized distributors serving smaller shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage play, as the cost of compliance with REACH regulations in Europe creates an opportunity compared to regions with less stringent hexavalent chromium restrictions.
For Market Incumbents: Acquire advanced R&D capabilities in next-generation non-chromium alternatives. Invest in high-performance trivalent passivates to counter the threat of substitution by other coating technologies. Expand manufacturing capacity in compliance-driven regions like Germany to leverage regulatory shifts. Focus R&D efforts on sulfate-free electrolytes to reduce wastewater treatment costs.
For New Entrants and Emerging Players: The significant price differential between specialized high-performance trivalent finishes and commodity decorative coatings offers a penetration point. Target electronics applications and high-performance passivates for US defense contractors as white-space opportunities. Smaller finishers seeking cost-effective, compliant solutions represent a penetrable segment. A go-to-market angle focusing on simplified process control and reduced wastewater treatment costs will resonate.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory mandates force rapid technology transitions across supply chains. The market shows strong long-term viability driven by irreversible regulatory shifts and sustained demand for compliant functional coatings. Specialized electroplating solution providers with proprietary high-performance trivalent chemistries represent an attractive acquisition target archetype. The rate of OEM requalification for non-chromium alternatives serves as a signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Germany | Supports automotive component suppliers transitioning to REACH-compliant processes. |
| R&D into Sulfate-Free Chemistries | Delivers improved plating efficiency and simplified wastewater treatment for finishers. |
| Strategic Partnership with Electronics OEM | Secures high-value contracts for miniaturized devices in the electronics sector. |
| Acquisition of Specialized Applicator | Extends market reach and operational control in complex immersion coating applications. |
| Green Manufacturing Transition | Addresses evolving GB standards for industrial pollutants in China. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary interviews with industry stakeholders and secondary validation. Interviews included chemical R&D directors, automotive OEM procurement leads, finishing shop owners, and environmental compliance officers. Secondary data sources encompassed EU REACH documentation, US EPA reports, China GB standards, and company annual reports, triangulated through bottom-up and top-down approaches.
The segment-weighting approach informed the analytical framework across the analysis window. Segmentation dimensions modeled included product type, end-user, application, technology, and regional regulatory stringency. Compound annual growth rates were derived through a proprietary algorithm considering historical data and future projections. Hexavalent chromium sunset dates and electric vehicle production forecasts served as key industry-specific forecast inputs.
Caveats apply where unforeseen technological breakthroughs in non-chromium alternatives or significant shifts in global trade policies could materially shift the outlook. Forecasts reflect assumptions regarding regulatory enforcement and market adoption rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Copper Sputtering Target Market
Metals
7075 T6 Aluminum Market
Metals
Palladium Market
Metals
Rolled Steel Motor Market
Metals
Ferro Aluminum Market
Metals
Platinum Group Metals Market
Metals
Steel Drums Market
Metals
Global Welding Powder Market
Metals
Aluminum Ingots Market
Metals
Global Brass Rods Market
Metals
Lithium Tungstate Market
Metals
Steel Wire Market
Metals
Asia-Pacific Metal Finishing Market
Metals
Aluminum Smelting Market
Metals
Europe Aluminium Wire Rod Market
Metals
Merchant Bar Quality (MBQ) Steel Market