
 Amorphous Metal Cores Market | 2026-2036
Amorphous Metal Cores Market Size, Share, and Industry Trends Forecast 2026-2036
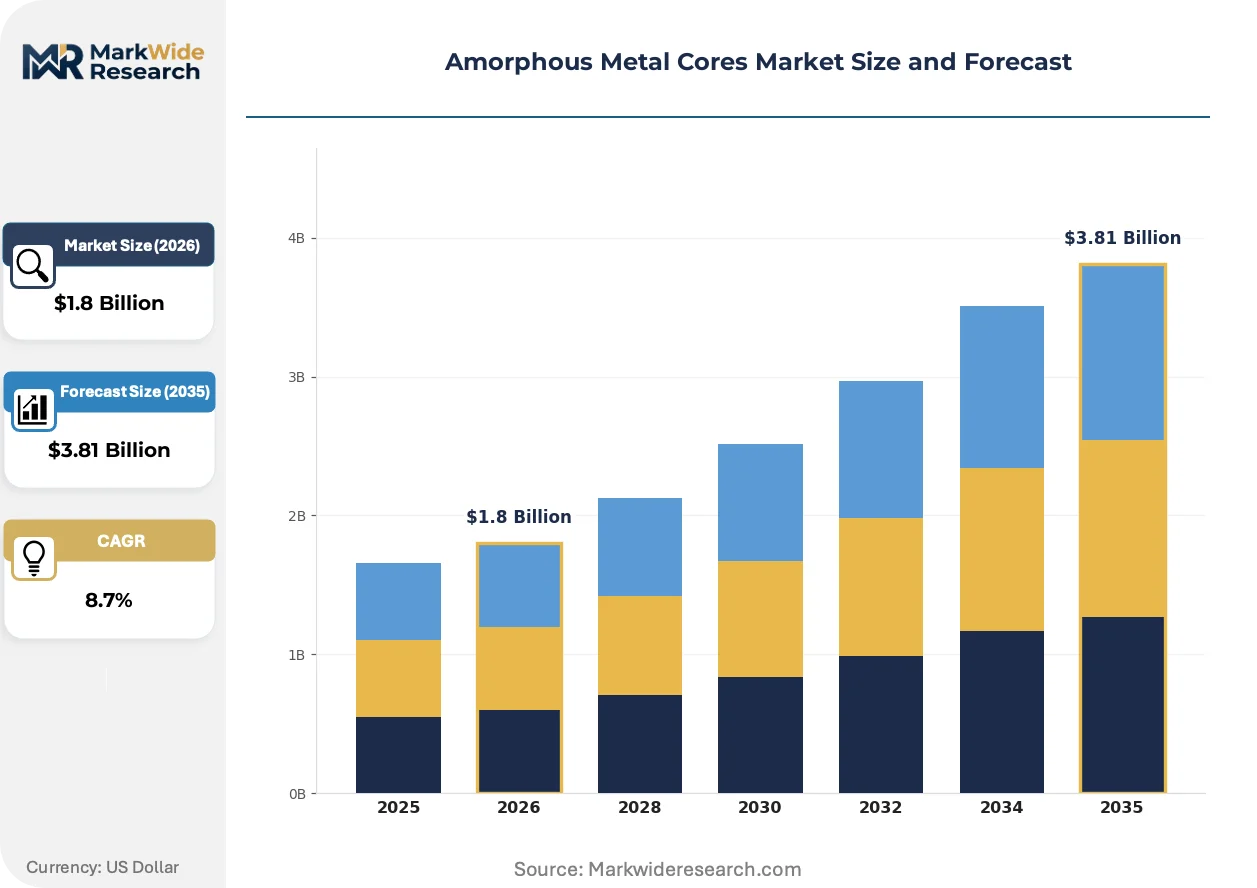
Amorphous Metal Cores Market Outlook
Asset-light leasing models for distribution transformers are reconfiguring competitive entry barriers, allowing smaller operators to access amorphous core technology without heavy capital deployment. China Amorphous Technology Co., Ltd. leverages integrated melt-spinning capabilities to dominate domestic transformer core supply. VACUUMSCHMELZE GmbH & Co. KG anchors premium inductor applications through precision-controlled rapid solidification expertise. Hitachi, Ltd. competes across both power grid and automotive inverter segments with proprietary alloy formulations.
Amorphous metal cores consist of ferromagnetic alloys—typically iron-based with boron, silicon, or carbon additions—produced through melt spinning at cooling rates exceeding 10^6 K/s, yielding non-crystalline structures with near-zero hysteresis loss and saturation induction around 1.5-1.8 T. Their primary purpose centers on magnetic core applications where eddy current minimization drives energy efficiency, particularly in distribution transformers and high-frequency power electronics. Laminated cores occupy the mature volume tier in grid transformer replacements, while composite cores capture expanding demand in electric vehicle onboard chargers where geometric flexibility outweighs raw permeability. The automotive end user segment shows the fastest structural ascent as 800V architectures and silicon carbide inverters multiply high-frequency magnetics count per vehicle.
EPA efficiency standards for distribution transformers and the EU Ecodesign Directive's tiered loss requirements are tightening permissible core loss ceilings, directly advantaging amorphous alloys over conventional grain-oriented silicon steel. China's GB standards for transformer energy consumption, enforced by SAMR compliance testing, create parallel demand pull in the world's largest grid investment market. Stakeholders must monitor alloy feedstock cost volatility against rare earth price movements and assess captive ribbon casting capacity as a supply security determinant.
Market Dynamics
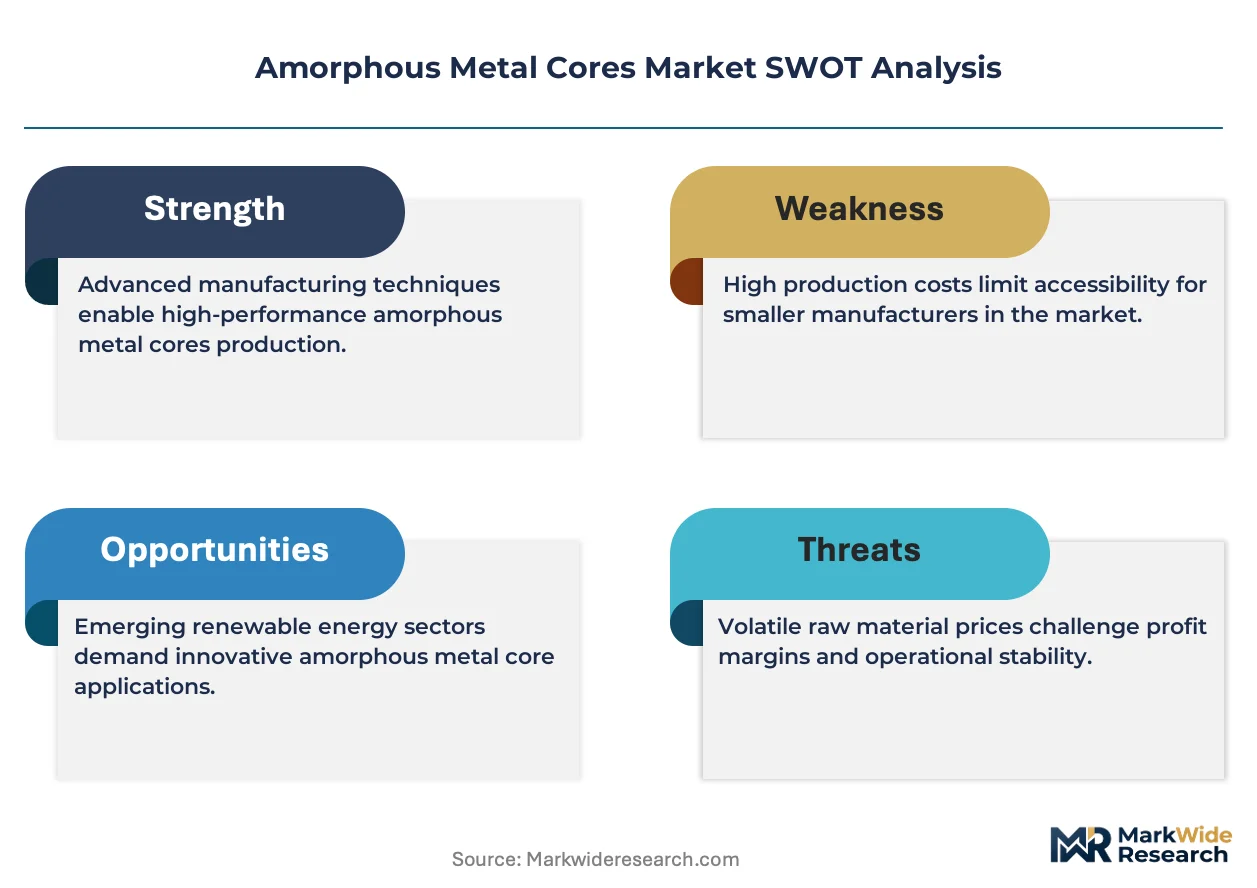
Transformer efficiency mandates under the EU Green Deal and China's GB standards are compressing permissible core loss ceilings, forcing grid operators and OEMs to requalify magnetic materials faster than conventional silicon steel supply chains can adapt.
Growth Catalysts
- EU Ecodesign Directive tiered loss requirements:The regulation mandates maximum load and no-load losses for distribution transformers, directly advantaging amorphous alloys over grain-oriented silicon steel in European grid procurement.
- 800V EV architectures:Silicon carbide inverters operating at higher switching frequencies multiply high-frequency magnetics count per vehicle, expanding addressable core volume in automotive onboard chargers.
- China's state-backed grid modernization:SAMR-enforced GB standards for transformer energy consumption create concentrated procurement pull through state grid corporations and provincial distribution network upgrades.
Market Restraints
- Boron and iron feedstock cost volatility:Amorphous alloy ribbon production depends on ferroboron pricing, which tracks rare earth market movements and creates margin pressure for non-integrated casters.
- Captive melt-spinning capacity concentration:Integrated producers with in-house rapid solidification lines control supply security, leaving merchant buyers exposed to allocation risk during demand spikes.
- Geometric inflexibility of laminated cores:Traditional amorphous transformer cores cannot match composite core form factors for toroidal or complex geometries required in compact EV power electronics.
Strategic Opportunities
- Asset-light leasing models:Transformer-as-a-service arrangements allow smaller distribution utilities to access amorphous core efficiency without capital deployment, opening municipal and cooperative utility segments.
- Composite core convergence with additive manufacturing:Powder metallurgy and binder jetting techniques enable net-shape amorphous composite cores for geometrically constrained inductor applications in aerospace and medical imaging.
- India's PLI scheme for power equipment:Production-linked incentives for domestic transformer manufacturing create localized demand pull as the country's central electricity authority tightens loss norms for distribution infrastructure.
Industry Challenges
- Rapid solidification process control expertise:Melt-spinning operations require precise cooling rate management exceeding 10^6 K/s, creating talent scarcity for thermal engineering and ribbon quality assurance functions.
- Core annealing furnace capex intensity:Field-annealing equipment for large distribution transformer cores demands significant capital outlay, constraining service provider entry and regional repair capabilities.
- Multi-standard certification timelines:Simultaneous qualification under IEEE, IEC, and GB testing protocols extends product approval cycles and complicates inventory positioning for multinational OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amorphous Metal Cores Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amorphous Steel, Amorphous Alloys, Laminated Cores, Composite Cores Application: Transformers, Inductors, Motors, Sensors End User: Power Generation, Automotive Industry, Consumer Electronics, Renewable Energy Distribution Channel: Direct Sales, Online Retail, Distributors, Manufacturers |
| Companies Covered | China Amorphous Technology Co., Ltd., Zhaojing Incorporated, Hitachi, Ltd., ENPAY, Proterial, Ltd., Advanced Technology & Materials Co., Ltd., VACUUMSCHMELZE GmbH & Co. KG, Usha Amorphous Metals Ltd., Qingdao Yunlu New Energy Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amorphous Metal Cores Market Strategic Shifts
Computational materials design and in-situ process monitoring are compressing alloy development cycles and enabling real-time quality control that was previously impossible in rapid solidification manufacturing.
Machine learning-driven alloy composition optimization is virtualizing traditional metallurgical trial-and-error protocols. Materials informatics platforms trained on melt-spinning process data predict glass-forming ability and magnetic properties before physical casting. Tier-1 automotive suppliers and grid transformer OEMs are adopting these tools to compress qualification timelines from years to months. This capability is virtualizing the competitive moat historically held by producers with decades of empirical alloy libraries.
EPA efficiency standards for distribution transformers are tightening no-load loss limits through tiered implementation schedules. The rulemaking forces utilities to re-evaluate total cost-of-ownership calculations and accelerates replacement cycles for aging silicon steel assets. Distribution cooperatives in the US Midwest and Southeast are responding with pilot procurement programs specifying amorphous cores for new substation installations.
Leasing structures for distribution transformers are displacing traditional equipment purchase models among capital-constrained utilities. Municipal power authorities and rural electric cooperatives now contract for transformer performance rather than hardware ownership, transferring core technology risk to specialized asset operators. This pattern is most visible in Germany's municipal utility sector and among US cooperative utilities navigating IRA-funded grid hardening programs.
Amorphous Metal Cores Market Segmentation
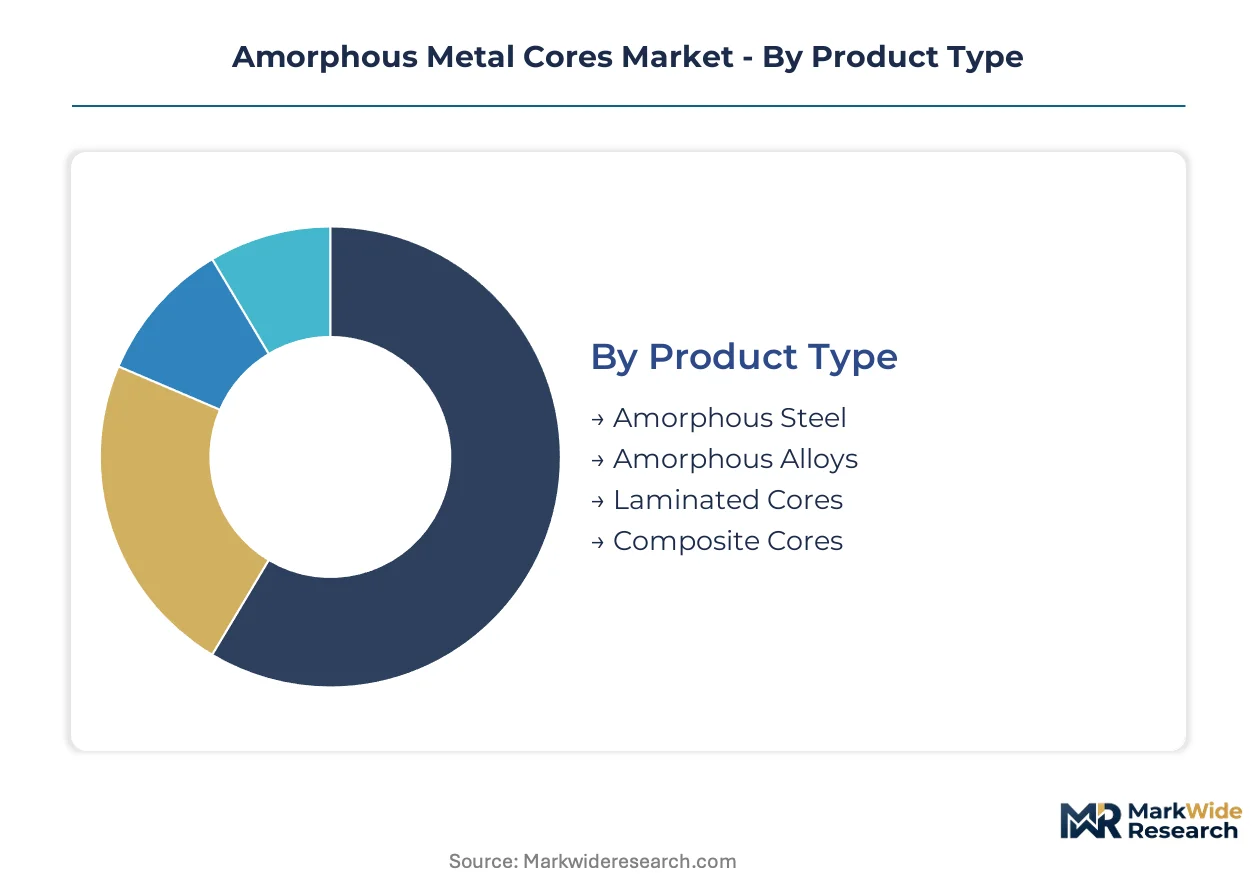
Amorphous metal cores serve divergent magnetic applications where material selection hinges on cooling rate tolerance, geometric constraints, and frequency operating windows. Segmentation reveals how laminated architectures dominate grid infrastructure while composite formulations capture automotive power electronics requiring toroidal flexibility.
Product Type:
Cost tier stratification separates commodity ribbon supply from premium alloy formulations commanding precision rapid solidification capabilities.
- Laminated Cores:Layered ribbon constructions stack melt-spun amorphous strips with interlaminar insulation, achieving eddy current suppression in distribution transformers. Demand concentrates in China's state grid procurement and German municipal utilities under EU Ecodesign loss ceilings, with procurement volume tied to transformer replacement cycles mandated by efficiency regulations.
- Composite Cores:Powder metallurgy and binder jetting techniques consolidate amorphous particulate into net-shape geometries, enabling toroidal and complex inductor forms. Automotive onboard chargers for 800V silicon carbide inverters represent the steepest expansion trajectory, where geometric flexibility outweighs raw permeability specifications.
- Amorphous Steel:Iron-boron-silicon alloys produced through single-wheel melt spinning deliver saturation induction around 1.5 T for standard transformer duty.
- Amorphous Alloys:Cobalt-based and specialized iron-based formulations target high-frequency inductor applications requiring near-zero magnetostriction.
Laminated cores hold installed capacity. Composite cores are rotating up the share rankings.
Application:
Application segmentation tracks frequency operating regimes, with grid-scale magnetics at 50-60 Hz diverging sharply from power electronics switching above 20 kHz.
- Transformers:Distribution and power transformer cores exploit near-zero hysteresis loss in amorphous alloys to meet EPA and EU Ecodesign no-load loss mandates. Procurement concentrates in China's GB standard compliance programs and US cooperative utility pilot installations funded by IRA grid hardening allocations.
- Inductors:High-frequency magnetics for EV onboard chargers, DC-DC converters, and renewable energy inverters demand composite core geometries. Silicon carbide inverter adoption at 800V architectures multiplies inductor count per vehicle, with automotive OEMs specifying amorphous solutions for switching frequencies exceeding 100 kHz.
- Motors:High-efficiency motor stator laminations employ amorphous ribbon where loss reduction justifies material cost premium over grain-oriented silicon steel.
- Sensors:Fluxgate and current sensing applications leverage amorphous alloy magnetostrictive properties for precision measurement in industrial automation and power monitoring.
Transformers anchor current revenue. Inductors are climbing the fastest.
End User:
End user segmentation reflects divergent procurement authority structures, from centralized state grid corporations to fragmented automotive tier-1 supply chains.
- Power Generation:Utility-scale transformer procurement operates through centralized tenders with multi-year qualification cycles, favoring laminated core suppliers with captive melt-spinning capacity and established IEEE/IEC certification libraries.
- Automotive Industry:EV platform electrification multiplies high-frequency magnetics demand per vehicle, with tier-1 suppliers qualifying composite cores for onboard chargers and DC-DC converters under automotive IATF quality protocols.
- Consumer Electronics:Miniaturized inductors for adapters and power supplies employ amorphous alloy powder cores where efficiency regulations drive material substitution.
- Renewable Energy:Solar and wind inverter manufacturers specify amorphous cores for DC-link inductors and filtering applications, with procurement scaling alongside grid-tied storage deployment.
Power generation commands procurement volume concentration. Automotive is gaining share fastest.
Distribution Channel:
Channel structure varies by customer scale and technical specification complexity, with direct engagement dominating large transformer OEMs and distributor networks serving fragmented industrial accounts.
- Direct Sales:Integrated producers with captive ribbon casting and core finishing capabilities contract directly with grid transformer OEMs and automotive tier-1 suppliers, capturing margin through specification engineering and field annealing service bundling.
- Distributors:Regional industrial distributors stock standard amorphous core laminations and toroidal forms for motor repair shops, small transformer manufacturers, and maintenance procurement.
- Online Retail:E-commerce channels capture prototype and R&D volume for universities, startups, and design houses evaluating amorphous materials against conventional magnetic solutions.
- Manufacturers:Captive distribution through transformer OEMs with backward integration into core production serves internal demand and spot market allocation.
Direct sales holds contractual lock-in. Distributors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export capacity for amorphous metal ribbon concentrates in East Asian melt-spinning operations, while import dependency shapes procurement strategies in Europe and North America. Trade flows reflect captive production advantages and regulatory-driven demand asymmetries across major grid investment markets.
China
State Grid Corporation procurement and provincial distribution network upgrades drive concentrated demand pull under SAMR-enforced GB standards for transformer energy consumption. Domestic melt-spinning capacity expansion reduces import exposure for core manufacturing. Qingdao and Zhengzhou host integrated ribbon casting and core finishing clusters serving both domestic grid tenders and export markets.
United States
EPA efficiency standards for distribution transformers tighten no-load loss limits, accelerating cooperative utility pilot programs specifying amorphous cores. IRA-funded grid hardening allocations redirect capital toward high-efficiency transformer procurement. Midwest and Southeast distribution cooperatives lead adoption, with field annealing service networks developing around regional transformer OEMs.
Germany
EU Ecodesign Directive tiered loss requirements force municipal utilities to requalify magnetic materials faster than silicon steel supply chains adapt. Transformer-as-a-service leasing models proliferate among capital-constrained Stadtwerke. Bavaria and North Rhine-Westphalia concentrate transformer manufacturing and core annealing infrastructure.
India
Central Electricity Authority loss norm tightening and PLI scheme incentives for domestic power equipment manufacturing create localized demand pull. State electricity boards in Maharashtra and Gujarat issue tenders specifying amorphous core transformers for urban distribution upgrades. Domestic ribbon production remains limited, sustaining import dependency from East Asian suppliers.
Japan
METI efficiency guidelines and utility decarbonization targets shape procurement specifications for distribution infrastructure. Automotive tier-1 suppliers qualify amorphous composite cores for 800V EV onboard chargers under domestic IATF protocols. Chubu and Kansai industrial corridors concentrate precision inductor manufacturing for export-oriented power electronics.
Amorphous Metal Cores Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in ribbon supply and core finishing. Market structure exhibits tiered concentration, with integrated producers controlling melt-spinning capacity and merchant buyers facing allocation risk during demand spikes. Three archetypes dominate: captive ribbon casters with backward integration into alloy feedstock, transformer OEMs with in-house core production, and specialized inductor suppliers serving automotive power electronics. Competitive moves center on capacity expansion in rapid solidification lines and strategic partnerships for field annealing service networks.
Within the integrated production tier, China Amorphous Technology Co., Ltd. and VACUUMSCHMELZE GmbH & Co. KG exemplify divergent geographic and application positioning. Hitachi, Ltd. occupies a position spanning both grid infrastructure and automotive electrification segments. These three entities represent the spectrum from domestic market concentration to premium inductor specialization and diversified end-use coverage.
| Leading Market Players |
|---|
| China Amorphous Technology Co., Ltd. |
| Zhaojing Incorporated |
| Hitachi, Ltd. |
| ENPAY |
| Proterial, Ltd. |
| Advanced Technology & Materials Co., Ltd. |
| VACUUMSCHMELZE GmbH & Co. KG |
| Usha Amorphous Metals Ltd. |
| Qingdao Yunlu New Energy Technology Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Qingdao and Zhengzhou ribbon casting clusters concentrate melt-spinning capacity under state-backed grid modernization programs, concentrating pricing power among integrated producers with captive ferroboron supply while exposing merchant buyers to allocation risk during demand spikes.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with volume-scale and certification-grade differentiation. Premium IEC/GB dual-certified ribbon commands substantial markups over standard transformer-grade supply. Cost compression in standard grades is intensifying because ferroboron feedstock tracks rare earth volatility. Municipal utilities and cooperative grid operators exhibit highest price sensitivity, while automotive tier-1 suppliers prioritize magnetic performance over unit economics.
Supply Chain Analysis
Export-control regimes on rapid solidification equipment limit technology transfer to emerging production markets. Supply concentrates in China, Germany, and Japan, with melt-spun ribbon drawing from ferroboron, high-purity iron, and cobalt feedstocks. Single-source vulnerability in specialized annealing furnace equipment creates chokepoint risk. Distribution runs through direct sales contracts with transformer OEMs and automotive tier-1 suppliers, supplemented by regional industrial distributors for maintenance procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market faces substitution pressure from nanocrystalline alloy cores targeting high-frequency inductor applications, forcing incumbents to defend laminated core positioning through efficiency certification and captive capacity.
For Market Incumbents: Harden competitive positioning by securing captive melt-spinning capacity in Qingdao or Zhengzhou clusters and accelerating IEEE/IEC/GB multi-standard certification libraries. Defend against nanocrystalline substitution by embedding field-annealing service networks with municipal utility customers, transferring technology risk through performance-based contracting. For New Entrants and Emerging Players: India's PLI scheme for power equipment and state electricity board tenders in Maharashtra represent the most penetrable entry point for merchant ribbon supply. Target composite core geometries for 800V EV onboard chargers where geometric flexibility requirements exceed incumbent laminated core capabilities. Pursue qualification partnerships with automotive tier-1 suppliers under IATF protocols. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated producers with backward integration into alloy feedstock and rapid solidification equipment. Long-term viability hinges on exposure to grid efficiency mandates rather than commodity transformer replacement cycles. Monitor SAMR enforcement intensity and GB standard revision timing as inflection indicators for China demand pull.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Melt-Spinning Capacity Expansion | Qingdao and Zhengzhou clusters reduce ferroboron cost exposure and secure allocation priority during demand spikes. |
| Multi-Standard Certification Investment | Simultaneous IEEE, IEC, and GB qualification compresses approval cycles for multinational OEM procurement. |
| Field-Annealing Service Network Buildout | Performance-based contracting with municipal utilities transfers core technology risk from capital-constrained grid operators. |
| Composite Core Additive Manufacturing Partnership | Binder jetting techniques enable net-shape geometries for toroidal inductors in 800V EV architectures. |
| Transformer-as-a-Service Leasing Model | Asset-light arrangements open cooperative utility segments without heavy capital deployment requirements. |
Study Parameters
Desk research of customs trade data, SAMR compliance filings, and IEEE/IEC certification databases preceded structured interviews with transformer OEM procurement directors, automotive tier-1 supplier quality engineers, melt-spinning plant managers, and municipal utility planning officers. Primary intelligence combined with secondary validation through SEC 10-K disclosures, State Grid Corporation tender announcements, and EU Ecodesign Directive implementation reports. Bottom-up ribbon production estimates and top-down grid investment forecasts underwent triangulation.
Assumptions held fixed include continued EPA and EU Ecodesign tiered loss requirement enforcement, sustained China GB standard compliance programs, and stable 800V EV architecture penetration rates. Modeled segmentation spans product type (laminated versus composite), application frequency regime (50-60 Hz grid versus 20-100 kHz power electronics), and end-user procurement structure (centralized state tenders versus fragmented automotive supply chains). CAGRs derived from regression analysis of historical transformer replacement cycles and projected EV platform electrification timelines.
Practitioners should monitor ferroboron price volatility, SAMR enforcement intensity, and nanocrystalline alloy qualification progress for early signals. Material shifts in EU Ecodesign implementation schedules or China dual carbon goal acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Europe Metal Service Centers Market
Metals
Global Flat Carbon Steel Market
Metals
High Purity Tungsten Market
Metals
Metallurgical Silicon Market
Metals
Metal Forging Parts Market
Metals
Ferro Vanadium Market
Metals
Global Metal and Metal Manufactured Products Market
Metals
Aluminum Tubes Market
Metals
Finished Steel Products Market
Metals
High Purity Pig Iron Market
Metals
Osmium Market
Metals
United States Metal Casting Market
Metals
Wear Steel Plate Market
Metals
Galvanizing Market
Metals
HSLA Steel Plate Market
Metals
Shipbuilding Steel Plate Market