
 South Korea Engineering Plastics Market | 2026-2036
South Korea Engineering Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Engineering Plastics Market Insights
Aftermarket recycling and compounding services is reconfiguring margin distribution across the South Korea engineering plastics value chain. SK Chemicals leverages its integrated PET and copolyester operations to secure feedstock cost advantages. Korea Engineering Plastics anchors domestic nylon supply for automotive Tier-1 suppliers. LG Chem sustains technology leadership through proprietary polycarbonate optical-grade formulations.
South Korea engineering plastics comprise thermoplastic polymers engineered to withstand mechanical stress, thermal loads, and chemical exposure beyond commodity plastics, typically exhibiting tensile strengths above 40 MPa and continuous service temperatures exceeding 100°C. These materials serve critical load-bearing, insulating, and dimensional-stability functions across precision manufacturing sectors. Polycarbonate dominates optical and electronic housing applications due to its transparency and impact resistance. Nylon captures expanding share in under-hood automotive components where heat-aging performance matters. Acrylonitrile Butadiene Styrene retains cost-competitive positioning in consumer electronics enclosures despite pressure from specialized alloys.
MFDS regulates medical-device-grade polymer biocompatibility, while K-REACH mandates registration and hazard assessment for chemical substances manufactured or imported above one ton annually. The Korea Automotive Testing and Research Institute enforces crashworthiness and flammability standards that directly specify engineering plastic grades for interior and structural vehicle applications. Stakeholders must monitor evolving EU-REACH equivalence agreements and carbon-border adjustment mechanisms that threaten export competitiveness for Korean compounders serving European automotive OEMs.
Market Dynamics
Automotive electrification is compressing material qualification cycles while K-REACH chemical safety protocols force compounders to revalidate entire product portfolios simultaneously. This dual pressure is restructuring competitive advantage around regulatory anticipation and formulation agility rather than scale economics alone.
Growth Catalysts
- Battery enclosure thermal management:Electric vehicle OEMs specify flame-retardant polycarbonate blends for module housings. MFDS medical-grade certification opens implantable device polymer demand.
- Seoul-Incheon corridor concentration:Precision electronics manufacturers cluster within 50 kilometers of compounder technical service centers. Just-in-time color-matching capabilities reduce inventory carrying costs for consumer electronics brands.
- K-REACH pre-registration incentives:Early chemical substance filings secure market access ahead of compliance deadlines. Domestic compounders leverage registration data to accelerate customer qualification timelines.
Market Restraints
- Caprolactam feedstock volatility:Nylon 6 production costs fluctuate with benzene derivative pricing. Korean compounders lack backward integration into basic petrochemicals.
- Optical-grade polycarbonate technical barriers:Birefringence control and yellowing resistance specifications limit qualified suppliers. Japanese and German material producers retain specification authority.
- MFDS biocompatibility testing backlog:Medical-device polymer approvals face 14-18 month evaluation queues. Extended timelines compress product launch windows for Korean device exporters.
Strategic Opportunities
- Busan-Ulsan recycling infrastructure:Post-industrial scrap collection networks enable closed-loop compounding. Chemical recycling investments convert mixed polymer waste to virgin-equivalent feedstock.
- 5G base station housing specifications:Dielectric constant and dimensional stability requirements favor specialized PBT and PPS formulations. Telecommunications equipment makers qualify Korean compounders for Asian supply contracts.
- Carbon-border adjustment preparation:Life-cycle assessment documentation positions domestic producers for EU automotive export compliance. Scope 3 emissions tracking becomes a contract prerequisite.
Industry Challenges
- Colorimetric formulation expertise scarcity:Masterbatch compounding requires spectral analysis capabilities and pigment chemistry knowledge. Technical training programs lag industry expansion.
- Multi-standard certification complexity:Automotive Tier-1 suppliers demand simultaneous UL, KATRI, and OEM-specific validations. Parallel testing protocols strain laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Engineering Plastics Market |
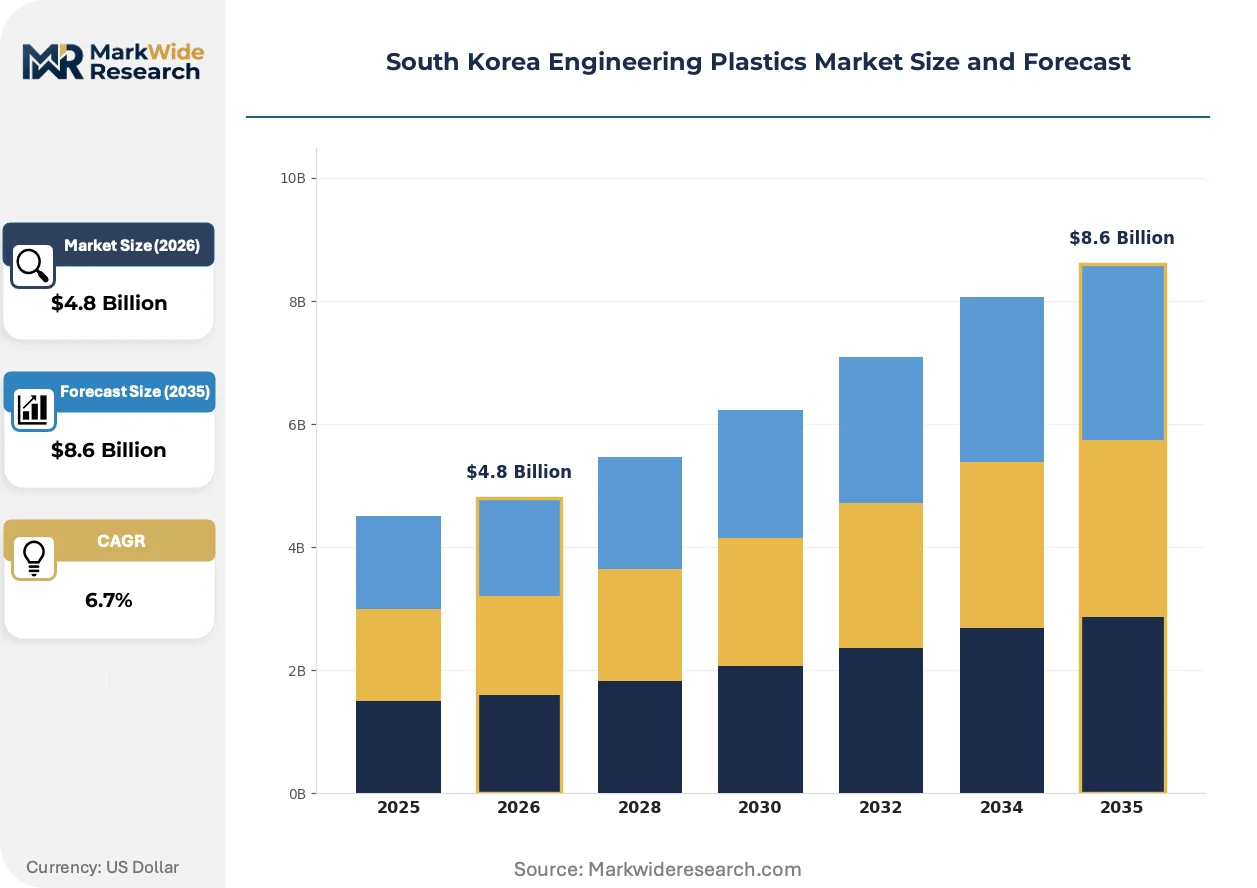
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Nylon, Polybutylene Terephthalate, Acrylonitrile Butadiene Styrene End User: Automotive, Consumer Electronics, Aerospace, Medical Devices Application: Automotive Parts, Electrical Components, Structural Applications, 3D Printing Form: Sheets, Rods, Granules, Films |
| Companies Covered | SK Chemicals, Korea Engineering Plastics, LG Chem, Samyang Corporation, INEOS, Kumho Petrochemical, Kolon Industries, LX MMA, Lotte Chemical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Engineering Plastics Market Trends and Innovations
Material substitution patterns are accelerating as performance specifications tighten and sustainability metrics enter procurement scorecards. Korean compounders invest in characterization laboratories to compress customer qualification cycles.
High-heat polyamide formulations are migrating from conventional metal replacement in internal combustion engine bays to electric motor housing and inverter applications. Battery system integrators specify these materials for thermal runaway containment. The shift is compressing demand for legacy glass-filled nylons optimized for fluid-contact resistance.
K-REACH substance evaluation deadlines are forcing compounders to reformulate legacy additive packages. Hazardous substance restrictions eliminate certain flame retardants and plasticizers from qualified material lists. Medical-device and food-contact applications face the most acute reformulation pressure due to MFDS migration testing requirements.
Specification-driven procurement now dominates automotive and electronics verticals. Buyers consolidate approved supplier lists to three qualified compounders per material family. Tier-1 automotive suppliers in Gyeonggi-do province enforce this consolidation most aggressively.
South Korea Engineering Plastics Market Segmentation
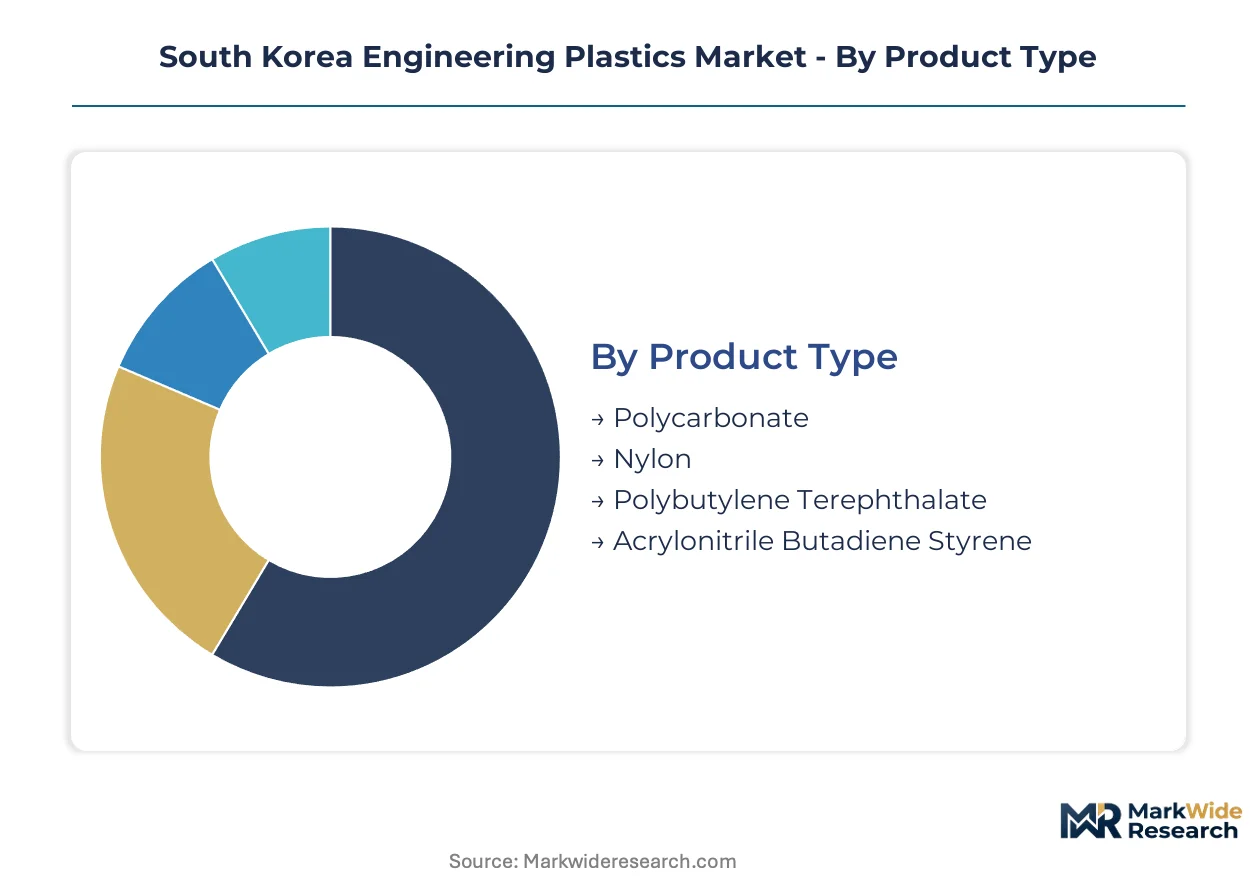
Engineering plastics procurement in South Korea demands precise material matching across divergent performance specifications. Compounders configure technical service intensity around segment-specific qualification protocols.
Product Type:
After-sales technical support requirements vary sharply across polymer chemistries, with optical-grade formulations demanding sustained formulation troubleshooting.
- Polycarbonate:Transparent amorphous thermoplastic with exceptional impact resistance and optical clarity. Seoul-Incheon electronics manufacturers specify flame-retardant grades for battery module housings as electric vehicle production scales. K-REACH substance evaluations force additive package reformulations.
- Nylon:Semi-crystalline polyamide with superior fatigue resistance and heat-aging performance. Under-hood automotive applications in Gyeonggi-do province drive demand for glass-filled and heat-stabilized variants. Caprolactam feedstock volatility compresses margin predictability for domestic compounders.
- Polybutylene Terephthalate:Crystalline polyester offering dimensional stability and electrical insulation properties.
- Acrylonitrile Butadiene Styrene:Cost-competitive terpolymer retaining share in consumer electronics enclosures despite alloy substitution pressure.
By volume, ABS leads. By growth pace, polycarbonate is expanding most quickly.
End User:
Customer concentration patterns reshape margin capture, with automotive Tier-1 suppliers consolidating approved vendor lists most aggressively.
- Automotive:Battery enclosure thermal management and electric motor housing specifications dominate procurement. KATRI crashworthiness and flammability standards dictate material grades for interior and structural applications. Hyundai Motor Group and Kia Corporation qualification timelines stretch 18-24 months.
- Consumer Electronics:Samsung Electronics and LG Electronics drive just-in-time color-matching requirements within 50 kilometers of compounder technical centers. 5G base station dielectric specifications favor specialized formulations.
- Aerospace:Limited domestic demand concentrated in MRO applications and component sourcing for international OEMs.
- Medical Devices:MFDS biocompatibility testing queues extend 14-18 months, compressing product launch windows for Korean device exporters.
Automotive commands the largest volume share. Medical devices are climbing the fastest.
Application:
Specification complexity determines compounding margin tiers, with multi-standard certification requirements stratifying supplier profitability.
- Automotive Parts:Structural load-bearing components and thermal management systems. MFDS migration testing applies to cabin air-contact applications.
- Electrical Components:Connectors, housings, and insulation systems. 5G infrastructure dielectric constant requirements favor PBT and PPS formulations for telecommunications equipment.
- Structural Applications:Metal replacement in precision manufacturing equipment.
- 3D Printing:Filament and powder formulations for additive manufacturing prototyping.
Automotive parts dominate volume. Electrical components are gaining share fastest.
Form:
Processing method selection shapes logistics configuration and inventory carrying cost structures across the value chain.
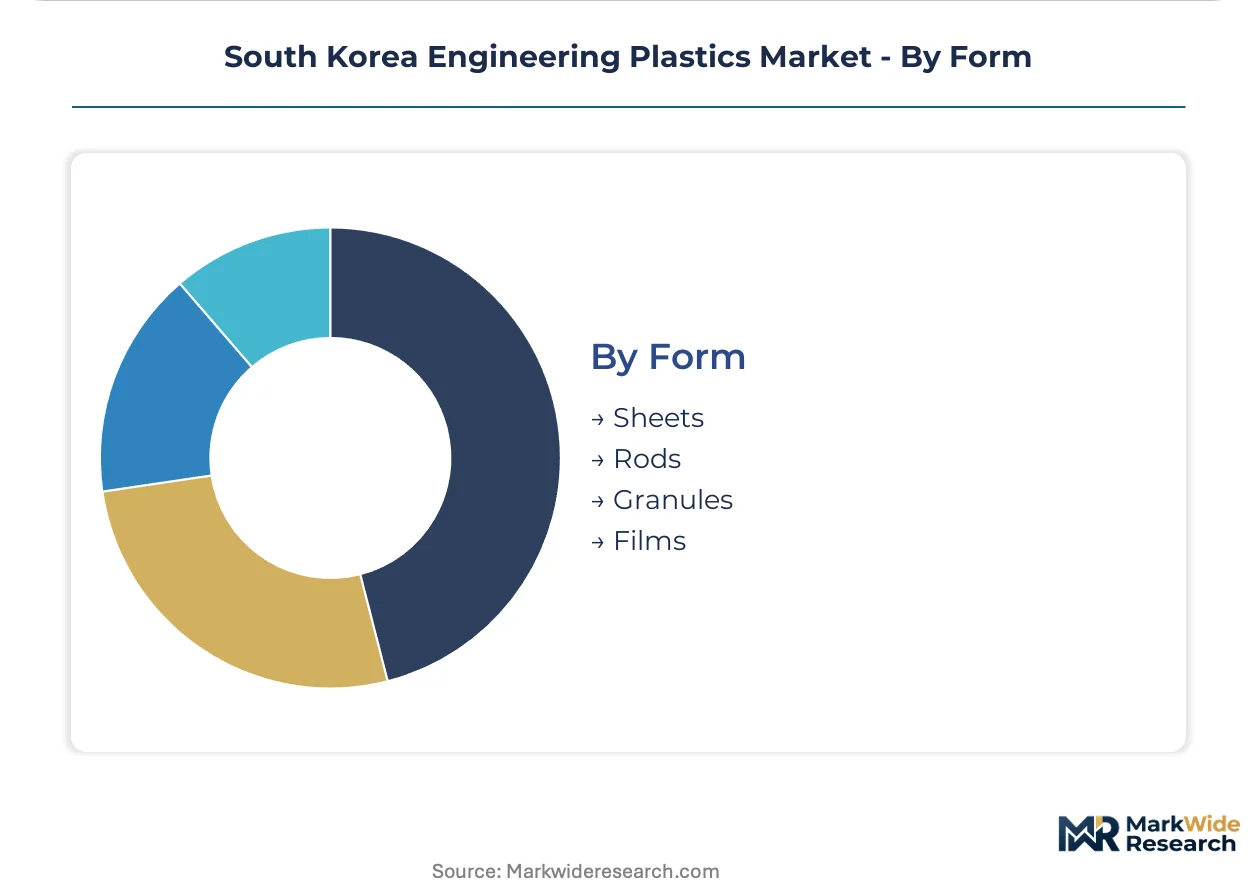
- Sheets:Thermoformed housings and display covers for electronics and automotive interior trim.
- Rods:Machined prototypes and small-batch precision components.
- Granules:Injection molding feedstock for high-volume automotive and electronics production.
- Films:Flexible electronics substrates and membrane switch applications.
Granules lead by volume. Films are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feedstock integration and compounder technical service density concentrate engineering plastics supply in the Seoul-Incheon corridor and Busan-Ulsan petrochemical cluster. Domestic demand for battery enclosure materials and medical-grade formulations is reshaping regional production priorities. Sub-regional specialization patterns reflect automotive electrification timelines and electronics manufacturing concentration.
Seoul Capital Area
Electric vehicle battery module housings and 5G telecommunications equipment drive polycarbonate and PBT formulation demand. MFDS medical-device biocompatibility testing queues extend 14-18 months, compressing launch windows for Seoul-based device exporters. Gyeonggi-do province hosts Hyundai Motor Group and Kia Corporation qualification centers where Tier-1 suppliers enforce three-compounder consolidation rules.
Busan-Ulsan
Petrochemical feedstock availability and deepwater port access anchor nylon and ABS resin production. K-REACH substance evaluation deadlines force reformulation of legacy additive packages at Ulsan compounding facilities. Chemical recycling investments convert mixed polymer waste to virgin-equivalent feedstock, closing loops with Seoul-Incheon electronics manufacturers.
Daegu-Gyeongbuk
Automotive under-hood component suppliers cluster around heat-stabilized nylon demand from electric motor housing specifications. KATRI crashworthiness standards dictate material grades for interior applications sourced from this region. Daegu-based compounders serve secondary automotive suppliers with shorter qualification timelines than Seoul-Tier-1 relationships.
Daejeon-Sejong
Government research institutes and testing laboratories support polymer characterization and regulatory pre-certification. K-REACH registration data aggregation accelerates customer qualification for compounders leveraging Sejong regulatory coordination. The region functions as a technical service hub rather than volume production center.
Gwangju-Honam
Consumer electronics enclosure manufacturing for mid-tier brands concentrates ABS and PC/ABS alloy demand. Just-in-time color-matching capabilities from Seoul-Incheon compounders reduce inventory carrying costs for Gwangju electronics assemblers. The region captures spillover demand from saturated Seoul corridor capacity.
South Korea Engineering Plastics Market Competitive Landscape
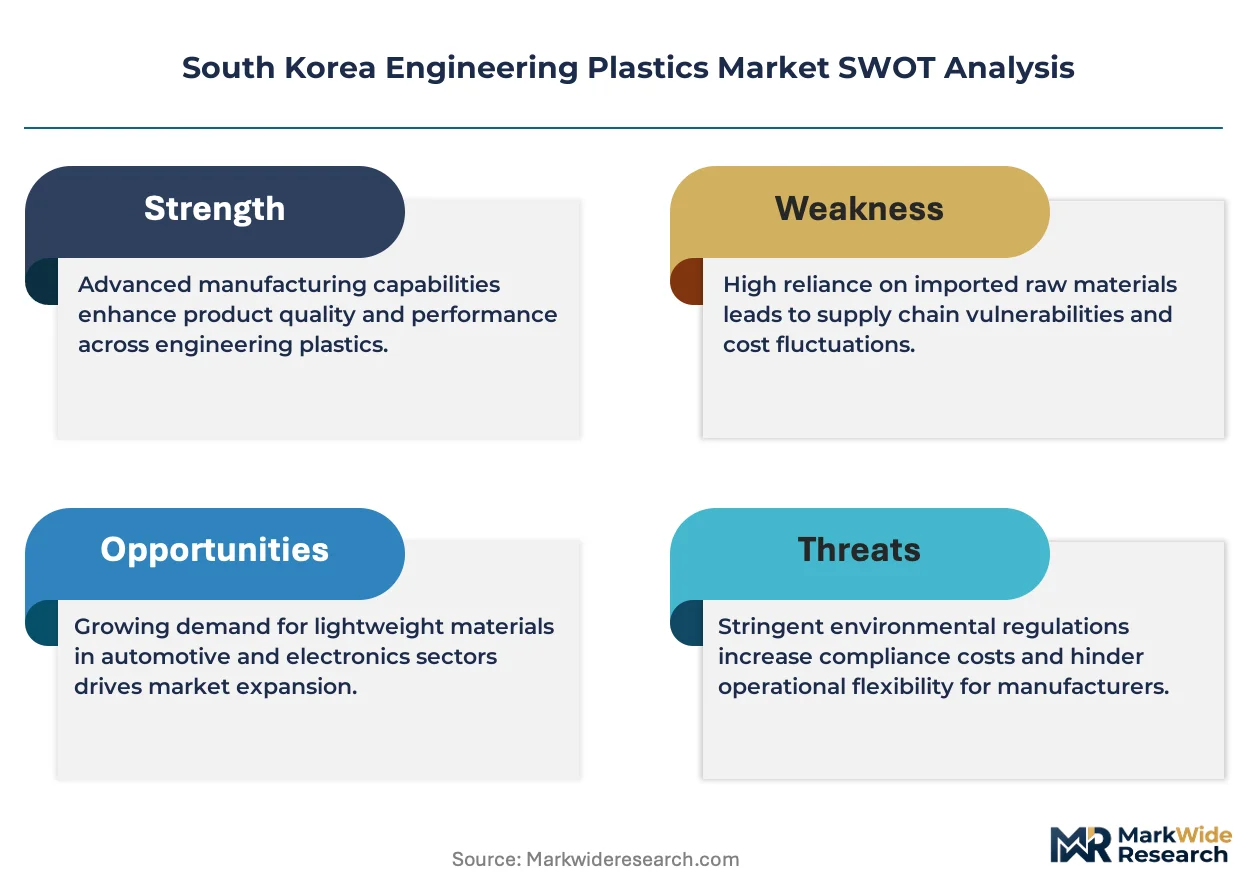
Integrated petrochemical conglomerates and specialized engineering plastics compounders split the market along feedstock control versus formulation agility lines. The structure tilts toward consolidation in optical-grade polycarbonate where birefringence specifications limit qualified suppliers, while nylon and ABS segments retain fragmentation. Three archetypes dominate: backward-integrated resin producers, independent compounders with colorimetric expertise, and global material suppliers with specification authority. Competitive moves center on K-REACH registration data monetization and carbon-border adjustment documentation investments.
Among domestic integrated producers, SK Chemicals, Korea Engineering Plastics, and LG Chem occupy positions reflecting distinct strategic emphases. SK Chemicals exemplifies the feedstock-integrated archetype through PET and copolyester operations. Korea Engineering Plastics anchors the specialized compounder tier with domestic nylon supply relationships. LG Chem represents technology-led positioning in optical-grade formulations. Samyang Corporation, Kumho Petrochemical, and Kolon Industries sit within mid-tier compounder categories, while INEOS and Lotte Chemical reflect multinational and diversified chemical conglomerate participation patterns.
| Leading Market Players |
|---|
| SK Chemicals |
| Korea Engineering Plastics |
| LG Chem |
| Samyang Corporation |
| INEOS |
| Kumho Petrochemical |
| Kolon Industries |
| LX MMA |
| Lotte Chemical |
| Others |
Pricing and Supply Chain Analysis
Caprolactam feedstock volatility compresses margin predictability for domestic compounders while simultaneously widening pricing tier spreads between integrated resin producers and independent compounders. K-REACH substance evaluation deadlines force simultaneous portfolio-wide reformulation, concentrating pricing power among suppliers with captive registration data and technical service density in the Seoul-Incheon corridor.
Pricing Analysis
K-REACH compliance timelines dictate the pricing tier structure across South Korea's engineering plastics market. Three-tier pricing separates optical-grade polycarbonate formulations from standard automotive grades from commodity ABS compounds, with certification grade and volume scale as the primary differentiation drivers. Cost compression in nylon compounds is intensifying because Korean compounders lack backward integration into benzene derivatives. Tier-1 automotive suppliers in Gyeonggi-do province exhibit the least price sensitivity due to 18-24 month qualification lock-ins, while mid-tier electronics assemblers in Gwangju-Honam negotiate aggressively on ABS volumes.
Supply Chain Analysis
Export-control restrictions on advanced polymer characterization equipment limit domestic laboratory capacity expansion and constrain formulation development velocity. Feedstock supply draws from Saudi Arabia for benzene derivatives, China for caprolactam intermediates, and Japan for specialized flame-retardant additives. Single-source vulnerability concentrates in optical-grade polycarbonate resin where birefringence control technology remains restricted. Distribution runs through just-in-time technical service centers within 50 kilometers of Seoul-Incheon electronics manufacturers and Busan-Ulsan petrochemical offtake points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation agility and regulatory anticipation capability now separate viable competitors from margin-squeezed commodity suppliers in South Korea's engineering plastics sector. The acute shortage of colorimetric expertise and spectral analysis capabilities compounds this capability gap.
For Market Incumbents: Build K-REACH registration data moats by monetizing compliance documentation and accelerating customer qualification timelines. SK Chemicals and LG Chem should deepen backward integration into specialty additive packages to defend against Japanese and German specification authority in optical grades. Capacity addition in Busan-Ulsan chemical recycling infrastructure captures closed-loop feedstock economics before regulatory mandates harden. For New Entrants and Emerging Players: Mid-market medical-device compounders facing MFDS testing backlogs represent the most penetrable entry point for agile formulation specialists. Daegu-Gyeongbuk automotive under-hood suppliers offer shorter qualification timelines than Seoul-Tier-1 relationships. A go-to-market angle anchored on 5G base station dielectric specifications bypasses entrenched automotive supply relationships. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors compounders with pre-registered substance portfolios and carbon-border adjustment documentation capabilities. Long-term viability hinges on Scope 3 emissions tracking infrastructure and life-cycle assessment certification. The signal to watch is EU-REACH equivalence agreement finalization, which would immediately revalue domestic compliance-ready assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Additives | Reduces formulation cost exposure to K-REACH restricted substance lists. |
| Chemical Recycling Capacity Buildout | Closes virgin-equivalent feedstock loops with Seoul-Incheon electronics manufacturers. |
| MFDS Pre-Certification Laboratory Investment | Compresses 14-18 month biocompatibility queues for medical-device compounders. |
| Carbon-Border Documentation Platform | Positions domestic producers for EU automotive OEM contract eligibility. |
| 5G Dielectric Formulation Partnership | Captures telecommunications infrastructure specifications from Samsung and LG. |
Research Methodology
The analysis maps polycarbonate optical grades, nylon under-hood formulations, PBT electrical components, and ABS consumer electronics compounds, each validated through procurement managers at Hyundai Motor Group and Kia Corporation Tier-1 suppliers, technical directors at SK Chemicals and LG Chem compounding facilities, and MFDS regulatory affairs specialists. Secondary sources include Korea Customs Service trade statistics, KATRI crashworthiness test protocols, K-REACH registration databases, and SEC filings from multinational material suppliers. Bottom-up volume estimates from compounder production records triangulate against top-down demand modeling from automotive and electronics OEM bill-of-materials data.
Forecasts assume K-REACH substance evaluation deadlines proceed on current administrative timelines, electric vehicle production scales according to domestic OEM platform announcements, and EU-REACH equivalence negotiations conclude without disruptive tariff imposition across the projection horizon. Segmentation dimensions include polymer chemistry family, end-use industry vertical, performance grade tier, and regional manufacturing cluster. CAGRs derive from elasticity-adjusted demand projections incorporating battery enclosure thermal management specifications and medical-device biocompatibility migration testing requirements.
Practitioners should monitor K-REACH substance restriction list expansions, caprolactam derivative pricing volatility, and EU carbon-border adjustment implementation timelines for early signals of forecast deviation. Material shifts in MFDS biocompatibility testing capacity or optical-grade polycarbonate specification authority would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Conductive Polymers Market
Polymers & Resins
Sugar Polymers Market
Polymers & Resins
Polyamide 11 & 12 Market
Polymers & Resins
Global Structural Foam Market
Polymers & Resins
Methyl Silicone Resins Market
Polymers & Resins
Global Anti-Vibration Polymer Market
Polymers & Resins
Polyamide Resins Market
Polymers & Resins
Polylactic Acid Market
Polymers & Resins
Polymers for Electric Vehicle (EV) Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Global Polybutene Market
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
South America Thermoplastics Market
Polymers & Resins
Ethylene-Vinyl Alcohol Copolymer (EVOH) Market
Polymers & Resins
South-East Asia Low-Density Polyethylene (LDPE) Market
Polymers & Resins
BPA-Free Epoxy Resins Market