
 Beryllium Copper for Telecommunication Market | 2026-2036
Beryllium Copper for Telecommunication Market Size, Share, and Industry Trends Forecast 2026-2036
Beryllium Copper for Telecommunication Market Insights
High-conductivity alloy grades is bifurcating the competitive landscape between performance-specialists and volume producers. Materion leverages captive beryllium sourcing to sustain margin control across North American connector supply chains. NGK Metals anchors Japanese precision wire demand through proprietary heat-treatment protocols. AMETEK Specialty Metal Products competes on cold-formed strip geometries for RF shielding applications.
Beryllium copper for telecommunication denotes a copper-beryllium alloy typically containing 0.2–2.0% beryllium by weight, valued for its combination of electrical conductivity approaching 60% IACS and yield strength exceeding 200 ksi after precipitation hardening. The material serves primarily as a spring-contact and current-carrying substrate in miniature connectors subject to repeated mechanical cycling. Strip and wire categories dominate volume flows, with strip commanding premium positioning in high-density backplane connectors where flatness tolerances below 0.001 inch justify alloy cost premiums. Precision machining technology leads value-add capture, though cold forming gains share in cost-sensitive relay contact production where near-net-shape geometries reduce material scrap rates.
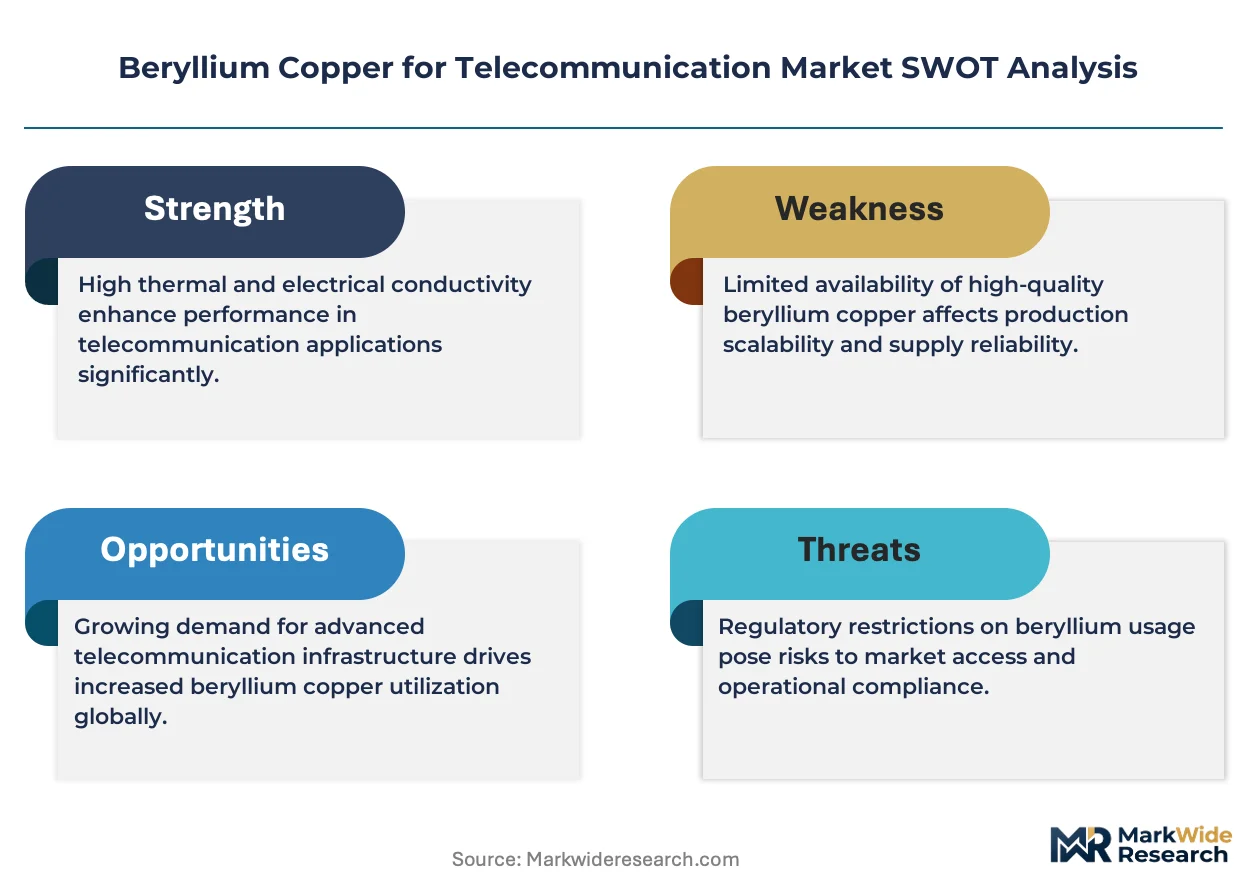
FCC Part 15 electromagnetic compatibility mandates shape alloy selection for RF components in United States telecom infrastructure, while REACH beryllium compound restrictions in Europe constrain supply chain configurations for exporters. China's GB standards for telecommunications equipment impose additional compositional testing that favors certified domestic melt sources. Stakeholders must monitor evolving RoHS exemption timelines for beryllium content in electronic contacts, as renewal decisions will reshape alloy substitution economics across connector portfolios.
Market Dynamics
5G base station deployment is compressing connector procurement cycles while REACH and FCC electromagnetic standards simultaneously tighten material purity thresholds, forcing alloy processors to recalibrate heat-treatment protocols against certification timelines.
Growth Catalysts
- 5G Infrastructure Mandates:China's MIIT base station construction targets are pulling high-conductivity strip demand through domestic certified melt sources. Telecom equipment manufacturers face connector specification upgrades that favor precipitation-hardened alloys.
- REACH Compliance Deadlines:ECHA beryllium compound restrictions in Europe are locking in certified supply chains for exporters, creating preference premiums for documented purity traceability from mine to finished strip.
- RF Shielding Intensification:FCC Part 15 electromagnetic compatibility enforcement is expanding cold-formed strip applications in United States telecom infrastructure where flatness tolerances below 0.001 inch justify alloy cost premiums.
Market Restraints
- Beryllium Supply Concentration:Captive mine-to-mill operations in sparse geographies expose connector manufacturers to concentrate pricing leverage from primary beryllium producers.
- Substitution Pressure from Copper-Nickel-Silicon:C70250 alloys are penetrating cost-sensitive relay contact applications where electrical conductivity trade-offs fall within acceptable bandwidth for lower-duty cycling.
- RoHS Exemption Uncertainty:Renewal timelines for beryllium content exemptions in electronic contacts create inventory planning friction across connector portfolios.
Strategic Opportunities
- India Telecom Infrastructure Buildout:TRAI spectrum allocation policies are accelerating domestic base station programs where certified alloy importers can establish early specification relationships.
- Precision Wire Miniaturization:Micro-connector architectures in handsets and IoT modules are expanding addressable demand for sub-0.025-inch diameter wire with yield strength exceeding 200 ksi.
- Dual Carbon Alignment in China:MIIT energy efficiency mandates for telecommunications equipment are favoring domestic producers with verified low-carbon melt technologies.
Industry Challenges
- Precipitation Hardening Expertise Gap:Qualified furnace operators capable of maintaining ±5°F temperature control across aging salt-bath systems are retiring faster than training programs replace them.
- GB Standard Certification Timelines:China's compositional testing protocols for telecommunications equipment impose 12-18 month qualification cycles that lock out uncertified foreign melt sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beryllium Copper for Telecommunication Market |
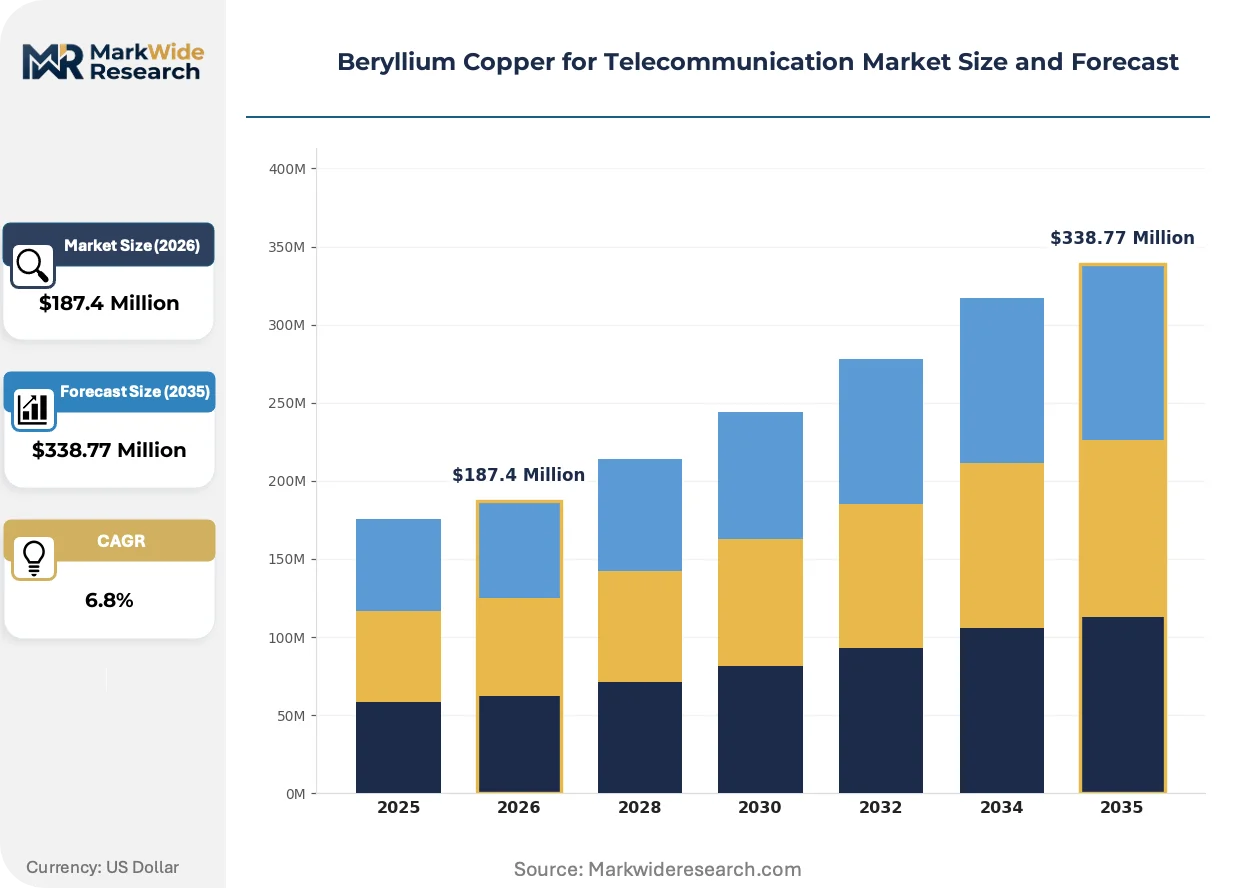
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strip, Wire, Rod, Plate, Bar Technology: Precision Machining, Cold Forming, Heat Treatment, Casting, Forging Application: Connectors, Switches, Relays, RF Components, Circuit Breakers, Sensors End User: Telecom Equipment Manufacturers, Data Center Operators, Network Service Providers, Electronic Component Producers |
| Companies Covered | Materion, NGK Metals, AMETEK Specialty Metal Products, IBC Advanced Alloys, Wieland, Mitsubishi Shindoh, Belmont Metals, Aviva Metals, Fisk Alloy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beryllium Copper for Telecommunication Market Trends and Innovations
Alloy processing methods and regulatory compliance frameworks are fragmenting competitive positioning between performance-specialists and volume producers across connector supply chains.
Near-net-shape cold forming is fragmenting traditional precision machining value capture in relay contact production. Cost-sensitive telecom equipment manufacturers are adopting multi-stage pressing sequences that reduce material scrap rates from 40% to 8% in high-volume runs. The technology is fragmenting margin structures between integrated processors and independent stamping houses.
REACH beryllium compound registration requirements are tightening documentary burden on European connector exporters. ECHA downstream user obligations now mandate Safety Data Sheet cascade through three supply chain tiers. Strip and wire categories face divergent compliance costs, with precision wire importers absorbing disproportionate testing overhead.
Specification-driven procurement consolidation is compressing supplier qualification cycles among tier-one telecom equipment manufacturers. Connector assemblers in China and Japan are consolidating purchase orders with certified domestic melt sources that pre-qualify against GB and JIS standards simultaneously. The pattern is most visible in high-density backplane connector programs where single-source approval reduces incoming inspection overhead.
Beryllium Copper for Telecommunication Market Segmentation
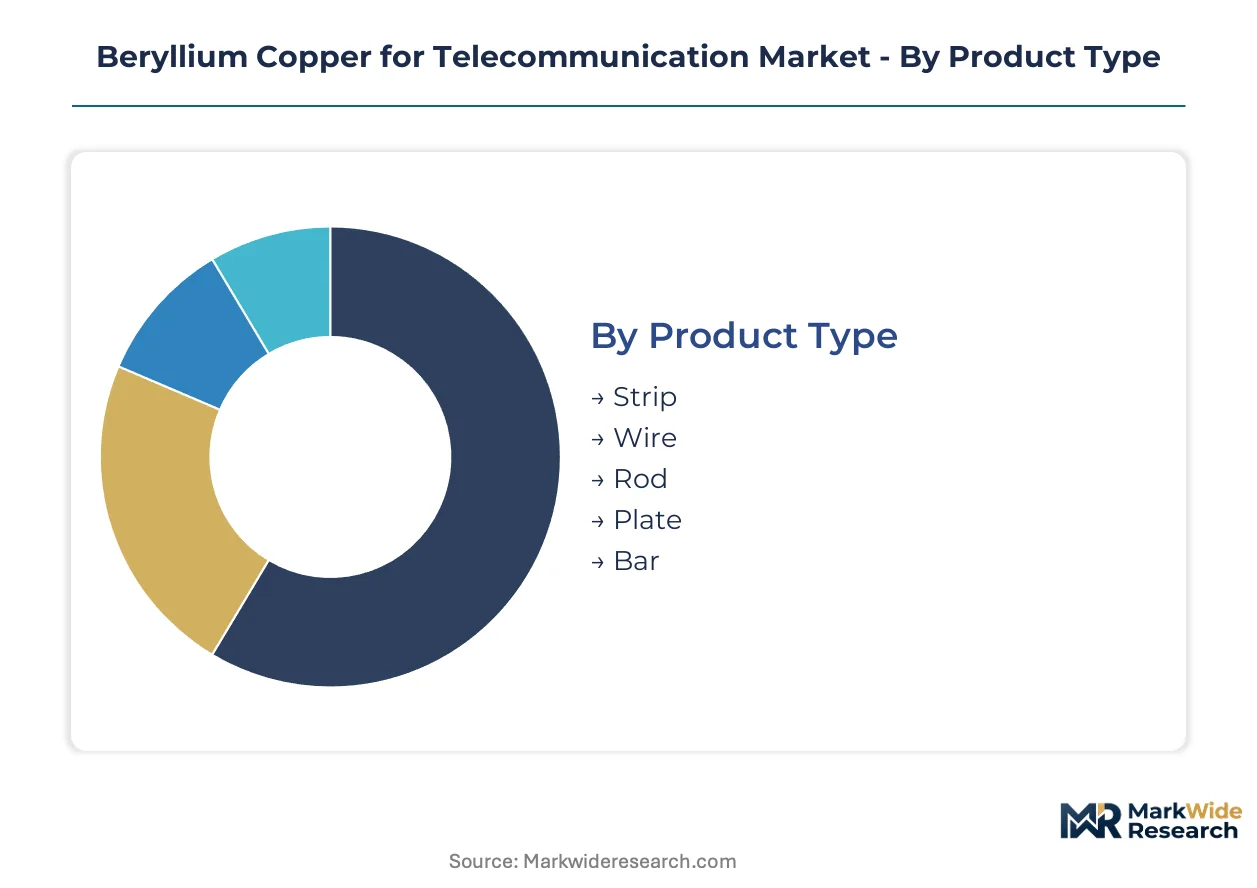
Beryllium copper alloys fragment into distinct product categories based on dimensional form and processing route. Each segment carries unique substitution exposure and margin structure that shapes competitive positioning across connector supply chains.
Product Type:
Copper-nickel-silicon alloys threaten cost-sensitive segments most aggressively, while premium flatness-tolerant categories defend position through specification lock-in.
- Strip:Flat-rolled material with thickness tolerances below 0.001 inch serves high-density backplane connectors in 5G base stations. China's MIIT construction targets concentrate demand through domestic certified melt sources that pre-qualify against GB standards. Flatness premiums resist substitution despite alloy cost differentials.
- Wire:Drawn product in diameters from 0.008 to 0.250 inch supplies spring contacts and precision current paths. Micro-connector architectures in handsets and IoT modules are pulling sub-0.025-inch diameter demand through Japanese precision wire suppliers with proprietary heat-treatment protocols.
- Rod:Round solid stock for machining operations in relay contact production. C70250 alloys penetrate cost-sensitive applications where conductivity trade-offs fall within acceptable bandwidth.
- Plate:Thick-section material for structural EMI shielding and busbar applications. Data center operators in India specify plate for grounding systems under TRAI infrastructure mandates.
- Bar:Rectangular and hexagonal extrusions for connector housings and mechanical support members. Telecom equipment manufacturers specify bar for custom relay frames where machinability overrides conductivity optimization.
Strip retains volume leadership; wire holds the steepest expansion curve.
Technology:
Process selection bifurcates between scrap-intensive precision methods and near-net-shape forming that captures cost-sensitive volume.
- Precision Machining:CNC turning and milling of rod and bar stock produces complex connector geometries with tight tolerances. Traditional value capture faces erosion as cold forming penetrates relay contact production with 8% scrap rates versus 40% for machining.
- Cold Forming:Multi-stage pressing sequences shape strip and wire into near-net connector contacts without material removal. Telecom equipment manufacturers in China adopt cold forming for high-volume relay production where material efficiency outweighs tooling investment.
- Heat Treatment:Precipitation hardening in salt-bath furnaces achieves yield strength exceeding 200 ksi after aging. Qualified furnace operators capable of ±5°F temperature control are retiring faster than training programs replace them.
- Casting:Investment and die casting for complex RF shielding housings with internal geometries. FCC Part 15 electromagnetic compatibility mandates shape alloy selection for cast RF components in United States infrastructure.
- Forging:Closed-die forging for high-strength connector bodies requiring directional grain flow. Limited penetration in telecommunications due to dimensional precision requirements.
Cold forming is climbing the fastest; precision machining defends share in specification-critical applications.
Application:
Connector architectures drive the majority of alloy consumption, while emerging RF and sensor categories reshape demand composition.
- Connectors:Spring contacts, socket terminals, and backplane interfaces constitute the dominant application. High-density backplane programs in China and Japan consolidate purchase orders with certified domestic melt sources.
- Switches:Toggle and rocker mechanisms for telecom power distribution panels. REACH beryllium compound restrictions in Europe constrain supply chain configurations for switch exporters.
- Relays:Electromechanical switching devices for signal routing and load control. Cost-sensitive manufacturers substitute C70250 alloys where duty cycling permits conductivity trade-offs.
- RF Components:Antenna contacts, filter housings, and waveguide interfaces for 5G infrastructure. FCC Part 15 enforcement expands cold-formed strip applications where flatness tolerances justify alloy premiums.
- Circuit Breakers:Overcurrent protection devices for telecom power systems. Limited penetration due to copper-tungsten preference in high-interrupt applications.
- Sensors:Proximity and pressure sensing elements for equipment monitoring. Emerging demand from IoT module integration in base station thermal management.
Connectors retain volume leadership; RF components gain share fastest.
End User:
Procurement consolidation among tier-one equipment manufacturers compresses supplier qualification cycles and favors certified domestic sources.
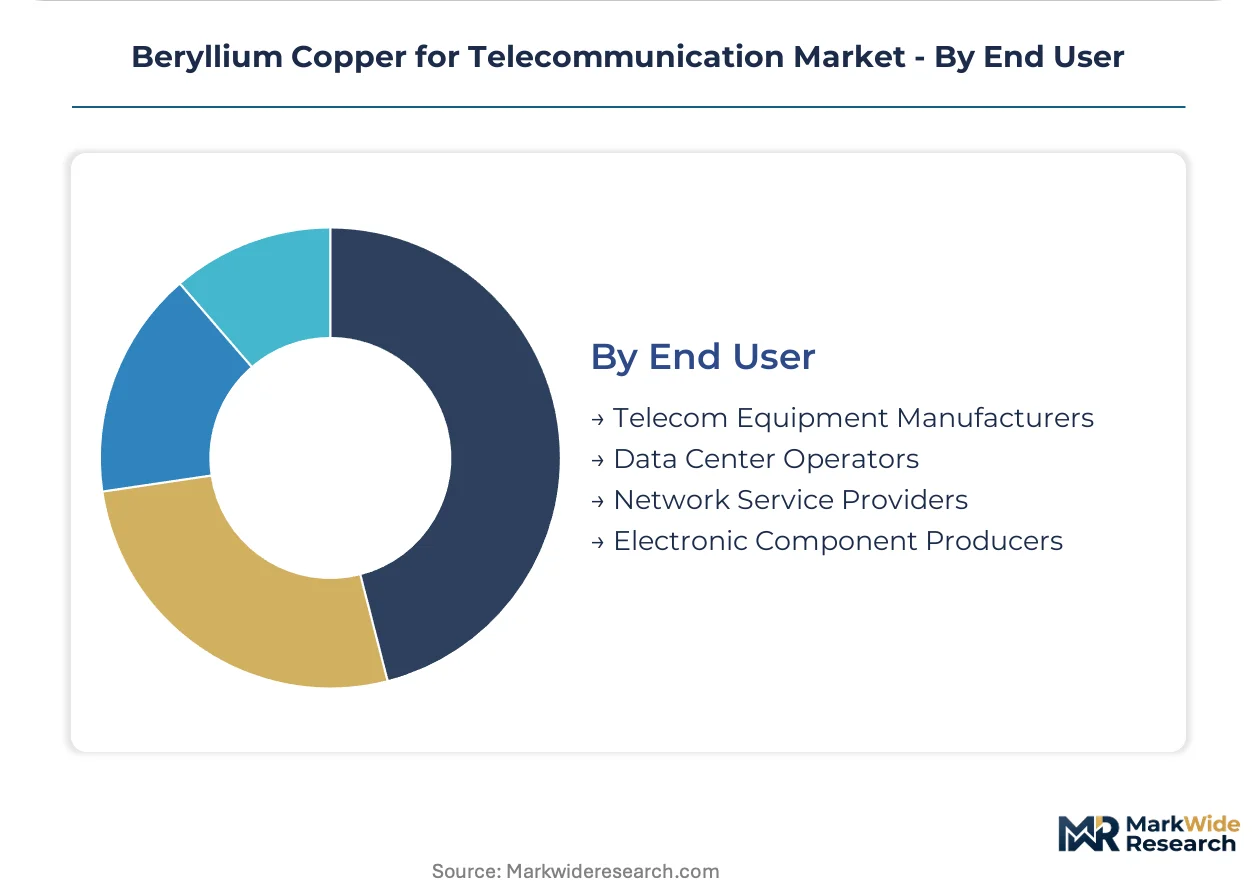
- Telecom Equipment Manufacturers:Base station OEMs and network infrastructure suppliers constitute the primary demand source. Specification-driven consolidation locks in certified melt relationships that reduce incoming inspection overhead.
- Data Center Operators:Hyperscale and colocation facilities for grounding, busbar, and EMI shielding applications. India's TRAI spectrum policies accelerate domestic programs where certified alloy importers establish early relationships.
- Network Service Providers:Mobile operators and fixed-line carriers with direct material procurement for maintenance and expansion. Limited direct alloy purchasing; specifications flow through equipment vendor requirements.
- Electronic Component Producers:Connector assemblers and relay manufacturers purchasing processed strip and wire. GB standard certification timelines impose 12-18 month qualification cycles that lock out uncertified foreign sources.
Telecom equipment manufacturers retain volume leadership; data center operators hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beryllium copper supply chains concentrate around certified melt sources in three dominant manufacturing clusters. FCC Part 15 mandates in the United States, REACH obligations in Europe, and GB standards in China fragment procurement patterns across distinct regulatory jurisdictions.
China
MIIT base station construction targets pull high-conductivity strip demand through domestic certified sources. GB standards for telecommunications equipment impose 12-18 month qualification cycles that lock out uncertified foreign melt suppliers. Yangtze River Delta connector assemblers consolidate purchase orders with pre-qualified domestic sources to reduce incoming inspection overhead.
United States
FCC Part 15 electromagnetic compatibility enforcement expands cold-formed strip applications in telecom infrastructure. Flatness tolerances below 0.001 inch justify alloy cost premiums in RF shielding components. Midwestern precision metal processors serve tier-one equipment manufacturers with documented purity traceability from mine to finished strip.
Japan
METI industrial policy supports precision wire demand through proprietary heat-treatment protocols. JIS standards pre-qualify domestic melt sources against connector specification upgrades. Kansai region wire suppliers anchor micro-connector architectures in handsets and IoT modules with sub-0.025-inch diameter capabilities.
Germany
ECHA beryllium compound restrictions lock in certified supply chains for European connector exporters. REACH downstream user obligations mandate Safety Data Sheet cascade through three supply chain tiers. Bavarian precision stamping houses absorb disproportionate testing overhead for precision wire imports.
India
TRAI spectrum allocation policies accelerate domestic base station programs. Certified alloy importers establish early specification relationships with telecom infrastructure buildout. Maharashtra data center operators specify plate for grounding systems under national telecommunications mandates.
Beryllium Copper for Telecommunication Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the beryllium copper value chain. The market structures around captive beryllium sourcing operations, precision heat-treatment specialists, and cold-forming volume processors. Three archetypes dominate: integrated miners-to-mill operators controlling primary material flows, certified processors with documented purity traceability, and stamping houses capturing cost-sensitive relay production. Competitive moves concentrate on backward integration into captive beryllium supply and multi-stage pressing technology licensing.
Among North American integrated operators, Materion exemplifies the captive-sourcing archetype with mine-to-mill control over primary material. NGK Metals occupies a position within the precision-specialist tier, while AMETEK Specialty Metal Products represents certified processing capabilities for RF shielding applications. These three anchors illustrate how competitive positioning fragments between performance-premium and cost-optimized vectors.
| Leading Market Players |
|---|
| Materion |
| NGK Metals |
| AMETEK Specialty Metal Products |
| IBC Advanced Alloys |
| Wieland |
| Mitsubishi Shindoh |
| Belmont Metals |
| Aviva Metals |
| Fisk Alloy |
| Others |
Pricing and Supply Chain Analysis
C70250 alloy substitution in cost-sensitive relay contacts simultaneously redraws supply geography toward South Korean and Taiwanese copper-nickel-silicon processors while compressing pricing premiums for standard-grade beryllium copper rod. This displacement forces incumbent beryllium copper suppliers to recalibrate tier boundaries between certified high-conductivity strip and commoditized machined components.
Pricing Analysis
REACH beryllium compound registration dictates the pricing tier structure across European connector supply chains, separating certified mine-to-mill traceability premiums from uncertified spot-market material. Pricing stratifies across certified high-purity, standard commercial, and economy-grade recycled tiers, with differentiation anchored in ECHA documentation depth and GB standard pre-qualification status. Cost compression in economy rod runs through C70250 substitution for duty-cycled relay applications. Telecom equipment manufacturers exhibit highest price sensitivity in high-volume relay procurement, while base station OEMs accept alloy premiums for flatness-critical backplane strip.
Supply Chain Analysis
Inventory cycles for precision wire extend 16-20 weeks due to salt-bath heat-treatment queue constraints at qualified furnace operators. Primary beryllium supply concentrates in Utah and Kazakhstan, with secondary refining anchored in Japan and Germany. Finished strip and wire distribution feeds from Yangtze River Delta and Kansai region certified processors. Tariff exposure on Chinese-origin strip threatens European connector exporter margins under evolving EU carbon border adjustment mechanisms. Downstream distribution runs through tier-one telecom equipment manufacturer consolidated procurement portals with pre-approved supplier lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat-treatment furnace operator certification services and precipitation hardening protocol licensing represent faster-expansion revenue layers than raw alloy sales, as qualified technical labor scarcity outpaces material demand growth.
For Market Incumbents: Consolidate captive beryllium sourcing through long-term offtake agreements with Kazakh and Utah primary producers to lock in margin control against concentrate pricing leverage. Acquire or license multi-stage cold forming technology to defend relay contact share against C70250 substitution pressure. Expand certified melt capacity in Yangtze River Delta to capture MIIT base station procurement consolidation. For New Entrants and Emerging Players: Aftermarket certification and re-qualification services for legacy connector inventories present the most penetrable white-space, as incumbent processors under-serve European exporters facing REACH documentation cascade obligations. Target precision wire micro-connector architectures in Indian handset assembly through TRAI-mandated domestic content relationships. Lead with furnace operator training and salt-bath protocol certification as the go-to-market wedge. For Investors and Strategic Acquirers: RoHS beryllium exemption renewal timelines reshape the acquisition landscape, elevating certified processors with documented purity traceability above commodity alloy traders. Five-to-ten-year viability favors integrated mine-to-mill operators and precision heat-treatment specialists with proprietary aging protocols. Watch ECHA downstream user obligation enforcement intensity as the signal for certification-premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Beryllium Supply Agreement | Locks in margin control against Kazakh and Utah concentrate pricing leverage. |
| Multi-Stage Cold Forming Technology License | Reduces relay contact scrap rates from 40% to 8% versus precision machining. |
| GB Standard Pre-Qualification Investment | Secures 12-18 month certification timeline advantage for China MIIT base station procurement. |
| Furnace Operator Training Program | Addresses retiring qualified salt-bath technician scarcity with proprietary protocol certification. |
| REACH Documentation Cascade Service | Captures Safety Data Sheet tier-three compliance overhead from European connector exporters. |
Research Methodology
The analysis maps strip, wire, rod, plate, and bar sub-sectors, each validated through connector assembler procurement managers, telecom equipment manufacturer specification engineers, and certified melt source quality directors. Primary interviews with salt-bath furnace operators, ECHA compliance consultants, and TRAI infrastructure policy specialists combined with secondary validation from MIIT construction target disclosures, FCC Part 15 enforcement bulletins, and customs trade flow data. Bottom-up alloy consumption estimates and top-down infrastructure capex allocation triangulate market sizing across the projection horizon.
Consistency checks against external benchmarks validated volume and value outputs, with segmentation modeling across product form, processing technology, connector application, and end-user procurement consolidation patterns. CAGRs derived from 5G base station deployment curves, REACH compliance deadline phasing, and substitution elasticity parameters for copper-nickel-silicon alloys. Forecast inputs incorporated MIIT annual construction targets, FCC electromagnetic enforcement intensity indices, and furnace operator retirement rate projections.
Underlying assumptions cover sustained 5G infrastructure capex, stable beryllium compound regulatory frameworks, and qualified heat-treatment labor replacement rates, with deviation risk concentrated in RoHS exemption renewal outcomes and C70250 alloy conductivity improvements. Revision becomes warranted when substitution alloy performance crosses 55% IACS conductivity thresholds or ECHA tightens downstream user obligations beyond three-tier documentation cascade.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Rhodium Market
Metals
Steel Drums and Ibcs Market
Metals
Industrial Metal Strips Market
Metals
Steel Drums Market
Metals
Copper and Brass Flat Products Market
Metals
Platinum Group Metals Market
Metals
United States Aluminum Extrusion Market
Metals
Monel Alloy Market
Metals
Niobium Oxide Market
Metals
Global Metal and Metal Manufactured Products Market
Metals
Electrodeposited Copper Foil Market
Metals
Europe Welding Consumables Market
Metals
Aluminum Plates and Sheet Coils Market
Metals
Colloidal Metal Particles Market
Metals
Aluminum Extrusion Market
Metals
High Purity Lead Market