
 Smelting Chemicals Market | 2026-2036
Smelting Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Smelting Chemicals Market Analytics
Copper and nickel recovery from complex sulfide ores is shifting toward hydrometallurgical and flash-smelting circuits that demand specialized flux and additive packages. BASF SE leverages its mining chemicals portfolio to supply customized reductant and frother systems for high-arsenic concentrates. Solvay anchors European supply through its soda ash and specialty reagent production for lead-zinc smelters. Clariant competes in the flux segment with bentonite and organic binder technologies that improve pellet strength and furnace permeability.
Smelting chemicals encompass reagents, fluxes, reducing agents, and slag conditioners formulated to lower melting points, remove impurities, and control oxidation-reduction potentials during pyrometallurgical extraction. These formulations typically contain silica, lime, alumina, or carbonaceous materials in ratios calibrated to specific ore gangue chemistry and target metal recovery rates. Ferrous smelting applications dominate volume consumption due to the scale of blast furnace and direct-reduction iron operations, though non-ferrous smelting commands premium pricing for high-purity copper, nickel, and cobalt extraction. Powder and bulk delivery modes lead in raw material cost efficiency for integrated smelters, while packaged formats sustain margins among smaller foundries and recycling facilities requiring precise dosing control.
EPA emissions standards for sulfur dioxide and particulate matter shape North American product formulation requirements, while REACH and the EU Green Deal restrict certain halogenated and heavy-metal-containing reagents in European smelting circuits. China's MEE enforces increasingly stringent SO2 concentration limits that force domestic smelters to adopt alternative flux chemistries with lower volatile organic content. Stakeholders must monitor how Indonesia's evolving nickel ore export restrictions and domestic processing mandates redirect regional chemical procurement patterns without assuming linear supply chain replication from established copper or aluminum corridors.
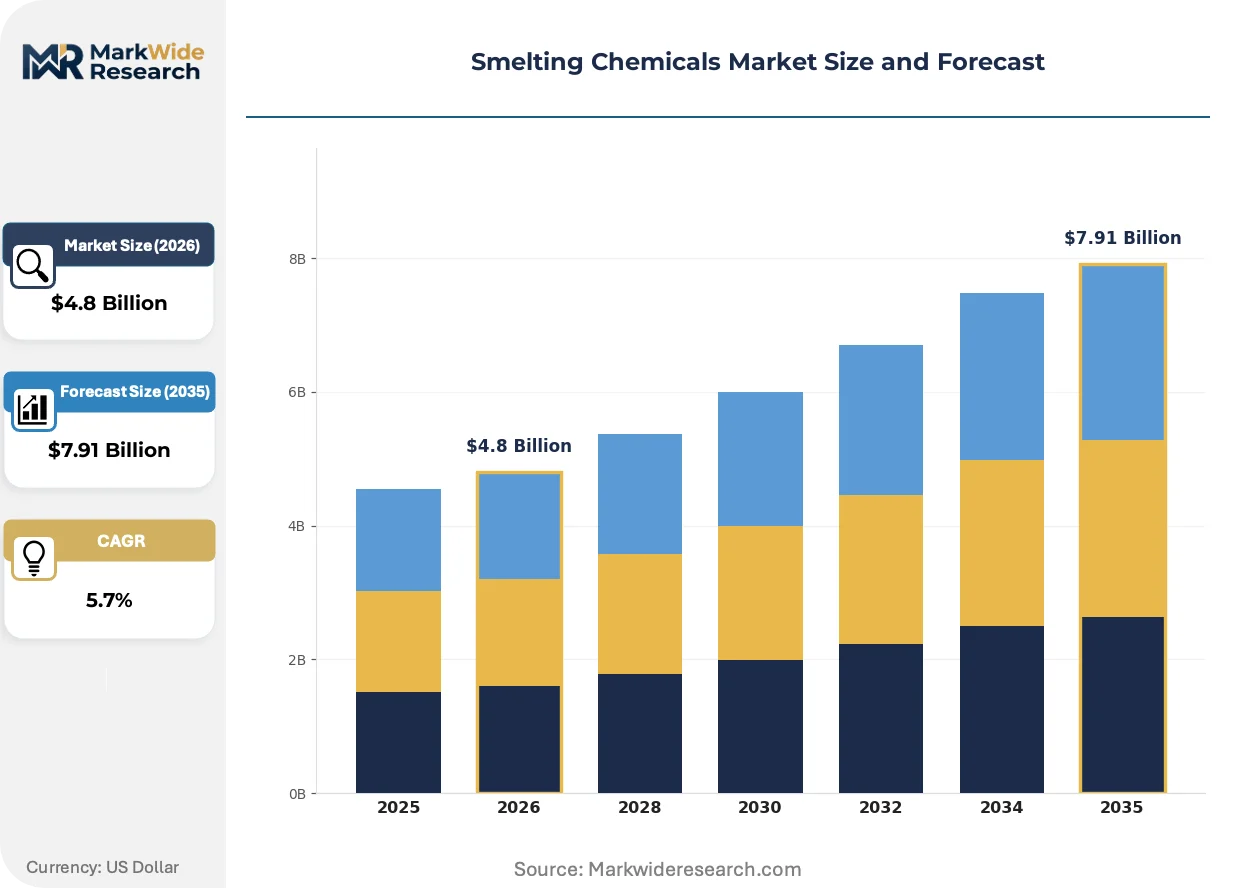
Market Dynamics
China's dual carbon goals and tightening emissions standards are forcing smelters to reformulate flux and reductant chemistries, redirecting procurement patterns across the nickel-copper processing corridor.
Growth Catalysts
- Electric vehicle battery cathode material production:High-purity copper and nickel smelting chemicals face surging demand from cathode manufacturers securing offtake agreements in Indonesia's processing corridor.
- REACH and EU Green Deal restrictions:European smelters are replacing halogenated reagents with alternative flux chemistries, opening formulation contracts for compliant suppliers.
- Hydrometallurgical circuit adoption:Complex sulfide ore processing is shifting toward flash-smelting and hydrometallurgical methods that require specialized additive packages.
Market Restraints
- Input cost volatility:Soda ash and carbonaceous reductant prices fluctuate with energy markets, compressing margins for blast furnace operators.
- Supply concentration risk:Bentonite and specialty binder production clusters in specific mining districts, creating vulnerability for pellet strength formulations.
- Substitution threat:Direct-reduction iron processes are displacing traditional blast furnace routes, reducing volume demand for conventional flux packages.
Strategic Opportunities
- Indonesia's nickel processing corridor:Domestic processing mandates and export restrictions are creating captive demand for localized chemical formulation facilities.
- ISO certification tailwinds:Smelters pursuing environmental management certification are sourcing traceable, low-VOC flux systems from audited suppliers.
- Recycling circuit integration:Urban mining and battery scrap processing are converging with primary smelting, requiring hybrid reagent formulations for mixed feedstocks.
Industry Challenges
- Pyrometallurgical skill scarcity:Flash-smelting and bath smelting operations require specialized furnace control expertise that outpaces vocational training pipelines.
- Capex intensity for emissions compliance:China's MEE SO2 concentration limits force acid plant and gas cleaning investments that strain mid-tier smelter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smelting Chemicals Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluxes, Reductants, Additives, Slag Formers End User: Metal Manufacturers, Foundries, Recycling Facilities, Construction Application: Ferrous Smelting, Non-Ferrous Smelting, Alloy Production, Waste Recycling Delivery Mode: Bulk, Packaged, Liquid, Powder |
| Companies Covered | BASF SE, Solvay, Clariant, KGHM, Vedanta Limited, Boliden Group, Techint Group, Dow Chemical Company, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smelting Chemicals Market Evolving Landscape
Digital process control and closed-loop reagent dosing are compressing yield variability in smelting circuits, while regulatory chemistry mandates and buyer consolidation reshape supplier relationships.
Sensor-driven flux dosing is automating real-time slag chemistry adjustment in copper-nickel flash smelters. Integrated operators in Indonesia's Morowali corridor are deploying these systems to maintain target iron-silica ratios across variable ore blends. The technology is automating what required manual sampling and laboratory turnaround, compressing batch-to-batch variation and reducing reagent overconsumption.
China's MEE enforcement of SO2 concentration limits is prohibiting certain volatile organic carriers in traditional flux formulations. Domestic copper smelters in Jiangxi and Shandong provinces are reformulating with lower-VOC alternatives to maintain operating permits. The policy shift is accelerating procurement switches toward suppliers with verified emission-compliant product lines.
Long-term offtake contracting is displacing spot purchasing among battery-grade nickel processors. Korean and Chinese cathode makers are locking multi-year chemical supply agreements directly with smelters, bypassing traditional distributor networks. This pattern concentrates most visibly in Indonesia's Weda Bay and Obi Island industrial zones where integrated battery material parks anchor demand.
Smelting Chemicals Market Segmentation
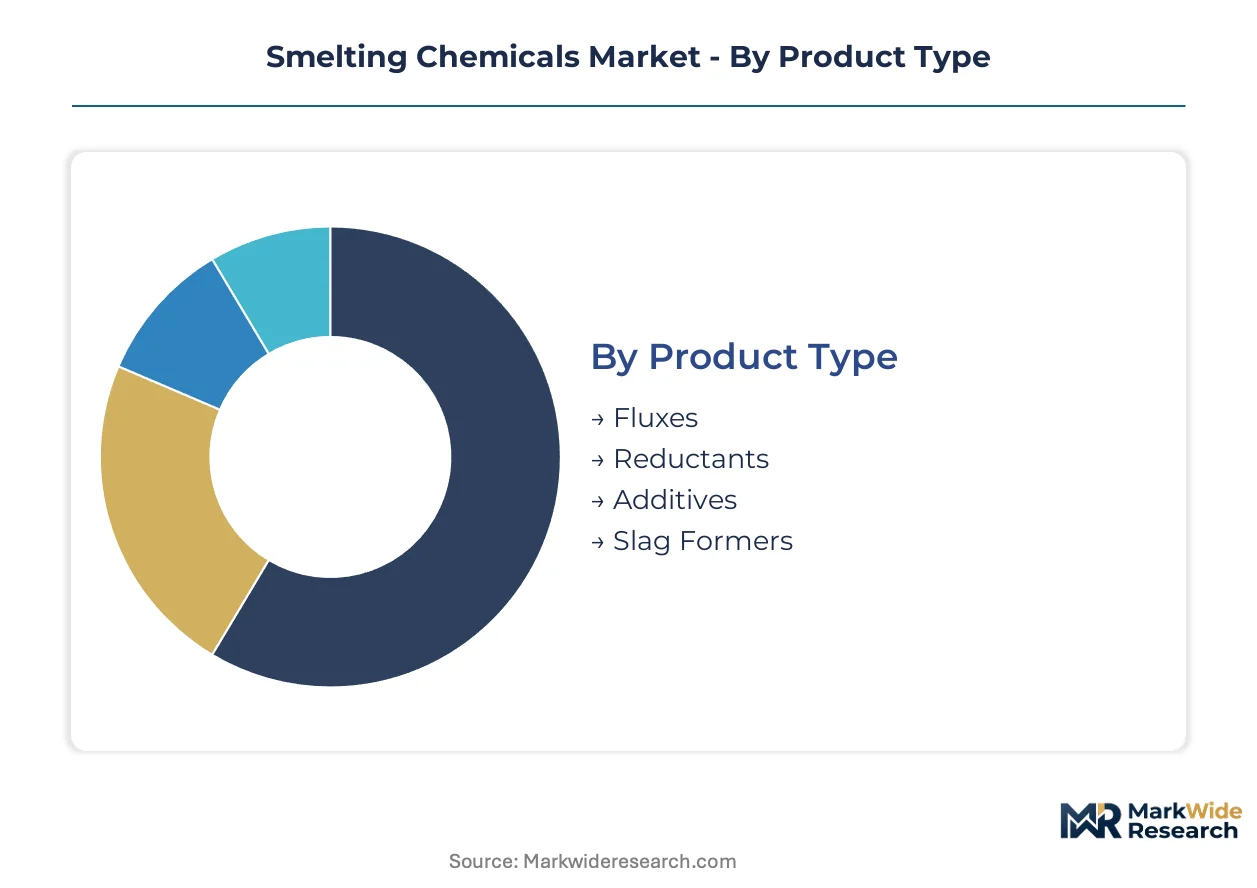
Segmentation in smelting chemicals reveals divergent margin structures between commodity-scale ferrous operations and precision-driven non-ferrous extraction. Product formulation requirements split sharply across ore chemistry, furnace technology, and emissions compliance tiers.
Product Type:
Volume consumption clusters in basic flux and carbonaceous reductant categories, while specialty additives command formulation premiums for complex concentrate processing.
- Fluxes:Silica-lime-alumina blends calibrated to gangue chemistry lower melting points and control slag fluidity in pyrometallurgical circuits. Integrated copper smelters in Indonesia's Morowali corridor consume bulk soda ash and limestone fluxes under long-term offtake contracts tied to cathode material output.
- Reductants:Carbonaceous materials including metallurgical coke, anthracite, and petroleum coke reduce metal oxides and maintain bath reduction potentials. China's Jiangxi province smelters are reformulating with lower-volatile alternatives to meet MEE SO2 enforcement, redirecting procurement toward compliant suppliers.
- Additives:Frothers, collectors, and depressants optimize metal recovery rates in flotation and smelting stages.
- Slag Formers:Magnesia and calcium aluminate conditioners modify slag chemistry for impurity removal and metal entrainment control.
Today's leader: Fluxes. Tomorrow's challenger: Additives.
End User:
Customer scale determines packaging economics, with integrated metal manufacturers driving bulk procurement and smaller foundries sustaining packaged format margins.
- Metal Manufacturers:Primary copper, nickel, and ferrous producers operating flash-smelting and blast furnace circuits. Korean and Chinese battery cathode makers have anchored multi-year chemical supply agreements directly with Indonesian nickel processors, bypassing traditional distributor networks.
- Foundries:Secondary metal casting operations requiring precise dosing control for alloy chemistry management.
- Recycling Facilities:Urban mining and battery scrap processors handling mixed feedstocks of primary and secondary materials.
- Construction:Cement and aggregate applications utilizing smelting slag byproducts as supplementary materials.
Metal Manufacturers concentrate procurement volume. Recycling Facilities are climbing the fastest as battery scrap streams expand.
Application:
Ferrous smelting dominates tonnage consumption while non-ferrous extraction sustains premium pricing for high-purity metal recovery.
- Ferrous Smelting:Blast furnace and direct-reduction iron operations consuming silica, lime, and carbonaceous fluxes at massive scale. Direct-reduction processes are displacing traditional blast furnace routes in some corridors, compressing conventional flux package demand.
- Non-Ferrous Smelting:Copper, nickel, and cobalt extraction requiring specialized reductant and additive formulations for complex sulfide concentrates. Hydrometallurgical circuit adoption in Indonesia's Weda Bay industrial zone is pulling demand for high-purity processing chemicals.
- Alloy Production:Precision ferroalloy and master alloy manufacturing with tight oxidation-reduction control.
- Waste Recycling:Electronic scrap and industrial residue processing with hybrid reagent requirements.
Ferrous Smelting holds volume dominance. Non-Ferrous Smelting is expanding most quickly on battery material demand.
Delivery Mode:
Supply chain configuration separates integrated smelters receiving bulk rail and vessel shipments from smaller operators requiring packaged precision.
- Bulk:Unpackaged rail, barge, and pneumatic trailer delivery minimizing raw material cost for high-volume consumers.
- Packaged:Supersacks and drums enabling precise dosing for foundries and recycling facilities without bulk handling infrastructure.
- Liquid:Aqueous and solvent-based reagent solutions for automated dosing systems.
- Powder:Fine-grind materials for pneumatic injection and rapid dissolution in molten baths.
Bulk delivery commands tonnage share. Packaged formats are gaining share fastest among battery scrap processors and urban mining operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting smelting chemical procurement toward jurisdictions where emissions compliance costs remain manageable, accelerating capacity migration from mature markets to emerging processing corridors.
China
Domestic copper and nickel processors in Jiangxi and Shandong provinces are reformulating flux chemistries to meet MEE SO2 concentration limits. The dual carbon goals framework is prohibiting volatile organic carriers in traditional reductant packages. Smelters in the Yangtze River Delta industrial belt are redirecting procurement toward verified low-VOC suppliers to maintain operating permits.
Indonesia
Battery-grade nickel processing in Morowali and Weda Bay industrial zones is pulling demand for high-purity smelting chemicals upward. Domestic processing mandates and export restrictions are creating captive demand for localized chemical formulation facilities. Korean and Chinese cathode manufacturers have anchored multi-year supply agreements directly with processors in Obi Island, bypassing traditional distributor networks.
Germany
REACH restrictions and the EU Green Deal are forcing lead-zinc smelters to replace halogenated reagents with compliant alternative fluxes. ECHA enforcement is tightening on heavy-metal-containing additives in pyrometallurgical circuits. Specialty chemical producers in the North Rhine-Westphalia industrial corridor are securing formulation contracts from smelters pursuing CSRD-aligned environmental certification.
United States
EPA emissions standards for sulfur dioxide and particulate matter are shaping product formulation requirements across copper smelting operations. IRA clean manufacturing provisions are incentivizing domestic battery material supply chains that depend on high-purity nickel and copper extraction. Arizona and Nevada smelting clusters are adapting flux packages to meet combined federal and state air quality thresholds.
Australia
Complex sulfide ore processing in Western Australia's nickel-copper belt is shifting toward hydrometallurgical circuits requiring specialized additive packages. The country's national environmental regulator is tightening disclosure requirements for smelter emissions intensity. Perth-based mining chemical distributors are expanding technical service capabilities to support flash-smelting conversions in the Kalgoorlie region.
Smelting Chemicals Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers position near Indonesia's nickel processing corridor and China's reformulating smelter base. The market structure concentrates around integrated chemical conglomerates with mining sector portfolios, mid-tier regional specialists, and captive in-house formulation units at major smelters. Three archetypes define competitive positioning: diversified multinationals with customized reagent systems, regional suppliers anchored to specific ore chemistry requirements, and technology licensors monetizing process patents. Geographic expansion and portfolio diversification represent the dominant competitive vectors, with players racing to establish localized blending facilities before offtake contracts lock in.
Within the diversified multinational tier, BASF SE and Solvay occupy positions exemplifying integrated chemical supply to mining and metallurgical end-users. BASF SE represents the archetype of customized reductant and frother system supply for complex concentrate processing. Solvay anchors European supply chain security through soda ash and specialty reagent production. Among mid-tier specialists, Clariant sits within the flux segment with bentonite and organic binder technologies. These three entities illustrate how competitive positioning splits between scale-driven formulation breadth and technology-specific specialization.
| Leading Market Players |
|---|
| BASF SE |
| Solvay |
| Clariant |
| KGHM |
| Vedanta Limited |
| Boliden Group |
| Techint Group |
| Dow Chemical Company |
| Evonik Industries |
| Others |
Value Network & Pricing Analysis
Flash-smelting and hydrometallurgical circuit adoption across Indonesia's nickel processing corridor is compressing cost economics while concentrating procurement power among integrated cathode manufacturers, simultaneously reshaping supplier pricing leverage and feedstock sourcing patterns. Long-term offtake contracting between Korean battery makers and Morowali processors is displacing spot market liquidity, locking in volume commitments that marginalize smaller distributors.
Pricing Analysis
Distributor margins in traditional chemical supply chains are compressing as direct-to-smelter contracting proliferates. Contract-based long-term offtake dominates, with price differentiation driven by ISO 14001 certification tier and volume scale commitments. Pricing pressure stems from soda ash and carbonaceous reductant cost volatility linked to energy markets. Integrated metal manufacturers exhibit lowest price sensitivity due to pass-through mechanisms in cathode supply agreements, while smaller foundries face acute margin compression.
Supply Chain Analysis
ISO 14001 and MEE emissions compliance certification now gates supplier eligibility for Chinese and Indonesian smelter procurement. Geographic supply concentrates in China, Indonesia, and Germany for specialty flux formulations. Raw material dependencies include bentonite from specific mining districts, metallurgical coke from coking coal corridors, and high-purity soda ash from Solvay's European production. Single-source vulnerability characterizes specialty binder supply. Distribution runs through integrated processor direct contracts, bypassing traditional distributor networks in battery material corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in smelting chemicals rests on the shift from commodity flux sales toward certified, low-VOC formulation premiums, compounded by captive supply integration into Indonesia's nickel processing value chain.
For Market Incumbents: Cement market position through backward integration into bentonite mining districts and certification investment for MEE-compliant reductant lines. Direct-reduction iron substitution threatens traditional blast furnace flux volumes; counter by anchoring long-term supply agreements with Indonesian nickel processors before cathode maker consolidation completes. For New Entrants and Emerging Players: E-commerce technical service platforms offer a route to bypass entrenched distributor relationships in Southeast Asian recycling corridors. Target battery scrap processors in Indonesia's emerging urban mining zones, where packaged format demand outpaces local formulation capacity. Lead with on-site technical dosing support rather than price competition. For Investors and Strategic Acquirers: Roll-up economics work for regional specialty flux blenders because buyer consolidation among cathode manufacturers is fragmenting supplier relationships into discrete, acquirable contracts. Five-to-ten year viability favors operators with verified low-VOC product lines and Morowali corridor proximity. Watch for MEE enforcement acceleration in Shandong province as inflection signal for compliant supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bentonite Mining | Secures pellet strength formulation supply against concentrated mining district vulnerability. |
| Green Manufacturing Transition | MEE SO2 compliance unlocks operating permits for Jiangxi and Shandong copper smelters. |
| Long-term Supply Agreement | Korean cathode makers lock multi-year chemical offtake with Indonesian nickel processors. |
| Joint Venture | Localized blending facilities in Morowali corridor capture captive demand from export restrictions. |
| Capacity Expansion | Low-VOC reductant production scale-up serves China's dual carbon goals enforcement. |
Research Methodology
Bottom-up smelter consumption modeling reconciled against top-down chemical production tracking forms the analytical core of this study. Primary interviews with plant managers at Indonesian nickel processors, procurement leads at Korean cathode manufacturers, distribution channel partners in European lead-zinc corridors, and technical R&D directors at flux suppliers were cross-validated against secondary sources including customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from diversified chemical conglomerates, and MEE emissions disclosure databases.
Historical trendline analysis of flux and reductant consumption patterns across ferrous and non-ferrous smelting circuits informed the projection framework. Segmentation dimensions modeled include product type tier, end-use industry concentration, delivery mode format, and regional processing hub regulatory cluster. CAGRs were derived from slope analysis of technology adoption curves and contract volume disclosures. Key forecast inputs encompass hydrometallurgical circuit conversion rates in Indonesia and REACH compliance substitution timelines in Europe.
The model assumes a particular technology adoption path for flash-smelting and sensor-driven flux dosing; alternative pathways for bath smelting retention would alter the outlook. Forecasts reflect assumptions regarding MEE enforcement consistency, Indonesian export policy stability, and cathode material demand trajectories. A model refresh is warranted upon material change in China's dual carbon goals implementation intensity or battery scrap recycling regulatory frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Prebaked Anodes for Aluminum Market
Metals
China Neodymium Iron Boron Magnet Market
Metals
Galvanized Steel Market
Metals
Tinplate Market
Metals
Medical Metal Tubing Market
Metals
Europe Welding Consumables Market
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
Osmium Market
Metals
Neodymium Market
Metals
Metallurgical Coal Market
Metals
Steel Sheet for Home Appliances Market
Metals
Palladium Market
Metals
Arc Ferrite Magnet Market
Metals
Global Stainless Steel Lashing Wire Market
Metals
Seamless Stainless Steel Products Market
Metals
Global Nickel Alloy Welding Consumables Market