
 North America Aluminium Powder Market | 2026-2036
North America Aluminium Powder Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aluminium Powder Market Intelligence
Direct supply agreements between atomization plants and additive manufacturing service bureaus are reshaping how aluminium powder moves through North American industrial channels. Alcoa Corporation leverages captive bauxite-to-powder integration to control feedstock quality across its Appalachian operations. VALIMET, Inc. anchors its position through dedicated spherical powder capacity serving defense-qualified suppliers. Kymera International competes via multi-site atomization assets that reduce regional logistics exposure for chemical industry buyers.
Aluminium powder consists of finely divided metallic aluminium particles produced through gas or water atomization, typically ranging from 1 to 200 microns in diameter, with controlled oxide surface layers that determine reactivity in pyrotechnic and metallurgical applications. Its primary commercial purpose centers on powder metallurgy compaction, chemical process catalysis, and solid propellant formulation where high surface-area-to-mass ratios enable rapid energy release. Atomized powder dominates volume flows across North America due to established air and inert gas atomization infrastructure serving automotive press-and-sinter operations. Additive manufacturing represents the fastest-growing application segment, with aerospace parts qualification driving premium pricing for narrow particle-size-distribution spherical grades. Flake powder maintains mature demand in chemical industry pigment and pyrotechnic applications where lamellar geometry controls burn rates and reflectivity.
The US EPA enforces National Ambient Air Quality Standards for particulate matter that constrain open-atomization facility permitting, while OSHA's combustible dust standards mandate explosion protection systems across powder handling operations. These frameworks elevate capital requirements for new entrants and favor incumbents with installed environmental controls. Canada's PMRA regulates aluminium-based pesticide formulations that absorb a portion of regional flake powder output. Stakeholders must monitor evolving EPA New Source Performance Standards for secondary non-ferrous metals as these rules will determine whether Gulf Coast and Midwest producers can expand atomization capacity without prohibitively expensive baghouse and scrubber retrofits.
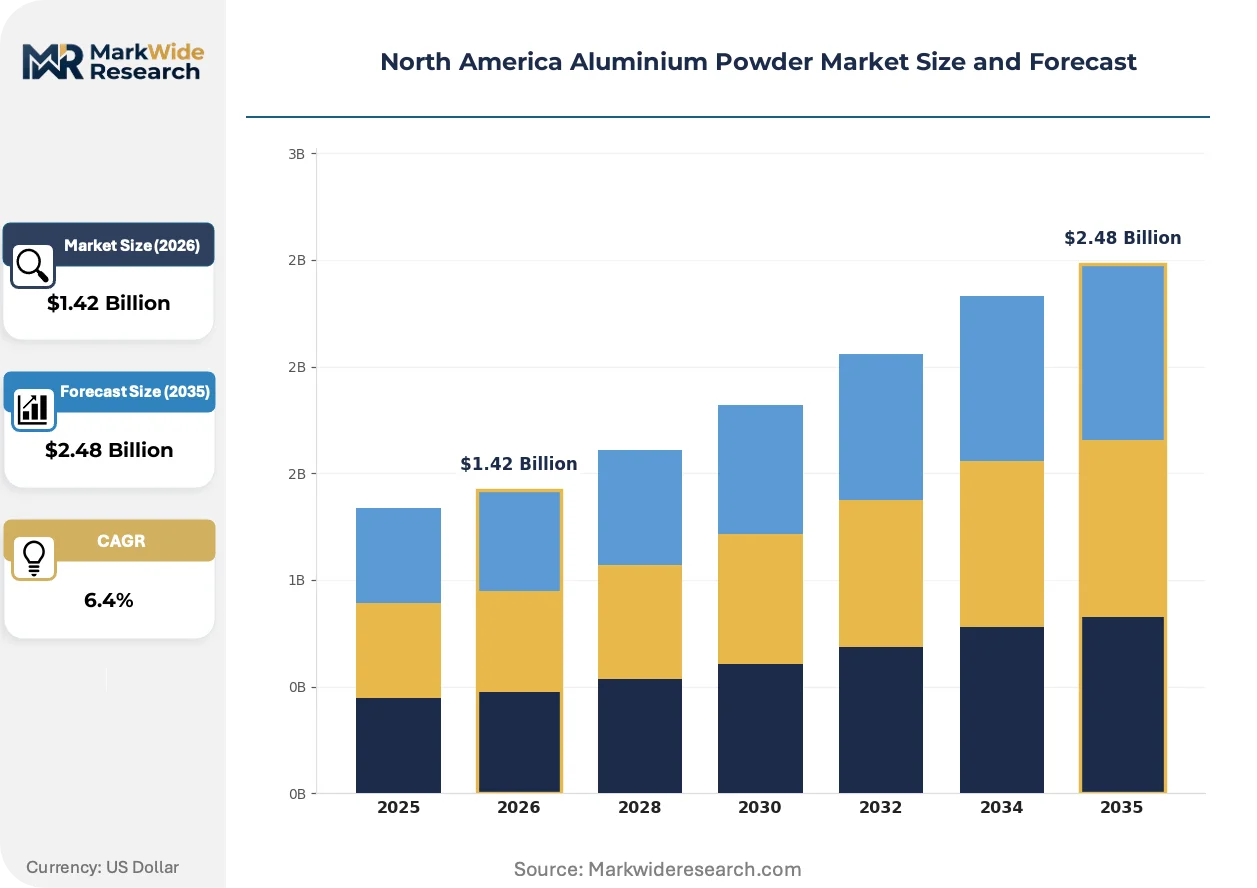
Market Dynamics
Closed-loop atomization systems are forcing capital reallocation across North American aluminium powder production as EPA particulate standards tighten permitting thresholds for new capacity additions.
Growth Catalysts
- Electric vehicle battery pack housings:Powder metallurgy compaction techniques enable lightweight structural components that improve vehicle range metrics. Automotive OEMs in Michigan and California are qualifying press-and-sinter suppliers for 2026 platform launches.
- OSHA combustible dust standards:Mandated explosion protection systems in powder handling operations are accelerating facility consolidation among compliant incumbents with installed infrastructure.
- Gulf Coast industrial corridor concentration:Overlapping chemical processing and aerospace clusters in Texas and Louisiana generate localized demand density that reduces logistics costs for spherical grade distribution.
Market Restraints
- Alumina feedstock volatility:Bauxite refining capacity constraints and energy cost spikes in primary aluminium smelting transmit directly to atomization plant input costs.
- Midwest-Gulf Coast supply concentration:Over 70% of North American atomization capacity sits within 800 miles of Pittsburgh or Houston, creating regional disruption exposure from hurricane or winter storm events.
- Open-atomization permitting friction:EPA New Source Performance Standards for secondary non-ferrous metals impose multi-year approval timelines that deter greenfield investments.
Strategic Opportunities
- Canadian additive manufacturing expansion:Montreal and Toronto aerospace clusters lack qualified spherical powder suppliers within 500 miles, creating white space for dedicated atomization assets.
- Dual-use defense qualification pathways:Department of Defense supplier certification requirements for solid propellant applications enable premium pricing capture for narrow particle-size-distribution grades.
- Closed-loop water atomization retrofit incentives:State-level industrial efficiency programs in Ohio and Pennsylvania subsidize environmental control upgrades that reduce particulate emissions below federal thresholds.
Industry Challenges
- Additive manufacturing metallurgist scarcity:Qualification of aerospace parts requires specialized expertise in laser powder bed fusion parameter development that outpaces technical training program output.
- Spherical powder certification timelines:FAA and DoD material qualification protocols demand 18-36 month validation cycles that delay revenue recognition for new production lines.
- Legacy flake powder asset stranding:Chemical industry pigment demand stagnation threatens utilization rates at facilities configured for lamellar geometry production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aluminium Powder Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atomized Powder, Flake Powder, Granulated Powder, Spherical Powder Application: Automotive Components, Aerospace Parts, Chemical Industry, Additive Manufacturing Packaging Type: Bulk Bags, Drums, Bags, Containers End User: Manufacturers, Research Institutions, Construction Industry, Metal Fabricators |
| Companies Covered | Alcoa Corporation, VALIMET, Inc., AMPAL Inc., Toyal America, Inc., NovaCentrix, Kymera International, ECKA Granules, United States Metal Powders, Inc., AMG Advanced Metallurgical Group NV, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aluminium Powder Market Strategic Shifts & Innovations
Plasma spheroidization technology is collapsing cost structures for premium additive manufacturing feedstock while regulatory pressure on particulate emissions accelerates process chemistry innovation across atomization methods.
Plasma spheroidization converts irregular atomized particles into near-perfect spheres through high-temperature thermal treatment. Aerospace tier-1 suppliers and medical implant manufacturers are adopting plasma-treated powder at triple-digit annual growth rates for laser powder bed fusion applications. This process is collapsing the historical 40-60% price premium for spherical grades over irregular atomized powder, compressing margin structures for incumbent gas atomization specialists.
EPA New Source Performance Standards for secondary non-ferrous metals production impose stringent baghouse and wet scrubber requirements on new atomization facilities. The rulemaking elevates capital intensity for capacity expansion while grandfathering existing installations with dated environmental controls. Gulf Coast producers with pre-2020 permits are accelerating throughput at legacy assets before potential regulatory retrofit mandates take effect.
Direct mill-to-print supply contracts are displacing traditional distributor intermediaries in additive manufacturing feedstock procurement. Large-format service bureaus in Texas and California are negotiating multi-year offtake agreements with atomization plants, securing volume commitments and lot traceability that powder brokers cannot match. This channel compression is most visible in defense and space verticals where material pedigree documentation requirements exceed commercial distributor capabilities.
North America Aluminium Powder Market Segmentation
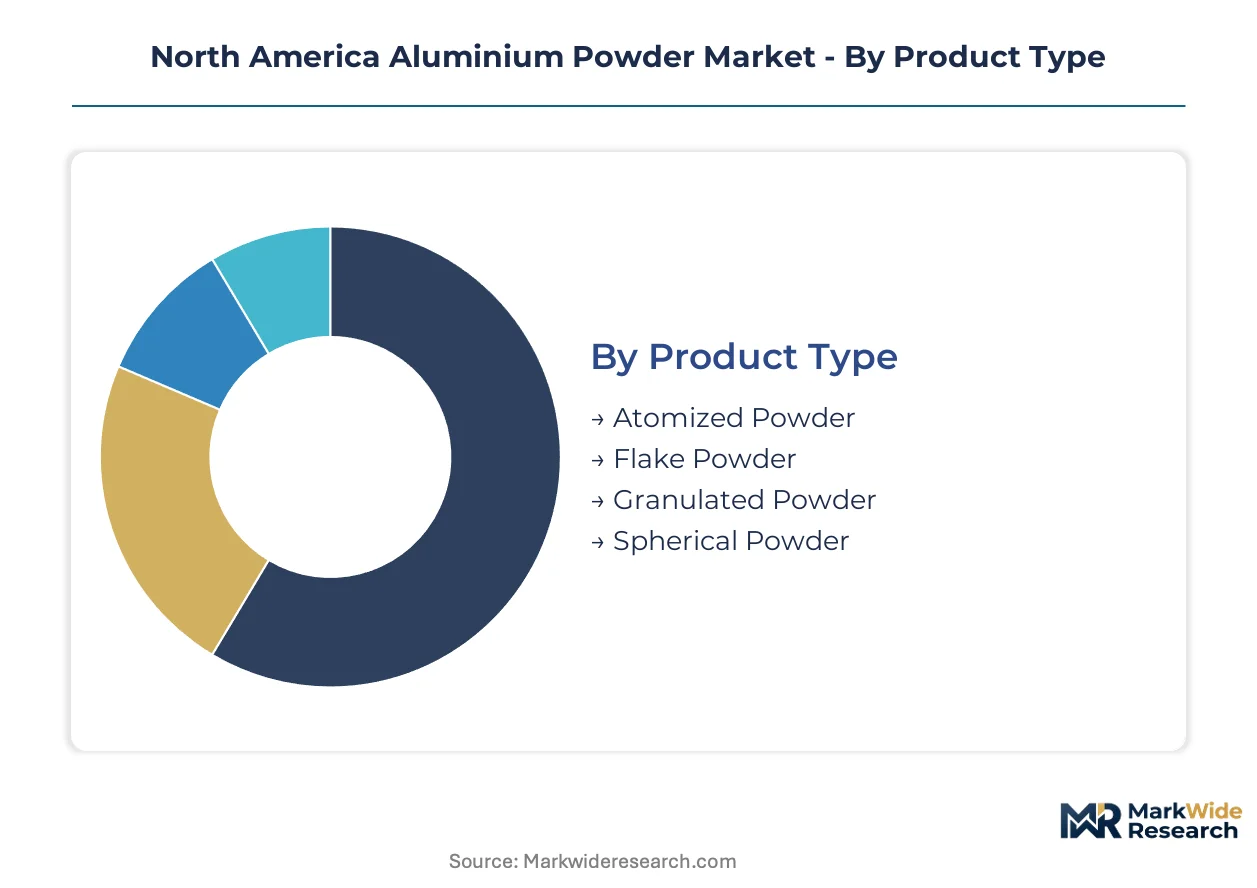
Aluminium powder demand fragments across distinct technical specifications and end-use requirements. Each segment category reflects divergent atomization methods, handling protocols, and qualification standards that shape procurement patterns across North American industrial channels.
Product Type:
Cost tier differentiation separates commodity-grade irregular particles from premium spherical grades commanding specialized atomization investments.
- Atomized Powder:Irregular particles produced through air or inert gas atomization dominate volume flows across automotive press-and-sinter operations. Michigan and Ohio automotive suppliers consume substantial tonnages for transmission and engine components where surface finish tolerances permit non-spherical geometries. EPA particulate emission standards constrain new open-atomization capacity additions.
- Spherical Powder:Near-perfect spherical morphology achieved through advanced gas atomization or plasma spheroidization serves laser powder bed fusion applications. Aerospace tier-1 suppliers in California and Texas drive qualification protocols for narrow particle-size-distribution grades. Plasma spheroidization retrofits are compressing historical price premiums for these grades.
- Flake Powder:Lamellar particles produced via ball milling or stamping mill processes supply chemical pigment and pyrotechnic applications where high aspect ratios control reflectivity and burn rates.
- Granulated Powder:Agglomerated fine particles formed into free-flowing granules improve handling characteristics for chemical process applications and metallurgical flux formulations.
Atomized powder holds installed capacity. Spherical powder is rotating up the share rankings.
Application:
Application focus determines specification stringency, with aerospace and additive manufacturing imposing material pedigree requirements that commodity automotive applications do not.
- Additive Manufacturing:Laser powder bed fusion and directed energy deposition processes demand tight particle-size distributions and low satellite content. Texas and California service bureaus negotiate direct mill-to-print contracts bypassing traditional distributor channels. FAA part qualification timelines extend 18-36 months for flight-critical components.
- Automotive Components:Press-and-sinter powder metallurgy enables lightweight structural parts for electric vehicle battery pack housings. OEM qualification programs in Michigan target platform launches requiring consistent lot-to-lot chemistry. Powder metallurgy compaction techniques improve vehicle range metrics through mass reduction.
- Aerospace Parts:Solid propellant formulations and structural components require defense-qualified suppliers with documented thermal and chemical property histories. Department of Defense certification enables premium pricing capture.
- Chemical Industry:Catalytic applications and pigment formulations absorb flake and irregular powder grades where surface area drives reaction kinetics.
Automotive components hold installed capacity. Additive manufacturing is rotating up the share rankings.
Packaging Type:
Volume scale and handling automation requirements separate bulk industrial shipments from precision-weighed laboratory containers.
- Bulk Bags:One-ton flexible intermediate bulk containers serve high-volume automotive and chemical processors with automated conveying systems. Gulf Coast chemical clusters prefer bulk formats to minimize handling labor.
- Drums:Steel and fiber drums provide moisture protection and UN certification for hazardous material shipping. Additive manufacturing service bureaus favor drum packaging for lot traceability and contamination control.
- Bags:Multi-wall paper and polymer bags suit mid-volume metal fabricators and construction applications where fork truck access is limited.
- Containers:Specialized gas-tight and vacuum-sealed containers preserve spherical powder quality for aerospace and medical implant applications requiring ultra-low moisture content.
Bulk bags hold installed capacity. Containers are rotating up the share rankings.
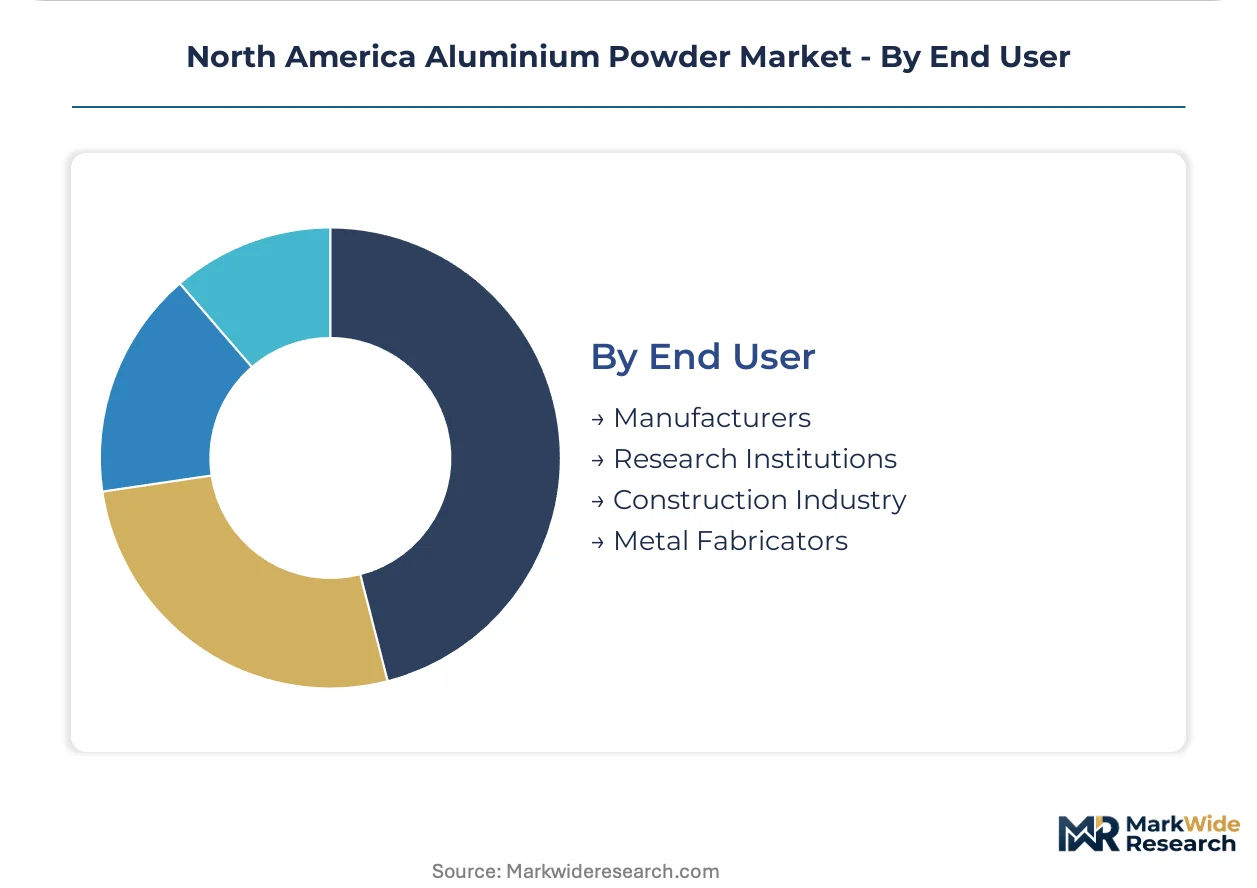
End User:
Customer type governs procurement sophistication, with defense-qualified manufacturers demanding documentation that research institutions and construction buyers do not require.
- Manufacturers:Tier-1 automotive and aerospace producers enforce statistical process control and lot traceability requirements. Direct supply agreements with atomization plants are displacing distributor intermediaries for volume accounts.
- Metal Fabricators:Job shops and specialty metalworkers purchase smaller quantities for thermal spray coatings and brazing paste formulations. Regional logistics exposure drives preference for multi-site atomization suppliers.
- Research Institutions:National laboratories and university materials science departments source experimental quantities for alloy development and process parameter studies.
- Construction Industry:Grout and concrete admixture applications consume lower-purity grades where oxide content does not compromise performance.
Manufacturers hold installed capacity. Metal fabricators are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical pipeline network and Great Lakes rail corridors lock in North America's aluminium powder distribution architecture, with atomization capacity clustering around Houston and Pittsburgh to exploit these freight arteries.
United States
Automotive powder metallurgy in Michigan and aerospace additive manufacturing in California absorb the majority of spherical grade output. EPA New Source Performance Standards for secondary non-ferrous metals impose multi-year permitting timelines on new atomization facilities. The Texas-Louisiana industrial corridor concentrates chemical processing demand that pulls flake and irregular powder grades through Gulf Coast ports.
Canada
Montreal and Toronto aerospace clusters generate unmet demand for qualified spherical powder suppliers within 500 miles. Health Canada's PMRA regulates aluminium-based pesticide formulations that consume a portion of regional flake powder production. Quebec's hydroelectric grid supports energy-intensive atomization operations with lower carbon intensity than US Gulf Coast alternatives.
Mexico
Automotive OEM assembly plants in Nuevo León and Guanajuato are qualifying North American powder metallurgy suppliers for transmission component sourcing. Mexico's environmental regulator SEMARNAT enforces air quality standards that constrain open-atomization facility permitting near Monterrey. The Bajío Region's growing aerospace supplier base creates inbound logistics demand for US-produced spherical grades.
North America Aluminium Powder Market Key Industry Players
On the supply side, the industry is consolidating around integrated aluminium producers and specialized atomization specialists with installed environmental controls. Three strategic archetypes dominate: captive bauxite-to-powder integrators, dedicated spherical powder specialists, and multi-site regional suppliers. Competitive moves center on direct mill-to-print supply contracts and closed-loop atomization retrofits to secure EPA permitting advantages.
Among integrated aluminium producers, Alcoa Corporation exemplifies the captive feedstock archetype through Appalachian bauxite-to-powder operations. VALIMET, Inc. occupies a specialist position serving defense-qualified additive manufacturing suppliers with dedicated spherical capacity. Kymera International anchors the multi-site regional model, reducing logistics exposure for chemical industry buyers through distributed atomization assets.
| Leading Market Players |
|---|
| Alcoa Corporation |
| VALIMET, Inc. |
| AMPAL Inc. |
| Toyal America, Inc. |
| NovaCentrix |
| Kymera International |
| ECKA Granules |
| United States Metal Powders, Inc. |
| AMG Advanced Metallurgical Group NV |
| Others |
Cost & Logistics Intelligence
Undercapacity in spherical powder atomization across the US Gulf Coast and Midwest corridors grants incumbent producers pricing leverage over aerospace and additive manufacturing buyers. EPA permitting friction constrains new capacity additions while plasma spheroidization retrofits compress historical grade premiums. Suppliers with installed environmental controls exploit this scarcity to enforce volume-commitment contracts with tier-1 manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs aluminium powder transactions. Premium spherical grades command elevated pricing based on FAA and DoD certification pedigree plus narrow particle-size-distribution tolerances. Cost compression in standard atomized grades is intensifying because plasma spheroidization retrofits collapse the historical premium for near-spherical morphology. Automotive press-and-sinter buyers exhibit highest price sensitivity due to commodity-grade specifications, while defense-qualified additive manufacturing suppliers show lowest sensitivity given material pedigree requirements.
Supply Chain Analysis
Export controls on plasma spheroidization equipment limit technology transfer to non-allied manufacturing jurisdictions. Primary supply concentration rests on the United States, Canada, and Mexico under the USMCA framework. Raw material flows draw from bauxite refining capacity in Jamaica and Guinea plus domestic alumina processing. Single-source vulnerability persists in spherical powder qualification expertise concentrated among defense-cleared suppliers. Distribution runs through direct mill-to-print contracts displacing traditional powder broker intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where material qualification support and lot-traceability documentation generate recurring revenue streams expanding faster than base powder tonnage. After-sales technical services for laser powder bed fusion parameter development capture margin unavailable to commodity suppliers.
For Market Incumbents: Build regulatory-permit moats by accelerating closed-loop atomization retrofits ahead of potential EPA New Source Performance Standards mandates. Consolidate position through captive bauxite-to-powder integration securing feedstock quality continuity. Plasma spheroidization technology access represents the critical lever for margin defense against gas atomization specialists. For New Entrants and Emerging Players: Canadian aerospace cluster underpenetration offers qualified spherical powder supply white space within 500 miles of Montreal and Toronto demand centers. Target state-level industrial efficiency programs in Ohio and Pennsylvania subsidizing environmental control upgrades as capital formation angle. Pursue dual-use defense qualification pathways enabling premium pricing capture unavailable to commercial-grade competitors. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because atomization asset scarcity under tightening EPA particulate standards favors scale operators with installed baghouse infrastructure. Acquisition targets cluster around multi-site regional suppliers with distributed logistics networks reducing hurricane and winter storm disruption exposure. Monitor FAA part qualification timeline compression as inflection signal for spherical powder demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-loop Atomization Retrofit | EPA New Source Performance Standards compliance secures permitting advantage for capacity expansion. |
| Plasma Spheroidization Capacity Addition | Collapses spherical grade cost structures threatening incumbent gas atomization margin structures. |
| Direct Mill-to-Print Supply Contract | Bypasses distributor intermediaries capturing lot traceability value in defense verticals. |
| Defense Qualification Pathway Investment | DoD certification enables premium pricing capture for narrow particle-size-distribution grades. |
| Canadian Atomization Asset Deployment | Montreal-Toronto aerospace cluster proximity reduces logistics costs for spherical powder distribution. |
Research Approach
Desk research of SEC 10-K filings, customs and trade databases, and EPA regulatory dockets preceded structured interviews with atomization plant managers, aerospace tier-1 procurement leads, additive manufacturing service bureau operators, and chemical industry purchasing directors. Bottom-up capacity and utilization estimates triangulated against top-down demand segmentation across product type, application, and end-user categories.
Assumptions held fixed include EPA New Source Performance Standards enforcement timelines and USMCA aluminum tariff structures, while energy cost trajectories and electric vehicle platform launch schedules varied across sensitivity scenarios. Segmentation modeling captured atomization method, particle morphology, certification tier, packaging format, and regional production cluster dimensions. CAGRs derived from historical volume elasticities applied to projected electric vehicle battery pack housing and additive manufacturing adoption curves.
Practitioners should monitor EPA enforcement discretion on grandfathered pre-2020 permits and plasma spheroidization equipment export licensing shifts for early signals of supply disruption. Forecasts reflect these documented assumptions regarding regulatory trajectory and technology diffusion rates. Material shifts in EPA retrofit mandate timing or defense qualification protocol streamlining would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminum Extrusion Market
Metals
Aluminum Welding Market
Metals
Global Aluminum Market
Metals
Carbon Steel Market
Metals
Ferrochrome Market
Metals
Copper Powder Market
Metals
Copper and Copper Alloy Foil Market
Metals
Recycled Metal Market
Metals
North America Metal Casting Market
Metals
Silver Nitrate Market
Metals
Wear Steel Plate Market
Metals
Beryllium Copper Billet Market
Metals
Ferro Vanadium Market
Metals
Anodized Titanium Market
Metals
Tin Chloride Market
Metals
China Neodymium Iron Boron Magnet Market