
 Ruthenium Market | 2026-2036
Ruthenium Market Size, Share, and Industry Trends Forecast 2026-2036
Ruthenium Market Outlook
South Africa is tilting the supply landscape through beneficiation policies that push local refining of platinum-group metals before export. Johnson Matthey leverages its integrated precious metals complex in Royston to secure captive ruthenium streams for catalyst production. Anglo American sustains upstream dominance through its Mogalakwena and Amandelbult mine complexes, which yield ruthenium as a by-product of platinum extraction. Sibanye-Stillwater competes through its US-based Stillwater mine, the only primary source of platinum-group metals outside southern Africa.
Ruthenium is a hard, brittle transition metal with atomic number 44, melting point 2,334°C, and exceptional corrosion resistance even at elevated temperatures; it serves primarily as an alloying agent, catalyst, and thin-film material in semiconductor manufacturing. Ruthenium metal occupies the highest margin tier due to stringent purity requirements for sputtering targets used in extreme ultraviolet lithography. Catalysts represent the fastest-growing application segment as hydrogen economy infrastructure expands, while ruthenium compounds retain stable demand from the chemical industry for olefin metathesis processes.
REACH registration in Europe mandates full substance characterization for ruthenium salts imported above one tonne annually, raising compliance costs for non-EU suppliers. The EPA Office of Chemical Safety and Pollution Prevention monitors ruthenium tetroxide under the Toxic Substances Control Act due to its volatility and respiratory toxicity. Stakeholders must monitor how the EU Critical Raw Materials Act reclassifies platinum-group metals, as this will reshape offtake obligations and strategic stockpiling requirements across the value chain.
Market Dynamics
Semiconductor node shrinkage below 3 nanometers is forcing a wholesale transition from copper to ruthenium interconnects, compressing deposition process windows and elevating purity specifications across the entire supply base.
Growth Catalysts
- EUV Lithography Expansion:Sputtering targets for extreme ultraviolet systems now require 99.999% purity ruthenium, pulling volumes from traditional chemical applications into semiconductor fabrication lines.
- REACH Substance Characterization:ECHA registration mandates for ruthenium salts above one tonne annually are consolidating supplier bases toward integrated refiners with in-house analytical capabilities.
- Hydrogen Economy Infrastructure:Proton exchange membrane electrolyzers are incorporating ruthenium-iridium catalyst coatings for oxygen evolution reactions, opening dedicated offtake agreements with renewable hydrogen developers.
Market Restraints
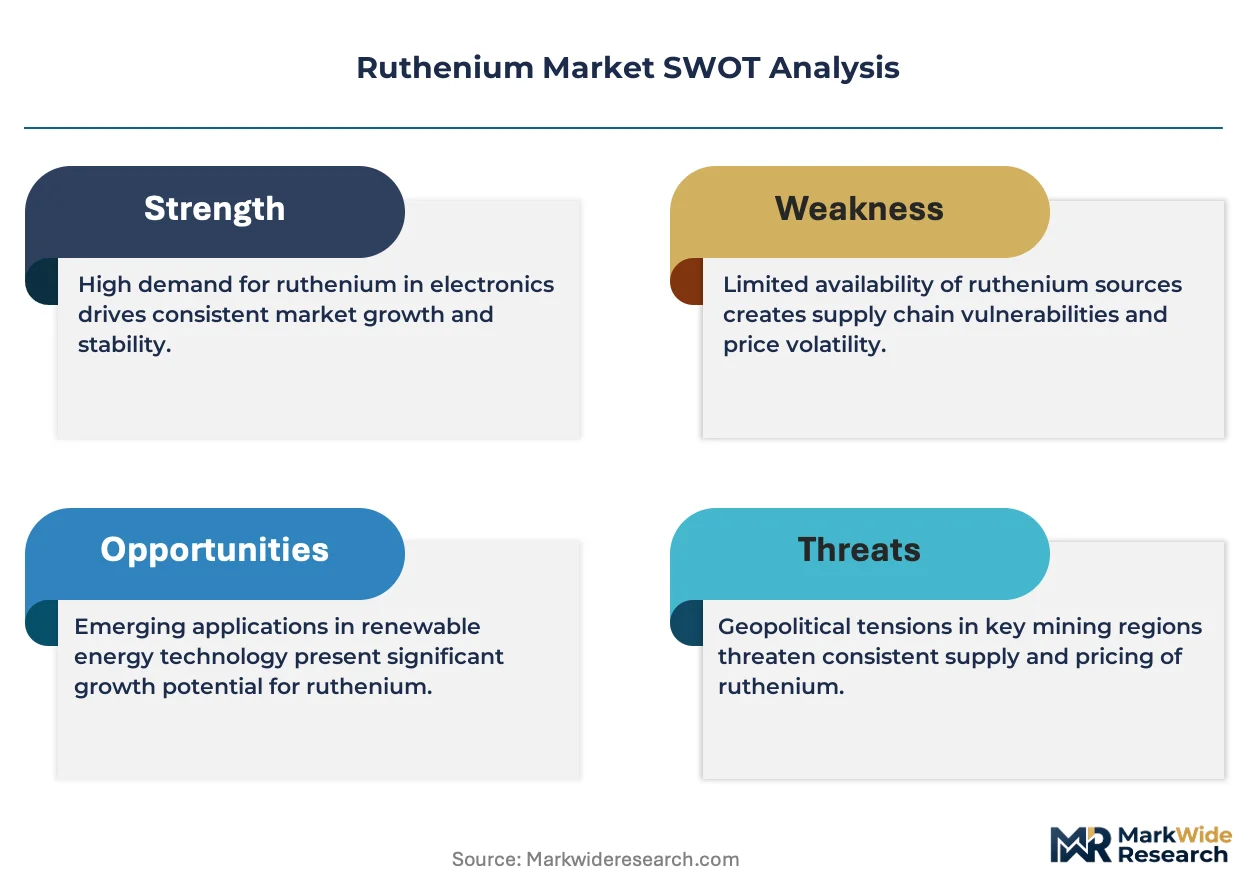
- By-Product Supply Dependency:Ruthenium output remains captive to platinum and palladium mining economics at South Africa's Bushveld Complex and Russia's Norilsk operations, decoupling price formation from direct demand signals.
- Volatility of Ruthenium Tetroxide:OSHA respiratory exposure limits and EPA TSCA monitoring requirements impose specialized handling infrastructure costs that exclude smaller chemical processors from the market.
- Iridium Substitution in Catalysis:Chlor-alkali membrane cells are partially migrating to iridium-based anode coatings where ruthenium supply tightness disrupts long-term catalyst procurement contracts.
Strategic Opportunities
- Domestic Refining Partnerships in South Korea:Samsung and SK Hynix are constructing captive precious metal recovery facilities to bypass concentrated South African export channels.
- EU Critical Raw Materials Act Reclassification:Strategic stockpiling obligations for platinum-group metals will reshape offtake commitments and create preferential access tiers for European semiconductor fabricators.
- Atomic Layer Deposition Convergence:ALD precursors combining ruthenium with hafnium or zirconium oxides are enabling 2D material integration for gate-all-around transistor architectures.
Industry Challenges
- Plasma Etch Chemistry Expertise Gap:Semiconductor fabs lack process engineers trained in ruthenium-specific reactive ion etch recipes, extending yield ramp timelines at advanced nodes.
- Multi-Jurisdictional Certification Timelines:Simultaneous EPA TSCA pre-manufacture notices, ECHA REACH dossiers, and MFDS chemical substance registrations extend new compound commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ruthenium Market |
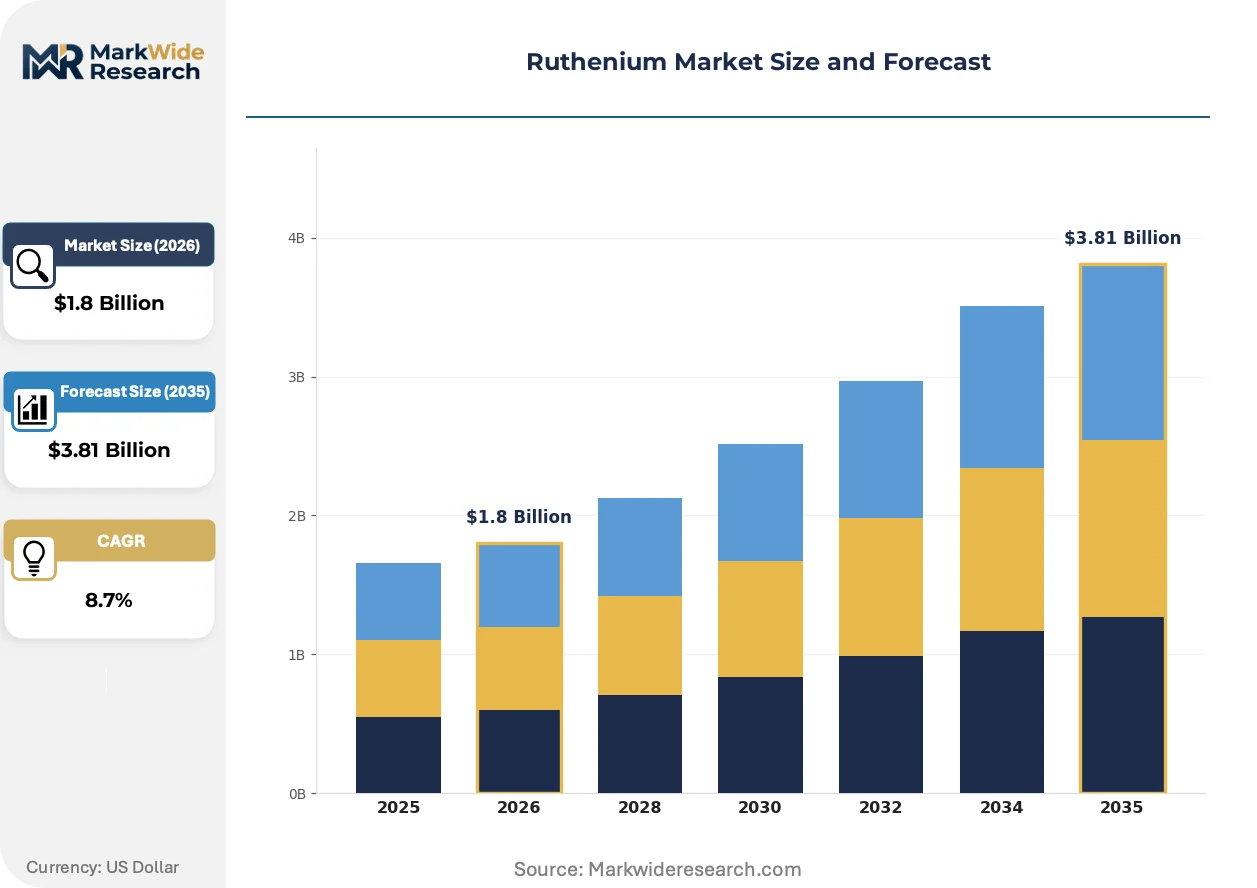
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ruthenium Powder, Ruthenium Salt, Ruthenium Metal, Ruthenium Compound Application: Catalysts, Electronics, Biomaterials, Chemical Processing End User: Electronics Industry, Chemical Industry, Automotive Sector, Medical Field Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Johnson Matthey, Anglo American, Sibanye-Stillwater, American Elements, Heraeus, Umicore, Impala Platinum Holdings Limited, TANAKA Holdings Co., Ltd., FURUYA METAL Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ruthenium Market Strategic Shifts
Process integration constraints at sub-3nm nodes are accelerating materials science investment, while regulatory frameworks recalibrate supply security priorities across major consuming regions.
Atomic layer deposition ruthenium is migrating from experimental interconnect seed layers to production-worthy gapfill applications in high-aspect-ratio vias. TSMC and Intel are qualifying ALD ruthenium for their respective 2nm-class processes, compressing the technology adoption cycle from five years to under three. The shift is displacing chemical vapor deposition tools and forcing equipment makers to redesign precursor delivery systems for lower-temperature processing.
REACH authorization requirements for ruthenium trichloride and related salts are tightening substance volume tracking across the European chemical industry. ECHA's 2024 updated guidance on metal compound hazard classification is forcing reformulation of olefin metathesis catalysts used in pharmaceutical intermediate manufacturing. German and Dutch fine chemical producers are consolidating supplier audits to reduce compliance documentation burdens.
Long-term offtake contracting is displacing spot market purchasing among semiconductor materials buyers. Memory manufacturers in South Korea and Taiwan are negotiating five-year supply agreements directly with Anglo American and Johnson Matthey, bypassing traditional precious metal traders. This behavioral shift concentrates procurement leverage among the three largest DRAM and NAND producers, compressing margins for intermediate distributors in Singapore and Hong Kong.
Ruthenium Market Segmentation
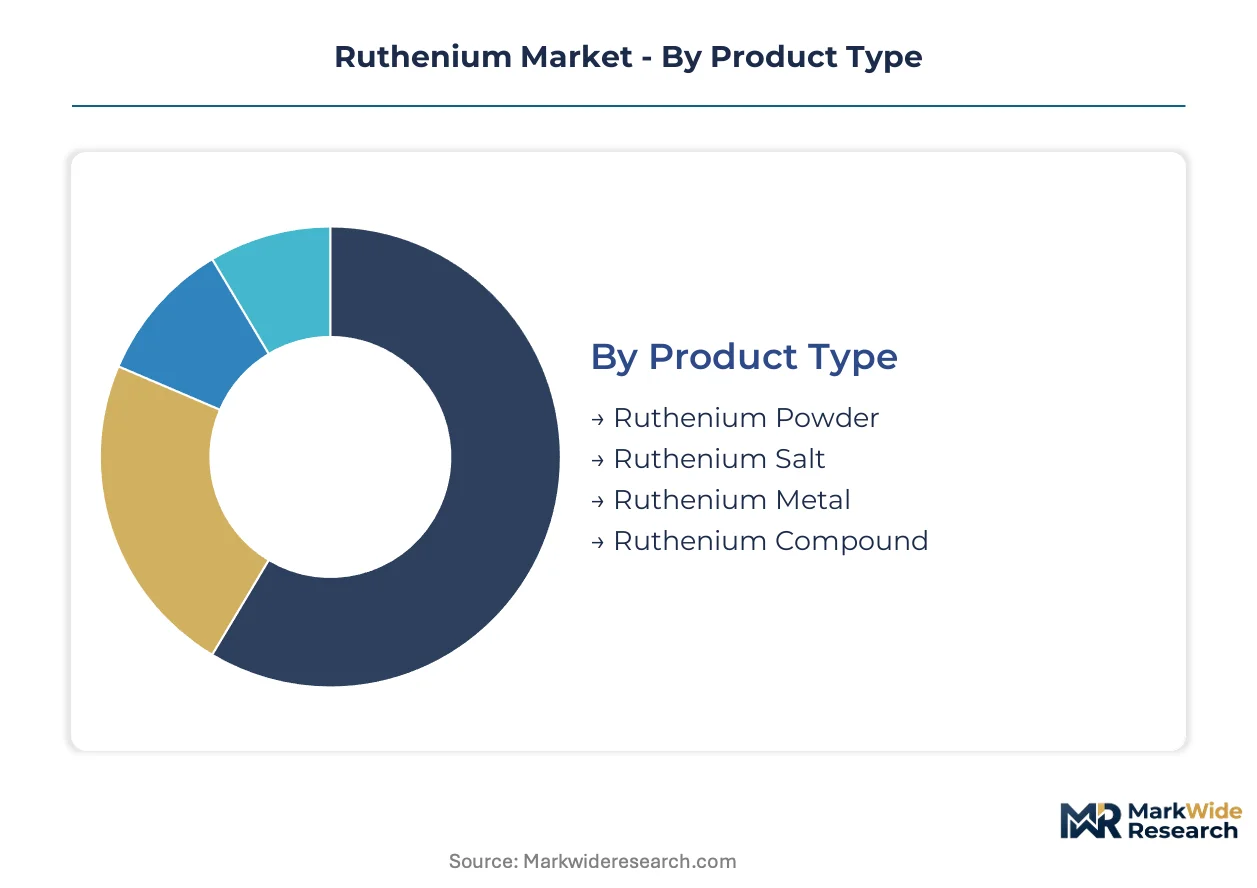
Ruthenium's value chain fragments across four distinct dimensions, each with divergent margin profiles and inventory velocity. Product form determines purification intensity, while application mix dictates exposure to semiconductor cycle volatility versus hydrogen infrastructure build-out.
Product Type:
Cycle times vary dramatically across product forms, with powder and salts turning over quarterly for chemical processors while metal ingots for sputtering targets sit in qualification pipelines for 18-24 months.
- Ruthenium Metal:99.999% purity ingots and sputtering targets command the highest margin tier in the value chain. TSMC and Intel qualification programs for extreme ultraviolet lithography systems are absorbing incremental output from South African refiners, compressing availability for legacy chemical applications.
- Ruthenium Powder:Sponge and micronized grades serve chlor-alkali anode coating and hard disk drive platter manufacturing. Johnson Matthey's Royston complex processes powder streams for catalyst precursors, with lot-to-lot consistency requirements tightening under REACH substance characterization mandates.
- Ruthenium Salt:Ruthenium trichloride and nitrosyl nitrate solutions feed olefin metathesis catalyst synthesis for pharmaceutical intermediates. ECHA registration dossiers above one tonne annually are consolidating supplier bases toward integrated refiners with in-house analytical capabilities.
- Ruthenium Compound:Organometallic precursors for atomic layer deposition are gaining traction as semiconductor nodes shrink below 3 nanometers. Hafnium-ruthenium oxide combinations are emerging for gate-all-around transistor architectures.
Ruthenium metal anchors the volume base while ruthenium compounds gain share at the steepest rate.
Application:
Cost tier stratification separates commodity catalyst consumption from premium semiconductor materials, with a tenfold purity differential driving price separation.
- Catalysts:Chlor-alkali membrane cells and hydrogen electrolyzer anode coatings represent the largest volume sink. Proton exchange membrane systems are incorporating ruthenium-iridium oxygen evolution coatings, opening dedicated offtake agreements with renewable hydrogen developers in Germany and Japan.
- Electronics:Extreme ultraviolet lithography sputtering targets and atomic layer deposition precursors sit at the apex of the value chain. Samsung and SK Hynix are negotiating five-year supply agreements directly with Anglo American, bypassing Singapore precious metal traders.
- Biomaterials:Ruthenium complexes for photodynamic therapy and radiopharmaceutical labeling occupy niche volumes with extended regulatory timelines. FDA and EMA clinical trial requirements stretch commercialization cycles to 7-10 years.
- Chemical Processing:Olefin metathesis catalysts for fine chemical synthesis face reformulation pressure under ECHA's updated metal compound hazard classification guidance. German and Dutch producers are consolidating supplier audits to reduce compliance documentation burdens.
Catalysts anchor the volume base while electronics gains share at the steepest rate.
End User:
Customer concentration intensifies toward semiconductor memory manufacturers, with procurement leverage consolidating among three dominant DRAM and NAND producers.
- Electronics Industry:Memory fabs in South Korea and Taiwan are constructing captive precious metal recovery facilities to bypass concentrated South African export channels. Long-term offtake contracting is displacing spot market purchasing across the sector.
- Chemical Industry:Chlor-alkali producers and fine chemical manufacturers face iridium substitution pressure where ruthenium supply tightness disrupts catalyst procurement contracts. BASF and Evonik are dual-sourcing strategies across South African and Russian supply channels.
- Automotive Sector:Hydrogen fuel cell stack manufacturers are qualifying ruthenium-iridium catalyst coatings for proton exchange membrane systems. Toyota and Hyundai are securing dedicated supply lines for electrolyzer and fuel cell production scaling.
- Medical Field:Radiopharmaceutical developers and oncology device manufacturers source ruthenium complexes for targeted therapy applications. Supply security priorities are elevating under the EU Critical Raw Materials Act reclassification discussions for platinum-group metals.
The chemical industry anchors the volume base while the electronics industry gains share at the steepest rate.
Distribution Channel:
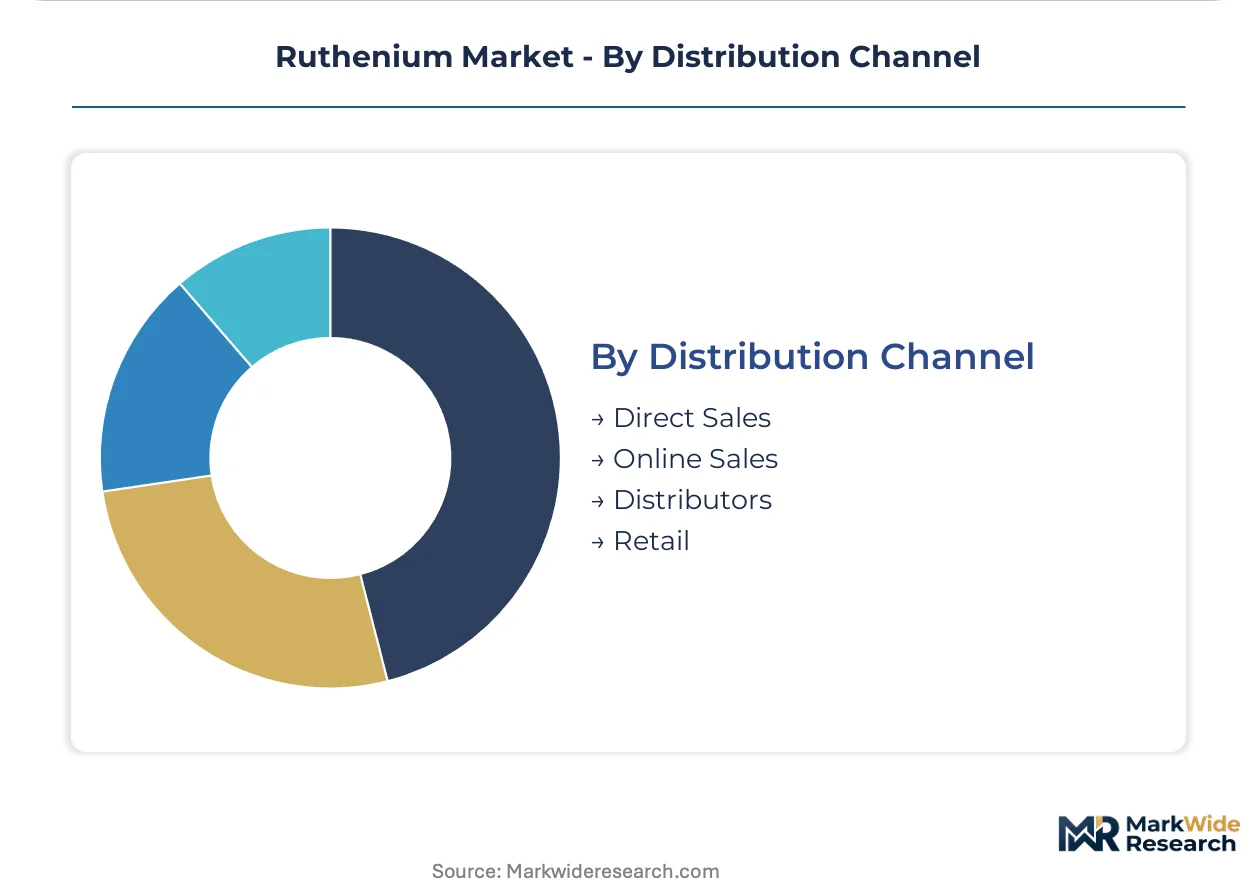
Channel economics reflect lot size and certification intensity, with direct sales capturing high-purity semiconductor volumes while distributors handle fragmented chemical industry accounts.
- Direct Sales:Anglo American and Johnson Matthey are negotiating multi-year supply agreements directly with Samsung, SK Hynix, and TSMC. This channel captures 99.999% purity metal and precursor volumes with dedicated logistics and documentation packages.
- Distributors:Singapore and Hong Kong precious metal traders are compressing margins as procurement leverage concentrates among memory manufacturers. Remaining distributor value concentrates on smaller chemical processors and regional alloy blenders.
- Online Sales:Laboratory-grade salts and research quantities are migrating to specialized chemical procurement platforms. ECHA REACH compliance documentation is becoming a table-stakes requirement for platform listing.
- Retail:Investment-grade ruthenium bars and numismatic products occupy negligible volume. This channel serves collector demand with premiums disconnected from industrial pricing benchmarks.
Direct sales anchors the volume base while distributor share contracts under customer consolidation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea consumes ruthenium predominantly for semiconductor interconnects, while Germany channels volumes into hydrogen electrolyzer catalysts, and South Africa retains upstream control through beneficiation mandates that reshape export flows.
South Korea
Samsung and SK Hynix are expanding domestic precious metal refining partnerships to secure sputtering target supply for sub-3nm processes. MFDS chemical substance registrations govern ruthenium precursor imports above specified thresholds. The Seoul Capital Area hosts concentrated DRAM and NAND fabrication complexes where captive recovery facilities are under construction.
Germany
BASF and Evonik are dual-sourcing ruthenium-iridium catalyst precursors for proton exchange membrane electrolyzer scaling. ECHA REACH authorization requirements for ruthenium trichloride are consolidating supplier audits among Rhine-Ruhr chemical producers. The Ludwigshafen and Marl industrial clusters are negotiating long-term offtake agreements directly with South African refiners.
South Africa
Beneficiation policies mandate local refining of platinum-group metals before export, tilting supply leverage toward domestic processors. The Department of Mineral Resources and Energy enforces export permit conditions that elevate value-added product thresholds. The Bushveld Complex around Rustenburg and Polokwane yields ruthenium as a by-product of platinum extraction at Anglo American's Mogalakwena operations.
United States
Intel and Applied Materials are qualifying ALD ruthenium precursors for 2nm-class process ramps at Arizona and Oregon fabs. EPA TSCA pre-manufacture notice requirements extend new compound commercialization timelines for organometallic precursors. The Pacific Northwest semiconductor corridor is attracting precious metal logistics investments to bypass Asian distribution hubs.
Japan
Toyota and Hyundai suppliers are securing dedicated ruthenium-iridium supply lines for fuel cell stack manufacturing scaling. METI hydrogen roadmap targets are accelerating electrolyzer catalyst procurement from domestic trading houses. The Kansai industrial belt around Osaka maintains specialized handling infrastructure for ruthenium tetroxide under OSHA-aligned respiratory exposure protocols.
Ruthenium Market Competitive Environment
Capability concentration sits with integrated refiners possessing in-house analytical and purification infrastructure; scale advantage sits with diversified mining conglomerates capturing ruthenium as a by-product of platinum operations. The market structures around three archetypes: upstream miners with captive metal streams, integrated refiners with precious metals complexes, and specialized chemical processors with precursor formulation expertise. Competitive moves center on backward integration into refining capacity and long-term offtake contracting that displaces spot market purchasing.
Among integrated precious metals refiners, Johnson Matthey and Heraeus exemplify the capability-driven tier with established Royston and Hanau complexes. Anglo American anchors the upstream mining archetype through Bushveld Complex operations. Sibanye-Stillwater occupies a distinctive position as the only primary platinum-group metals source outside southern Africa through its Stillwater mine holdings.
| Leading Market Players |
|---|
| Johnson Matthey |
| Anglo American |
| Sibanye-Stillwater |
| American Elements |
| Heraeus |
| Umicore |
| Impala Platinum Holdings Limited |
| TANAKA Holdings Co., Ltd. |
| FURUYA METAL Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
South Africa's Bushveld Complex beneficiation mandates concentrate refining leverage upstream, pushing margin pools toward integrated processors with captive metal streams and in-house analytical capabilities. Contract structures downstream now bifurcate between semiconductor fabs locking in five-year offtake agreements and chemical processors exposed to spot volatility.
Pricing Analysis
Long-term offtake contracting dominates semiconductor-grade volumes, displacing spot purchasing as Samsung and SK Hynix negotiate direct agreements with Anglo American and Johnson Matthey. Price differentiation rests on purity certification tier and volume scale, with 99.999% sputtering targets commanding substantial premiums over catalyst-grade material. Cost compression runs through chemical application tiers as iridium substitution pressure intensifies. Memory manufacturers exhibit lowest price sensitivity due to supply security priorities, while chlor-alkali producers face acute margin pressure from volatile ruthenium tetroxide handling costs.
Supply Chain Analysis
Contract manufacturing concentration sits with Johnson Matthey's Royston complex, Heraeus's Hanau facilities, and Anglo American's Mogalakwena refining streams. Supply draws from South Africa, Russia's Norilsk operations, and Sibanye-Stillwater's Stillwater mine in the United States. Raw material dependencies center on platinum-group metal ore concentrates, sulfuric acid leaching reagents, and specialized precursor formulations. Single-source vulnerability pervades the upstream tier where beneficiation policies restrict export flexibility. Distribution runs through direct sales channels for high-purity semiconductor volumes, with Singapore and Hong Kong traders handling fragmented chemical industry accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as hydrogen economy infrastructure and sub-3nm semiconductor nodes create divergent purity requirements and procurement timelines. Demand-side specialization is splintering the supplier base into distinct capability tiers.
For Market Incumbents: Build analytical capability moats around REACH dossier preparation and ECHA substance characterization. Invest in captive refining partnerships with South Korean memory fabs to preempt distributor disintermediation. Defend against iridium substitution in chlor-alkali applications by securing dual-source ore agreements across Bushveld and Norilsk channels. For New Entrants and Emerging Players: Establish a beachhead in organometallic ALD precursor formulation for gate-all-around transistor architectures. Target renewable hydrogen developers in Germany and Japan with ruthenium-iridium oxygen evolution coating packages. Penetrate through technical service partnerships with equipment makers redesigning low-temperature precursor delivery systems. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed chemical processors lacking integrated refining infrastructure. Five-to-ten-year viability hinges on positioning within EU Critical Raw Materials Act strategic stockpiling tiers. Watch for ECHA reclassification of platinum-group metals as the inflection signal for preferential offtake access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refining Capacity | Johnson Matthey's Royston complex secures captive ruthenium streams for catalyst production. |
| Long-term Supply Agreement | Anglo American negotiates five-year contracts with Samsung and SK Hynix for sputtering targets. |
| Joint Venture | Domestic refining partnerships in South Korea bypass concentrated South African export channels. |
| Capacity Expansion | Captive precious metal recovery facilities under construction in Seoul Capital Area DRAM complexes. |
| Green Manufacturing Transition | Proton exchange membrane electrolyzer scaling drives renewable hydrogen catalyst procurement. |
Study Parameters
A spread of perspectives from plant managers at chlor-alkali facilities, procurement leads at memory fabs, technical R&D directors at precursor formulators, and distribution channel partners in Singapore converged on the working assumptions. Primary interview insights combined with customs and trade data, SEC 10-K filings from diversified mining conglomerates, ECHA registration dossiers, and Anglo American technical reports. Bottom-up volume modeling triangulated against top-down platinum-group metal production estimates.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product form tier, application purity requirement, end-use industry concentration, and regional regulatory cluster. CAGRs derived from regression analysis against semiconductor capital expenditure cycles and hydrogen infrastructure deployment trajectories. Forecast inputs incorporated EU Critical Raw Materials Act reclassification scenarios and REACH authorization timeline probabilities.
Stress conditions across platinum mining economics volatility, iridium substitution rates, and ECHA metal compound hazard classification stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about beneficiation policy enforcement and sub-3nm node ramp schedules. Quarterly review of semiconductor fab qualification timelines and hydrogen electrolyzer capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Carbon Steel Market
Metals
Aluminum Extrusion Market
Metals
Brazing Strips Market
Metals
Steel Drums Market
Metals
Beryllium Copper Plate Market
Metals
Copper and Copper Alloy Market
Metals
Copper and Copper Alloy Scrap and Recycling Market
Metals
Global Metal and Metal Manufactured Products Market
Metals
Aluminum Slugs Market
Metals
Steel Casting Market
Metals
Global Bronze Market
Metals
Expanded Metal Foils Market
Metals
Amorphous Metal Cores Market
Metals
Bismuth Market
Metals
Platinum Market
Metals
Europe Metal Service Centers Market