
 Nickel Market | 2026-2036
Nickel Market Size, Share, and Industry Trends Forecast 2026-2036
Nickel Market Intelligence
Lithium iron phosphate chemistry is repositioning cathode economics for mid-range electric vehicles, yet high-nickel formulations retain energy density advantages for premium segments. MMC Norilsk Nickel leverages its Arctic polymetallic deposits to sustain class-one electrolytic output. BHP Group anchors Western supply through its Western Australia nickel sulfide operations. Vale competes via its integrated Brazilian laterite-to-refinery corridor.
Nickel is a silvery-white transition metal with atomic number 28, typically refined to 99.8% purity for industrial use through pyrometallurgical or hydrometallurgical processing; its corrosion resistance and catalytic properties make it indispensable for stainless steel production and electrochemical applications. Battery Alloys command accelerating investment as cathode manufacturers secure long-term offtake agreements, while Stainless Steel remains the dominant volume pool with mature pricing benchmarks. Electrolytic Nickel differentiates on purity premiums for aerospace and electronics specifications.
Indonesia's Ministry of Energy and Mineral Resources enforces downstream processing mandates that reshape investment flows, while China's Ministry of Industry and Information Technology sets battery-grade purity thresholds through GB standards. The EU Battery Regulation imposes carbon footprint disclosure and recycled content quotas that filter market access for Indonesian and Russian supply. Stakeholders must track how regulatory divergence between Asian production hubs and European consumption markets reconfigures arbitrage flows and certification requirements.
Market Dynamics
Indonesia's downstream processing mandates are forcing capital reallocation from ore exports to domestic smelting and refining infrastructure, locking in supply chain geography for the next decade.
Growth Catalysts
- High-nickel cathode chemistry:NCM 811 and 9½½ formulations deliver superior energy density for premium electric vehicle segments, sustaining offtake commitments from battery manufacturers.
- EU Battery Regulation recycled content quotas:Mandates for minimum recovered nickel in new batteries create certified supply premiums and filter market access for compliant producers.
- Arctic sulfide deposits:Russian and Canadian high-grade ore bodies yield class-one electrolytic nickel with lower impurity profiles than laterite alternatives.
Market Restraints
- Laterite ore processing energy intensity:High-pressure acid leach and rotary kiln electric furnace routes consume 2-3x more energy per ton than sulfide smelting, exposing margins to power cost volatility.
- Indonesian supply concentration:Over 40% of global mined output now originates from Indonesian laterite deposits, creating single-point vulnerability to export policy reversals or logistical disruptions.
- Lithium iron phosphate substitution:LFP chemistry eliminates nickel entirely from mid-range vehicle cathodes, compressing addressable volume in the fastest-growing price segment.
Strategic Opportunities
- North American battery supply chain reshoring:IRA domestic content credits incentivize integrated mine-to-cathode investments in Canada and the US, bypassing Indonesian-Chinese processing corridors.
- Hydrometallurgical tailings reprocessing:Pressure oxidation and bioleach technologies unlock nickel and cobalt from historical sulfide waste piles in Ontario and Western Australia.
- Aviation sector nickel superalloy demand:Next-generation turbine blade specifications require higher rhenium and ruthenium-doped nickel alloys for supersonic and hypersonic propulsion systems.
Industry Challenges
- HPAL engineering talent scarcity:Fewer than two dozen operational high-pressure acid leach facilities worldwide have produced experienced process engineers, constraining project ramp timelines.
- Battery-grade sulfate certification delays:Cathode manufacturers require 12-18 month qualification cycles for new nickel sulfate sources, freezing out speculative producers without guaranteed offtake.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nickel Market |
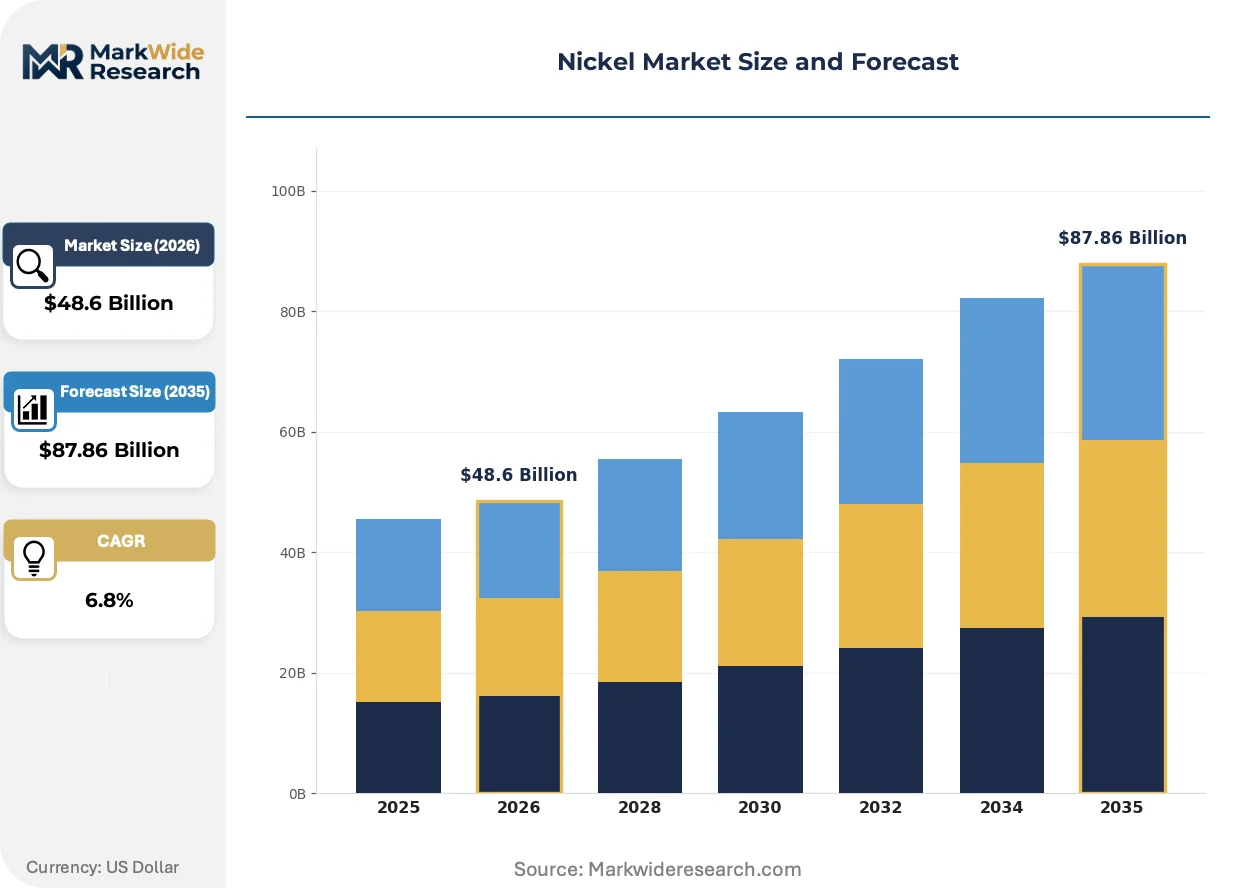
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $87.86 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nickel Pig Iron, Stainless Steel, Battery Alloys, Electrolytic Nickel Application: Electronics, Aerospace, Automotive Components, Energy Storage End User: Manufacturers, Battery Producers, Alloy Makers, Industrial Users Delivery Mode: Direct Shipping, Warehousing, Freight Service, Online Distribution |
| Companies Covered | MMC Norilsk Nickel, First Quantum Minerals, Glencore, Anglo American, ArcelorMittal Mining, BHP Group, Rio Tinto, Lundin Mining, Vale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nickel Market Strategic Shifts & Innovations
Processing technology and regulatory compliance requirements are bifurcating the nickel supply base into battery-certified and industrial-commodity tiers, with diverging capital intensity and margin structures.
Direct nickel extraction from laterite ores using selective ion exchange resins is converging with renewable-powered electrowinning circuits, enabling integrated producers in Queensland and New Caledonia to bypass traditional pyrometallurgical smelting entirely. Battery cathode manufacturers in South Korea and Japan are qualifying these lower-carbon sulfate streams ahead of EU carbon border adjustments. The technology is compressing the traditional mine-to-metal timeline from 18 months to under 90 days for certain ore grades.
REACH nickel substance restrictions are tightening occupational exposure limits across European stainless steel fabrication and battery cell manufacturing facilities, forcing investments in closed-loop ventilation and automated material handling. The regulation's downstream notification requirements are propagating through automotive OEM supply chains, with German and French battery plants now demanding full material passport documentation from Indonesian refiners. Battery-grade nickel sulfate imports into Rotterdam and Hamburg face enhanced customs inspection protocols.
Long-term offtake contracting is displacing spot market procurement for battery-grade nickel sulfate, with Korean cathode producers locking in 5-7 year supply agreements indexed to LME nickel prices plus fixed conversion premiums. This contractual shift is concentrating procurement leverage among three integrated trading houses with established Indonesian smelter relationships. The pattern is most visible in binding supply agreements for European electric vehicle battery gigafactories under construction in Hungary and Poland.
Nickel Market Segmentation
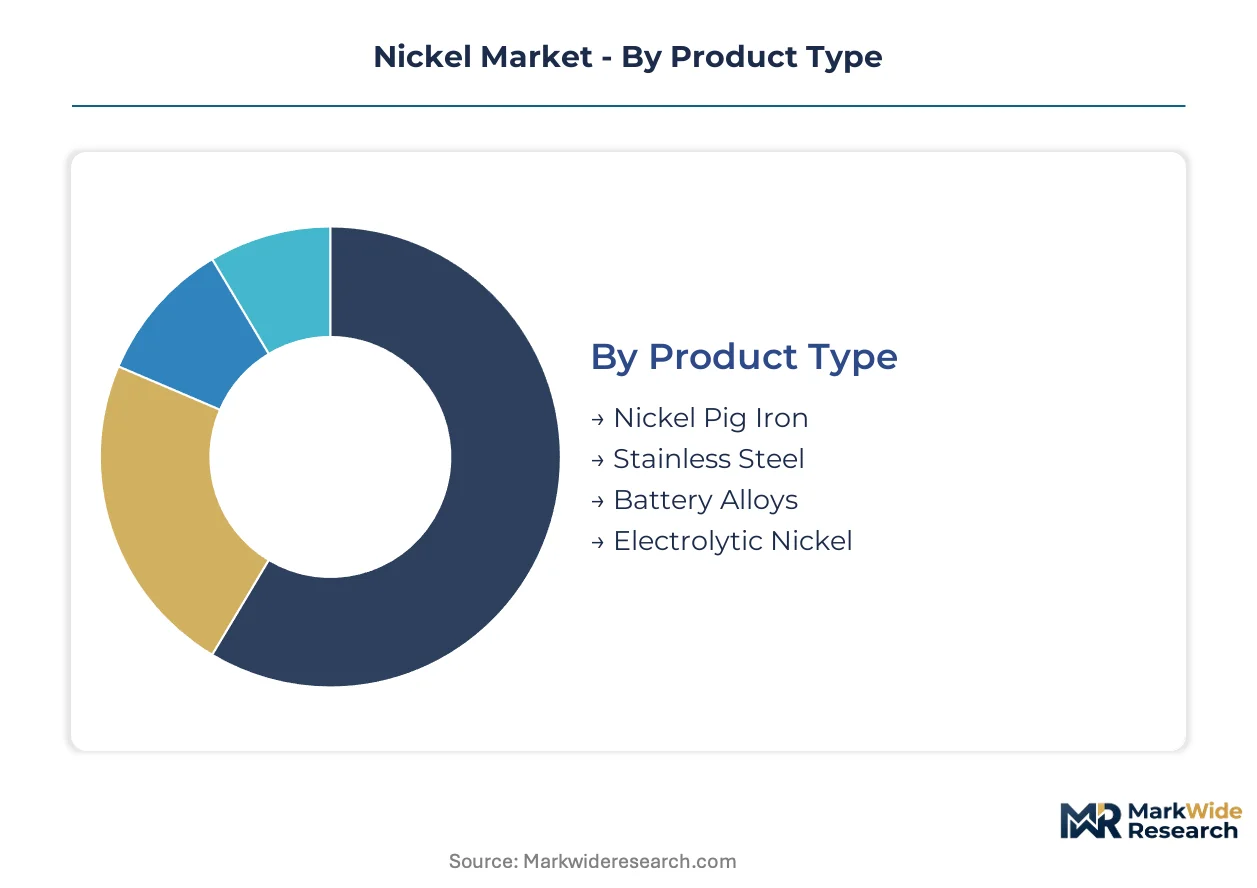
Nickel market segmentation reflects divergent purity requirements between mature industrial applications and emerging battery chemistry specifications. Buyers select product grades based on end-use certification thresholds, with battery-grade sulfate commanding distinct procurement protocols from stainless steel feedstock.
Product Type:
Cost tiers separate commodity-grade feedstock from high-purity refined metal, with conversion premiums widening between pyrometallurgical and hydrometallurgical output.
- Battery Alloys:High-purity nickel sulfate and hydroxide meet cathode manufacturer specifications for NCM and NCA chemistries. Korean and Japanese battery producers dominate procurement, locking in long-term offtake agreements with Indonesian HPAL operators to secure supply for European gigafactory expansions.
- Electrolytic Nickel:Class-one metal refined to 99.8% purity serves aerospace superalloy and electronics plating applications. Russian and Canadian Arctic sulfide deposits sustain output with lower impurity profiles than laterite alternatives, qualifying for EU carbon border adjustment exemptions.
- Stainless Steel:Ferro-nickel and nickel pig iron feed China's integrated melt shops, with Indonesian NPI furnaces supplying over half of global stainless crude production.
- Nickel Pig Iron:Intermediate product from rotary kiln electric furnace processing of Indonesian laterite ore, traded primarily on long-term contracts to Chinese stainless mills.
Volume sits with Stainless Steel; growth tilts toward Battery Alloys.
Application:
End-use specifications fragment the market into certification-bound premium tiers and commoditized industrial grades.
- Energy Storage:Lithium-ion battery cathodes absorb rising volumes of nickel sulfate, with high-nickel NCM 811 formulations requiring stringent impurity controls on cobalt and manganese cross-contamination.
- Aerospace:Turbine blade superalloys demand rhenium-doped nickel with trace element specifications enforced by Rolls-Royce and Pratt & Whitney material qualification protocols.
- Automotive Components:Exhaust system catalyst substrates and high-temperature fasteners utilize nickel-chromium-iron alloys specified by German and Japanese OEM supply chains.
- Electronics:Connector plating and semiconductor packaging require electrolytic nickel with controlled sulfur and carbon content for solderability performance.
Procurement scale concentrates in Energy Storage; margin expansion favors Aerospace.
End User:
Customer sophistication determines contract structures, with integrated producers capturing value through captive refining versus merchant market exposure.
- Battery Producers:Korean cathode manufacturers POSCO and LG Chem negotiate 5-7 year supply agreements indexed to LME prices plus fixed conversion premiums, concentrating procurement leverage among established trading houses.
- Alloy Makers:Specialty steel producers in Germany and Japan purchase electrolytic nickel through quarterly tenders with purity premiums negotiated against ASTM specifications.
- Manufacturers:Stainless steel mills in China and Indonesia source nickel pig iron through affiliated trading arms, minimizing working capital exposure to price volatility.
- Industrial Users:Plating shops and chemical processors procure smaller volumes through distributor networks with 30-60 day inventory cycles.
Contract duration differentiates Battery Producers; spot market liquidity serves Industrial Users.
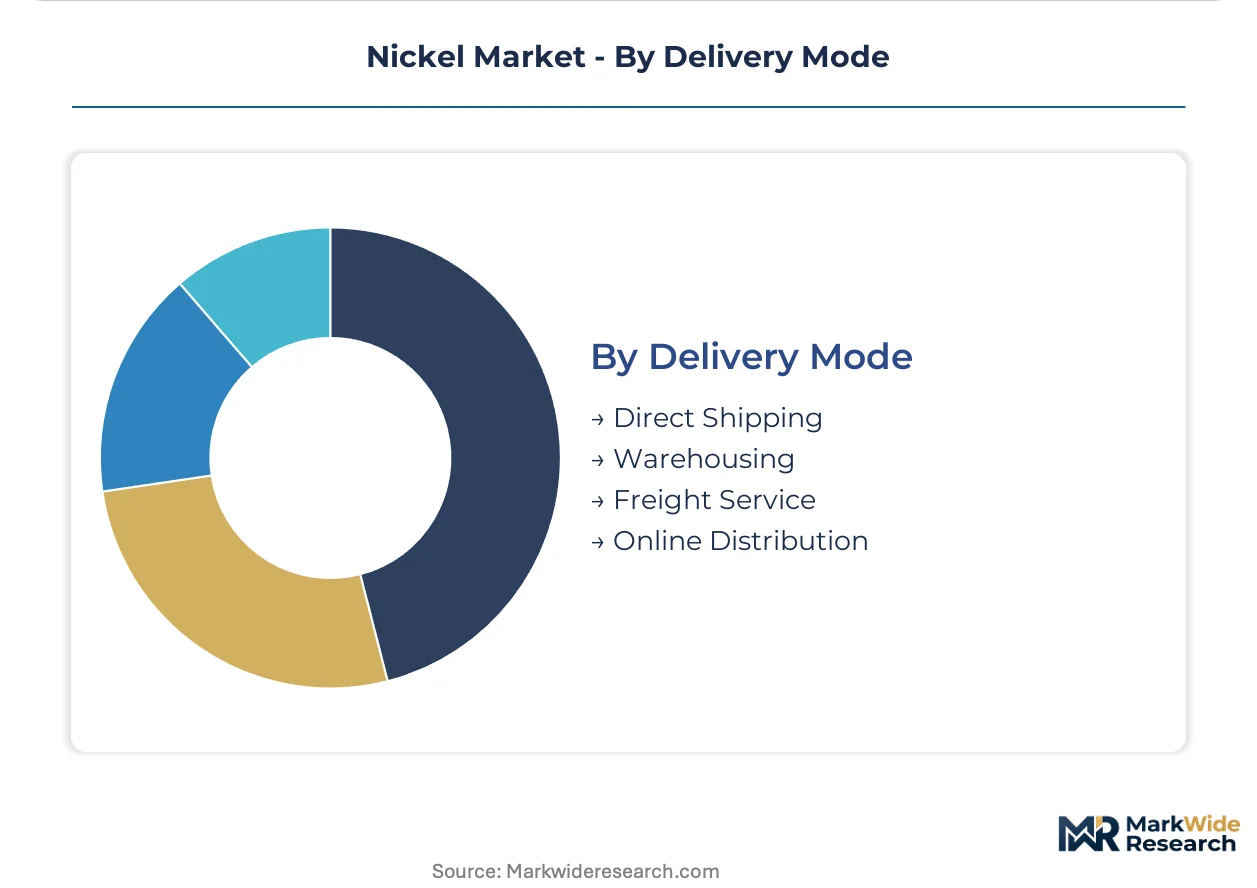
Delivery Mode:
Logistics configuration tracks supply chain geography, with Indonesian-origin material routing through Singapore and Rotterdam hubs.
- Direct Shipping:Bulk vessel charters move nickel pig iron from Sulawesi to Chinese port terminals under long-term freight agreements with Indonesian national carriers.
- Warehousing:LME-registered warehouses in Rotterdam and Singapore store electrolytic nickel warrants, enabling collateralized financing for trading houses and hedge funds.
- Freight Service:Containerized nickel sulfate moves via dedicated refrigerated units from Queensland processing plants to South Korean cathode facilities.
- Online Distribution:Spot market platforms facilitate small-lot procurement for plating shops and research institutions, with digital settlement reducing counterparty risk.
Unit economics favor Direct Shipping for bulk flows; Warehousing underpins price discovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's integrated stainless steel and battery supply chains absorb the dominant share of refined nickel output, while Indonesia's export ban on unprocessed ore redirects investment toward domestic smelting corridors. Regulatory divergence between Asian production hubs and European consumption markets reconfigures arbitrage flows.
China
MIIT battery-grade purity thresholds through GB standards enforce impurity controls on nickel sulfate for NCM cathode production. The Yangtze River Delta concentration hosts cathode manufacturers securing long-term offtake agreements with Indonesian HPAL operators. Qingdao and Ningbo ports function as primary entry points for nickel pig iron from Sulawesi smelters.
Indonesia
The Ministry of Energy and Mineral Resources downstream processing mandates lock in supply chain geography through domestic smelting and refining infrastructure. Export restrictions on unprocessed laterite ore force capital reallocation from ore exports to rotary kiln electric furnace and high-pressure acid leach facilities. The Sulawesi nickel corridor now supplies over half of global stainless crude production.
Russia
Arctic polymetallic deposits sustain class-one electrolytic output with lower impurity profiles than laterite alternatives. MMC Norilsk Nickel operations in the Norilsk-Talnakh district face EU carbon border adjustment scrutiny on export routes. The Kola Peninsula refining complex qualifies for aerospace superalloy specifications through controlled sulfur and carbon content.
Australia
Western Australia nickel sulfide operations anchor Western supply through BHP Group and other integrated producers. The Kalgoorlie-Norseman belt hosts hydrometallurgical tailings reprocessing projects using pressure oxidation technologies. Queensland processing plants deploy selective ion exchange resins with renewable-powered electrowinning for lower-carbon sulfate streams.
Canada
IRA domestic content credits incentivize integrated mine-to-cathode investments bypassing Indonesian-Chinese processing corridors. The Sudbury Basin polymetallic district hosts historical sulfide waste pile reprocessing through bioleach technologies. Ontario refineries supply battery-grade material to North American cathode qualification cycles.
Nickel Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated mining houses commanding cathode supply negotiations while merchant refiners serve industrial spot markets. Three archetypes dominate: Arctic sulfide operators with polymetallic byproduct credits, Indonesian laterite processors with captive energy integration, and diversified majors with battery supply chain offtake leverage. Consolidation pressure concentrates procurement leverage among established trading houses with smelter relationships. Capacity expansion and long-term contracting represent the dominant competitive moves.
Within the diversified major tier, BHP Group exemplifies Western supply anchoring through sulfide operations, while Vale occupies a position bridging Brazilian laterite-to-refinery integration. MMC Norilsk Nickel represents the Arctic sulfide archetype with polymetallic deposit economics.
| Leading Market Players |
|---|
| MMC Norilsk Nickel |
| First Quantum Minerals |
| Glencore |
| Anglo American |
| ArcelorMittal Mining |
| BHP Group |
| Rio Tinto |
| Lundin Mining |
| Vale |
| Others |
Cost & Logistics Intelligence
Sovereign-backed Indonesian producers anchor supply discipline through captive energy integration and export licensing controls, translating mineral resource nationalism into sustained pricing power for battery-grade sulfate premiums. State mandates on downstream processing compress spot market liquidity while locking Chinese and Korean cathode manufacturers into indexed long-term offtake structures.
Pricing Analysis
Volume sits with stainless steel feedstock trading at commodity discounts; margins concentrate in battery-grade nickel sulfate where cathode qualification cycles enforce purity premiums. Three-tier pricing structure across battery-certified, industrial-electrolytic, and nickel-pig-iron levels separates premium sulfate from standard ferro-nickel from economy NPI grades. Pricing pressure stems from LFP chemistry substitution in mid-range electric vehicles, compressing addressable volume for nickel-intensive cathodes. Stainless steel mills exhibit highest price sensitivity through affiliated trading arms, while aerospace superalloy buyers absorb purity premiums with limited elasticity.
Supply Chain Analysis
Laterite ore supply rests on Indonesian mining concessions and Philippine ore exports, with sulfide concentrates drawing from Russian Arctic and Canadian Sudbury deposits. HPAL processing circuits and RK-E furnaces constitute critical infrastructure bottlenecks, while sulfuric acid and thermal coal feed processing economics. Single-source vulnerability concentrates in Indonesian laterite corridors where export policy reversals disrupt flows. Distribution runs through Singapore warehousing hubs for LME warrant financing and direct bulk charter routes to Chinese Yangtze Delta ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HPAL engineering talent scarcity props battery-grade sulfate pricing by constraining qualified project ramp timelines, cementing incumbent processor advantages. This supply-constrained structure rewards early offtake commitment and penalizes speculative capacity without guaranteed cathode qualification.
For Market Incumbents: Anticipate LFP substitution pressure by securing aerospace superalloy certification for Arctic sulfide output, insulating margin pools from battery chemistry shifts. Deepen backward integration into Indonesian HPAL operations to capture conversion premiums currently accruing to trading houses. Prioritize rhenium-doped nickel alloy R&D for next-generation turbine specifications demanded by Rolls-Royce and Pratt & Whitney material protocols. For New Entrants and Emerging Players: Direct nickel extraction using selective ion exchange resins offers a technology-first wedge into Queensland and New Caledonia processing corridors, bypassing traditional pyrometallurgical smelting entirely. Target North American battery supply chain reshoring under IRA domestic content credits, where integrated mine-to-cathode investments bypass Indonesian-Chinese corridors. Qualify lower-carbon sulfate streams ahead of EU carbon border adjustments to capture certified supply premiums. For Investors and Strategic Acquirers: Distressed-cycle entries favor Australian sulfide tailings reprocessing specialists with pressure oxidation technology licenses, positioned for battery-grade output without greenfield mining risk. Long-term viability frames around 5-10 year cathode chemistry evolution windows, with high-nickel formulations retaining premium vehicle segment dominance. Watch EU Battery Regulation recycled content quota enforcement as inflection signal for certified supply premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| HPAL Capacity Expansion | Indonesian operators lock in cathode offtake with Korean LG Chem and POSCO through 5-7 year supply agreements. |
| Backward Integration into Sulfide Mining | BHP Group and Canadian operators secure class-one electrolytic output with lower carbon intensity than laterite alternatives. |
| Green Manufacturing Transition | Queensland processors deploy renewable-powered electrowinning to qualify for EU carbon border adjustment exemptions. |
| Long-term Supply Agreement | Korean cathode producers index contracts to LME nickel prices plus fixed conversion premiums, freezing out speculative entrants. |
| Joint Venture with Trading Houses | Established Indonesian smelter relationships concentrate procurement leverage among three integrated trading houses serving European gigafactories. |
Research Approach
Multi-period observation of HPAL project ramp timelines, cathode qualification cycles, and Indonesian export licensing patterns anchored the trend analysis, supplemented by interviews with plant engineers at sulfide and laterite operations, procurement leads at Korean cathode manufacturers, and regulatory affairs specialists tracking EU Battery Regulation implementation. Secondary validation drew from SEC 10-K filings of diversified mining majors, Indonesian Ministry of Energy and Mineral Resources policy circulars, LME warehouse stock data, and customs records through Rotterdam and Singapore ports. Bottom-up project economics modeling triangulated against top-down demand forecasts from stainless steel and battery sector consumption patterns.
Input-output matrices structured the forecast framework across product type, application, end user, and delivery mode dimensions, with regional production hub clustering capturing Indonesian, Chinese, Russian, Australian, and Canadian supply dynamics. CAGRs derived from segment-level volume trajectories weighted by purity-premium pricing differentials, incorporating electric vehicle penetration curves and stainless steel capacity expansion schedules as nickel demand drivers. The analysis window spans the full projection horizon without interim year specificity.
Several conditions sit outside the modeled scope, including abrupt Indonesian export policy reversals, breakthrough solid-state battery chemistry eliminating nickel cathodes, and Arctic logistics disruptions affecting Russian sulfide concentrate flows. Forecasts reflect documented assumptions on HPAL engineering talent availability, cathode manufacturer qualification timelines, and EU regulatory enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
TMCP Steel Market
Metals
Finished Steel Products Market
Metals
Shipbuilding Steel Plate Market
Metals
Silver Enamel Market
Metals
Asia-Pacific Metal Finishing Market
Metals
South America Metal Finishing Market
Metals
Titanium Mill Products Market
Metals
Wear Steel Plate Market
Metals
Zinc Plating Market
Metals
Stainless Steel Panels Market
Metals
High Carbon Bearing Steel Market
Metals
Steel Long Products Market
Metals
Ore Metals Market
Metals
Welding Materials Market
Metals
Ferrosilicon Market
Metals
Nickel Sulfate Market