
 Steel Drums Market | 2026-2036
Steel Drums Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Drums Market Intelligence
Plastic intermediate bulk containers is pivoting toward hybrid steel-plastic designs as resin volatility reshapes total cost of ownership for bulk shippers. Greif leverages captive steel recycling to insulate margin structures from scrap price swings. Mauser Packaging Solutions anchors European chemical logistics through its closed-head drum specialization. SCHÜTZ GmbH & Co. KGaA competes on tight-head precision for hazardous liquid containment.
Steel drums are cylindrical shipping containers fabricated from cold-rolled carbon steel with seam-welded bodies and chime-reinforced rims, typically rated for liquids and solids between 15 and 55 gallons. They serve as the dominant UN-certified packaging for hazardous material transport under DOT and IATA regulations. Chemical-grade drums command premium positioning due to UN performance testing and corrosion-resistant interior coatings. Food-grade variants are gaining share as processors substitute fiberboard for moisture-sensitive ingredients. The 55-gallon capacity retains volume leadership in petroleum and lubricant logistics.
EPA hazardous waste manifest rules and DOT 49 CFR shipping container standards govern drum integrity testing and reconditioning cycles in the United States. REACH compliance in Europe restricts certain epoxy lining chemistries, pushing coating suppliers toward water-based alternatives. Stakeholders must weigh reconditioning economics against single-use regulatory traceability requirements as circularity mandates tighten across multiple jurisdictions.
Market Dynamics
Steel drum procurement is tightening around UN-certified reconditioning cycles as circularity mandates compress single-use economics across chemical logistics corridors.
Growth Catalysts
- BIS packaging norms:India's Bureau of Indian Standards tightened drum integrity requirements for chemical processors, forcing fleet upgrades and expanding replacement demand in Maharashtra's industrial belt.
- Food-grade lining chemistry:Water-based epoxy alternatives are penetrating European dairy logistics as REACH restrictions phase out conventional coating solvents.
- Hazardous waste manifest rules:EPA hazardous waste tracking requirements in the United States extend drum lifecycle accountability, reinforcing demand for certified reconditioning services.
Market Restraints
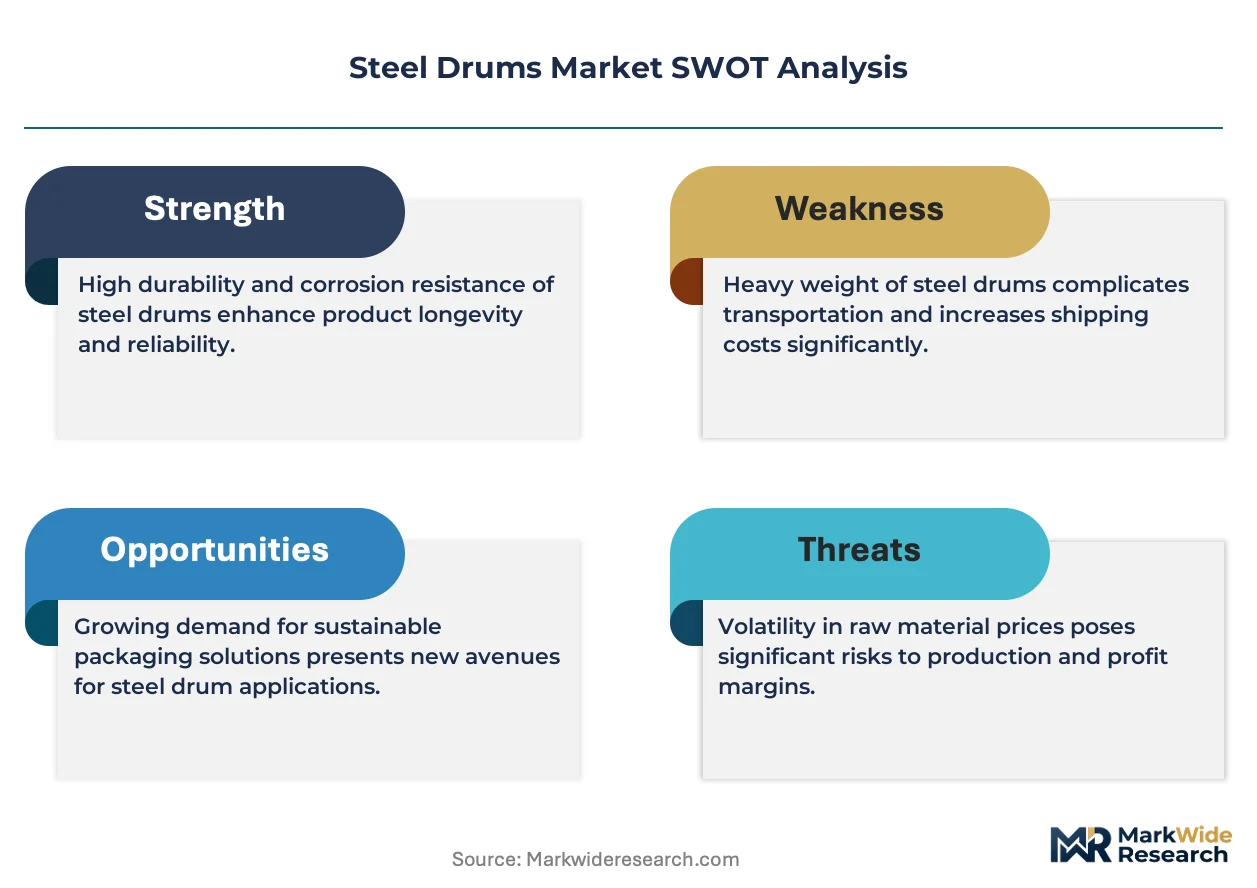
- Scrap steel volatility:Cold-rolled carbon steel input costs swing with ferrous scrap auction prices, compressing margin predictability for fabricators without captive recycling.
- Resin substitution pressure:Plastic intermediate bulk containers compete for non-hazardous liquid logistics, particularly in food and beverage distribution where UN certification is not required.
- REACH compliance friction:ECHA restrictions on specific epoxy lining chemistries force coating reformulation, extending product development timelines for drum manufacturers serving European chemical processors.
Strategic Opportunities
- Hybrid steel-plastic designs:Composite drum architectures combining steel structural integrity with plastic chemical resistance open penetration paths into specialty solvent logistics.
- Closed-loop reconditioning networks:Geographic concentration of chemical processors in Germany's Rhine-Ruhr corridor supports hub-and-spoke drum pooling systems with tracked lifecycle data.
- Food-grade conversion:Fiberboard substitution for moisture-sensitive ingredients creates drum demand in North American ingredient processing, particularly for hygroscopic powder transport.
Industry Challenges
- Welding certification scarcity:UN-performance-rated seam welding requires specialized operator credentials that lag demand growth in India's expanding drum fabrication sector.
- Coating application consistency:Interior lining thickness uniformity for corrosive chemical containment demands capital-intensive automated spray systems that mid-scale producers struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Drums Market |
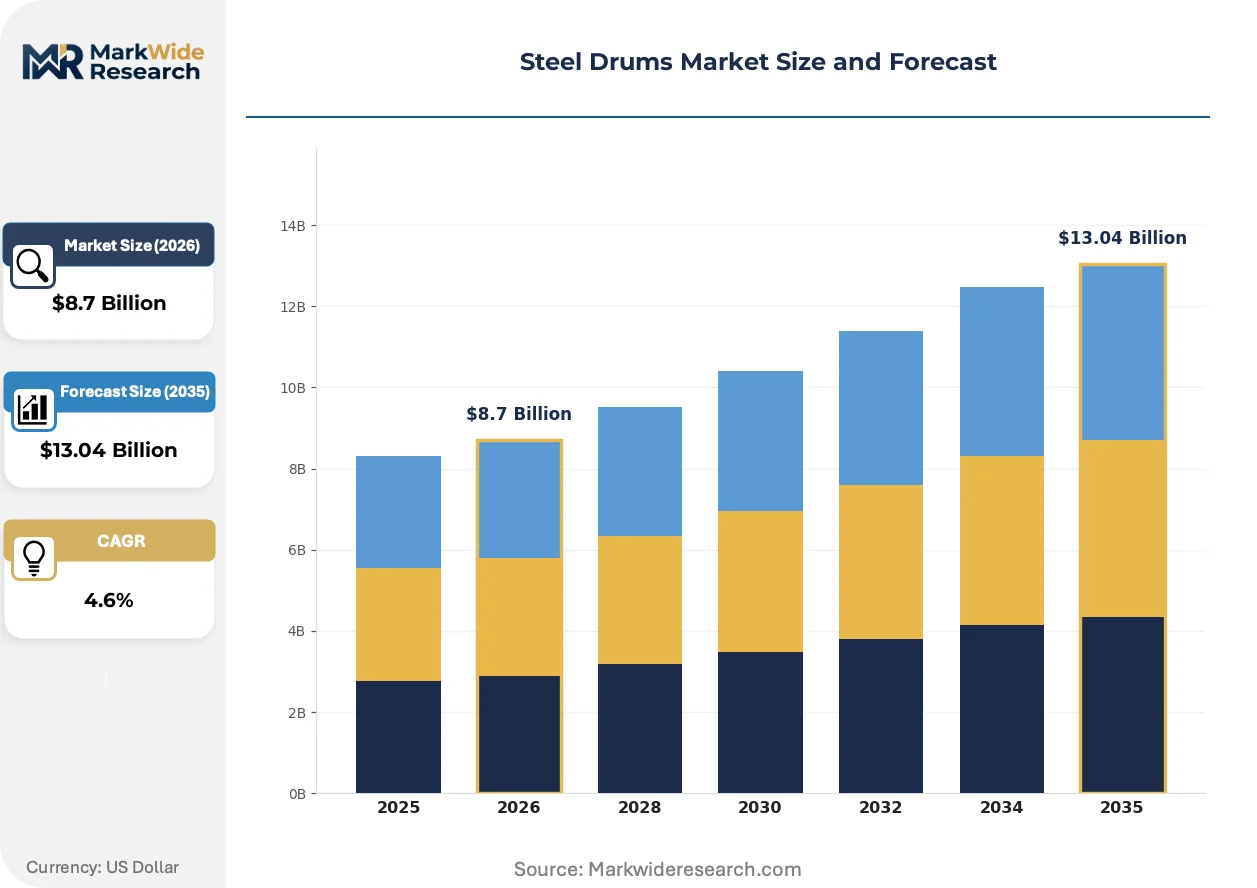
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Head, Closed Head, Tight Head, Flammable Liquids Grade: Food Grade, Industrial Grade, Chemical Grade, Lubricant Grade Capacity: 55 Gallon, 30 Gallon, 20 Gallon, 15 Gallon End User: Chemicals, Pharmaceuticals, Food & Beverage, Oil & Gas |
| Companies Covered | Greif, Mauser Packaging Solutions, SCHÜTZ GmbH & Co. KGaA, BWAY Corporation, Time Technoplast Ltd., Skolnik Industries, Balmer Lawrie & Co. Ltd., Great Western Containers Inc., Peninsula Drums, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Drums Market Strategic Shifts & Innovations
Drum architecture is pivoting toward material hybridization and regulatory data integration as chemical logistics operators seek packaging that satisfies both performance certification and circularity tracking.
Water-based epoxy lining systems are absorbing the functional requirements previously met by solvent-based coatings in European dairy and food ingredient logistics. Dairy processors in the Netherlands and Denmark are specifying these linings for moisture-sensitive powder transport. The technology is absorbing compliance burden from REACH-restricted chemistries while maintaining FDA and EFSA food-contact approvals.
EPA hazardous waste manifest rules and DOT 49 CFR container integrity standards are tightening reconditioning documentation requirements for drums circulating in United States chemical logistics. Reconditioners must now maintain chain-of-custody records across multiple use cycles. Small and mid-scale drum service providers face compliance cost pressure that favors consolidated reconditioning networks with integrated data systems.
Buyers in petroleum and lubricant logistics are compressing supplier rosters to favor drum providers with captive steel recycling and integrated reconditioning capabilities. Major lubricant blenders in Texas and Louisiana are consolidating procurement around vendors offering lifecycle tracking. This concentration is visible most acutely in Gulf Coast petrochemical corridors where single-source drum management contracts are displacing spot purchasing.
Steel Drums Market Segmentation
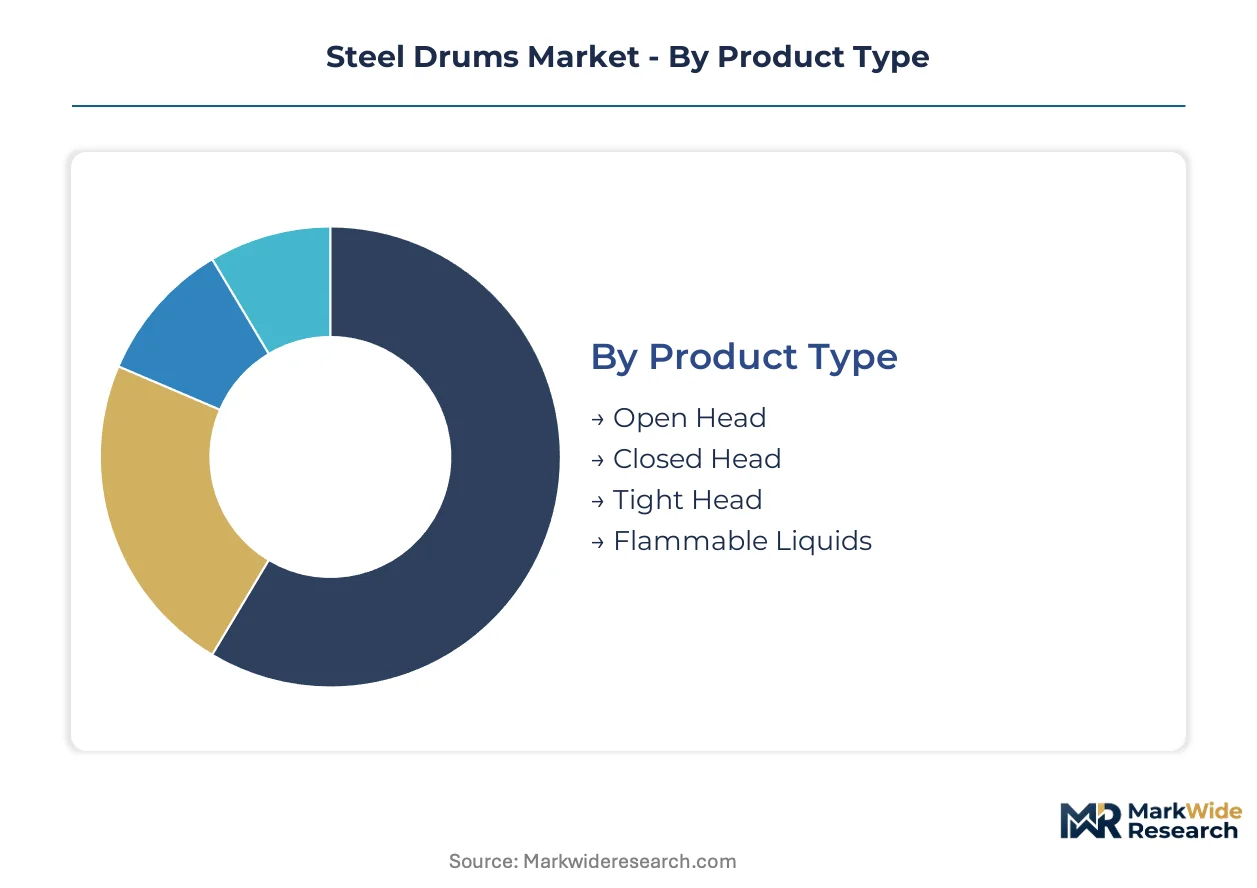
Steel drum segmentation reflects divergent certification requirements across hazardous material handling versus food-contact applications. Product architecture and grade specifications determine margin structures, with UN-certified variants commanding substantial premiums over standard industrial formats.
Product Type:
Open head configurations dominate volume procurement for solids and semi-solids, while closed and tight head variants capture premium positioning in liquid containment.
- Open Head:Removable lid design with bolt ring closure supports solids, powders, and viscous materials. Chemical processors in Maharashtra's industrial corridor favor these for pigment and resin handling where frequent access outweighs spillage risk.
- Closed Head:Fixed top construction with small bung openings delivers maximum integrity for liquid transport. REACH-compliant reconditioning networks in Germany's Rhine-Ruhr corridor concentrate procurement here for solvent logistics requiring lifecycle tracking.
- Tight Head:Seam-welded body with precision-machined chimes and dual bung configuration meets DOT 49 CFR standards for hazardous liquid containment. Dairy logistics operators in the Netherlands specify tight head drums with water-based epoxy linings for moisture-sensitive powder transport.
- Flammable Liquids:Specialized venting and grounding features address IATA dangerous goods regulations. Petroleum blenders in Texas and Louisiana consolidate procurement around flammable-rated drums with integrated reconditioning services.
Today's leader: Closed Head. Tomorrow's challenger: Tight Head.
Grade:
Grade differentiation separates food-contact compliance from industrial chemical resistance, with coating chemistry driving procurement decisions in regulated corridors.
- Food Grade:FDA and EFSA-approved interior linings enable direct contact with dairy, edible oils, and hygroscopic ingredients. North American ingredient processors substitute fiberboard drums with food-grade steel for moisture-sensitive powder logistics.
- Industrial Grade:Standard epoxy or phenolic coatings serve general manufacturing without specialized certification. Indian fabricators under BIS packaging norms upgrade industrial-grade fleets to meet tightened integrity requirements.
- Chemical Grade:UN performance testing and corrosion-resistant linings command premium positioning. Gulf Coast petrochemical operators demand chemical-grade drums with captive steel recycling and documented reconditioning cycles.
- Lubricant Grade:Formulated for petroleum product compatibility with enhanced seal integrity. Major lubricant blenders compress supplier rosters to favor providers offering lifecycle tracking and closed-loop recovery.
Food Grade is climbing the fastest as dairy and ingredient processors abandon fiberboard for moisture protection.
Capacity:
Capacity selection balances shipping economics against handling constraints, with the 55-gallon standard retaining dominance in bulk liquid corridors.
- 55 Gallon:The petroleum and lubricant logistics standard optimizes railcar and tanker truck loading factors. Texas and Louisiana petrochemical clusters source almost exclusively at this capacity for crude oil derivatives and synthetic lubricants.
- 30 Gallon:Mid-scale format serves specialty chemical batches and limited-run pharmaceutical intermediates. European chemical processors in smaller Rhine-Ruhr facilities specify 30-gallon drums for high-value solvent distribution.
- 20 Gallon:Compact capacity supports laboratory-scale chemical supply and food ingredient sampling. Indian pharmaceutical manufacturers in Maharashtra procure 20-gallon drums for active pharmaceutical ingredient export.
- 15 Gallon:Smallest standard format addresses niche applications in hazardous sample transport and precision lubricant dispensing. Danish dairy equipment suppliers utilize 15-gallon drums for concentrated cleaning chemical delivery.
The 55-gallon format holds volume leadership. The 30-gallon segment shows steepest expansion trajectory in specialty chemical logistics.
End User:
End-use concentration determines coating specifications and reconditioning intensity, with chemical and petroleum sectors driving premium-grade demand.
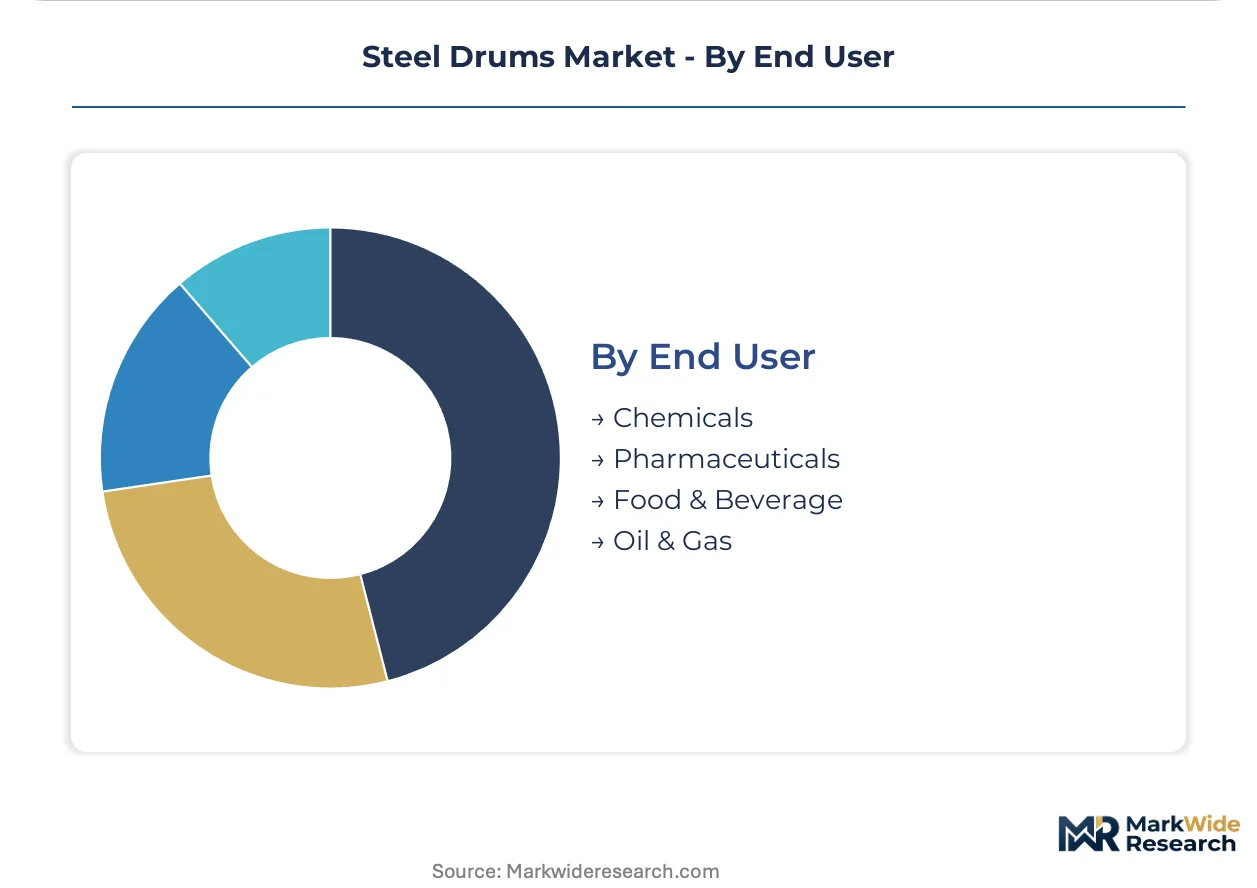
- Chemicals:Corrosive substance handling demands UN-certified drums with tailored interior linings and tracked reconditioning cycles. EPA hazardous waste manifest rules in the United States extend lifecycle accountability for chemical sector drums.
- Pharmaceuticals:Active ingredient and solvent logistics require contamination-resistant coatings with batch documentation. CDSCO oversight in India drives pharmaceutical drum procurement toward BIS-certified fabrication.
- Food & Beverage:Edible oil, dairy, and ingredient transport prioritizes FDA and EFSA food-contact approvals over chemical resistance. Water-based epoxy innovations displace conventional coatings in European dairy logistics.
- Oil & Gas:Crude derivatives, lubricants, and drilling chemicals require flammable-rated construction with grounding compatibility. Gulf Coast operators consolidate procurement around vendors with captive recycling and integrated reconditioning.
Chemicals anchors current demand. Food & Beverage represents the fastest-growing end-use as processors convert from fiberboard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's industrial corridor around Mumbai and Pune anchors regional procurement intensity as chemical processors expand drum fleets under tighter certification regimes.
United States
Gulf Coast petrochemical clusters in Texas and Louisiana drive concentrated demand for flammable-rated drums with integrated reconditioning services. EPA hazardous waste manifest rules extend lifecycle accountability across multiple use cycles. Major lubricant blenders in Houston consolidate procurement around vendors offering captive steel recycling and documented chain-of-custody tracking.
Germany
Rhine-Ruhr chemical logistics corridors support hub-and-spoke drum pooling systems with tracked lifecycle data for solvent distribution. REACH compliance restricts conventional epoxy lining chemistries, pushing coating suppliers toward water-based alternatives. Closed-head drum specialization dominates procurement for hazardous liquid containment in Leverkusen and Duisburg processing facilities.
India
Maharashtra's industrial belt around Mumbai and Pune experiences fleet upgrade pressure under tightened BIS packaging norms for chemical processors. CDSCO oversight drives pharmaceutical drum procurement toward certified fabrication standards. Welding certification scarcity for UN-performance-rated seam welding lags demand growth in the expanding drum fabrication sector.
Netherlands
Dairy logistics operators specify tight head drums with water-based epoxy linings for moisture-sensitive powder transport. EFSA food-contact approvals govern procurement decisions for edible oil and ingredient handling. Rotterdam chemical terminals anchor reconditioning network demand for tracked container cycles serving European distribution corridors.
Denmark
Dairy equipment suppliers utilize compact 15-gallon drums for concentrated cleaning chemical delivery to processing facilities. REACH restrictions phase out solvent-based coating systems in favor of compliant alternatives. Copenhagen-area ingredient processors convert from fiberboard to steel drums for hygroscopic powder protection in Nordic distribution networks.
Steel Drums Market Key Industry Players
Backward integration into captive steel recycling dominates the current landscape as margin protection against scrap price volatility. The vendor base stratifies across integrated reconditioning networks, specialized coating innovators, and regional fabrication specialists. Three archetypes define competitive positioning: full-service lifecycle managers, precision containment specialists, and emerging market scale players. M&A activity and geographic expansion represent the dominant competitive moves as participants seek consolidated procurement relationships.
Among North American lifecycle managers, Greif exemplifies the integrated archetype through captive recycling capabilities. Mauser Packaging Solutions occupies a position within the European precision tier, while SCHÜTZ GmbH & Co. KGaA represents German engineering specialization in tight-head containment systems. These three anchors illustrate how competitive positioning stratifies around certification depth, geographic footprint density, and circularity service integration rather than commodity fabrication scale alone.
| Leading Market Players |
|---|
| Greif |
| Mauser Packaging Solutions |
| SCHÜTZ GmbH & Co. KGaA |
| BWAY Corporation |
| Time Technoplast Ltd. |
| Skolnik Industries |
| Balmer Lawrie & Co. Ltd. |
| Great Western Containers Inc. |
| Peninsula Drums |
| Others |
Cost & Logistics Intelligence
UN-performance-rated seam welding certification scarcity in Maharashtra's expanding fabrication sector widens labor-cost differentials between premium-certified and standard-grade drum production tiers.
Pricing Analysis
Cold-rolled carbon steel input costs pass through to drum pricing with varying elasticity across certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates UN-certified chemical-grade drums with documented reconditioning cycles from industrial-grade variants and basic open-head formats. Price differentiation hinges on certification depth and captive recycling integration. Cost compression in economy tiers is intensifying because resin substitution pressure from plastic intermediate bulk containers erodes spot-market pricing power. Small-scale chemical processors in India exhibit highest price sensitivity, while Gulf Coast petrochemical operators demonstrate lowest sensitivity due to lifecycle-tracking requirements.
Supply Chain Analysis
India's tightened BIS packaging norms function as de facto local-content rules, reshaping sourcing toward domestic fabrication with certified welding credentials. Steel drum manufacturing draws from cold-rolled carbon steel feedstock anchored in China, India, and the United States, with interior lining chemistries sourced from European specialty coating suppliers. Distribution runs through hub-and-spoke reconditioning networks concentrated in Germany's Rhine-Ruhr corridor and Texas-Louisiana petrochemical clusters. Single-source vulnerability in seam-welding operator certification creates bottleneck risk for UN-performance-rated production expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in steel drums rests on coating innovation premiums and captive recycling economics that insulate fabricators from ferrous scrap auction volatility.
For Market Incumbents: Extend reconditioning network density through tracked lifecycle data systems that satisfy EPA hazardous waste manifest documentation requirements. Deepen backward integration into captive steel recycling to defend margin structures against scrap price swings. Consolidate procurement relationships with Gulf Coast lubricant blenders seeking single-source drum management contracts.
For New Entrants and Emerging Players: Begin with food-grade drum conversion opportunities in North American ingredient processing, where fiberboard substitution for hygroscopic powder transport creates penetration white space. Target European dairy logistics corridors with water-based epoxy lining capabilities that satisfy REACH-compliant coating restrictions. Build go-to-market positioning around EFSA food-contact approval expertise rather than commodity fabrication scale.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Indian fabricators struggling to justify capital-intensive automated spray systems for interior lining consistency. Long-term viability favors participants with integrated reconditioning networks and certification depth across multiple regulatory jurisdictions. Watch for inflection in BIS enforcement intensity as the signal for consolidation timing in Maharashtra's industrial belt.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Steel Recycling | Greif's margin insulation from scrap volatility demonstrates competitive protection for integrated operators. |
| Water-Based Epoxy Coating Reformulation | REACH compliance in European dairy logistics opens premium positioning for coating innovation leaders. |
| Closed-Loop Reconditioning Network Expansion | Hub-and-spoke systems in Germany's Rhine-Ruhr corridor satisfy tracked lifecycle data requirements. |
| Hybrid Steel-Plastic Drum Architecture Development | Composite designs penetrate specialty solvent logistics with structural integrity plus chemical resistance. |
| Welding Certification Training Program Investment | UN-performance-rated operator credential scarcity in India constrains certified production expansion. |
Research Approach
Direct dialogue with drum fabrication plant managers, chemical processor procurement leads, coating supplier technical directors, and reconditioning network operators grounded qualitative insights in operational reality. Secondary validation drew from BIS packaging norm filings, EPA hazardous waste manifest documentation, ECHA REACH restriction updates, and SEC disclosures from listed packaging manufacturers. Bottom-up volume estimates from individual facility capacities triangulated against top-down demand projections from end-use consumption patterns.
Segmented outputs across product type, grade tier, capacity format, and end-use industry dimensions calibrated penetration assumptions throughout the forecast period. CAGRs derived from historical shipment trajectories adjusted for regulatory inflection points including BIS norm tightening and REACH coating phase-outs. Scrap steel price volatility indices and reconditioning cycle documentation requirements fed industry-specific forecast sensitivity.
Several conditions sit outside the modeled scope, including hypothetical tariff restructuring on cold-rolled carbon steel trade flows and breakthrough substitution technologies displacing steel drum formats entirely. Forecasts reflect documented assumptions about regulatory enforcement continuity and certification standard stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
India Metal Fabrication Market
Metals
North America Metal Casting Market
Metals
TMCP Steel Market
Metals
Rare Earth Metals Market
Metals
Galvanized Steel Coil Market
Metals
High Purity Boron Market
Metals
Aluminum Sheet Market
Metals
High Purity Base Metals Market
Metals
Aluminum Tubes Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
North America Aluminum Casting Market
Metals
Recycled Metal Market
Metals
Aluminium Forging Market
Metals
US Metal Fabrication Market
Metals
Metal Injection Molding (Mim) Powders Market
Metals
Cold Drawn Wire Market