
 Global Tool Steel Market | 2026-2036
Global Tool Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tool Steel Market Analysis
Buyer concentration among automotive and aerospace OEMs is shifting toward fewer, larger contract manufacturers with in-house die-making capabilities. Voestalpine leverages its integrated steel-to-component model to serve premium tooling customers in Central Europe. Hitachi Metals sustains technology leadership in powder metallurgy high-speed steel for cutting applications. Sandvik competes through advanced coating technologies paired with substrate optimization for extreme wear environments.
Tool steel comprises alloyed and carbon steels engineered for hardness, wear resistance, and dimensional stability at elevated temperatures, typically containing chromium, molybdenum, tungsten, or vanadium in precise ratios to achieve Rockwell hardness exceeding 60 HRC after heat treatment. Cold work tool steel dominates volume consumption in blanking and forming dies where abrasion resistance governs tool life, while high-speed steel captures the fastest expansion in aerospace machining centers running titanium alloys. The bars segment anchors distribution channels for job shops requiring customized geometries, whereas plates and coils serve high-volume stamping operations with standardized die sets.
EPA emissions rules in the United States constrain domestic electric arc furnace operations producing tool steel grades, while REACH registration requirements in the European Union elevate compliance costs for cobalt-bearing high-performance alloys. China's GB standards under SAMR oversight mandate traceability certificates for imported tool steel used in critical infrastructure applications. Stakeholders must monitor evolving alloy substitution patterns as tungsten supply constraints and regulatory pressure on hexavalent chromium plating reshape raw material sourcing strategies.
Market Dynamics
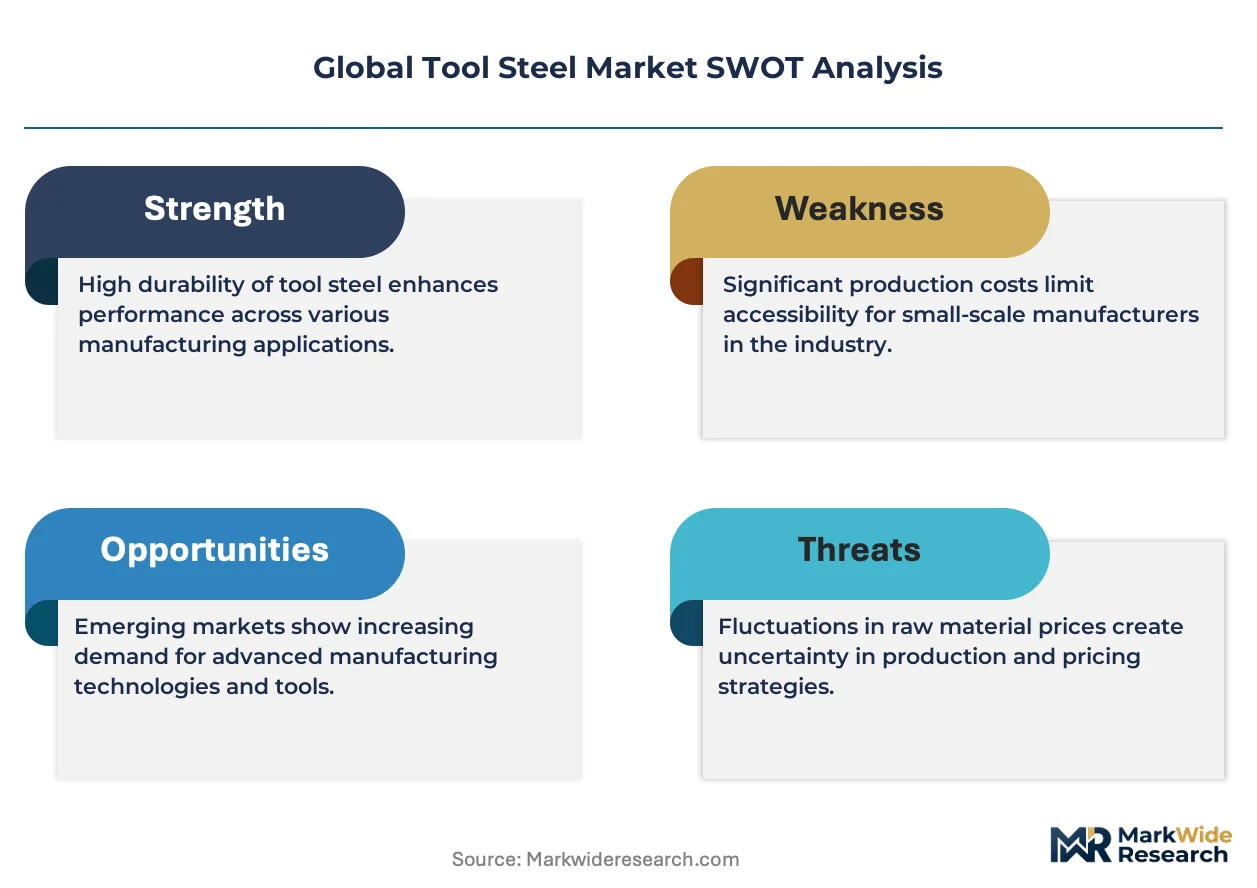
Automotive OEMs are consolidating die-making operations in-house while tightening cobalt and tungsten sourcing requirements under REACH and EPA frameworks. This dual pressure is compressing margins for independent tool steel distributors and forcing substrate-coating integration.
Growth Catalysts
- EV stamping die demand:Electric vehicle platforms require hardened tool steel for high-strength aluminum forming, with automotive OEMs expanding captive die shops.
- REACH compliance differentiation:European Union ECHA registration requirements for cobalt-bearing alloys create competitive moats for compliant suppliers serving aerospace machining centers.
- Powder metallurgy adoption:Near-net-shape PM-HSS reduces material waste in cutting tool production, accelerating uptake among precision component manufacturers.
Market Restraints
- Tungsten supply concentration:Chinese state-owned miners control 80% of global tungsten concentrate output, exposing Western tool steel producers to export quota volatility.
- Hexavalent chromium plating bans:EPA and EU REACH restrictions on Cr(VI) surface treatments eliminate conventional hard chrome alternatives for wear-resistant die coatings.
- Electric arc furnace emissions caps:United States EPA greenhouse gas rules constrain domestic EAF production of high-alloy tool steel grades requiring precise chemistry control.
Strategic Opportunities
- India automotive tooling:PLI scheme incentives for domestic manufacturing are creating first-mover advantages for tool steel suppliers establishing local heat treatment partnerships.
- Coating-substrate convergence:Physical vapor deposition integration with premium substrate optimization enables premium pricing for extreme wear environments.
- Traceability certification services:China's SAMR-mandated GB standard documentation for critical infrastructure applications creates recurring revenue streams for compliance-enabled distributors.
Industry Challenges
- Metallurgical heat treatment expertise:Vacuum hardening and cryogenic processing capabilities require specialized technician training that outpaces vocational pipeline output.
- Alloy substitution R&D timelines:Developing vanadium-molybdenum alternatives to tungsten-heavy grades demands 18-24 month qualification cycles with aerospace OEMs.
- Legacy ERP integration:Batch-level traceability systems for SAMR compliance require middleware development to connect with decades-old shop floor management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tool Steel Market |
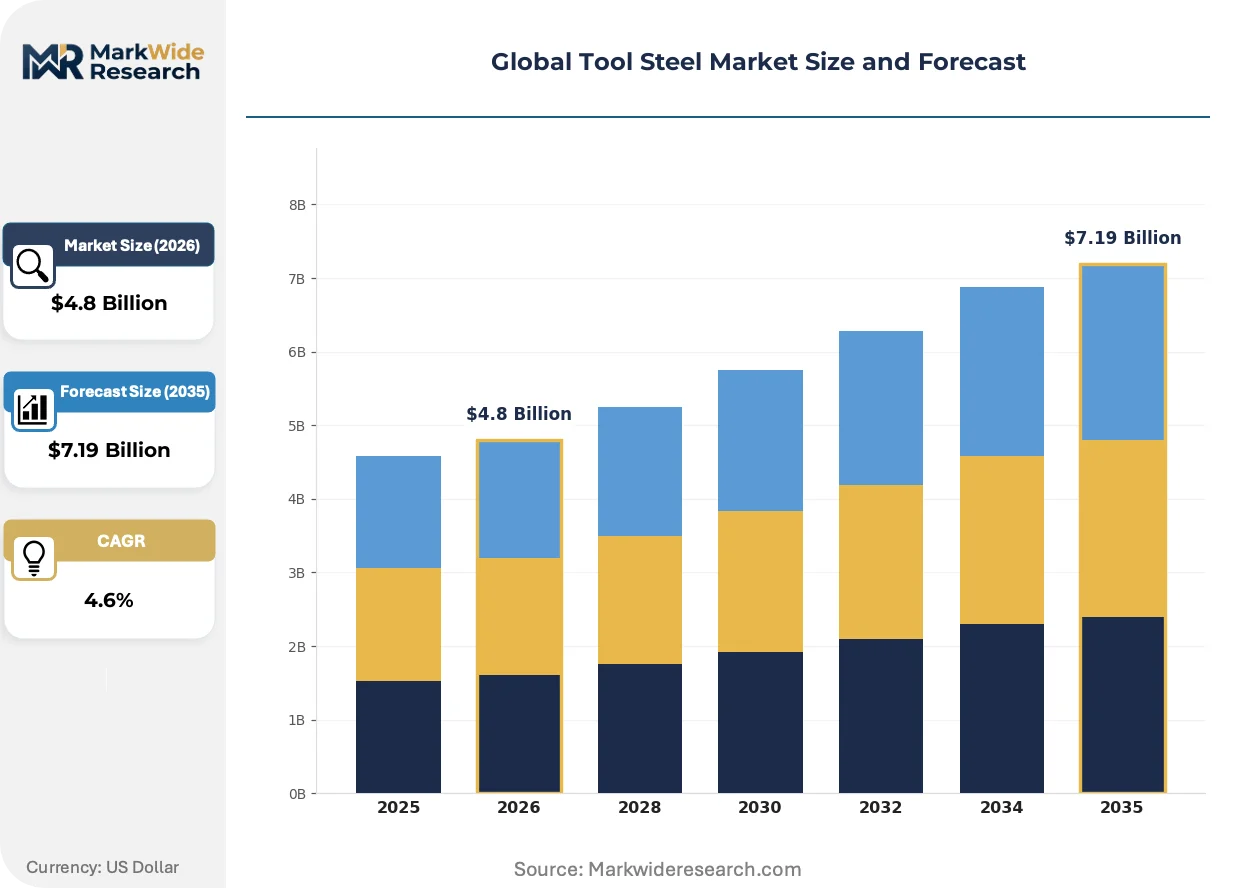
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Speed Steel, Cold Work Tool Steel, Hot Work Tool Steel, Alloy Tool Steel End User: Aerospace, Automotive, Manufacturing, Metalworking Form: Bars, Plates, Coils, Blanks Application: Cutting Tools, Dies, Molds, Industrial Equipment |
| Companies Covered | Voestalpine, Hitachi Metals, Sandvik, Nachi-Fujikoshi Corp, Samuel, Son & Co., Baosteel Group, Tiangong International, Schmolz + Bickenbach, QiLu Special Steel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tool Steel Market Emerging Trajectories
Additive manufacturing of conformal-cooled die inserts is compressing lead times for complex geometries. Powder metallurgy high-speed steel is consolidating grade portfolios. Regulatory pressure on hexavalent chromium is accelerating coating technology substitution.
Powder metallurgy high-speed steel is consolidating cold work and high-speed applications into unified substrate platforms. Tier-one automotive stamping operations in Germany and Japan are adopting PM-HSS for progressive dies previously split between separate D2 and M2 inventories. This substrate unification is compressing distributor SKU counts while elevating technical support requirements for heat treatment parameter optimization.
REACH authorization requirements for cobalt chloride and nickel compounds are forcing reformulation of premium high-performance grades. ECHA's sunset date enforcement is eliminating legacy alloy chemistries from EU-sourced cutting tools. Aerospace suppliers in Italy and Sweden are accelerating tungsten-carbide-cobalt substitution programs to maintain CE-marked product eligibility.
Direct mill-to-OEM contracting is displacing traditional distributor intermediaries for high-volume plate and coil orders. Tier-one stamping houses in China's Yangtze River Delta are negotiating annual tonnage agreements with Voestalpine and Sandvik for standardized die set materials. This channel compression is visible most acutely in automotive supply chains where die life predictability outweighs lot-size flexibility.
Global Tool Steel Market Segmentation
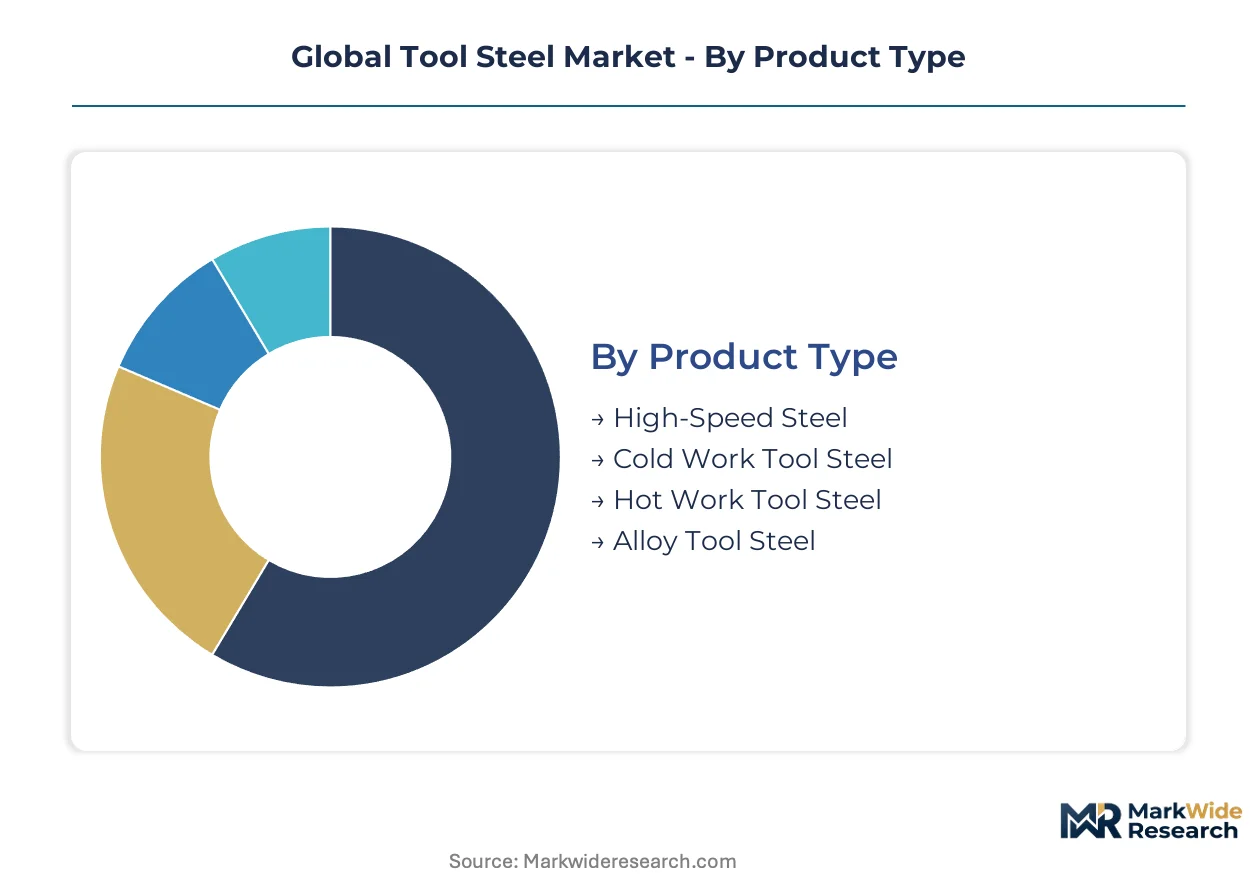
Tool steel procurement patterns diverge sharply between captive die shops requiring heat-treatable blanks and job shops sourcing standardized mill forms. Understanding these structural splits illuminates where substrate-coating integration and compliance documentation create pricing power.
Product Type:
Integration depth varies: cold work grades ship predominantly as standalone die blanks requiring post-processing, while high-speed steel increasingly arrives as coated cutting inserts ready for spindle mounting.
- Cold Work Tool Steel:Chromium-rich air-hardening grades dominate blanking and forming dies where abrasion resistance governs tool life. Automotive OEMs in Germany and Japan consolidate D2 inventories for progressive die applications.
- High-Speed Steel:Tungsten-molybdenum alloys engineered for cutting speeds exceeding 50 meters per minute in titanium machining. Aerospace suppliers in Italy accelerate PM-HSS adoption as REACH cobalt restrictions eliminate legacy M35 chemistries.
- Hot Work Tool Steel:Heat-checking resistant grades for aluminum die casting and forging dies.
- Alloy Tool Steel:Intermediate hardness grades for plastic injection molds and fixture components.
Cold work tool steel leads volumes today; high-speed steel is gaining share fastest.
End User:
Cost tier separation is pronounced: aerospace and automotive OEMs pay premiums for batch-traceable grades with vacuum arc remelt certification, while metalworking job shops prioritize spot-market availability over pedigree documentation.
- Automotive:Stamping operations consume plate and coil tonnage for standardized die sets, with EV platform launches in China's Yangtze River Delta driving high-strength aluminum forming die demand. OEMs consolidate captive die shops to control heat treatment parameters.
- Aerospace:Titanium alloy machining centers specify powder metallurgy substrates with cobalt-reduced chemistries to maintain CE marking under ECHA sunset dates. Italian and Swedish suppliers lead qualification programs for alternative binder systems.
- Manufacturing:General industrial tooling spans maintenance-grade carbon steels through precision instrument applications.
- Metalworking:Job shops and contract manufacturers sourcing bars for customized geometries with flexible lot sizes.
Automotive commands the largest volume position; aerospace exhibits the steepest expansion trajectory.
Form:
Supply concentration shapes availability: bar stock flows through distributor networks serving fragmented job shops, while plates and coils move via direct mill contracts to high-volume stamping houses.
- Bars:Round and square stock for machining custom punch and die components. Voestalpine and Sandvik maintain inventory positions near Stuttgart and Nagoya for just-in-time delivery to tier-one toolrooms.
- Plates:Flat-rolled product for die sets and fixture bases requiring minimal subsequent processing. China's SAMR-mandated traceability certificates add documentation overhead for imported grades used in critical infrastructure.
- Coils:Continuous strip for high-volume progressive die operations with standardized widths and thicknesses.
- Blanks:Pre-cut dimensions for near-net-shape machining, reducing material waste in cutting tool production.
Bars anchor distribution channels today; plates are climbing fastest as direct contracting displaces intermediaries.
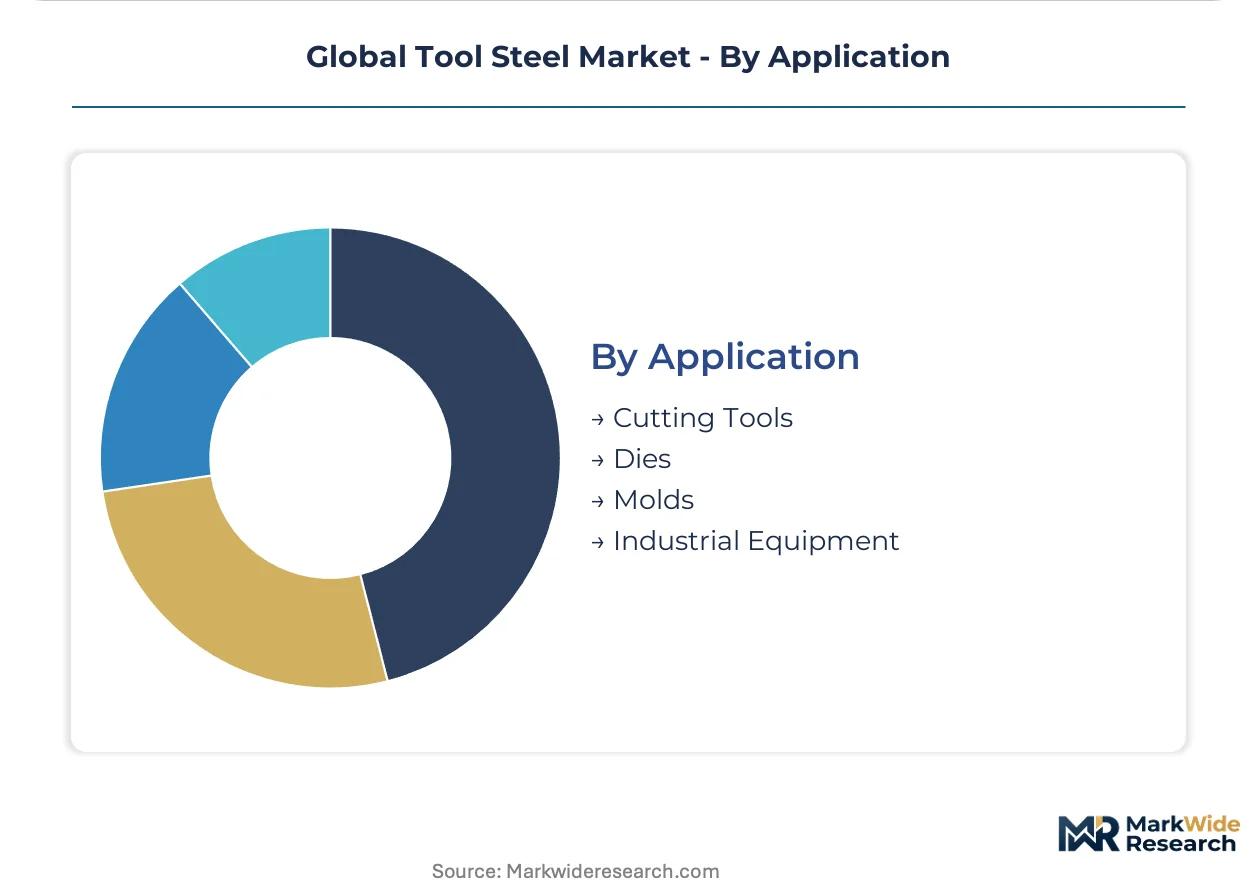
Application:
Customer type determines specification intensity: cutting tool manufacturers demand metallurgical consistency for automated grinding operations, while mold builders prioritize polishability and dimensional stability over bulk hardness.
- Dies:Blanking, forming, and drawing tools for sheet metal operations. REACH hexavalent chromium plating bans accelerate physical vapor deposition substitution for wear-resistant coatings.
- Cutting Tools:Drills, end mills, and inserts for metal removal operations. Powder metallurgy consolidation merges cold work and high-speed requirements into unified substrate platforms.
- Molds:Plastic injection and die casting tooling requiring corrosion resistance and thermal conductivity balance.
- Industrial Equipment:General machinery components, wear parts, and specialized tooling for process industries.
Dies represent the largest application segment; cutting tools are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tool steel metallurgists cluster around Stuttgart, Nagoya, and Shanghai, anchoring regional supply chains to deep heat treatment expertise. These talent concentrations determine where substrate-coating integration and vacuum hardening capabilities concentrate.
United States
Automotive stamping operations in Detroit and the Southeast consume plate tonnage for EV platform dies. EPA greenhouse gas rules constrain electric arc furnace output of high-alloy grades. Tool steel distributors near Chicago maintain inventory positions for tier-one captive die shops.
Germany
Premium automotive OEMs in Baden-Württemberg consolidate D2 inventories for progressive die applications. ECHA REACH authorization requirements for cobalt-bearing alloys elevate compliance costs for cutting tool suppliers. Voestalpine serves Central European tooling customers through integrated steel-to-component contracts.
China
State-owned miners control tungsten concentrate output, exposing Western producers to export quota volatility. SAMR-mandated GB standard traceability certificates add documentation overhead for imported grades. Yangtze River Delta stamping houses negotiate direct mill contracts for standardized die set materials.
Japan
Powder metallurgy high-speed steel adoption accelerates among precision component manufacturers in Nagoya and Osaka. METI industrial standards govern heat treatment parameter certification for aerospace suppliers. Hitachi Metals sustains technology leadership in PM-HSS for cutting applications.
India
PLI scheme incentives for domestic manufacturing create first-mover advantages for suppliers establishing local heat treatment partnerships. BIS standards govern alloy content verification for critical infrastructure applications. Automotive tooling demand concentrates in Maharashtra and Tamil Nadu manufacturing corridors.
Global Tool Steel Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across substrate, coating, and distribution layers. Market structure tilts toward tiered consolidation: integrated steelmakers with captive melt shops command premium grades, while regional distributors serve fragmented job shops with standardized mill forms. Three archetypes dominate: metallurgical integrators controlling chemistry from ore to finished bar; coating-technology developers pairing PVD with optimized substrates; and compliance-enabled distributors monetizing traceability documentation. Competitive moves center on direct mill-to-OEM contracting and substrate-coating convergence.
Among European metallurgical integrators, Voestalpine and Schmolz + Bickenbach occupy positions bridging premium substrate production with component-level delivery. Japanese specialists exemplify powder metallurgy leadership: Hitachi Metals anchors the PM-HSS tier, while Nachi-Fujikoshi Corp sits within cutting tool manufacturing. Chinese state-linked producers including Baosteel Group and Tiangong International represent scale-driven supply concentration. These named entities illustrate how geographic origin and corporate structure map to competitive archetype rather than discrete strategic action.
| Leading Market Players |
|---|
| Voestalpine |
| Hitachi Metals |
| Sandvik |
| Nachi-Fujikoshi Corp |
| Samuel, Son & Co. |
| Baosteel Group |
| Tiangong International |
| Schmolz + Bickenbach |
| QiLu Special Steel |
| Others |
Supply Flow & Price Mechanics
Powder metallurgy high-speed steel consolidation simultaneously compresses distributor SKU economics and elevates substrate-coating bundling premiums. Automotive OEMs in Germany and Japan now source unified PM-HSS platforms that merge previously separate cold work and high-speed inventories, forcing margin recapture through technical service attachment rather than commodity tonnage markups.
Pricing Analysis
Coated-versus-uncoated service splits dominate transaction structures. Three-tier pricing separates vacuum-arc-remelt certified grades from standard air-melt stock and economy carbon steels. Price differentiation hinges on batch-traceable documentation for SAMR compliance and heat treatment parameter certification. Cost compression in standard grades intensifies as direct mill contracting displaces distributor intermediaries. Metalworking job shops exhibit highest price sensitivity; aerospace OEMs absorb premiums for cobalt-reduced REACH-compliant chemistries.
Supply Chain Analysis
Tungsten concentrate supply rests on Chinese state-owned miners controlling concentrate output. Raw material feeds draw from molybdenum Chilean mine operations, vanadium South African processing facilities, and chromium Turkish ferroalloy smelters. Single-source vulnerability concentrates in tungsten export quota volatility. Distribution runs through regional heat treatment partnerships for automotive die shops and direct mill contracts for high-volume stamping houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tool steel procurement functions as a geographic-arbitrage play between EPA-constrained US electric arc furnace production and China's state-subsidized tungsten concentrate dominance. The cost differential creates margin capture opportunities for integrated producers with cross-border logistics capabilities.
For Market Incumbents: Anchor metallurgical expertise through captive vacuum hardening facilities in Stuttgart and Nagoya clusters. Backward integration into tungsten carbide recycling secures input cost stability against Chinese export quota volatility. Certification investment in ECHA REACH-compliant cobalt-reduced grades defends aerospace positioning against sunset date enforcement.
For New Entrants and Emerging Players: Enter via PLI scheme partnerships in Maharashtra and Tamil Nadu manufacturing corridors. India's automotive tooling white space offers lowest incumbent saturation among major demand centers. Local heat treatment joint ventures provide regulatory credibility faster than greenfield melt shop construction.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors lacking SAMR traceability documentation capabilities. Long-term viability favors compliance-enabled intermediaries with middleware integration for batch-level ERP systems. Watch ECHA cobalt authorization enforcement as inflection trigger for alternative binder system qualification premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Recycling | Secures input supply against Chinese export quota volatility. |
| Coating-Substrate Technical Partnership | Enables PVD integration with PM-HSS for aerospace cutting tool demand. |
| SAMR Traceability Certification Service | Creates recurring revenue from GB standard documentation requirements. |
| PLI Scheme Heat Treatment Joint Venture | Captures first-mover positioning in Maharashtra automotive tooling corridor. |
| REACH-Compliant Alloy Reformulation | Maintains CE marking eligibility as ECHA sunset dates eliminate legacy chemistries. |
Methodological Framework
Coverage spans Germany, China, Japan, India, and the United States, with primary inputs from each market cluster. The analysis combines interviews with die shop procurement managers, heat treatment facility technicians, aerospace supplier quality directors, and distributor inventory planners. Secondary validation draws from SAMR GB standard filings, ECHA REACH authorization databases, EPA emissions compliance records, and customs trade flow data. Bottom-up demand modeling triangulates against top-down steel production capacity assessments.
Granularity extends to product type, end user industry, mill form, and application-specific consumption patterns across the projection horizon. The analytical framework models cold work, high-speed, hot work, and alloy grade demand separately, with PM-HSS adoption tracked as cross-cutting technology transition. CAGRs derive from segment-level volume buildups validated against regional automotive stamping capacity expansion and aerospace machining center investment cycles. Tungsten price volatility scenarios inform input cost sensitivity bands.
Inputs from Chinese state-owned miner production statistics and Indian PLI scheme disbursement records were available through the study window; gaps in proprietary heat treatment cost structures introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding REACH enforcement timelines and EPA emissions rule stringency. Material deviation in tungsten export quota allocations or ECHA sunset date acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
High Carbon Bearing Steel Market
Metals
Merchant Bar Quality (MBQ) Steel Market
Metals
Global Titanium Metal Market
Metals
Aluminum Flat-Rolled Products Market
Metals
Saudi Arabia Aluminum Market
Metals
Metal Casting Market
Metals
Aluminium Collars Market
Metals
GCC Metal Forging Market
Metals
Molybdenum Market
Metals
Electrodeposited Copper Foil Market
Metals
Clutch Spring Wires Market
Metals
Copper Azoles Market
Metals
Carbon Steel Market
Metals
North America Metal Finishing Market
Metals
Copper and Copper Alloy Foil Market
Metals
Iron Ore Market