
 Brazil Magnesium Phosphate Market | 2026-2036
Brazil Magnesium Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Magnesium Phosphate Market Insights
A shift from single-source phosphate rock imports toward diversified supplier portfolios is repositioning procurement strategy across Brazilian magnesium phosphate buyers. The Mosaic Company leverages its integrated phosphate mining assets in Peru and Florida to secure captive feedstock for regional blending operations. Yara International ASA anchors its position through controlled-release fertilizer formulations tailored to Cerrado soil conditions. ICL Group Ltd competes via specialty-grade magnesium phosphates serving pharmaceutical and food additive segments.
Magnesium phosphate comprises a family of inorganic salts—dibasic, monobasic, and tribasic forms—produced through neutralization reactions between phosphoric acid and magnesium oxide or hydroxide, with purity grades ranging from technical to food and pharmaceutical specifications. These compounds function primarily as nutrient delivery systems in agriculture, leavening agents and pH stabilizers in food processing, and tablet binders and mineral supplements in pharmaceutical applications. Fertilizer applications dominate volume throughput, reflecting Brazil's status as a leading global soybean and corn exporter, while pharmaceutical-grade tribasic salts command premium pricing due to ANVISA-mandated impurity thresholds. Food additive demand sustains steady growth through processed meat and bakery sector expansion in southern Brazil.
ANVISA governs pharmaceutical-grade magnesium phosphate through Resolução da Diretoria Colegiada standards that mandate heavy metal limits and microbial specifications, directly elevating compliance costs for domestic compounders. The Brazilian Ministry of Agriculture's MAPA regulations classify fertilizer-grade products under Instrução Normativa protocols that require guaranteed nutrient content labeling and restrict contaminant levels. Brazil's adherence to Mercosur technical regulations further harmonizes cross-border trade specifications with Argentine and Paraguayan markets. Stakeholders must monitor evolving fertilizer blending mandates in the new Brazilian Forest Code implementation zones and assess backward integration into domestic phosphate rock beneficiation as import dependency creates margin vulnerability.
Market Dynamics
ANVISA's pharmaceutical-grade purity mandates are compressing margins for domestic compounders while fertilizer-grade volumes expand through soybean belt mechanization. This regulatory divergence splits competitive strategy between premium pharmaceutical positioning and cost-optimized agricultural supply.
Growth Catalysts
- Cerrado Soil Deficiency Correction:Brazilian soybean growers deploy magnesium phosphate to address endemic magnesium depletion in western Mato Grosso and Goiás savanna soils, driving sustained volume demand from precision agriculture adopters.
- Instrução Normativa Fertilizer Blending Mandates:MAPA regulations requiring guaranteed nutrient content labeling force domestic blenders toward certified magnesium phosphate inputs, eliminating unstandardized alternatives from formal channels.
- Controlled-Release Formulation Chemistry:Polymer-coated magnesium phosphate granules extend nutrient availability across Brazilian rainy seasons, reducing application frequency for large-scale corn operations in Paraná.
Market Restraints
- Phosphate Rock Import Concentration:Brazilian manufacturers depend on Moroccan and Russian phosphate rock shipments, exposing margin structures to Black Sea logistics volatility and currency fluctuation.
- Resolução da Diretoria Colegiada Compliance Burden:ANVISA-mandated heavy metal testing and microbial specifications add 15-20% cost premiums to pharmaceutical-grade production, limiting domestic capacity expansion.
- Dolomitic Limestone Substitution:Brazilian lime producers in Minas Gerais market magnesium-enriched agricultural limestone as lower-cost soil amendment alternatives in cattle pasture rehabilitation segments.
Strategic Opportunities
- Pampa Region Food Processing Expansion:Rio Grande do Sul's processed meat and bakery sectors generate untapped food-grade magnesium phosphate demand for pH stabilization and leavening applications.
- Amazon Biome Restoration Incentives:Brazilian Forest Code implementation zones create mandated fertilizer markets for degraded pasture recovery, opening institutional procurement channels.
- Direct-to-Cooperative Distribution:Bypassing traditional agrochemical distributors through digital platforms serving Mato Grosso farm cooperatives reduces working capital cycles and captures price-sensitive volume.
Industry Challenges
- Pharmaceutical Excipient Certification Timeline:ANVISA facility inspections and stability testing protocols extend product registration cycles to 18-24 months, freezing working capital and delaying revenue recognition.
- Multi-Grade Production Switching Costs:Technical-grade to food-grade line conversions require dedicated equipment cleaning and quality system revalidation, constraining operational flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Magnesium Phosphate Market |
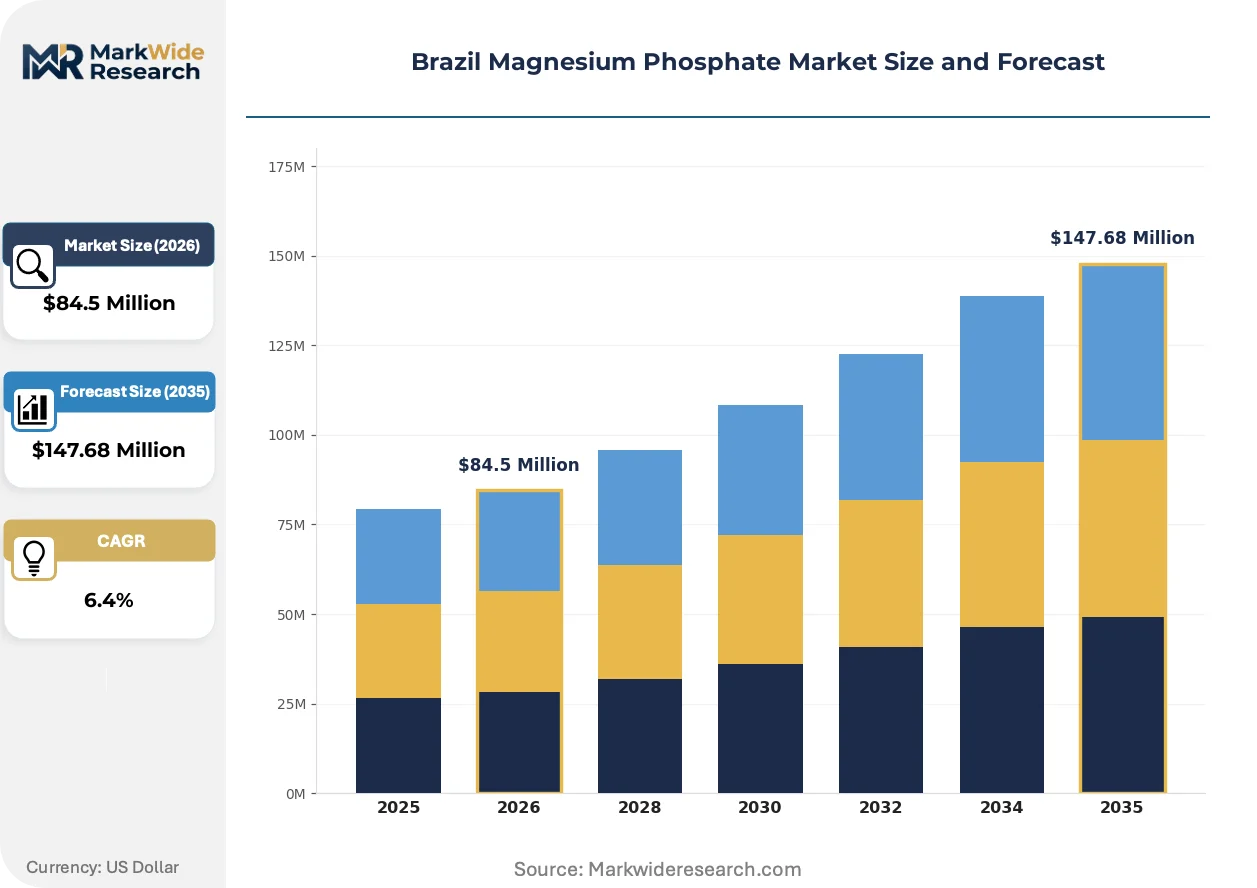
| Market Size in 2026 | $84.5 Million |
| Market Size in 2035 | $147.68 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnesium Phosphate Dibasic, Magnesium Phosphate Monobasic, Magnesium Phosphate Tris, Others Application: Fertilizers, Food Additives, Pharmaceuticals, Animal Feed Form: Powder, Granular, Liquid, Coated End User: Agriculture, Food Industry, Healthcare, Nutraceuticals |
| Companies Covered | The Mosaic Company, Yara International ASA, ICL Group Ltd, Nutrien Ltd, Nortox, Heringer, Innophos Holdings, American Elements, Jost Chemical Co, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Magnesium Phosphate Market Trends and Innovations
Granulation technology and regulatory digitization are restructuring how Brazilian magnesium phosphate reaches agricultural and pharmaceutical end-users. These shifts favor integrated producers with captive technical capabilities.
Fluidized bed granulation is overtaking conventional rotary drum processing for fertilizer-grade magnesium phosphate production. Brazilian blenders serving the Cerrado mechanized soybean sector adopt this technology to achieve uniform particle size distribution and reduce dust emissions during aerial application. The structural compression of smaller batch processors unable to finance equipment upgrades is concentrating supply among capitalized regional compounders.
ANVISA's electronic submission platform for pharmaceutical excipient registrations is accelerating documentation workflows while tightening audit trails. Domestic compounders must now maintain real-time batch records accessible to inspectorate review, elevating IT infrastructure requirements. São Paulo state's pharmaceutical corridor sees first-mover advantages accruing to facilities with integrated manufacturing execution systems.
Cooperative procurement consortia in Mato Grosso and Goiás are consolidating fertilizer purchasing power through volume aggregation platforms. Traditional distributor networks face margin compression as large-scale operations negotiate direct manufacturer contracts with price transparency. This behavioral shift is most visible among soybean producers exceeding 5,000 hectares, where logistics optimization and input standardization override relationship-based supply arrangements.
Brazil Magnesium Phosphate Market Segmentation
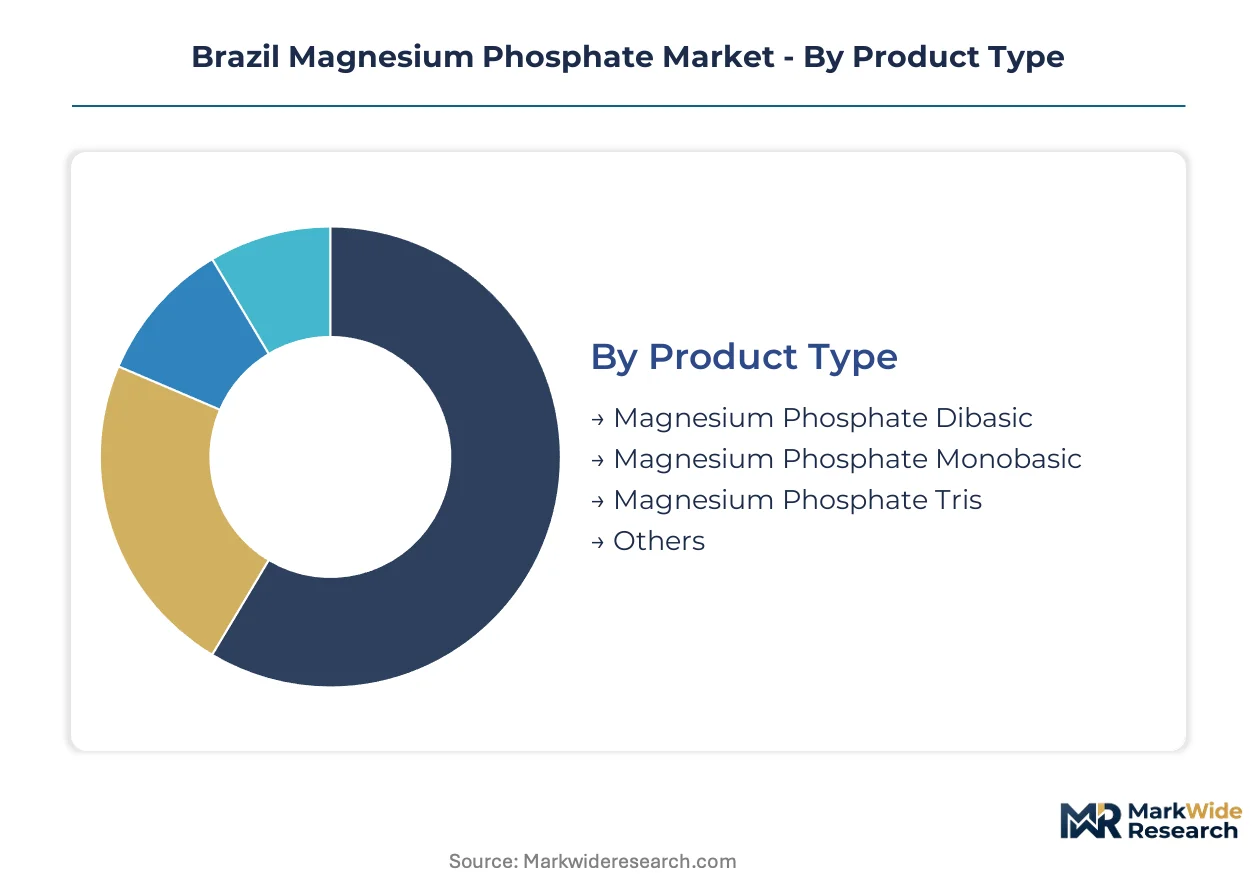
Magnesium phosphate segmentation in Brazil reflects divergent purity requirements across agricultural and pharmaceutical channels. ANVISA-mandated excipient standards create pricing stratification that separates commodity fertilizer grades from certified pharmaceutical formulations.
Product Type:
Fertilizer-grade dibasic salts dominate volume throughput, while pharmaceutical-grade tribasic compounds capture premium pricing tiers.
- Magnesium Phosphate Dibasic:Neutral salt formed through controlled reaction of phosphoric acid with magnesium oxide, yielding MgHPO₄·3H₂O. Brazilian soybean operations in Mato Grosso deploy dibasic formulations for Cerrado soil magnesium correction, with MAPA-mandated nutrient labeling forcing blenders toward certified inputs.
- Magnesium Phosphate Monobasic:Acidic salt (Mg(H₂PO₄)₂) serving specialized fertilizer blends and food leavening applications. Rio Grande do Sul meat processors utilize monobasic salts for pH stabilization in cured products, driving steady demand from southern Brazil's food manufacturing corridor.
- Magnesium Phosphate Tris:Basic salt (Mg₃(PO₄)₂) meeting ANVISA pharmaceutical excipient purity thresholds. São Paulo pharmaceutical compounders absorb 15-20% cost premiums for heavy metal-compliant tribasic grades.
- Others:Specialty hydrates and anhydrous variants serving niche industrial catalyst applications.
Mature deployment sits with dibasic fertilizer grades. Newer deployment is concentrated in tribasic pharmaceutical excipients.
Application:
Volume concentration favors soil amendment uses, while margin capture concentrates in regulated pharmaceutical and food channels.
- Fertilizers:Dominant application channel serving Brazil's soybean-corn rotation systems. Western Goiás mechanized farms deploy magnesium phosphate alongside NPK blends to address endemic magnesium depletion in Cerrado savanna soils.
- Food Additives:Leavening agent and pH buffer functions in processed meat and bakery sectors. Rio Grande do Sul's expanding food processing base generates rising food-grade magnesium phosphate consumption.
- Pharmaceuticals:Tablet binder and mineral supplement applications governed by ANVISA Resolução da Diretoria Colegiada standards. Extended 18-24 month registration timelines constrain domestic supply expansion.
- Animal Feed:Nutritional fortification for poultry and swine operations in Santa Catarina and Paraná.
Cost-optimized deployment centers on fertilizer blending. Premium deployment is accelerating in pharmaceutical excipient certification.
Form:
Physical formulation dictates application economics, with granulation technology investments separating capitalized regional compounders from batch processors.
- Powder:Fine-milled material serving pharmaceutical tableting and food processing. Dust handling requirements limit large-scale agricultural deployment.
- Granular:Fluidized bed granulation products achieving uniform particle distribution for aerial fertilizer application. Cerrado soybean operators favor granular forms for mechanized spreading equipment compatibility.
- Liquid:Suspension concentrates for foliar feeding and specialized fertigation systems.
- Coated:Polymer-encapsulated granules extending nutrient release across Brazilian rainy seasons. Paraná corn operations adopt coated forms to reduce application frequency.
Established supply concentrates in standard powder and granular grades. Coated controlled-release formulations are expanding most quickly among precision agriculture adopters.
End User:
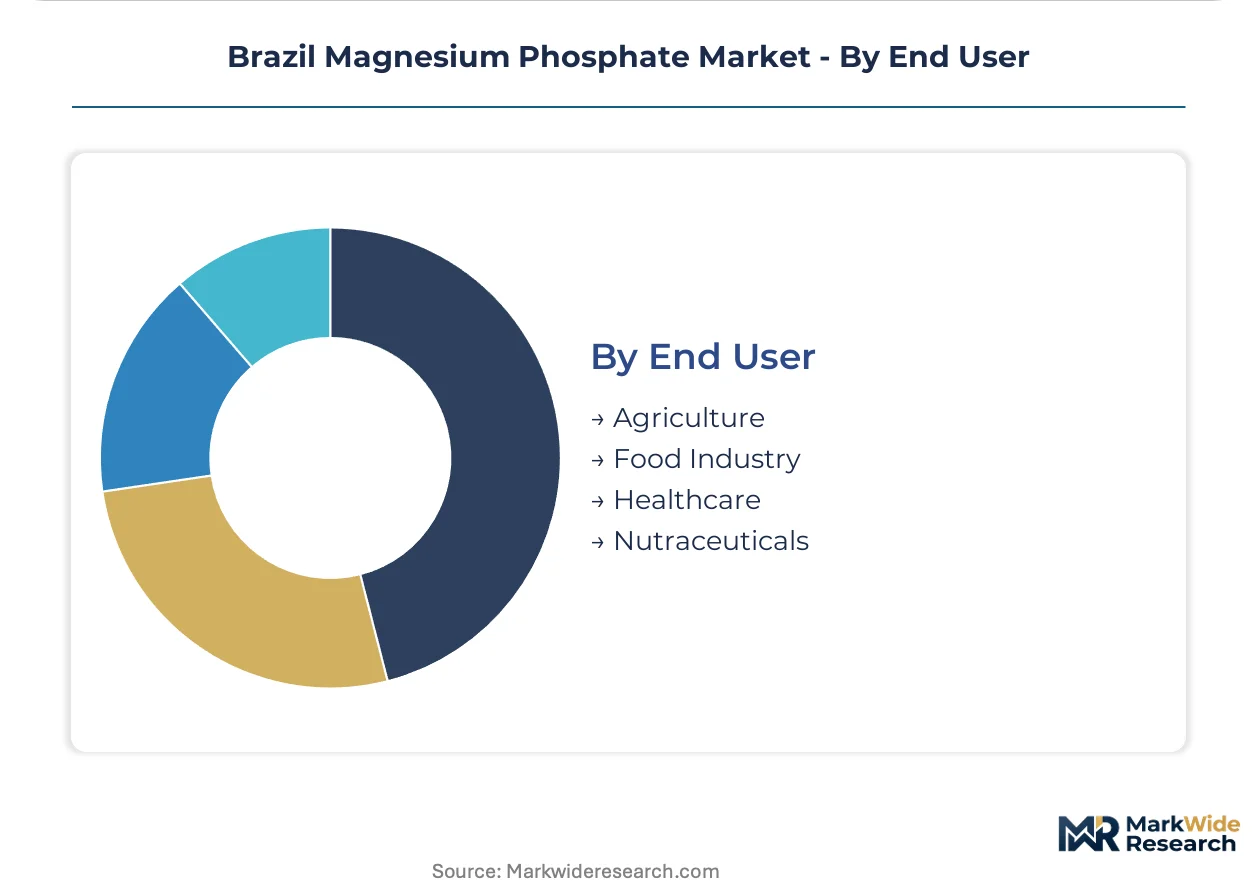
Customer concentration patterns split between dispersed agricultural cooperatives and consolidated pharmaceutical manufacturing clusters.
- Agriculture:Primary demand source encompassing soybean, corn, and cotton operations across Mato Grosso, Goiás, and Paraná. Cooperative procurement consortia in these states are consolidating purchasing power through volume aggregation platforms.
- Food Industry:Processed meat, bakery, and dairy manufacturers in southern Brazil. Rio Grande do Sul's meatpacking sector drives regional food-grade demand concentration.
- Healthcare:Pharmaceutical manufacturers and compounding pharmacies under ANVISA jurisdiction. São Paulo state's pharmaceutical corridor hosts the densest excipient consumption.
- Nutraceuticals:Dietary supplement formulators serving domestic and Mercosur export markets.
Volume leadership resides with agricultural procurement. Margin expansion is concentrated in healthcare excipient supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phosphate rock deposits in Minas Gerais and imported feedstock corridors through Santos port anchor Brazil's magnesium phosphate production geography. State-level regulatory variations and soil chemistry differences create distinct demand clusters across five sub-regions.
São Paulo
Pharmaceutical manufacturing concentration in São Paulo state's industrial corridor drives premium-grade magnesium phosphate consumption. ANVISA's electronic submission platform for excipient registrations accelerates documentation workflows for facilities with integrated manufacturing execution systems. The metropolitan region hosts the densest excipient consumption cluster, with compounders absorbing cost premiums for heavy metal-compliant tribasic grades.
Mato Grosso
Mechanized soybean operations across western Mato Grosso deploy magnesium phosphate to correct endemic magnesium depletion in Cerrado savanna soils. MAPA's Instrução Normativa protocols mandate guaranteed nutrient content labeling, forcing blenders toward certified inputs. Cooperative procurement consortia in this state consolidate purchasing power through volume aggregation platforms, bypassing traditional distributor networks.
Goiás
Precision agriculture adopters in western Goiás sustain volume demand for dibasic fertilizer formulations. The state's location within the Cerrado biome positions it for Brazilian Forest Code implementation zone mandates requiring degraded pasture recovery fertilizers. Fluidized bed granulation technology adoption concentrates among capitalized regional compounders serving this mechanized farm belt.
Rio Grande do Sul
Processed meat and bakery sector expansion generates rising food-grade magnesium phosphate demand for pH stabilization and leavening applications. Monobasic salts serve regional meatpacking operations in cured product manufacturing. The Pampa region's food processing base represents untapped consumption growth relative to established agricultural channels.
Paraná
Corn operations in Paraná adopt polymer-coated magnesium phosphate granules to extend nutrient availability across Brazilian rainy seasons. Controlled-release formulation chemistry reduces application frequency for large-scale operations. The state's position in southern Brazil connects it to Mercosur trade harmonization with Argentine and Paraguayan fertilizer specifications.
Brazil Magnesium Phosphate Market Competitive Landscape
Global majors compete with regional champions across feedstock access and formulation technology. Market structure shows moderate concentration, with integrated phosphate miners holding supply advantages and domestic blenders competing on distribution proximity. Three archetypes dominate: captive-feedstock multinationals, specialty-grade chemical producers, and regional fertilizer compounders. Competitive moves center on backward integration into phosphate rock beneficiation and direct-to-cooperative distribution platform development.
Among captive-feedstock multinationals, The Mosaic Company and Yara International ASA exemplify the integrated mining-to-blending model, leveraging controlled phosphate rock assets to secure regional supply positions. ICL Group Ltd occupies the specialty-grade tier, with its positioning reflecting pharmaceutical and food additive segment focus rather than commodity fertilizer volume play. These three anchors illustrate how feedstock control, formulation chemistry capabilities, and regulatory compliance infrastructure separate competitive tiers in this market.
| Leading Market Players |
|---|
| The Mosaic Company |
| Yara International ASA |
| ICL Group Ltd |
| Nutrien Ltd |
| Nortox |
| Heringer |
| Innophos Holdings |
| American Elements |
| Jost Chemical Co |
| Others |
Pricing and Supply Chain Analysis
Specialized chemical process engineers concentrated in São Paulo state's pharmaceutical corridor drive labor-cost differentials that widen pricing spreads between ANVISA-certified excipient grades and commodity fertilizer formulations. These workforce premiums compound with import-dependent phosphate rock feedstock costs to stratify margin structures across the Brazilian magnesium phosphate market.
Pricing Analysis
Warranty and technical service bundling separates premium pharmaceutical-grade supply from unbundled fertilizer-grade transactions. Three-tier pricing structure across ANVISA-certified, MAPA-labeled, and unstandardized technical grades reflects purity testing and documentation overhead. Price differentiation hinges on heavy metal compliance certification and volume scale, with pharmaceutical compounders absorbing cost premiums for excipient-grade tribasic salts. Cost compression in fertilizer-grade dibasic salts intensifies as cooperative procurement consortia negotiate direct manufacturer contracts. Large-scale soybean operations exceeding 5,000 hectares exhibit lowest price sensitivity, while small cattle pasture rehabilitators in Minas Gerais show highest sensitivity to magnesium-enriched limestone substitutes.
Supply Chain Analysis
Direct-to-cooperative digital platforms serving Mato Grosso farm consortia handle hyperscale agricultural demand, while traditional distributor networks retain pharmaceutical and food-grade channels. Geographic supply concentration draws from Moroccan and Russian phosphate rock shipments, with Peruvian and Florida mining assets providing captive feedstock for integrated multinationals. Raw material dependencies rest on phosphoric acid, magnesium oxide, and polymer coating chemistries for controlled-release formulations. Single-source vulnerability to Black Sea logistics volatility threatens margin stability for domestic compounders lacking backward integration. Distribution runs through Santos port import corridors for feedstock, with regional blending operations in Goiás and Mato Grosso serving final agricultural demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where ANVISA's Resolução da Diretoria Colegiada standards erect barrier-to-entry moats favoring capitalized incumbents with integrated manufacturing execution systems and real-time batch record capabilities.
For Market Incumbents: Anticipate margin compression from cooperative procurement digitization by securing long-term offtake agreements with Mato Grosso and Goiás farm consortia before volume aggregation platforms achieve critical mass. Backward integration into phosphate rock beneficiation mitigates import dependency vulnerability exposed by Black Sea logistics disruptions. Prioritize fluidized bed granulation capacity additions in western Cerrado zones to capture precision agriculture mechanization demand. For New Entrants and Emerging Players: Brazilian Forest Code implementation zones in Amazon Biome restoration areas open a window for institutional procurement channel development, with mandated fertilizer markets for degraded pasture recovery offering white-space access. Rio Grande do Sul's processed meat and bakery sector expansion presents underexploited food-grade magnesium phosphate demand for pH stabilization applications. Pursue direct-to-food-processor distribution bypassing established agrochemical networks to capture margin in southern Brazil's manufacturing corridor. For Investors and Strategic Acquirers: Re-rating potential sits with specialty-grade chemical producers possessing ANVISA excipient certification infrastructure given pharmaceutical outsourcing trends and extended registration timelines freezing domestic capacity expansion. Long-term viability over a 5-10 year window favors targets with captive phosphate rock positions or established controlled-release formulation chemistry capabilities. Monitor cooperative procurement platform transaction volumes as inflection indicator for traditional distributor network displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock Beneficiation | Moroccan and Russian import dependency creates margin vulnerability for compounders lacking captive feedstock security. |
| ANVISA Excipient Certification Investment | Heavy metal compliance infrastructure captures 15-20% cost premium absorption by São Paulo pharmaceutical compounders. |
| Fluidized Bed Granulation Capacity Expansion | Uniform particle distribution technology serves Cerrado mechanized soybean aerial application requirements. |
| Direct-to-Cooperative Distribution Platform | Digital volume aggregation bypasses traditional agrochemical distributor networks in Mato Grosso and Goiás. |
| Controlled-Release Formulation Development | Polymer-coated granules reduce application frequency for Paraná corn operations across Brazilian rainy seasons. |
Research Methodology
Independent corroboration across ANVISA regulatory filings, MAPA fertilizer registration databases, and Brazilian customs trade records underwrites the qualitative findings in this study. Primary interviews with plant managers at phosphate compounders, procurement leads at Mato Grosso farm cooperatives, distribution channel partners in São Paulo's agrochemical corridor, and technical R&D directors at specialty chemical producers combined with secondary validation from SEC 10-K filings of listed phosphate miners, Cefic chemical industry reports, and Brazilian Ministry of Agriculture statistical releases. Bottom-up demand modeling and top-down supply capacity assessment triangulate volume estimates.
Comparable-period anchoring to historical fertilizer consumption patterns and pharmaceutical excipient registration timelines established the forecast window baseline. Across the analysis window, segmentation dimensions modeled include product grade tier, application channel, physical form specification, and regional production hub. CAGRs derive from weighted average growth assumptions applied to each segment. Industry-specific forecast inputs incorporate Cerrado soil magnesium deficiency correction rates and ANVISA electronic submission platform adoption curves.
The model assumes a particular technology adoption path; alternative pathways for fluidized bed granulation would alter the outlook if rotary drum processing retains cost advantages for smaller batch processors. Forecasts reflect base-case assumptions regarding phosphate rock import price stability and cooperative procurement platform penetration rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Lithium Bromide Market
Bulk Chemicals
Hydrated Lime Market
Bulk Chemicals
Ethylbenzene Market
Bulk Chemicals
Aluminum Sulfide Market
Bulk Chemicals
Global 2-Ethylhexanoic Acid Market
Bulk Chemicals
Barium Nitrate Market
Bulk Chemicals
Tallow Market
Bulk Chemicals
Diisopropylbenzene Market
Bulk Chemicals
North America Polyvinyl Chloride (PVC) Market
Bulk Chemicals
Ferric Sulfate Market
Bulk Chemicals
Formate Brine Market
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market
Bulk Chemicals
North America Potassium Permanganate Market
Bulk Chemicals
Asia-Pacific Polyvinyl Chloride (PVC) Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market