
 Metal Forging Parts Market | 2026-2036
Metal Forging Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Forging Parts Market Insights
Defense contractors and renewable energy OEMs are reorganizing procurement priorities toward domestic and near-shore forging sources. Bharat Forge Ltd. anchors Indian supply capacity for artillery and aerospace-grade components. Thyssenkrupp Forged Technologies dominates European closed-die production for power generation shafts. Precision Castparts Corp. specializes in titanium aerospace forgings with exacting metallurgical consistency.
Metal forging parts are workpieces shaped by compressive forces under controlled temperature and pressure, typically achieving grain flow alignment that delivers fatigue resistance above 100,000 psi in critical aircraft and powertrain applications. Closed die forging commands the largest value share due to dimensional precision in automotive and aerospace batch production, while cold forging is expanding fastest among aluminum chassis and electric motor shaft segments where net-shape forming reduces machining waste. Titanium and nickel-based superalloy material categories carry the deepest margin pools given aerospace certification barriers and limited qualified supplier bases.
The US FAA and EPA regulate airframe material traceability and foundry emissions respectively, tightening market access for uncertified producers. India's BIS and CDSCO enforce domestic material standards and defense procurement qualification protocols that shape local forge capacity expansion. Stakeholders must monitor evolving alloy specification changes from ISO and ASTM committees that determine qualification timelines and capital allocation across forge shop upgrades.
Market Dynamics
Commercial aircraft production recovery and defense procurement acceleration are compressing qualified supplier lead times for aerospace-grade forgings, while EPA emissions enforcement and FAA material traceability mandates are raising capital barriers for forge shop certification.
Growth Catalysts
- Commercial aviation recovery:Airframe OEMs are expanding titanium and nickel superalloy component orders as narrowbody and widebody production rates climb, pulling demand through qualified forging networks.
- IRA clean energy incentives:US tax credits for domestic wind turbine and nuclear component manufacturing are redirecting capital toward certified forge capacity for power generation shafts and pressure vessels.
- Closed-die precision requirements:Automotive powertrain electrification is demanding net-shape aluminum forgings with tighter dimensional tolerances, favoring capital-intensive press investments over open-die alternatives.
Market Restraints
- Scrap metal price volatility:Nickel and titanium sponge input costs swing with mining supply disruptions and speculative trading, compressing margin predictability for long-delivery aerospace contracts.
- Qualified supplier concentration:FAA-certified titanium forging capacity clusters among a handful of North American and European facilities, creating single-source vulnerability for critical airframe components.
- Additive manufacturing substitution:Powder-bed fusion and directed energy deposition are capturing low-volume aerospace bracket and manifold applications previously served by machined forgings.
Strategic Opportunities
- Indian defense localization:BIS certification pathways and domestic procurement mandates under the Defence Acquisition Procedure are opening captive demand for artillery and armored vehicle forging capacity expansion.
- Offshore wind monopile transitions:European North Sea installation scale-up is requiring forged transition piece flanges in dimensions exceeding current press capabilities, rewarding greenfield capacity investments.
- Digital thread integration:Convergence of IoT furnace monitoring with blockchain material traceability is enabling real-time certification documentation that accelerates FAA and EASA audit cycles.
Industry Challenges
- Metallurgical engineer scarcity:Specialized expertise in superalloy thermal-mechanical processing and grain structure control is retiring faster than apprenticeship pipelines can replenish across US and European forge shops.
- Multi-year certification timelines:FAA airframe material qualification protocols require extensive fatigue testing and statistical process validation that locks capital in pre-revenue development for three to five years.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Forging Parts Market |
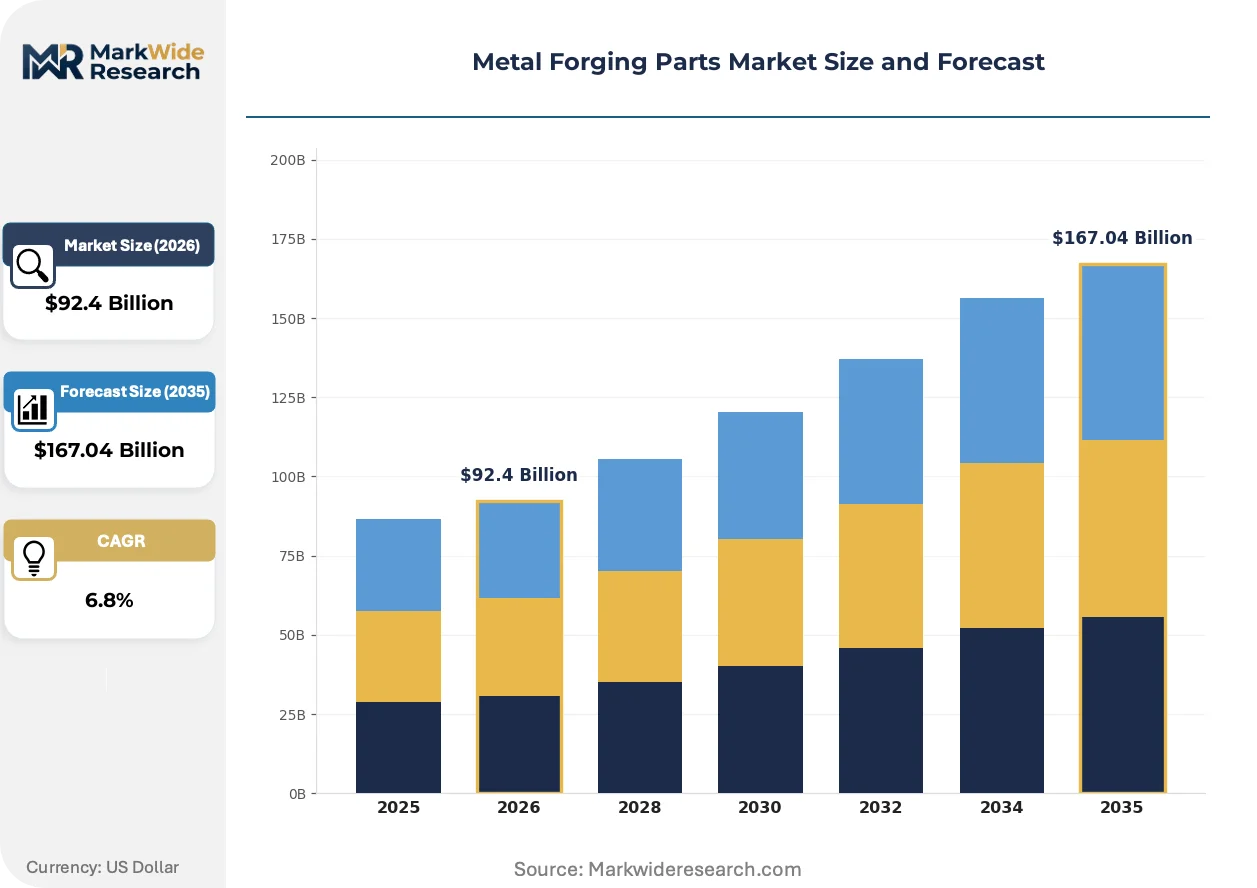
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $167.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Die Forging, Closed Die Forging, Impression Die Forging, Roll Forging, Cold Forging Material: Carbon Steel, Alloy Steel, Stainless Steel, Aluminum, Titanium, Brass Application: Aerospace Components, Construction Equipment, Power Generation, Heavy Machinery, Shipbuilding End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Scot Forge, Ellwood Group Inc., Bharat Forge Ltd., Allegheny Technologies Inc., China First Heavy Industries, Thyssenkrupp Forged Technologies, Japan Casting & Forging Corporation, American Axle & Manufacturing, Precision Castparts Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Forging Parts Market Trends and Innovations
Digital process control and alternative forming technologies are fragmenting traditional competitive moats in forging, while regulatory data requirements are reshaping what constitutes a qualified supplier.
Isothermal forging is decomposing the conventional hot-die production paradigm for complex titanium aerospace components. Pratt & Whitney and Rolls-Royce engine programs are specifying isothermally forged compressor disks at accelerating rates. This controlled-temperature approach is decomposing the volume advantages of mechanical press operations by enabling near-net shapes that eliminate 40-60 percent of downstream machining.
REACH substance restrictions and EU Green Deal carbon border adjustments are tightening documentation requirements for imported steel and nickel alloy feedstocks. European forge shops must now demonstrate Scope 3 emissions transparency across ore extraction and primary refining stages. Aerospace tier-one suppliers with EU manufacturing footprints are responding by qualifying domestic European melt sources ahead of anticipated carbon tariff implementation.
Buyer consolidation among airframe OEMs is compressing supplier negotiation cycles and unbundling traditional long-term forging contracts. Boeing and Airbus procurement teams are shifting toward modular component sourcing with shorter renewal windows and performance-indexed pricing. This behavioral shift is most visible in North American titanium forging procurement, where multi-year sole-source agreements are fragmenting into competitive annual tenders with embedded volume flexibility clauses.
Metal Forging Parts Market Segmentation
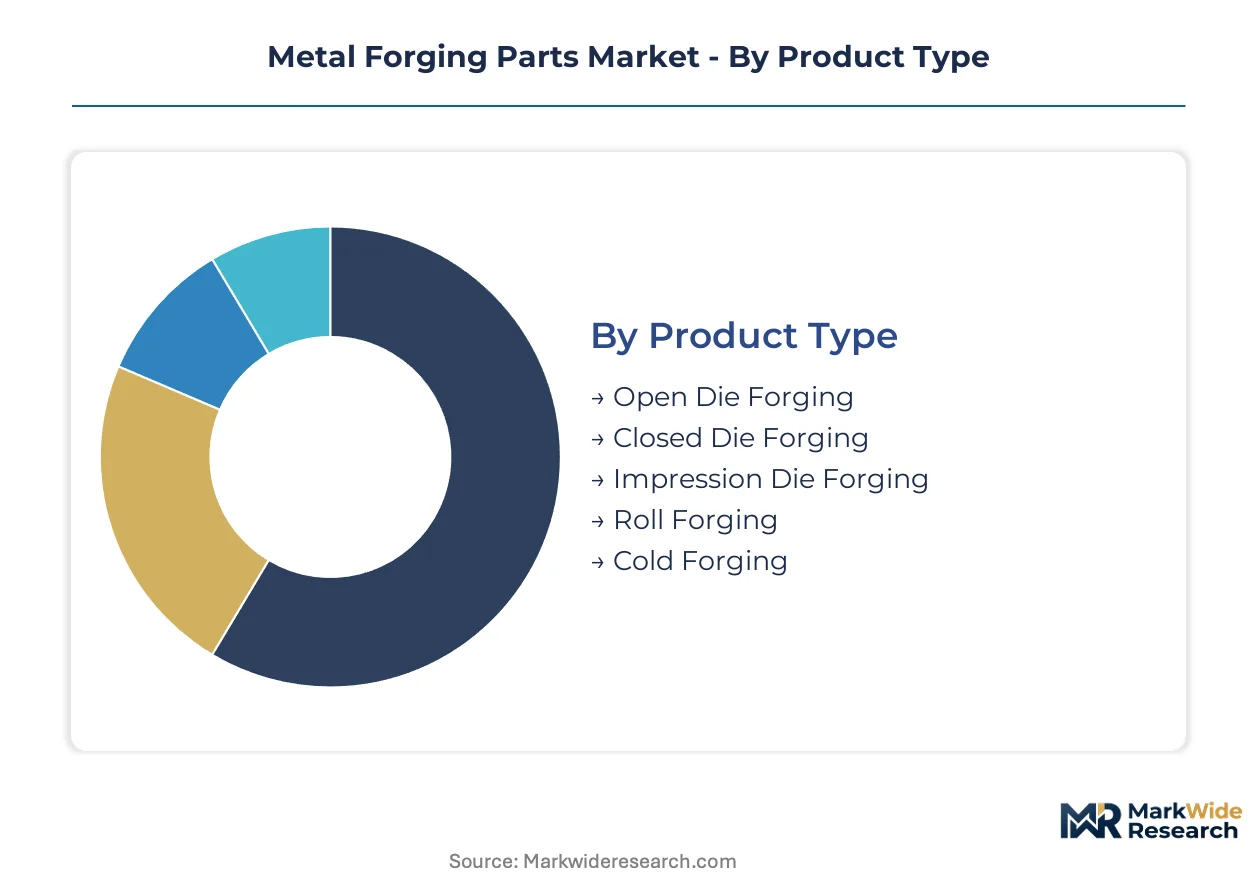
Metal forging parts segmentation reflects divergent certification requirements across aerospace, defense, and industrial end-uses. Each product type and material category carries distinct capital intensity barriers and regulatory qualification timelines that reshape supplier competitive positioning.
Product Type:
FAA airframe traceability mandates and EPA foundry emissions standards create tiered certification barriers that concentrate qualified capacity among closed-die and isothermal forging specialists.
- Open Die Forging:Large-scale hammer or press forming without enclosure dies produces rough geometries requiring extensive secondary machining. Demand concentrates in US and German heavy machinery shaft applications where dimensional tolerance requirements remain permissive and lot sizes justify the lower tooling investment.
- Closed Die Forging:Enclosed die cavities deliver net-shape precision with aligned grain flow exceeding 100,000 psi fatigue resistance. Aerospace OEMs in France and Japan specify closed-die compressor disks and landing gear components where FAA and EASA material qualification protocols lock out uncertified competitors.
- Impression Die Forging:Partial enclosure dies balance geometric complexity with tooling economy for mid-volume automotive and construction equipment runs.
- Roll Forging:Rotary reduction mills elongate bar stock into crankshafts and axle beams with continuous grain orientation.
- Cold Forging:Near-net aluminum forming at ambient temperature eliminates machining waste for electric motor shafts and chassis brackets in Japanese and South Korean automotive supply chains.
Established volume favors closed-die precision; emerging adoption favors cold forging efficiency.
Material:
Cost tiers separate commodity carbon grades from superalloy categories where limited qualified melt sources create supply concentration.
- Carbon Steel:Plain iron-carbon alloys below 0.3% carbon content dominate construction equipment and general machinery forgings. Indian and Chinese forge shops exploit raw material proximity for cost-competitive output in non-certified industrial applications.
- Alloy Steel:Chromium, molybdenum, and nickel additions enhance hardenability for crankshafts and transmission gears. German and Italian automotive Tier-1 suppliers specify vacuum-degassed alloy grades where inclusion control determines fatigue life.
- Stainless Steel:Corrosion-resistant austenitic and martensitic grades serve chemical processing and marine hardware with varying chromium-nickel ratios.
- Aluminum:6XXX and 7XXX series alloys enable weight reduction in electric vehicle structural members with lower forming temperatures than ferrous alternatives.
- Titanium:Alpha-beta alloys Ti-6Al-4V dominate aerospace compressor and fan disk applications where specific strength requirements exclude substitute materials.
- Brass:Copper-zinc alloys provide machinability and corrosion resistance for plumbing fittings and electrical hardware at moderate mechanical loads.
Commodity grades concentrate in Asian volume production; titanium and superalloys anchor Western aerospace margins.
Application:
Customer maturity and specification stringency fragment procurement patterns across end-use verticals.
- Aerospace Components:FAA and EASA material qualification mandates govern every heat of titanium and nickel superalloy forgings for airframes and engines. US and French OEMs maintain approved supplier lists with multi-year audit cycles that exclude new entrants lacking statistical process control documentation.
- Construction Equipment:Hydraulic cylinder rods and boom pivot forgings prioritize yield strength and weldability over dimensional precision. Chinese and Indian infrastructure investment cycles drive demand volatility in this price-sensitive segment.
- Power Generation:Steam and gas turbine rotor forgings require vacuum arc remelted ingots with ultrasonic inspection certification per ASME standards.
- Heavy Machinery:Mining and agricultural equipment frames utilize open-die forgings where impact toughness outweighs surface finish requirements.
- Shipbuilding:Propeller shafts and rudder stocks demand longitudinal grain alignment for torsional fatigue resistance in corrosive marine environments.
Certification intensity favors aerospace component specialization; infrastructure cyclicality favors construction equipment scale.
End User:
Supply chain position determines technical collaboration depth and contract duration across procurement tiers.
- OEMs:Airframe and powertrain manufacturers specify proprietary alloy chemistries and thermal-mechanical processing windows. Boeing, Airbus, and Rolls-Royce engineering teams co-develop forging sequences with qualified suppliers, embedding intellectual property that extends contract tenors.
- Tier-1 Suppliers:System integrators like landing gear and transmission specialists consolidate multi-component sourcing with forge shops capable of concurrent engineering support.
- Aftermarket Providers:MRO distributors procure replacement forgings through spot market channels with reduced documentation requirements.
- Vehicle Assemblers:Final manufacturers in commercial trucking and agricultural equipment source standard-grade forgings through competitive tender processes.
Technical integration favors OEM direct relationships; price transparency favors aftermarket spot procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian forging exports to European aerospace OEMs are accelerating as supply chain reconfiguration displaces traditional sourcing corridors. German automotive Tier-1 suppliers are absorbing capacity from shuttered Eastern European forge shops. Chinese state-directed investment in closed-die capacity is capturing domestic wind turbine flange demand previously served by imports.
United States
FAA-certified titanium forging demand from Boeing and Pratt & Whitney engine programs is absorbing capacity across Pennsylvania and Ohio industrial corridors. The EPA enforces foundry emissions standards that raise capital barriers for new market entrants. Houston and Dallas-Fort Worth clusters host oilfield equipment forging operations serving Permian Basin extraction equipment replacement cycles.
Germany
REACH substance restrictions and EU Green Deal carbon border adjustments are forcing documentation upgrades across Ruhr Valley forge operations. The KBA enforces automotive component traceability mandates that reshape supplier qualification protocols. Baden-Württemberg precision forgers supply Bosch and ZF Friedrichshafen with transmission gear blanks requiring vacuum-degassed alloy grades.
India
BIS certification pathways and Defence Acquisition Procedure localization mandates are opening captive demand for artillery and armored vehicle components. Bharat Forge anchors Maharashtra-based capacity expansion serving domestic OEM supply chains. Pune and Chennai industrial belts concentrate closed-die operations for automotive powertrain exports to Southeast Asian assemblers.
China
MIIT-directed capacity rationalization is consolidating open-die forging operations in Hebei and Shandong provinces. GB standards enforcement raises quality documentation requirements for wind turbine flange exports to European developers. Yangtze River Delta clusters supply CRRC with rail axle forgings for high-speed network expansion.
Japan
METI industrial policy supports isothermal forging technology adoption for aerospace compressor disk applications. JIS standards govern material qualification for IHI and Kawasaki Heavy Industries turbine component sourcing. Nagoya and Osaka industrial corridors concentrate precision forgers serving Toyota and Honda electrification programs with aluminum chassis components.
Metal Forging Parts Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive metallurgical expertise and specialized aerospace certification holders. Consolidation patterns favor scale-driven operators capable of absorbing multi-year FAA qualification timelines. Two strategic archetypes dominate: vertically integrated primary metal producers with downstream forging assets, and independent precision specialists with exclusive OEM engineering relationships. Competitive moves center on capacity expansion in Indian defense corridors and strategic partnerships for digital thread certification technologies.
Among diversified industrial conglomerates, Thyssenkrupp Forged Technologies and China First Heavy Industries exemplify scale-driven archetypes with integrated primary metal and downstream forging operations. Bharat Forge Ltd. occupies a position within the defense-aerospace specialist tier, representing Indian localization momentum. Precision Castparts Corp. anchors the premium certification holder segment, sitting within a narrow qualified supplier base for titanium aerospace components. These three entities collectively illustrate the geographic and capability stratification shaping procurement negotiations.
| Leading Market Players |
|---|
| Scot Forge |
| Ellwood Group Inc. |
| Bharat Forge Ltd. |
| Allegheny Technologies Inc. |
| China First Heavy Industries |
| Thyssenkrupp Forged Technologies |
| Japan Casting & Forging Corporation |
| American Axle & Manufacturing |
| Precision Castparts Corp. |
| Others |
Pricing and Supply Chain Analysis
Titanium sponge substitution for nickel-based superalloys in select compressor applications is redrawing raw material procurement maps and compressing margin structures across aerospace forging tiers. This displacement simultaneously elevates Indian and Chinese sponge supply positions while pressuring legacy Western melt-based pricing premiums.
Pricing Analysis
Technology-generation pricing gaps separate isothermal-forged next-generation compressor disks from conventional hot-die legacy components and transitional closed-die precision grades. Three-tier pricing structure across premium, standard, and economy levels reflects FAA certification intensity, vacuum arc remelting requirements, and statistical process control documentation depth. Pricing pressure stems from buyer consolidation among Boeing and Airbus procurement teams shifting toward competitive annual tenders with embedded volume flexibility. Aftermarket providers exhibit highest price sensitivity due to reduced documentation requirements and spot-market procurement channels, while OEM direct relationships sustain premium tiers through co-development IP embedding.
Supply Chain Analysis
Inbound logistics costs for titanium sponge from Ukrainian and Russian feedstock corridors have rerouted through Rotterdam and Singapore transshipment nodes, elongating lead-time uncertainty. Supply concentrates in India, China, and the United States for qualified closed-die capacity, with Germany and Japan anchoring precision isothermal operations. Raw material flows draw from Australian rutile sand, Chinese magnesium reduction facilities, and US vacuum arc remelting ingot sources. Single-source vulnerability clusters around FAA-certified titanium forging capacity concentrated among Pennsylvania and Ohio industrial corridors. Distribution runs through aerospace tier-one system integrators consolidating multi-component sourcing with concurrent engineering support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital thread certification services and blockchain material traceability subscriptions are expanding faster than physical forging capacity, creating recurring-revenue layers that outpace hardware margin trajectories. This service-attach dynamic redefines supplier valuation beyond tonnage throughput toward data-integrated qualification persistence.
For Market Incumbents: Consolidate around captive metallurgical expertise and multi-year FAA certification investments to defend against additive manufacturing substitution in low-volume aerospace bracket applications. Prioritize backward integration into titanium sponge reduction capacity to offset nickel and titanium input cost volatility. Expand isothermal forging press installations in Maharashtra and Ohio corridors to capture Pratt & Whitney and Rolls-Royce engine program specifications. For New Entrants and Emerging Players: Differentiate on digital thread integration capabilities that compress FAA and EASA audit cycles through real-time IoT furnace monitoring and blockchain documentation. Target Indian defense localization corridors where BIS certification pathways and Defence Acquisition Procedure mandates open captive demand for artillery and armored vehicle components. Pursue joint development agreements with European offshore wind developers requiring forged transition piece flanges exceeding current press capabilities. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision forging specialists holding exclusive OEM engineering relationships but lacking capital for multi-year FAA qualification timelines. Long-term viability over a five-to-ten-year horizon hinges on digital certification technology integration and geographic diversification into Indian defense corridors. Monitor isothermal forging adoption rates among engine OEMs as inflection indicator for next-generation capacity obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Isothermal Forging Capacity Expansion | Pratt & Whitney and Rolls-Royce specifications are accelerating near-net shape adoption for compressor disks. |
| Backward Integration into Titanium Sponge | Captive reduction capacity insulates margin predictability against Australian rutile supply disruptions. |
| Digital Thread Certification Platform | IoT furnace monitoring with blockchain traceability accelerates FAA audit cycles and reduces qualification friction. |
| Indian Defense Localization Partnership | BIS certification and Defence Acquisition Procedure mandates create captive demand for artillery forging capacity. |
| Offshore Wind Monopile Flange Qualification | European North Sea installation scale-up rewards greenfield capacity for dimensionally extreme transition pieces. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with forging plant managers, aerospace OEM procurement directors, metallurgical engineers, and aftermarket service heads; and secondary validation through FAA airframe material qualification databases, EPA foundry emissions filings, customs and trade data, and SEC 10-K disclosures from diversified industrial conglomerates. Bottom-up capacity and utilization estimates triangulated against top-down end-use demand segmentation across commercial aviation, defense, and power generation verticals.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type precision tiers, material certification grades, application stringency levels, and regional regulatory clusters. CAGRs derived from historical production rate correlations with airframe OEM delivery schedules and defense procurement cycles. Forecast inputs incorporated IRA clean energy incentive impacts on domestic wind turbine component demand and REACH substance restriction compliance costs across European forge operations.
Material uncertainties — alloy specification changes from ISO and ASTM committees, scrap metal price volatility from mining supply disruptions, and additive manufacturing substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding qualified supplier concentration persistence and certification timeline stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Stainless Steel Sheet Market
Metals
Copper and Copper Alloy Powder Market
Metals
Global Oxygen-Free Copper Market
Metals
Europe Aluminum Extrusion Market
Metals
Global Nickel Alloy Welding Consumables Market
Metals
GCC Aluminium Powder Market
Metals
Rolled Steel Motor Market
Metals
Armour Steel Plate Market
Metals
Tin Chloride Market
Metals
Global Vanadium Market
Metals
Aluminum Sheet Market
Metals
Global Copper Cathode Market
Metals
Clutch Spring Wires Market
Metals
Beryllium Copper Billet Market
Metals
Carbon Steel Market
Metals
Stainless Steel Round Bar Market