
 Ceramic Ware Market | 2026-2036
Ceramic Ware Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Ware Market Outlook
Premium-grade porcelain is bifurcating the Ceramic Ware landscape as hospitality buyers demand higher thermal shock resistance and translucency benchmarks. Villeroy & Boch leverages its German manufacturing heritage to sustain dominance in fine-dining tableware across European capitals. Noritake anchors Asian supply through advanced glaze chemistry R&D in its Japanese production facilities. Clay Craft India competes aggressively on hand-painted artisan designs for boutique hotel chains.
Ceramic ware encompasses fired clay bodies shaped into functional and decorative vessels, typically vitrified at temperatures exceeding 1,200°C for porcelain to achieve non-porous, durable surfaces suitable for food contact and thermal cycling. The primary commercial purpose spans food service presentation, cooking containment, and interior décor across residential and institutional settings. Dinnerware and tableware categories lead volume throughput due to replacement cycles in restaurant operations, while bone china commands the deepest margin pools among material grades. Cookware applications are gaining structural traction as induction-compatible ceramic coatings penetrate professional kitchen procurement lists.
EU REACH restrictions on lead and cadmium in food-contact ceramics are compelling reformulation of traditional glazes across export-oriented producers. FDA compliance for import clearance into the United States shapes quality documentation requirements for Asian manufacturers. ISO 6486 testing protocols for metal release from ceramic surfaces increasingly determine market access eligibility in premium segments. Stakeholders must monitor evolving carbon-border tariff implementations and their cascading impact on kiln-energy sourcing decisions.
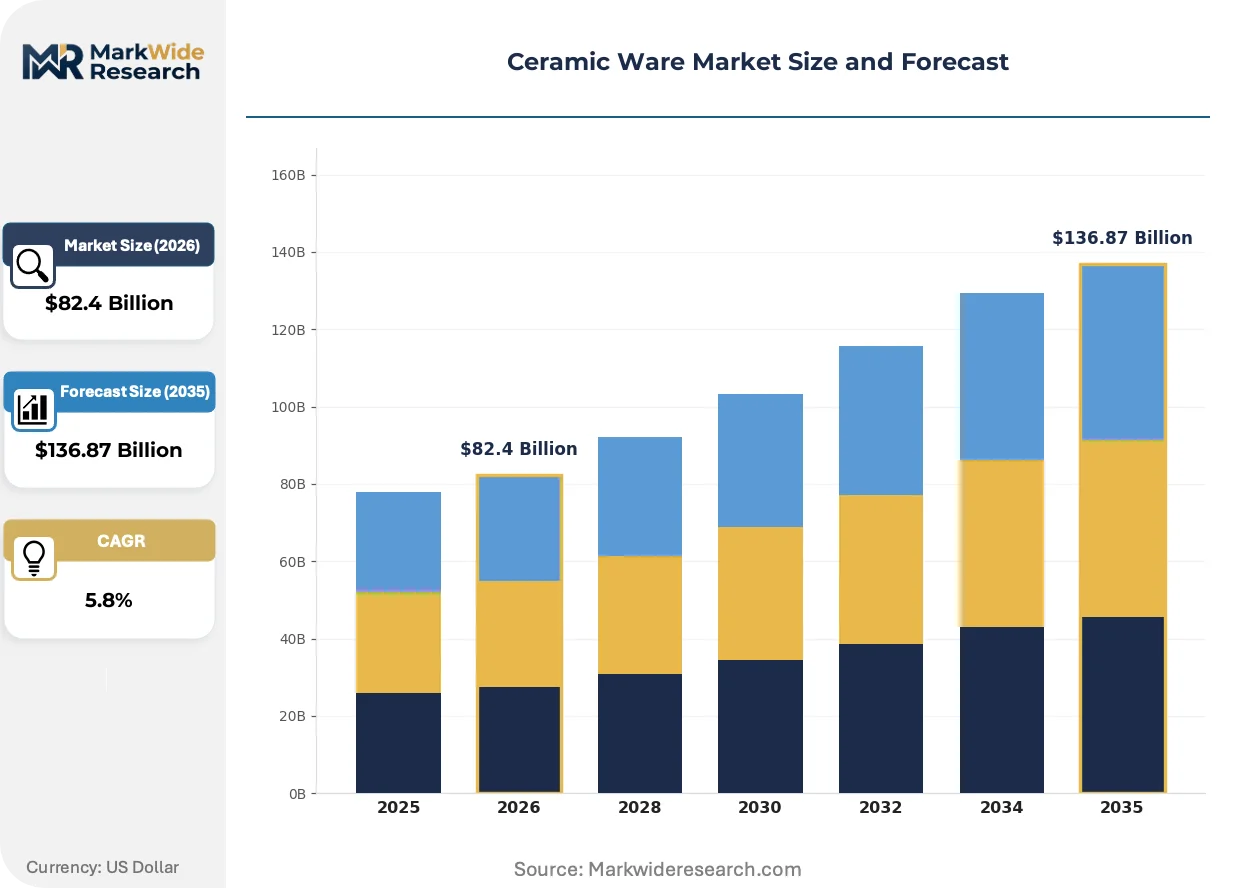
Market Dynamics
EU Green Deal carbon-border adjustments are forcing export-oriented kilns to restructure energy sourcing, bifurcating competitive advantage between gas-dependent legacy producers and renewable-powered facilities.
Growth Catalysts
- Induction-compatible ceramic coatings:Professional kitchen procurement lists now specify cookware with ferromagnetic bases, pulling specialty glaze R&D investment from Japanese and German technical ceramics clusters.
- REACH compliance elevation:Lead and cadmium restrictions in food-contact surfaces are locking out non-compliant Asian exporters, creating protected margin pools for reformulation-capable manufacturers serving European hospitality buyers.
- Vietnam ceramics cluster expansion:Hanoi and Ho Chi Minh City production zones are capturing restaurant and catering service contracts across Southeast Asia through integrated porcelain and bone china supply chains.
Market Restraints
- Natural gas price volatility:Kiln firing consumes 35-45% of production energy; European manufacturers face input cost compression that renewable-transitioning competitors in Vietnam partially escape.
- China supply concentration:Rare earth stabilizers and specialized feldspar shipments originate from concentrated domestic Chinese processors, exposing downstream glaze formulators to single-source disruption risk.
- Technical limitation in thin-wall production:Bone china translucency benchmarks below 0.8mm wall thickness remain achievable only by established German and Japanese facilities with proprietary mold-flow control.
Strategic Opportunities
- Underpenetrated Indian boutique hospitality:Clay Craft India demonstrates demand for hand-painted artisan designs; replication potential exists across Rajasthan and Gujarat heritage hotel chains seeking differentiated tableware.
- EU Green Deal regulatory tailwind:Carbon-border tariff phase-in creates first-mover advantage for Vietnamese facilities completing biomass kiln conversions before 2026 enforcement deadlines.
- Direct-to-hospitality platform distribution:Procurement aggregators bypass traditional import distributors, enabling Vietnamese and Indian manufacturers to capture margin previously allocated to European trading houses.
Industry Challenges
- ISO 6486 certification timeline:Metal release testing protocols require 12-18 month documentation cycles that delay market access for reformulated glazes, compressing product launch windows.
- Legacy kiln reconfiguration capex:Biomass or hydrogen burner retrofits demand $2-4 million per facility, straining mid-cap producers without parent-company balance sheet support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Ware Market |
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $136.87 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
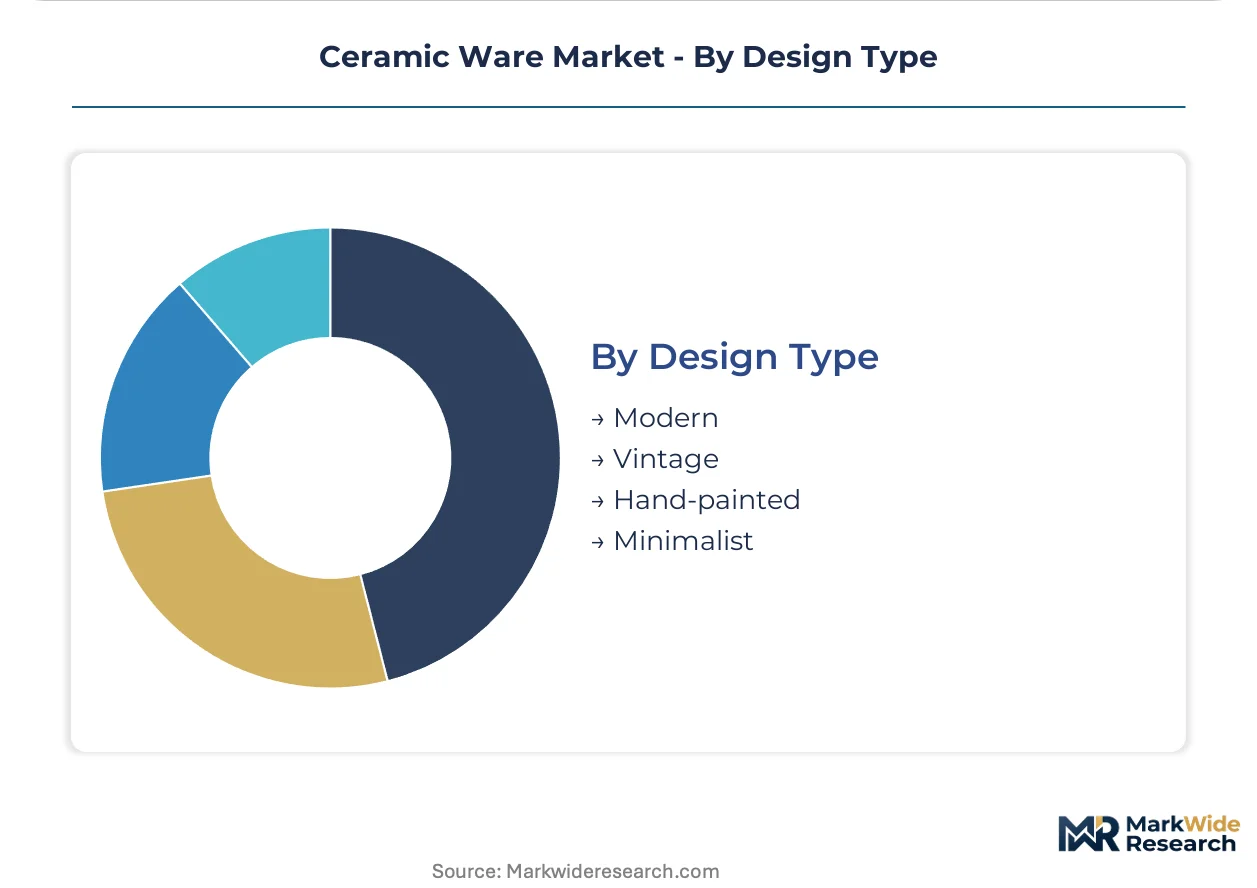
| Segmentation | Product Type: Dinnerware, Bakeware, Tableware, Cookware End User: Households, Restaurants, Cafes, Catering Services Material: Stoneware, Porcelain, Earthenware, Bone China Design Type: Modern, Vintage, Hand-painted, Minimalist |
| Companies Covered | Villeroy & Boch, Rosenthal GmbH, Noritake, Lenox, Royal Doulton, Wedgwood, Churchill China, Sacmi, Clay Craft India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Ware Market Strategic Shifts
Digital glaze formulation tools and automated quality inspection systems are compressing development cycles while regulatory compliance software embeds directly into production workflows.
Advanced thermal shock-resistant porcelain is fragmenting the traditional dinnerware category. Hospitality buyers now specify 150°C thermal differential tolerance as standard for banquet service, forcing manufacturers to abandon conventional feldspathic bodies. Fine-dining procurement teams in Paris and Tokyo are piloting these specifications, compressing margins for suppliers unable to meet translucency-thermal performance dual benchmarks.
EU REACH restrictions on heavy metal migration are compelling reformulation of centuries-old glaze recipes. ECHA enforcement of 0.002 mg/dm² lead release limits is disqualifying traditional majolica techniques across export-oriented Spanish and Italian producers. Bone china manufacturers serving London and Frankfurt hospitality markets are accelerating lead-free frit substitution, extending R&D timelines by 8-14 months.
Buyer concentration among restaurant groups is consolidating procurement authority. Multi-property hospitality operators in Singapore and Dubai now mandate centralized ceramic ware sourcing through approved vendor lists, displacing property-level purchasing autonomy. This pattern concentrates volume with manufacturers offering ISO-compliant documentation packages and regional logistics hubs, squeezing smaller exporters dependent on fragmented distributor networks.
Ceramic Ware Market Segmentation
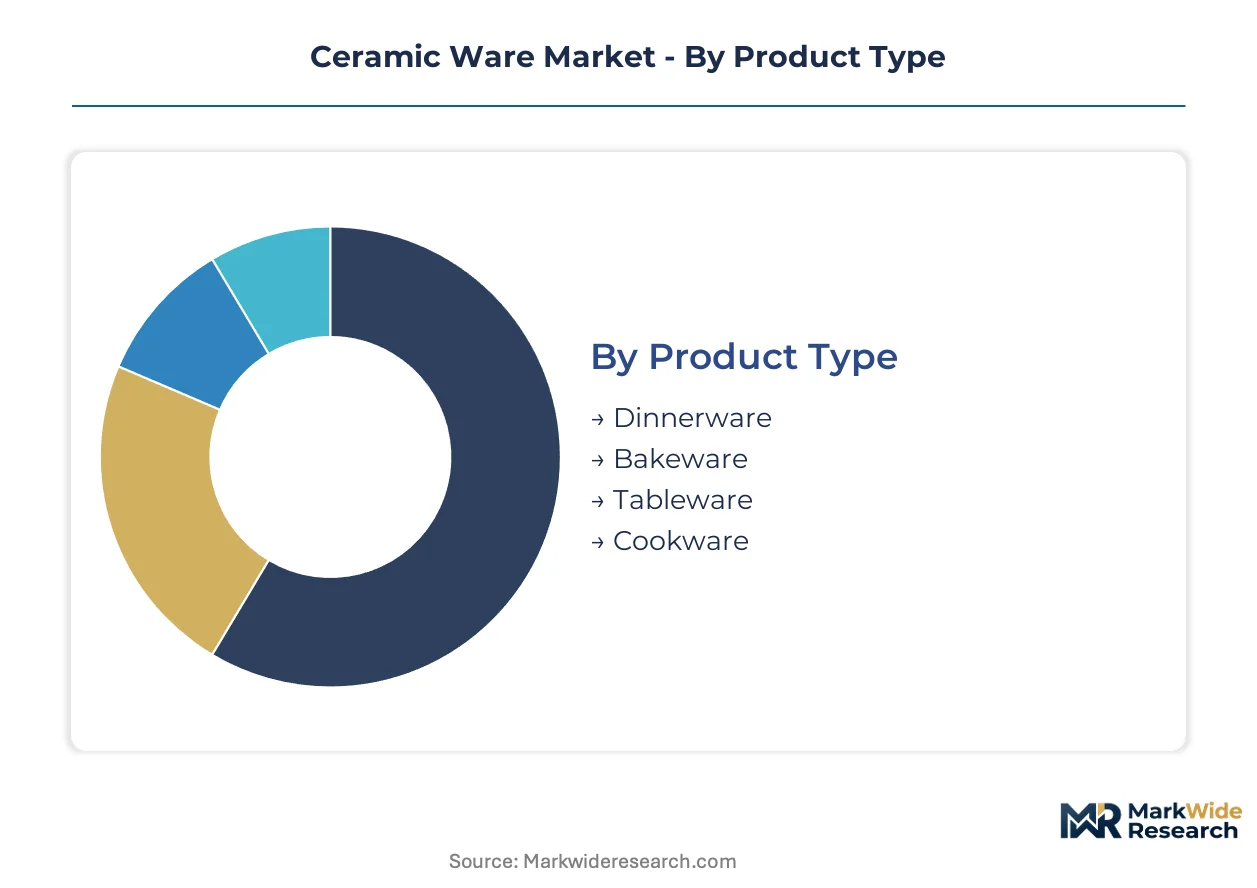
Ceramic ware procurement patterns diverge sharply between domestic consumption and export-led manufacturing hubs. Vietnam's emerging production clusters and India's artisan networks illustrate how geography dictates segment prioritization across material grades and design categories.
Product Type:
Dinnerware and tableware dominate export volume from Vietnamese facilities serving Southeast Asian hospitality chains, while bakeware and cookware concentrate in European domestic markets with stricter thermal performance standards.
- Dinnerware:Plates, bowls, and serving pieces fired at 1,200-1,400°C achieve vitrified, non-porous surfaces essential for commercial dishwasher cycles. Demand concentrates in Singapore and Dubai restaurant groups specifying ISO 6486-compliant documentation for centralized procurement.
- Tableware:Complementary serving accessories including platters, tureens, and beverage service sets. European fine-dining buyers in Paris and Frankfurt drive specification of 150°C thermal shock resistance as standard for banquet service.
- Bakeware:Oven-safe ceramic dishes with thermal cycling durability for residential and institutional baking applications.
- Cookware:Induction-compatible vessels with ferromagnetic bases penetrating professional kitchen procurement lists across German technical ceramics clusters.
Dinnerware holds the largest share; momentum sits with cookware as induction compatibility specifications expand.
End User:
Cost tiers separate mass-market household procurement from premium hospitality contracts, with restaurants and catering services commanding stricter compliance documentation and longer production runs.
- Households:Replacement-driven consumption through retail channels with lower certification thresholds than institutional buyers.
- Restaurants:Multi-property operators in Singapore and Dubai mandate centralized sourcing through approved vendor lists, displacing property-level purchasing autonomy. Volume concentrates with manufacturers offering REACH-compliant glaze documentation.
- Cafes:Boutique coffee service operations favoring hand-painted artisan designs from Rajasthan and Gujarat heritage production zones.
- Catering Services:High-volume banquet operations across Southeast Asia expanding procurement of porcelain and bone china service sets from Hanoi and Ho Chi Minh City production zones.
Restaurants command premium pricing power; catering services are expanding most quickly as event volume recovers.
Material:
Margin stratification runs deepest in material grades, with bone china capturing the highest value pools while earthenware serves price-sensitive domestic markets.
- Stoneware:Dense, durable bodies fired at 1,200-1,300°C with lower translucency than porcelain but superior chip resistance for high-turnover food service.
- Porcelain:Fully vitrified, translucent ceramic achieving non-porous surfaces through 1,400°C+ firing. German and Japanese facilities with proprietary mold-flow control dominate thin-wall production below 0.8mm thickness.
- Earthenware:Porous, lower-fired bodies requiring glaze sealing for food contact; concentrated in domestic Indian and Vietnamese markets with less export penetration.
- Bone China:Contains bone ash for exceptional translucency and strength; London and Frankfurt hospitality markets accelerate lead-free frit substitution extending R&D timelines.
Porcelain holds the largest share; bone china shows the steepest margin expansion as REACH compliance locks out non-compliant competitors.
Design Type:
Supply concentration in hand-painted artisan networks creates differentiation barriers that automated production cannot replicate, while minimalist and modern designs scale through digital glaze formulation tools.
- Modern:Clean lines and uniform glazes suited to automated production and international hotel chain standardization.
- Vintage:Reproduction patterns drawing on European and Asian decorative traditions for heritage property positioning.
- Hand-painted:Individual artisan decoration requiring skilled labor; Clay Craft India demonstrates replication potential across Rajasthan and Gujarat boutique hotel chains seeking differentiated tableware.
- Minimalist:Reduced surface ornamentation emphasizing material quality and form; aligns with contemporary fine-dining aesthetics in Tokyo and Copenhagen.
Modern designs hold the largest share; hand-painted work is gaining share fastest as boutique hospitality seeks supply-constrained differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospitality procurement in Vietnam and India operates with acute price sensitivity, while German and Japanese buyers prioritize thermal performance specifications that command substantial premiums. This elasticity divergence shapes where manufacturers invest in compliance documentation versus cost engineering.
Germany
Fine-dining procurement teams in Frankfurt and Berlin specify 150°C thermal shock resistance as baseline for banquet service, filtering out conventional feldspathic suppliers. ECHA enforcement of REACH lead release limits at 0.002 mg/dm² disqualifies traditional majolica exporters from market access. Villeroy & Boch leverages its manufacturing heritage to sustain dominance across European capitals through proprietary mold-flow control for sub-0.8mm wall thickness.
Vietnam
Restaurant and catering services across Southeast Asia are expanding procurement of porcelain and bone china service sets from integrated supply chains. The EU Green Deal carbon-border adjustment phase-in creates first-mover advantage for facilities completing biomass kiln conversions before enforcement deadlines. Hanoi and Ho Chi Minh City production zones capture regional contracts through centralized procurement mandates from Singapore and Dubai hospitality operators.
Japan
Advanced glaze chemistry R&D anchors Asian supply through facilities achieving translucency-thermal performance dual benchmarks for Tokyo fine-dining markets. METI technical standards for food-contact ceramics align with ISO 6486 metal release protocols that determine premium segment eligibility. Nagoya-area production clusters specialize in induction-compatible ceramic coatings penetrating professional kitchen procurement lists.
India
Boutique hotel chains in Rajasthan and Gujarat seek differentiated tableware through hand-painted artisan designs that automated production cannot replicate. BIS certification requirements for food-contact surfaces shape quality documentation for export-oriented manufacturers. Clay Craft India demonstrates replication potential across heritage production zones where skilled labor concentration creates supply-constrained differentiation barriers.
United States
FDA compliance for import clearance shapes quality documentation requirements for Asian manufacturers serving hospitality procurement. Multi-property restaurant operators mandate centralized sourcing through approved vendor lists, displacing property-level purchasing autonomy. California and New York Metro hospitality markets concentrate volume with manufacturers offering REACH-compliant glaze documentation packages and regional logistics hubs.
Ceramic Ware Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with German and Japanese facilities dominating thin-wall thermal performance while Vietnamese and Indian producers capture scale through integrated supply chains. The market structure consolidates around three strategic tiers: heritage European manufacturers with proprietary mold-flow capabilities, Asian technical ceramics specialists with advanced glaze R&D, and emerging cluster-based producers leveraging biomass energy transitions. Dominant competitive moves include geographic expansion into underpenetrated boutique hospitality segments and backward integration into specialized feldspar and rare earth stabilizer sourcing.
Among heritage European manufacturers, Villeroy & Boch and Rosenthal GmbH exemplify the premium-tier archetype through sustained positioning in fine-dining tableware. Noritake anchors the Asian technical specialist tier through advanced production facilities. Clay Craft India occupies a position within the artisan-differentiation segment where hand-painted designs serve boutique hotel chains seeking supply-constrained uniqueness. These three company types represent the structural divergence between performance-specification dominance and cost-engineered scale.
| Leading Market Players |
|---|
| Villeroy & Boch |
| Rosenthal GmbH |
| Noritake |
| Lenox |
| Royal Doulton |
| Wedgwood |
| Churchill China |
| Sacmi |
| Clay Craft India |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lead times for REACH-compliant glaze certification compress pricing power for Asian exporters while rewarding German and Japanese facilities with pre-approved documentation packages. This inventory-to-certification lag bifurcates margin capture between legacy European incumbents and emerging Vietnamese producers racing biomass kiln conversions.
Pricing Analysis
After-sales service contracts for commercial dishwasher compatibility testing now drive lifetime value in hospitality procurement. Three-tier pricing structure across premium, standard, and economy levels separates bone china with ISO 6486 documentation from uncertified porcelain and commodity earthenware. Price differentiation hinges on thermal shock resistance certification and glaze heavy-metal compliance tier. Cost compression in standard-grade porcelain intensifies as Vietnamese facilities scale biomass-fired output. Catering services exhibit acute price sensitivity; Frankfurt fine-dining buyers show elasticity only at sub-0.8mm wall thickness thresholds.
Supply Chain Analysis
Inventory buffers for rare earth stabilizers stretch to 120 days as Chinese domestic processors control feldspar shipments. Manufacturing concentrates in Vietnam, Germany, and Japan, with glaze chemistry R&D anchored in Nagoya-area clusters and thin-wall molding proprietary to German facilities. Production draws from concentrated Chinese rare earth processors, Vietnamese kaolin deposits, and Indian artisan labor pools. Single-source vulnerability in stabilizer supply exposes downstream formulators to disruption. Distribution runs through hospitality procurement aggregators displacing European trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
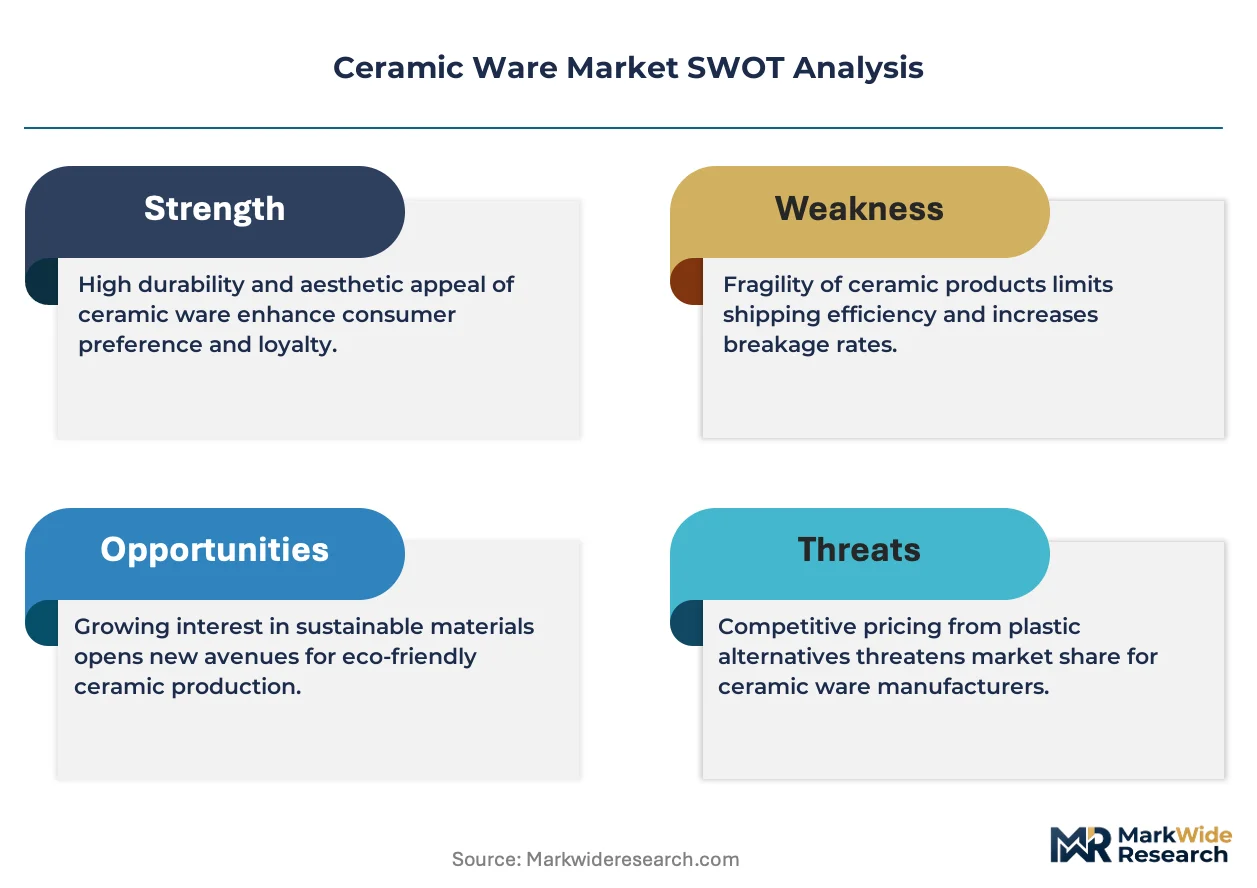
Melamine and advanced polymer tableware threaten substitution in high-turnover catering segments, forcing ceramic incumbents to defend through performance certification and artisan differentiation that synthetics cannot replicate.
For Market Incumbents: Secure backward integration into specialized feldspar sourcing to insulate glaze formulation from Chinese supply concentration. Lock in long-term service contracts with Dubai and Singapore multi-property operators before procurement aggregator consolidation accelerates. Prioritize ISO 6486 pre-certification for reformulated lead-free glazes to compress competitor launch windows.
For New Entrants and Emerging Players: Anchor in Rajasthan and Gujarat boutique hospitality clusters where hand-painted artisan designs face no automated replication threat. Target catering service procurement in Ho Chi Minh City production zones with biomass kiln credentials ahead of EU Green Deal enforcement. Pursue direct-to-hospitality platform distribution to bypass margin-stacking import distributors.
For Investors and Strategic Acquirers: Carve-out targets emerge from European heritage manufacturers with proprietary mold-flow capabilities stranded by energy transition capex demands. Five-to-ten-year viability favors facilities completing renewable kiln conversions with REACH documentation infrastructure intact. Watch for inflection when carbon-border tariff phase-in accelerates Vietnamese biomass facility valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomass Kiln Conversion | Vietnamese facilities capturing EU Green Deal first-mover advantage before carbon-border enforcement. |
| Lead-Free Glaze Reformulation | REACH compliance investment locking out traditional majolica competitors from European hospitality access. |
| Direct-to-Hospitality Platform Launch | Procurement aggregators enabling Vietnamese and Indian manufacturers to displace European trading house margins. |
| Artisan Network Expansion | Clay Craft India model replicating across Rajasthan heritage zones for supply-constrained differentiation. |
| Induction-Compatible Coating R&D | Nagoya-area clusters penetrating professional kitchen procurement with ferromagnetic base specifications. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade records, hospitality procurement databases, and kiln energy transition filings across Vietnamese industrial zones. Plant managers at Hanoi and Ho Chi Minh City facilities, procurement leads at Dubai and Singapore restaurant groups, glaze R&D directors at German technical ceramics clusters, and channel partners in European import distribution provided structured input. FDA import clearance documentation, ECHA REACH enforcement records, and ISO 6486 certification timelines furnished secondary validation. Bottom-up volume modeling triangulated against top-down spending estimates from hospitality capital expenditure surveys.
Segmentation dimensions modeled include material grade, end-use application, thermal performance tier, design type, and regional regulatory cluster across the analysis window. Value projections incorporate replacement cycle frequencies in restaurant operations, event volume recovery patterns in catering services, and compliance-driven upgrade mandates in European export markets. CAGRs derive from elasticity-adjusted adoption curves for induction-compatible coatings and biomass kiln conversion penetration rates.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal implementation and stable rare earth stabilizer supply; material deviation in carbon-border tariff schedules or Chinese export restrictions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Clay Market
Ceramics
Methyl Silicate Market
Ceramics
Nano Ceramic Coatings Market
Ceramics
Co-Fired Ceramic Market
Ceramics
Asia-Pacific Kaolin Market
Ceramics
Global Wollastonite Powder Market
Ceramics
Dielectric Ceramics Market
Ceramics
Calcite Market
Ceramics
Ceramic Substrate Market
Ceramics
Refractories Market
Ceramics
Solid-Ion Conductors Market
Ceramics
Mullite Market
Ceramics
Asia-Pacific Ceramic Coatings Market
Ceramics
South Korea Ceramic Sanitaryware Market
Ceramics
Titanium Carbide Market
Ceramics
Ceramic Fabrication Services Market