
 Stainless Steel Panels Market | 2026-2036
Stainless Steel Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Stainless Steel Panels Market Analytics
Chinese integrated stainless producers is broadening slab-to-panel conversion capacity along coastal zones. Tsingshan Holding Group leverages captive nickel supply to anchor cost positions in austenitic grades. Outokumpu differentiates through cold-rolling precision for architectural specification markets. Jindal Stainless dominates Indian distribution networks for pharmaceutical-grade finishes.
Stainless steel panels are flat-rolled products containing minimum 10.5% chromium by mass, typically manufactured through hot rolling followed by annealing and pickling to achieve corrosion resistance and formability for structural and decorative applications. Polished and embossed product types command premium positioning in visible architectural installations where surface aesthetics determine specification. Food processing and pharmaceutical end users drive specification intensity through hygienic surface finish requirements that exceed standard commercial grades. Wall panel and partition applications absorb volume in healthcare and cleanroom construction where cleanability and durability intersect.
FDA food contact surface regulations and EU REACH restrictions on hexavalent chromium plating shape product formulation and finishing chemistry across export-oriented mills. China's MEE enforces emission caps on pickling acid regeneration that elevate capital requirements for new capacity. India's BIS certification mandates for structural stainless grades filter substandard imports from regional traders. Stakeholders must monitor evolving carbon border mechanisms and alloy surcharge volatility when committing to long-term supply agreements.
Market Dynamics
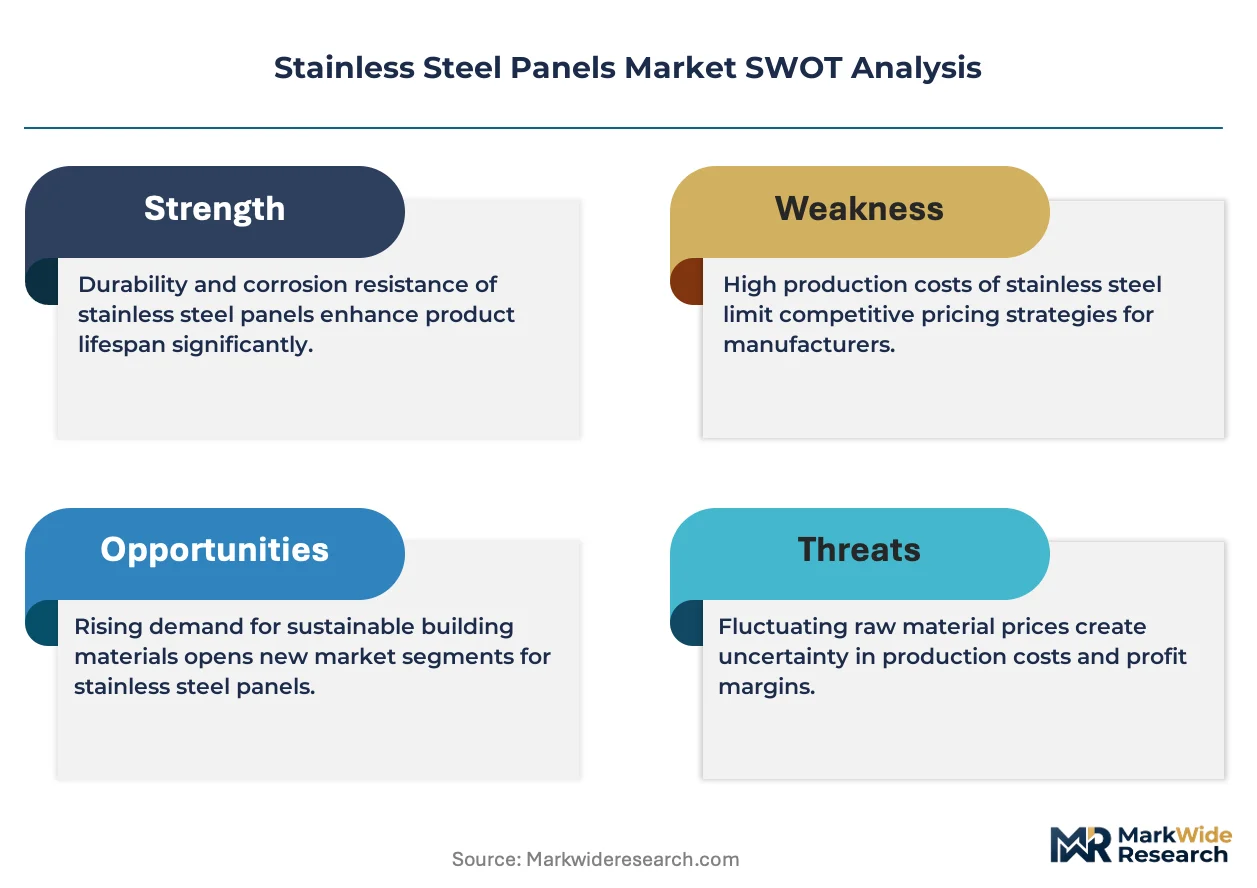
China's MEE emission caps on pickling acid regeneration are forcing coastal mills to absorb heavy capital costs for compliant capacity, compressing margins across austenitic grade production while redirecting investment toward low-emission cold-rolling technology.
Growth Catalysts
- FDA Food Contact Surfaces:Hygienic finish requirements in food processing equipment specify Ra 0.8 micrometer surface roughness, mandating panel upgrades across North American dairy and meat facilities.
- EU REACH Hexavalent Chromium Restrictions:Plating chemistry reforms are accelerating trivalent chromium and PVD coating substitution in architectural specification markets.
- India's Pharmaceutical Corridor:Cleanroom construction near Hyderabad and Ahmedabad concentrates demand for pharmaceutical-grade 316L panels with electropolished finishes.
Market Restraints
- Nickel Price Volatility:LME nickel contract swings above 40,000 USD per tonne in 2022-2024 have destabilized austenitic grade surcharge calculations, forcing mills to index long-term contracts against volatile input baskets.
- Indonesian Nickel Concentration:Tsingshan Holding Group and Chinese integrated producers control over 60% of global nickel pig iron supply, creating single-source dependency risk for non-integrated cold-rollers.
- Technical Thickness Limitations:Cold-rolling precision below 0.3mm for architectural specification panels requires specialized Sendzimir mills with limited installed base in Europe and North America.
Strategic Opportunities
- Brazilian Food Processing Expansion:ANVISA-aligned sanitary equipment mandates in poultry and soybean crushing facilities create import substitution potential for 304-grade panels with 2B finishes.
- Modular Cleanroom Prefabrication:Wall panel and partition systems are converging with HVAC and electrical chase integration, enabling turnkey cleanroom providers to capture margin from general contractors.
- China Dual Carbon Goals:MEE carbon intensity benchmarks for steel production are creating first-mover advantage for mills deploying hydrogen-annealing and renewable-powered cold-rolling lines.
Industry Challenges
- Electropolishing Certification Delays:ASME BPE and 3A Sanitary Standards compliance for pharmaceutical-grade finishes requires 12-18 month qualification timelines with end-user auditors, extending sales cycles.
- Legacy ERP Integration:Alloy surcharge indexing systems must reconcile LME, ferrochrome, and scrap price feeds in real-time, creating IT complexity for mid-tier distributors serving project-based construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stainless Steel Panels Market |
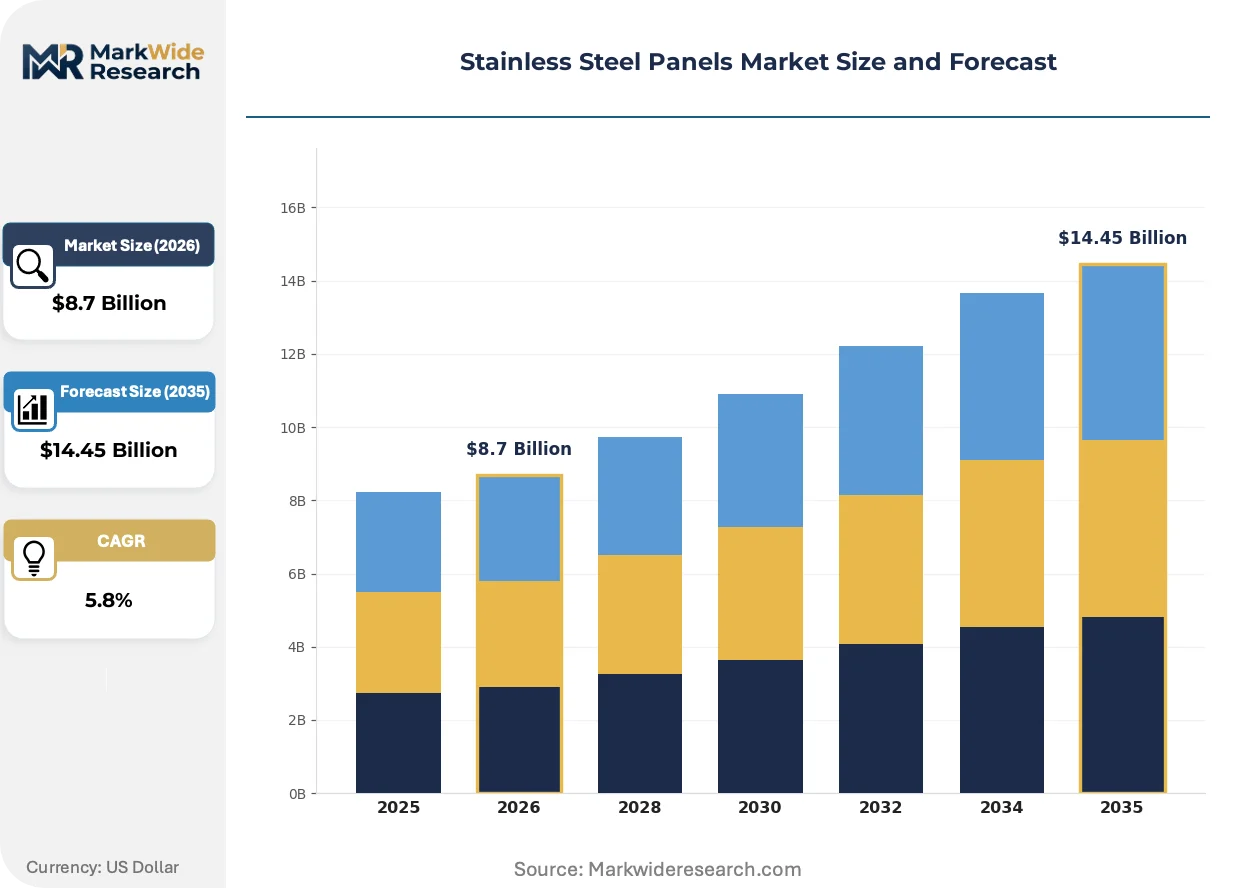
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Galvanized, Coated, Polished, Embossed End User: Construction, Automotive, Food Processing, Pharmaceutical Application: Wall Panels, Roof Panels, Ceiling Tiles, Partitions Thickness: Thin, Medium, Thick, Custom |
| Companies Covered | Tsingshan Holding Group, China Baowu Steel Group Corporation, POSCO, Outokumpu, Acerinox, Jindal Stainless, Nippon Steel Corporation, ArcelorMittal, Aperam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stainless Steel Panels Market Evolving Landscape
Surface engineering and process metallurgy are compressing the performance gap between commodity and specification grades, while regulatory chemistry restrictions and buyer procurement centralization reshape competitive positioning across food, pharma, and architectural verticals.
Laser-textured roll surfaces are absorbing the decorative panel segment's demand for embossed and patterned finishes without mechanical tooling changeover. Architectural specifiers in Germany and the UAE are specifying these finishes for high-traffic transit stations and luxury retail facades. The technology is absorbing market share from traditional mechanical embossing by eliminating die inventory and enabling lot-size-one customization.
EU REACH Annex XVII restrictions on hexavalent chromium compounds are forcing European mills to convert plating lines to trivalent chemistry or physical vapor deposition. Cold-rollers serving automotive trim and appliance markets face 18-24 month conversion timelines with significant wastewater system upgrades. Architectural specification panels bound for EU projects now require third-party certification of chromium-free finishing, creating compliance differentiation for early converters.
Consolidated procurement by multinational food processors is compressing distributor margins and favoring direct mill relationships for standardized 304 and 316 grades. Tyson Foods and Nestlé manufacturing engineering teams are issuing global panel specifications with approved mill lists, bypassing regional metal service centers. This concentration is most visible in North American and Western European dairy equipment replacement cycles, where total cost of ownership modeling now dominates spot price minimization.
Stainless Steel Panels Market Segmentation
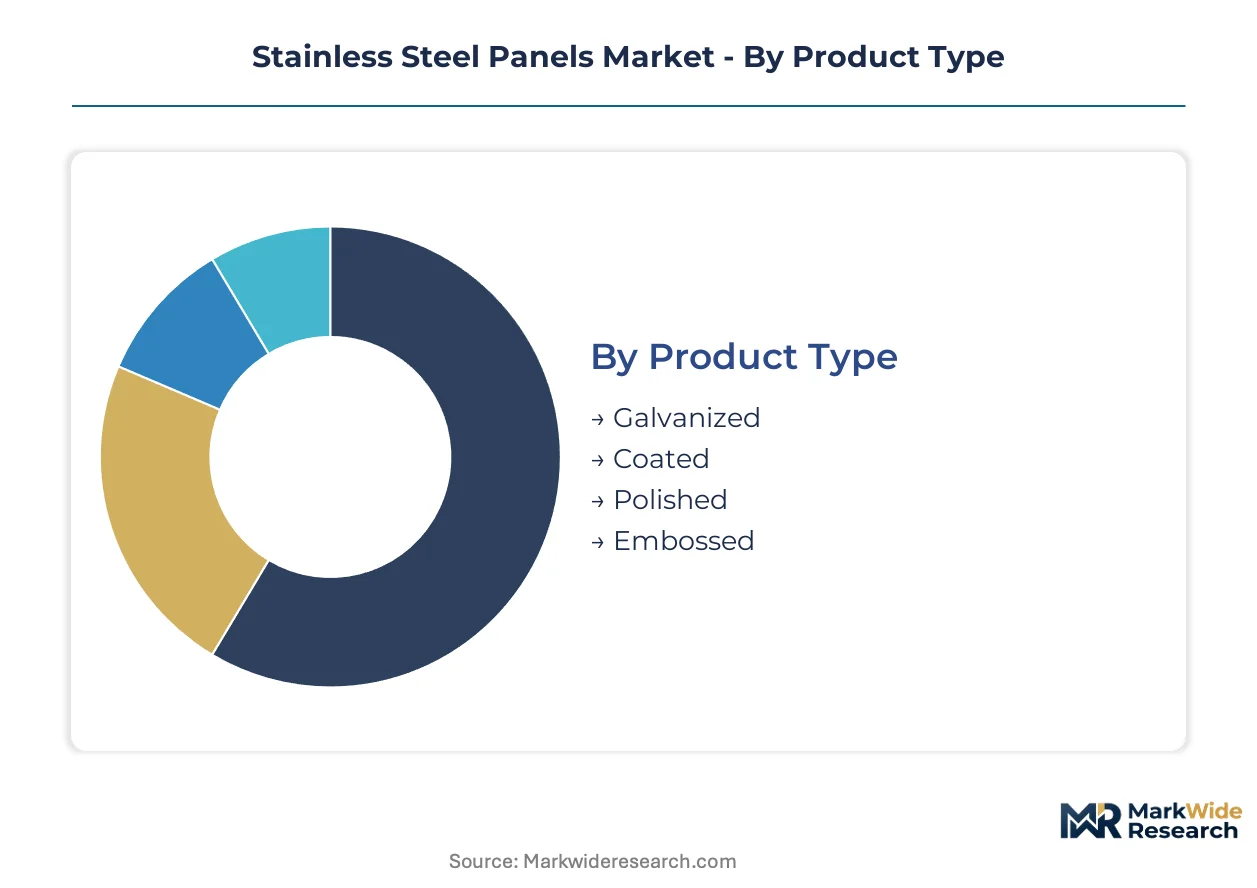
Stainless steel panel specifications diverge sharply across end-use verticals, with surface finish requirements and thickness tolerances driving fundamentally different procurement patterns. Upgrade cycles in food safety infrastructure and pharmaceutical cleanroom construction are reshaping demand composition faster than traditional construction applications.
Product Type:
Equipment replacement timelines in food processing and pharmaceutical manufacturing are accelerating specification intensity for surface-engineered grades that exceed baseline corrosion resistance.
- Polished:Mirror and satin finishes achieve Ra 0.8 micrometer surface roughness required by FDA food contact regulations. Dairy and meat processing facilities in Wisconsin and California mandate these upgrades during scheduled equipment refreshes to eliminate bacterial harborage points.
- Embossed:Laser-textured roll surfaces now replicate mechanical patterns without die inventory, enabling lot-size-one customization for transit stations and luxury retail facades in Germany and the UAE. Architectural specifiers specify these finishes for high-traffic environments where scratch concealment matters.
- Galvanized:Zinc-coated substrates provide cost-effective corrosion protection for industrial roofing and agricultural structures where aesthetic requirements remain secondary.
- Coated:PVD and trivalent chromium coatings substitute for hexavalent plating under EU REACH restrictions, requiring 18-24 month conversion timelines for European mills serving automotive trim markets.
Volume placements concentrate in Galvanized for baseline industrial applications; the faster expansion belongs to Polished as hygienic finish mandates tighten across North American food processing.
End User:
Customer procurement centralization is compressing distributor margins and favoring direct mill relationships for standardized grades with approved supplier lists.
- Food Processing:Tyson Foods and Nestlé manufacturing engineering teams issue global panel specifications with approved mill lists, bypassing regional metal service centers. Ra 0.8 micrometer surface roughness requirements mandate panel upgrades across North American dairy facilities during replacement cycles.
- Pharmaceutical:Cleanroom construction near Hyderabad and Ahmedabad concentrates demand for 316L panels with electropolished finishes. ASME BPE and 3A Sanitary Standards compliance requires 12-18 month qualification timelines with end-user auditors.
- Construction:Healthcare and cleanroom wall panel applications absorb volume where cleanability and durability intersect, though procurement remains fragmented across general contractors.
- Automotive:Exterior trim and appliance markets face plating chemistry reforms under EU REACH, with mills converting lines to trivalent chromium or PVD coating.
Revenue concentration sits with Food Processing; Pharmaceutical claims the steepest expansion trajectory as India's cleanroom construction accelerates.
Application:
Modular prefabrication is converging wall systems with HVAC and electrical chase integration, enabling turnkey providers to capture margin from general contractors.
- Wall Panels:Healthcare and pharmaceutical cleanroom construction specifies these for cleanability and durability where surface integrity prevents contamination. Modular systems integrate insulation and utility routing offsite.
- Partitions:Cleanroom sub-divisions require pharmaceutical-grade finishes with electropolished surfaces; qualification delays extend sales cycles but lock in long-term supply agreements.
- Roof Panels:Industrial and agricultural structures prioritize cost efficiency through galvanized grades with functional corrosion protection rather than aesthetic specification.
- Ceiling Tiles:Suspended systems in food processing and healthcare environments specify smooth finishes that resist particle accumulation and enable washdown protocols.
Specification intensity peaks in Wall Panels; Partitions are gaining share fastest as modular cleanroom prefabrication displaces stick-built construction.
Thickness:
Cost structures and performance requirements stratify procurement across standardized and custom specifications, with precision cold-rolling capacity constraining supply for architectural grades.
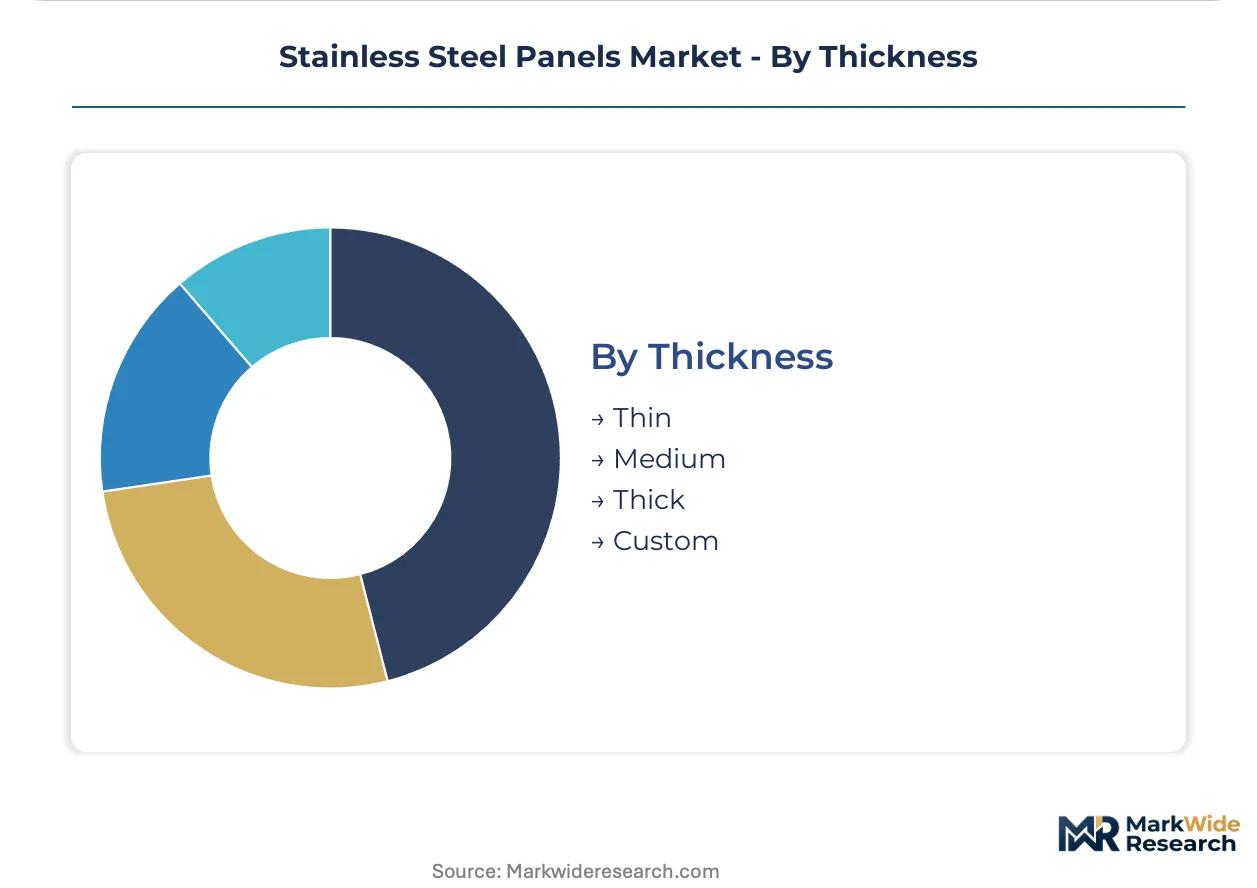
- Thin:Cold-rolling precision below 0.3mm for architectural specification panels requires specialized Sendzimir mills with limited installed base in Europe and North America. German and UAE luxury retail facades specify these for lightweight cladding systems.
- Medium:Standard 0.5-1.5mm gauges dominate food processing equipment and pharmaceutical cleanroom construction where structural integrity must balance material efficiency.
- Thick:Heavy-gauge panels serve industrial roofing and structural applications where load-bearing requirements exceed cosmetic considerations.
- Custom:Project-specific thicknesses accommodate unique architectural or equipment designs, requiring flexible mill scheduling and extending lead times.
Production volumes cluster in Medium gauges; Custom thicknesses are expanding most quickly as architectural specifiers pursue distinctive facade geometries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian nickel pig iron deposits anchor raw material sourcing for austenitic grade production, while coastal Chinese mills and Indian pharmaceutical clusters absorb finished panel demand.
China
Tsingshan Holding Group and Baowu Steel dominate slab-to-panel conversion along coastal zones. MEE emission caps on pickling acid regeneration force heavy capital absorption for compliant capacity. Yangtze River Delta mills redirect investment toward hydrogen-annealing and renewable-powered cold-rolling lines under dual carbon goals.
India
Cleanroom construction near Hyderabad and Ahmedabad concentrates pharmaceutical-grade 316L panel demand with electropolished finishes. BIS certification mandates for structural stainless grades filter substandard imports from regional traders. Jindal Stainless anchors domestic distribution networks for pharmaceutical-grade finishes.
Germany
Architectural specifiers in transit stations and luxury retail facades drive laser-textured roll surface adoption. EU REACH Annex XVII restrictions on hexavalent chromium compounds force plating line conversions to trivalent chemistry or PVD coating. Ruhr region cold-rollers face 18-24 month wastewater system upgrade timelines.
United States
FDA food contact surface regulations mandate Ra 0.8 micrometer surface roughness for dairy and meat processing equipment across Wisconsin and California. Tyson Foods and Nestlé manufacturing engineering teams issue global panel specifications with approved mill lists. Midwest equipment replacement cycles bypass regional metal service centers.
Brazil
ANVISA-aligned sanitary equipment mandates in poultry and soybean crushing facilities create import substitution potential for 304-grade panels with 2B finishes. São Paulo state food processors upgrade hygienic infrastructure to meet export compliance requirements. Southern region crushing facilities absorb volume for standardized commercial grades.
Stainless Steel Panels Market Competitive Landscape
Global majors compete with regional champions across cold-rolling precision and captive nickel supply. The vendor base stratifies between integrated producers with upstream ore access and specialized cold-rollers serving specification markets. Three archetypes dominate: nickel-integrated giants, precision cold-rolling specialists, and regional distribution champions. Competitive moves concentrate on low-emission capacity conversion and direct mill relationships bypassing distributors.
Within the nickel-integrated tier, Tsingshan Holding Group and China Baowu Steel Group Corporation represent upstream control strategies through captive Indonesian supply. Among precision cold-rolling specialists, Outokumpu exemplifies architectural specification positioning through surface finish differentiation. These three anchors illustrate how raw material security, technical precision, and regulatory compliance create divergent competitive vectors across food processing, pharmaceutical, and architectural end uses.
| Leading Market Players |
|---|
| Tsingshan Holding Group |
| China Baowu Steel Group Corporation |
| POSCO |
| Outokumpu |
| Acerinox |
| Jindal Stainless |
| Nippon Steel Corporation |
| ArcelorMittal |
| Aperam |
| Others |
Value Network & Pricing Analysis
Consolidated procurement by Tyson Foods and Nestlé manufacturing engineering teams demanding direct mill relationships with approved supplier lists is forcing regional metal service centers to absorb margin compression or exit standardized 304 and 316 grade distribution entirely.
Pricing Analysis
Service bundling separates electropolishing certification support from base panel supply, with ASME BPE and 3A Sanitary Standards compliance timelines unbundled as premium add-ons. Three-tier pricing structure across pharmaceutical-grade electropolished, food-grade 2B finish, and commercial galvanized levels reflects certification intensity and surface roughness specifications. Cost compression in commodity 304 grades is intensifying because Chinese coastal mills redirect investment toward low-emission cold-rolling capacity under MEE emission caps. Food processing equipment buyers exhibit highest price sensitivity due to total cost of ownership modeling, while pharmaceutical cleanroom constructors accept premium positioning for qualification-locked supply agreements.
Supply Chain Analysis
Scrap metal recovery and off-spec panel reprocessing flows remain underdeveloped, creating material loss points that Indonesian nickel-integrated producers partially offset through captive pig iron supply. Raw material sourcing concentrates in Indonesia for nickel pig iron, China for ferrochrome and slab conversion, and Finland for precision cold-rolling equipment. Production rests on nickel ore grade volatility, energy cost differentials for annealing operations, and specialized Sendzimir mill availability. Single-source vulnerability risk concentrates in Tsingshan Holding Group's control over 60% of global nickel pig iron supply. Distribution runs through Jindal Stainless in India, Outokumpu in Europe, and direct mill relationships in North America bypassing traditional service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH Annex XVII hexavalent chromium restrictions and China's MEE emission caps on pickling acid regeneration erect compliance moats that filter substandard regional traders and reward early-converting integrated producers with specification market access.
For Market Incumbents: Anchor cost positions through captive Indonesian nickel supply and hydrogen-annealing capacity deployment under China's dual carbon goals. Defend against emerging precision cold-rolling specialists by locking pharmaceutical-grade qualification timelines with Hyderabad and Ahmedabad cleanroom developers. Prioritize direct mill relationship investments with Nestlé and Tyson Foods manufacturing engineering teams to bypass distributor margin compression. For New Entrants and Emerging Players: Enter via modular cleanroom prefabrication integration, converging wall panel systems with HVAC and electrical chase assembly to capture margin from general contractors. Target Brazil's ANVISA-aligned poultry and soybean crushing facility upgrades where import substitution potential for 304-grade 2B finish panels remains underexploited. Pursue laser-textured roll surface technology licensing to serve German and UAE architectural specifiers without mechanical die inventory burdens. For Investors and Strategic Acquirers: The window for entry favors precision cold-rolling specialists with ASME BPE certification capabilities and established pharmaceutical end-user auditor relationships. Long-term viability hinges on low-emission process technology deployment and renewable-powered annealing lines that align with tightening carbon border mechanisms. Monitor nickel pig iron supply concentration indicators and EU carbon border adjustment mechanism implementation signals for inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Emission Cold-Rolling Capacity Deployment | MEE emission caps force capital absorption that rewards first-movers with compliant coastal capacity. |
| Pharmaceutical-Grade Certification Investment | ASME BPE and 3A Sanitary Standards compliance creates 12-18 month qualification moats against commodity competitors. |
| Direct Mill Relationship Development | Tyson Foods and Nestlé procurement centralization bypasses regional distributors for standardized grade volume. |
| Modular Cleanroom System Integration | Wall panel prefabrication with utility routing captures margin from general contractors in Hyderabad and Ahmedabad clusters. |
| Alternative Coating Chemistry Conversion | EU REACH hexavalent chromium restrictions mandate trivalent or PVD plating line upgrades for architectural specification access. |
Research Methodology
Document review covered SEC filings from integrated steel producers, EU REACH regulatory submissions, and MEE emission cap enforcement records, complemented by interviews with cold-rolling plant managers, pharmaceutical facility engineering directors, food processing equipment procurement leads, and architectural specification consultants. Secondary validation drew from customs trade databases, BIS certification registries, and stainless steel surcharge index publications. Bottom-up volume modeling across polished, embossed, galvanized, and coated product types triangulated with top-down value projections.
Segmented outputs across thickness tiers, surface finish specifications, and end-use verticals informed CAGR derivation through regression analysis of replacement cycle timing, regulatory compliance deadlines, and capacity expansion announcements. The analytical framework incorporated nickel price volatility scenarios, carbon intensity benchmarking trajectories, and pharmaceutical cleanroom construction permit flows across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nickel pig iron supply disruption or accelerated EU carbon border adjustment implementation. Projections reflect assumptions regarding MEE enforcement consistency, ASME BPE auditor availability, and Indonesian ore grade stability. Practitioners should monitor LME nickel contract volatility, Hyderabad cleanroom construction permit issuance rates, and EU REACH Annex XVII amendment proposals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Superconducting Wire Market
Metals
Global Precious Metal Market
Metals
Steel Wire Market
Metals
Niobium Market
Metals
Electrodeposited Copper Foil Market
Metals
Lithium Foil Market
Metals
Shipbuilding Steel Plate Market
Metals
Iron Casting Market
Metals
Nickel Powder Plating Market
Metals
Aluminium Rolled Products Market
Metals
Weathering Steel Market
Metals
Lightweight Aluminium Pistons Market
Metals
Nickel Market
Metals
Cobalt Market
Metals
Silver Nitrate Market
Metals
Welding Materials Market