
 Middle-East and Africa Metal Finishing Market | 2026-2036
Middle-East and Africa Metal Finishing Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Metal Finishing Market Foresight
Modular service bundling is recalibrating how Tier-1 Suppliers and Fabricators procure metal finishing across the Middle-East and Africa. Chemetall GmbH leverages its pretreatment chemical portfolio to anchor long-term supply relationships with Gulf-based automotive plants. BASF SE differentiates through electrochemical process R&D aimed at aerospace-grade coatings for regional MRO facilities. MacDermid Inc. competes on plating chemistry specialization for electronics substrates serving Israeli and South African circuit board manufacturers.
Middle-East and Africa Metal Finishing encompasses electrochemical, mechanical, chemical, and thermal processes that deposit protective or functional layers onto metal substrates, typically achieving thicknesses from 0.1 micrometers for decorative chrome to 500 micrometers for heavy-build industrial coatings, primarily to enhance corrosion resistance, wear durability, electrical conductivity, or aesthetic properties across industrial applications. Electroplating occupies the largest value share due to its entrenched use in automotive and electronics manufacturing, while Powder Coating represents the fastest-expanding product category as Gulf construction booms and environmental restrictions on solvent-based paints accelerate adoption. The Technology dimension shows Electrochemical processes commanding premium pricing for aerospace and precision electronics, whereas Thermal spraying gains traction in oilfield equipment refurbishment across Saudi Arabia and the UAE.
Saudi Arabia's SFDA and environmental regulator MEE-aligned frameworks, alongside South Africa's DEFF chemical control regulations and Egypt's industrial environmental compliance mandates, collectively restrict hexavalent chromium and mandate wastewater treatment for plating operations. These standards force process substitutions and capital upgrades among Fabricators and Aftermarket Providers seeking market access across the region. Stakeholders must monitor regulatory harmonization between Gulf standardization bodies and African national agencies to anticipate certification burdens and localize compliant chemistries.
Market Dynamics
Water-based pretreatment chemistries are displacing solvent-heavy legacy systems across Gulf industrial zones, forcing Fabricators and Aftermarket Providers to reconfigure capital equipment and supplier relationships simultaneously.
Growth Catalysts
- REACH-aligned chemical restrictions:Saudi Arabia's MEE and South Africa's DEFF are enforcing hexavalent chromium bans that accelerate process substitution toward trivalent alternatives.
- Automotive OEM expansion:Electroplating demand concentrates in South Africa's manufacturing corridors and Gulf-based assembly plants for corrosion-resistant chassis components.
- Powder coating technology:Construction booms across the UAE and Saudi Arabia are pulling solvent-free application methods into structural steel and architectural metalwork.
Market Restraints
- Specialty chemical import dependence:Pretreatment formulations and plating additives flow primarily from European and Asian suppliers, exposing Fabricators to currency volatility and shipping disruptions.
- Wastewater treatment capex:MEE and DEFF mandates for zero-liquid-discharge systems impose six-figure capital burdens on small and mid-sized plating operations.
- Substrate substitution threat:Carbon-fiber reinforced polymers and engineered thermoplastics are capturing weight-sensitive applications in aerospace and premium automotive segments.
Strategic Opportunities
- Egyptian industrial zone development:New government-backed manufacturing clusters near Suez Canal logistics corridors offer first-mover positioning for compliant finishing services.
- Electronics substrate plating:Israeli and South African circuit board manufacturers are expanding capacity for high-density interconnect boards requiring precision gold and nickel deposits.
- Digital process monitoring:IoT-enabled bath chemistry control and predictive maintenance systems are opening subscription-based service models for regional Aftermarket Providers.
Industry Challenges
- Electrochemical process engineering talent:Gulf states and South Africa face acute shortages of technicians trained in trivalent chromium conversion coating and pulse-plating parameter optimization.
- Legacy equipment integration:Fabricators operating 15-20 year-old rectifier and conveyor systems struggle to retrofit water-based chemistry compatibility without full line replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Metal Finishing Market |
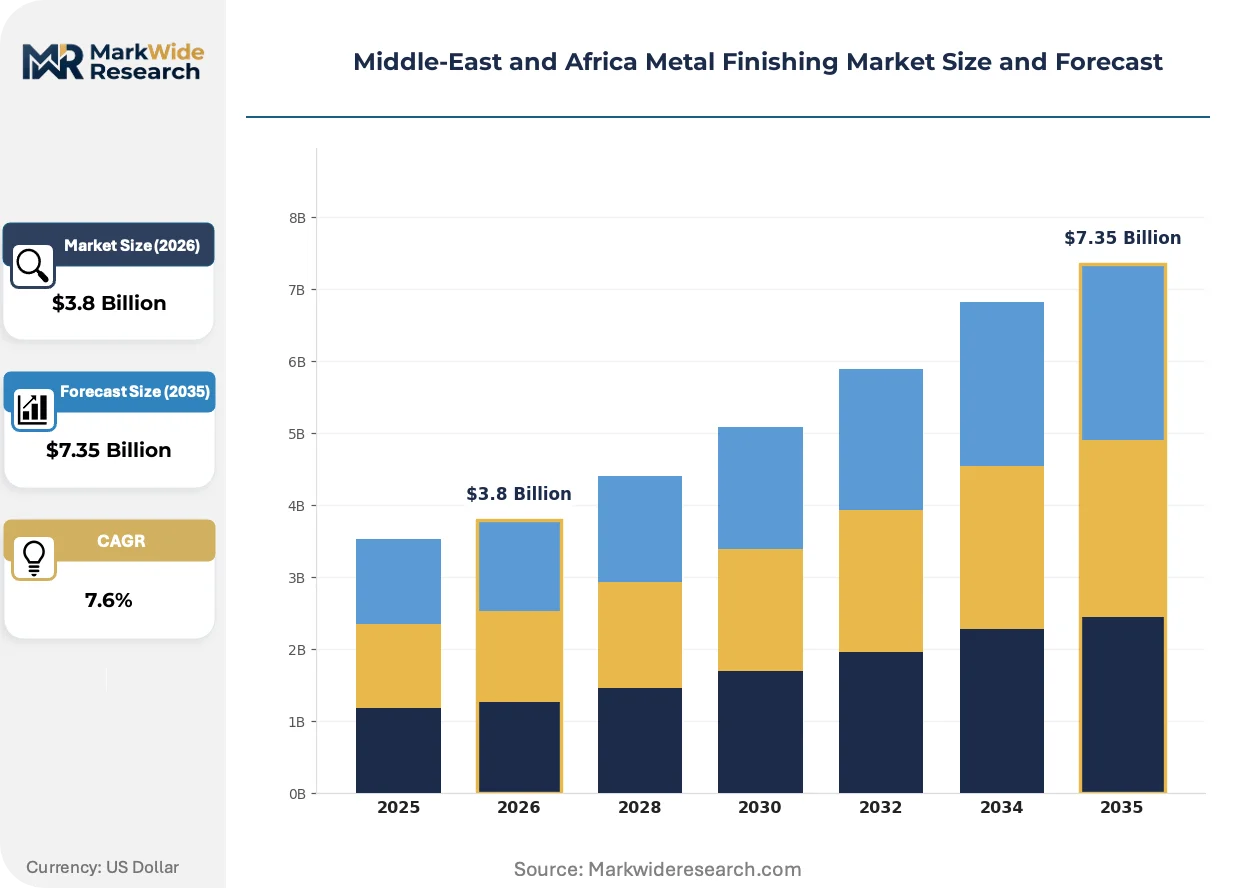
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroplating, Painting, Anodizing, Powder Coating Technology: Electrochemical, Mechanical, Chemical, Thermal Application: Aerospace, Automotive, Construction, Electronics End User: OEMs, Tier-1 Suppliers, Fabricators, Aftermarket Providers |
| Companies Covered | Atotech, Chemetall GmbH, MacDermid Inc., BASF SE, Dow Chemical Company, Quaker Chemical Corporation, Elementis plc, Coventya Group, Platform Specialty Products Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Metal Finishing Market Shifts & Advancements
Thermal spray deposition methods and digital bath management systems are restructuring competitive capabilities across the Middle-East and Africa, compressing the advantage window for conventional electroplating specialists.
Tungsten carbide-cobalt thermal spray coatings are overtaking hard chrome plating for oilfield pump components and drilling equipment refurbishment in Saudi Arabia and the UAE. National oil companies are specifying these deposits for downhole tools exposed to abrasive formation fluids. The shift is compressing demand for hexavalent chromium electroplating in energy sector supply chains.
South Africa's DEFF has tightened hazardous chemical licensing timelines for plating operations, extending permit review periods from 90 to 180 days. Fabricators are responding by front-loading environmental impact documentation and pre-qualifying treatment chemistries. Aftermarket Providers serving mining equipment sectors report the longest certification backlogs.
Automotive OEMs in the Gulf are consolidating supplier panels from 8-12 finishing houses to 3-4 strategic partners capable of integrated pretreatment-plating-topcoat sequences. Tier-1 Suppliers are absorbing quality assurance functions previously performed by OEM incoming inspection teams. This concentration is most visible in Saudi Arabia's industrial zones where new vehicle assembly capacity is scaling.
Middle-East and Africa Metal Finishing Market Segmentation
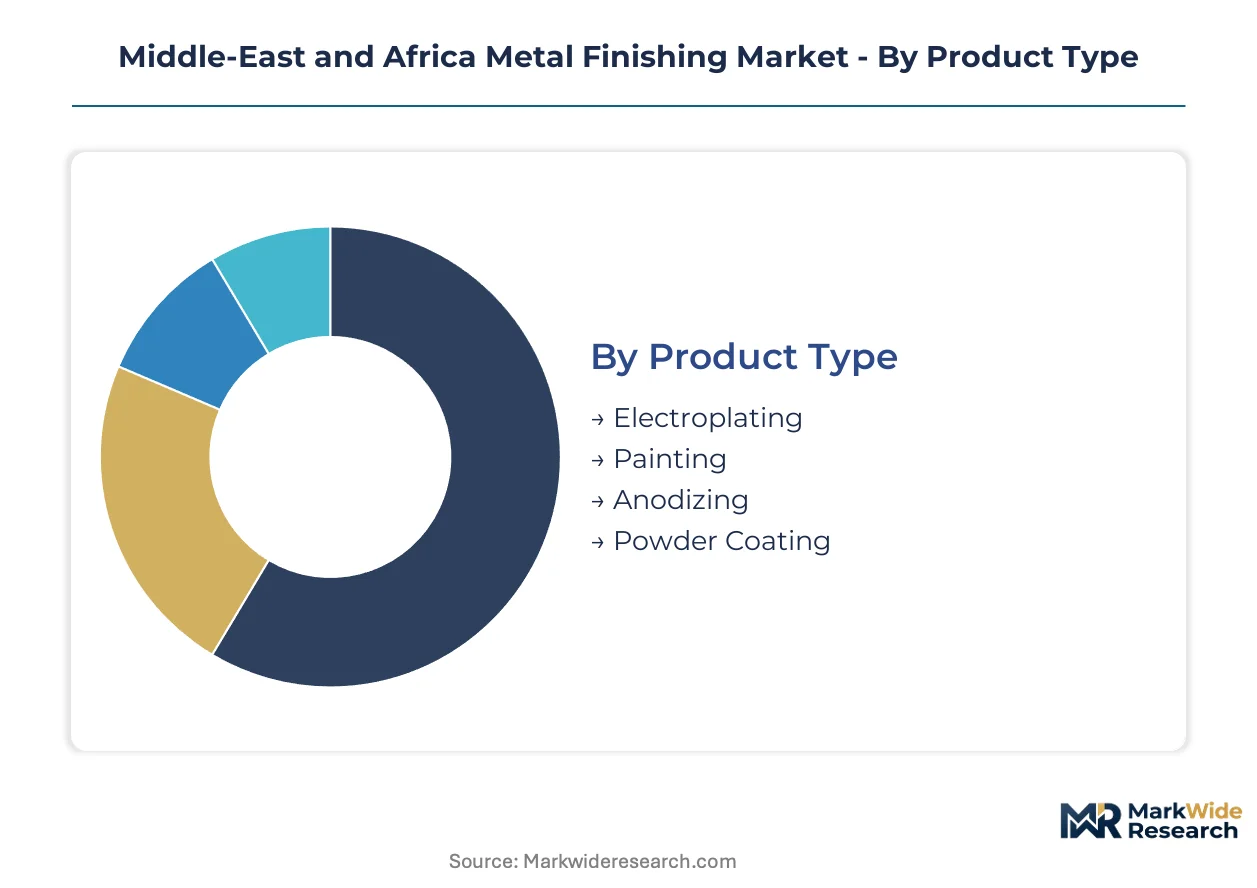
Metal finishing procurement patterns diverge sharply across the Middle-East and Africa based on whether buyers prioritize corrosion resistance for oilfield equipment, aesthetic durability for architectural metals, or precision conductivity for electronics substrates. Understanding these segment boundaries clarifies where technology investments and regulatory compliance burdens concentrate.
Product Type:
Buyers differentiate primarily by environmental compliance tolerance and capital intensity of application equipment.
- Electroplating:Deposits metallic coatings through electrolytic reduction, achieving thickness control down to 0.1 micrometers for decorative finishes. Demand concentrates in Saudi Arabia's automotive assembly zones and South Africa's chassis component manufacturing, where OEMs specify nickel-chrome systems for corrosion-resistant underbody parts. MEE enforcement of hexavalent chromium restrictions is forcing process retrofits toward trivalent alternatives.
- Powder Coating:Applies thermoset or thermoplastic powders electrostatically before heat curing, eliminating solvent emissions entirely. UAE and Saudi Arabia construction booms are pulling this technology into structural steel and aluminum facade systems, with environmental agencies accelerating bans on solvent-based alternatives.
- Painting:Conventional liquid coating systems persist in maintenance and repair operations where color matching flexibility outweighs environmental penalties.
- Anodizing:Electrochemical oxide layer formation on aluminum, specified for architectural and electronics applications requiring dielectric insulation.
Electroplating leads volumes today; powder coating is gaining share fastest.
Technology:
Technology selection tracks substrate material, required coating thickness, and precision specifications rather than end-use sector alone.
- Electrochemical:Encompasses electroplating, anodizing, and electroless deposition processes relying on controlled current or autocatalytic reduction. Israeli and South African circuit board manufacturers specify electrochemical gold and nickel deposits for high-density interconnect substrates, with pulse-plating parameter optimization commanding premium pricing.
- Thermal:Flame and plasma spray methods deposit tungsten carbide-cobalt and ceramic coatings at 500+ micrometer thickness. Saudi Aramco and ADNOC specifications for downhole pump components are displacing hard chrome plating in oilfield equipment refurbishment.
- Mechanical:Shot peening, polishing, and abrasive blasting prepare surfaces without chemical alteration, serving maintenance operations with minimal regulatory exposure.
- Chemical:Conversion coatings and phosphating pretreatments anchor subsequent coating adhesion, with Chemetall formulations dominating Gulf automotive plant supply relationships.
Electrochemical processes dominate value capture; thermal methods show steepest expansion trajectory in energy sector applications.
Application:
Application segments separate by performance certification requirements and exposure severity in operating environments.
- Automotive:Chassis, powertrain, and trim components requiring salt-spray corrosion resistance and decorative durability. South Africa's manufacturing corridors and Saudi Arabia's new assembly capacity concentrate electroplating demand for OEM corrosion specifications.
- Aerospace:Landing gear, engine components, and airframe structures subject to fatigue and thermal cycling. Regional MRO facilities in the UAE and South Africa specify electrochemical coatings meeting OEM repair manual requirements.
- Construction:Structural steel and architectural metalwork exposed to coastal and desert atmospheric corrosion. UAE building codes now mandate powder coating for exterior aluminum systems.
- Electronics:Printed circuit boards and connector systems requiring controlled conductivity and solderability. Israeli and South African substrate manufacturers drive precision plating demand.
Automotive applications anchor current volumes; electronics plating climbs fastest as regional circuit board capacity expands.
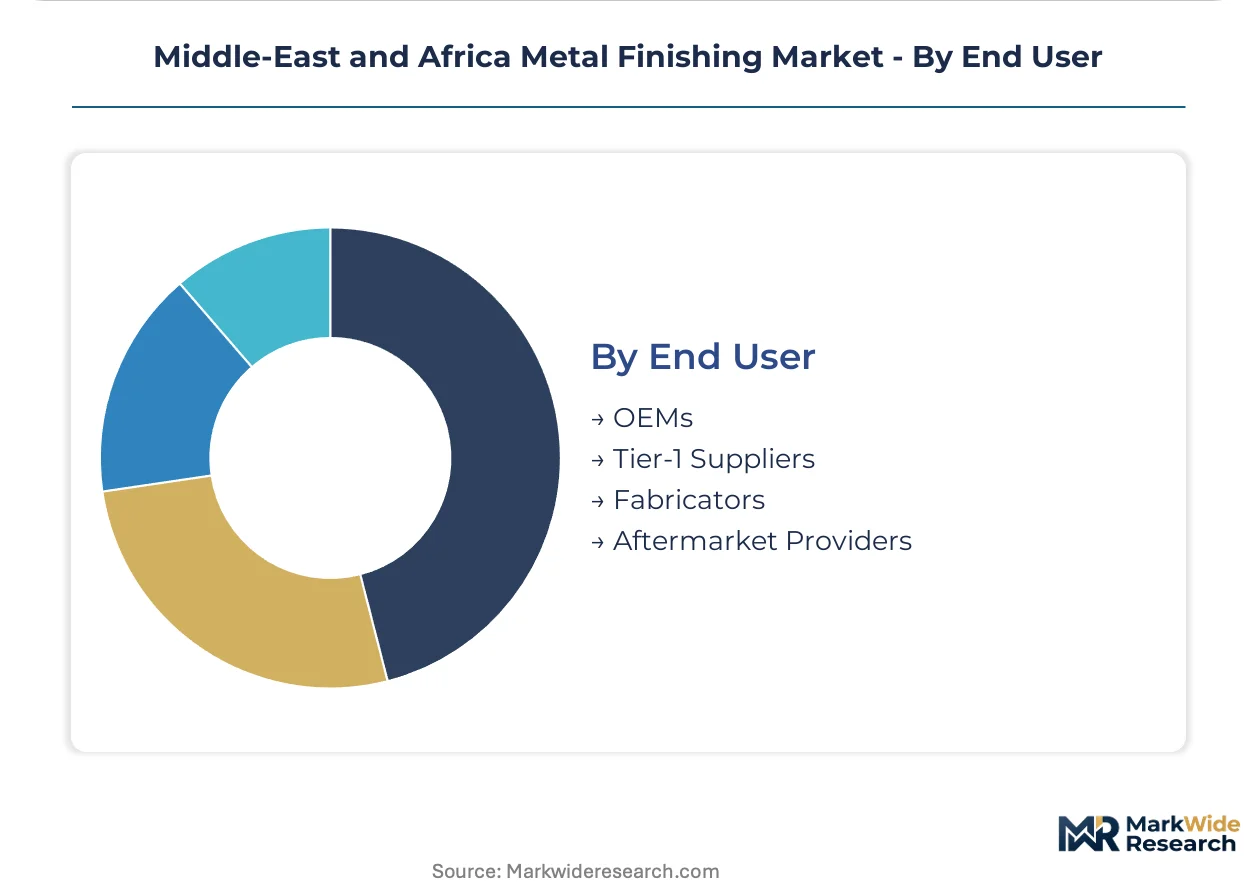
End User:
End user categories distinguish by procurement scale, technical specification authority, and captive finishing capability.
- OEMs:Original equipment manufacturers with direct coating specifications and incoming quality control. Gulf automotive OEMs are consolidating supplier panels from 8-12 finishing houses to 3-4 strategic partners capable of integrated pretreatment-plating-topcoat sequences.
- Tier-1 Suppliers:Component manufacturers absorbing quality assurance functions previously performed by OEM inspection teams. These suppliers are absorbing environmental compliance documentation burdens for their OEM customers.
- Fabricators:Job shops and metalworking contractors serving construction and industrial equipment sectors. DEFF permit review extensions from 90 to 180 days are creating certification backlogs for mining equipment service providers.
- Aftermarket Providers:Repair, refurbishment, and maintenance operations with fragmented demand patterns. IoT-enabled bath chemistry monitoring is opening subscription-based service models for this dispersed segment.
Tier-1 Suppliers and Fabricators handle the greatest transaction volumes; Aftermarket Providers show fastest adoption of digital process monitoring tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metal finishing operations across the Middle-East and Africa trace their industrial lineage to South Africa's mining equipment manufacturing of the 1970s and the Gulf's oilfield services expansion during the 1980s. These historical anchors continue shaping where electroplating and thermal spray capacity concentrates today.
Saudi Arabia
Automotive OEM assembly plants and oilfield equipment refurbishment drive electroplating demand in the Eastern Province and Riyadh industrial zones. The Ministry of Environment, Water and Agriculture enforces hexavalent chromium restrictions that force fabricators toward trivalent conversion coatings. Jubail Industrial City hosts the densest concentration of compliant plating operations serving both energy and automotive supply chains.
United Arab Emirates
Construction booms across Dubai and Abu Dhabi pull powder coating capacity into structural steel and architectural aluminum applications. Dubai Municipality building codes now mandate solvent-free coating systems for exterior metalwork. Jebel Ali Industrial Zone clusters the largest thermal spray operations serving regional MRO facilities.
South Africa
Automotive chassis component manufacturing and mining equipment refurbishment anchor electroplating demand in Gauteng and the Eastern Cape. The Department of Environment, Forestry and Fisheries extended hazardous chemical licensing timelines, creating certification backlogs for plating operations. Port Elizabeth's automotive manufacturing corridor concentrates the highest density of OEM-specified finishing capacity.
Israel
Printed circuit board manufacturing and precision electronics drive demand for gold and nickel electroplating in the Tel Aviv metropolitan area and northern industrial zones. The national environmental regulator enforces wastewater discharge standards that push fabricators toward closed-loop treatment systems. Haifa's technology corridor hosts specialized plating operations serving high-density interconnect substrate manufacturers.
Egypt
Government-backed manufacturing clusters near Suez Canal logistics corridors attract first-mover finishing services for industrial equipment and consumer goods. Industrial environmental compliance mandates from the national environmental agency restrict legacy solvent-based processes. The New Administrative Capital construction zone pulls powder coating capacity into architectural metalwork applications.
Middle-East and Africa Metal Finishing Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology specialization and environmental compliance certification. The vendor base organizes into three tiers: multinational chemical suppliers with integrated pretreatment-plating portfolios, regional plating job shops serving construction and maintenance sectors, and specialized thermal spray contractors focused on oilfield refurbishment. Strategic moves concentrate on supplier panel consolidation by automotive OEMs and digital process monitoring subscriptions for aftermarket providers.
Within the multinational chemical supplier tier, Chemetall GmbH and BASF SE exemplify the pretreatment and electrochemical process specialists anchoring long-term automotive plant relationships. MacDermid Inc. occupies a position among plating chemistry specialists serving electronics substrate manufacturers. These three entities represent distinct competitive archetypes: the integrated process portfolio provider, the electrochemical R&D-focused supplier, and the substrate-specific chemistry specialist.
| Leading Market Players |
|---|
| Atotech |
| Chemetall GmbH |
| MacDermid Inc. |
| BASF SE |
| Dow Chemical Company |
| Quaker Chemical Corporation |
| Elementis plc |
| Coventya Group |
| Platform Specialty Products Corporation |
| Others |
Supply & Pricing Matrix
Environmental compliance certification tiers split the Middle-East and Africa metal finishing landscape into premium-priced MEE-aligned operations in Saudi Arabia's Jubail Industrial City and commodity-grade job shops serving informal construction markets. This bifurcation concentrates pricing power among pretreatment chemical suppliers anchoring automotive OEM supply relationships while squeezing margins for fabricators lacking zero-liquid-discharge capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with REACH-aligned trivalent chromium systems commanding 40-60% premiums over hexavalent legacy processes. Price differentiation rests on MEE certification status and wastewater treatment infrastructure maturity. Cost compression in standard-tier electroplating is intensifying because fabricators absorb DEFF permit delay costs without pass-through mechanisms. Aftermarket providers serving mining equipment show highest price sensitivity, while aerospace MRO facilities in the UAE demonstrate lowest sensitivity due to OEM repair manual mandates.
Supply Chain Analysis
SFDA and MEE plating chemistry approvals function as supply chain gatekeepers, restricting formulation sourcing to Chemetall, BASF, and MacDermid distributors with established Gulf regulatory dossiers. Specialty chemical inputs draw from Germany, Japan, and China, with nickel sulfate and trivalent chromium salts resting on single-source pharmaceutical-grade suppliers. Tariff exposure on European pretreatment formulations creates margin volatility for South African fabricators. Distribution runs through Chemetall-anchored direct supply contracts with Saudi automotive plants alongside regional distributor networks serving Egyptian and Israeli job shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
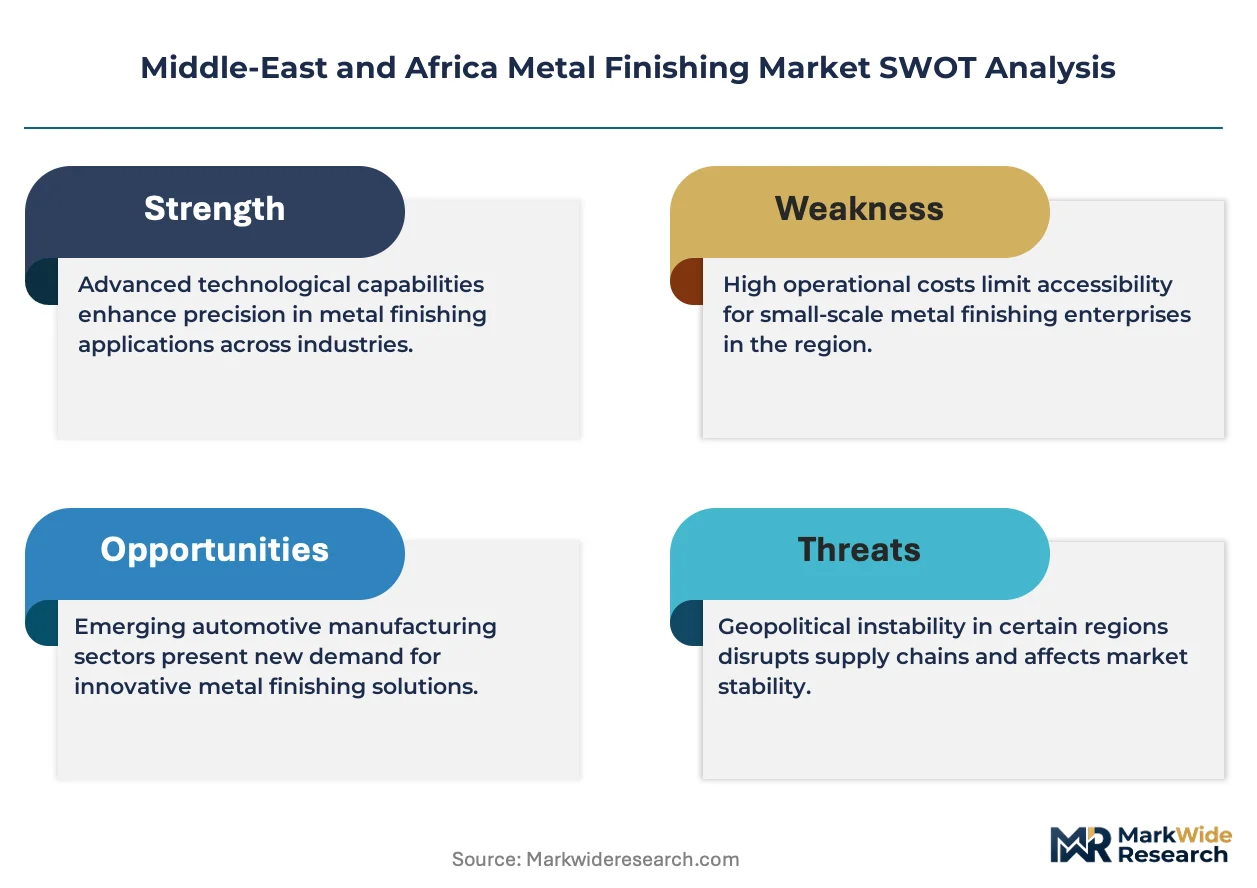
Margin expansion opportunities concentrate in trivalent chromium conversion coating substitution and digital bath monitoring subscriptions, as MEE enforcement eliminates commodity hexavalent competition.
For Market Incumbents: Deploy backward integration into captive trivalent chromium salt production to defend against BASF and Chemetall formulation pricing power. Consolidate supplier panels from 8-12 fabricators to 3-4 strategic partners capable of integrated pretreatment-plating-topcoat sequences, absorbing quality assurance functions previously performed by OEM inspection teams.
For New Entrants and Emerging Players: Launch via IoT-enabled bath chemistry control subscription models targeting the fragmented aftermarket provider segment across South African mining equipment corridors. Egyptian government-backed manufacturing clusters near Suez Canal logistics corridors offer first-mover positioning for compliant finishing services with lower DEFF permitting backlogs.
For Investors and Strategic Acquirers: Consolidation pressure builds where DEFF permit review extensions from 90 to 180 days strand sub-scale plating operations without environmental compliance documentation capabilities. Target acquisition archetypes include Israeli precision electronics platers with SFDA-aligned wastewater systems and Saudi thermal spray contractors holding ADNOC maintenance contracts. The signal to watch is MEE harmonization with Gulf standardization bodies accelerating certification burdens beyond sub-scale fabricator adaptation capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Trivalent Chromium Process Retrofit | MEE enforcement eliminates hexavalent competition, creating captive demand for certified conversion coating capacity. |
| Digital Bath Monitoring Subscription | IoT-enabled chemistry control opens recurring revenue streams from dispersed aftermarket providers. |
| Zero-Liquid-Discharge System Installation | DEFF mandates impose six-figure capital barriers that strand competitors without treatment infrastructure. |
| Thermal Spray Capability Expansion | Saudi Aramco specifications for downhole pump coatings displace hard chrome in energy sector supply chains. |
| Egyptian Industrial Zone First-Mover Positioning | Suez Canal logistics corridors attract government-backed manufacturing clusters with lower compliance backlogs. |
Research Methodology
Multiple input streams — primary interviews with pretreatment chemical procurement managers, plating operation plant engineers, and automotive OEM quality assurance directors; secondary validation through customs/trade data, MEE enforcement bulletins, and SEC filings from multinational chemical suppliers — were reconciled through bottom-up capacity assessment and top-down demand triangulation.
Historical capacity utilization patterns were cross-referenced against panel input from regional distributor networks and national oil company maintenance specification committees. The analytical framework modeled product type, technology, application, and end-user segmentation across the projection horizon, with CAGRs derived from electrolytic process adoption curves and powder coating substitution elasticities. Industry-specific inputs included DEFF permit approval timelines and SFDA chemical registration databases.
Several conditions sit outside the modeled scope, including unannounced regulatory harmonization between Gulf standardization bodies, abrupt carbon-fiber substrate substitution in aerospace applications, and currency volatility effects on European chemical import costs. A model refresh is warranted upon material change in MEE enforcement intensity or trivalent chromium salt supply concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Steel Wire Market
Metals
Metal Coil Lamination Market
Metals
Global Aluminum Extruded Products Market
Metals
Copper Clad Aluminum Wire Market
Metals
Aluminum Fluoride Market
Metals
Rare Earth Metals Market
Metals
Ferrite Market
Metals
Potassium Platinochloride Market
Metals
North America Electrical Steel Market
Metals
Global Wire Rods Market
Metals
Trivalent Chromium Finishing Market
Metals
China Copper Market
Metals
Brazil Aluminum Market
Metals
North America Metal Casting Market
Metals
Aluminum Tubes Market
Metals
Precious Metals Wire Market